- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$2.37 BnMarket Estimate, 2026
$2.63 BnMarket Forecast, 2034
$6.02 BnCAGR, 2026–2034
10.92%Executive Summary: Asia Pacific Hyaluronic Acid Products Market
- Market Scope: Comprehensive Asia-Pacific hyaluronic acid products market analysis covering product types (single, three, and five-cycle injections), clinical and aesthetic applications, country-level landscapes, and regional regulatory trends.
- Market Valuation: Valued at USD 2.37 billion in 2025, estimated at USD 2.63 billion in 2026, and projected to reach USD 6.02 billion by 2034, registering a compound annual growth rate (CAGR) of 10.92% from 2026 to 2034.
- Primary Growth Drivers: Growing applications in dermatology, cosmetic anti-aging treatments, and orthopedic procedures (such as intra-articular therapy for knee osteoarthritis); rising demand for minimally invasive beauty enhancements; and an expanding geriatric population across key regional markets. Key market restraints include high product costs, strict approval protocols, the proliferation of counterfeit products, and limited awareness in rural healthcare settings.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Product Type | Single-Cycle & Three-Cycle Injection Products (commanded major market shares due to high clinical preference in osteoarthritis therapy and convenience) | Five-Cycle Injection & Advanced Derma-Filler Formulations (growing steadily alongside specialized aesthetic procedures) |
| By Application | Dermal Fillers & Osteoarthritis (held the largest market shares driven by booming medical beauty markets and joint health therapies) | Dermal Fillers & Ophthalmic Surgeries (expanding rapidly due to rising aesthetic awareness among young and older consumers) |
| By Country / Region | China (leads the regional market with surging sales in medical beauty, expanding volumes, and a rapidly aging population) | Japan & India (Japan projected to grow fast due to a massive aging demographic and R&D intensity; India growing at ~8.7% CAGR supported by rising disposable incomes and bone-health concerns) |
Major Market Players & Market Structure
Market Structure: Highly competitive pharmaceutical and aesthetic medical device landscape featuring major global corporations expanding their footprints across fast-growing Asia-Pacific economies through advanced formulations and strict regulatory compliance.
Key Companies: Allergan, Sanofi, Ferring B.V., Zimmer Biomet, Fidia Farmaceutici, Salix Pharmaceuticals, Anika Therapeutics, Seikagaku Corporation, Hoffmann-La Roche Ltd, Alcon, Inc., Smith & Nephew plc, and Merz Aesthetics, Inc.
Asia Pacific Hyaluronic Acid Products Market Size
The size of the Asia Pacific hyaluronic acid products market was worth USD 2.37 billion in 2025. The Asia Pacific market is anticipated to grow at a CAGR of 10.92% from 2026 to 2034, reaching USD 6.02 billion by 2034, up from USD 2.63 billion in 2026.
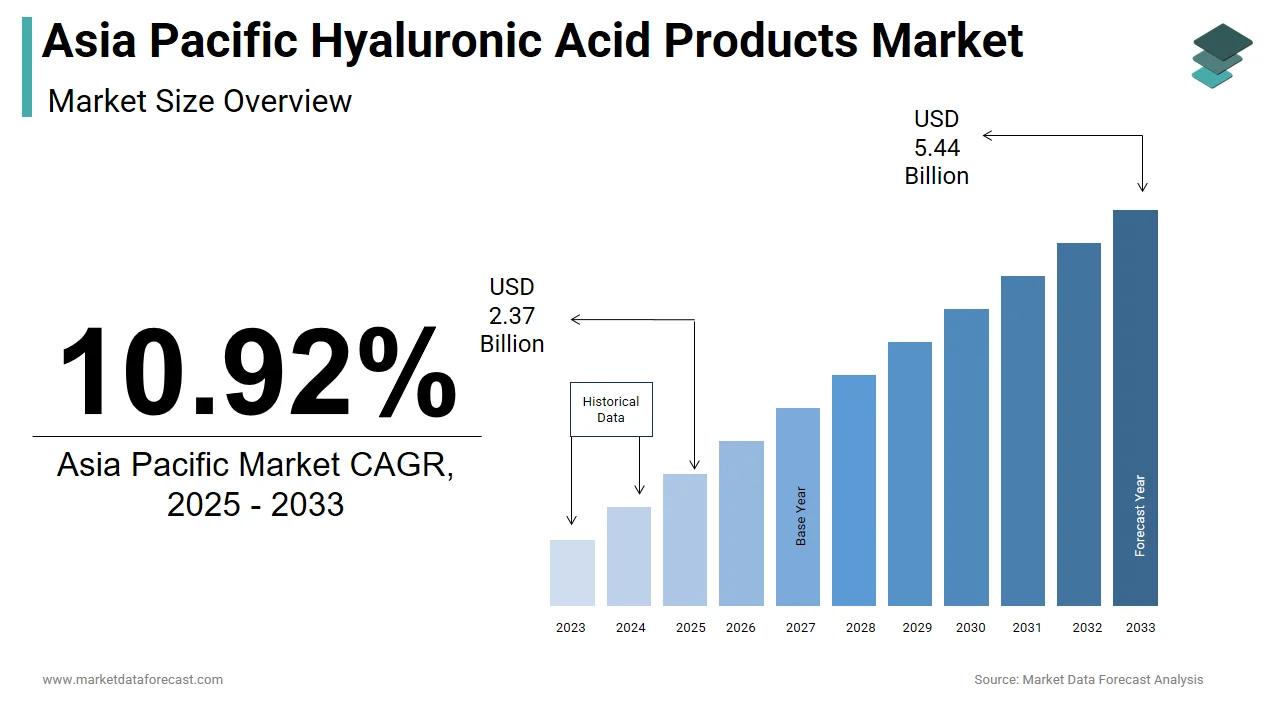
The Asia-Pacific hyaluronic acid products market is experiencing robust expansion driven by rapid urbanization, rising disposable incomes, and an increasing focus on personal wellness across the region. According to the United Nations Department of Economic and Social Affairs, the population aged 65 years and older in Asia is projected to reach 1.3 billion by 2050, creating a substantial demographic base for age-related therapeutic and cosmetic interventions. According to the International Society of Aesthetic Plastic Surgery, Asia accounts for over 40% of global non-surgical cosmetic procedures, with hyaluronic acid injections being the most frequently performed treatment. These statistics underscore the critical role of hyaluronic acid in both medical and aesthetic domains. The prevalence of dry skin conditions due to varying climatic zones further fuels demand for hydrating topical products. Regulatory bodies in countries like Japan and South Korea are implementing stringent quality standards to ensure product safety. This evolving landscape supports the integration of advanced cross-linked technologies. Consequently, the market serves as a pivotal component of the broader dermatological and orthopedic healthcare ecosystems in the Asia Pacific region.
MARKET DRIVERS
Surging Demand for Minimally Invasive Aesthetic Procedures
The escalating preference for minimally invasive aesthetic procedures majorly drives the Asia-Pacific hyaluronic acid products market expansion forward. Consumers are increasingly seeking alternatives to surgical facelifts due to lower costs, reduced recovery time, and minimal scarring. According to the International Society of Aesthetic Plastic Surgery, non-surgical procedures in East Asia increased by 25% in the last year, with hyaluronic acid fillers constituting the largest share of these treatments. This trend is particularly pronounced in urban centers like Seoul, Shanghai, and Bangkok, where aesthetic enhancement is socially accepted and widely practiced. According to the American Society of Plastic Surgeons, hyaluronic acid injections offer immediate results with high patient satisfaction rates, driving repeat usage. Social media influence and celebrity endorsements further amplify the desire for youthful appearances among younger demographics. Clinics are expanding their service offerings to include advanced injection techniques that require specialized hyaluronic acid formulations. The availability of skilled practitioners in major cities ensures safe administration, building consumer trust. This cultural shift toward preventive aesthetics sustains consistent demand for high-quality dermal fillers. The ease of access to these procedures in medical tourism hubs also attracts international clients, boosting local market volume.
Rising Prevalence of Osteoarthritis and Aging Population
The growing incidence of osteoarthritis and other joint disorders further contributes to the Asia-Pacific hyaluronic acid products market growth. Hyaluronic acid injections are widely used to alleviate pain and improve mobility in patients with knee osteoarthritis by restoring the viscosity of synovial fluid. According to the World Health Organization, musculoskeletal conditions are the leading contributor to disability globally, with prevalence rates rising sharply in aging populations across Asia. According to the National Health Commission, over 100 million adults in China suffer from some form of joint degeneration, creating a large patient pool for therapeutic interventions. According to the European League Against Rheumatism, viscosupplementation can delay the need for joint replacement surgery by up to 5 years in moderate cases. This clinical benefit drives adoption among patients seeking conservative management options. Healthcare providers in Japan and Australia are increasingly incorporating hyaluronic acid injections into standard treatment protocols for osteoarthritis. Insurance coverage for these therapies is expanding in certain private health plans, improving accessibility. The aging demographic in the region ensures a steady increase in the number of individuals requiring joint care. This medical necessity complements the aesthetic demand, diversifying the market base.
MARKET RESTRAINTS
High Cost of Premium Hyaluronic Acid Formulations
The substantial financial burden associated with premium hyaluronic acid formulations is a significant restraint on market penetration in many parts of the Asia Pacific region. Advanced cross-linked hyaluronic acid products, which offer longer-lasting results and superior stability, command high prices that are often prohibitive for the average consumer. According to the World Bank, out-of-pocket health expenditure in several Southeast Asian nations exceeds 50% of total health spending, limiting disposable income for elective aesthetic or advanced therapeutic procedures. In countries like Vietnam and Indonesia, the cost of a single syringe of branded hyaluronic acid filler can equal a month’s salary for many workers. This economic disparity restricts access primarily to affluent urban populations. The absence of comprehensive insurance coverage for cosmetic procedures further exacerbates the affordability issue. Even for medical indications like osteoarthritis, patients often face high co-payments or full self-payment requirements. The high import duties on medical devices and cosmetics in some countries also inflate final retail prices. Manufacturers struggle to balance quality with affordability in price-sensitive markets. Consequently, many consumers opt for cheaper, unregulated alternatives or forego treatment entirely. This financial barrier limits the overall volume of legitimate hyaluronic acid products sold in the region.
Prevalence of Counterfeit and Unregulated Products
The widespread availability of counterfeit and unregulated hyaluronic acid products acts as a major restraint on the growth of the legitimate market in the Asia Pacific region. The lack of stringent regulatory enforcement in some areas allows substandard and fake products to enter the supply chain, posing serious health risks to consumers. According to the World Health Organization, up to 10% of medical products in low- and middle-income countries are estimated to be substandard or falsified, including dermal fillers and injectables. These counterfeit products often contain impurities or incorrect concentrations of hyaluronic acid, leading to severe adverse reactions such as infections, nodules, and tissue necrosis. High-profile cases of complications from illegal injections have eroded public trust in aesthetic procedures. According to the National Medical Products Administration in China, multiple warnings have been issued against unlicensed clinics offering cheap filler treatments, highlighting the scale of the problem. Legitimate manufacturers face reputational damage and liability issues due to the actions of illicit operators. The difficulty in distinguishing authentic products from fakes discourages potential users from seeking professional treatment. Regulatory bodies struggle to monitor the vast informal market effectively. This environment creates uncertainty and hesitation among consumers, slowing down the adoption of safe and approved hyaluronic acid products.
MARKET OPPORTUNITIES
Expansion of Medical Tourism Hubs
The rapid development of medical tourism hubs in the Asia Pacific region presents a substantial opportunity for the expansion of the hyaluronic acid products market. Countries like Thailand, South Korea, and Singapore are positioning themselves as global destinations for affordable and high-quality cosmetic and medical treatments. According to the Global Wellness Institute, the Asia Pacific region saw a 15% annual growth in wellness tourism expenditure, with aesthetic procedures being a key driver. International patients traveling for hyaluronic acid injections and joint therapies contribute significantly to local revenue. These tourists often seek premium brands and advanced formulations, driving demand for high-end products. Clinics in Bangkok and Seoul invest in state-of-the-art facilities and certified practitioners to attract this clientele. Government support for medical tourism infrastructure facilitates easier visa processes and accreditation for healthcare providers. This influx of foreign patients encourages local distributors to stock a wider variety of hyaluronic acid products. Partnerships between international manufacturers and local hospitals enhance the availability of genuine products. The reputation of these hubs for safety and quality builds confidence among regional consumers. This trend creates a sustainable demand channel that is less susceptible to local economic fluctuations.
Growing Awareness of Skincare and Hydration Benefits
The increasing consumer awareness regarding the importance of skincare and hydration in diverse climates is another significant opportunity for the regional market. Residents in various parts of Asia face extreme weather conditions, from humidity to dryness, which affect skin health and accelerate aging. According to the Journal of Clinical and Aesthetic Dermatology, transepidermal water loss is significantly higher in arid environments, necessitating effective humectants like hyaluronic acid. Consumers are becoming more educated about ingredient efficacy through digital platforms and dermatologist recommendations. This knowledge drives demand for serums, moisturizers, and masks containing hyaluronic acid. Local beauty brands are launching specialized lines formulated for specific climate needs, capturing market share from international competitors. The rise of e-commerce platforms makes these products accessible to consumers in remote areas. Social media influencers in the region frequently promote hydration routines, normalizing the use of active ingredients. Retailers are expanding their skincare sections to include a wider range of hyaluronic acid-based items. This shift from purely aesthetic injections to daily skincare routines broadens the customer base. The recurring nature of skincare purchases ensures steady revenue streams for manufacturers.
MARKET CHALLENGES
Stringent and Varied Regulatory Frameworks
Navigating the complex and varied regulatory frameworks for medical devices and cosmetics is a significant challenge to the hyaluronic acid products market in the Asia Pacific region. Each country has its own registration requirements, approval timelines, and compliance standards, creating a fragmented landscape for manufacturers. The Association of Southeast Asian Nations has made strides in harmonizing regulations, but differences still exist between member states and other Asian nations. According to the Pharmaceuticals and Medical Devices Agency in Japan, rigorous clinical data is required for product registration, which can delay market entry by several months. The National Medical Products Administration in China has recently tightened controls on imported cosmetics, requiring additional documentation and local testing. These bureaucratic hurdles increase operational costs and time to market for global players. Small and medium enterprises often lack the resources to navigate these complex processes effectively. Changes in regulatory policies can occur with little notice, disrupting supply chains. The lack of mutual recognition agreements means that approvals in one country do not automatically apply to others. This fragmentation hinders the efficient distribution of hyaluronic acid products across the region. Manufacturers must maintain dedicated regulatory affairs teams for each market, adding to the overhead. These challenges slow down the introduction of innovative products and limit consumer access.
Shortage of Trained Medical Professionals
The acute shortage of trained medical professionals qualified to administer hyaluronic acid injections safely presents a persistent challenge to the market in the Asia Pacific region. Proper administration of dermal fillers and viscosupplementation requires specialized knowledge of anatomy and injection techniques to avoid complications. According to the World Health Organization, many developing Asian countries face a critical deficit of healthcare workers, with physician density often below the recommended threshold. In rural areas of countries like India and the Philippines, access to qualified dermatologists or orthopedic specialists is extremely limited. This scarcity forces patients to travel to urban centers or seek treatment from unqualified practitioners, increasing the risk of adverse events. The lack of standardized training programs for aesthetic medicine in some regions exacerbates the problem. Professional societies are working to establish certification courses, but uptake is slow due to cost and time constraints. The fear of complications from improper injection techniques deters potential users from seeking treatment. Clinics struggle to find and retain skilled staff, limiting their capacity to serve patients. This human resource gap restricts the safe expansion of the injectable hyaluronic acid market. Addressing this challenge requires significant investment in education and training infrastructure.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Product Type, Application, and Country. |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered | India, China, Japan, South Korea, Australia, New Zealand, Thailand, Malaysia, Vietnam, Philippines, Indonesia, Singapore and Rest of APAC. |
| Market Leaders Profiled | Allergan, Sanofi, Ferring B.V., LG Chem, Zimmer Biomet, Fidia Farmaceutici, Salix Pharmaceutical, Anika Therapeutics, Seikagaku Corporation, Bloomage Biotechnology, Hoffmann-La Roche Ltd, Alcon, Inc., Smith & Nephew plc, Shiseido Company, and F.Merz Aesthetics, Inc. |
SEGMENTAL ANALYSIS
By Product Type Insights
The single-cycle injection products segment led the Asia Pacific hyaluronic acid market by holding 54.9% of the regional market share in 2025 due to its superior convenience and alignment with the fast-paced lifestyles of urban consumers. This product type requires only one administration session, significantly reducing the time commitment for patients seeking aesthetic or therapeutic relief. The dominance of single-cycle injection products is primarily driven by the high demand for time-efficient treatments among busy professionals in major Asia-Pacific metropolitan areas. According to the World Health Organization, adherence to multi-visit medical protocols drops by approximately 40% in densely populated urban centers due to commuting challenges and work commitments. Single injection therapies eliminate the logistical burden of repeated clinic visits, ensuring patients receive the full therapeutic or aesthetic benefit immediately. This convenience is particularly valued in cities like Tokyo and Singapore where productivity is culturally prioritized. According to the American Academy of Orthopaedic Surgeons, single-injection viscosupplementation has demonstrated comparable efficacy to three-cycle regimens for mild osteoarthritis, validating its clinical utility. Patients are more likely to complete treatment when it requires minimal disruption to their daily schedules. Healthcare providers also benefit from streamlined appointment scheduling and reduced administrative overhead associated with follow-up visits. The preference for efficiency over prolonged engagement drives widespread adoption across both medical and aesthetic applications. This factor ensures single-cycle products remain the volume leader in the region.
On the other end, the five-cycle injection products segment is anticipated to grow at a promising CAGR of 12.5% over the forecast period in the Asia-Pacific hyaluronic acid products market owing to the clinical preferences for sustained therapeutic outcomes in chronic conditions. The rapid growth of five-cycle injection products is fueled by increasing clinical evidence supporting their superior long-term efficacy for managing chronic osteoarthritis and severe joint degeneration. Physicians in aging societies like Japan and South Korea are increasingly adopting extended regimens to maximize cartilage protection and delay surgical intervention. According to the European League Against Rheumatism, extended viscosupplementation protocols can maintain symptom relief for up to 12 months, compared to 6 months for shorter cycles. This extended duration aligns with the goals of geriatric care in super-aged societies where preserving mobility is paramount. According to the Journal of Bone and Joint Surgery, patients completing five-cycle regimens report 25% higher satisfaction scores regarding pain management and functional improvement. This clinical superiority drives adoption among specialists treating elderly populations with complex comorbidities. Insurance providers in developed markets are beginning to recognize the cost-effectiveness of preventing joint replacement through extended conservative therapy. The focus on disease modification rather than temporary symptom relief supports the uptake of intensive protocols. As the region’s population continues to age, demand for durable solutions will accelerate this segment's growth.
By Application Insights
The dermal fillers segment led the market by holding 50.9% of the regional market share in 2025. The dominance of the dermal fillers segment in the Asia-Pacific market is attributed to the profound cultural shifts toward aesthetic enhancement and the normalization of cosmetic procedures, commanding a leading market share of approximately 52% according to recent industry databases. The dominance of the dermal fillers segment is primarily driven by the deep cultural acceptance and social normalization of aesthetic enhancements across East and Southeast Asia. Unlike Western markets where anti-aging is often the primary motivator, Asian consumers frequently seek facial contouring and harmonization aligned with specific beauty ideals. According to the International Society of Aesthetic Plastic Surgery, South Korea and China collectively account for over 30% of global non-surgical cosmetic procedures, with hyaluronic acid fillers being the most prevalent. Social media platforms and K-pop culture have amplified these trends, making aesthetic maintenance a routine aspect of personal grooming for younger demographics. The stigma surrounding cosmetic intervention has largely dissipated in urban centers, encouraging open discussion and peer recommendation. Clinics compete by offering specialized techniques for Asian facial anatomy, further stimulating demand. The integration of aesthetic services into dermatology and general practice has increased accessibility. This cultural embeddedness ensures a consistent and resilient demand base that is less susceptible to economic downturns than purely discretionary luxury goods. The social imperative to conform to prevailing beauty standards sustains the segment's leadership position.
However, the osteoarthritis application segment is estimated to showcase a prominent CAGR of 11.4% over the forecast period in the Asia-Pacific hyaluronic acid products market owing to the unprecedented pace of population aging and rising obesity rates. The rapid growth of the osteoarthritis segment is fueled by the unprecedented speed of population aging in the Asia-Pacific region, which is creating an urgent demand for joint preservation therapies. Countries like Japan, South Korea, and China are transitioning to super-aged societies faster than any previous generation in history. According to the United Nations Department of Economic and Social Affairs, the number of people aged 65 and above in East Asia is projected to double by 2050, reaching over 400 million. This demographic shift directly correlates with exponential increases in osteoarthritis prevalence. Hyaluronic acid viscosupplementation is positioned as a critical intermediate therapy between oral analgesics and joint replacement surgery. Governments are actively promoting conservative management strategies to reduce the burden on surgical infrastructure and healthcare budgets. The sheer scale of the aging cohort ensures that even modest penetration rates translate to massive volume growth. Public health campaigns emphasizing active aging and mobility preservation further drive awareness. As life expectancy continues to rise, the addressable patient pool for joint health interventions will expand relentlessly.
COUNTRY LEVEL ANALYSIS
China Hyaluronic Acid Products Market Analysis
China held the largest share of the Asia-Pacific hyaluronic acid products market in 2025 and is expected to experience robust market expansion over the next few years owing to its massive population scale, rising disposable incomes, and stricter regulatory oversight that fosters consumer trust. The country serves as both a major consumer market and a global manufacturing hub for raw hyaluronic acid. According to the National Medical Products Administration, stricter regulations on medical aesthetics have been implemented, enhancing consumer confidence in licensed products. According to the Ministry of Civil Affairs, the population over 60 reached 280 million in recent years, creating immense demand for osteoarthritis treatments. Simultaneously, the aesthetic sector is expanding beyond tier 1 cities to tier 2 and tier 3 markets as disposable incomes rise. Local manufacturers are gaining market share by offering cost-competitive alternatives to imported brands. The government’s dual circulation strategy supports domestic consumption and innovation in biomedical materials. Digital platforms like Xiaohongshu drive trends and educate consumers about product safety. These factors combine to maintain China’s dominant position in the regional landscape.
Japan Hyaluronic Acid Products Market Analysis
Japan is expected to maintain steady market development over the next few years, heavily influenced by its world-leading elderly demographic, strict PMDA quality controls, and a preference for natural aesthetic outcomes. Japan represents a mature and technologically advanced market for hyaluronic acid products, characterized by the world’s oldest population and high healthcare standards. The country leads in orthopedic applications due to the high prevalence of age-related joint disorders. According to the Ministry of Health, Labour and Welfare, over 29% of the population is aged 65 or older, sustaining steady demand for viscosupplementation. Japan is also a pioneer in ophthalmic applications of hyaluronic acid for cataract and glaucoma surgeries. The aesthetic market is more conservative but growing steadily, with emphasis on natural-looking results and safety. Strict regulatory oversight by the Pharmaceuticals and Medical Devices Agency ensures high product quality and limits counterfeit penetration. Domestic companies like Seikagaku and Kaken Pharmaceutical hold strong positions through proprietary technologies. The universal health insurance system covers approved medical indications, ensuring broad access. Cultural preferences for subtlety influence product development and marketing strategies. These dynamics sustain Japan’s prominent position in the therapeutic segment.
South Korea Hyaluronic Acid Products Market Analysis
South Korea is anticipated to record dynamic market growth over the next few years, supported by its status as a global cosmetic capital, advanced R&D biotech capabilities, and high consumer digital literacy. South Korea features a highly dynamic and innovative market for hyaluronic acid products, driven by its status as a global aesthetic capital and advanced biotechnology sector. The country has one of the highest per capita rates of cosmetic procedures worldwide. According to the Korean Society for Aesthetic Plastic Surgery, hyaluronic acid fillers are the most performed non-surgical procedure, with continuous innovation in formulation and technique. Domestic manufacturers like LG Chem and Huons have gained significant market share through competitive pricing and localized R&D. The medical tourism industry attracts patients from across Asia, boosting export-oriented production. Regulatory reforms have streamlined approvals for combination products and novel delivery systems. High digital literacy drives online consultation and e-commerce for topical products. The cultural acceptance of aesthetic enhancement creates a resilient demand base. Strong intellectual property protection encourages investment in next-generation technologies. These factors make South Korea a key innovation hub and consumption center.
India Hyaluronic Acid Products Market Analysis
India is projected to witness significant market growth in the coming years, propelled by an expanding middle class, rising aesthetic awareness among millennials, and an increasing prevalence of lifestyle joint disorders. India holds a significant and rapidly growing position in the Asia Pacific hyaluronic acid market, driven by its large young population, rising affluence, and expanding healthcare infrastructure. The country is witnessing a surge in aesthetic awareness among urban millennials and Gen Z. According to the Indian Association of Dermatologists, Venereologists and Leprologists, a 30% annual increase in non-surgical aesthetic procedures has been reported in metropolitan cities. The osteoarthritis segment is also expanding due to rising obesity and lifestyle diseases among younger adults. Price sensitivity drives demand for affordable generic and locally manufactured products. The Central Drugs Standard Control Organization is strengthening regulations to curb unapproved imports and ensure safety. Medical tourism from neighboring countries and the Middle East contributes to market volume. Tier 2 and tier 3 cities are emerging as new growth frontiers as healthcare access improvements continue. Digital marketing and influencer culture are accelerating adoption. These elements position India as a high-growth volume market with distinct segmentation dynamics.
Australia Hyaluronic Acid Products Market Analysis
Australia is poised for steady market expansion over the next few years, sustained by rigorous TGA compliance frameworks, high healthcare expenditure, and a mature demand for both anti-aging and sun-repair skin solutions. Australia maintains a premium and regulated market for hyaluronic acid products, driven by high healthcare spending, strong sun safety awareness, and an aging population. The country has stringent regulatory oversight through the Therapeutic Goods Administration, ensuring product safety and efficacy. According to the Australian Bureau of Statistics, 17% of the population is over 65, driving demand for osteoarthritis and ophthalmic applications. The aesthetic market is mature with high per capita spending on non-surgical procedures. Sun damage awareness creates unique demand for skin hydration and repair products containing hyaluronic acid. Private health insurance covers some therapeutic indications, improving accessibility. The market is dominated by international premium brands due to strict registration requirements. Telehealth adoption has expanded access to consultations in remote areas. Consumer advocacy groups play an active role in promoting safety and transparency. These factors sustain Australia’s position as a high-value, quality-driven market.
COMPETITIVE LANDSCAPE
The competition in the Asia Pacific hyaluronic acid products market is characterized by intense rivalry between established global pharmaceutical giants and agile regional manufacturers. International players dominate the premium segment with branded dermal fillers and advanced viscosupplementation therapies leveraging strong clinical data and brand recognition. Local firms compete primarily on price and accessibility, offering generic alternatives and basic skincare formulations tailored to regional preferences. The market sees fierce competition in countries like China and South Korea, where domestic brands have gained significant traction through innovation and cost efficiency. Companies differentiate themselves through superior after-sales support, practitioner training, and anti-counterfeit measures. Strategic alliances with government health bodies are crucial for securing approvals and participating in public health tenders for osteoarthritis treatments. The fragmented regulatory landscape across Asian nations creates barriers to entry favoring companies with robust compliance capabilities. Innovation in product longevity and safety profiles is key to retaining customer loyalty in the aesthetic sector. Continuous investment in local infrastructure and education is essential for sustaining growth and overcoming logistical challenges in this diverse and evolving region.
KEY MARKET PLAYERS
The leading companies operating in the Asia Pacific hyaluronic acid products market include:
- Allergan
- Sanofi
- Ferring B.V.
- LG Chem
- Zimmer Biomet
- Fidia Farmaceutici
- Salix Pharmaceuticals
- Anika Therapeutics
- Seikagaku Corporation
- Bloomage Biotechnology
- Hoffmann-La Roche Ltd.
- Alcon, Inc.
- Smith & Nephew plc
- Shiseido Company
- Merz Aesthetics, Inc.
TOP PLAYERS IN THE MARKET
- LG Chem contributes significantly to the Asia Pacific hyaluronic acid market through its subsidiary LG Life Sciences, which manufactures premium dermal fillers under the Yvoire and Neuramis brands. The company leverages its advanced cross-linking technology to produce high-stability and long-lasting products favored by aesthetic practitioners. Recently, LG Chem expanded its manufacturing facilities in South Korea to increase production capacity for export markets across Asia. This expansion strengthens their position by ensuring consistent supply to growing demand centers. They also engage in extensive clinical training programs for doctors in China and Southeast Asia. These initiatives build professional trust and promote safe usage protocols. Their focus on innovation and quality control maintains their reputation as a leading provider of safe and effective aesthetic solutions in the region.
- Bloomage Biotechnology plays a vital role as the world’s largest producer of raw hyaluronic acid and a key supplier of finished medical and cosmetic products. The company utilizes microbial fermentation technology to achieve high purity and scalability in production. Bloomage recently invested heavily in research and development to create novel molecular weight variants for specialized skincare and orthopedic applications. This innovation diversifies their product portfolio and addresses specific consumer needs in Japan and Australia. They have established strategic partnerships with international cosmetic brands to supply premium raw materials. These collaborations enhance their global reach and brand recognition. Their vertical integration from raw material to finished goods allows for cost efficiency and quality assurance. This comprehensive approach solidifies their leadership in the upstream and downstream segments of the market.
- Shiseido Company supports the Asia Pacific hyaluronic acid market through its extensive portfolio of high-end skincare products containing advanced hyaluronic acid formulations. The Japanese beauty giant focuses on combining traditional botanical ingredients with modern biotechnology to enhance skin hydration and elasticity. Shiseido recently launched new serum lines featuring microencapsulated hyaluronic acid for deeper penetration and sustained release. This technological advancement appeals to consumers seeking superior anti-aging benefits. The company leverages its strong retail network and e-commerce platforms to distribute products across China and Southeast Asia. They also invest in consumer education campaigns to highlight the science behind their formulations. These efforts strengthen brand loyalty and drive repeat purchases. Their commitment to sustainability and ethical sourcing further enhances their appeal to environmentally conscious consumers in the region.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the Asia Pacific hyaluronic acid products market employ strategic localization of product formulations to meet diverse cultural beauty standards and climatic conditions across the region. Companies frequently invest in clinical training and certification programs for healthcare professionals to ensure safe administration and build practitioner loyalty. This approach fosters trust and encourages the prescription of premium brands. Another prevalent strategy involves leveraging digital marketing and social media influencers to drive consumer awareness and demand for aesthetic treatments. Firms focus on expanding distribution networks through e-commerce platforms to reach underserved rural areas and younger demographics. Partnerships with local manufacturers and distributors help navigate complex regulatory landscapes and reduce import costs. Furthermore, participants actively engage in research and development to innovate new delivery systems and combination therapies. These combined strategies enable companies to maintain competitive advantage while addressing the unique regulatory and cultural nuances of the diverse Asia Pacific markets.
MARKET SEGMENTATION
This Asia Pacific hyaluronic acid products market research report is segmented and sub-segmented into the following categories.
By Product Type
- Single Cycle Injection Products
- Three-Cycle Injection Products
- Five-Cycle Injection Products
By Application
- Osteoarthritis
- Ophthalmic
- Dermal Fillers
- Vesicoureteral Reflux
By Country
- India
- China
- Japan
- South Korea
- Australia
- New Zealand
- Thailand
- Malaysia
- Vietnam
- Philippines
- Indonesia
- Singapore
- Rest Of APAC