- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$1.71 BnMarket Estimate, 2026
$1.85 BnMarket Forecast, 2034
$3.45 BnCAGR, 2026–2034
8.1%Executive Summary: Asia Pacific Microscopy Market
- Market Scope: Comprehensive Asia-Pacific microscopy market analysis covering product types, microscope categories (optical, electron, scanning probe), industrial/research applications, end-user verticals, and country-level landscapes.
- Market Valuation: Valued at USD 1.71 billion in 2025, estimated at USD 1.85 billion in 2026, and projected to reach USD 3.45 billion by 2034, registering a compound annual growth rate (CAGR) of 8.10% from 2026 to 2034.
- Primary Growth Drivers: Increasing R&D funds and investments in microscopy technologies, rising focus on nanotechnology and regenerative medicine, low cost of raw materials and experienced labor, and the integration of artificial intelligence (AI) in advanced microscopy systems. Key market restraints include high capital costs for advanced microscopes, excise taxes, and limited awareness in certain regional sectors.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Product | Microscopes (commanded the majority market share as essential standalone diagnostic and inspection systems) | Accessories & Digital Software Upgrades (growing rapidly backed by imaging software and modular enhancements) |
| By Type | Optical & Electron Microscopes (held prominent market shares across life sciences and semiconductor manufacturing) | Advanced Scanning Probe Microscopes (AFM/STM) (expanding via nanotechnology and semiconductor R&D demands) |
| By Application & End User | Semiconductor & Electronics / Research Institutes (dominated market usage driven by high-tech manufacturing and academic research) | Nanotechnology & Industrial Inspection (growing strongly alongside electronics and materials science sectors) |
| By Country / Region | China (leads as the largest regional market due to high demand, local manufacturing capabilities, and low-cost production) | Japan (projected to showcase the highest CAGR driven by technological advancements and major local manufacturers) |
Major Market Players & Market Structure
Market Structure: Highly competitive scientific instrumentation market featuring global technology giants and regional optical leaders competing through product innovation, AI integration, and precision nanotechnology solutions.
Key Companies: Carl Zeiss, Danaher Corporation, Thermo Fisher Scientific, Nikon Corporation, Bruker Corporation, Olympus Corporation, Oxford Instruments, JEOL Ltd., Hitachi High-Tech Corporation, Keyence Corporation, Vision Engineering, and Helmut Hund GmbH.
 Download Free Sample Report
Asia Pacific Microscopy Market Size
The size of the Asia Pacific microscopy market was worth USD 1.71 billion in 2025. The Asia Pacific market is anticipated to grow at a CAGR of 8.1% from 2026 to 2034, reaching USD 3.45 billion by 2034, up from USD 1.85 billion in 2026.
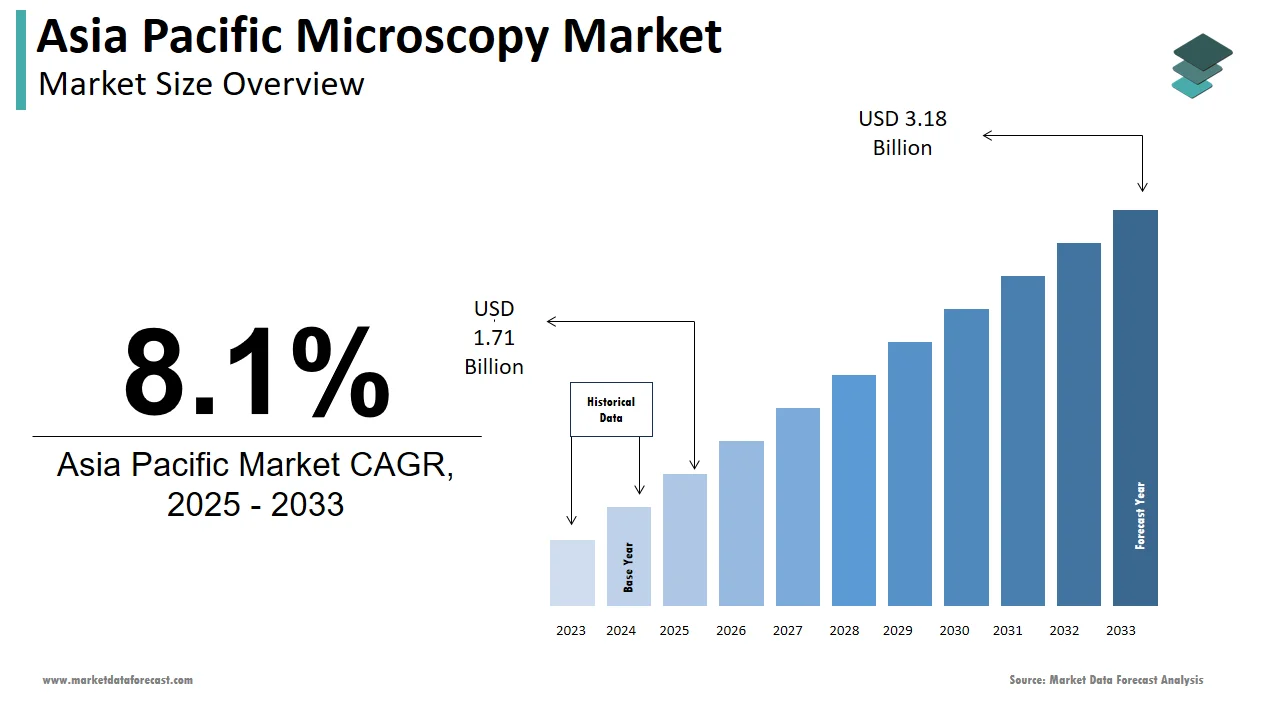
The Asia-Pacific microscopy market serves as the backbone of scientific discovery and diagnostic precision across the region. According to the United Nations Educational, Scientific and Cultural Organization, research and development expenditure in Asia has surpassed 2% of regional gross domestic product, signaling robust investment in advanced analytical infrastructure. According to the World Health Organization, the burden of infectious diseases and cancer in the Asia Pacific region necessitates sophisticated diagnostic tools, with pathology laboratories requiring high-throughput microscopy systems for accurate disease identification. These health imperatives drive the adoption of digital and automated microscopy solutions. Furthermore, the rapid expansion of semiconductor manufacturing in countries like South Korea and Taiwan demands precise defect inspection capabilities. The integration of artificial intelligence with imaging platforms enhances data analysis speed and accuracy. Consequently, the market is evolving from traditional manual observation to intelligent, connected imaging ecosystems that support complex biomedical and industrial applications.
MARKET DRIVERS
Escalating Government Investment in Life Sciences Research
The substantial increase in government funding for life sciences and biomedical research is propelling the Asia-Pacific microscopy market expansion. National initiatives aimed at achieving scientific self-sufficiency and improving public health outcomes are driving the procurement of advanced imaging equipment. According to the Chinese Ministry of Science and Technology, national spending on basic research reached approximately 180 billion USD in recent years, with a significant portion allocated to biological and medical instrumentation. This financial commitment enables universities and research institutes to upgrade their facilities with state-of-the-art confocal and super-resolution microscopes. According to the Japanese Agency for Medical Research and Development, billions of yen are allocated annually to projects focusing on regenerative medicine and drug discovery, which rely heavily on high-precision imaging. According to the Australian National Health and Medical Research Council, the importance of advanced microscopy in understanding cellular mechanisms of disease is emphasized. These institutional investments create a steady demand for high-end microscopy systems. Researchers require tools that offer superior resolution and multimodal capabilities to compete globally. This sustained funding environment ensures continuous modernization of laboratory infrastructure across the region.
Rising Prevalence of Chronic Diseases and Diagnostic Needs
The growing incidence of chronic diseases such as cancer and cardiovascular disorders is further contributing to the microscopy market growth in Asia-Pacific. Accurate diagnosis and staging of these conditions require detailed histological and cytological examination using high-quality microscopes. According to the International Agency for Research on Cancer, Asia accounts for nearly 50% of global cancer cases, creating an immense workload for pathology departments. This volume necessitates the adoption of digital pathology and automated microscopy systems to improve throughput and reduce human error. According to the Indian Council of Medical Research, non-communicable diseases contribute to over 60% of total deaths in the country, driving the need for precise diagnostic infrastructure. Hospitals and diagnostic centers are investing in whole slide imaging scanners to facilitate remote consultation and second opinions. The shift toward personalized medicine further requires detailed molecular imaging to identify specific biomarkers. Governments are upgrading public health facilities to meet these diagnostic challenges. This clinical urgency ensures that microscopy remains a critical component of modern healthcare delivery. The need for faster and more accurate diagnoses supports the transition from conventional to digital microscopy platforms.
MARKET RESTRAINTS
High Capital Expenditure and Maintenance Costs
The prohibitive cost of acquiring and maintaining advanced microscopy systems is a significant restraint on market penetration in developing economies within the Asia Pacific region. High-end electron and super-resolution microscopes require substantial initial investment, often exceeding hundreds of thousands of dollars per unit. According to the World Bank, healthcare expenditure per capita in low-income Asian nations remains below 100 USD, limiting the budget available for expensive diagnostic equipment. This financial constraint forces many smaller hospitals and research labs to rely on outdated or lower-resolution instruments. According to the Association for Clinical Biochemistry and Laboratory Medicine, annual maintenance contracts for complex microscopy systems can cost up to 15% of the purchase price, adding to the long term financial burden. Specialized training for operators and service engineers further increases operational expenses. In rural areas of countries like Indonesia and Vietnam, the lack of funding for technical support leads to prolonged downtime when equipment fails. These economic barriers restrict access to cutting-edge technology for a large segment of the population. Manufacturers struggle to offer affordable solutions without compromising performance. This cost sensitivity limits the overall market growth potential in emerging economies.
Shortage of Skilled Technical Personnel
The acute shortage of trained professionals capable of operating and interpreting data from advanced microscopy systems is another major restraint on market utilization in the Asia Pacific region. Modern microscopy techniques require specialized knowledge in optics, sample preparation, and image analysis software. According to the World Health Organization, the Asia Pacific region faces a deficit of over 4 million healthcare workers, including pathologists and laboratory technicians. This workforce gap limits the effective deployment of sophisticated imaging technologies in clinical and research settings. According to the Royal College of Pathologists of Australasia, a significant disparity exists in the number of qualified pathologists per capita between urban and rural areas. Many institutions possess advanced equipment but lack the expertise to maximize its potential. Training programs are often limited to major metropolitan centers, leaving peripheral facilities underserved. The complexity of new digital and AI-integrated systems exacerbates this skills gap. Without adequate human resources, the return on investment for high-end microscopy is diminished. This human capital challenge hinders the widespread adoption and efficient use of advanced microscopy solutions across the region.
MARKET OPPORTUNITIES
Integration of Artificial Intelligence and Digital Pathology
The integration of artificial intelligence and machine learning algorithms with microscopy platforms is a substantial opportunity for market expansion in the Asia Pacific region. AI-enabled systems can automate image analysis, detect anomalies, and quantify features with greater speed and accuracy than manual methods. According to the Journal of Pathology Informatics, AI-assisted diagnosis can reduce the time required for slide interpretation by up to 50%, addressing the bottleneck caused by personnel shortages. This efficiency gain is crucial for high-volume diagnostic centers in countries like China and India. The Singapore Health Services has implemented pilot programs using AI for cancer screening, demonstrating improved diagnostic consistency. Digital pathology allows for remote collaboration and telemedicine, extending expert care to underserved areas. According to the Asian Society of Pathology, the standardization of digital imaging protocols is advocated to facilitate data sharing. Manufacturers are developing cloud-based platforms that enable real-time analysis and storage of large image datasets. This technological convergence transforms microscopy from a purely observational tool into a quantitative diagnostic engine. The ability to process vast amounts of data opens new avenues for research and clinical decision support.
Expansion of Semiconductor and Electronics Manufacturing
The rapid growth of the semiconductor and electronics manufacturing industry in the Asia Pacific region is another notable opportunity for the Asia-Pacific microscopy market. Precise defect inspection and quality control at the nanoscale are critical for producing advanced chips and electronic components. According to the Semiconductor Industry Association, the Asia Pacific region accounts for over 75% of global semiconductor production, with major hubs in Taiwan, South Korea, and China. This dominance drives demand for high-resolution scanning electron microscopes and atomic force microscopes. According to the Ministry of Economy, Trade and Industry in Japan, the need for advanced metrology tools is emphasized to support next-generation chip fabrication processes. Manufacturers require instruments capable of detecting defects smaller than 5 nanometers to ensure yield and performance. The rise of electric vehicles and 5G technology further increases the complexity of electronic components, necessitating more sophisticated inspection capabilities. Industrial players are investing in automated optical inspection systems integrated with microscopy for real-time quality assurance. This industrial demand provides a stable and growing revenue stream for microscopy manufacturers beyond the life sciences sector.
MARKET CHALLENGES
Fragmented Regulatory Landscape
Navigating the diverse and fragmented regulatory frameworks for medical devices and scientific instruments is a significant challenge to the microscopy market in the Asia Pacific region. Each country has distinct approval processes, safety standards, and import regulations, creating complexity for multinational manufacturers. The Association of Southeast Asian Nations has made progress in harmonizing medical device regulations, but significant differences remain among member states. According to the National Medical Products Administration in China, extensive clinical data and local testing are required for diagnostic microscopy systems, delaying market entry. According to the Therapeutic Goods Administration in Australia, stringent quality standards are maintained that differ from those in neighboring Asian countries. These varying requirements increase compliance costs and extend time to market for new products. Small and medium enterprises often lack the resources to manage multiple regulatory submissions effectively. Changes in trade policies and tariffs can further disrupt supply chains and pricing strategies. The lack of mutual recognition agreements means that approvals in one country do not automatically apply to others. This regulatory fragmentation hinders the efficient distribution of advanced microscopy technologies across the region. Manufacturers must maintain dedicated regulatory affairs teams for each market, adding to operational overhead.
Infrastructure Limitations in Rural Areas
The inadequate infrastructure in rural and remote areas of the Asia Pacific region is another major challenge to the equitable distribution and effective use of microscopy technologies. Reliable electricity, internet connectivity, and climate-controlled environments are essential for the operation of sensitive microscopy equipment. According to the Asian Development Bank, over 200 million people in the region still lack access to reliable electricity, particularly in rural parts of South and Southeast Asia. This instability can damage sensitive electronic components and compromise image quality. Poor internet connectivity hinders the implementation of digital pathology and cloud-based image analysis solutions. According to the World Health Organization, many rural health centers lack basic laboratory infrastructure, let alone advanced microscopy capabilities. Transportation challenges make it difficult to deliver reagents and maintain equipment in remote locations. These logistical barriers limit the reach of modern diagnostic services to the populations that often need them most. Governments face difficulties in allocating resources for infrastructure development in scattered rural communities. This disparity creates a two-tier system where advanced microscopy is available only in urban centers. Addressing these infrastructure gaps requires coordinated efforts beyond the scope of individual manufacturers.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Product, Type, Application, End User, and Country. |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered | India, China, Japan, South Korea, Australia, New Zealand, Thailand, Malaysia, Vietnam, Philippines, Indonesia, Singapore, and the rest of APAC. |
| Market Leaders Profiled | Carl Zeiss, Danaher, Thermo Fisher, Nikon, Bruker Corporation, Olympus, Oxford Instruments, JEOL, Hitachi High-Technologies, Keyence, Vision Engineering, and Helmut Hund. |
SEGMENTAL ANALYSIS
By Product Insights
The microscopes segment led the market by holding 60.6% of the regional market share in 2025 due to its fundamental role as the primary imaging instrument across life sciences, materials science, and industrial applications. The dominance of the microscopes segment is primarily driven by their status as indispensable tools for basic and applied scientific research across the Asia Pacific region. Universities and government-funded research institutes prioritize the acquisition of high-resolution imaging systems to support breakthroughs in biology and nanotechnology. According to the United Nations Educational, Scientific and Cultural Organization, gross domestic expenditure on research and development in East Asia has exceeded 2.5% of GDP, with a significant portion allocated to laboratory instrumentation. This sustained investment ensures continuous procurement of advanced microscope systems. The Chinese Academy of Sciences operates over 100 national key laboratories that require state-of-the-art microscopy for cellular and molecular studies. These facilities drive demand for confocal and super-resolution microscopes capable of visualizing subcellular structures. Researchers rely on these instruments to validate hypotheses and publish findings in high-impact journals. The competitive nature of global science pushes institutions to upgrade their equipment regularly. This foundational need for visualization capabilities secures the leading position of microscopes in the product landscape.
However, the accessories segment is anticipated to record a healthy CAGR of 7.07% over the forecast period in the Asia-Pacific microscopy market owing to the increasing adoption of digital cameras, image analysis software, and automated stages that enhance the functionality of base microscope units. Researchers and clinicians are transitioning from manual observation to quantitative digital analysis, requiring specialized hardware and software add-ons. According to the Journal of Microscopy, the integration of artificial intelligence algorithms for image processing has increased the demand for high-resolution cameras and compatible computing interfaces by 30% in recent years. These accessories enable automated cell counting, tissue segmentation, and 3D reconstruction, which are essential for modern research workflows. Laboratories in South Korea and Japan are upgrading existing microscope bodies with digital modules to leverage AI capabilities without replacing entire systems. This modular approach offers a cost-effective way to enhance performance. The need for data storage and management solutions also drives sales of external hard drives and cloud connectivity kits. Manufacturers are focusing on developing plug-and-play accessories that simplify digital transformation. This trend toward digitization sustains the high growth rate of the accessories segment.
By Type Insights
The optical microscope segment led the market with 59.7% of the Asia-Pacific microscopy market share in 2025. The leadership of the optical microscope segment is primarily attributed to its extensive use in educational institutions and routine clinical laboratories across the Asia-Pacific region. Light microscopes are the standard tool for teaching biology and conducting basic pathological examinations. According to the Ministry of Education in China, all secondary schools are mandated to possess basic laboratory equipment, including optical microscopes, to support science curricula. This policy ensures a consistent baseline demand for millions of units annually. In clinical settings, optical microscopes remain the first line of defense for diagnosing blood disorders and parasitic infections. According to the Southeast Asian Federation of Laboratory Medicine, over 80% of diagnostic tests in regional hospitals rely on light microscopy for initial screening. The ease of use and low operational cost make optical microscopes accessible even in resource-limited settings. They do not require vacuum systems or complex maintenance like electron microscopes. This practicality ensures their continued dominance in high-volume applications. The sheer number of students and patients served by these instruments solidifies their market leadership.
However, the electron microscope segment is experiencing the fastest growth and is predicted to register a CAGR of 10.5% over the forecast period in the Asia-Pacific microscopy market owing to the booming semiconductor industry in Asia-Pacific, which requires atomic-level imaging for chip design and failure analysis. As transistor sizes shrink below 5 nanometers, optical microscopy reaches its physical limits, necessitating the use of scanning and transmission electron microscopes. According to the Semiconductor Industry Association, the Asia Pacific region produces over 75% of the world’s semiconductors, creating immense demand for high-resolution inspection tools. Companies like TSMC in Taiwan and Samsung in South Korea invest billions in electron microscopy facilities to ensure yield and performance. These instruments are critical for identifying defects that can compromise chip functionality. The push toward 3D stacking and advanced packaging technologies further increases the complexity of imaging requirements. Electron microscopes provide the necessary depth of field and resolution to visualize these intricate structures. Government subsidies for semiconductor self-sufficiency in China and India also drive procurement of these expensive instruments. This industrial imperative ensures sustained high growth for the electron microscope segment.
COUNTRY LEVEL ANALYSIS
China Microscopy Market Analysis
China dominated the market by accounting for the highest share of the Asia-Pacific microscopy market in 2025 due to its massive manufacturing base, extensive research infrastructure, and government support for scientific innovation. The country is a global leader in semiconductor and electronics production, creating huge demand for industrial microscopy. According to the Ministry of Science and Technology, R&D spending has grown by over 10% annually, fueling procurement of advanced instruments. Domestic manufacturers are emerging as competitive players in the optical microscope segment. The Belt and Road Initiative facilitates technology exchange and equipment export. Urbanization and healthcare expansion drive demand for clinical microscopy in hospitals. Regulatory reforms are improving the approval process for imported medical devices. The large student population ensures steady demand for educational microscopes. These factors combine to maintain China’s dominant position in the regional market.
Japan Microscopy Market Analysis
Japan is expected to maintain steady market development over the next few years, heavily influenced by high-precision manufacturing expertise, advanced corporate R&D, and an aging demographic driving medical imaging needs. Japan represents a mature and technologically advanced market for microscopy, characterized by high-precision manufacturing and strong domestic brands. The country is home to leading microscope manufacturers like Nikon and Olympus, which drive innovation and export. According to the Ministry of Economy, Trade and Industry, the development of next-generation imaging technologies for robotics and healthcare is actively supported. An aging population increases demand for diagnostic microscopy in pathology and geriatrics. Research institutes focus on nanotechnology and materials science, requiring high-end electron microscopes. Strict quality standards in automotive and electronics industries sustain industrial demand. The market is driven by replacement and upgrades rather than new installations. Collaboration between academia and industry fosters continuous improvement. These dynamics sustain Japan’s leadership in high-value microscopy segments.
South Korea Microscopy Market Analysis
South Korea is anticipated to record dynamic market growth over the next few years, supported by its world-leading semiconductor and display manufacturing sectors and proactive digital healthcare initiatives. South Korea features a dynamic microscopy market driven by its world-leading semiconductor and display industries. Companies like Samsung and LG require advanced electron microscopy for chip and panel inspection. The government invests heavily in R&D to maintain technological leadership. The Korea Basic Science Institute operates central facilities with state-of-the-art microscopes for public use. Biomedical research is expanding, driving demand for confocal and fluorescence systems. The healthcare sector is adopting digital pathology to improve diagnostic efficiency. Strong intellectual property protection encourages innovation. The market is characterized by high adoption of the latest technologies. These factors make South Korea a key hub for premium microscopy solutions.
India Microscopy Market Analysis
India is projected to witness significant market growth in the coming years, propelled by an expanding generic pharmaceutical industry, rising healthcare infrastructure investments, and government-backed biotechnology initiatives. India holds a significant and rapidly growing position in the Asia Pacific microscopy market, driven by its expanding pharmaceutical industry and improving healthcare infrastructure. The country is a major producer of generic drugs, requiring quality control microscopy. According to the Department of Biotechnology, research projects that involve advanced imaging are funded extensively. Medical education expansion drives demand for optical microscopes in colleges. Government initiatives like Ayushman Bharat aim to improve rural healthcare access, increasing demand for basic diagnostic tools. Local manufacturing of affordable microscopes is growing. The IT sector supports the development of digital pathology software. Price sensitivity favors cost-effective solutions. These elements position India as a high-growth volume market.
Australia is poised for steady market expansion over the next few years, sustained by robust academic research grants, strict regulatory standards, and growing adoption of digital telepathology solutions. Australia maintains a sophisticated microscopy market driven by strong research funding and high healthcare standards. According to the National Health and Medical Research Council, biomedical research requiring advanced imaging is heavily supported. Universities collaborate with international partners on large-scale projects. The mining and resources sector uses microscopy for geological analysis. Strict regulatory oversight ensures high-quality imports. The market is dominated by premium brands due to high purchasing power. Telepathology is gaining traction in remote areas. Environmental research drives demand for specialized microscopy. These factors sustain Australia’s position as a high-value market.
COMPETITIVE LANDSCAPE
The competition in the Asia Pacific microscopy market is characterized by the presence of established global leaders and emerging domestic manufacturers. International companies dominate the high-end segment with advanced electron and super-resolution microscopes, leveraging their technological superiority and brand reputation. Local firms compete primarily on price and accessibility, offering cost-effective optical microscopes for educational and routine clinical use. The market sees intense rivalry in countries like China and Japan, where domestic brands have gained significant traction through government support and innovation. Companies differentiate themselves through superior after-sales service, comprehensive training programs, and integrated software solutions. Strategic alliances with research institutions and hospitals are crucial for securing long-term contracts and building credibility. The fragmented regulatory landscape across Asian nations creates barriers to entry, favoring companies with robust compliance capabilities. Innovation in digital pathology and artificial intelligence integration is key to retaining customer loyalty in the research and healthcare sectors. Continuous investment in local manufacturing and distribution networks is essential for sustaining growth and overcoming logistical challenges in this diverse and rapidly evolving region.
KEY MARKET PLAYERS
The leading companies operating in the Asia Pacific microscopy market include:
- Carl Zeiss
- Danaher
- Thermo Fisher Scientific
- Nikon
- Bruker Corporation
- Olympus
- Oxford Instruments
- JEOL
- Hitachi High-Technologies
- Keyence
- Vision Engineering
- Helmut Hund
TOP PLAYERS IN THE MARKET
- Olympus Corporation contributes significantly to the Asia Pacific microscopy market through its comprehensive portfolio of optical and digital imaging systems. The company focuses on delivering high-resolution solutions for life sciences and industrial applications. Recently, Olympus expanded its manufacturing capabilities in Japan to meet the rising demand for advanced endoscopes and microscopes. This expansion strengthens its position by ensuring consistent supply and faster delivery times. They also collaborate with research institutions in China and South Korea to develop customized imaging protocols. These partnerships enhance product relevance and user adoption. Their commitment to innovation drives the integration of artificial intelligence into diagnostic workflows. This technological advancement improves accuracy and efficiency for healthcare professionals across the region.
- Nikon Corporation plays a vital role in the market by providing precision optical instruments and semiconductor inspection tools. Their products are widely used in academic research and high-tech manufacturing sectors. Nikon recently launched new super-resolution microscope systems tailored for nanotechnology research in Singapore and Australia. This innovation addresses the growing need for atomic-level imaging in materials science. The company also invests in training programs for engineers and scientists to maximize instrument utility. These initiatives build strong customer loyalty and technical expertise. Nikon’s focus on quality and reliability maintains its reputation among industrial users. Their strategic alliances with local distributors improve market penetration in emerging economies.
- Shimadzu Corporation supports the Asia Pacific microscopy market with its analytical instruments and electron microscopy solutions. The company emphasizes robust performance and user-friendly interfaces for diverse applications. Shimadzu recently introduced compact electron microscopes designed for small laboratories and educational institutions in Southeast Asia. This product launch expands access to advanced imaging technologies in resource-constrained settings. They also partner with government agencies to support public health diagnostics and environmental monitoring. These collaborations increase brand visibility and trust in the public sector. Shimadzu’s dedication to affordability and durability appeals to a broad customer base. Their extensive service network ensures timely maintenance and support across the region.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the Asia Pacific microscopy market employ strategic localization of products to meet specific regional regulatory and operational requirements. Companies frequently invest in research and development centers within major markets like China and India to accelerate innovation and reduce time to market. This approach allows for customization of features based on local user feedback and preferences. Another prevalent strategy involves forming partnerships with local distributors and system integrators to enhance supply chain efficiency and after-sales support. Firms focus on offering comprehensive training and technical assistance to address the shortage of skilled operators in the region. Acquisitions of specialized software companies enable manufacturers to integrate advanced image analysis and artificial intelligence capabilities into their hardware. Furthermore, participants actively engage in academic collaborations to establish their instruments as industry standards in research publications. These combined strategies enable companies to maintain competitive advantage while navigating the diverse and complex landscape of the Asia Pacific market.
MARKET SEGMENTATION
This Asia Pacific microscopy market research report is segmented and sub-segmented into the following categories.
By Product
- Microscopes
- Accessories
By Type
- Optical Microscope
- Electron Microscope
- AFM
- STM
- NSOM
By Application
- Semiconductor
- Nanotechnology
- Electronics
By End User
- Industrial
- Research Institutes
- Blood Bank
By Country
- India
- China
- Japan
- South Korea
- Australia
- New Zealand
- Thailand
- Malaysia
- Vietnam
- Philippines
- Indonesia
- Singapore
- Rest Of APAC