- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$9.16 BnMarket Estimate, 2026
$9.78 BnMarket Forecast, 2034
$16.48 BnCAGR, 2026–2034
6.74%Executive Summary: Asia Pacific Refrigerant Market
- Market Scope: Overview of the Asia Pacific refrigerant market outlining chemical types, primary cooling applications, country-level dynamics, and major industry competitors.
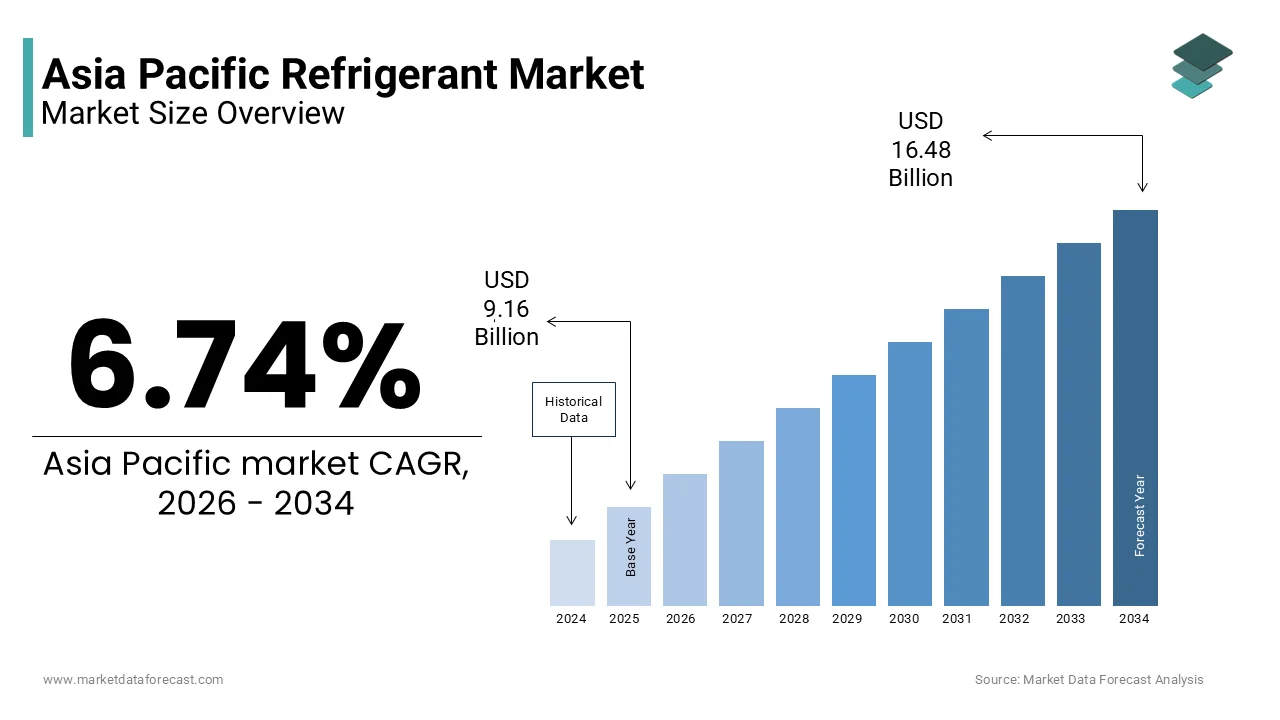
- Market Valuation: Valued at USD 9.16 billion in 2025, reaching USD 9.78 billion in 2026, and projected to expand to USD 16.48 billion by 2034, registering a steady CAGR of 6.74%.
- Primary Growth Drivers: Rising demand for cooling solutions in automobiles and food products, improving living standards, rapid urbanization, and higher disposable salaries across emerging nations (e.g., China, India, Malaysia, Indonesia).
Key Market Segment Metrics
| Category | Leading Segment Position | Transition / Core Focus Segment |
|---|---|---|
| By Type | Hydrocarbons (accounted for the major historical share due to heavy use in refrigeration and AC devices) | HFOs, Propane, Ammonia, Isobutane, and CO2 (gaining momentum as HCFCs and traditional fluorocarbons face phase-out targets by 2040) |
| By Application | Air Conditioners (estimated to account for the highest revenue share) | Large-scale Refrigerators, Standard Refrigerators, Chillers, and Heat Pumps |
| Key Countries | China, India, Korea, Japan, and Australia (fueled by large-scale investments and rising energy demands) | Developing economies across Southeast Asia (Malaysia, Indonesia) |
Major Market Players & Market Structure
Market Structure: Competitive regional landscape comprising major global chemical enterprises and specialized domestic producers transitioning toward eco-friendly, low-environment-impact cooling alternatives.
Key Companies: Arkema, The Linde Group, Honeywell International Inc., Asahi Glass Co., Sinochem Group, HyChill, Hess Corporation, Airgas Inc., A-Gas International, and Dongyue Group.
 Download Free Sample Report
Asia Pacific Refrigerant Market Size
The Asia Pacific refrigerant market size was valued at USD 9.16 billion in 2025 and is projected to reach USD 16.48 billion by 2034 from USD 9.78 billion in 2026, growing at a CAGR of 6.74%.
A refrigerant is a specialised chemical fluid or compound used inside air conditioners, refrigerators, and heat pumps to transfer heat from one place to another. This market includes hydrofluorocarbons, hydrochlorofluorocarbons and emerging natural refrigerants essential for air conditioning, refrigeration and heat pump applications in countries like China, India and Japan. According to sources, the Asia-Pacific region is a critical growth market for refrigerants due to rapid urbanisation, rising temperatures, and a robust HVAC manufacturing base. As per the International Energy Agency, the stock of air conditioners in Southeast Asia is projected to triple by 2035–2040, which will significantly drive up electricity consumption. This surge in cooling requirements directly correlates with increased refrigerant volumes needed for new installations and maintenance services. Manufacturers are increasingly shifting toward low global warming potential alternatives to comply with the Kigali Amendment mandates. The automotive sector in South Korea and Thailand further drives demand through vehicle air conditioning systems. Regulatory bodies in Australia and New Zealand enforce strict leak detection protocols, which influence product formulation and handling practices. The transition from high-impact substances to eco-friendly options creates both technical challenges and innovation opportunities for industry stakeholders. This dynamic landscape positions the Asia Pacific refrigerant market at the forefront of global sustainability efforts in the HVACR industry.
MARKET DRIVERS
Rapid Urbanization and Rising Demand For Air Conditioning Systems Fuel Growth
Rapid urbanisation across the region directly fuels the demand for air conditioning systems, which are a key driver of the Asia Pacific refrigerant market. According to the Asian Development Bank, the urban population in Asia and the Pacific is projected to reach an estimated 2.5 billion people by 2030, which will continue to drive significant infrastructure demand. Higher density living conditions and increasing disposable incomes enable households in countries like Indonesia, Vietnam, and the Philippines to purchase air conditioning units for the first time. As per sources, electricity requirements linked to space cooling systems within rapidly growing tropical urban hubs have historically outpaced general utility grid expansions. Each new air conditioning unit requires a specific charge of refrigerant, thereby expanding the total addressable market for these chemicals. Commercial real estate development in major cities such as Shanghai, Mumbai, and Bangkok further amplifies demand for large-scale chillers and centralised cooling systems. These industrial applications consume substantial volumes of refrigerants for initial charging and ongoing maintenance. The harsh climatic conditions in many parts of the region make cooling a necessity rather than a luxury, ensuring consistent demand regardless of economic fluctuations. Manufacturers respond by scaling up production capacities to meet this surging requirement. This demographic and infrastructural trend underpins the long term growth trajectory of the refrigerant market in the region.
Stringent Environmental Regulations Under The Kigali Amendment Accelerate Transition To Low GWP Alternatives
Stringent environmental regulations under the Kigali Amendment accelerate the transition to low global warming potential refrigerants, which drive innovation and replacement cycles in the Asia Pacific market. According to the Kigali Amendment to the Montreal Protocol, developing nations (including those in the Asia-Pacific region) have committed to phasing down hydrofluorocarbon consumption by 80% to 85% by 2045 or 2047 compared to their baseline levels. This mandate forces manufacturers and end users to phase out high global warming potential substances such as R404A and R134a in favour of newer alternatives. The Ministry of Ecology and Environment in China implemented strict quotas on hydrofluorocarbon production starting in 2024, which immediately impacted supply dynamics and pricing structures. Companies must invest in research and development to formulate compliant products that maintain efficiency while meeting safety standards. The Japanese Ministry of the Environment provides subsidies for businesses adopting natural refrigerants, encouraging faster adoption rates. This regulatory pressure creates a forced upgrade cycle where older equipment is replaced with newer models using eco-friendly refrigerants. Service technicians require retraining to handle flammable or high-pressure alternatives safely. The legal imperative ensures that market participants cannot delay the transition, providing a clear roadmap for product evolution. This policy-driven driver guarantees sustained demand for next-generation refrigerant technologies.
MARKET RESTRAINTS
High Flammability and Safety Concerns Associated With Next Generation Refrigerants Limit Adoption
High flammability and safety concerns associated with next-generation refrigerants significantly limit their widespread adoption in the Asia Pacific market. According to the International Institute of Refrigeration, many low global warming potential alternatives such as hydrocarbons and some hydrofluoroolefins are classified as mildly or highly flammable, posing risks in densely populated urban areas. Building codes in countries like Singapore and Malaysia often restrict the use of flammable refrigerants in high-rise residential complexes due to fire safety regulations. As per sources, transitioning to alternative refrigeration setups often introduces specialised mechanical layout requirements and advanced fluid monitoring protocols that alter baseline procurement costs. According to studies, improper management of highly volatile operational elements introduces workforce safety liabilities that influence technology uptake rates. Training gaps among technicians in developing nations exacerbate these safety risks as proper protocols are not always followed. Insurance premiums for facilities using flammable refrigerants may be higher, discouraging commercial adoption. Consumers remain sceptical about the safety of new chemical formulations, preferring familiar albeit less environmentally friendly options. Manufacturers face additional testing and certification hurdles to prove the safety of their products in various applications. These safety barriers slow down the replacement rate of legacy systems. The perceived risk acts as a psychological and regulatory brake on market expansion.
High Initial Costs Of Retrofitting And Equipment Modification Restrain Market Penetration
High initial costs of retrofitting existing equipment and modifying new systems to accommodate alternative refrigerants restrain penetration in the Asia Pacific market. According to studies, modifying industrial HVAC infrastructure to support low global warming potential compounds involves significant capital expenditure due to structural adjustments and compound-specific lubricants. Many small and medium enterprises in countries like India and Thailand operate on tight margins and cannot afford these capital expenditures without financial incentives. As per research, capital allocation barriers for eco-efficient plant modifications often restrict immediate commercial adoption of environmentally friendly heating and cooling mechanisms. Older infrastructure often requires complete replacement rather than simple retrofitting, which is prohibitively expensive for many end users. Supply chain disruptions for specialised components further drive up prices and delay projects. The complexity of integrating new refrigerants into existing control systems necessitates expert consultation, adding to labour costs. Price-sensitive consumers in emerging markets often opt to repair old inefficient units rather than replace them with compliant ones. This behaviour extends the lifecycle of high-impact refrigerants, contrary to regulatory goals. The economic burden of transition remains a significant barrier for widespread adoption. Financial constraints thus act as a persistent restraint on market growth.
MARKET OPPORTUNITIES
Expansion Of Cold Chain Infrastructure For Food And Pharmaceutical Sectors Presents Growth Potential
The expansion of cold chain infrastructure for food and pharmaceutical sectors offers substantial growth opportunities for the Asia Pacific refrigerant market. According to research, agricultural supply chain gaps stemming from limited post-harvest cold storage capacity across developing markets prompt public and private logistics network investments. The Indian government launched initiatives to build thousands of new cold storage units requiring significant volumes of industrial refrigerants for ammonia- and carbon dioxide-based systems. Similarly, the pharmaceutical industry in China and South Korea is expanding vaccine and biologics storage capabilities, which demand precise temperature control using specialised refrigerants. The World Health Organization emphasizes the importance of robust cold chains for healthcare delivery, driving demand for reliable cooling solutions. Emerging technologies in cascade systems allow for the use of natural refrigerants in large-scale warehouses, offering an eco-friendly alternative. Logistics companies are upgrading their fleets with refrigerated trucks that use efficient and compliant refrigerants to meet international export standards. This infrastructural boom creates a steady stream of demand for both initial charging and maintenance services. Partnerships between refrigerant suppliers and cold chain operators can lead to long term contracts. The focus on food security and public health ensures sustained investment in this sector. This opportunity allows market players to diversify beyond traditional residential and commercial air conditioning segments.
Growing Automotive Industry In Southeast Asia Drives Demand For Mobile Air Conditioning Refrigerants
The growing automotive industry in Southeast Asia propels significant demand for mobile air conditioning refrigerants, which create a lucrative opportunity for participants in the Asia Pacific refrigerant market. According to studies, the expansion of regional automotive production networks highlights a concentrated scaling of assembly operations within key Southeast Asian automotive corridors. Modern vehicles increasingly feature advanced climate control systems that require high-efficiency, low-global-warming-potential refrigerants such as R1234yf to comply with global emissions standards. The Society of Automotive Engineers highlights that electric vehicles require specialised thermal management systems which use novel refrigerant blends to optimise battery performance and cabin comfort. As electric vehicle adoption rises in countries like China and Japan, the demand for these specialised fluids will surge. Automakers are seeking suppliers who can provide consistent quality and regulatory compliance for their global supply chains. Aftermarket services for vehicle air conditioning maintenance also contribute to recurring revenue streams. The trend toward larger vehicles such as SUVs with bigger cabin volumes increases the total refrigerant charge per unit. Strategic partnerships with original equipment manufacturers can secure long term supply agreements. This sector offers high volume potential with stringent quality requirements. The shift toward electrification further expands the application scope for advanced thermal management fluids.
MARKET CHALLENGES
Technical Complexity and Compatibility Issues With Existing Infrastructure Pose Significant Hurdles
Technical complexity and compatibility issues with existing infrastructure are significant hurdles for the adoption of new options in the Asia Pacific refrigerant market. According to the American Society of Heating, Refrigerating and Air-Conditioning Engineers, many low global warming potential refrigerants operate at higher pressures or require different lubricants than traditional substances, making direct drop-in replacements impossible. Older compressors and heat exchangers may fail when exposed to new chemical formulations, leading to costly repairs and system failures. As per studies, continuous exposure to synthetic chemical formulations can contribute to underlying material degradation in fluid handling hardware if preventative engineering practices are omitted. Service technicians in rural areas of countries like Indonesia and the Philippines often lack the diagnostic tools and training to identify these compatibility issues. This knowledge gap leads to improper installations and reduced system efficiency, undermining consumer confidence. Manufacturers must provide extensive technical support and detailed guidelines to mitigate these risks. The need for specialised seals and gaskets adds complexity to the supply chain and inventory management. Retrofitting kits are not universally available for all legacy systems, forcing complete replacements. These technical barriers increase the total cost of ownership for end users. The industry faces the challenge of educating the workforce while managing the transition. This operational complexity slows down the pace of market transformation.
Supply Chain Disruptions And Raw Material Volatility Affect Production Stability
Supply chain disruptions and raw material volatility affect production stability for manufacturers in the Asia Pacific refrigerant market. According to sources, macrochemical raw material supply networks face logistics backlogs and input shortages due to regional industrial limits and shifting global trade patterns. As per research, shifting regulatory limits and environmental compliance reviews within major raw chemical production hubs can result in regional supply shifts for downstream manufacturing. According to the World Trade Organisation, a prominent trade dispute between Japan and South Korea involved tight export licensing controls and non-tariff friction on specific industrial chemicals used in technology manufacturing. These fluctuations make it difficult for manufacturers to maintain stable pricing and consistent supply for their customers. Small distributors struggle to manage inventory levels amidst unpredictable lead times, leading to stockouts or excess holding costs. The reliance on a few key suppliers for critical raw materials creates vulnerability to single-point failures. Energy-intensive production processes are also susceptible to power grid instability in developing nations. Manufacturers must invest in diversified sourcing strategies and strategic stockpiling to mitigate these risks. However, these measures increase operational expenses and reduce profit margins. The unpredictability of the supply environment challenges long term planning. This instability remains a persistent challenge for the industry.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 6.74% |
| Segments Covered | By Type, Application, and Region |
| Various Analyses Covered | Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | India, China, Japan, South Korea, Australia, New Zealand, Thailand, Malaysia, Vietnam, Philippines, Indonesia, Singapore, and the Rest of Asia-Pacific |
| Market Leaders Profiled | Daikin Industries, Ltd., The Chemours Company, Honeywell International Inc., Arkema S.A., AGC Inc., Sinochem Group, Dongyue Group Limited, Zhejiang Juhua Co., Ltd., Linde plc, Air Liquide, Navin Fluorine International Limited, Gujarat Fluorochemicals Limited, SRF Limited, Mexichem, and Koura Global. |
SEGMENTAL ANALYSIS
By Type Insights
The HFCs segment remained the largest in 2025 and occupied a commanding share of the Asia Pacific refrigerant market. This prominence of the segment was credited to established infrastructure and widespread compatibility with existing equipment. According to sources, hydrofluorocarbons have historically served as the dominant synthetic working fluids across major regional cooling infrastructure because they allowed a transition away from classic ozone-depleting substances without requiring immediate redesigns of mechanical systems. The extensive network of service technicians and spare parts for HFC-based systems ensures continued usage despite phase-down mandates. The American Society of Heating, Refrigerating and Air-Conditioning Engineers notes that R134a and R410A remain the standard for many automotive and residential applications due to their proven safety and performance records. Manufacturers in China and India continue to produce HFCs at scale to meet the immediate demand for replacements and repairs. The lack of immediate affordable alternatives for certain specialised applications keeps HFCs relevant in niche markets. Supply chain stability for HFC precursors allows for consistent pricing and availability. Regulatory timelines for phase-out extend over several decades, providing a long transition period. Many consumers prefer the familiarity of HFC systems, avoiding the perceived risks of new technologies. This inertia sustains the dominant market share of HFCs. The segment benefits from mature production technologies and economies of scale.
Cost effectiveness compared to emerging alternatives supports the dominance of HFCs in the Asia Pacific refrigerant market. As per studies, the baseline synthesis costs of mature hydrofluorocarbon generations remain economically favourable compared to newer unsaturated fluorinated alternatives due to scaled chemical manufacturing facilities. Price-sensitive markets in Southeast Asia prioritise affordability, making HFCs the preferred choice for mass-market air conditioners and refrigerators. According to research, initial consumer procurement capital represents a primary variable steering air conditioning purchases within highly budget-conscious, developing infrastructure sectors. Service and maintenance for HFC systems are cheaper due to the widespread availability of trained personnel and tools. Flammable alternatives like hydrocarbons require expensive safety modifications and certified installers, increasing the total cost of ownership. High-pressure refrigerants like CO2 need robust components that raise manufacturing expenses. HFCs offer a balanced performance profile that meets most consumer needs without premium pricing. Retailers and distributors prefer stocking HFC products due to their fast turnover and low risk. This economic advantage ensures that HFCs remain the default option for many applications. The segment continues to benefit from legacy demand and repair markets.
The HFOs segment is the fastest-growing in the Asia Pacific refrigerant market owing to regulatory mandates for low global warming potential substances. According to the Kigali Amendment to the Montreal Protocol, developed nations like Japan and South Korea are legally required to gradually reduce their hydrofluorocarbon consumption by 80% to 85% by 2036, rather than delaying this target timeline out to 2047. HFOs such as R1234yf and R1234ze offer ultra-low global warming potential values below 1, making them ideal replacements for high-impact HFCs. As per sources, state-guided industrial catalogues within large manufacturing economies frequently introduce structural preferences or statutory motivations to accelerate the manufacturing adoption of low-carbon alternative materials. Automotive giants in Thailand and India are switching to R1234yf for new vehicle models to meet international export standards. The European Union regulations influence Asian manufacturers who supply global markets, forcing early adoption of HFOs. Research and development investments by chemical companies have improved the purity and stability of HFO products. Safety standards for mildly flammable HFOs are being harmonised across the region, facilitating wider acceptance. The premium pricing of HFOs is offset by their environmental compliance and future-proofing benefits. This regulatory push ensures rapid market penetration. The segment benefits from strong intellectual property protection and innovation.
Superior energy efficiency and performance characteristics drive the growth of HFOs in the Asia Pacific refrigerant market. According to sources, the specialised thermodynamic traits of synthetic blends containing unsaturated fluorinated molecules can alter the continuous system efficiency metrics of certain climate control plants depending on cycle geometry. Consumers and businesses are increasingly aware of lifecycle costs, favouring systems that offer long-term savings despite higher upfront refrigerant prices. According to studies, alternative fluorinated working fluids demonstrate favourable physical properties during phase changes, allowing for optimised internal space configurations within modernised commercial evaporator setups. This efficiency gain is crucial for meeting stringent energy labelling requirements in countries like Australia and Singapore. Data centres in Japan use HFO-based cooling solutions to manage high heat loads efficiently, supporting the digital economy. The compatibility of HFOs with existing lubricants simplifies the transition for some applications. Manufacturers highlight the environmental and economic benefits in marketing campaigns to educate customers. The versatility of HFOs in both mobile and stationary applications expands their market reach. Continuous improvement in formulation enhances their appeal. The segment grows as performance becomes a key differentiator.
By Application Insights
In 2025, the air conditioners segment held the majority share in the Asia Pacific refrigerant market because of the intense tropical climate and rising living standards across the region. According to the International Energy Agency, energy use for air conditioners in Southeast Asia has historically risen significantly, and space cooling is projected to account for almost 19% of the region's electricity consumption within the next two decades. The rapid urbanisation in nations like India and Indonesia has led to a housing boom where air conditioning is considered a standard amenity rather than a luxury item. As per studies, increasing exposure to extreme seasonal heatwaves makes commercial and domestic climate regulation an essential health metric, guiding regional programmatic support for efficient thermal hardware. Each residential split or window unit requires a specific charge of refrigerant, creating a massive cumulative demand volume. Consumer preference for energy-efficient inverter technology further supports the use of advanced refrigerants, which offer better thermodynamic performance. Retail expansion in tier two and tier three cities ensures wider accessibility for middle-class households. The replacement cycle for older, inefficient units also contributes significantly to refrigerant consumption. Manufacturers continuously launch new models with lower global warming potential fluids to meet regulatory standards. This consistent volume demand cements air conditioners as the primary driver of the refrigerant market. The sheer scale of residential installations outweighs other applications in terms of total refrigerant mass required.
Commercial real estate expansion across major Asian metropolises fuels industrial refrigerant consumption within the air conditioner application segment. According to research, infrastructure expansion across major commercial centres in Asia continues to scale up demand for large-capacity central fluid chilling configurations. These facilities utilise chillers and rooftop units that contain substantial quantities of refrigerants for initial charging and ongoing maintenance. The Green Building Council of Australia notes that sustainable building certifications often mandate the use of low global warming potential refrigerants, influencing procurement decisions in developed markets. High-rise buildings in cities like Shanghai and Singapore rely on complex HVAC networks that require specialised refrigerant blends for optimal efficiency. The hospitality sector recovery post pandemic has accelerated renovations and new openings, further boosting demand. Facility managers prioritise reliability and ease of service, which drives the adoption of established refrigerant types with available supply chains. Energy codes in Japan and South Korea enforce strict efficiency standards, pushing the industry toward next-generation fluids. The concentration of economic activity in urban centres ensures steady growth for commercial cooling applications. This sector provides high-value opportunities for premium refrigerant products. The integration of smart building technologies also enhances the precision of refrigerant management.
The heat pumps segment is expanding swiftly within the Asia Pacific refrigerant market due to aggressive government incentives for decarbonization and energy efficiency. According to sources, regional adoption rates for energy-efficient heating equipment have trended upward as part of broader macroeconomic adjustments away from primary fossil fuels. Governments in China and Japan offer substantial subsidies for households and businesses installing air-source and ground-source heat pumps to meet carbon neutrality goals. As per studies, government-led energy transition targets aimed at replacing domestic combustion appliances with electric heat pumps create a corresponding shift in long-term chemical refrigerant demand. These systems typically use larger charges of refrigerants compared to standard air conditioners due to their dual heating and cooling capabilities. The European Union’s influence on global standards encourages Asian manufacturers to adopt eco-friendly refrigerants like R290 and CO2 in heat pump designs. Rising natural gas prices have made electric heat pumps a cost-effective alternative for industrial process heating. The versatility of heat pumps in providing both space heating and domestic hot water appeals to consumers in temperate regions. Regulatory mandates for new buildings to include renewable heating solutions further drive market penetration. This policy support creates a robust growth trajectory for the segment. The shift toward electrification of thermal energy positions heat pumps as a key technology.
Technological advancements in industrial process heating boost the growth of this segment in the Asia Pacific refrigerant market. According to research, industrial fluid heating mechanisms allow major manufacturing installations to recapture thermal waste streams, helping to lower input energy overheads. Companies in South Korea and Thailand are increasingly adopting high-temperature heat pumps to replace steam boilers, aligning with corporate sustainability targets. As per a roadmap cited by the International Energy Agency, high-temperature industrial heat pumps could cover roughly 15% of industrial process heat below 400 °C in light industries by 2030. These systems require specialised high-pressure refrigerants capable of operating at elevated temperatures, such as R1234ze or ammonia blends. Manufacturers are developing compact and efficient units that integrate seamlessly into existing factory infrastructure. The focus on circular economy principles encourages industries to maximise energy reuse through heat pump technology. Training programs for engineers on heat pump design and maintenance are expanding the skilled workforce. The ability to provide precise temperature control enhances product quality in sensitive manufacturing processes. This technical evolution opens new avenues for refrigerant applications beyond traditional comfort cooling. The industrial sector offers high-volume and long term contracts for refrigerant suppliers.
REGIONAL ANALYSIS
India Market Analysis
India is rapidly expanding in the Asia Pacific refrigerant market. This acceleration is fuelled by its massive population and growing cooling needs. As per the India Cooling Action Plan, the country's cooling demand is projected to increase nearly eightfold by 2037–38 compared to the 2017–18 baseline, rather than being an initiative driven under the Ministry of Power. The government’s India Cooling Action Plan promotes the use of energy-efficient and environmentally friendly refrigerants, encouraging the shift from HCFCs to HFCs and eventually HFOs. According to studies, India's local assembly and production lines for domestic climate-control units continue to scale up rapidly, building a substantial consumer base for structural refrigerant chemical applications. The Bureau of Energy Efficiency implements star rating programs that influence the choice of refrigerants based on efficiency metrics. Rural electrification initiatives expand the addressable market for residential cooling appliances. Indian chemical companies are investing in capacity to produce HFCs and explore HFO synthesis to reduce import dependency. The automotive sector also contributes to demand with rising vehicle sales. Regulatory frameworks are evolving to align with global environmental standards. India remains a key growth engine for the regional market.
China Market Analysis
China maintained dominance in the Asia Pacific refrigerants market and accounted for a substantial share in 2025. It served as the central manufacturing hub for global room air conditioner (RAC) systems. In addition, the country controls the majority of regional HFC quotas via strict MEE policies. High market velocity is driven by a massive domestic push toward HFOs and natural CO₂/hydrocarbon systems in supermarkets and industrial sectors. According to the Ministry of Ecology and Environment, China produces over 70 per cent of the world’s hydrofluorocarbons, serving both domestic needs and export markets. The country has implemented strict production quotas under the Kigali Amendment, forcing manufacturers to optimise efficiency and shift toward lower impact substances. Major chemical hubs in Shandong and Zhejiang drive innovation in refrigerant formulations, including HFOs. The booming electric vehicle industry in China demands advanced thermal management fluids, creating new application avenues. Government subsidies for green manufacturing encourage the adoption of natural refrigerants in industrial settings. China’s Belt and Road Initiative facilitates the export of cooling equipment and refrigerants to neighbouring countries. Regulatory enforcement is becoming stricter, ensuring compliance with environmental norms. China continues to set the pace for the regional market dynamics.
Japan Market Analysis
Japan is a highly mature player in the Asia Pacific refrigerant market. The market is known for the early adoption of low-global-warming-potential alternatives. According to the Ministry of the Environment, Japan has successfully phased out most HCFCs and is leading the transition to HFOs and natural refrigerants in commercial and industrial applications. The country’s stringent Fluorocarbon Leakage Prevention Law mandates regular inspections and reporting, driving demand for high-quality and stable refrigerants. Japanese manufacturers like Daikin and Mitsubishi Electric pioneer the development of R32 and CO2-based systems for global export. The ageing infrastructure requires regular maintenance and retrofitting, supporting a steady service market. Consumer awareness of environmental issues is high, influencing purchasing decisions toward eco-friendly products. Research institutions collaborate with industry to develop next-generation refrigerants with zero ozone depletion potential. Japan serves as a hub for innovation and regulatory best practices. The market values precision and reliability in refrigerant performance.
Indonesia Market Analysis
Indonesia is a rising country in the Asia Pacific refrigerant market due to its large population and archipelagic geography. The rapid expansion of e-commerce warehouses and last-mile delivery cooling requires immediate refrigeration expansion. According to the Ministry of Environment and Forestry, Indonesia has committed to reducing HFC consumption under the Kigali Amendment. The fisheries and agriculture sectors require extensive cold chain infrastructure to reduce post-harvest losses, driving industrial refrigerant demand. Urbanisation in Java and Sumatra increases residential air conditioning usage. Local manufacturing of appliances is growing to meet domestic needs. Government subsidies for energy-efficient appliances influence market trends. The challenge of distribution across islands affects supply chain logistics. Indonesia is focusing on building technical capacity for refrigerant management. The market offers significant long term growth potential.
Australia Market Analysis
Australia holds a noteworthy position in the Asia Pacific refrigerant market with a strong focus on environmental sustainability and regulatory compliance. According to the Department of Climate Change, Energy, the Environment and Water, Australia has implemented one of the earliest HFC phase-down schedules in the region, restricting imports and consumption. The country promotes the use of natural refrigerants like ammonia and CO2 in commercial refrigeration and industrial processes. Strict licensing requirements for technicians ensure proper handling and minimise leaks. Consumer preference for energy-efficient air conditioning systems drives the adoption of R32 in residential sectors. The mining and resources sector utilises large-scale cooling systems requiring reliable and safe refrigerants. Government grants support the retrofitting of old equipment with eco-friendly alternatives. Australia serves as a model for regulatory enforcement in the Asia Pacific. The market prioritises long-term environmental impact over short-term costs.
COMPETITIVE LANDSCAPE
Competition in the Asia Pacific refrigerant market is characterized by intense rivalry between global chemical giants and regional manufacturers striving for technological leadership. Established multinational corporations leverage their extensive research capabilities and patent portfolios to dominate the high value segment of low global warming potential refrigerants. Meanwhile local producers compete on price and availability for traditional hydrofluorocarbons serving price sensitive markets in developing nations. Differentiation increasingly hinges on sustainability credentials and regulatory compliance rather than cost alone as governments enforce stricter environmental norms. Supply chain resilience has become a critical competitive factor given recent disruptions in raw material availability. Strategic alliances with equipment manufacturers ensure early adoption of new refrigerant types in consumer appliances. Regulatory complexity across diverse national jurisdictions necessitates significant compliance investments favoring well capitalized participants. The competitive landscape continues evolving as new entrants focus on natural refrigerants challenging synthetic dominance. Success requires balancing innovation with operational efficiency and strong distribution networks. Trust and technical support play crucial roles in retaining customers during the transition to new technologies. This dynamic environment drives continuous improvement and adaptation among market players.
Key Market Players
Some of the key players in the Asia Pacific refrigerant market are
- Daikin Industries, Ltd.
- The Chemours Company
- Honeywell International Inc.
- Arkema S.A.
- AGC Inc.
- Sinochem Group
- Dongyue Group Limited
- Zhejiang Juhua Co., Ltd.
- Linde plc
- Air Liquide
- Navin Fluorine International Limited
- Gujarat Fluorochemicals Limited
- SRF Limited
- Mexichem
- Koura Global
Top Players in the Market
- Honeywell International Inc. is a leading innovator in low global warming potential refrigerants with its Solstice brand widely adopted across the Asia Pacific region. The company actively collaborates with original equipment manufacturers in China and Japan to integrate hydrofluoroolefin technologies into next generation air conditioning and automotive systems. Recently Honeywell expanded its production capacity for R1234yf in Asia to meet surging demand from the electric vehicle sector. This strategic expansion ensures reliable supply for regional automakers transitioning to eco friendly thermal management solutions. The firm also invests heavily in technician training programs to promote safe handling of mildly flammable alternatives. These initiatives reinforce its reputation as a technology leader and trusted partner in sustainable cooling. Honeywell continues to drive regulatory compliance and energy efficiency standards through advanced chemical formulations.
- Chemours Company plays a pivotal role in the Asia Pacific refrigerant market by supplying high quality Opteon and Freon brands to diverse industrial sectors. The company focuses on providing drop in replacements for legacy hydrochlorofluorocarbons helping businesses comply with phase out mandates without costly equipment changes. Chemours recently launched new marketing campaigns in Southeast Asia to educate distributors about the benefits of low global warming potential alternatives. It also strengthened partnerships with local service providers to ensure proper installation and maintenance practices. The firm leverages its global research capabilities to develop customized solutions for specific climatic conditions in tropical regions. These efforts enhance customer loyalty and facilitate smoother transitions to environmentally responsible refrigerants. Chemours remains committed to sustainability and operational excellence in the region.
- Daikin Industries Ltd. is a dominant force in the Asia Pacific refrigerant market leveraging its vertical integration from chemical production to end user equipment manufacturing. The company pioneered the widespread adoption of R32 in residential air conditioners across India and Southeast Asia due to its superior efficiency and lower environmental impact. Daikin recently invested in new fluorine chemical plants in Thailand to secure raw material supply for its growing appliance business. This move reduces dependency on external suppliers and enhances cost competitiveness. The firm also promotes circular economy initiatives by recovering and recycling refrigerants from old units. Daikin’s comprehensive approach combines product innovation with sustainable practices. It continues to set industry benchmarks for performance and environmental stewardship.
Top Strategies Used by Key Market Participants
Key players in the Asia Pacific refrigerant market prioritize research and development to create low global warming potential alternatives that meet stringent regulatory standards. Companies invest heavily in patenting new hydrofluoroolefin formulations to secure intellectual property rights and maintain competitive advantage. Strategic partnerships with original equipment manufacturers enable early integration of novel refrigerants into air conditioning and automotive designs. Vertical integration allows firms to control production costs and ensure supply chain stability amidst raw material volatility. Educational initiatives targeting technicians and distributors help overcome safety concerns associated with flammable alternatives. Geographic expansion into emerging markets like Vietnam and Indonesia captures growth from rising cooling demand. Compliance with international treaties such as the Kigali Amendment guides long term product roadmaps. Digital tools for leak detection and monitoring enhance service offerings and customer retention. These multifaceted strategies collectively strengthen market positioning by addressing technical regulatory and economic challenges within the dynamic Asia Pacific business environment.
MARKET SEGMENTATION
This research report on the Asia Pacific refrigerant market has been segmented and sub-segmented into the following categories.
By Type
- HCFC
- HFC
- HFO
- Propane
- Ammonia
- Isobutane
- CO2
By Application
- Large-scale Refrigerators
- Air Conditioners
- Refrigerators
- Chillers
- Heat Pumps
By Country
- India
- China
- Japan
- South Korea
- Australia
- New Zealand
- Thailand
- Malaysia
- Vietnam
- Philippines
- Indonesia
- Singapore
- Rest of Asia Pacific