- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$11.25 BnMarket Estimate, 2026
$12.87 BnMarket Forecast, 2034
$37.70 BnCAGR, 2026–2034
14.38%Executive Summary: Asia Pacific Sparkling Bottled Water Market
- Market Scope: Overview of the Asia Pacific sparkling bottled water market, detailing product variants, distribution networks, country-level adoption, and competitive positioning.
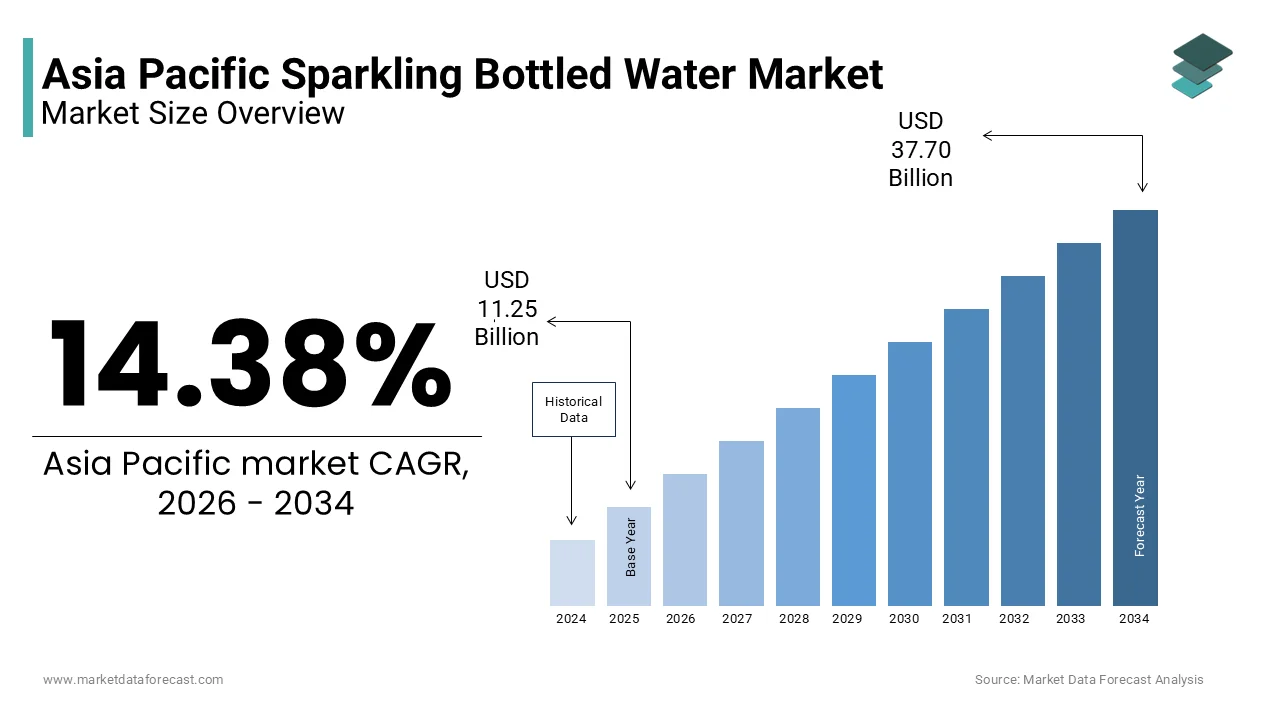
- Market Valuation: Valued at USD 11.25 billion in 2025, reaching USD 12.87 billion in 2026, and projected to scale up to USD 37.70 billion by 2034, registering a strong CAGR of 14.38% (2026–2034).
- Primary Growth Drivers: Rising health consciousness shifting consumers away from sugary sodas and carbonated beverages, growing rates of childhood obesity prompting healthier dietary alternatives, and beverage brands introducing diverse product flavors.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment Position | Core Focus / Alternative Segment |
|---|---|---|
| By Product | Unflavoured Sparkling Bottled Water (accounts for a major market share and serves as a popular social substitute for alcohol or carbonated drinks) | Flavoured Sparkling Bottled Water (appealing to consumers seeking variety and taste) |
| By Distribution Channel | Supermarkets, Convenience Stores, Independent Retailers, and On-Trade Channels | E-commerce and retail expansions driving wide consumer accessibility |
| By Region / Country | Asia-Pacific (fastest-growing regional market driven by changing lifestyles and rising disposable incomes) | China, India, Japan, Australia, Singapore, and South Korea (supported by rapid industrialization and retail infrastructure) |
Major Market Players & Market Structure
Market Structure: Highly competitive consumer beverage market featuring multinational beverage corporations and specialized water brands expanding flavor portfolios and health-centric options.
Key Companies: Danone, Cott, PepsiCo, Nestlé, A.G. Barr, Coca-Cola, Crystal Geyser, Vintage, Tempo Beverages, Sparkling Ice, Dr. Pepper Snapple, and VOSS of Norway.
 Download Free Sample Report
Asia Pacific Sparkling Bottled Water Market Size
The Asia Pacific sparkling bottled water market size was valued at USD 11.25 billion in 2025 and is expected to reach USD 37.70 billion by 2034 from USD 12.87 billion in 2026. The market's promising CAGR for the predicted period is 14.38%.
Sparkling bottled water is sealed drinking water that contains dissolved carbon dioxide gas, which creates fizzy bubbles and a refreshing, tangy taste. This category covers both natural mineral waters with inherent effervescence and artificially carbonated purified waters that cater to evolving consumer palates across diverse regional demographics. According to the World Health Organisation, noncommunicable diseases account for approximately 80% to 90% of all deaths in the Western Pacific region, prompting governments to advocate for sugar reduction, which directly benefits zero-calorie sparkling water alternatives. As per the International Diabetes Federation, approximately 215 million adults in the Western Pacific region and 107 million adults in the South-East Asia region live with diabetes. This massive health demographic represents a major driver for the expanding market of unsweetened hydration options. These epidemiological points underscore the critical role of sparkling bottled water as a functional substitute for sugary sodas in public health strategies. Urbanisation trends in countries like China and India further amplify demand as rising disposable incomes enable premium beverage purchases. According to sources, regulatory frameworks around the world increasingly tax high-sugar drinks, though Australia and Japan have notably resisted or avoided implementing a national sugary beverage levy, leaving manufacturers and consumers to navigate separate fiscal landscape dynamics. This convergence of health awareness, economic growth, and policy support defines the current market landscape.
MARKET DRIVERS
Rising Health Consciousness And Sugar Reduction Initiatives Fuel Demand
Rising health consciousness and government-led sugar reduction initiatives contribute to the expansion of the Asia Pacific sparkling bottled water market. As per the World Health Organisation, over 60% of adults in some Pacific Island nations are obese, driving urgent public health campaigns to replace sugary beverages with zero-calorie alternatives like sparkling water. National dietary guidelines in countries such as Singapore and Thailand explicitly recommend reducing added sugar intake, which positions carbonated water as a compliant and socially acceptable choice. As per the World Health Organisation and medical consensus, high blood pressure and elevated fasting plasma glucose are established as the top metabolic risk factors driving the cardiovascular disease burden in Southeast Asia. Manufacturers leverage this trend by marketing sparkling water as a guilt-free indulgence that satisfies the desire for carbonation without metabolic risks. Retailers allocate more shelf space to these products as consumers actively seek them out during grocery shopping. Corporate wellness programs also promote sparkling water in offices to improve employee health outcomes. This alignment between individual health goals and public policy creates a sustained demand pull. The perception of sparkling water as a sophisticated yet healthy beverage enhances its appeal across age groups. Consequently, health-driven substitution remains the primary engine of market growth.
Premiumization Trends And Lifestyle Aspirations Boost Consumption
Premiumization trends and lifestyle aspirations further propel the growth of the Asia Pacific sparkling bottled water market. This growth is especially visible among affluent urban consumers. According to the Organisation for Economic Co-operation and Development (OECD), the middle-class population in Asia is projected to reach 3.5 billion by 2030, creating a vast demographic willing to pay premiums for perceived quality and status. Consumers in metropolitan hubs like Tokyo, Seoul, and Shanghai associate imported or artisanal sparkling water brands with cosmopolitan lifestyles and discerning taste. As per research, a substantial percentage of millennial consumers in emerging Asian markets increasingly evaluate premium beverage formats as distinct reflections of lifestyle, personal identity, and social signalling. High-end restaurants and hotels curate exclusive sparkling water lists to enhance dining experiences, further elevating the category’s prestige. Limited edition packaging and unique flavour infusions cater to the desire for novelty and exclusivity. Social media amplification of these products reinforces their aspirational value among younger demographics. Brands invest heavily in storytelling about source purity and craftsmanship to justify higher price points. This cultural shift transforms sparkling water from a basic utility to a lifestyle accessory. The willingness to trade up ensures robust revenue growth even if volume increases moderately.
MARKET RESTRAINTS
Environmental Concerns Regarding Single-Use Plastic Packaging Hinder Growth
Environmental concerns regarding single-use plastic packaging significantly hinder the expansion of the Asia Pacific sparkling bottled water market. According to the United Nations Environment Programme, plastic released from Asian rivers represents 86% of the global river plastic inputs into the world's oceans, contributing to intense scrutiny of bottled beverage containers. Consumers in environmentally aware markets like New Zealand and Australia increasingly boycott plastic bottles despite preferring the product inside, creating a paradoxical demand suppression. As per research, Ocean Conservancy data from global beach cleanups frequently highlights plastic beverage bottles as the single most-collected litter item worldwide, directly linking the product format to widespread ecological damage. Municipal bans on single-use plastics in cities like Bangkok and Jakarta focus strictly on restricting single-use shopping bags, cups, and straws at traditional or convenience markets, which restricts specific distribution channels and forces packaging shifts. Negative media coverage of plastic waste erodes brand equity and deters eco-conscious millennials from purchasing. Recycling infrastructure deficits in many developing nations mean most bottles end up in landfills or waterways, exacerbating guilt associated with consumption. Manufacturers face pressure to adopt glass or aluminium alternatives, which increase costs and logistical complexity. This environmental backlash acts as a persistent brake on volume expansion. Sustainable packaging solutions must first achieve scale and affordability. Until then, the market will face ethical headwinds.
Price Sensitivity And Competition From Tap Water Limit Penetration
Price sensitivity and competition from improved tap water infrastructure limit the penetration of sparkling bottled water in price-conscious segments of the Asia Pacific market. As per the World Bank, inflation rates in several Southeast Asian countries exceeded 5% in 2023, squeezing household discretionary spending and making premium beverages vulnerable to trading down. In developed markets like Singapore and Japan, advanced municipal water treatment provides safe and palatable tap water, reducing the functional necessity of bottled alternatives. According to research, a high percentage of urban households in developed Asia-Pacific regions enjoy continuous access to safe, potable tap water, which structurally diminishes the foundational safety rationale for bottled beverage purchases. Home carbonation systems offer a cheaper per-litre alternative to ready-to-drink sparkling water, capturing budget-conscious consumers who still desire effervescence. Street vendors and local eateries often serve free filtered water, undermining the value proposition of paid sparkling options in informal settings. Economic downturns amplify this price elasticity as consumers prioritise essentials over discretionary hydration. Mass market brands struggle to maintain margins while competing against virtually free tap water. This economic reality confines sparkling bottled water to niche or occasional consumption occasions rather than daily habit formation.
MARKET OPPORTUNITIES
Expansion Of Functional And Flavored Variants Creates New Revenue Streams
The expansion of functional and flavoured variants creates significant opportunities for differentiation and revenue growth in the Asia Pacific sparkling bottled water market. According to sources, consumer interest and market demand for functional beverages offering targeted health benefits beyond basic hydration have demonstrated strong annual growth patterns across key Asian markets. Infusing sparkling water with electrolytes, vitamins, adaptogens, or botanical extracts addresses specific wellness needs like immunity, energy or relaxation without adding sugar. As per studies, Chinese consumers demonstrate a strong baseline willingness to buy and pay a premium for functional food and beverage innovations that offer clear health and lifestyle benefits. Flavour innovation using local fruits like yuzu, lychee, or calamansi appeals to regional palates and distinguishes brands from generic international offerings. These variants bridge the gap between plain water and sugary soft drinks, capturing consumers seeking sensory satisfaction with health credentials. Retailers welcome functional SKUs as they command higher margins and drive basket size. Partnerships with wellness influencers validate efficacy claims and accelerate trial. This diversification strategy reduces reliance on commoditised plain sparkling water. It transforms the category into a platform for personalised nutrition and experiential consumption.
Growth of E-commerce and Direct-to-Consumer Channels Enhances Accessibility
The growth of e-commerce and direct-to-consumer channels offers a major opportunity to bypass traditional retail constraints and reach niche audiences in the Asia-Pacific sparkling bottled water market. According to research, the broader Asia-Pacific region commands a dominant share of global online retail and digital commerce, creating a vast foundational digital infrastructure for the distribution of consumer beverage brands. Subscription models allow brands to secure recurring revenue and build loyalty through automated replenishment of heavy, bulky items that consumers prefer not to carry from stores. As per sources, cross-border e-commerce networks offer premium international brands an alternative entry pathway into regional digital retail spaces, minimising the necessity for traditional physical storefront distribution footprints. Digital platforms facilitate targeted marketing based on purchase history and preferences, enabling hyper-personalised recommendations. Direct feedback loops via online reviews inform rapid product iteration and flavour development. Logistics partners specialising in cold chain delivery ensure product integrity for temperature-sensitive variants. This channel democratizes access to niche and premium brands previously confined to elite urban retailers. It empowers small players to compete with incumbents through agility and data-driven engagement. The scalability of digital commerce unlocks latent demand in underserved geographies.
MARKET CHALLENGES
Supply Chain Volatility and Raw Material Sourcing Disrupt Operations
Supply chain volatility and raw material sourcing disruptions remain serious obstacles to operational stability in the Asia-Pacific sparkling bottled water market. According to the Federal Reserve Bank of New York, the Global Supply Chain Pressure Index plummeted to a record low of -1.59 in mid-2023 before returning toward its historical average, indicating that supply disruptions actually abated throughout the year rather than remaining elevated. Fluctuations in the cost of PET resin, aluminium cans, and carbon dioxide directly impact production margins as these inputs constitute a large portion of unit economics. As per studies, extreme weather events linked to climate change have disrupted global agricultural outputs used for natural food components, causing localised ingredient shortages and price spikes for flavoured variants. Reliance on imported glass bottles from limited suppliers creates vulnerability to trade disputes and shipping delays. Just-in-time inventory models prevalent in the region amplify the impact of any disruption, leading to stockouts and lost sales. Currency depreciation in emerging markets further inflates the cost of imported machinery and ingredients. Manufacturers must navigate complex customs regulations across multiple jurisdictions, slowing response times. Building resilient multi-sourced supply chains requires capital investment that strains balance sheets. This operational fragility threatens consistent availability and profitability. Uncertainty makes long-term planning and pricing strategies difficult to execute.
Regulatory Fragmentation And Labeling Compliance Complexity Impede Scalability
Regulatory fragmentation and labelling compliance complexity impede scalable growth across the diverse jurisdictions of the Asia Pacific sparkling bottled water market. According to the World Trade Organisation, each country in the region maintains distinct food safety standards, labelling requirements, and import tariffs, creating a labyrinth of compliance obligations for pan-regional brands. The Codex Alimentarius Commission sets international guidelines, but national authorities in China, Japan, and ASEAN members often impose additional restrictions on additives, health claims, and packaging materials. As per studies, non-tariff measures applied to food and agricultural trade introduce substantial operational premiums due to duplicate testing, localised compliance certifications, and product reformulation requirements. Missteps in labelling can result in costly recalls, fines, or market bans, damaging brand reputation irreparably. Frequent regulatory changes require constant monitoring and adaptation, diverting resources from innovation and marketing. Harmonisation efforts remain slow, leaving companies to manage dozens of unique SKUs for essentially the same product. Small and medium enterprises lack the legal expertise to navigate this complexity, limiting their geographic expansion. Even multinationals face delays launching new products while awaiting approvals. This regulatory mosaic fragments the market and stifles economies of scale. Standardisation would unlock significant efficiency gains but remains elusive.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 14.38% |
| Segments Covered | By Product, Distribution Channel, and Region |
| Various Analyses Covered | Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | India, China, Japan, South Korea, Australia, New Zealand, Thailand, Malaysia, Vietnam, Philippines, Indonesia, Singapore, and the Rest of Asia-Pacific |
| Market Leaders Profiled | Danone, Cott, PepsiCo, Nestlé S.A., A.G. Barr, Coca-Cola, Crystal Geyser, Vintage, Tempo Beverages, Sparkling Ice, Dr. Pepper Snapple, and VOSS of Norway. |
SEGMENTAL ANALYSIS
By Product Insights
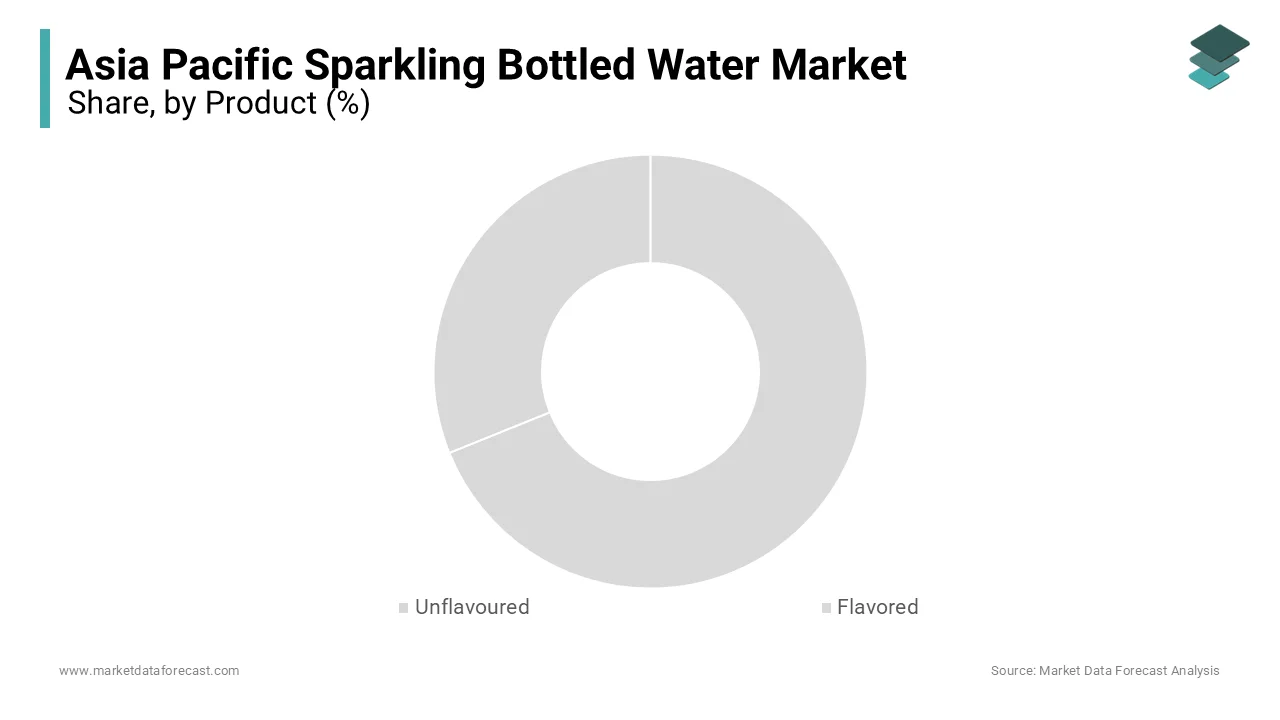
In 2025, the unflavoured segment held the majority share in the Asia Pacific sparkling bottled water market because of a strong consumer preference for natural hydration without artificial additives or sweeteners. As per studies, rising public awareness of noncommunicable diseases has increasingly led health-conscious consumers in urban Asia to seek beverages free from added sugars and artificial ingredients. This health-conscious demographic views unflavoured sparkling water as a pure and safe alternative to sugary sodas and juices. According to the American Dental Association, plain sparkling water is generally safe for teeth and far less erosive than sugar-sweetened beverages or citrus juices, reinforcing its position as an effective alternative to soft drinks. Consumers in countries like Japan and Australia associate unflavoured variants with premium quality and mineral richness often sourced from natural springs. Retailers stock extensive ranges of unflavoured options to cater to this demand for simplicity and transparency. Marketing campaigns emphasise the purity of source and absence of calories, which resonates with fitness enthusiasts and dieters. The versatility of unflavoured water allows it to be consumed at any time of day without palate fatigue. This broad appeal ensures consistent high-volume sales across all demographic segments. The segment benefits from established brand loyalty among consumers who prioritise health over novelty.
Cost efficiency and production simplicity significantly support the dominance of this segment. According to research, manufacturing plain sparkling water typically requires fewer raw inputs and shorter processing runs than flavoured variants, creating tangible operational cost advantages for beverage bottlers. Manufacturers do not need to source expensive natural extracts or synthetic flavourings, which are subject to price volatility and supply chain disruptions. As per sources, lower production and formulation costs enable manufacturers to price unflavoured sparkling waters competitively, broadening their appeal across diverse consumer segments. This affordability is crucial in price-sensitive markets like India and Indonesia, where discretionary spending on beverages is limited. Simplified inventory management reduces waste and improves profit margins for retailers and distributors. The longer shelf life of unflavoured products minimises spoilage risks during transportation and storage. These economic advantages enable brands to invest more in marketing and distribution rather than product development. The segment remains resilient during economic downturns as consumers trade down from premium flavoured options to basic unflavoured versions. This financial stability cements its leadership position.
The flavoured segment is the fastest-growing in the Asia-Pacific sparkling bottled water market due to innovation in localised flavour profiles that appeal to regional tastes. According to studies, beverage manufacturers in Southeast Asia have accelerated launches incorporating regional fruits such as yuzu, lychee, calamansi, and mango to cater to consumer demand for culturally resonant flavours. Consumers seek novel sensory experiences that combine the refreshment of carbonation with familiar and exotic tastes. As per research, younger demographic cohorts across East Asian markets show a pronounced preference for flavoured carbonated beverages over plain options due to higher perceived taste variety and sensory appeal. Brands collaborate with local farmers to source authentic ingredients, creating unique value propositions that differentiate them from global competitors. Limited edition seasonal flavours generate buzz and encourage trial among younger demographics. Social media influencers promote these innovative products, driving viral awareness and demand. The ability to customise sweetness levels using natural stevia or monk fruit appeals to health-conscious buyers who still desire taste. This continuous innovation keeps the category exciting and prevents consumer boredom. The segment captures impulse purchases through attractive packaging and bold flavour claims.
The rising demand for functional beverages with added benefits boosts the expansion of this segment. According to the Global Wellness Institute, the broader wellness market, including healthy food, nutrition, and wellness drinks, has experienced robust double-digit annual expansion across Asia as consumers demand products with benefits beyond basic hydration. Flavoured sparkling waters infused with electrolytes, vitamins, probiotics, or adaptogens address specific wellness needs such as immunity boosting, stress relief or energy enhancement. As per UNICEF and the World Health Organisation, more than 50% of young children and pregnant women in South Asia suffer from micronutrient deficiencies (hidden hunger), motivating parental interest in nutrient-dense and fortified products. Brands leverage these functional claims to justify premium pricing and attract health-focused shoppers. Flavours mask the taste of added nutrients, making them palatable for children and adults alike. Retailers dedicate shelf space to functional SKUs as they drive higher basket values and customer loyalty. Partnerships with healthcare professionals validate efficacy claims and build trust. The convergence of indulgence and nutrition creates a powerful growth driver. This trend transforms sparkling water from a simple thirst quencher into a holistic wellness solution.
By Distribution Channel Insights
The supermarket segment was the largest in 2025 and occupied a commanding share of the Asia-Pacific sparkling bottled water market. This supremacy of the segment was credited to its extensive reach and one-stop shopping convenience for households. According to sources, supermarkets and modern hypermarket chains command a dominant share of packaged food and beverage retail value across urban centres in developed Asian economies. Families prefer purchasing bulk packs of sparkling water during weekly grocery trips to ensure steady supply at home. The World Bank indicates that rising urbanisation has led to the proliferation of large-format retail stores in emerging markets like China and Thailand, expanding access to diverse beverage options. Supermarkets offer wide assortments, including private label and premium international brands, allowing consumers to compare prices and features easily. Promotional activities such as discounts and bundle deals drive volume sales and encourage trial of new products. Cold chain infrastructure in modern supermarkets ensures product quality and freshness, which is critical for carbonated beverages. The trusted environment of established retail chains builds consumer confidence in product safety. This channel benefits from high foot traffic and loyal customer bases. It remains the primary touchpoint for mass market consumption.
Strong bargaining power and superior shelf visibility significantly enhance sales of sparkling bottled water in the supermarket channel across the Asia Pacific region. As per studies, consolidated grocery store corporations leverage massive purchasing power to secure competitive trade concessions, prominent product exposure, and targeted marketing allowances from product manufacturers. According to sources, strategic product placements, eye-level shelf locations, and prominent end-cap configurations significantly elevate product visibility to drive spontaneous consumer grocery purchases. Supermarkets utilise data analytics to optimise inventory and tailor assortments to local preferences, ensuring high turnover rates. Private label sparkling waters offered by major chains provide affordable alternatives that capture price-sensitive shoppers while maintaining retailer margins. Loyalty programs incentivise repeat purchases through points and exclusive offers, building long term customer relationships. The ability to launch new flavours quickly through established distribution networks gives supermarkets a competitive edge. Manufacturers prioritise this channel due to its volume potential and brand-building capabilities. Strategic partnerships with retailers facilitate joint marketing campaigns that boost awareness. This symbiotic relationship sustains the dominance of supermarkets.
The convenience store segment is witnessing rapid expansion in the Asia-Pacific sparkling bottled water market owing to urban lifestyle demands and impulse buying behaviour. According to research, convenience store networks and proximity retail footprints across Southeast Asia have experienced continuous, robust multi-year expansion to support urban consumers seeking quick-consumption refreshment. High-density populations in cities like Tokyo, Seoul, and Bangkok rely on these stores for immediate consumption needs due to limited home storage space. As per sources, a substantial portion of point-of-sale volume inside convenience stores is driven entirely by spontaneous, immediate-need purchases, making product visibility and layout design critical to success. Sparkling water brands invest in chilled cabinets near checkout counters to capture thirsty customers on the go. Extended operating hours and widespread location coverage ensure availability at all times. Young professionals and students frequent these stores for affordable and convenient beverage options. The compact pack sizes suitable for single-serve consumption align with on-the-go lifestyles. This channel captures high-margin sales through premium positioning. The agility of convenience stores allows for rapid adoption of trending flavours.
The integration with digital payment and delivery services enhances the accessibility and growth of this segment. According to studies, digital ecosystem proliferation and high mobile wallet penetration throughout Asia have fundamentally simplified retail point-of-sale interactions, supporting frictionless transaction mechanics at small-format convenience outlets. Quick commerce platforms partner with local convenience stores to deliver sparkling water within minutes, meeting the demand for instant gratification. As per sources, quick-commerce fulfilment models and on-demand delivery apps have triggered substantial sales growth for consumer beverages across major Asian cities, driven by an intense consumer focus on rapid procurement. Digital loyalty apps offer personalised discounts and recommendations, driving repeat visits and higher spend. Real-time inventory tracking ensures popular flavours are always in stock, reducing missed sales opportunities. Social media integration allows brands to promote flash sales and new launches directly to nearby customers. This technological synergy creates a frictionless shopping experience that appeals to digital natives. Convenience stores evolve into micro fulfilment centres for efficient last-mile delivery. This innovation drives sustained growth in the channel.
REGIONAL ANALYSIS
India Market Analysis
India is experiencing the quickest growth in the Asia Pacific sparkling bottled water market. This expansion is driven by rising health awareness and urbanisation. According to the Ministry of Health and Family Welfare, the prevalence of diabetes in India has reached 11 per cent, prompting consumers to seek sugar-free alternatives like sparkling water. Major cities such as Mumbai and Delhi see growing demand for premium imported and local brands in supermarkets and cafes. The Food Safety and Standards Authority of India has streamlined regulations for carbonated beverages, encouraging new entrants. Local manufacturers leverage affordable pricing to penetrate mass markets while international brands target affluent segments. The expansion of modern retail chains facilitates wider distribution. Consumer education campaigns highlight the benefits of hydration without calories. The market is characterised by high growth potential but faces challenges from traditional beverage preferences. Infrastructure improvements support cold chain logistics. India represents a key future growth engine for the industry.
China Market Analysis
China led the Asia Pacific sparkling bottled water market and captured the largest share in 2025. Consumer preferences are rapidly transitioning away from conventional, high-sugar carbonated soft drinks. Driven by domestic brands and major players like Danone Waters China, the sugar-free sparkling category has successfully captured the health-conscious millennial demographic. According to the National Bureau of Statistics, China's core consumption sectors show steady baseline dynamics, with specific beverage categories demonstrating robust volume expansions across younger demographics. Domestic brands like Genki Forest have disrupted the market, with zero-sugar flavoured sparkling waters capturing significant market share. The State Administration for Market Regulation enforces strict labelling standards, ensuring product transparency. E-commerce platforms drive substantial sales through targeted marketing and convenient delivery. Consumers in tier one cities prefer premium imported waters for social status. The government’s Healthy China 2030 initiative supports reduced sugar intake, boosting sparkling water demand. Manufacturing capabilities allow for rapid innovation and cost efficiency. China leads in flavour diversity and packaging innovation. The market is highly competitive and fast-evolving.
Japan Market Analysis
Japan holds a significant position in the Asia Pacific sparkling bottled water market. The country is a mature and sophisticated market, known for high quality standards and diverse product offerings. According to studies, Japan maintains high non-alcoholic beverage consumption patterns, with carbonated and mineralised liquids holding an established share of daily per capita routines. Consumers prefer natural mineral sparkling waters from domestic sources for their perceived health benefits. The Japan Soft Drinks Association reports steady growth in premium and functional variants. Retailers offer extensive selections in vending machines and convenience stores, ensuring ubiquitous availability. Aging population drives demand for easy-to-digest and hydrating beverages. Strict recycling laws promote sustainable packaging practices. Japanese brands lead in technology and flavour refinement. The market values purity and tradition. Japan remains a benchmark for quality in the region.
South Korea Market Analysis
South Korea expands steadily in the Asia Pacific sparkling bottled water market due to strong health trends and digital influence. As per studies, consumer demand for low-calorie and zero-sugar soft drinks has grown rapidly across South Korea, driven by young adults and working individuals prioritising wellness alternatives. Local brands innovate with unique fruit flavours and sleek packaging appealing to young demographics. The Ministry of Food and Drug Safety regulates additives strictly, ensuring safety. Convenience stores and online platforms are primary distribution channels. Social media marketing plays a crucial role in brand building and trend setting. Consumers are willing to pay premiums for aesthetically pleasing and healthy products. The market is responsive to global trends and local tastes. Innovation in functional ingredients drives differentiation. South Korea is a hub for beverage creativity.
Australia Market Analysis
The Australian sparkling bottled water market is highly developed, owing to a distinct consumer demand for sustainable packaging and ethically sourced natural water. According to the Australian Bureau of Statistics, general consumer spending tracking indicates regular shifts in household discretionary categories, with health-focused and non-alcoholic premium beverage segments demonstrating sustained engagement. Consumers prefer locally sourced mineral waters with eco-friendly packaging. The Department of Climate Change, Energy, the Environment and Water promotes recycling initiatives influencing brand strategies. Supermarkets and independent retailers dominate distribution. High awareness of environmental issues drives demand for aluminium cans and glass bottles. Premium brands thrive in urban centres. Regulatory support for clear labelling builds trust. Australia leads in sustainable practices. The market values authenticity and environmental responsibility.
COMPETITIVE LANDSCAPE
Competition in the Asia Pacific sparkling bottled water market is characterized by intense rivalry between global beverage giants and agile local startups. Multinational corporations leverage their established distribution networks and brand recognition to maintain dominance in mainstream retail channels. Meanwhile emerging domestic brands compete on novelty and cultural relevance by introducing unique local flavors and affordable pricing strategies. Differentiation increasingly hinges on health credentials such as zero sugar and added functional ingredients rather than taste alone. Premiumization trends drive competition in the high end segment where provenance and packaging design play crucial roles. Regulatory pressures regarding plastic waste force companies to innovate in sustainable packaging solutions creating new competitive battlegrounds. E commerce platforms lower entry barriers allowing niche players to reach targeted audiences effectively. Strategic alliances with hospitality providers enhance brand visibility and credibility among affluent consumers. Price wars in mass market segments squeeze margins prompting a shift toward value added offerings. Success requires balancing scale with agility and authenticity to meet evolving consumer expectations. This dynamic landscape fosters continuous innovation and adaptation among all market participants.
KEY MARKET PLAYERS
- Danone
- Cott
- PepsiCo
- Nestlé S.A.
- A.G. Barr
- Coca-Cola
- Crystal Geyser
- Vintage
- Tempo Beverages
- Sparkling Ice
- Dr. Pepper Snapple
- VOSS of Norway
Top Players in the Market
- PepsiCo Inc. leverages its extensive distribution network to dominate the Asia Pacific sparkling bottled water market through brands like Bubly and SodaStream. The company focuses on zero sugar formulations to align with regional health trends and regulatory pressures against sugary drinks. Recently PepsiCo expanded its direct to consumer capabilities in Australia and Japan by integrating sparkling water subscriptions into its digital platforms. This move enhances customer loyalty and provides valuable data on consumption patterns. The firm also invests in sustainable packaging initiatives including recycled PET bottles to address environmental concerns. Strategic partnerships with local retailers ensure wide availability in urban centers. PepsiCo continues to innovate with new flavor profiles tailored to Asian palates. These actions strengthen its competitive position and brand relevance.
- The Coca Cola Company maintains a strong presence in the Asia Pacific sparkling bottled water sector with its premium brand Smartwater and Topo Chico. The company emphasizes natural mineral sources and electrolyte enhancement to differentiate its products from standard carbonated waters. Recently Coca Cola launched limited edition flavors in South Korea and China to attract younger demographics seeking novel experiences. It also upgraded manufacturing facilities in Thailand to improve production efficiency and reduce carbon footprint. The firm utilizes its global marketing prowess to position sparkling water as a lifestyle choice rather than just hydration. Collaborations with fitness influencers amplify brand visibility across digital channels. These efforts reinforce its leadership in the premium beverage segment.
- Nestlé S.A. contributes significantly to the market through its Perrier and San Pellegrino brands which are synonymous with premium sparkling water in Asia. The company focuses on high end dining and hospitality channels to build brand prestige and exclusivity. Recently Nestlé introduced eco friendly aluminum cans for its sparkling water range in Singapore and Malaysia to appeal to environmentally conscious consumers. It also partnered with luxury hotels in Japan to offer curated tasting experiences. The firm invests in source protection programs to ensure long term sustainability of its natural springs. Digital campaigns highlight the heritage and purity of its water sources. These strategies enhance brand equity and drive premium pricing power.
Top Strategies Used by Key Market Participants
Key players in the Asia Pacific sparkling bottled water market prioritize product innovation through localized flavor development to cater to diverse regional tastes. Companies invest heavily in research and development to create unique infusions using indigenous fruits such as yuzu lychee and calamansi. Strategic partnerships with e commerce platforms enable direct to consumer sales models that bypass traditional retail constraints. Sustainability initiatives focus on reducing plastic waste by adopting recycled materials and aluminum packaging. Marketing campaigns leverage social media influencers to target health conscious millennials and Gen Z consumers. Expansion into premium hospitality sectors builds brand prestige and drives trial among affluent demographics. Cost optimization through local sourcing and manufacturing enhances competitiveness in price sensitive markets. Regulatory compliance ensures adherence to strict food safety and labeling standards across different jurisdictions. These multifaceted strategies collectively strengthen market positioning by addressing consumer preferences environmental concerns and operational efficiency within the dynamic Asia Pacific business environment.
MARKET SEGMENTATION
This research report on the Asia Pacific sparkling bottled water market has been segmented and sub-segmented into the following categories.
By Product
- unflavoured
- flavored
By Distribution Channel
- supermarkets
- on-trade
- independent retailer
- convenience stores.
By Country
- India
- China
- Japan
- South Korea
- Australia
- New Zealand
- Thailand
- Malaysia
- Vietnam
- Philippines
- Indonesia
- Singapore
- Rest of Asia Pacific