- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$205.3 MnMarket Estimate, 2026
$220.9 MnMarket Forecast, 2034
$395.7 MnCAGR, 2026–2034
7.56%Executive Summary: Asia Pacific Whole Milk Powder Market
- Market Scope: Comprehensive Asia-Pacific whole milk powder market analysis covering product types, application sectors, country-level insights, and dairy industry demand trends.
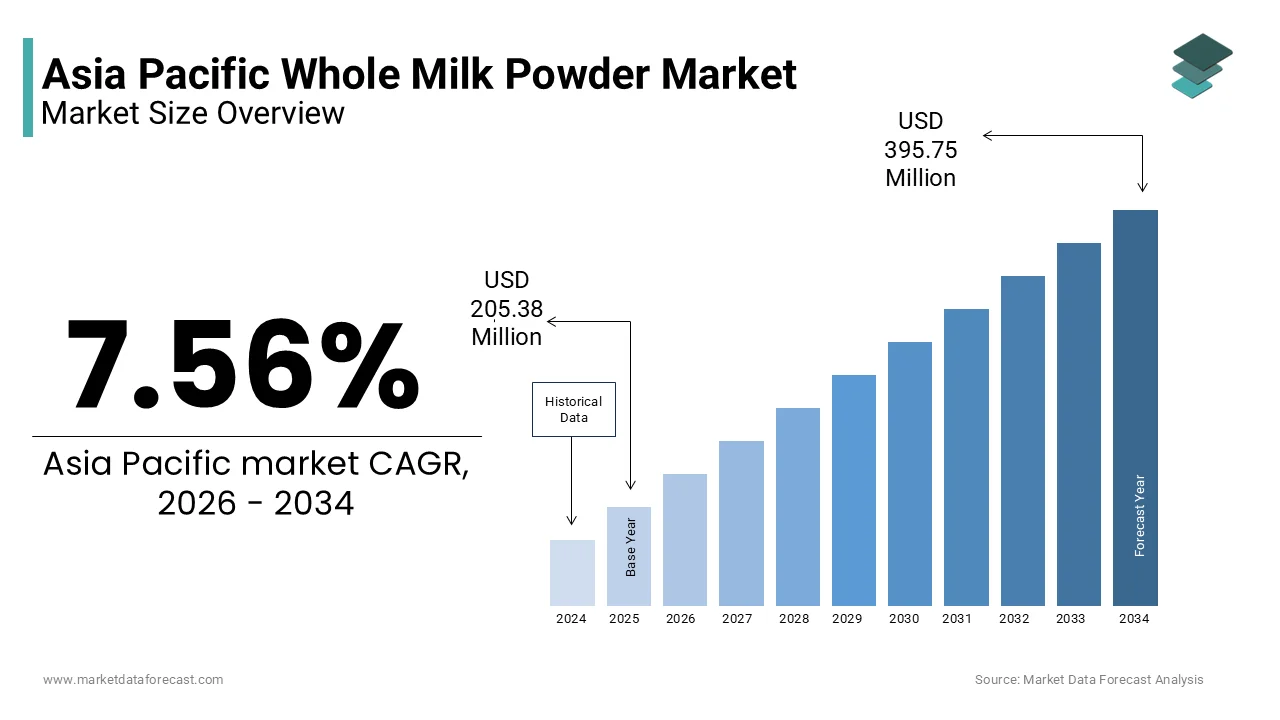
- Market Valuation: Valued at USD 205.38 million (2025), estimated at USD 220.91 million (2026), and projected to reach USD 395.75 million by 2034, registering a robust CAGR of 7.56% (2026–2034).
- Primary Growth Drivers: Rising disposable incomes, shift in consumer diets towards dairy-rich tastes, longer shelf life of milk powder suitable for regions with extreme temperatures, and low transportation and storage costs.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Type | Dry Whole Milk (holding the primary market share as a core alternative to fresh milk) | Dry Dairy Blends & Non-fat Dry Milk (driven by industrial food manufacturing demand) |
| By Application | Infant Formulas & Nutritional Foods (leading application sector supported by rising infant nutrition and health trends) | Confectionaries & Baked Sweets & Savories (expanding rapidly through commercial food processing growth) |
| By Country | China & India (dominating regional consumption and production driven by massive populations and growing distribution channels) | Asia-Pacific Region overall (predicted to grow with the highest CAGR during the forecast period) |
Major Market Players & Market Structure
Market Structure: Highly competitive dairy and food products landscape featuring global multinational corporations competing on brand loyalty, supply chain efficiency, product safety, and extensive regional distribution networks.
Key Companies: Kraft Foods, Belgomilk, Unilever, Nestle, and Friesland Campina.
 Download Free Sample Report
Asia Pacific Whole Milk Powder Market Size
The Asia Pacific whole milk powder market size was valued at USD 205.38 million in 2025 and is projected to reach USD 395.75 million by 2034 from USD 220.91 million in 2026, growing at a CAGR of 7.56%.
Whole milk powder is a dry, shelf-stable powder made by removing almost all the water from pasteurized full-fat milk. This dehydrated dairy product retains essential nutrients while facilitating easier storage and transportation across vast geographical distances in countries like China India and Indonesia. According to the Food and Agriculture Organization of the United Nations (FAO), global milk production reached approximately 930 million tons in 2022 (and reached 944 million tons in 2023), with Asia contributing significantly to consumption growth despite lower per capita yields compared to Western nations. As per studies, powdered milk accounts for a meaningful share of global dairy trade volumes due to its extended shelf life and stability in tropical climates prevalent in Southeast Asia. Urbanization trends drive demand as busy consumers seek convenient nutrition sources that require minimal preparation. Manufacturers utilize whole milk powder in confectionery bakery and infant formula sectors ensuring consistent quality and flavor profiles. Regulatory bodies in Australia and New Zealand enforce strict hygiene standards which enhance consumer trust in exported products. The rising prevalence of lactose intolerance in certain Asian demographics has led to innovations in processing techniques that maintain nutritional integrity. As disposable incomes rise in emerging economies the preference for premium dairy derivatives strengthens market dynamics. This sector remains vital for food security strategies given its role in emergency relief and institutional feeding programs across the region.
MARKET DRIVERS
Rapid Urbanization And Changing Lifestyle Patterns Fuel Convenience Demand
Rapid urbanization across the region accelerates the growth of the Asia Pacific whole milk powder market. This is due to its convenience and ease of storage in compact living spaces. According to the Asian Development Bank (ADB), the urban population in Asia is projected to rise to 55% of the total regional population, or an estimated 2.5 billion people, by 2030, creating a massive consumer base in rapidly expanding cities. Whole milk powder offers a practical solution for households that prioritize quick meal preparation without compromising on nutritional value. As per sources, household expenditure on convenience and processed food products in Southeast Asia has shifted steadily toward ready-to-use ingredients due to rising urban consumer demand. Consumers in metropolitan areas such as Shanghai Mumbai and Jakarta prefer products that reduce daily chores including frequent grocery shopping for perishable items. Retailers respond by stocking various pack sizes of whole milk powder catering to single individuals and small families. The longer shelf life of powdered milk reduces food waste which aligns with growing environmental consciousness among urban dwellers. Additionally the portability of powdered milk makes it ideal for office workers and students who require nutritious snacks on the go. This lifestyle adaptation ensures steady demand regardless of seasonal fluctuations in fresh milk availability. The integration of whole milk powder into instant beverages and breakfast cereals further embeds it into daily routines. This driver sustains market growth by addressing the fundamental needs of modern urban life.
Growing Infant Formula Industry Drives Premium Quality Requirements
The expanding infant formula industry in the region is a powerful driver for high quality milk powder used as a primary ingredient, which further propels the Asia Pacific whole milk powder market. According to the United Nations Children's Fund (UNICEF), birth rates in countries like India and Indonesia remain robust, with India alone leading global statistics with over 23 million annual births, providing a large target demographic for nutrition products. Parents increasingly seek premium formulas that mimic breast milk composition requiring whole milk powder with specific protein and fat profiles. The International Code of Marketing of Breast milk Substitutes influences regulatory frameworks ensuring that manufacturers adhere to strict safety and quality standards. As per studies, large-scale micronutrient fortification in dairy products has successfully improved objective child health and development outcomes in participating Asian countries. This health focus encourages formula producers to source whole milk powder from reputable suppliers with certified hygiene practices. Brands leverage the natural nutrient density of whole milk powder to market their products as superior alternatives to synthetic blends. Consumer trust in established dairy brands drives loyalty and repeat purchases in this sensitive category. The demand for organic and grass fed whole milk powder further segments the market allowing for premium pricing strategies. Regulatory approvals for new formula compositions often depend on the quality of the base milk powder. This sector demands consistent supply and rigorous testing which supports stable long term contracts for producers.
MARKET RESTRAINTS
Volatility In Raw Milk Prices Impacts Production Stability
Volatility in raw milk prices significantly restrains the Asia Pacific whole milk powder market. This creates uncertainty in production costs and profit margins. According to sources, global food price indices have fluctuated in recent years due to climate-induced supply shocks and geopolitical tensions affecting production costs. Dairy farmers in regions like New Zealand and Australia face varying weather conditions that impact pasture quality and milk yield directly influencing procurement prices for processors. As per research, input costs for dairy farming including energy and fertilizers have increased significantly in recent years, squeezing producer margins. These cost increases are often passed on to manufacturers who struggle to maintain competitive pricing for whole milk powder in price sensitive markets. Small scale processors lack the financial buffers to absorb sudden price spikes leading to reduced output or market exit. Consumers in developing nations may switch to cheaper alternatives such as plant based powders when dairy prices surge. This substitution effect limits market expansion and erodes brand loyalty. Long term contracts become difficult to negotiate when future milk prices are unpredictable. Investors hesitate to fund capacity expansions amid such financial instability. The ripple effect of raw material volatility disrupts the entire supply chain from farm to retail shelf. This economic constraint hampers consistent market growth and planning.
Stringent Regulatory Standards Increase Compliance Burdens
Stringent regulatory standards across diverse countries in the region increase the compliance burden for manufacturers in the Asia Pacific whole milk powder market. This restricts market entry and expansion. According to the World Health Organization food safety regulations vary significantly between nations requiring exporters to adapt formulations and packaging to meet local requirements. For instance, China implements rigorous testing for contaminants and additives which adds time and cost to the import process for foreign suppliers. The Codex Alimentarius Commission sets international guidelines but national authorities often impose additional restrictions that complicate cross border trade. As per studies, rejection rates for non-compliant dairy imports present ongoing financial challenges and losses for exporters trying to navigate varying trade standards. Manufacturers must invest in advanced laboratory equipment and quality assurance personnel to ensure adherence to these evolving standards. Small and medium enterprises often lack the resources to navigate complex regulatory landscapes limiting their competitive ability. Frequent changes in labeling requirements necessitate constant updates to packaging designs increasing operational expenses. Delays in customs clearance due to documentation errors further disrupt supply chains and affect product freshness. Consumer awareness of food safety issues pressures regulators to tighten controls continuously. This regulatory fragmentation creates barriers to efficient market integration. Companies must balance compliance costs with profitability which can stifle innovation and market responsiveness.
MARKET OPPORTUNITIES
Expansion Into Functional and Fortified Dairy Products Presents Growth Potential
The expansion into functional and fortified dairy products offers significant opportunities for the Asia Pacific whole milk powder market. This caters to health conscious consumers. According to the World Health Organization, micronutrient deficiencies affect over 40% of children in South Asia, creating a strong demand for enriched food solutions. Whole milk powder serves as an ideal vehicle for adding vitamins minerals and probiotics due to its stable matrix and widespread consumption. As per sources, fortified dairy products experienced strong sales growth across Southeast Asia as regional consumers prioritized functional health benefits and immune support. Manufacturers can develop specialized variants targeting specific health needs such as bone health for the aging population or energy boosting for active adults. Partnerships with nutritionists and healthcare providers help validate health claims and build consumer trust. Regulatory bodies in countries like Japan and South Korea encourage innovation in functional foods through streamlined approval processes for scientifically backed ingredients. Branding these products as premium wellness solutions allows for higher profit margins and differentiation from standard offerings. E commerce platforms facilitate direct education and marketing to niche consumer segments seeking personalized nutrition. The trend toward preventive healthcare drives adoption of these enhanced dairy products. This opportunity enables companies to move beyond commodity trading into value added specialization. It aligns with broader public health goals while driving commercial success.
Rising Demand for Plant Based Dairy Alternatives Creates Hybrid Innovation Spaces
The rising demand for plant based dairy alternatives creates unique growth areas for hybrid innovation using whole milk powder in the Asia Pacific market. According to the Good Food Institute, global private investment in alternative proteins slowed down significantly in 2023, falling by 44 percent, mirroring widespread venture funding declines across climate tech and food tech sectors. While plant based milks gain popularity many consumers still desire the taste and texture of real dairy leading to blended products. Whole milk powder can be combined with oat almond or soy bases to create hybrid beverages that offer balanced nutrition and familiar flavor. As per research, hybrid dairy-plant protein blends generally achieve higher sensory validation and liking scores from consumers in consumer test panels compared to pure plant-based alternatives. This innovation appeals to flexitarians who reduce but do not eliminate animal product consumption. Manufacturers can leverage existing dairy infrastructure to produce these novel blends efficiently. Marketing campaigns emphasizing reduced environmental impact and enhanced nutritional profiles resonate with eco conscious buyers. Retailers are eager to stock innovative products that attract diverse customer groups. Collaborations between traditional dairy firms and plant based startups accelerate product development and market entry. This strategy mitigates the risk of declining pure dairy consumption by adapting to changing dietary trends. It opens new revenue streams and keeps brands relevant in a dynamic marketplace.
MARKET CHALLENGES
Climate Change Threatens Dairy Farming Sustainability
Climate change is a severe challenge to the Asia Pacific whole milk powder market. This threatens the sustainability of dairy farming operations. According to sources, climate scenarios show that while high-fertility systems like dairy production in New Zealand could experience regional variation, total national pasture production has faced shifting suitability models. Heat stress affects cow health and milk yield leading to lower raw material availability for powder production. The Food and Agriculture Organization warns that water scarcity will intensify competition for resources needed in dairy processing facilities. Extreme weather events such as floods and droughts disrupt supply chains causing temporary shortages and price spikes. Farmers face increased costs for cooling systems and irrigation which strain already tight margins. The unpredictability of seasonal outputs makes long term planning difficult for processors relying on consistent milk flows. Environmental regulations aimed at reducing greenhouse gas emissions from livestock add further operational pressure. Consumers are increasingly aware of the carbon footprint of dairy products influencing purchasing decisions. Companies must invest in climate resilient practices and sustainable sourcing to mitigate these risks. Failure to adapt could lead to supply disruptions and reputational damage. This environmental challenge requires coordinated action across the entire value chain.
Competition From Substitute Products Erodes Market Share
Competition from substitute products such as plant-based powders and synthetic creamers is increasing, which slows down the expansion of the Asia Pacific whole milk powder market. This trend erodes the market share of whole milk powder in the region. According to research, sales of non-dairy creamers have experienced steady growth across Southeast Asia, driven by lower costs and expanding vegan trends. These alternatives often offer longer shelf lives and easier solubility appealing to commercial buyers in the food service sector. As per the Institute of Food Technologists, advancements in texturizing technologies have improved the sensory qualities of plant-based substitutes, making them viable replacements in many applications. Price sensitive consumers in developing markets frequently opt for cheaper alternatives during economic downturns reducing demand for premium dairy products. Marketing efforts by plant based brands emphasize health and environmental benefits which resonate with younger demographics. Traditional dairy companies struggle to match the aggressive pricing and innovation speed of niche competitors. The perception of dairy as less healthy due to lactose intolerance concerns further drives substitution. Retail shelf space is increasingly allocated to diverse non dairy options limiting visibility for whole milk powder. Manufacturers must differentiate their products through quality and nutritional superiority to retain customers. This competitive pressure forces continuous innovation and cost optimization. It challenges the traditional dominance of dairy in the beverage and culinary sectors.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 7.56% |
| Segments Covered | By Type, Application, and Region |
| Various Analyses Covered | Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | India, China, Japan, South Korea, Australia, New Zealand, Thailand, Malaysia, Vietnam, Philippines, Indonesia, Singapore, and the Rest of Asia-Pacific |
| Market Leaders Profiled | Fonterra Co-operative Group Limited, Nestlé S.A., FrieslandCampina, Lactalis Group, Arla Foods amba, Danone S.A., Murray Goulburn Co-operative Co. Limited, Yili Group, China Mengniu Dairy Company Limited, Inner Mongolia Junzheng Energy & Chemical Group, Gujarat Cooperative Milk Marketing Federation Ltd. (Amul), Mother Dairy Fruit & Vegetable Pvt. Ltd., Lactalis Ingredients, Westland Milk Products, and Tatua Co-operative Dairy Company Ltd. |
SEGMENTAL ANALYSIS
By Type Insights
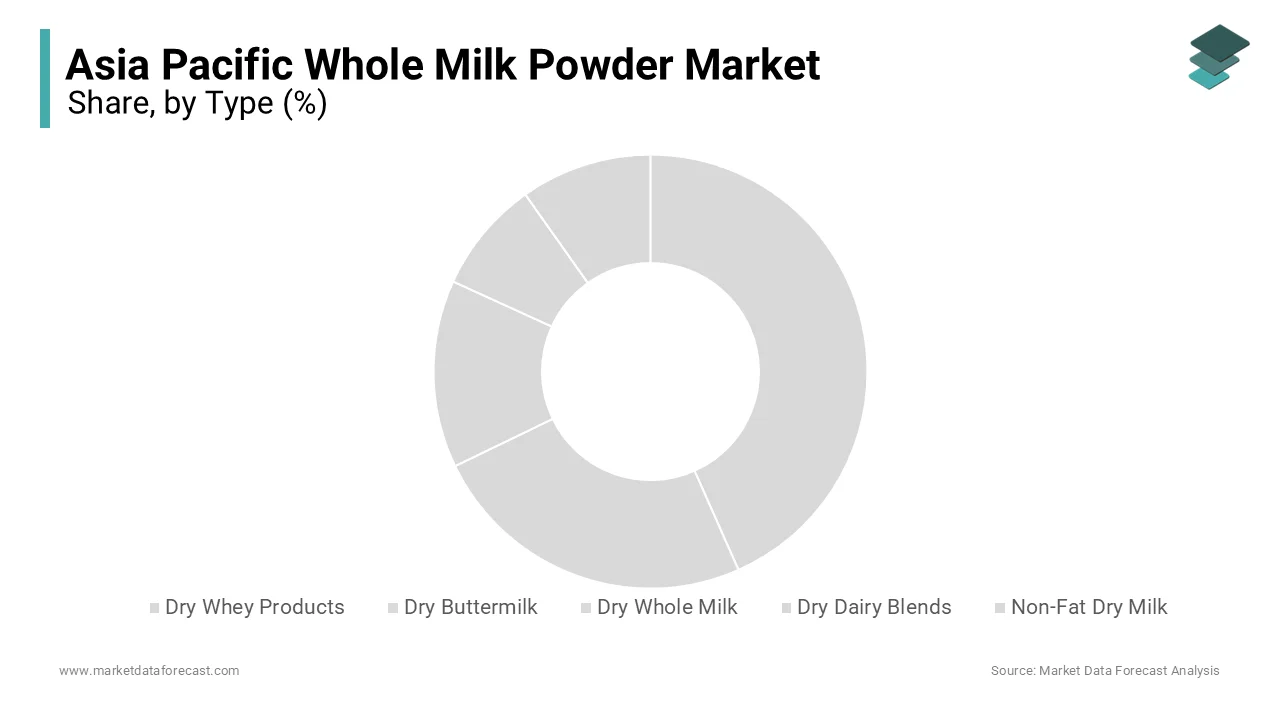
The dry whole milk segment maintained dominance in the Asia Pacific market and accounted for a substantial share in 2025. Its critical role in reconstituting liquid milk in regions with limited fresh dairy infrastructure contributed to the dominance of this segment. As per studies, milk powder plays a major role in recombination processes across the Asia Pacific region, with countries like China and Indonesia serving as key importers to satisfy regional dairy production needs. The ability to restore whole milk powder to a state closely resembling fresh milk allows distributors to supply remote areas where cold chain logistics are underdeveloped. According to the Food and Agriculture Organization (FAO), changing diets and urban demographic shifts have led to a steady increase in regional per capita milk consumption across Southeast Asia, heavily supported by affordable imported and recombined dairy products. This accessibility ensures that essential nutrients reach populations that would otherwise lack regular access to fresh dairy. Manufacturers prefer dry whole milk for its balanced fat to protein ratio which delivers the creamy texture consumers expect in beverages. The long shelf life of up to 24 months reduces inventory losses for retailers operating in tropical climates. Government subsidies in nations like India often support the distribution of fortified recombined milk to improve public health outcomes. This widespread institutional and commercial usage cements the dominance of dry whole milk. The segment benefits from established processing technologies that maintain quality during dehydration. These factors collectively ensure that dry whole milk remains the backbone of the regional dairy supply chain.
The preference for full fat content in traditional Asian culinary applications significantly supports the authority of dry whole milk in the region. As per the Journal of Dairy Science, the fat content in whole milk powder contributes to the mouthfeel and flavor release in traditional sweets such as Indian kheer and Chinese milk teas which are deeply embedded in cultural diets. Consumers in South and East Asia associate richness with quality and nutritional value making low fat alternatives less appealing for these specific uses. According to sources, household spending on traditional confectionery and beverages in emerging Asian economies continues to grow steadily, reflecting sustained consumer demand for authentic regional flavors. Dry whole milk provides the necessary lipid profile to replicate the sensory experience of fresh cream without the spoilage risks. Bakeries and street food vendors rely on this ingredient for consistency in high volume preparation. The natural emulsifying properties of milk fat enhance the texture of baked goods and sauces. Marketing campaigns by local brands often highlight the traditional heritage of their products using whole milk powder as a key authenticity marker. This cultural alignment drives repeat purchases and brand loyalty among diverse demographic groups. The segment also benefits from the growing popularity of bubble tea shops across the region which use milk powder bases for cost efficiency. This culinary integration ensures stable and recurring demand.
The non-fat dry milk segment is the fastest growing in the Asia Pacific market due to the rising fitness culture and increasing demand for protein supplementation among health conscious consumers. According to the Global Wellness Institute, the wellness economy in the Asia-Pacific region represents a massive multi-billion dollar market where healthy eating, nutrition, and weight loss stand out as prominent leading sectors. Non-fat dry milk offers a high protein content with minimal calories and fat making it an ideal ingredient for sports nutrition products and meal replacements. As per sources, recommendations for daily protein intake among physically active populations have steadily fueled the market growth and consumer adoption of dairy-based protein powders in urban centers. Gym goers and athletes prefer non-fat dry milk for post workout recovery due to its complete amino acid profile. Food manufacturers are incorporating this ingredient into protein bars shakes and ready to drink beverages to meet this surging demand. The clean label trend favors non-fat dry milk as it is perceived as a natural and minimally processed source of protein. Retailers are expanding their health food sections to include diverse dairy based supplements. Social media influencers promote the benefits of lean protein sources further driving consumer interest. This shift toward functional nutrition positions non-fat dry milk as a preferred choice for modern lifestyles. The segment benefits from continuous innovation in flavoring and formulation techniques.
Industrial demand for the functional properties of non-fat dry milk in food processing boosts its expansion rate in the Asia Pacific region. According to the Institute of Food Technologists, non-fat dry milk improves water binding capacity, texture, and browning in baked goods and processed meats which are essential for product quality. The bakery industry in countries like Thailand and Vietnam utilizes non-fat dry milk to enhance dough strength and crumb structure in bread production. As per the American Association of Cereal Chemists, the addition of skim milk powder can increase loaf volume by up to 10% in commercial baking operations. Processed meat manufacturers use it as a binder to improve yield and reduce cooking losses. The confectionery sector employs non-fat dry milk in chocolate and candy formulations to control viscosity and provide body without adding excess fat. These technical advantages allow manufacturers to optimize production costs while maintaining high sensory standards. The stability of non-fat dry milk during storage simplifies supply chain management for large scale producers. Regulatory approvals for its use as a safe food additive are widespread across the region. This versatility ensures consistent demand from various industrial sectors. The segment grows as food processors seek efficient and multifunctional ingredients.
By Application Insights
The infant formulas segment led the Asia Pacific whole milk powder market and captured a significant share in 2025. This leading position of the segment was mainly strengthened by stringent safety standards and deep seated trust in dairy based nutrition for early childhood development. According to sources, regional consumer demand for milk powder is heavily supported by infant feeding needs across Asia-Pacific countries where a significant portion of infants rely partially or fully on commercial formula solutions. Whole milk powder serves as the primary substrate for infant formulas because it provides the essential balance of fats proteins and carbohydrates required for growth. The World Health Organization emphasizes that high quality dairy ingredients are crucial for meeting the nutritional needs of infants who cannot be breastfed. Regulatory bodies in China and Japan enforce some of the strictest global standards for infant formula composition which favors established suppliers of premium whole milk powder. Parents prioritize safety and efficacy over price leading to strong brand loyalty for reputable formula manufacturers. The emotional weight of infant feeding decisions drives consumers to choose products with proven track records. Marketing efforts focus heavily on scientific research and pediatric endorsements to build confidence. The segment benefits from high barriers to entry which protect market leaders from low cost competitors. Continuous innovation in formula composition such as the addition of prebiotics keeps the category dynamic. This combination of regulatory protection and consumer devotion sustains the dominance of infant formulas.
Urbanization and the increasing number of working mothers in the Asia Pacific region sustain the top position of the infant formula application segment. As per the Asian Development Bank, rising urbanization and changing social patterns across Southeast Asian economies have contributed to shifts in household routines and lifestyle structures. Working parents require formula products that are easy to prepare and store making whole milk powder based formulas highly practical. The International Labour Organization notes that lack of adequate maternity leave in some Asian countries further necessitates the use of formula feeding. Urban lifestyles often limit access to fresh milk or breastfeeding support systems increasing dependence on commercial formulas. Retail expansion into suburban areas ensures wide availability of these products for busy families. E commerce platforms offer subscription services for formula delivery adding convenience for time constrained parents. Government policies in countries like Singapore provide subsidies for childcare which indirectly supports the purchase of quality nutrition products. The perception of formula as a scientifically advanced alternative to traditional feeding methods appeals to educated urban consumers. This demographic shift ensures a steady and growing customer base. Manufacturers continue to tailor products to meet the specific needs of modern families.
The nutritional foods segment is rapidly expanding in the Asia Pacific whole milk powder market owing to a quickly aging population and the need for chronic disease management. According to the World Health Organization, the proportion of people aged 60 and above in Asia is projected to reach 25% by 2050, creating an urgent demand for age-appropriate nutrition. Whole milk powder is extensively used in medical nutrition supplements and senior food products due to its high energy density and ease of digestion. As per studies, sarcopenia represents an expanding health concern among aging populations in Asia, underscoring the general market demand for targeted nutritional interventions. Healthcare providers recommend dairy based nutritional supplements to prevent malnutrition and support recovery in older adults. The rise of lifestyle diseases such as diabetes and hypertension drives demand for specialized nutritional products that manage these conditions while providing essential nutrients. Manufacturers develop targeted formulations using whole milk powder as a base for easy consumption. Retail pharmacies and health stores expand their offerings of nutritional supplements catering to this demographic. Insurance coverage for medical nutrition in developed markets like Japan and Australia further supports adoption. This demographic shift creates a robust and expanding market for nutritional applications.
Innovation in fortified and functional dairy products enhances the appeal of whole milk powder in the nutritional foods segment across the Asia Pacific region. According to the Institute of Food Technologists, the global functional food market is expected to grow by 7% annually, with Asia being a key contributor due to rising health awareness. Whole milk powder is integrated into protein bars meal replacements and fortified beverages that offer additional health benefits beyond basic nutrition. Brands add ingredients such as fiber vitamins and minerals to create value added products that address specific health concerns like bone health and immunity. The European Food Safety Authority approves various health claims for dairy based functional foods which influences Asian regulatory frameworks and consumer perceptions. Consumers seek convenient solutions that support overall wellness in their busy lives. Digital marketing campaigns educate consumers about the benefits of functional dairy products driving trial and adoption. Collaborations between dairy companies and health tech startups lead to personalized nutrition solutions. The versatility of whole milk powder allows for seamless integration into diverse product formats. This innovation keeps the segment dynamic and responsive to changing consumer needs. The focus on holistic wellness ensures sustained growth for nutritional food applications.
REGIONAL ANALYSIS
India Market Analysis
India continues to be a strong player in the Asia Pacific whole milk powder market. The country’s presence is supported by its status as the largest milk producer globally. According to the National Dairy Development Board India produced over 230 million tons of milk in 2023 providing a vast raw material base for domestic powder production. The government initiatives such as Operation Flood have modernized dairy infrastructure enabling efficient conversion of surplus milk into powder for storage and export. Domestic consumption remains high due to cultural preferences for dairy in sweets teas and traditional beverages. As per sources, India exports milk powder alongside other dairy commodities to regional markets including the Middle East, though the domestic market absorbs the vast majority of national milk output. Rising disposable incomes in rural areas drive demand for affordable nutrition sources. Local cooperatives play a crucial role in collecting and processing milk ensuring fair prices for farmers. The presence of major dairy players fosters competition and innovation in product offerings. Regulatory support for quality standards enhances consumer trust in domestic brands. India continues to be a key supplier and consumer in the regional market.
China Market Analysis
China was the largest player in the Asia Pacific whole milk powder market and occupied a commanding share in 2025. It ranks as the world’s largest importer of whole milk powder and a top global producer (producing 1.15 million metric tons in the 2025/2026 cycle), holding roughly 26.1% of global WMP production. According to Chinese customs and trade data, China's total imports of milk powder (including whole milk powder and skim milk powder) dropped significantly in 2023 to around 770,000–800,000 metric tons due to rising domestic milk production and high local inventories. The historical concerns regarding domestic dairy safety have led consumers to strongly prefer imported whole milk powder from New Zealand and Europe. The State Administration for Market Regulation enforces strict quality controls on imported dairy ensuring high safety standards. Rising urbanization and changing dietary habits increase per capita dairy consumption significantly. E commerce platforms facilitate easy access to international brands for consumers across the country. The government promotes dairy consumption as part of national health guidelines supporting market growth. Major multinational companies have established local production facilities to cater to this vast market. China remains the primary driver of global milk powder trade dynamics.
Australia Market Analysis
Australia is a mature country within the Asia Pacific whole milk powder market. It is a major exporter of whole milk powder in the region, leveraging its reputation for high quality and safe dairy production. According to industry export data, Australia's total exports of all combined dairy products were around 700,000 tonnes, while its milk powder exports specifically (SMP and WMP) totaled well under 200,000 tonnes in 2023. Favorable climatic conditions and advanced farming practices ensure consistent milk quality and yield. The Australian government supports trade agreements that facilitate easier access to Asian markets. Consumers in Australia also consume whole milk powder for baking and emergency preparedness. The industry focuses on sustainability and animal welfare which appeals to ethical consumers globally. Investment in processing technology enhances efficiency and product quality. Australia remains a trusted supplier in the regional market due to its stringent biosecurity measures.
New Zealand Market Analysis
New Zealand occupies a dominant position in the Asia Pacific whole milk powder market as one of the world's largest exporters. It represents 32.3% of global WMP production (1.42 million MT). Flat domestic population keeps market velocity locked strictly to outbound shipments. According to DairyNZ, the country produced over 1.87 billion kilograms (approximately 1.88 million metric tons) of milk solids in the 2023/24 season, with a significant portion converted into whole milk powder for export. The pasture based farming system results in high quality milk with favorable nutritional profiles. Trade agreements with Asian countries ensure tariff free or reduced tariff access for New Zealand dairy products. The industry is highly consolidated with major cooperatives driving efficiency and scale. Consumers in Asia trust New Zealand brands for their purity and safety standards. Environmental sustainability initiatives are increasingly important for maintaining market access. New Zealand continues to lead in volume and value in the regional milk powder trade.
Philippines Market Analysis
The Philippines is a promising landscape in the Asia Pacific whole milk powder market due to a large young population and limited local dairy production. According to the Philippine Statistics Authority, the country remains highly dependent on external dairy markets as domestic output fulfills less than 1% of its total annual milk consumption requirement. Whole milk powder is widely used in households for cooking and beverages due to its affordability and shelf life. The school feeding program incorporates dairy products to improve child nutrition. Retail distribution is expanding through supermarkets and convenience stores. Consumer preference for sweetened and flavored milk products drives specific formulation demands. Economic growth enables greater access to premium dairy options. The Philippines remains dependent on imports for its dairy supply.
Indonesia Market Analysis
Indonesia is also a high growth country in the Asia Pacific whole milk powder market. It exhibits significant growth potential owing to its large population. According to Statistics Indonesia (BPS), imported dairy products actually decreased by 14 percent in 2023 due to regulatory issues obtaining import licenses and softened consumer purchasing power. Halal certification is critical for market acceptance among the Muslim majority. The bakery and confectionery industries are major users of imported milk powder. Rising middle class consumers are shifting toward branded and packaged dairy products. Government policies aim to boost local dairy farming but imports will remain essential. Digital marketing influences purchasing decisions among younger consumers. Indonesia continues to be a key growth engine in the regional market.
COMPETITIVE LANDSCAPE
Competition in the Asia Pacific whole milk powder market is characterized by intense rivalry between multinational dairy giants and strong regional domestic producers. Established global firms leverage their extensive supply chains and brand reputation to serve premium segments in developed markets like Japan and Australia. Meanwhile local players compete through cost leadership and deep understanding of cultural preferences in emerging economies such as India and Indonesia. Differentiation increasingly hinges on sustainability credentials and nutritional innovation rather than price alone as consumers demand higher quality standards. Regulatory complexity across diverse national jurisdictions necessitates significant compliance investments favoring well capitalized participants with robust quality assurance systems. Strategic alliances with local distributors enable foreign firms to navigate market nuances while domestic companies seek international certifications to access export opportunities. The competitive landscape continues evolving as new entrants focus on niche organic or functional categories challenging traditional volume based models. Success requires balancing operational efficiency with authentic storytelling and technical support to build lasting stakeholder trust in this dynamic regional marketplace where food security and health consciousness drive demand.
Key Market Players
Some of the key players in the Asia Pacific whole milk powder market are
- Fonterra Co-operative Group Limited
- Nestlé S.A.
- FrieslandCampina
- Lactalis Group
- Arla Foods amba
- Danone S.A.
- Murray Goulburn Co-operative Co. Limited
- Yili Group
- China Mengniu Dairy Company Limited
- Inner Mongolia Junzheng Energy & Chemical Group
- Gujarat Cooperative Milk Marketing Federation Ltd. (Amul)
- Mother Dairy Fruit & Vegetable Pvt. Ltd.
- Lactalis Ingredients
- Westland Milk Products
- Tatua Co-operative Dairy Company Ltd.
Top Players in the Market
- Fonterra Co-operative Group Limited Fonterra Co-operative Group Limited serves as a dominant supplier of whole milk powder to the Asia Pacific region leveraging its extensive pasture based production in New Zealand. The company focuses on sustainable farming practices and high quality standards which appeal to premium consumers in China and Southeast Asia. Recently Fonterra expanded its consumer food service division in Shanghai to provide tailored dairy solutions for local bakeries and beverage chains. This strategic move strengthens direct relationships with key industrial buyers and enhances brand visibility in urban markets. The firm also invested in advanced drying technologies to improve product solubility and nutritional retention. These initiatives demonstrate commitment to meeting evolving regional demands while maintaining supply chain resilience. Fonterra continues to lead through innovation and strong distribution networks across major Asian hubs.
- Nestlé S.A. Nestlé S.A. maintains a strong presence in the Asia Pacific whole milk powder market through its diverse portfolio of infant nutrition and culinary products. The company leverages its global research capabilities to develop fortified milk powders that address specific regional nutritional deficiencies. Nestlé recently launched a new line of organic whole milk powder in Japan and South Korea targeting health conscious parents and adults. This product expansion aligns with growing consumer preference for clean label and sustainable ingredients. The firm also partnered with local distributors in Indonesia to improve rural access to affordable dairy nutrition. These actions enhance market penetration and build trust among diverse consumer segments. Nestlé’s focus on scientific validation and community engagement reinforces its leadership position.
- Inner Mongolia Yili Industrial Group Co. Ltd. Inner Mongolia Yili Industrial Group Co. Ltd. is a leading domestic player in China driving growth in the Asia Pacific whole milk powder sector through aggressive expansion and innovation. The company utilizes its vast local milk sourcing network to ensure cost efficiency and supply stability for regional markets. Yili recently established a new intelligent manufacturing base in Inner Mongolia to increase production capacity for high end milk powder products. This facility incorporates digital monitoring systems to guarantee consistent quality and safety standards. The firm also expanded its e commerce channels to reach younger consumers seeking convenient nutrition solutions. These efforts strengthen its competitive edge against international brands. Yili continues to invest in brand building and product diversification to capture emerging opportunities.
Top Strategies Used by Key Market Participants
Key players in the Asia Pacific whole milk powder market prioritize vertical integration to secure raw material access and ensure consistent quality control. Companies establish direct partnerships with local dairy farmers to stabilize supply chains and reduce dependency on volatile global markets. Strategic investments in advanced processing technologies enable firms to produce specialized milk powders with enhanced solubility and nutritional profiles for specific applications. Digital transformation initiatives are increasingly adopted to optimize logistics and provide real time traceability for consumers demanding transparency. Product differentiation focuses on developing organic fortified and lactose free variants to cater to diverse dietary needs and health trends. Collaborative research with academic institutions helps validate health claims and support regulatory approvals for novel formulations. Expansion into e commerce platforms allows companies to reach remote consumers and gather valuable data on purchasing behaviors. These multifaceted strategies collectively strengthen competitive positioning by addressing supply security quality assurance consumer preferences and technological advancement within the dynamic Asia Pacific business environment.
MARKET SEGMENTATION
This research report on the Asia Pacific Whole milk powder market has been segmented and sub-segmented into the following categories.
By Type
- Dry Whey Products
- Dry Buttermilk
- Dry Whole Milk
- Dry Dairy Blends
- Non-Fat Dry Milk
By Application
- Nutritional Foods
- Infant Formulas
- Confectionaries
- Baked Sweets & Savories
By Country
- India
- China
- Japan
- South Korea
- Australia
- New Zealand
- Thailand
- Malaysia
- Vietnam
- Philippines
- Indonesia
- Singapore
- Rest of Asia Pacific