- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$2.23 BnMarket Estimate, 2026
$2.44 BnMarket Forecast, 2034
$5.02 BnCAGR, 2026–2034
9.43%Asia Pacific Air Traffic Management Market Size, Share & Growth Analysis (2026–2034)
The Asia Pacific air traffic management market was valued at USD 2.23 billion in 2025, reaching USD 2.44 billion in 2026, and is projected to expand to USD 5.02 billion by 2034, registering a compound annual growth rate (CAGR) of 9.43% during the forecast period from 2026 to 2034.
- Market Scope: Comprehensive regional assessment spanning technologies, system components, airport size categories, and key country markets across China, India, Japan, Australia, Singapore, and Southeast Asia.
- Primary Growth Drivers: Exponential rise in air passenger traffic, massive airport expansion projects, and the urgent adoption of next-generation ATM solutions (such as ADS-B and satellite navigation).
Key Market Segment Metrics
| Category | Leading Segment | Fastest-Growing / Promising Segment |
|---|---|---|
| By Technology | Surveillance Systems (Held 38.2% market share in 2024, driven by legacy radar overhauls and space-based ADS-B expansion) | Navigation Systems (Projected to register a CAGR of 9.4%, fueled by PBN, RNAV, and RNP procedure adoptions) |
| By Component | Hardware (Accounted for 45.3% market share in 2024, supported by heavy government outlays for radar and comms infrastructure) | Software & Solutions (Anticipated to expand at a CAGR of 10.2%, driven by automation, cloud systems, and AI flow management) |
| By Country | China (Top market performer capturing 28.7% share in 2024, propelled by massive domestic passenger growth and BeiDou integration) | Australia & India (Executing multi-billion-dollar modernization frameworks like OneSky and NSS-CA to alleviate severe hub congestion) |
Major Market Players & Industry Landscape
Competitive Structure: A highly regulated, technology-intensive ecosystem where global aviation leaders leverage digital transformation, AI integration, and localized strategic partnerships with regional authorities.
Leading Companies: Thales S.A., RTX Corporation, Indra Sistemas S.A., L3Harris Technologies, Inc., Leonardo S.p.A., Frequentis AG, Leidos Holdings, Inc., Honeywell International Inc., Airbus SE, and Saab AB.
Asia Pacific Air Traffic Management Market Size
The Asia Pacific air traffic management market was valued at USD 2.23 billion in 2025 and is anticipated to reach USD 2.44 billion in 2026 to reach USD 5.02 billion by 2034, growing at a CAGR of 9.43% during the forecast period from 2026 to 2034.

Air traffic management (ATM) refers to the systematic control and coordination of aircraft movements within a defined airspace to ensure safety, efficiency, and optimal utilization of air navigation resources. In the Asia Pacific region, ATM systems are undergoing rapid modernization due to increasing air traffic volumes, infrastructure upgrades, and regulatory advancements. The market encompasses technologies such as surveillance systems, communication networks, navigation aids, and automation tools that support real-time flight monitoring and control.
MARKET DRIVERS
Increasing Air Passenger Traffic and Airport Expansion
The Asia Pacific region has witnessed exponential growth in air passenger traffic over the past decade, directly fueling demand for advanced air traffic management systems. According to the International Air Transport Association (IATA), the region accounted for nearly 38% of global air travel in 2023, with countries like China, India, and Vietnam experiencing double-digit annual growth rates. For instance, China's civil aviation sector handled over 560 million passengers in 2023, a 27% increase from the previous year, as reported by the Civil Aviation Administration of China (CAAC). Similarly, India's Ministry of Civil Aviation noted a 19% year-on-year rise in domestic air traffic during the same period.
This surge in passenger numbers has led to severe congestion at major airports, particularly in cities such as Beijing, Mumbai, and Jakarta. To address these challenges, governments and airport authorities are investing heavily in infrastructure modernization. As per data from the Airports Authority of India (AAI), over USD 12 billion has been allocated for airport expansion and ATM system upgrades by 2030. These investments include deploying automated air traffic control towers, satellite-based navigation systems, and AI-integrated flight scheduling tools. The result is an urgent need for scalable and intelligent air traffic management solutions capable of handling high-density airspace without compromising safety or efficiency.
Adoption of Next-Generation ATM Technologies
The integration of next-generation air traffic management technologies is another critical driver of market growth in the Asia Pacific region. Governments and aviation authorities are increasingly adopting performance-based navigation (PBN), automatic dependent surveillance-broadcast (ADS-B), and data link communication systems to enhance airspace capacity and reduce delays. In addition, Japan’s Aeronautical Telecommunication Network (ATN) and Automatic Dependent Surveillance-Contract (ADS-C) systems have significantly improved real-time aircraft monitoring, especially over remote oceanic routes. Furthermore, the Chinese government, through the Civil Aviation Administration of China (CAAC), has mandated the installation of ADS-B Out equipment on all commercial aircraft by 2025, aligning with global standards set by ICAO. The push toward digitization and automation in air traffic control is not only enhancing operational efficiency but also reducing human error and fuel consumption.
MARKET RESTRAINTS
High Implementation Costs and Budgetary Constraints
One of the primary restraints impeding the growth of the Asia Pacific air traffic management market is the substantial capital investment required for implementing advanced ATM systems. Modernizing air traffic control infrastructure involves significant expenditures on radar systems, communication networks, software platforms, and workforce training. Moreover, the procurement of cutting-edge technology—such as satellite-based navigation systems, data link communications, and digital towers—requires long-term financial commitments. In India, the Airports Authority of India (AAI) has faced repeated delays in rolling out its nationwide Automatic Dependent Surveillance-Broadcast (ADS-B) network due to funding shortages, despite being mandated by the Directorate General of Civil Aviation (DGCA). Similarly, in Indonesia, the implementation of the National Airspace Strategy (NAS) has been sluggish due to fiscal constraints, as reported by the Indonesian Directorate General of Civil Aviation. Additionally, maintenance and operational costs associated with next-generation ATM systems further burden national budgets. According to Deloitte, the total lifecycle cost of deploying a modern ATM system can be up to three times the initial investment.
Regulatory Complexity and Lack of Standardization
Regulatory fragmentation across the Asia Pacific region presents a significant challenge to the seamless deployment of unified air traffic management systems. Each country operates under distinct regulatory frameworks, leading to inconsistencies in technology adoption, procedural protocols, and airspace design. For example, while countries like Japan and Australia have aligned their ATM regulations with ICAO’s Global Air Navigation Plan, others, such as Thailand and Vietnam, are still in the process of updating their regulatory architectures. This inconsistency hampers cross-border coordination and limits the effectiveness of regional air traffic flow management initiatives. Furthermore, the absence of a unified certification process for ATM technologies complicates vendor participation and system interoperability. According to Eurocontrol, differences in certification requirements between China, India, and South Korea delay the introduction of new ATM solutions by 18–24 months compared to Europe or North America. These regulatory complexities deter foreign investment and slow down technological diffusion, which is acting as a major restraint on market growth in the Asia Pacific region.
MARKET OPPORTUNITIES
Growth of Unmanned Aerial Vehicle (UAV) Traffic and Urban Air Mobility (UAM)
The rapid proliferation of unmanned aerial vehicles (UAVs) and the emergence of urban air mobility (UAM) present a transformative opportunity for the Asia Pacific air traffic management market. With increasing drone usage in logistics, agriculture, emergency response, and surveillance, managing low-altitude airspace has become a priority for aviation authorities. Governments across the region are investing in UAV traffic management (UTM) systems to integrate drones safely into existing airspace. For instance, the Civil Aviation Authority of Singapore (CAAS) has launched the “Urban Air Mobility Grand Challenge” to test autonomous flying vehicles in controlled environments. Moreover, the development of eVTOL (electric vertical takeoff and landing) aircraft by companies like EHang (China) and SkyDrive (Japan) signals a future where urban air taxis will coexist with traditional air traffic.
Rise of Satellite-Based Navigation and Data Communication Systems
The increasing adoption of satellite-based navigation and data communication systems offers a compelling growth avenue for the Asia Pacific air traffic management market. Traditional ground-based navigation aids are being replaced by space-based solutions such as GPS, Galileo, and BeiDou, enabling more precise aircraft positioning and route optimization. China’s BeiDou Navigation Satellite System (BDS), now fully operational, is being integrated into civil aviation operations across the country. As per the Civil Aviation Administration of China (CAAC), over 70% of commercial aircraft in China are equipped with BDS-compatible avionics, facilitating area navigation (RNAV) and required navigation performance (RNP) procedures. In parallel, data link communication systems such as Controller-Pilot Data Link Communications (CPDLC) and Automatic Dependent Surveillance-Contract (ADS-C) are gaining traction in transcontinental and oceanic flights. According to Boeing’s 2023 Pilot and Technician Outlook, over 65% of new aircraft deliveries in the Asia Pacific region come equipped with CPDLC capabilities. These advancements enable real-time data exchange between pilots and controllers, improving situational awareness and reducing reliance on voice communication.
MARKET CHALLENGES
Cybersecurity Threats to Air Traffic Control Systems
As air traffic management systems become increasingly digitized and interconnected, cybersecurity threats pose a growing challenge to the Asia Pacific air traffic management market. The reliance on IP-based communication networks, cloud computing, and real-time data exchange exposes critical ATM infrastructure to cyberattacks that could disrupt flight operations and compromise passenger safety. According to a report by the Center for Strategic and International Studies (CSIS), there were over 120 documented cyber incidents targeting aviation systems globally in 2023, with several affecting ATM networks in the Asia Pacific region. In Japan, the Ministry of Land, Infrastructure, Tr, and Tourism (MLIT) issued a security advisory following a ransomware attack on a regional air traffic control center in 2022, temporarily disrupting radar surveillance capabilities. Similarly, in India, the National Critical Information Infrastructure Protection Centre (NCIIPC) identified air traffic control systems as high-risk assets, prompting the Civil Aviation Ministry to issue mandatory cybersecurity compliance guidelines for all aerodrome operators. Moreover, the migration towards open data link systems and satellite-based navigation introduces vulnerabilities that malicious actors can exploit. According to ENISA (European Union Agency for Cybersecurity), spoofing attacks on GPS signals have increased by 75% globally since 2020, posing risks to aircraft navigation accuracy. As ATM systems evolve, ensuring robust cybersecurity frameworks becomes imperative.
Skilled Workforce Shortage and Training Gaps
A significant challenge facing the Asia Pacific air traffic management market is the shortage of skilled personnel and inadequate training infrastructure to support the deployment of advanced ATM systems. As air traffic volumes grow and technology evolves, there is an increasing demand for air traffic controllers, technical staff, and cybersecurity specialists proficient in next-generation ATM tools. Training programs for air traffic management are often outdated or insufficiently funded, limiting the ability of aviation authorities to onboard and certify new professionals. For instance, the Civil Aviation Authority of Thailand (CAAT) reported a 30% backlog in controller training due to limited simulator availability and instructor shortages. Moreover, the complexity of integrating new technologies such as digital towers, data link communications, and artificial intelligence-driven scheduling tools requires continuous upskilling of existing personnel. According to the Asian Development Bank (ADB), only 12 out of 25 Asia Pacific countries have established dedicated ATM training academies with modern simulation facilities.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 5.33% |
| Segments Covered | By Technology, Component, Airport Size, And Region. |
| Various Analyses Covered | Global, Regional, and Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | India, China, Japan, South Korea, Australia, New Zealand, Thailand, Malaysia, Vietnam, Philippines, Indonesia, Singapore, and the Rest of APAC |
| Market Leaders Profiled | Thales S.A., RTX Corporation, Indra Sistemas, S.A., L3Harris Technologies, Inc., Leonardo S.p.A., Frequentis AG, Leidos Holdings, Inc., Honeywell International Inc., Airbus SE, Saab AB. |
SEGMENTAL ANALYSIS
By Technology Insights
The surveillance systems segment was the largest and held 38.2% of the Asia Pacific air traffic management market share in 2024. One key driver is the modernization of legacy radar infrastructure across major aviation hubs. For instance, according to the Civil Aviation Administration of China (CAAC), over 65% of China’s primary radar systems are more than two decades old, prompting a national upgrade initiative that includes the installation of over 200 ADS-B ground stations by 2025. Similarly, in India, the Airports Authority of India (AAI) has allocated USD 700 million toward deploying next-generation surveillance equipment at 100 airports under its National Surveillance System for Civil Aviation (NSS-CA) program. Another factor fueling growth is the expansion of remote and oceanic coverage through space-based ADS-B. As per Aireon, a leading provider of space-based ADS-B services, its satellite constellation now tracks over 10,000 flights daily across the Pacific Ocean, significantly improving real-time monitoring in previously unmonitored regions.
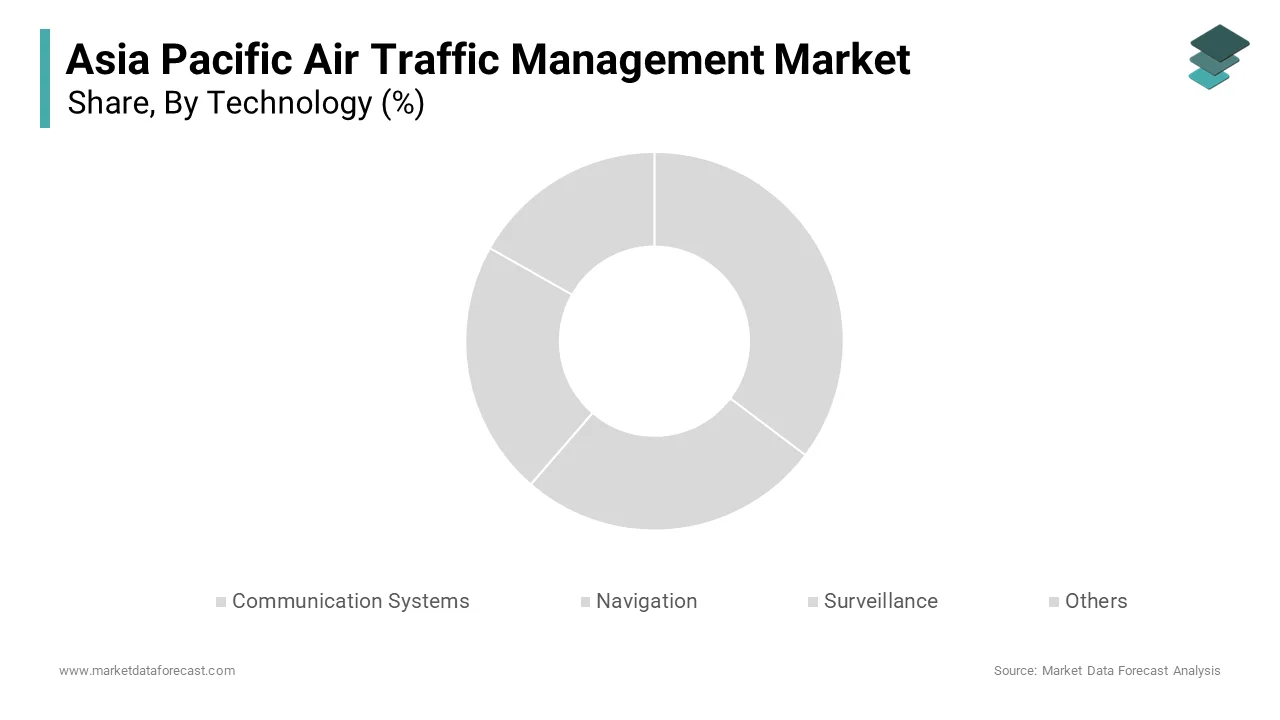
The navigation systems segment is projected to register a CAGR of 9.4% in the coming years. A major catalyst for this transition is the implementation of area navigation (RNAV) and required navigation performance (RNP) procedures across commercial airlines. According to Boeing’s 2023 Pilot and Technician Outlook, over 70% of new aircraft deliveries in the Asia Pacific region are equipped with PBN-capable avionics, enhancing route efficiency and reducing fuel burn. In China, the Civil Aviation Administration (CAAC) mandates all domestic carriers to adopt RNP AR approaches at high-altitude airports, boosting demand for advanced onboard navigation systems. Additionally, government-backed initiatives like India’s GPS-Aided Geo-Augmented Navigation (GAGAN) system have enabled precision landing capabilities across 35 airports, as reported by the Airports Authority of India (AAI). The Japanese Ministry of Land, Infrastructure, Transport and Tourism (MLIT) also promotes the use of GNSS-based flight paths to optimize airspace utilization.
By Component Insights
The hardware segment was the largest by accounting for 45.3% of the Asia Pacific air traffic management market share in 2024. According to the Asian Development Bank (ADB), governments in Southeast Asia have committed over USD 6 billion toward upgrading ATC hardware, including radar installations and VHF communication systems, to meet rising airspace demands. In Indonesia, the Directorate General of Civil Aviation has initiated a multi-phase project to deploy new secondary surveillance radars (SSRs) at 12 strategic locations, enhancing nationwide coverage. Moreover, defense applications contribute significantly to hardware investments. The Indian Ministry of Defence allocated USD 1.2 billion under its “Make in India” defense production policy for indigenous radar development, supporting both civilian and military air traffic needs.
The software & solutions segment is anticipated to grow with a CAGR of 10.2% in the coming years. One major growth driver is the push for automation and data-centric decision-making in air traffic control. In Australia, Airservices Australia launched the OneSky program, which integrates civil and military air traffic data using cloud-based software platforms, improving operational efficiency by 18% since its inception. Furthermore, regulatory mandates for digital transformation are accelerating software adoption. In South Korea, the Ministry of Land, Infrastructure and Transport mandated the rollout of NextGen-compatible flight data processing systems by 2025, as outlined by the Korea Office of Air Traffic Control (KOACT). Meanwhile, Singapore’s Civil Aviation Authority (CAAS) has partnered with ST Engineering to develop AI-powered air traffic flow management solutions, enhancing capacity during peak hours.
COUNTRY-LEVEL ANALYSIS
China Air Traffic Management Market Analysis
China was the top performer in the Asia Pacific air traffic management market, with 28.7% of the share in 2024toh the rapid expansion of China's civil aviation industry. According to the Civil Aviation Administration of China (CAAC), the country handled over 580 million passengers in 2023, a 27% increase from the previous year, necessitating enhanced air traffic control capabilities. Additionally, China's indigenous BeiDou Navigation Satellite System (BDS) has been fully integrated into civil aviation, enabling precise aircraft navigation and optimized flight routing. As per the China Satellite Navigation Office (CSNO), over 70% of commercial aircraft in China now operate with BDS-enabled avionics.
India Air Traffic Management Market Analysis
India ranked second in the Asia Pacific air traffic management market with a share of 15.3% in 2024. According to the Ministry of Civil Aviation, India recorded a 19% year-on-year rise in domestic air travel in 2023, with over 165 million passengers transported domestically. This surge has led to severe congestion at major airports, prompting significant investments in ATM upgrades.
Japan Air Traffic Management Market Analysis
Japan's air traffic management market growth is driven by its strong presence due to its early adoption of advanced ATM technologies, stringent regulatory frameworks, and robust investment in aerospace research. Additionally, Japan is pioneering the use of digital towers and remote air traffic control centers. The country’s first digital tower facility was commissioned at Sendai Airport in 2022, allowing controllers to monitor multiple airports from a centralized location. As per Mitsubishi Electric, which developed the system, digital towers can reduce infrastructure costs by up to 40% while improving situational awareness.
Australia Air Traffic Management Market Analysis
Australia's air traffic management market growth is likely to have significant opportunities with the well-developed aviation infrastructure, high levels of technological integration, and strategic coordination with neighboring countries. Airservices Australia, the country’s air navigation service provider, has undertaken one of the most comprehensive ATM modernization programs in one region. OneSky's initiative, a USD 1.3 billion endeavor, integrates civil and military air traffic management through digital automation and satellite-based surveillance. In addition, Australia leads in the deployment of space-based ADS-B technology. As per Aireon, its satellite constellation provides real-time aircraft tracking over the Pacific and Indian Oceans, where traditional radar coverage is limited. This capability supports safer and more efficient routing for international carriers operating in these regions.
Singapore Air Traffic Management Market Analysis
Singapore's air traffic management market is steadily growing with its status as a premier aviation hub and a center for technological innovation. The Civil Aviation Authority of Singapore (CAAS) has actively pursued the implementation of AI-driven air traffic flow management systems, enabling better coordination of arrivals and departures at one of the world’s busiest airports. Additionally, Singapore is a key participant in the ASEAN Single Sky initiative, aimed at harmonizing air traffic control procedures across Southeast Asia. As part of this effort, the country has collaborated with regional partners to establish common communication protocols and surveillance standards. Furthermore, partnerships with companies like ST Engineering and Thales have facilitated the testing of urban air mobility (UAM) traffic management solutions. These strategic moves reinforce Singapore’s influential role in shaping the future of air traffic management in the Asia Pacific.
KEY MARKET PLAYERS
These are the market players that are dominating the Asia Pacific air traffic management market
- Thales S.A.
- RTX Corporation
- Indra Sistemas, S.A
- L3Harris Technologies, Inc.
- Leonardo S.p.A.
- Frequentis AG
- Leidos Holdings, Inc.
- Honeywell International Inc.
- Airbus SE
- Saab AB.
Top Players In The Market
- Thales Group is a global leader in air traffic management solutions and holds a strong presence in the Asia Pacific region. The company provides advanced radar systems, communication networks, and digital tower technologies that enhance airspace efficiency and safety. Thales has been actively involved in modernizing air traffic control infrastructure across key markets such as India, Australia, and Singapore. Its collaboration with local aviation authorities and integration of AI-driven tools have significantly contributed to the evolution of ATM systems in the region.
- Indra Sistemas is another major player shaping the Asia Pacific air traffic management landscape. Known for its end-to-end ATM solutions, Indra offers next-generation surveillance, navigation, and automation platforms tailored for high-density airspaces. The company has deployed its systems in several countries, including China, South Korea, and Thailand. Indra’s focus on digital transformation, satellite-based navigation, and remote tower capabilities supports the region's efforts to streamline air traffic operations and improve airspace capacity without compromising safety standards.
- Honeywell Aerospace plays a pivotal role in the Asia Pacific air traffic management market by delivering cutting-edge avionics, ground-based systems, and data communication solutions. Honeywell collaborates with regional airlines and airport authorities to integrate performance-based navigation and flight optimization tools. The company’s emphasis on innovation and system interoperability has enabled seamless adoption of NextGen and SESAR-compliant technologies across various APAC nations. Its continuous investment in research and development reinforces its strategic position in the evolving ATM ecosystem.
Top Strategies Used by Key Market Participants
One of the primary strategies adopted by leading players in the Asia Pacific air traffic management market is technology innovation and digital transformation. Companies are investing heavily in artificial intelligence, automation, and cloud-based air traffic control systems to meet the growing demand for efficient and scalable solutions. These advancements help manage increasing air traffic volumes while improving operational accuracy and reducing human intervention.
Another key strategy is strategic partnerships and collaborations with regional aviation authorities, defense agencies, and airport operators. By working closely with local stakeholders, companies can tailor their offerings to regional regulatory frameworks and airspace complexities. These alliances also facilitate knowledge transfer and support long-term deployment of advanced ATM systems across multiple countries. The firms are focusing on market expansion through localization initiatives, including setting up regional R&D centers, establishing joint ventures, and acquiring local firms. This approach enables them to better understand regional needs, accelerate product customization, and strengthen their foothold in emerging markets within the Asia Pacific region.
RECENT MARKET NEWS
- In February 2024, Thales Group partnered with Japan’s Ministry of Land, Infrastructure, Transport, and Tourism to deploy an advanced digital tower solution at Sendai Airport by enhancing remote air traffic monitoring capabilities.
- In June 2023, Indra Sistemas signed a strategic agreement with the Civil Aviation Authority of Vietnam to implement a new-generation air traffic control system aimed at improving airspace efficiency and safety.
- In November 2023, Honeywell Aerospace launched a new satellite-based navigation initiative in collaboration with Indian aviation authorities to support precision landing and route optimization across domestic airspace.
- In March 2024, Saab AB inaugurated a regional air traffic management training center in Malaysia to provide specialized simulation and controller training services for Southeast Asian countries.
- In September 2023, Frequentis AG expanded its communication network infrastructure in the Philippines by deploying VHF radio systems to support improved air-ground connectivity and flight coordination.
MARKET SEGMENTATION
This research report on the Asia Pacific Air traffic management market is segmented and sub-segmented into the following categories.
By Technology
- Communication Systems
- Navigation
- Surveillance
- Others
By Component
- Hardware
- Software & Solutions
By Airport Size
- Small Airport
- Medium Airport
- Large Airport
By Country
- India
- China
- Japan
- South Korea
- Australia
- New Zealand
- Thailand
- Malaysia
- Vietnam
- Philippines
- Indonesia
- Singapore
- Rest Of APAC