- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$3.21 BnMarket Estimate, 2026
$4.13 BnMarket Forecast, 2034
$30.79 BnCAGR, 2026–2034
28.56%Executive Summary: Asia-Pacific Antibody Drug Conjugates Market
- Market Scope: Comprehensive Asia-Pacific antibody-drug conjugates (ADCs) market analysis covering pipeline phases, technology platforms, end-user settings, country frameworks, and oncology treatment adoption metrics.
- Market Valuation: Valued at USD 3.21 billion (2025), estimated at USD 4.13 billion in 2026, and projected to reach USD 30.79 billion by 2034, registering an exceptional CAGR of 28.56% (2026–2034).
- Primary Growth Drivers: High and rising prevalence of cancer across the region, a rapidly expanding geriatric population, and targeted oncology therapies offering superior efficacy over conventional chemotherapy without harming healthy cells. Key market constraints include high drug and treatment costs, strict regulatory hurdles, and localized diagnosis fluctuations.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Pipeline | Clinical-stage phases and HER2-targeted antibody configurations (led oncology pipelines) | Advanced IgG1 and customized targeted-moiety formats |
| By Technology | Proprietary Seattle Genetics and Immunogen linker-payload technology platforms | Next-generation site-specific conjugation platforms |
| By End User | Hospitals and specialized oncology centers (dominated regional administration volume) | Advanced research institutes and clinical trial centers |
| By Country | China and India (dominated regional growth driven by large drug manufacturing bases and patient volumes) | Japan, South Korea, and Singapore (expanding rapidly via dedicated R&D funds and advanced healthcare infrastructure) |
Major Market Players & Market Structure
Market Structure: Highly dynamic and fast-evolving Asia-Pacific and global oncology landscape featuring major biopharmaceutical pioneers competing intensely on targeted cytotoxic payloads, clinical pipeline expansions, and research partnerships.
Key Companies: Seattle Genetics, Genentech, Takeda Pharmaceuticals, F. Hoffmann-La Roche, Bayer Healthcare, Agensys, Inc., Immunogen, Novartis, Oxford Biotherapeutics, and Synthon Biopharmaceuticals.
 Download Free Sample Report
Asia Pacific Antibody Drug Conjugates Market Size
The Asia-Pacific antibody drug conjugates market was valued at USD 3.21 billion in 2025. The market is estimated at USD 4.13 billion in 2026 and is projected to reach USD 30.79 billion by 2034, growing at a CAGR of 28.56% from 2026 to 2034.

Antibody-drug conjugates are designed to target cancer cells with precision by linking monoclonal antibodies to cytotoxic drugs. As per the World Health Organization, noncommunicable diseases, including cancer, are responsible for over 80% of deaths in the region, underscoring the urgency for effective treatment options. As per clinical guidelines, the adoption of antibody-drug conjugates is accelerating due to their superior efficacy in treating refractory cancers such as breast and gastric malignancies. Regulatory bodies in countries like Japan and China are expediting approvals for innovative biologics, facilitating faster patient access. Manufacturing capabilities are expanding in India and South Korea, supporting local production and cost reduction.
MARKET DRIVERS
Surging Prevalence of Targetable Cancers and Aging Demographics
The escalating incidence of targetable cancers such as breast, gastric, and lung malignancies is driving the growth of the Asia-Pacific antibody-drug conjugates market. According to the International Agency for Research on Cancer, new cancer cases in Asia will rise by 45% between 2020 and 2030, driven by lifestyle changes and demographic shifts. Breast cancer remains the most commonly diagnosed cancer in women across many Asian countries, creating a substantial patient pool eligible for HER2 targeted therapies. According to the United Nations Department of Economic and Social Affairs, the population aged 60 and older in Asia will double to 1.3 billion by 2050, increasing susceptibility to age-related cancers. Older patients often require treatments with manageable side effect profiles, making antibody-drug conjugates an attractive option compared to traditional chemotherapy. Healthcare systems in Japan, South Korea, and China are prioritizing early detection programs that identify candidates for targeted therapies at earlier stages. Government initiatives to expand cancer screening coverage further amplify the diagnosed patient base.
Regulatory Acceleration and Government Healthcare Initiatives
The proactive regulatory reforms and government-led healthcare initiatives are significantly boosting the growth of the Asia-Pacific antibody-drug conjugates market. The National Medical Products Administration in China has implemented streamlined review pathways for innovative drugs, reducing approval times from several years to under one year for priority therapies. This regulatory agility allows patients faster access to global standard treatments, including recently approved antibody-drug conjugates for gastric and urothelial cancers. The Japanese Ministry of Health, Labour and Welfare actively supports the inclusion of novel biologics in the national health insurance scheme, ensuring broad affordability for citizens. Governments in Australia and Singapore provide subsidies for high-cost cancer treatments through dedicated pharmaceutical benefit schemes. These policy frameworks reduce financial barriers and encourage hospital adoption of advanced therapies. Public-private partnerships facilitate clinical trials locally, generating regional data that supports regulatory submissions. Investment in biomedical research hubs in countries like South Korea fosters domestic innovation and manufacturing. Insurance coverage expansions for targeted therapies drive volume growth as out-of-pocket costs decrease.
MARKET RESTRAINTS
Exorbitant Treatment Costs and Limited Reimbursement Coverage
The prohibitive treatment costs and inconsistent reimbursement policies are hindering the growth of the Asia-Pacific antibody-drug conjugates market. The average annual cost of antibody-drug conjugate therapy can exceed 100000 United States dollars, placing it out of reach for patients in low- and middle-income countries without robust insurance support. Public health insurance schemes in countries like India and Indonesia often exclude newer high-cost therapies or impose strict caps on coverage. Patients face significant financial toxicity, leading to treatment discontinuation or reliance on less effective alternatives. Healthcare providers hesitate to prescribe these drugs due to budget constraints within public hospitals. The lack of harmonized pricing strategies across the region creates disparities in access between urban and rural areas. Pharmaceutical companies struggle to balance profitability with accessibility in price-sensitive markets. Economic volatility and currency fluctuations further exacerbate affordability issues for imported medications.
Complex Manufacturing Requirements and Supply Chain Vulnerabilities
The intricate manufacturing processes and fragile supply chains is another factor degrading the growth of the Asia-Pacific antibody-drug conjugates market. Producing antibody-drug conjugates requires highly specialized facilities capable of handling potent cytotoxic payloads safely, which limits the number of qualified manufacturers globally. Only a handful of contract development and manufacturing organizations possess the expertise to scale up ADC production while maintaining quality standards. Supply chain disruptions for key raw materials such as specific linkers and antibodies can delay production and impact drug availability. Many Asia Pacific countries rely on imports for finished ADC products, making them vulnerable to geopolitical tensions and logistics bottlenecks. Cold chain requirements for storage and transportation add complexity and cost to distribution networks, particularly in tropical climates. Regulatory inspections for manufacturing sites are rigorous and time-consuming, delaying market entry for new players. Local manufacturing capabilities are still developing in most regions, forcing dependence on external suppliers.
MARKET OPPORTUNITIES
Expansion into Novel Targets and Bispecific Antibody Conjugates
The development of targeting novel antigens and the emergence of bispecific formats are creating new opportunities for the growth of the Asia-Pacific antibody-drug conjugates market. Researchers are identifying new tumor-specific markers beyond HER2 and TROP2, allowing for treatment of diverse cancer types prevalent in the region, such as esophageal and liver cancers. The bispecific antibody-drug conjugates can engage multiple targets simultaneously, enhancing tumor specificity and overcoming resistance mechanisms. This innovation opens therapeutic avenues for patients who have exhausted standard options. Pharmaceutical companies in China and Japan are investing heavily in next-generation ADC pipelines focusing on unique biological insights from Asian patient populations. Clinical trials exploring combination therapies with immunotherapies show promising results in improving response rates. Regulatory agencies offer breakthrough designations for novel mechanisms, accelerating development timelines. Partnerships between academic institutions and biotech firms foster innovation in linker technology and payload optimization. The ability to tailor treatments to specific genetic profiles aligns with the region's growing emphasis on precision medicine.
Growth of Domestic Biopharmaceutical Manufacturing Hubs
The rapid expansion of domestic biopharmaceutical manufacturing capabilities in countries like China, South Korea, and India offers a strategic opportunity to reduce costs and enhance supply security. Local manufacturing reduces dependency on imports, lowering tariffs and logistics costs, which can translate to more affordable pricing for patients. Governments provide incentives such as tax breaks and grants to encourage domestic production of high-value biologics. Contract manufacturing organizations in the region are upgrading facilities to meet international quality standards, enabling them to serve global clients. This localization strategy improves supply chain resilience against global disruptions. Collaborations between local firms and multinational corporations facilitate technology transfer and skill development. The availability of skilled scientists and engineers supports innovation in process optimization. Regional trade agreements facilitate easier export of manufactured ADCs to neighboring countries.
MARKET CHALLENGES
Heterogeneity in Regulatory Standards and Approval Timelines
The disparate regulatory frameworks and varying approval timelines create significant hurdles for uniform launch and distribution, which is a major challenge for the growth of the Asia-Pacific antibody-drug conjugates market. Each nation maintains distinct requirements for clinical data safety assessments and manufacturing inspections, complicating multinational submission strategies. The Asia Pacific Economic Cooperation forum notes that regulatory harmonization remains incomplete, leading to delays of up to two years between approvals in developed and emerging countries. Manufacturers must navigate complex bureaucratic processes in each jurisdiction, increasing administrative burdens and costs. Differences in accepted clinical endpoints and comparator drugs require separate trials for certain markets. Intellectual property protection varies widely, affecting market exclusivity and generic competition timelines. Lack of mutual recognition agreements means redundant inspections and reviews. Small biotech firms struggle to manage these complexities, limiting their ability to enter multiple markets simultaneously. Patients in countries with slower approval processes face delayed access to life-saving therapies.
Limited Clinical Data Specific to Asian Populations
The scarcity of robust clinical trial data specific to Asian ethnic groups is also limiting the growth of the Asia-Pacific antibody-drug conjugates market. Genetic variations in drug metabolism and target expression levels among Asian populations may differ significantly from Western cohorts used in global trials. Physicians hesitate to prescribe new ADCs without local safety and efficacy evidence. Conducting separate regional trials is expensive and time-consuming, delaying market entry. Regulatory bodies increasingly require local bridging studies before approval, adding to development costs. Small sample sizes in rare cancer types make statistical significance difficult to achieve. Lack of standardized biomarker testing infrastructure hinders patient selection for targeted therapies. Healthcare providers rely on real-world evidence, which takes years to accumulate. This data gap creates uncertainty in clinical decision-making and limits confidence in adopting new therapies.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Pipeline, Technology, End User, and Country. |
| Various Analyses Covered | Global, Regional and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered | India, China, Japan, South Korea, Australia, New Zealand, Thailand, Malaysia, Vietnam, Philippines, Indonesia, Singapore, and Rest of APAC |
| Market Leaders Profiled | Seattle Genetics, Genentech, Daiichi Sankyo, Takeda Pharmaceuticals, Jiangsu Hengrui Medicine Co Ltd., F. Hoffmann-La Roche, Seagen Inc., Bayer Healthcare, Agensys, Inc., Immunogen, Novartis, Oxford Biotherapeutics, and Synthon Biopharmaceuticals. |
SEGMENTAL ANALYSIS
By Pipeline Insights
The HER2 antibodies segment was the largest, accounting for 34.2% of the Asia-Pacific antibody drug conjugates market share in 2025, with the high prevalence of HER2-positive breast and gastric cancers, which are particularly common in Asian populations. As per the International Agency for Research on Cancer, breast cancer is the most frequently diagnosed cancer among women in Asia, accounting for over 20% of all new female cancer cases. This substantial disease burden creates a consistent and large patient pool eligible for HER2 targeted therapies such as trastuzumab emtansine. Clinical guidelines from the Chinese Society of Clinical Oncology recommend HER2 testing for all invasive breast cancers, ensuring accurate identification of candidates for antibody-drug conjugate treatment. The proven efficacy of HER2-directed conjugates in extending overall survival in metastatic settings reinforces their status as standard of care. Pharmaceutical companies prioritize this target due to well-established biological pathways and successful clinical trial histories. Regulatory approvals for multiple HER2-based conjugates have expanded treatment options for resistant cases. Reimbursement policies in countries like Japan and South Korea increasingly cover these high-cost therapies, improving patient access.
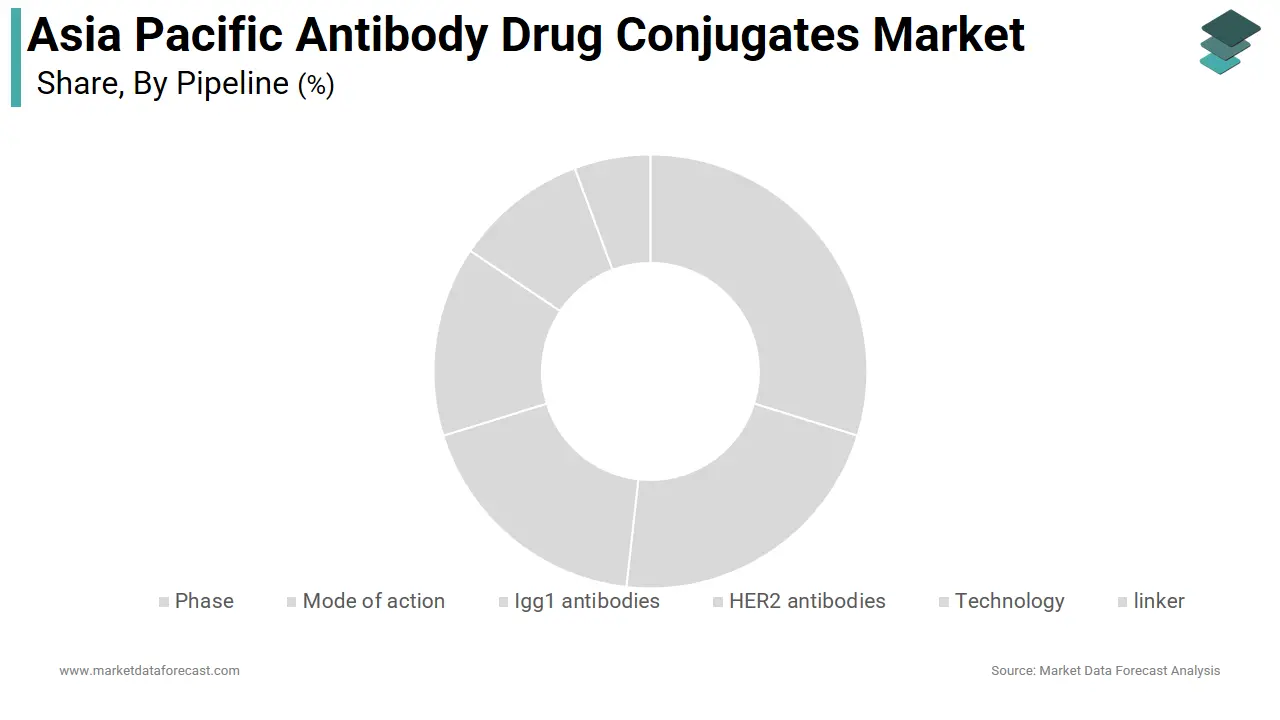
The linker technology segment is likely to grow at the fastest CAGR of 11.9% from 2026 to 2034, with innovations that enhance stability and reduce off-target toxicity. Advanced linkers such as cleavable and non-cleavable variants allow for precise control over drug release mechanisms, improving the therapeutic index. This technological advancement enables the use of more potent cytotoxic agents that were previously too toxic for systemic administration. Researchers in China and Japan are actively developing proprietary linker platforms to differentiate their pipeline candidates from global competitors. The ability to tailor linker chemistry to specific tumor microenvironments offers personalized treatment advantages. Regulatory agencies favor innovations that demonstrate superior safety data, accelerating approval timelines for next-generation conjugates. Manufacturing processes for complex linkers are becoming more scalable, reducing production costs. Partnerships between biotech firms and chemical suppliers facilitate rapid integration of new linker technologies.
By Technology Insights
The Seattle Genetics technology segment held a significant share of the Asia-Pacific antibody-drug conjugates market in 2025 due to its widespread adoption of the mcMMAE linker payload platform. This technology utilizes a maleimidocaproyl linker attached to monomethyl auristatin E, which has demonstrated robust efficacy in multiple approved drugs, including brentuximab vedotin and polatuzumab vedotin. Brentuximab vedotin has become a cornerstone therapy for Hodgkin lymphoma and peripheral T-cell lymphoma, driving high utilization rates across Asian healthcare facilities. The reliability of this platform in maintaining stability in circulation while releasing payload intracellularly builds trust among clinicians. Many pharmaceutical companies in the region license this technology for their own pipeline development, reducing research risks. Established manufacturing protocols ensure consistent quality and supply chain reliability. Regulatory precedents set by earlier approvals facilitate faster acceptance of new drugs using similar technology. Clinical experience with this platform provides extensive real-world data supporting its continued use.
The immunomedics technology segment is likely to witness the fastest CAGR of 9.2% from 2026 to 2034 with the success of sacituzumab govitecan and its innovative SN 38 payload mechanism. This technology employs a hydrolyzable linker that releases the active metabolite of irinotecan, offering a unique mechanism of action distinct from microtubule inhibitors. The New England Journal of Medicine published results showing significant improvement in progression-free survival for triple-negative breast cancer patients treated with sacituzumab govitecan compared to standard chemotherapy. This clinical breakthrough has spurred rapid adoption in oncology centers across China, Japan, and South Korea. The versatility of the SN-38 payload allows for application in various solid tumors beyond breast cancer, including urothelial and lung cancers. Regulatory approvals in key Asian markets have been expedited due to urgent unmet needs in triple-negative breast cancer. Local manufacturers are exploring licensing opportunities to produce biosimilars or next-generation variants. The ability to overcome resistance to other therapies makes this technology highly attractive for second-line treatments.
By End User Insights
The hospitals segment was the largest, holding 44.3% of the Asia-Pacific antibody-drug conjugates market share in 2025 due to their capacity to administer complex intravenous therapies and manage potential adverse events. These specialized biologics require infusion centers equipped with trained oncology nurses and immediate access to emergency care for reactions such as anaphylaxis or infusion-related symptoms. Hospitals possess the necessary cold chain storage infrastructure to maintain the stability of antibody-drug conjugates, which are sensitive to temperature fluctuations. Multidisciplinary tumor boards in major hospitals guide treatment decisions, ensuring appropriate patient selection for targeted therapies. Accreditation standards require strict protocols for handling cytotoxic drugs, which hospitals are better equipped to implement than smaller clinics. Insurance reimbursement processes are often streamlined through hospital billing systems, facilitating patient access. Clinical trials for new conjugates are predominantly conducted in hospital settings, driving early adoption. The concentration of specialist oncologists in hospitals ensures expert management of treatment courses.
The clinics segment is anticipated to exhibit the fastest CAGR of 8.6% during the forecast period with the decentralization of cancer care and rise of specialized outpatient infusion centers. Patients increasingly prefer receiving treatments in community-based clinics to avoid the long wait times and high costs associated with large hospital visits. The outpatient care models are gaining traction as they improve quality of life and reduce healthcare system burden. Specialized oncology clinics are investing in infrastructure to safely administer antibody-drug conjugates, including dedicated infusion chairs and monitoring equipment. Telemedicine integration allows remote consultation with specialists while receiving local administration. Insurance providers are incentivizing outpatient care through lower co-payments, encouraging patient migration from hospitals. The expansion of private healthcare networks in urban areas facilitates easier access to these services. Clinics offer personalized attention and shorter appointment durations, enhancing patient satisfaction.
COUNTRY LEVEL ANALYSIS
India Antibody Drug Conjugates Market Analysis
India was the top performer in the Asia-Pacific antibody drug conjugates market by capturing a 45.7% share in 2025 with the growing domestic manufacturing base and increasing accessibility to biosimilars. The Indian Department of Pharmaceuticals promotes the production of affordable biologics through initiatives like the Production Linked Incentive scheme, which encourages local manufacturing of complex drugs. The rising incidence of breast and cervical cancers drives demand for targeted therapies among the expanding middle class. Private hospitals in metropolitan cities are adopting international treatment protocols, including antibody-drug conjugates for refractory cases. The cost advantage of Indian manufactured biosimilars makes these therapies more accessible compared to imported branded products. Regulatory harmonization efforts with global standards improve the quality of locally produced conjugates. Clinical trial activity is increasing as global sponsors seek diverse patient populations for recruitment. Government health insurance schemes begin to cover certain high-cost cancer treatments, improving affordability. Distribution networks are expanding to tier two and three cities, enhancing reach.
China Antibody Drug Conjugates Market Analysis
China antibody drug conjugates market was ranked second, holding 22.2% of the share in 2025, with the massive patient volume and aggressive regulatory reforms. The National Medical Products Administration has approved multiple domestic and international antibody-drug conjugates in recent years, significantly reducing approval lag times compared to historical norms. The high prevalence of gastric and liver cancers, which are more common in China than in Western countries, creates specific demand for targeted therapies. Government investment in biomedical parks fosters innovation among local biotech companies developing novel conjugates. National health insurance listings now include several antibody-drug conjugates, making them affordable for millions of patients. Clinical research capabilities have matured, allowing China to participate in global multicenter trials. Manufacturing capacity for biologics has expanded rapidly, supporting both domestic consumption and exports. Patient awareness of precision medicine is rising due to extensive digital health education campaigns. Collaborations between academic institutions and pharmaceutical firms accelerate translation of research into commercial products.
Japan Antibody Drug Conjugates Market Analysis
Japan antibody drug conjugates market growth is largely propelled by universal health coverage and high regulatory standards. The Ministry of Health, Labour and Welfare actively includes innovative antibody drug conjugates in the national health insurance reimbursement list, ensuring broad patient access. An aging population contributes to high cancer incidence rates, driving steady demand for effective treatments with manageable side effects. Japanese pharmaceutical companies are global leaders in ADC development, leveraging expertise in monoclonal antibody engineering. Clinical practice guidelines strongly recommend targeted therapies for eligible patients, ensuring consistent utilization. The country's robust pharmacovigilance system monitors safety data closely, maintaining high trust in these medications. Research institutions collaborate with international partners to develop next-generation conjugates with improved payloads. Manufacturing facilities adhere to stringent quality controls, ensuring product reliability. Patient advocacy groups play a significant role in influencing policy and access decisions.
South Korea Antibody Drug Conjugates Market Analysis
South Korea antibody drug conjugates market is likely to grow with the strong biotechnology sector and rapid adoption of new therapies. The Ministry of Food and Drug Safety accelerates reviews for breakthrough cancer drugs, facilitating quick market entry for global and domestic products. High healthcare spending per capita enables patients to access premium treatments, including latest-generation conjugates. Local biotech firms are actively developing proprietary ADC platforms, attracting significant venture capital and global partnerships. National health insurance covers many targeted therapies, reducing financial barriers for patients. Clinical trial infrastructure is well developed, supporting participation in global studies. Physicians are highly trained in precision oncology, ensuring appropriate patient selection. The government supports R&D through tax incentives and grants for biopharmaceutical innovation. Medical tourism attracts patients from neighboring countries seeking advanced cancer care.
Australia Antibody Drug Conjugates Market Analysis
The Australian antibody drug conjugates market is likely to grow with the regulated Pharmaceutical Benefits Scheme and high-quality healthcare standards. The Pharmaceutical Benefits Scheme subsidizes the cost of many antibody drug conjugates, making them accessible to public and private patients alike. The Cancer Council Australia advocates for equitable access to the latest treatments, ensuring guideline adherence across states. High prevalence of skin and breast cancers drives demand for targeted interventions. Clinical trials are actively conducted in major cancer centers, contributing to the global knowledge base. Regulatory approval by the Therapeutic Goods Administration ensures safety and efficacy standards are met. Specialist oncologists in urban centers lead adoption of new therapies. Rural access programs aim to reduce disparities in treatment availability. Patient support programs provided by manufacturers help navigate administrative hurdles.
COMPETITIVE LANDSCAPE
The competitive landscape of the Asia-Pacific antibody-drug conjugates market features a mix of global pharmaceutical giants and emerging regional biotechnology firms vying for dominance in targeted oncology. These players emphasize innovation in linker technology and payload potency to differentiate their offerings from competitors. Regional companies, particularly in China and South Korea, compete by developing biosimilars and novel indigenous ADCs tailored to local disease profiles and price sensitivities. Strategic alliances between global and local entities are common to navigate regulatory complexities and distribution challenges. Differentiation through superior clinical outcomes and safety profiles remains key to securing premium pricing and formulary inclusion.
KEY MARKET PLAYERS
The leading companies operating in the Asia-Pacific antibody-drug conjugates market include:
- Seattle Genetics
- Genentech
- Daiichi Sankyo
- Takeda Pharmaceuticals
- Jiangsu Hengrui Medicine Co. Ltd.
- Hoffmann-La Roche
- Seagen Inc.
- Bayer Healthcare
- Agensys, Inc.
- ImmunoGen
- Novartis
- Oxford Biotherapeutics
- Synthon Biopharmaceuticals
TOP PLAYERS IN THE MARKET
- Daiichi Sankyo Company Limited stands as a global leader in the Asia-Pacific antibody-drug conjugates market driven by its proprietary DXd linker technology. The company has achieved significant commercial success with trastuzumab deruxtecan for breast and gastric cancers across Japan, China, and other regions. Recent actions include expanding manufacturing capacity in Japan to meet surging global demand and securing new regulatory approvals for additional indications. Daiichi Sankyo actively collaborates with international partners like AstraZeneca to accelerate clinical development and market access. The company invests heavily in next-generation ADC pipelines targeting novel antigens prevalent in Asian populations. Strategic alliances with local distributors ensure efficient supply chain management.
- Seagen Inc contributes significantly to the Asia-Pacific antibody-drug conjugates market through its robust portfolio of approved therapies, including brentuximab vedotin and polatuzumab vedotin. The company leverages its extensive experience in linker payload technology to support internal programs and external collaborations. Recent initiatives involve expanding clinical trial sites across South Korea and Australia to generate regional data for regulatory submissions. Seagen strengthens its market position by partnering with local biotechnology firms to explore novel targets specific to Asian cancer profiles. The company focuses on educating healthcare professionals about the benefits of its ADC platforms. Investments in supply chain resilience ensure consistent product availability.
- Jiangsu Hengrui Medicine Co Ltd is a dominant domestic player in the China market and increasingly influential in the broader Asia Pacific Antibody Drug Conjugates sector. The company has successfully launched multiple indigenous ADC products for breast and lung cancers leveraging local manufacturing capabilities. Recent actions include initiating global multicenter clinical trials to support international regulatory filings and market expansion. Hengrui invests substantially in research and development to build a diverse pipeline of next-generation conjugates. Partnerships with global pharmaceutical companies facilitate technology exchange and co-development opportunities.
TOP STRATEGIES USED BY THE KEY MARKET PARTICIPANTS
Key players in the Asia-Pacific antibody-drug conjugates market employ strategic licensing agreements and collaborations to expand their therapeutic pipelines and geographic reach. These partnerships enable companies to access novel technologies and share development risks while accelerating time to market. Firms invest heavily in clinical trials focused on Asian patient populations to generate local data required for regulatory approvals and reimbursement decisions. Manufacturing scalability is addressed through facility expansions and contract manufacturing partnerships to ensure consistent supply. Regulatory engagement involves proactive dialogue with health authorities to navigate complex approval pathways efficiently. Pricing strategies balance affordability with value proposition to secure inclusion in national insurance schemes. Intellectual property protection remains critical to maintaining competitive advantage.
MARKET SEGMENTATION
This research report on the Asia Pacific antibody drug conjugates market has been segmented and sub-segmented into the following categories
By Pipeline
- Phase
- Mode of action
- Igg1 antibodies
- HER2 antibodies
- Technology
- linker
By Technology
- Seattle genetics
- Immunogen
- Immunomedics
By End User
- Research institutes
- Hospitals
- Clinics
By Country
- India
- China
- Japan
- South Korea
- Australia
- New Zealand
- Thailand
- Malaysia
- Vietnam
- Philippines
- Indonesia
- Singapore
- Rest of APAC