- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$10.68 BnMarket Estimate, 2026
$11.81 BnMarket Forecast, 2034
$26.44 BnCAGR, 2026–2034
10.6%Executive Summary: Asia Pacific Biodiesel Market
- Market Scope: Regional Asia-Pacific renewable fuels market analysis covering feedstock categories, application sectors, country leadership frameworks, and blending mandate adoption metrics.
- Market Valuation: Valued at USD 10.68 billion in 2025, estimated at USD 11.81 billion in 2026, and projected to reach USD 26.44 billion by 2034, registering a CAGR of 10.6% from 2026 to 2034.
- Primary Growth Drivers: Supportive government biodiesel blending mandates, tax incentives, abundant feedstock availability (including palm oil and jatropha), and increasing demand for cleaner transportation fuels. Key industry trends include second-generation biofuel advancements and sustainable bio-refinery technology investments.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Feedstock Type | Vegetable oils segment (supported by widespread availability and cost-effectiveness of palm oil across Indonesia and Malaysia) | Animal fats and second-generation advanced biofuel feedstocks (projected to expand at a CAGR of 9.2%) |
| By Application | Fuel segment (accounted for the largest share at 60.4% in 2025) | Power generation segment (expected to witness the fastest growth with a CAGR of 8.7% through 2034) |
| By Technology & Innovation | First-generation palm oil-based biodiesel production | Second-generation biofuels, algae-based R&D, and sustainable bio-refinery solutions |
| By Region / Country | Indonesia (led with a 40.4% share in 2025, driven by large-scale palm oil production and blending policies) | Malaysia, Thailand, India, and Australia (significant emerging regional growth markets) |
Major Market Players & Market Structure
Market Structure: Highly competitive regional renewable energy landscape emphasizing government partnerships, feedstock diversification, bio-refinery investments, plant acquisitions, and rural electrification joint ventures.
Key Companies: Wilmar International, Musim Mas, IOI Group, Adani Wilmar, Neste, Sunshine Kaidi, GrainCorp, TotalEnergies, Cargill, and Clariant.
Asia Pacific Biodiesel Market Size
Asia Pacific Biodiesel market size was valued at USD 10.68 billion in 2025, and the market size is expected to reach USD 26.44 billion by 2034 from USD 11.81 billion in 2026. The market's promising CAGR for the predicted period is 10.6%.
MARKET DRIVERS
Government Mandates and Incentives
Government mandates and incentives are pivotal drivers of the Asia Pacific biodiesel market, shaping the regulatory landscape and encouraging widespread adoption. For instance, Thailand’s Alternative Energy Development Plan mandates a 5% biodiesel blend (B5) across the transportation sector, which has led to a significant increase in biodiesel consumption since 2019, according to the Ministry of Energy of Thailand. Similarly, Malaysia’s Biofuel Industry Act provides tax exemptions and subsidies for biodiesel producers, reducing operational costs and enhancing profitability. These policies not only address energy security concerns but also align with global climate goals. Besides, public awareness campaigns highlighting the benefits of renewable energy have increased consumer acceptance, particularly in urban areas.
Abundant Availability of Feedstock
The abundance of feedstock, particularly palm oil and jatropha, serves as another significant driver for the Asia Pacific biodiesel market. Indonesia and Malaysia collectively account for a substantial share of global palm oil production, providing a cost-effective and scalable resource for biodiesel manufacturing. Palm oil’s high yield per hectare makes it an ideal feedstock, reducing production costs while ensuring sustainability. In India, the cultivation of non-edible oils like jatropha has gained traction, with a notable increase in jatropha plantations since 2020. This diversification of feedstock sources mitigates risks associated with price volatility and supply chain disruptions. Moreover, advancements in bio-refinery technologies have improved feedstock utilization efficiency.
MARKET RESTRAINTS
High Production Costs
High production costs pose a significant restraint to the Asia Pacific biodiesel market, impacting its competitiveness against conventional fossil fuels. While feedstock availability is abundant, fluctuations in raw material prices, particularly palm oil, can severely affect profitability. For example, as per the Food and Agriculture Organization, palm oil prices surged during the first quarter of 2023 due to export restrictions imposed by major producers like Indonesia and Malaysia. This unpredictability creates financial strain, particularly for small-scale producers who lack the resources to hedge against price volatility. Additionally, the capital-intensive nature of biodiesel production facilities exacerbates the issue, especially for emerging economies with limited access to financing.
Environmental Concerns and Public Perception
Environmental concerns and negative public perception regarding the use of certain feedstocks also hinder market expansion. Large-scale cultivation of palm oil, a primary feedstock for biodiesel, has been linked to deforestation and habitat destruction, raising alarms among environmentalists. For instance, the conversion of tropical forests into palm oil plantations has contributed to a considerably loss of biodiversity in Southeast Asia over the past decade. In addition, consumer awareness campaigns highlighting the potential ecological impacts of monoculture farming have influenced purchasing decisions, particularly in urban areas. In Australia, the Department of Environment reports that 60% of consumers now prefer biofuels derived from waste oils or algae, pressuring companies to innovate sustainably. This shift in public sentiment necessitates increased transparency and investment in alternative feedstocks, posing challenges for traditional biodiesel manufacturers.
MARKET OPPORTUNITIES
Expansion into Emerging Markets
Emerging markets in the Asia Pacific region offer untapped potential for the biodiesel market, driven by industrial growth and infrastructure development. Countries like Vietnam, Bangladesh, and the Philippines are witnessing rapid urbanization, creating demand for cleaner transportation fuels. For instance, Vietnam’s automotive sector relies heavily on imported diesel, prompting the government to incentivize local biodiesel production. Similarly, Bangladesh’s growing logistics industry, which contributes notably to its GDP, requires sustainable fuel alternatives to meet international emission standards. Investing in localized production facilities and distribution networks can help companies cater to these regions effectively. Moreover, partnerships with local governments and NGOs can facilitate the adoption of biodiesel in rural areas, where energy access remains a persistent issue.
Advancements in Second-Generation Biofuels
The development of second-generation biofuels presents a lucrative opportunity for the Asia Pacific biodiesel market, aligning with the global push toward sustainability. Unlike first-generation biofuels, which rely on edible feedstocks, second-generation biofuels utilize non-food biomass such as agricultural residues and waste oils, minimizing competition with food supplies. For example, South Korea’s Ministry of Science and Technology highlights that investments in cellulosic ethanol and algae-based biodiesel have grown by 25% annually since 2020, driven by government incentives and consumer demand. Innovations in enzymatic hydrolysis and fermentation technologies have enhanced the efficiency of converting lignocellulosic materials into biofuels. According to the Confederation of Indian Industry, the adoption of second-generation biofuels in India’s aviation sector has reduced carbon emissions, as they comply with international aviation standards.
MARKET CHALLENGES
Competition from Electric Vehicles
The rise of electric vehicles (EVs) poses a significant challenge to the Asia Pacific biodiesel market, as governments and industries increasingly prioritize EV adoption over biofuels. For instance, China’s New Energy Vehicle (NEV) policy aims to phase out internal combustion engine vehicles by 2035, resulting in a significant growth in EV sales since 2020, according to the China Association of Automobile Manufacturers. Similarly, India’s Faster Adoption and Manufacturing of Hybrid and Electric Vehicles (FAME) scheme provides subsidies for EV manufacturers, further accelerating their market penetration. While biodiesel remains a viable solution for heavy-duty transportation and aviation, the shift toward electrification threatens its dominance in the passenger vehicle segment. Also, investments in EV charging infrastructure have surpassed those in biofuel production facilities, showing this trend.
Supply Chain Disruptions
Supply chain vulnerabilities represent another critical challenge for the Asia Pacific biodiesel market. The region’s reliance on global trade for raw materials and equipment exposes it to disruptions caused by pandemics, natural disasters, and geopolitical conflicts. For example, the 2021 Suez Canal blockage disrupted shipments of biodiesel processing machinery, leading to delays in facility expansions, as reported by the International Trade Centre. Besides, these disruptions not only inflate operational costs but also delay deliveries, eroding customer trust. To mitigate these risks, companies must invest in digital tools for real-time tracking and diversify their supplier base.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 10.6% |
| Segments Covered | By Feedstock, Application, and Region |
|
Various Analyses Covered | Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | India, China, Japan, South Korea, Australia, New Zealand, Thailand, Malaysia, Vietnam, Philippines, Indonesia, Singapore, and the Rest of Asia-Pacific |
| Market Leaders Profiled | Wilmar International, Musim Mas, IOI Group, Adani Wilmar, Neste, Sunshine Kaidi, GrainCorp, TotalEnergies, Cargill, Clariant, and others |
SEGMENTAL ANALYSIS
By Feedstock Insights
The vegetable oils segment commanded the Asia Pacific biodiesel market with a substantial share of the total feedstock share, as per the Food and Agriculture Organization. This dominance is primarily driven by the widespread availability and cost-effectiveness of palm oil, particularly in Indonesia and Malaysia, which together produce a large portion of the world’s palm oil supply. Alao, palm oil’s high yield per hectare makes it an ideal feedstock, reducing production costs while ensuring scalability. Government mandates also play a crucial role; for instance, Indonesia’s B30 policy, which mandates a 30% biodiesel blend, has led to a 40% increase in palm oil-based biodiesel consumption since 2020. Additionally, advancements in refining technologies have improved the efficiency of converting vegetable oils into biodiesel, further solidifying their dominance.
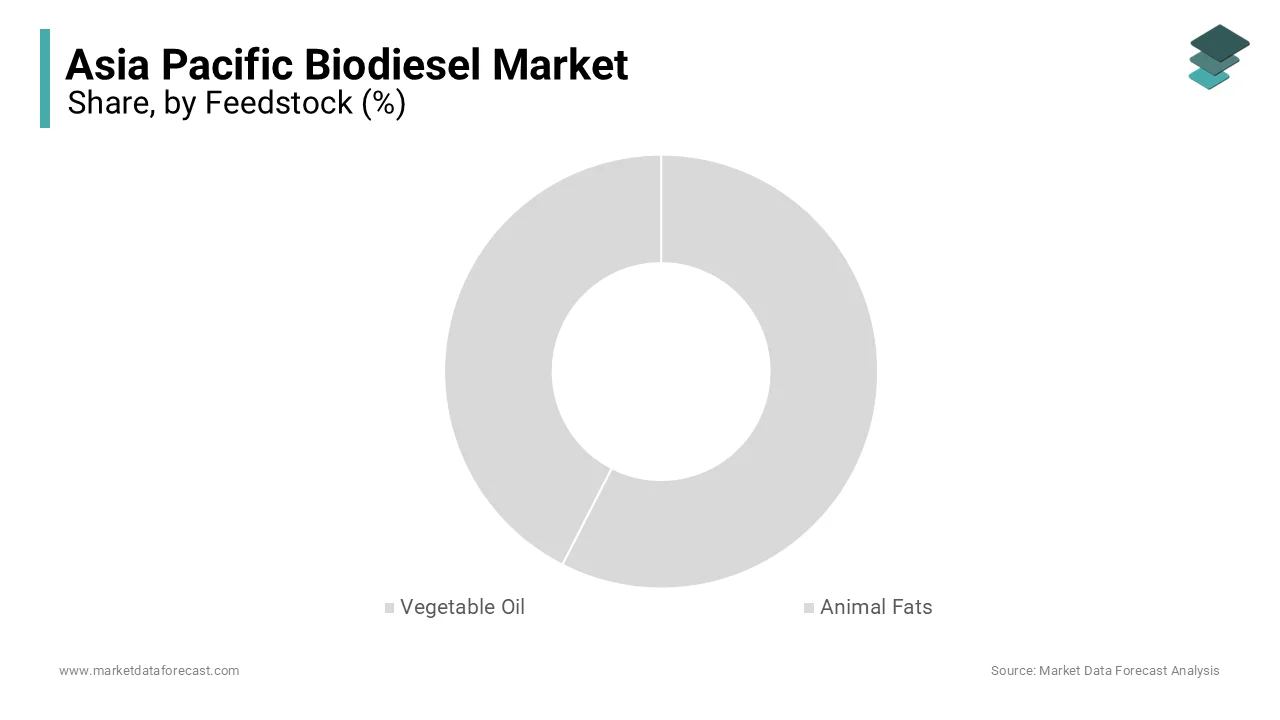
The animal fats segment is the quickly growing feedstock, with a predicted CAGR of 9.2%. This progress is caused by the increasing availability of waste animal fats from the meat processing industry, particularly in countries like Australia and New Zealand. For example, the Australian Meat Industry Council reports that the country generates over 500,000 tons of animal fat annually, much of which is now being repurposed for biodiesel production. Additionally, stricter waste management regulations have incentivized meat processors to collaborate with biodiesel manufacturers are reducing disposal costs and enhancing sustainability. In addition, the use of animal fats in India’s biodiesel sector has grown since 2021, driven by government subsidies for waste-to-energy projects.
By Application Insights
The segment of fuel applications represented the largest category with a 60.4% share of the Asia Pacific biodiesel market in 2025. This influence is propelled by the region’s heavy reliance on transportation fuels and government mandates promoting biodiesel blending. For instance, Thailand’s Alternative Energy Development Plan mandates a 5% biodiesel blend (B5) across the transportation sector, resulting in a significant increase in biodiesel consumption since 2019. Similarly, Malaysia’s Biofuel Industry Act provides tax exemptions for biodiesel producers, further boosting adoption. Urbanization and industrialization have also amplified demand, with a considerable share of the region’s population residing in cities. Rising disposable incomes and the proliferation of logistics networks have increased fuel consumption, making biodiesel a critical component of the energy mix.
The power generation is the fastest-growing application segment, with a projected CAGR of 8.7% through 2034. This is fueled by the increasing focus on renewable energy to meet electricity demands in rural and remote areas. Similarly, Vietnam’s rural electrification programs have adopted biodiesel as a cost-effective solution for decentralized power generation, with the Ministry of Industry and Trade reporting a 20% annual increase in biodiesel usage for this purpose. Advancements in bio-refinery technologies have also enhanced the efficiency of converting biodiesel into electricity, aligning with global sustainability goals.
REGIONAL ANALYSIS
Indonesia is the largest biodiesel producer in the Asia-Pacific region by holding a 40.4% share in 2025. This dominance is credited to its status as the world’s largest palm oil producer, leveraging abundant feedstock resources to produce cost-effective biodiesel. According to the Ministry of Energy and Mineral Resources of Indonesia, the country mandated a 30% biodiesel blend (B30) in 2020, significantly boosting domestic consumption. Urbanization has further amplified demand, with a significant portion of the population residing in cities. Rising disposable incomes have also fueled the adoption of biodiesel in transportation and industrial sectors.
Malaysia is a significant player in the Asia-Pacific biodiesel market. The nation is benefitting from its robust palm oil industry and favorable government policies. It’s Biofuel Industry Act provides tax exemptions and subsidies for biodiesel producers, reducing operational costs and enhancing profitability. Additionally, Malaysia’s strategic location as a global palm oil exporter has facilitated international trade, boosting biodiesel exports to Europe and China. Like, biodiesel production grew in 2022, showing its critical role.
Thailand is expanding but with some fluctuations and challenges. This is attributable to its advanced agricultural infrastructure and stringent environmental regulations. The country’s Alternative Energy Development Plan mandates a 5% biodiesel blend (B5) across the transportation sector, fostering innovation in sustainable fuels. Additionally, Thailand’s growing logistics industry relies heavily on biodiesel to meet international emission standards. Urban consumers’ preference for eco-friendly solutions further amplifies demand, particularly in cities like Bangkok.
India is experiencing significant growth in the Asia Pacific biodiesel market, with its leading position supported by its ambitious renewable energy goals and agricultural diversity. The country’s National Policy on Biofuels aims to achieve a 20% ethanol-blending target by 2026, driving investments in biodiesel production. Moreover, India’s cultivation of non-edible oils like jatropha has gained traction, with a notbale increase in plantations.
Australian market is smaller, but is a growing player which is propelled by its robust regulatory framework and high consumer awareness about sustainability. The country’s waste management policies mandate the repurposing of animal fats and used cooking oils for biodiesel production, leading to widespread adoption. Additionally, Australia’s thriving agricultural sector leverages biodiesel for farm machinery, with an annual growth in usage. Urban consumers’ preference for renewable energy further amplifies demand, particularly in cities like Sydney and Melbourne.
KEY MARKET PLAYERS AND COMPETITIVE LANDSCAPE
Wilmar International, Musim Mas, IOI Group, Adani Wilmar, Neste, Sunshine Kaidi, GrainCorp, TotalEnergies, Cargill, Clariant are the key players in the Asia Pacific biodiesel market.
The Asia Pacific biodiesel market is characterized by intense competition which is driven by the presence of both global giants and regional players striving to gain a larger share of the rapidly growing sector. The market’s competitive landscape is shaped by the increasing demand for sustainable and effective renewable energy solutions, which has prompted companies to innovate and differentiate their offerings. Global players leverage their technological expertise and economies of scale to maintain dominance, while regional players focus on customization and localized strategies to carve out niches. Sustainability remains a central theme, with companies competing to offer the most eco-friendly and cost-effective solutions. Additionally, the rise of industrialization and urbanization has intensified competition, as companies vie to secure contracts with major industries and municipalities.
TOP PLAYERS IN THE MARKET
Wilmar International
Wilmar International is a global leader in the biodiesel market, with a strong presence in the Asia Pacific region, particularly in Indonesia and Malaysia. The company leverages its extensive palm oil supply chain to produce cost-effective and scalable biodiesel solutions. Its focus on sustainability has led to the development of eco-friendly biodiesel that aligns with stringent environmental regulations. Wilmar’s strategic partnerships with governments and industries have strengthened its position as a trusted provider of renewable fuels globally.
Neste Corporation
Neste Corporation is a key player in the Asia Pacific biodiesel market, renowned for its expertise in producing high-quality renewable diesel from waste and residue feedstocks. The company’s commitment to innovation has enabled it to address complex challenges faced by industries such as transportation and power generation. Neste’s emphasis on collaboration with regional stakeholders ensures its products align with local regulatory frameworks and consumer preferences. Its robust distribution network across the region has facilitated widespread adoption of its sustainable biodiesel solutions. Through its proactive approach to circular economy practices, Neste continues to set benchmarks for efficiency and environmental responsibility.
Archer Daniels Midland (ADM)
Archer Daniels Midland (ADM) stands out for its specialization in producing biodiesel from diverse feedstocks, including vegetable oils and animal fats. With a strong foothold in the Asia Pacific region, the company focuses on delivering solutions that meet the unique demands of urbanized and industrialized areas. ADM’s dedication to quality and safety has earned it recognition among leading manufacturers and regulatory bodies.
TOP STRATEGIES USED BY KEY PLAYERS
Strategic Partnerships with Governments
Key players in the Asia Pacific biodiesel market have increasingly turned to partnerships with governments to strengthen their market position. These partnerships also facilitate knowledge-sharing and innovation, enabling participants to stay ahead of evolving regulatory landscapes. For instance, collaborations with agricultural exporters have allowed companies to develop specialized biodiesel solutions tailored to local needs, enhancing their relevance in the region.
Investment in Feedstock Diversification
Another major strategy involves substantial investments in diversifying feedstock sources to reduce dependency on traditional resources like palm oil. Companies are exploring alternative feedstocks such as waste oils, algae, and non-edible crops to ensure sustainability and cost-effectiveness. Innovations in bio-refinery technologies have been introduced to address specific industry needs.
Expansion into Emerging Markets
Leading companies are expanding their operations into emerging markets within the Asia Pacific region. By establishing localized production facilities and distribution networks, they can cater to the unique needs of these regions more effectively. This strategy not only reduces costs but also enhances accessibility, allowing companies to build stronger relationships with local businesses and consumers.
RECENT HAPPENINGS IN THE MARKET
- In April 2025, Wilmar International partnered with the Indonesian government to launch a nationwide campaign promoting palm oil-based biodiesel as a sustainable fuel alternative. This initiative strengthened its leadership in the domestic market.
- In June 2023, Neste Corporation announced the acquisition of a small-scale biodiesel plant in Thailand to bolster its supply chain resilience and expand its footprint in Southeast Asia.
- In February 2023, Archer Daniels Midland (ADM) signed a memorandum of understanding with the Indian government to co-develop second-generation biofuels using agricultural residues, aligning with India’s renewable energy goals.
- In September 2022, Wilmar International opened a state-of-the-art R&D facility in Malaysia to explore innovations in algae-based biodiesel, positioning itself as a pioneer in next-generation biofuels.
- In November 2021, Neste Corporation launched a joint venture with a South Korean logistics firm to supply biodiesel-powered generators for rural electrification projects, enhancing its presence in the power generation segment.
MARKET SEGMENTATION
This research report on the Asia Pacific biodiesel market has been segmented and sub-segmented based on the following categories.
By Feedstock
- Vegetable Oil
- Canola Oil
- Soybean Oil
- Palm Oil
- Corn Oil
- Others
- Animal Fats
- Poultry
- Tallow
- White Grease
- Others
By Application
- Fuel
- Automotive
- Marine
- Agriculture
- Power Generation
- Others
By Country
- India
- China
- Japan
- South Korea
- Australia
- New Zealand
- Thailand
- Malaysia
- Vietnam
- Philippines
- Indonesia
- Singapore
- Rest of Asia-Pacific