- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$13.41 BnMarket Estimate, 2026
$15.32 BnMarket Forecast, 2034
$44.35 BnCAGR, 2026–2034
14.21%Asia Pacific Biometrics Market Size, Growth, Trends & Forecast (2026–2034)
The Asia Pacific biometrics market size was calculated to be USD 13.41 billion in 2025, is anticipated to be worth USD 15.32 billion in 2026, and is projected to reach USD 44.35 billion by 2034, growing at a compound annual growth rate (CAGR) of 14.21% during the forecast period from 2026 to 2034. Market growth is propelled by rapid urbanization, massive government-led national ID programs, increasing smartphone and mobile biometric integration, and the convergence of artificial intelligence and machine learning technologies.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 13.41 Billion
- 2026 Current Valuation: USD 15.32 Billion
- 2034 Forecast Valuation: USD 44.35 Billion
- Compound Annual Growth Rate (CAGR): 14.21% (2026–2034)
- Dominant Technology Segment: Face Recognition (captures 35.09% of the total share, driven by public safety and border control)
- Fastest-Growing Technology Segment: Iris Recognition (projected at an 18.5% CAGR, fueled by high accuracy and financial/healthcare security)
- Dominant Functionality Segment: Non-Contact Systems (captured 40.4% market share in 2025 due to post-pandemic hygiene preferences)
- Fastest-Growing Functionality Segment: Combined Systems (projected at a 20.3% CAGR, enhancing multi-modal accuracy and reliability)
- Dominant Component Segment: Hardware (occupied 60.23% market share in 2025 via scanners, cameras, and sensors)
- Fastest-Growing Component Segment: Software (projected at a 22.7% CAGR, driven by AI and machine learning advancements)
- Regional Leadership: China (led the regional market with a 30.4% share in 2025, backed by large-scale deployments and smart city initiatives)
Core Market Drivers
- Government Initiatives & National ID Programs: Large-scale identification deployments like India's Aadhaar program enrolling over 1.3 billion citizens.
- Rising Demand for Mobile Biometrics: Over 70% of sold smartphones featuring fingerprint or facial recognition for secure mobile banking and e-commerce.
Primary Market Restraints & Challenges
- Privacy & Data Security Concerns: Vulnerabilities to data breaches, unauthorized access, and a lack of standardized cross-border privacy laws.
- High Implementation Costs: Substantial capital investments required for hardware installations and specialized technical personnel, challenging SMEs.
Asia Pacific Biometrics Market Segmentation Breakdown
| Segment Category | Largest / Dominant Sub-Segment | Fastest-Growing Sub-Segment |
|---|---|---|
| By Technology | Face Recognition (35.09% Share) | Iris Recognition (18.5% CAGR) |
| By Functionality | Non-Contact Systems (40.4% Share in 2025) | Combined Systems (20.3% CAGR) |
| By Component | Hardware (60.23% Share in 2025) | Software (22.7% CAGR) |
| By Region | China (30.4% Share in 2025) | India, Southeast Asia (High Growth Trajectory) |
Major Industry Players Profiled
Key technology leaders operating in the Asia Pacific biometrics market include NEC Corporation, Fujitsu, Hitachi, Panasonic Corporation, Aware Inc., Thales Group, IDEMIA, Suprema Inc., Hanwang Technology, ZKTeco, Daon Inc., Crossmatch, HID Global, BioEnable Technologies, and Dermalog Identification Systems.
 Download Free Sample Report
Asia Pacific Biometrics Market Size
The Asia Pacific biometrics market size was calculated to be USD 13.41 billion in 2025 and is anticipated to be worth USD 44.35 billion by 2034, from USD 15.32 billion in 2026, growing at a CAGR of 14.21% during the forecast period.
Biometric systems rely on unique physiological or behavioral characteristics such as fingerprints, facial recognition, iris scans, and voice patterns. The region’s rapid urbanization and digital transformation have fuelled the demand for secure and efficient identification solutions. For instance, over 200 million people are expected to migrate to urban areas by 2030, creating a pressing need for scalable biometric systems to manage population growth and enhance public safety. Additionally, advancements in artificial intelligence (AI) and machine learning have significantly improved the accuracy and affordability of biometric technologies. Government agencies across the Asia Pacific region are emphasizing the use of facial recognition technologies at airports to streamline passenger processing and enhance border security.
MARKET DRIVERS
Government Initiatives and National ID Programs
Government-led initiatives and national ID programs are key drivers of the Asia Pacific biometrics market as they necessitate scalable and secure identification systems. India’s Aadhaar program, managed by the Unique Identification Authority of India, has enrolled over 1.3 billion citizens, which creates one of the largest biometric databases globally. This initiative not only enhances social welfare delivery but also strengthens national security by enabling accurate identity verification. These systems are integral to managing the country’s vast population and ensuring compliance with regulatory frameworks.
Rising Demand for Mobile Biometrics
The increasing integration of biometric systems in smartphones is another significant driver. Over 70% of smartphones sold in the Asia Pacific region in 2022 featured fingerprint or facial recognition capabilities. Mobile biometrics are essential for secure mobile banking and e-commerce transactions, particularly in countries like Japan and Singapore where cashless payments are prevalent. Moreover, the growing emphasis on cybersecurity has further propelled the adoption of mobile biometrics. Biometric authentication reduces the risk of unauthorized access compared to traditional passwords by aligning with consumer preferences for convenience and security.
MARKET RESTRAINTS
Privacy Concerns and Ethical Challenges
Privacy concerns and ethical challenges pose significant restraints to the biometrics market, particularly regarding data misuse and surveillance. Unauthorized access to biometric databases can lead to identity theft and breaches of personal privacy. The lack of standardized privacy laws across the region exacerbates this issue while forcing companies to navigate complex regulatory environments. These ethical and legal challenges hinder the seamless adoption of biometric systems, particularly in sensitive applications like healthcare and finance.
High Implementation Costs
The high costs associated with implementing biometric systems also act as a restraint. The Federation of Indian Chambers of Commerce and Industry notes that small and medium enterprises (SMEs) often struggle to afford advanced biometric solutions despite their potential benefits. For example, installing biometric access control systems in workplaces can cost several thousand dollars, deterring smaller players from entering the market. Moreover, the lack of skilled personnel to operate and maintain biometric systems complicates adoption. Only 20.45% of businesses have access to trained professionals capable of deploying biometric technologies.
MARKET OPPORTUNITIES
Integration with AI and IoT
The integration of artificial intelligence (AI) and the Internet of Things (IoT) presents a transformative opportunity for the biometrics market. AI-driven analytics can process vast amounts of biometric data to generate actionable insights and enhance decision-making across industriesThe usese of AI in facial recognition systems for crowd management during large events ensures public safety. Similarly, China’s National Development and Reform Commission emphasizes the role of IoT-enabled biometric systems in smart cities where sensors capture data to optimize resource allocation and reduce congestion.
Expansion into Emerging Economies
Emerging economies in the Asia Pacific offer untapped potential for biometrics driven by industrialization and infrastructure development. Biometric systems are used to monitor workforce attendance and ensure transparency in construction projects. Similarly, Vietnam’s growing manufacturing sector relies on biometrics for factory access control and supply chain optimization. These trends emphasize the vast opportunities for biometric companies to expand their footprint in high-growth markets.
MARKET CHALLENGES
Data Security Vulnerabilities
Data security vulnerabilities pose a significant challenge, particularly in sensitive applications like banking and defense. The Australian Cyber Security Centre warns that cyberattacks targeting biometric databases can compromise national security and undermine public trust in these technologies. Similarly, India’s Ministry of Defence emphasizes the need for robust encryption protocols to protect classified biometric information. The lack of standardized cybersecurity measures across the region exacerbates this issue while forcing companies to invest heavily in securing their systems.
Regulatory Hurdles and Compliance Issues
Regulatory hurdles and compliance issues also present significant challenges to the biometrics market. The International Civil Aviation Organization states that many countries in the region have stringent regulations governing the use of biometric systems while limiting their adoption for commercial purposes. The absence of unified standards across the region creates operational inefficiencies. The importance of establishing unified regulatory frameworks to enable seamless cross-border biometric data sharing while safeguarding data privacy and security.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 14.21% |
| Segments Covered | By Technology, Functionality, Component, and Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis; Segment-Level Analysis; DROC, PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | India, China, Japan, South Korea, Australia, New Zealand, Thailand, Malaysia, Vietnam, Philippines, Indonesia, Singapore, Rest of Asia-Pacific |
| Market Leaders Profiled | NEC Corporation, Fujitsu, Hitachi, Panasonic Corporation, Aware Inc., Thales Group, IDEMIA, Suprema Inc., Hanwang Technology, ZKTeco, Daon Inc., Crossmatch, HID Global, BioEnable Technologies, Dermalog Identification Systems |
SEGMENTAL ANALYSIS
By Technology Insights
The face recognition segment dominated the Asia-Pacific biometrics market and accounted for a 35.1% share in 2025. This dominance was driven by its friction-free, contact-free operational model, high user acceptance, low cost of deployment on existing digital cameras, and seamless adaptability across both public infrastructure and consumer electronic devices. Spurred by immediate national security concerns and accelerated infrastructure upgrades, face recognition technology now dominates the Asia-Pacific biometrics industry, with widespread implementation in public safety and automated border control. Furthermore, as per the International Civil Aviation Organization (ICAO), major global airports are modernizing automated border control systems to significantly improve passenger throughput and shorten clearance wait times at immigration checkpoints. The direct relationship between these deployment statistics and the market lies in the large-scale procurement of enterprise facial recognition engines by government bodies, municipal transport networks, and border control agencies seeking to automate civilian verification without physical bottlenecks.
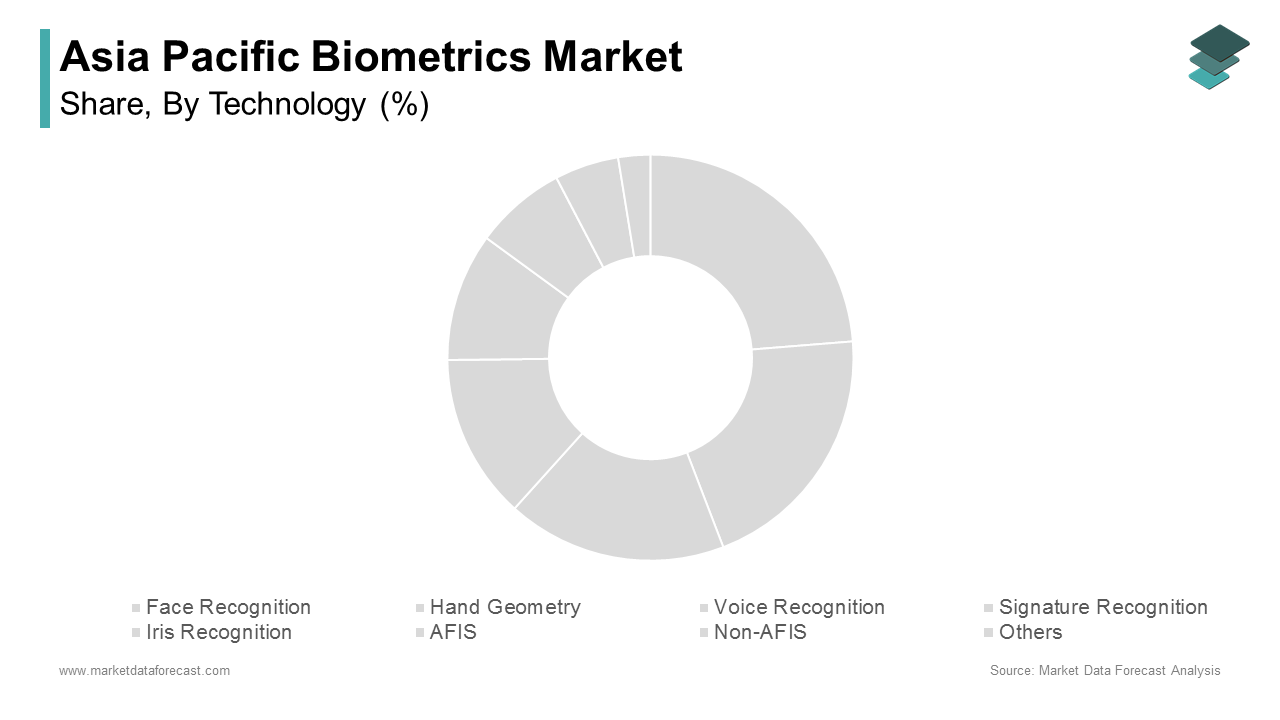
A rapid shift toward frictionless user experiences is fuelling the widespread adoption of face recognition technology. As a result, this technology has become the primary standard for secure, instantaneous authentication across Asia-Pacific mobile devices and digital commerce platforms. According to the GSM Association (GSMA), rising digital literacy and expanding connectivity across Asian economies are driving a surge in overall smartphone adoption rates. In addition, according to the National Payments Corporation of India (NPCI), the Unified Payments Interface (UPI) platform reached an all-time milestone by processing 16.58 billion transactions in a single month during October 2024. The direct relation to the market is that massive smartphone adoption obligates software developers, banking applications, and e-commerce platforms to embed facial recognition application programming interfaces, generating a continuous demand stream for facial biometric algorithms across the private sector. The iris recognition segment is predicted to witness the highest CAGR of 18.5% over the forecast period. This swift growth is fuelled by the unparalleled accuracy of iris patterns, which remain unchanged throughout human life and offer superior resistance against spoofing compared to other biometric modalities.
The rapid expansion of iris recognition within the Asia-Pacific biometrics sector is primarily fueled by state-led initiatives aimed at resolving critical framework deficiencies. This growth is propelled by its rapid deployment in large-scale national healthcare networks and rural financial inclusion initiatives. According to the Unique Identification Authority of India (UIDAI), the Aadhaar system covers over 1.3 billion registered citizens using multi-modal biometrics to streamline distribution systems and secure banking access. Moreover, as per the Reserve Bank of India (RBI), large private and public sector commercial banks are selectively incorporating artificial intelligence and advanced identity scanning capabilities to prevent high-value transactional fraud. The relation between these metrics and the market is that governments and microfinance institutions are compelled to purchase specialized iris scanners to achieve near-perfect accuracy in extreme operational environments where manual labor degrades fingerprints.
Strict regulatory mandates now require foolproof security access within critical healthcare and banking infrastructures. Driven by this zero-tolerance approach to data breaches, iris recognition has emerged as the fastest-growing technology segment in the Asia-Pacific biometrics market. As per the Financial Services Agency (FSA) of Japan, regional financial institutions are adopting robust cybersecurity networks and upgraded electronic authentication frameworks to secure retail banking platforms against external threats. Additionally, according to the Ministry of Health and Welfare of South Korea, major designated tertiary general hospitals are enforcing strict clinical accreditation metrics and data protection standards to bolster overall patient security and operational quality. These regulatory mandates directly accelerate market spending by forcing high-security facilities to transition away from basic security cards toward error-free iris scanning hardware.
By Functionality Insights
The contact systems segment led the Asia Pacific biometrics market and captured a 54.2% share in 2025. Factors such as the deeply entrenched global presence of fingerprint scanners, physical touch sensors on smart devices, and legacy biometric reader deployments across public and enterprise security setups have contributed to the leading position of this segment. Deeply embedded in national ID programs and workforce attendance systems, contact-based technology continues to secure its position as the market leader in the Asia-Pacific biometrics sector. According to the Unique Identification Authority of India (UIDAI), total biometric authentication requests powered by its multi-modal ecosystem surpassed 2,707 crore transactions in the 2024 to 2025 fiscal period. Furthermore, as per the Asian Professional Security Association (APSA), commercial facilities across the region are upgrading baseline physical workforce access management terminals to counter traditional operational vulnerabilities. Long-term infrastructure investment in fingerprint scanning technology has built a vast foundation of deployed hardware. This base yields steady contractual revenue through systemic maintenance, equipment replacements, and recurring software licensing.
Affordable integration with mobile hardware and low-cost POS terminals keeps contact-based systems leading the Asia-Pacific biometrics market. According to the National Bureau of Statistics of China, regional electronics facilities expanded mobile phone output to reach 1.67 billion total units in 2024, which includes 1.25 billion smartphones. Additionally, as per the Asian Development Bank (ADB), formal financial institutions are expanding mobile banking operations and micro-transaction networks to bridge the digital gap for small retail merchants. High-volume silicon fabrication drives down sensor component costs, positioning contact fingerprint scanners as the most economically viable option for large-scale hardware deployment.
The combined or multimodal biometrics segment is estimated to register the fastest CAGR of 20.3% from 2026 to 2034 due to the rising necessity for multi-factor authentication to combat sophisticated spoofing attacks, fake biometric templates, and high-risk digital fraud.
An escalating demand for high-assurance identity verification within sovereign defence operations is fast-tracking the expansion of this segment. According to the Ministry of Defence of India, border security forces are introducing advanced command systems and digital public infrastructure integrations to fortify tactical cross-border physical security. Besides, as per the Civil Aviation Administration of China (CAAC), major international airports are incorporating multi-layered digital tracking, palm vein identification, and facial matching technologies to refine overall terminal check-in safety standards. Sovereign procurement trends reveal a strong preference for multi-sensor hardware architectures; agencies are combining separate biometric identifiers to eliminate system failure in critical transit and military defense applications.
An urgent need to combat sophisticated generative AI threats and digital banking spoofing attacks is boosting this segment's growth. According to Sumsub, identity spoofing attempts involving deepfakes across the Asia Pacific region witnessed a prominent 194% year-on-year surge in 2024. Moreover, as per IBM Security, the global average financial damage caused by a data breach reached a record milestone of 4.88 million dollars per incident in 2024. In response to shifting market demands, enterprise data hubs and commercial banks are phasing out single-sensor authentication systems. They are moving toward integrated biometric frameworks that require simultaneous validation of face, voice, and true liveness.
By Component Insights
In 2025, the hardware segment held a 60.3% majority share in the Asia Pacific biometrics market because every biometric deployment requires physical infrastructure, including optical lenses, infrared cameras, capacitive fingerprint sensors, thermal modules, and specialized microcontrollers. Massive, government-led public sector procurement programs for large-scale physical devices are bolstering the market share of this segment. According to the Unique Identification Authority of India, national identity initiatives completed over 2 crore mandatory biometric updates for school children through dedicated school-level camps. Furthermore, as per the National Bureau of Statistics of China, production of smart wearable devices and high-tech electronic components expanded significantly to support urban digital network infrastructure. Sovereign infrastructure spending is a primary supporter of the hardware sector, with massive public works budgets translating into high-volume physical sensor contracts for original equipment manufacturers.
The explosive proliferation of embedded biometric modules across the consumer electronics sector is one of the major factors behind the supremacy of this segment. According to the Ministry of Industry and Information Technology of China, the added value of major enterprises in the electronic information manufacturing sector expanded by 11.8% year on year. In addition, as per the GSMA, global eSIM smartphone connections are projected to reach approximately 850 million by 2025. Fulfilling global consumer demand for biometric devices hinges entirely on component logistics, forcing electronics assembly lines to maintain a high-volume, uninterrupted pipeline of physical sensors.
The software segment is anticipated to witness the fastest CAGR of 22.7% during the forecast period. The main driver of this growth is the shifting industry emphasis toward cloud-based matching engines, machine learning algorithms, artificial intelligence, computer vision, and biometric software-as-a-service business models.
This segment grows even faster due to the widespread integration of advanced Artificial Intelligence and Machine Learning matching engines. According to sources, only 25% of organizations already using artificial intelligence have successfully developed an enterprise-wide AI strategy. Furthermore, as per the National Institute of Standards and Technology, facial recognition algorithms undergo testing under unconstrained real-world variations, including partial face occlusion from masks and headwear, to benchmark system accuracy. Market demand is shifting toward software-driven performance enhancements, with organizations purchasing advanced algorithm licenses to optimize the recognition capabilities of legacy camera endpoints.
An accelerating corporate and institutional transition toward scalable, cloud-based biometric authentication platforms is propelling the expansion of this market segment. As per mobile network reports published by the GSMA, the Open Gateway initiative has expanded to make 94 network APIs commercially available to enterprise developers across 21 markets globally. Additionally, according to research, cloud computing capabilities and identity access management systems are increasingly deployed as a service to deliver massively scalable IT capabilities. Enterprises are moving away from traditional, one-time hardware investments and toward subscription-based software deployments, providing software vendors with predictable, recurring revenue streams.
REGIONAL ANALYSIS
China Biometrics Market Analysis
China remained the top-performing region in the Asia Pacific biometrics market and occupied a 30.4% share in 2025. The country’s prominence in the regional market was supported by its massive industrial electronics manufacturing base paired with extensive municipal adoption of public surveillance and citizen verification infrastructure. According to the National Bureau of Statistics of China, domestic industrial facilities produced 1.25 billion smartphone units in 2024 while national value added in electronic information manufacturing grew by 11.8% year on year. Besides, as per the Ministry of Industry and Information Technology of China, national agencies will formulate more than 50 industrial standards for artificial intelligence by 2026 to guide the high-quality development of smart sectors.
India Biometrics Market Analysis
India was positioned second in the Asia Pacific biometrics market and secured a significant share in 2025. This growth of the Indian market was accelerated by the world's largest sovereign identity framework and rapid fintech expansion. According to the Unique Identification Authority of India, the national Aadhaar program has successfully generated more than 144 crore identity numbers and enabled over 2,707 crore authentications during the 2024 to 2025 period. Additionally, as per the National Payments Corporation of India, the unified payments interface recorded 16.58 billion transactions valued at 23.49 lakh crore rupees in October 2024 alone, marking a 45% year-on-year growth. Mandatory biometric eKYC regulations across state welfare networks and digital banking systems continuously drive demand for fingerprint scanners, iris modules, and facial verification software nationwide.
Japan Biometrics Market Analysis
Japan plays a major role in the Asia Pacific biometrics market. The country prioritizes privacy-compliant, contact-free authentication across commercial banking and public transit. As per the Digital Agency of Japan, public online service platforms are being expanded across financial and administrative systems to streamline authentication and secure transactions. Furthermore, according to the Immigration Services Agency of Japan, automated facial recognition gates have been deployed across major international airports to efficiently process a growing volume of inbound travelers, targeting 40 million annual visitors. These empirical metrics highlight how Japan's aging demographic and high standards for security drive commercial investment into automated, high-precision biometric terminals.
South Korea Biometrics Market Analysis
South Korea maintains a noteworthy share in the Asia Pacific biometrics market. A major driver of the country's prominent standing is its early embrace of mobile biometric solutions coupled with robust, government-backed smart city initiatives. According to the Ministry of Science and ICT of South Korea, the number of 5G mobile communication subscribers nationwide has surpassed 33.85 million, representing a substantial majority of the national population. Additionally, as per the Bank of Korea, internet-only banks and mobile transactions have expanded rapidly to comprise 25.7% of total transactions. Ultra-high-speed mobile connectivity empowers software developers to deploy low-latency cloud matching and multimodal biometric security solutions nationwide.
Australia Biometrics Market Analysis
Australia is also a key player in the Asia Pacific biometrics market due to strict national security standards, automated border clearance programs, and digital government transformation. According to the Department of Home Affairs of Australia, nearly three-in-four travellers are screened through automated SmartGates to accelerate secure processing across international airports. Moreover, as per the Digital Transformation Agency of Australia, the digital identity application has reached over 10.5 million Australians to interact with more than 130 services across 40 different government agencies. These statistics demonstrate how Australia's public sector investments in automated immigration infrastructure drive long-term procurement contracts for biometric system integrators.
COMPETITION OVERVIEW
The competitive ecosystem within the Asia Pacific biometrics sector exhibits high intensity, characterized by rapid technological innovation and expanding commercial deployments across public, enterprise, and consumer domains. Industry leaders compete vigorously by integrating artificial intelligence algorithms to enhance facial, iris, and fingerprint matching accuracy while expanding into contactless and multimodal verification tools. Competition centres heavily around securing massive government contracts for national digital identity frameworks, smart city security, and automated airport border management systems. Concurrently, financial technology expansion fuels intense rivalry among vendors offering embedded liveness verification, fraud prevention, and biometric payment authentication. Global technology conglomerates face stiff challenges from domestic manufacturers and local software developers who capitalize on lower operational costs, regional supply chain advantages, and tailored regulatory capabilities. To maintain leadership, primary participants frequently form strategic partnerships with local system integrators, expand cloud identity platforms, and continuously adapt to evolving regional data privacy laws. This multi-layered rivalry fosters rapid, continuous innovation across all major digital identity applications.
KEY MARKET PLAYERS
Major Players in the Asia Pacific Biometrics market include
- NEC Corporation
- Fujitsu
- Hitachi
- Panasonic Corporation
- Aware Inc.
- Thales Group
- IDEMIA
- Suprema Inc
- Hanwang Technology
- ZKTeco
- Daon Inc.
- Crossmatch
- HID Global
- BioEnable Technologies
- Dermalog Identification Systems
Top Strategies Used by Key Market Participants
Key industry players in the Asia Pacific biometrics ecosystem prioritize strategic alliances with regional government bodies to deploy large-scale identity programs, national border automation platforms, and civil registries. Companies heavily invest in local research facilities to refine multimodal biometric engines, integrating artificial intelligence and liveness detection to eliminate identity spoofing and meet varying regulatory compliance standards. Commercial expansion relies on partnerships with financial institutions and telecommunication providers to integrate contactless face and fingerprint authentication into digital payments and mobile banking applications. Additionally, providers leverage cloud-based delivery models, offering identity verification as continuous services that guarantee steady recurring revenues across expanding enterprise networks.
Leading Players in the Market
- NEC Corporation provides advanced artificial intelligence and biometric identity solutions across the Asia Pacific region. The organization delivers multimodal authentication tools like facial matching and iris scanning tailored for defense, governance, and public transportation infrastructure. To strengthen its regional standing, the company consistently implements strategic real-world deployments. The business launched dynamic recognition tools capable of simultaneously authenticating crowds in motion. Furthermore, the enterprise collaborated with major global payment networks to deploy face recognition checkout platforms across Southeast Asian retail locations. These targeted initiatives significantly elevate operational capabilities and secure long term growth throughout key regional commercial sectors.
- IDEMIA specializes in augmented identity technologies, providing access verification, digital security software, and physical identity cards across Asia Pacific markets. The organization supplies governments, financial networks, and telecom operators with reliable authentication hardware and biometric enrollment software. The enterprise continually scales operations through strategic geographic expansions and tailored regional offerings. Recent enterprise actions include deploying friction-free passenger processing solutions at major regional international airports to speed up customs and border processing. Additionally, the business partnered with local banking networks to introduce biometric payment cards, directly supporting financial cybersecurity and expanding its footprint within fast-growing Asian consumer markets.
- Thales Group offers high-security identity verification platforms, border control automation, and advanced data encryption systems tailored for complex regulatory environments in the Asia Pacific region. The enterprise delivers end-to-end digital identity solutions to public agencies and private enterprises alike. To reinforce its regional competitive positioning, the company aggressively expanded its localized research centers to customize liveness detection and multimodal biometrics. The firm recently completed key integrations with civil registration bodies across multiple Southeast Asian nations and secured government infrastructure contracts for cloud-based identity verification, ensuring strong institutional relationships and long-term service continuity.
RECENT HAPPENINGS IN THE MARKET
- In December 2023, Mastercard, in collaboration with the Japanese technology firm NEC, aimed to introduce a checkout system utilizing facial recognition. This partnership is anticipated to allow NEC to offer more comprehensive checkout solutions and strengthen the Asia Pacific Biometrics Market presence.
- In March 2024, NEC Corporation, a global technology provider, opened a new operations center in Johor. This expansion is anticipated to allow NEC to offer localized support capabilities and strengthen the Asia Pacific Biometrics Market presence.
- In April 2024, DynaTouch, a kiosk solutions provider, acquired KioWare, a kiosk management software company. This acquisition is anticipated to allow DynaTouch to offer more comprehensive kiosk solutions and strengthen the Asia Pacific Biometrics Market presence.
- In April 2024, NEC Corporation, an identity solutions provider, appointed a new regional chief executive officer in Singapore. This executive leadership change is anticipated to allow NEC to execute sharper expansion strategies and strengthen the Asia Pacific Biometrics Market presence.
- In April 2025, NEC Asia Pacific, an identity solutions provider, achieved environmental management accreditation in Singapore. This formal operational milestone is anticipated to allow NEC to secure larger sustainability-focused tenders and strengthen the Asia Pacific Biometrics Market presence.
MARKET SEGMENTATION
This research report on the Asia Pacific biometrics market has been segmented and sub-segmented based on technology, functionality, component, and region.
By Technology
- Face Recognition
- Hand Geometry
- Voice Recognition
- Signature Recognition
- Iris Recognition
- AFIS
- Non-AFIS
- Others
By Functionality
- Contact
- Non-contact
- Combined
By Component
- Hardware
- Software
By Region
- India
- China
- Japan
- South Korea
- Australia
- New Zealand
- Thailand
- Malaysia
- Vietnam
- Philippines
- Indonesia
- Singapore
- Rest of Asia-Pacific