- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$664 MnMarket Estimate, 2026
$720.24 MnMarket Forecast, 2034
$1,380 MnCAGR, 2026–2034
8.47%Asia Pacific Laboratory Filtration Market Size, Growth, Trends & Forecast (2026–2034)
The Asia Pacific laboratory filtration market size was valued at USD 664 million in 2025, is anticipated to reach a valuation of USD 720.24 million in 2026, and is projected to scale to USD 1,380 million by 2034, growing at a compound annual growth rate (CAGR) of 8.47% during the forecast period from 2026 to 2034. Market expansion across the region is primarily driven by surging biopharmaceutical production, rigorous water and food safety regulations, and expanding clinical research investments in economic powerhouses like China and India.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 664 Million
- 2026 Current Valuation: USD 720.24 Million
- 2034 Forecast Valuation: USD 1,380 Million
- Compound Annual Growth Rate (CAGR): 8.47% (2026–2034)
- Leading Country Market: China (holding approximately 30% market share, anchored by a massive generic drug manufacturing and biotech base)
- Key Countries Covered: India, China, Japan, South Korea, Australia, New Zealand, Thailand, Malaysia, Vietnam, Philippines, Indonesia, Singapore, and Rest of Asia-Pacific
Core Market Drivers & Opportunities
- Biopharmaceutical Manufacturing Surge: Massive expansion in biologics, biosimilars, and vaccine production (with APAC accounting for 35% of global pharmaceutical production by volume).
- Stringent Safety Regulations: Strict government frameworks on drinking water quality and foodborne illness prevention requiring microfiltration and ultrafiltration testing.
- Single-Use Technologies: Growing adoption of disposable sterile filters and modular membrane capsules in bioprocessing to eliminate cross-contamination risks.
Primary Market Restraints & Challenges
- High Initial Capital Outlay: Prohibitive upfront costs for advanced tangential flow systems and automated sterile filtration units, restricting adoption among SMEs.
- Skilled Labor Shortages: Limited local technical expertise in membrane chemistry and process optimization, alongside supply chain volatility and counterfeit risks.
Market Segmentation
| Segment Category | Largest Segment | Fastest-Growing Segment |
|---|---|---|
| By Technology | Microfiltration (Dominates due to widespread applications in sterilization, clarification, and vaccine processing) | Ultrafiltration (CAGR ~10.2% driven by protein concentration and monoclonal antibody R&D) |
| By Product | Membranes (Captures leading share as the core filtering medium across microfiltration and ultrafiltration systems) | Syringe Filters (CAGR ~11.4% powered by fast sample preparation needs in analytical chromatography) |
| By End User | Pharmaceutical & Biopharmaceutical Companies (Major consumers driven by drug manufacturing compliance) | Academic & Research Institutes (CAGR ~10.1% fueled by rising government science expenditures) |
Major Industry Players Profiled
Key global life sciences and filtration technology leaders dominating the Asia Pacific market include Merck KGaA, GE Healthcare, Sartorius Group, 3M Purification Inc., Thermo Fisher Scientific Inc., Danaher Corporation, Cantel Medical Corporation, Cuno, Dow Water & Process Solutions, FilmTec Corporation, and Sigma-Aldrich Corporation.
Asia Pacific Laboratory Filtration Market Size
The size of the Asia Pacific laboratory filtration market was worth USD 664 million in 2025. The Asia Pacific market is anticipated to grow at a CAGR of 8.47% from 2026 to 2034 and be worth USD 1,380 million by 2034, up from USD 720.24 million in 2026.
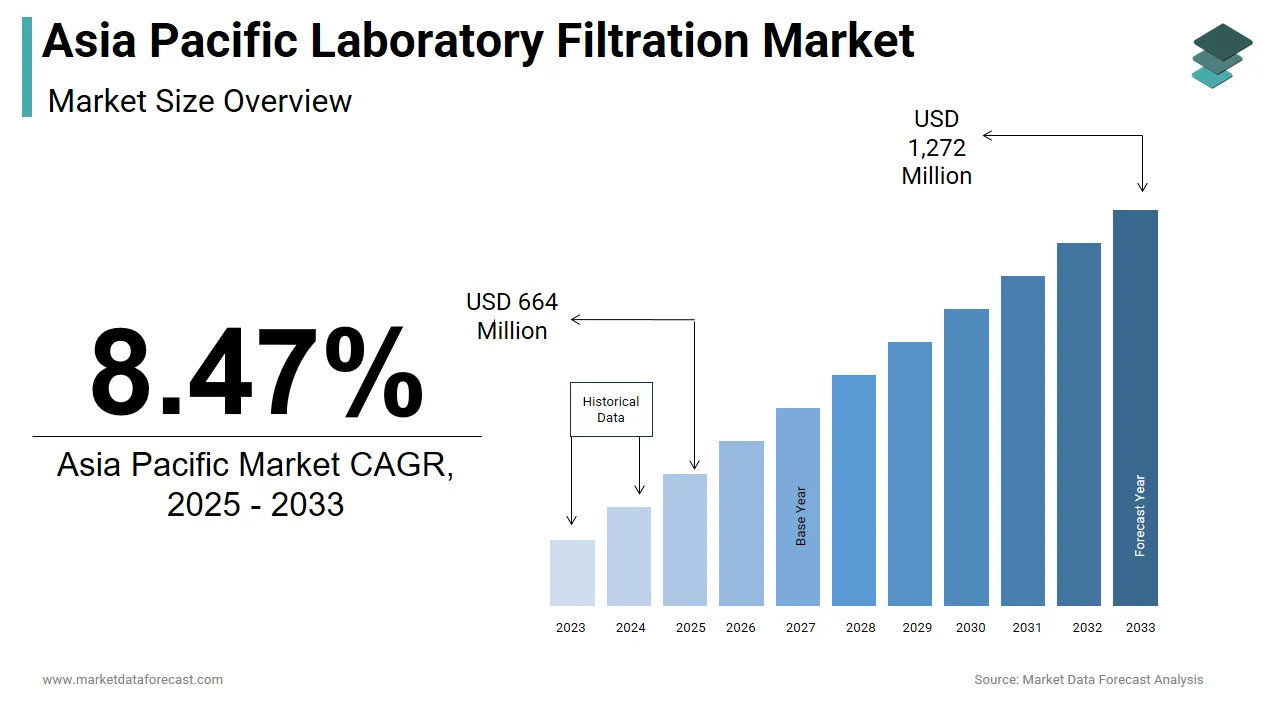
Asia-Pacific is witnessing a paradigm shift towards high-precision analytical techniques driven by stringent regulatory standards and increasing research expenditure. According to the United Nations Educational, Scientific and Cultural Organization, research and development expenditure in Asia-Pacific has increased by 12% annually over the past decade, with China and India leading the investment surge. According to the World Health Organization, the Asia-Pacific region accounts for nearly 40% of global vaccine production, necessitating robust sterile filtration processes to ensure product safety and efficacy. Furthermore, as revealed by data from the Asian Development Bank, water scarcity affects over 60% of the population in the region, driving extensive laboratory testing for water quality and purification efficiency. The proliferation of contract research organizations in countries like Singapore and South Korea further amplifies the demand for advanced filtration consumables and systems. These structural dynamics underscore the essential role of laboratory filtration in maintaining quality control and accelerating innovation across healthcare and industrial sectors in the Asia Pacific region.
MARKET DRIVERS
Expansion of Biopharmaceutical Manufacturing and Clinical Research
The rapid expansion of the biopharmaceutical industry in the Asia Pacific region is propelling the expansion of the Asia-Pacific laboratory filtration market. Governments across the region are actively promoting local drug manufacturing to reduce dependency on imports and enhance healthcare security. According to the International Federation of Pharmaceutical Manufacturers and Associations, the Asia Pacific region now accounts for 35% of global pharmaceutical production by volume, with a significant focus on biologics and biosimilars. Biologics require complex downstream processing where sterile and tangential flow filtration are critical for removing contaminants and concentrating active ingredients. According to the Chinese National Medical Products Administration, over 500 new biological drugs entered clinical trials in China in the last three years, each requiring extensive filtration during development and production. Similarly, India, known as the pharmacy of the world, produces over 60% of global vaccines, which rely heavily on membrane filtration for sterilization and viral removal. The establishment of large-scale bioparks in Singapore and South Korea has attracted multinational corporations to set up research and manufacturing facilities. These facilities utilize advanced single-use filtration technologies to minimize cross-contamination and improve process efficiency. The increasing number of clinical trials in the region further drives demand for high-purity filtration products used in sample preparation and analysis. This robust growth in biopharma creates a sustained and expanding customer base for laboratory filtration suppliers.
Stringent Regulatory Standards for Water and Food Safety
Increasingly stringent regulatory frameworks governing water quality and food safety are significantly driving the adoption of advanced laboratory filtration techniques in the Asia Pacific region, which is further aiding the regional market expansion. Public health concerns regarding contamination have prompted governments to enforce stricter testing protocols for drinking water, wastewater, and food products. According to the World Health Organization, approximately 2 billion people globally use drinking water sources contaminated with feces, with a substantial proportion located in Asia. In response, countries like Japan and Australia have implemented rigorous water quality standards requiring frequent laboratory testing using microfiltration and ultrafiltration methods to detect pathogens and particulates. According to the Food and Agriculture Organization of the United Nations, foodborne illnesses affect an estimated 150 million people in the Southeast Asia and Western Pacific regions annually. To combat this, regulatory bodies in countries like Thailand and Vietnam mandate comprehensive microbiological testing of food exports, which relies on membrane filtration for bacterial isolation and identification. The strict import requirements for Asian agricultural products also force local producers to adopt international standard filtration testing methods to maintain market access. Laboratories are upgrading their capabilities with high efficiency particulate air filters and sterile membrane discs to meet these compliance needs. This regulatory pressure ensures consistent demand for high-quality filtration consumables and equipment across public and private testing facilities.
MARKET RESTRAINTS
High Initial Costs of Advanced Filtration Systems
The substantial initial capital investment required for advanced laboratory filtration systems is a significant restraint on market growth, particularly for small and medium-sized enterprises and academic institutions. High-performance filtration technologies such as tangential flow filtration systems and automated sterile filtration units involve sophisticated engineering and premium materials which command high prices. According to the Asian Development Bank, small and medium-sized enterprises constitute over 90% of businesses in the Asia Pacific region but often lack the financial resources to invest in state-of-the-art laboratory equipment. The cost of importing these systems is further exacerbated by tariffs and logistics expenses in countries with limited local manufacturing capabilities. Many research laboratories in developing nations like Indonesia and the Philippines operate on constrained budgets, forcing them to rely on outdated or less efficient filtration methods. This financial barrier limits the adoption of innovative filtration solutions that could enhance research productivity and data accuracy. Additionally, the maintenance and calibration of advanced systems require specialized technical expertise, which adds to the operational costs. The lack of flexible financing options or leasing models for laboratory equipment further discourages procurement. Consequently, many potential users delay upgrades or opt for lower-quality alternatives, compromising the overall efficiency and reliability of their laboratory processes. This economic constraint restricts the widespread penetration of premium filtration technologies in the region.
Limited Technical Expertise and Skilled Workforce
A shortage of skilled personnel trained in the operation and maintenance of advanced laboratory filtration systems poses a significant challenge to the Asia Pacific market. Effective use of complex filtration technologies requires a deep understanding of membrane chemistry, fluid dynamics, and process optimization, which is not always available in the local workforce. According to the International Labour Organization, there is a significant skills gap in the science, technology, engineering, and mathematics sectors in many Asia Pacific countries, with only 30% of graduates possessing the practical skills required by modern laboratories. In rural areas and smaller diagnostic centers, staff often receive minimal training on new equipment, leading to improper usage and frequent breakdowns. This lack of expertise results in suboptimal performance, reduced filter lifespan, and inconsistent experimental results. The high turnover rate of skilled laboratory technicians further exacerbates the problem as experienced staff migrate to better-paying opportunities in developed countries or other industries. Training programs provided by manufacturers are often insufficient to bridge this gap due to language barriers and logistical challenges in reaching remote locations. The absence of standardized certification courses for laboratory filtration specialists means that knowledge transfer is informal and inconsistent. This human resource deficit hinders the effective adoption of advanced filtration technologies and limits the ability of laboratories to maximize the potential of their investments.
MARKET OPPORTUNITIES
Integration of single-use technologies in bioprocessing
The increasing adoption of single-use technologies in biopharmaceutical manufacturing is a significant opportunity for the laboratory filtration market in the Asia Pacific region. Single-use systems eliminate the need for cleaning and sterilization between batches, reducing the risk of cross-contamination and improving operational efficiency. According to the BioProcess International Conference, single-use technology adoption in Asia Pacific biopharma facilities has grown by 20% annually as companies seek to accelerate time to market for new drugs. These systems rely heavily on disposable sterile filters and membrane capsules, which generate recurring revenue streams for filtration manufacturers. The flexibility of single-use filtration allows for rapid scale-up from laboratory to pilot and commercial production, facilitating agile drug development. Major contract manufacturing organizations in Singapore and India are investing in single-use suites to attract global pharmaceutical clients. This trend drives demand for high-quality pre-sterilized filtration products that meet strict regulatory standards. Manufacturers can innovate by developing customized single-use filtration assemblies tailored to specific bioprocess needs. The shift towards modular and flexible manufacturing facilities further supports the integration of disposable filtration solutions. As the biopharma sector continues to expand, the reliance on single-use technologies will create sustained growth opportunities for suppliers of disposable laboratory filtration products.
Growing Environmental Monitoring and Sustainability Initiatives
Rising environmental awareness and government initiatives towards sustainability create lucrative opportunities for the laboratory filtration market in the Asia Pacific region. Countries are implementing stricter regulations on industrial emissions and wastewater discharge, requiring extensive monitoring and testing. According to the United Nations Environment Programme, air pollution causes over 4 million premature deaths annually in Asia, driving demand for accurate air quality monitoring that utilizes high-efficiency particulate filters. Laboratories are increasingly employing advanced filtration methods to analyze particulate matter, heavy metals, and volatile organic compounds in air and water samples. The push for circular economy practices encourages the development of recyclable and bio-based filtration materials, which appeal to environmentally conscious consumers and corporations. Governments in countries like South Korea and Japan are funding research projects focused on green chemistry and sustainable laboratory practices. This support fosters innovation in eco-friendly filtration products that reduce plastic waste and energy consumption. Industrial facilities are also investing in on-site laboratory testing to ensure compliance with environmental standards, driving demand for robust filtration equipment. The growing corporate social responsibility agenda among multinational companies operating in the region further promotes the adoption of sustainable laboratory practices. These factors collectively drive the demand for innovative and environmentally responsible filtration solutions.
MARKET CHALLENGES
Supply Chain Disruptions and Raw Material Volatility
The Asia-Pacific laboratory filtration market faces significant challenges due to supply chain disruptions and volatility in raw material prices. Many key components for filtration membranes, such as polymers and specialized plastics, are sourced from a limited number of global suppliers, making the market vulnerable to geopolitical tensions and trade restrictions. According to the World Trade Organization, global supply chain bottlenecks have increased lead times for laboratory consumables by up to 40% in recent years, affecting availability in the Asia Pacific region. Fluctuations in crude oil prices directly impact the cost of polymer-based filtration materials, leading to unpredictable pricing for end users. Natural disasters such as typhoons and earthquakes in major manufacturing hubs like Japan and Taiwan can disrupt production and logistics networks, causing sudden shortages. The reliance on imported raw materials in countries with limited domestic chemical industries exacerbates these vulnerabilities. Currency fluctuations in emerging markets further complicate procurement planning and cost management for local distributors. These supply chain instabilities force laboratories to maintain higher inventory levels, tying up capital and increasing storage costs. The lack of transparency in the supply chain makes it difficult for buyers to anticipate disruptions and mitigate risks. Addressing these vulnerabilities requires diversification of sourcing strategies and investment in local manufacturing capabilities, which remain underdeveloped in many parts of the region.
Counterfeit Products and Quality Control Issues
The prevalence of counterfeit filtration products and inconsistent quality control standards poses a serious threat to the integrity of the Asia-Pacific laboratory filtration market. The ease of online commerce and fragmented regulatory enforcement in some countries facilitate the distribution of substandard and fake filtration membranes and devices. According to the World Health Organization, up to 10% of medical products in low- and middle-income countries are substandard or falsified, including laboratory consumables. Counterfeit filters often fail to meet specified pore sizes and retention rates, leading to inaccurate test results and compromised sample integrity. This is particularly dangerous in clinical diagnostics and pharmaceutical quality control where precision is critical. The lack of robust anti-counterfeiting measures and traceability systems allows these inferior products to enter the supply chain unnoticed. Local manufacturers in some regions may cut corners to reduce costs, resulting in variable product quality that undermines user trust. The absence of harmonized quality standards across different Asia Pacific countries makes it challenging to enforce consistent quality control. Laboratories may unknowingly purchase low-quality products due to lower prices, risking experimental failure and regulatory non-compliance. Combating this issue requires stronger regulatory collaboration, enhanced authentication technologies, and consumer education, which are currently lacking in many parts of the region.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Technology, Product, End User, and Country. |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered |
|
| Market Leaders Profiled | Merck LGaA, GE Healthcare, Sartorius Group, 3M Purification Inc., Thermo Fisher Scientific Inc., Danaher Corporation, Cantel Medical Corporation, Cuno, Dow Water & Process Solutions, FilmTec Corporation, GE Healthcare, and Sigma-Aldrich Corporation. |
SEGMENTAL ANALYSIS
By Technology Insights
The microfiltration segment accounted for the dominant share of the regional market in 2025. The dominance of the microfiltration segment in this regional market is driven by its widespread application in sterilization, clarification, and cell harvesting across various industries. This technology utilizes membranes with pore sizes ranging from 0.1 to 10 micrometres, effectively removing bacteria, suspended solids and large particles without altering the chemical composition of the sample. The dominance of microfiltration is driven by its critical role in the biopharmaceutical sector for sterile filtration of buffer media and final drug products. According to the World Health Organization, over 60% of global vaccine production occurs in the Asia Pacific region, where microfiltration is indispensable for ensuring sterility and safety. The technology is also extensively used in the food and beverage industry for clarifying juices, wines, and beer, which are major export commodities for countries like Australia and New Zealand. According to the Food and Agriculture Organization of the United Nations, Asia is the largest producer of fruit juices, necessitating robust clarification processes to meet international quality standards. Additionally, microfiltration is a standard technique in environmental laboratories for preparing water samples for analysis by removing particulates that could interfere with sensitive instruments. Its versatility, cost-effectiveness, and ease of integration into existing laboratory workflows make it the preferred choice for routine filtration tasks. The established infrastructure and familiarity with microfiltration protocols among laboratory technicians further cement its market leadership.
However, the ultrafiltration segment is the fastest-growing segment in the Asia-Pacific laboratory filtration market and is estimated to showcase a CAGR of 10.2% over the forecast period owing to its increasing use in protein concentration, desalting, and buffer exchange in biopharmaceutical research and development. Unlike microfiltration, ultrafiltration uses membranes with smaller pore sizes, typically between 1 and 100 nanometers, allowing for the separation of macromolecules based on molecular weight. The boom in monoclonal antibody and vaccine development in the region has created a surge in demand for ultrafiltration devices. According to the BioProcess International Conference, the number of biologic drug candidates in clinical trials in Asia Pacific has increased by 25% in the last five years. Each stage of downstream processing requires precise concentration and purification steps where ultrafiltration is superior. The technology is also gaining traction in academic research for isolating specific proteins and nucleic acids. The availability of single-use ultrafiltration cassettes and centrifugal devices has simplified workflows and reduced cross-contamination risks. Laboratories are increasingly adopting these convenient formats to accelerate research timelines. The versatility of ultrafiltration in handling complex biological samples makes it an essential tool for modern life science research, driving its rapid adoption.
By Product Insights
The membranes segment led the market by capturing the leading share of the regional market in 2025 due to their fundamental role as the core filtering medium in various filtration technologies. These thin selective barriers are made from materials such as polyethersulfone, polyvinylidene fluoride, and cellulose acetate, offering diverse pore sizes and chemical compatibilities. The dominance of membranes is driven by their universal application in microfiltration, ultrafiltration, and reverse osmosis systems across pharmaceutical, food, and environmental sectors. According to Global Water Intelligence, the Asia Pacific region accounts for 45% of global membrane capacity installations, reflecting the heavy reliance on this technology. Membranes are consumable items requiring regular replacement, which generates recurring revenue for manufacturers. The biopharmaceutical industry alone consumes millions of square meters of membrane area annually for sterile filtration and tangential flow processing. The versatility of membranes allows them to be customized for specific applications such as virus removal or protein separation. Advances in membrane technology, including surface modifications to reduce fouling, have enhanced their performance and lifespan. Laboratories prefer high-quality membranes that ensure consistent flow rates and retention characteristics. The widespread availability of membrane discs, capsules, and cassettes caters to diverse laboratory needs. This central importance in filtration processes solidifies the membrane segment as the market leader.
However, the syringe filters segment is estimated to exhibit a CAGR of 11.4% during the forecast period. These small disposable devices are designed for filtering small volumes of liquid samples directly into syringes or vials. The rapid growth is driven by the increasing need for quick and convenient sample preparation in analytical laboratories. High-performance liquid chromatography and mass spectrometry techniques, which are widely used in drug discovery and environmental testing, require particle-free samples to protect sensitive columns and detectors. The expansion of analytical laboratories in China and India has boosted the demand for syringe filters. According to the American Chemical Society, the number of analytical instruments installed in Asia Pacific has increased by 15% annually. Syringe filters offer a simple one-step filtration process that saves time and reduces sample loss. The availability of various membrane materials and pore sizes allows users to select the optimal filter for their specific application. The rise of high-throughput screening in pharmaceutical research further accelerates the consumption of syringe filters. Their convenience, affordability, and effectiveness make them a preferred choice for routine laboratory tasks.
By End User Insights
The pharmaceutical and biopharmaceutical companies segment captured the major share of the regional market in 2025 due to the critical role of filtration in drug manufacturing and quality control. These companies require high-purity filtration for sterile product formation, buffer preparation, and viral clearance. The region is a global manufacturing hub for generics and biologics, driving substantial demand for filtration products. According to the International Federation of Pharmaceutical Manufacturers and Associations, the Asia Pacific region accounts for 35% of global pharmaceutical production. Strict regulatory requirements from regulatory agencies mandate rigorous filtration processes to ensure product safety and efficacy. The rise of biologic drugs, which are more sensitive to contamination, has increased the use of advanced filtration technologies. Contract manufacturing organizations in the region are expanding their capacities, requiring significant investment in filtration infrastructure. The high value of pharmaceutical products justifies the use of premium filtration solutions to minimize risk. The continuous introduction of new drugs and vaccines sustains the demand for filtration consumables. This sector's emphasis on quality and compliance makes it the largest consumer of laboratory filtration products.
However, the academic and research institutes segment is expected to grow at a CAGR of 10.1% over the forecast period in the Asia-Pacific market owing to the increased government funding for scientific research and the expansion of higher education institutions. According to the United Nations Educational, Scientific and Cultural Organization, research expenditure in Asia-Pacific has grown by 12% annually. Universities and research centers are conducting advanced studies in genomics, proteomics, and materials science, which require precise filtration techniques. The establishment of new research parks and innovation hubs in countries like China, India, and South Korea has boosted demand for laboratory equipment. Students and researchers use filtration for sample preparation in various experiments, driving high consumption of consumables. The focus on interdisciplinary research has expanded the application of filtration beyond traditional life sciences. Government initiatives to promote STEM education have increased the number of laboratories in educational institutions. This institutional growth creates a broad and expanding customer base for filtration products.
COUNTRY LEVEL ANALYSIS
China Laboratory Filtration Market Analysis
China dominated the market in Asia-pacific market in 2025 and is likely to maintain steady market dominance throughout the forecast period due to its massive pharmaceutical manufacturing base and aggressive biotechnology innovation policies. China holds the largest share of approximately 30% in the Asia Pacific laboratory filtration market, driven by its massive pharmaceutical manufacturing base and extensive research infrastructure. The country is the world's largest producer of generic drugs and active pharmaceutical ingredients requiring extensive filtration for quality control. According to the Chinese National Medical Products Administration, over 10000 pharmaceutical manufacturers operate in the country, creating substantial demand for filtration products. The government’s Made in China 2025 initiative promotes innovation in biotechnology, leading to increased investment in research and development. Major biopharma companies in Shanghai and Beijing are adopting advanced single-use filtration technologies. The presence of numerous contract research organizations further boosts market growth. China is also a major producer of membranes, reducing dependency on imports. The strong domestic supply chain supports competitive pricing and wide availability. Regulatory reforms have improved quality standards, driving demand for premium filtration products. The sheer scale of industrial and academic activity ensures China’s dominant position in the regional market.
India Laboratory Filtration Market Analysis
Over the next few years, India is likely to experience rapid market expansion supported by growing vaccine production and increasing export-oriented pharmaceutical manufacturing. The country produces over 60% of global vaccines and 20% of generic drugs, necessitating robust filtration processes. The Central Drugs Standard Control Organization mandates strict quality control measures, driving demand for sterile filtration products. The Indian pharmaceutical industry is highly export-oriented, requiring compliance with international standards. The Department of Biotechnology supports research in biologics and biosimilars, fostering innovation. Academic institutions in cities like Bangalore and Hyderabad are expanding their research capabilities. The cost-sensitive nature of the market favors affordable yet reliable filtration solutions. Local manufacturers are emerging to compete with global players. The growth of contract research and manufacturing services adds to the demand. India’s strong pharmaceutical foundation ensures sustained market growth.
Japan Laboratory Filtration Market Analysis
Japan holds a prominent share of the regional market distinguished by its advanced technological capabilities and high quality standards. The country is a leader in biopharmaceutical research and development, with major companies like Takeda and Astellas driving demand for premium filtration products. The Ministry of Health, Labour and Welfare enforces stringent regulations ensuring high-quality manufacturing practices. Japanese laboratories prefer high-performance and reliable filtration systems. The aging population increases demand for healthcare products, boosting pharmaceutical production. Academic research in universities is well funded, supporting advanced filtration applications. Japan is also a major exporter of high-quality membranes and filtration devices. The focus on precision and innovation maintains Japan’s strong market position. The mature market sees steady growth driven by technological advancements.
South Korea Laboratory Filtration Market Analysis
Over the next few years, South Korea is likely to witness robust market acceleration supported by government bio health investments and rising biosimilar manufacturing capabilities. The country is a global leader in biosimilars with companies like Samsung Biologics and Celltrion expanding production capacities. The Ministry of Science and ICT invests heavily in research and development. Korean laboratories adopt advanced filtration technologies quickly. The presence of major contract manufacturing organizations drives demand for single-use filtration systems. Academic research in stem cells and regenerative medicine requires specialized filtration tools. The government’s bio health vision aims to make Korea a global bio hub. This strategic focus supports market growth. High-quality standards and technological sophistication characterize the South Korean market.
Australia Laboratory Filtration Market Analysis
Australia is likely to sustain stable market development supported by strong medical research funding and stringent regulatory compliance frameworks, and its strong research infrastructure and regulatory standards. The country is a hub for medical research, with institutions like the CSIRO leading innovation. The Therapeutic Goods Administration ensures high-quality pharmaceutical manufacturing. Australian laboratories prefer premium filtration products for accurate results. The mining and environmental sectors also drive demand for filtration testing. The government funds extensive scientific research supporting market growth. High disposable income allows for investment in advanced equipment. Australia serves as a gateway for new technologies in the region. The mature market focuses on quality and sustainability.
COMPETITIVE LANDSCAPE
The Asia Pacific Laboratory Filtration Market features intense competition among multinational corporations, regional specialists, and emerging local manufacturers striving for technological superiority and market penetration. Global leaders leverage extensive research and development resources to introduce innovative membrane materials and automated filtration platforms that offer superior precision and efficiency. Local players compete primarily on price affordability and customized service models tailored to specific regional needs and regulatory requirements. The competitive landscape is characterized by continuous product launches, strategic collaborations, and aggressive marketing campaigns aimed at capturing share in rapidly growing segments like biopharmaceutical manufacturing and environmental testing. Regulatory heterogeneity across countries creates barriers to entry, requiring companies to navigate complex approval processes and adapt to varying quality standards. Supply chain resilience has become a critical differentiator following recent global disruptions, prompting investments in regional manufacturing hubs and localized distribution networks. Customer service excellence, including technical support and training programs, distinguishes leading brands in markets with skilled labor shortages. Price pressure from public procurement programs and cost-sensitive academic institutions forces manufacturers to optimize cost structures while maintaining quality. This dynamic environment drives constant evolution in business models and product offerings across the region.
KEY MARKET PLAYERS
The leading companies operating in the Asia Pacific laboratory filtration market include:
- Merck KGaA
- GE Healthcare
- Sartorius Group
- 3M Purification Inc.
- Thermo Fisher Scientific Inc.
- Danaher Corporation
- Cantel Medical Corporation
- Cuno
- Dow Water & Process Solutions
- FilmTec Corporation
- Sigma-Aldrich Corporation
TOP PLAYERS IN THE MARKET
- Merck KGaA is a global leader in the Asia Pacific Laboratory Filtration Market, providing high-performance membranes and filtration devices for life science research. The company serves pharmaceutical, biotechnology, and academic sectors with innovative solutions for sterile filtration and sample preparation. Recent actions include expanding its manufacturing facilities in Singapore to enhance regional supply chain resilience and reduce lead times. Merck collaborates with local research institutions to develop customized filtration protocols that address specific regional challenges. The company also invests in digital tools that help laboratories optimize filtration processes and reduce waste. By focusing on sustainability and product innovation, Merck strengthens its position as a trusted partner for scientists across the Asia Pacific region, ensuring consistent quality and reliability in critical laboratory applications.
- Thermo Fisher Scientific Inc plays a pivotal role in the Asia Pacific Laboratory Filtration Market through its comprehensive portfolio of filtration products and analytical instruments. The company supports diverse industries including pharmaceuticals, food and beverage, and environmental testing with advanced filtration technologies. Recent initiatives involve launching new single-use filtration systems designed to improve efficiency and reduce contamination risks in bioprocessing. Thermo Fisher expands its distribution network in emerging markets like India and Vietnam to increase accessibility for smaller laboratories. The company also provides extensive technical training and support services to ensure optimal product usage. These efforts reinforce Thermo Fisher's commitment to scientific advancement while strengthening its market presence through customer-centric solutions and robust logistical capabilities across the Asia Pacific region.
- Danaher Corporation contributes significantly to the Asia Pacific Laboratory Filtration Market through its subsidiary brands such as Pall Corporation and Cytiva, which specialize in separation and purification technologies. The company offers a wide range of membrane filters and tangential flow filtration systems for biopharmaceutical manufacturing. Recent actions include acquiring innovative startups focused on next-generation membrane materials to enhance product performance. Danaher invests heavily in local manufacturing hubs in China and South Korea to meet growing demand for high-quality filtration consumables. The company also partners with contract manufacturing organizations to provide integrated filtration solutions that streamline production workflows. These strategic moves solidify Danaher's reputation for technological excellence and reliability, ensuring strong customer loyalty and sustained growth in the competitive Asia Pacific laboratory filtration landscape.
TOP STRATEGIES USED BY THE KEY MARKET PARTICIPANTS
Key players in the Asia Pacific Laboratory Filtration Market employ strategic approaches to maintain competitive advantage and drive growth. Product innovation focuses on developing high-efficiency single-use and sustainable filtration solutions to meet evolving regulatory and environmental standards. Strategic partnerships with local distributors and research institutions facilitate market entry and expansion in emerging economies. Manufacturers invest in regional manufacturing facilities to reduce supply chain dependencies and lower operational costs. Digital transformation initiatives integrate smart monitoring tools into filtration systems, enhancing data accuracy and process efficiency. Educational programs train laboratory personnel on best practices, improving user proficiency and customer loyalty. Pricing strategies accommodate varying economic conditions, offering tiered products for different market segments. These multifaceted strategies collectively strengthen market positions while addressing unique regional healthcare and industrial challenges effectively.
MARKET SEGMENTATION
This Asia Pacific laboratory filtration market research report is segmented and sub-segmented into the following categories.
By Technology
- Ultrafiltration
- Microfiltration
- Nano filtration
- Reverse Osmosis
By Product
- Assembly
- Filter Paper
- Membrane
- Syringe Filters
- Filtration Microplate
- Accessories
By End User
- Pharmaceutical & Biopharmaceutical Companies
- Academic & Research Institutes
- Food & Beverage Companies
- Hospital & Diagnostic Laboratories
By Country
- India
- China
- Japan
- South Korea
- Australia
- New Zealand
- Thailand
- Malaysia
- Vietnam
- Philippines
- Indonesia
- Singapore
- Rest Of APAC