- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Asia Pacific Organic Feed Market Size
The Asia Pacific organic feed market size was valued at USD 2 billion in 2025 and is anticipated to reach USD 2.17 billion in 2026 and USD 4.25 billion by 2034, growing at a CAGR of 8.73% from 2026 to 2034.
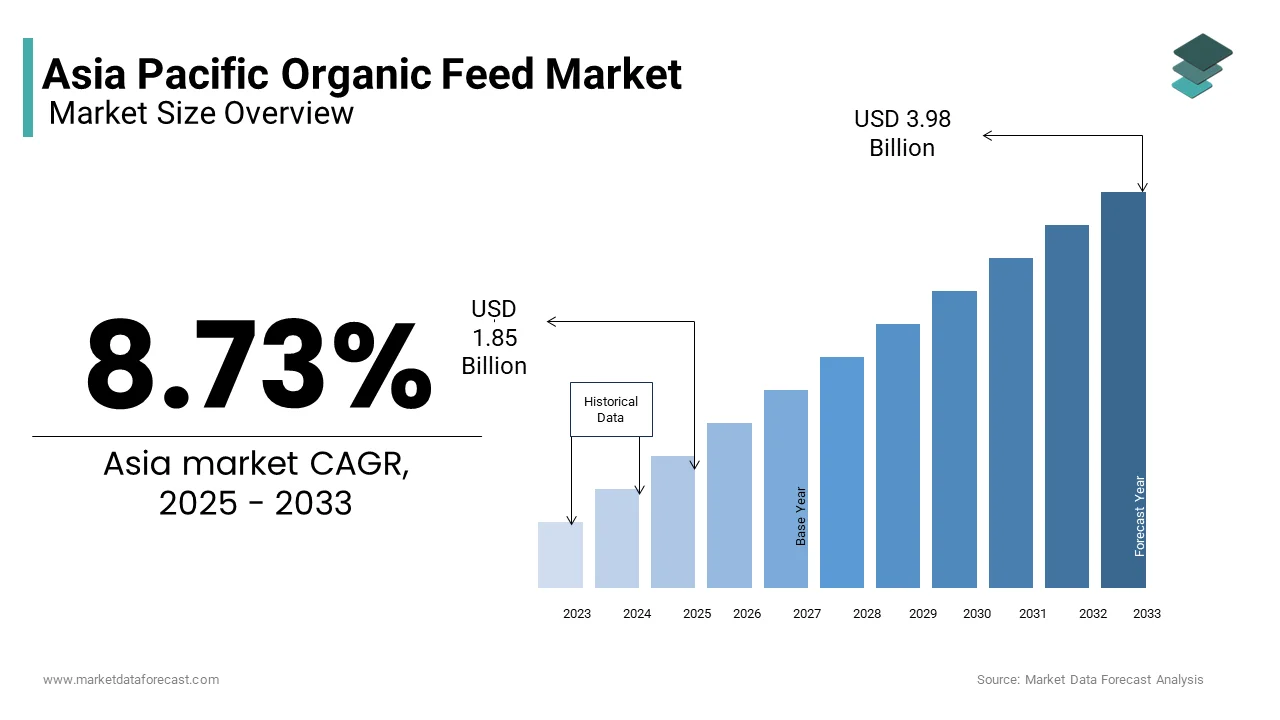
The organic feed is primarily used in livestock, poultry, aquaculture, and dairy farming to support the growing demand for organic meat, eggs, milk, and seafood across the region. According to the Food and Agriculture Organization (FAO), the demand for organic animal-based food products has surged in recent years due to increasing health consciousness among consumers and a rising preference for sustainable and ethically produced food. This shift is particularly evident in countries like Japan, South Korea, and Australia, where regulatory frameworks have been established to support organic agriculture and livestock management. The use of organic feed in commercial livestock operations has been further encouraged in China and India by government-backed programs supporting organic farming.
MARKET DRIVERS
Rising Consumer Preference for Organic Animal Products
The growing consumer demand for organic meat, dairy, and egg products is a major factor driving the Asia Pacific Organic Feed Market. This trend is noticeable in urban centers across Japan, South Korea, and Australia, where consumers are more informed about the benefits of organic food and are willing to pay a premium for sustainably sourced animal products. In response, livestock producers are transitioning to organic feeding systems to meet certification requirements and gain access to premium markets. For instance, according to the Ministry for Primary Industries in New Zealand, between 2021 and 2023, more than 700 farms switched to raising livestock organically, which necessitated a similar move toward the purchase of organic feed. Additionally, retailers and food service providers are increasingly adopting organic supply chain standards. The expansion of organic product lines by major supermarket chains like AEON in Japan and Woolworths in Australia has strengthened the demand for livestock fed organically and fuelled the rise of the organic feed market throughout the Asia Pacific region.
Government Support and Regulatory Frameworks for Organic Farming
The increased government support for organic agriculture through certification programs, subsidies, and policy reforms is another important driver driving the Asia Pacific Organic Feed Market. According to the United Nations Conference on Trade and Development (UNCTAD), several countries in the region have introduced national organic farming policies aimed at boosting domestic production and exports of organic goods. According to the Chinese Ministry of Agriculture and Rural Affairs, over the first two years of the plan, the area under organic agriculture grew by 20%, which in turn raised demand for organic feed ingredients like maize and soybean meal. The establishment of organic clusters has been facilitated more easily by India's Paramparagat Krishi Vikas Yojana (PKVY) initiative, which offers farmers direct financial support. According to the Indian Council of Agricultural Research (ICAR), this initiative helped raise organic livestock by 25% between 2020 and 2023, which will require a parallel rise in the supply of organic feed. Australia and Japan have also strengthened their organic certification systems to align with international standards, which enables smoother trade and encourages domestic producers to adopt compliant feed sourcing practices.
MARKET RESTRAINTS
High Cost of Organic Feed Production
The high cost of producing organic feed in comparison to conventional alternatives is one of the main factors restraining the Asia Pacific Organic Feed Market. According to the International Fund for Agricultural Development (IFAD), increased labor inputs, longer crop rotations, and limited use of synthetic fertilizers and pesticides are all factors that drive up the cost of producing organic feed. This price differential limits the affordability of organic feed for small and medium-sized livestock producers, particularly in developing economies like Vietnam and Indonesia. Furthermore, the certification process required for organic feed production adds another layer of expense. According to the Japan Organic Agriculture Association (JOAA), obtaining and maintaining organic certification can raise operating expenses by as much as 20%, which hinders new competitors and restricts market growth. Additionally, limited economies of scale in organic feed manufacturing reduce cost efficiency. Many organic feed manufacturers find it difficult to reach comparable output levels because of supply chain constraints and dispersed sourcing networks.
Limited Availability of Organic Raw Materials
The lack of certified organic raw materials needed for feed formulation is another significant restraint on the expansion of the Asia Pacific Organic Feed Market. According to the Food and Agriculture Organization (FAO), only a small fraction of total agricultural land in the region is dedicated to organic crop production, which leads to shortages of key feed ingredients such as organic grains, legumes, and forage crops. As per the Research Institute of Organic Agriculture (FiBL), less than 5% of arable land in Southeast Asia is under organic cultivation, which severely limits the supply of organic barley, wheat, and soybeans. According to the Department of Agricultural Extension, only fifteen percent of Thailand's domestic needs are met by local organic grain production, which demands imports. Import dependency introduces additional complexities, including fluctuating prices, logistical delays, and compliance with international certification standards. In Japan, where domestic organic feed production is limited, importers must navigate stringent quality checks enforced by the Japanese Agricultural Standards (JAS) system, which increases lead times and costs. These supply-side constraints make it difficult for producers to fulfill growing demand and cause obstacles in the scaling up of organic feed manufacturing, particularly in nations where organic animal farming is expanding quickly.
MARKET OPPORTUNITIES
Expansion of Organic Livestock Farming in Emerging Economies
The increasing popularity of organic livestock production in developing nations like Indonesia, the Philippines, and India presents an opportunity for the Asia Pacific Organic Feed Market. According to the International Livestock Research Institute (ILRI), these countries are witnessing a shift toward sustainable animal husbandry practices driven by both consumer demand and government support. In India, for example, according to data released by the National Dairy Development Board (NDDB), the number of registered organic dairy farms rose by 35% between 2020 and 2023, which indicates that the market is gaining significant popularity. This growth is supported by rising rural incomes and greater awareness of the health benefits associated with organic milk and dairy products. The Indonesian Ministry of Agriculture has started regional pilot projects to encourage organic cattle and poultry production to increase domestic production of organic meat and eggs. Additionally, private-sector players are investing in integrated organic livestock value chains that include feed supply, animal breeding, and end-product marketing. Companies such as PT Natural Nusantara in Indonesia and Organic Valley in the Philippines are expanding their operations to capitalize on this trend, which suggests an immense opportunity for long-term market growth.
Increasing Demand for Organic Aquafeed in Sustainable Fisheries
The growing need for organic aquafeed in sustainable fisheries and aquaculture operations is another opportunity for the Asia Pacific Organic Feed Market. According to the Network of Aquaculture Centres in Asia-Pacific (NACA), the region accounts for over 90% of global aquaculture production, with increasing focus on environmentally responsible feed solutions. Organic aquafeed, which excludes synthetic additives and GMO-based ingredients, is gaining traction among fish farmers supplying premium export markets. In China, the Ministry of Agriculture and Rural Affairs has introduced guidelines promoting the use of organic feed in aquaculture to enhance product safety and sustainability. State-backed research institutions such as the Chinese Academy of Fishery Sciences have developed alternative protein sources, such as insect-based and algae-derived feeds, to replace conventional fishmeal in organic formulations. Moreover, multinational companies like Skretting and Biomar are expanding their presence in the region by launching specialized organic aquafeed lines aimed at the production of salmon, tilapia, and shrimp.
MARKET CHALLENGES
Supply Chain Fragmentation and Distribution Gaps
The fragmented supply chain, which results in inefficiencies in sourcing, shipping, and distribution, is a significant challenge for the Asia Pacific organic feed market. According to the Asian Development Bank (ADB), organic feed producers often face difficulties in securing consistent supplies of certified raw materials due to the lack of well-integrated procurement networks. Smallholder farms are common in Vietnam and the Philippines, where the absence of centralized infrastructure for feed collection and processing results in irregular feed availability and variable feed quality, which affects animal productivity. As per the Philippine Council for Agriculture, Aquatic and Natural Resources Research and Development (PCAARRD), only 10% of organic feed manufacturers have access to reliable supply chains for key ingredients such as organic soy and corn. Additionally, transportation infrastructure remains a constraint in island nations and remote regions.
Lack of Awareness and Technical Expertise Among Farmers
The lack of technical expertise and awareness among livestock producers about the advantages and use of organic feeding systems is another significant challenge preventing the Asia Pacific Organic Feed Market from expanding. According to the Food and Agriculture Organization (FAO), many small-scale producers continue to rely on conventional feed due to misconceptions about organic alternatives and a lack of extension services. Adoption of organic feed is still limited in nations like Cambodia and Laos, where traditional farming practices are still used. As per the Regional Knowledge Hub on Organic Agriculture in Thailand, only 5% of surveyed farmers had received formal training on organic livestock nutrition, which indicates a substantial gap in educational outreach. Furthermore, the complexity of transitioning from conventional to organic feed systems poses a barrier. According to the Indian Council of Agricultural Research (ICAR), farmers frequently struggle with feed formulation, disease control, and organic certification standards when they are not given proper guidance.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 6.22% |
| Segments Covered | By Types, Additives, Form, and Region. |
| Various Analyses Covered | Global, Regional and Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | India, China, Japan, South Korea, Australia, New Zealand, Thailand, Malaysia, Vietnam, Philippines, Indonesia, Singapore, and the Rest of APAC |
| Market Leaders Profiled | Feedex Companies (US), Country Junction feed (US), Green Mountian Feeds (US), Unique Organic (US), ForFarmers (Netherlands), SunOpta (Canada), Purina Animal Nutrition LLC (US), Yorktown Organics, LLC (US), Kreamer Feed (US), Cargill (US), BernAqua (Belgium), Country Heritage Feeds (Australia), Ranch-Way Feeds (US), Aller Aqua (Denmark), Scratch and Peck Feeds (US), Cargill (US), K-Much Feed Industry Co., Ltd (Thailand), The Organic Feed Company (UK), B&W Feeds (UK) and Hi Peak Feeds (UK). |
SEGMENTAL ANALYSIS
By Type Insights
The cereals & grains segment dominated the market by capturing 48.6% of the Asia Pacific Organic Feed market share in 2025, with the foundational role of organic cereals such as corn, wheat, barley, and oats in livestock feed formulations. A major factor contributing to the dominance of this market is the high nutritional content of grains, which are the main source of energy in animal diets. Additionally, government-backed initiatives promoting organic grain production are contributing to a sustained supply. Moreover, the growing adoption of organic poultry and dairy farming in China and South Korea has further boosted demand for organic maize and wheat-based feeds.
The oilseeds segment is estimated to register the fastest CAGR of 12.9% over the forecast period 2025 to 2033. This rapid expansion is driven by the increasing need for plant-based protein sources in organic livestock nutrition. A major factor fueling this growth is the rising focus on non-soy alternatives due to concerns about allergens and GMO contamination in conventional soybean supplies. In addition, the shift toward antibiotic-free and hormone-free animal rearing practices has heightened demand for natural, protein-rich ingredients. According to the Australian Poultry Farmers Association, more than 40% of organic egg producers have shifted to diets based on flaxseed and canola to increase the amount of omega fatty acids in their eggs. Furthermore, regional governments are encouraging the cultivation of indigenous oilseed crops under organic farming schemes. According to Thailand's Department of Agriculture, organic groundnut and sesame output increased by 22% in 2023, which indicates that alternative oilseed sourcing is gaining popularity.
By Additives Insights
The vitamins segment dominated the Asia Pacific Organic Feed market with 35.4% of the share in 2025. The crucial role that vitamins play in preserving animal health, boosting immunity, and increasing output without the use of artificial inputs is what mostly drives this segment's domination. One of the main reasons for its leading position is the mandatory inclusion of vitamin supplements in organic poultry and dairy feed to compensate for nutrient deficiencies in plant-based diets. According to the National Institute of Nutrition (NIN) in India, organic laying hens require additional vitamin D and B12 supplementation to maintain eggshell quality and yolk coloration, which are critical for consumer acceptance. Moreover, regulatory bodies such as the Japanese Organic Agriculture Association (JOAA) mandate the inclusion of specific vitamins in certified organic feed to ensure compliance with animal welfare and health standards. As per JOAA guidelines, all registered organic feed products must contain minimum levels of fat-soluble and water-soluble vitamins derived from natural sources. Additionally, the rise in antibiotic-free poultry production has led to greater reliance on vitamin-enriched feed to prevent disease outbreaks and support immune function.
The phytogenic additives segment is estimated to register a CAGR of 14.3% from 2025 to 2033. This surge is largely attributed to the growing preference for plant-derived compounds that enhance digestion, improve gut health, and boost overall animal performance without synthetic stimulants. Regulatory authorities across the region are increasingly endorsing phytogenics as safe and effective alternatives to antibiotics in organic livestock management. As per the Food Standards Australia New Zealand (FSANZ), several herbal extracts, including garlic, thyme, and oregano, have been approved for use in certified organic feed formulations, which promotes their widespread adoption. Moreover, scientific research supports the efficacy of phytogenic compounds in improving feed efficiency and reducing methane emissions in ruminants. According to the Commonwealth Scientific and Industrial Research Organization (CSIRO), incorporating phytogenics to cattle feed reduced intestinal fermentation by as much as 18%, which is consistent with climate-conscious farming objectives. Additionally, the integration of traditional medicinal knowledge into modern feed formulation is accelerating innovation. In India, the Centre for Plant-Based Natural Alternatives at IIT Delhi collaborated with feed manufacturers to develop standardized phytogenic blends derived from neem, fenugreek, and tulsi for commercial use in organic poultry operations.
By Form Insights
The pellets segment led the market by occupying 52.3% othe f the Asia Pacific Organic Feed market share in 2025, with the advantages pellets offer in terms of nutrient retention, ease of feeding, and reduced wastage in large-scale livestock and poultry operations. One of the primary drivers behind this segment’s growth is the efficiency of pelleted feed in delivering balanced nutrition to animals. According to the International Livestock Research Institute (ILRI), pelleted organic feed reduces dust formation and improves palatability, which makes it preferred for broiler chickens and dairy cattle. Additionally, commercial feed mills favor pellet production due to its scalability and consistency. Moreover, the compact structure of pellets enhances storage and transportation logistics, especially in tropical climates where moisture can degrade loose feed. According to the Philippine Department of Agriculture, in humid circumstances, pelleted organic feed can remain stable for up to six months longer than mashes, which lowers the danger of spoiling. The demand for pelleted organic feed is anticipated to continue to be strong due to the growth of robotic feeding systems in major poultry and aquaculture farms in China and Thailand, which will strengthen its leading position in the regional market.
The crumbles segment is expected to witness a CAGR of 13.7% from 2025 to 2033 due to their suitability for young animals, particularly in poultry and aquaculture settings where feed particle size plays a crucial role in digestion and nutrient absorption. A key factor propelling this segment is the increasing adoption of crumbled feed in starter diets for broilers and fry-stage fish species. According to the Network of Aquaculture Centres in Asia-Pacific (NACA), crumbled organic feed improved weight gain and survival rates in juvenile shrimp by 15% compared to mash or whole grain alternatives in controlled trials conducted in Vietnam in 2023. Moreover, the transition from mash to crumble forms is being encouraged by veterinary nutritionists who focus on the benefits of pre-digested feed formats for early-stage development. As per the University of Queensland’s School of Veterinary Science, crumbles offer better feed conversion ratios and lower contamination risks in hatcheries and breeding farms. Additionally, technological advancements in feed processing have enabled more cost-effective crumble production, which makes it accessible even for mid-sized organic farms. Region-specific crumbled organic aquafeed lines have been introduced by companies like as Skretting and Nutreco for small-scale farmers in the Philippines and Indonesia.
COUNTRY-LEVEL ANALYSIS
India
India was the top performer in the Asia Pacific Organic Feed Market with 22.4% of the share in 2025. India is positioned as a major participant in the area due to its robust agricultural base, developing organic farming regulations, and rising domestic demand for organic poultry and dairy products. As per the Ministry of Agriculture and Farmers Welfare, over 6 million hectares of farmland were converted to organic status between 2015 and 2023, which increased the availability of organic feed ingredients. Moreover, India’s organic livestock sector is gaining traction, particularly in states like Rajasthan, Madhya Pradesh, and Karnataka. According to the National Dairy Development Board (NDDB), there had to be a corresponding increase in the production of organic feed since the number of certified organic dairy units increased by 30% between 2020 and 2023. Additionally, businesses like ITC and Patanjali are extending their involvement in the private sector by introducing specialized organic feed brands to meet the needs of emerging markets.
China
China was positioned second in the Asia Pacific Organic Feed Market with 18.9% of share in 2025. China is one of the biggest livestock producers in the world by adopting organic feed more to satisfy the demand for premium meat and dairy products locally as well as internationally. Additionally, rising consumer awareness regarding food safety and sustainability has fueled demand for organically raised pork, poultry, and dairy. The demand for certified organic feed in supply chains has increased as a result of major supermarkets like Walmart China and Freshippo expanding their organic product ranges. Moreover, state-backed research institutions are actively developing alternative protein sources for organic feed, including insect meal and microalgae. The Chinese Academy of Fishery Sciences has introduced organic aquafeed formulations to support the country’s booming aquaculture exports, which shows a broadening scope for organic feed applications.
Australia's Organic Feed market growth is more likely to have significant opportunities in the coming years. Australia, which is positioned as the leader in export-oriented agriculture and organic certification, has a strong organic feed business, which is supported by strict regulations and high demand from consumers. A major growth factor is the country’s focus on high-value organic exports, particularly to North America and Europe. Additionally, the Australian government supports organic agriculture through policy incentives and research funding. Moreover, the presence of well-established feed manufacturers such as Ridley Corporation and Midfield Group ensures consistent supply and quality assurance in organic feed distribution. Australia continues to play a significant role in the development of the regional market due to rising investments in the free-range poultry and organic dairy industries. Japan's organic feed market growth is driven by high consumer demand for organic meat and dairy products among urban populations. Furthermore, in 2021, Japan's Ministry of Agriculture, Forestry, and Fisheries (MAFF) updated its promotion strategy for organic farming to double the area planted to organic by 2030. This initiative includes financial support for organic feed procurement in livestock enterprises. Moreover, the country relies heavily on imported organic grains and protein meals due to limited domestic organic crop production. Importers must comply with the Japanese Agricultural Standards (JAS), which ensure traceability and purity of feed ingredients used in certified organic livestock operations.
Thailand
Thailand is gaining huge traction with the highest CAGR during the forecast period. Thailand, an emerging participant, is incorporating organic feed into the supply chains for livestock and aquaculture by utilizing its robust agri-food export base. The government's initiative to increase exports of organic rice and aquaculture is a significant growth driver. Moreover, the expansion of organic shrimp and tilapia farming has created new opportunities for organic aquafeed suppliers. According to Thailand's Marine Department, increased worldwide sustainability standards fueled a 25% increase in organic aquaculture exports in 2023. Additionally, private-sector investment in organic feed milling is growing. Companies such as Charoen Pokphand Foods and Betagro Group have launched certified organic feed lines targeting poultry and pig farming segments.
South Korea
South Korea is likely to have significant growth opportunities in the coming years. The increasing concern over food safety and antibiotic residues in conventionally raised livestock is propelling the growth of the market. Moreover, the Ministry of Agriculture, Food and Rural Affairs (MAFRA) has introduced policy incentives to encourage organic livestock conversions. The upstream demand for certified organic feed has also been strengthened by the expansion of organic meat and egg offers by large retail chains like E-Mart and Lotte Mart.
KEY MARKET PLAYERS
Feedex Companies (US), Country Junction feed (US), Green Mountian Feeds (US), Unique Organic (US), ForFarmers (Netherlands), SunOpta (Canada), Purina Animal Nutrition LLC (US), Yorktown Organics, LLC (US), Kreamer Feed (US), Cargill (US), BernAqua (Belgium), Country Heritage Feeds (Australia), Ranch-Way Feeds (US), Aller Aqua (Denmark), Scratch and Peck Feeds (US), Cargill (US), K-Much Feed Industry Co., Ltd (Thailand), The Organic Feed Company (UK), B&W Feeds (UK) and Hi Peak Feeds (UK). Are the market players that are dominating the Asia Pacific organic feed market?
Top Players In The Market
Cargill Incorporated
Cargill is a global leader in agricultural and animal nutrition products, with a strong presence in the Asia Pacific Organic Feed Market. The company has been actively expanding its sustainable feed portfolio by investing in organic sourcing networks and developing innovative feed formulations that meet international organic certification standards. Cargill supports farmers across the region through technical expertise, supply chain integration, and customized feeding solutions tailored for organic livestock production.
Archer Daniels Midland Company (ADM)
ADM plays a pivotal role in supplying high-quality organic ingredients used in feed manufacturing across the Asia Pacific region. The company focuses on sustainable sourcing, traceability, and value-added processing to ensure that its organic feed components meet stringent regulatory requirements. ADM collaborates with local producers and cooperatives to enhance organic grain availability and promote responsible farming practices, which strengthens its contribution to the global organic food supply chain.
Ridley Corporation Limited
Ridley is a leading animal nutrition company in Australia and has extended its influence across the broader Asia Pacific region. Ridley specializes in high-quality animal feeds and provides certified organic feed solutions for the dairy, poultry, and aquaculture industries. The company's commitment to quality assurance, research-driven product development, and regional market understanding positions it as a key player in advancing organic feed adoption across the region.
Top Strategies Used by Key Market Participants
One of the primary strategies employed by key players in the Asia Pacific Organic Feed Market is forming strategic partnerships and collaborations with local farmers, cooperatives, and certification bodies. These alliances help ensure a reliable supply of certified organic raw materials and facilitate market access in regions with growing demand for organic livestock products.
Another major approach involves product innovation and formulation diversification to meet specific nutritional needs across different livestock categories. Companies are investing in R&D to develop high-performance, non-GMO, and antibiotic-free feed options that align with evolving consumer preferences and regulatory standards.
Additionally, market leaders are enhancing their regional distribution networks and investing in localized customer support services. The companies improve accessibility and provide tailored guidance to farmers transitioning to organic feed systems, thereby strengthening their market presence.
COMPETITION OVERVIEW
The competition in the Asia Pacific Organic Feed Market is intensifying as multinational corporations, regional agribusinesses, and emerging startups vie for a stronger position in a rapidly evolving market. Established global players leverage their extensive supply chains, brand recognition, and technological expertise to maintain dominance, while regional firms capitalize on localized knowledge and cost efficiencies to gain traction. The market is witnessing a shift toward collaborative strategies with players forming alliances to access indigenous raw materials, navigate certification complexities, and tailor feed formulations to regional livestock needs. At the same time, new entrants are disrupting traditional models by introducing niche organic feed products and leveraging digital platforms for supply chain transparency and traceability. Companies are continuously refining their positioning to capture market share while addressing sustainability and ethical sourcing expectations as consumer awareness and regulatory frameworks evolve.
RECENT HAPPENINGS IN THE MARKET
- In March 2024, Cargill announced the launch of an integrated organic feed sourcing initiative in India by partnering with farmer cooperatives to secure a steady supply of certified organic soy and maize, which is supporting its regional expansion strategy.
- In July 2023, ADM expanded its organic ingredient processing facility in Queensland, Australia, which aims to increase capacity for clean-label feed inputs and strengthen its position in the country’s growing organic livestock sector.
- In November 2023, Ridley Corporation introduced a new line of certified organic aquafeed products in New Zealand, designed specifically for salmon and trout farming, which aligns with increasing demand for sustainable seafood production.
- In May 2024, Charoen Pokphand Foods (CPF) launched an organic feed mill in Thailand, which focuses on poultry and swine nutrition to vertically integrate its organic meat supply chain and reduce import dependency.
- In September 2023, Nutreco initiated a collaboration with a Vietnamese aquaculture research institute to develop plant-based organic aquafeed formulations aimed at improving fish health and reducing environmental impact.
MARKET SEGMENTATION
This research report on the Asia Pacific Organic Feed Market is segmented and sub-segmented into the following categories.
By Type
- Cereals & Grains
- Oilseeds
- Others
By Additives
- Vitamins
- Amino Acids
- Minerals
- Enzymes
- Phytogenic
- Other Supplements
By Livestock
- Swine
- Ruminant
- Poultry
- Aquatic Animals
By Form
- Pellets
- Crumbles
- Mashes
By Country
- India
- China
- Japan
- South Korea
- Australia
- New Zealand
- Thailand
- Malaysia
- Vietnam
- Philippines
- Indonesia
- Singapore