- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$5.87 BnMarket Estimate, 2026
$6.44 BnMarket Forecast, 2034
$13.41 BnCAGR, 2026–2034
9.6%Asia-Pacific Plasma Fractionation Market Size, Growth, Trends & Forecast (2026–2034)
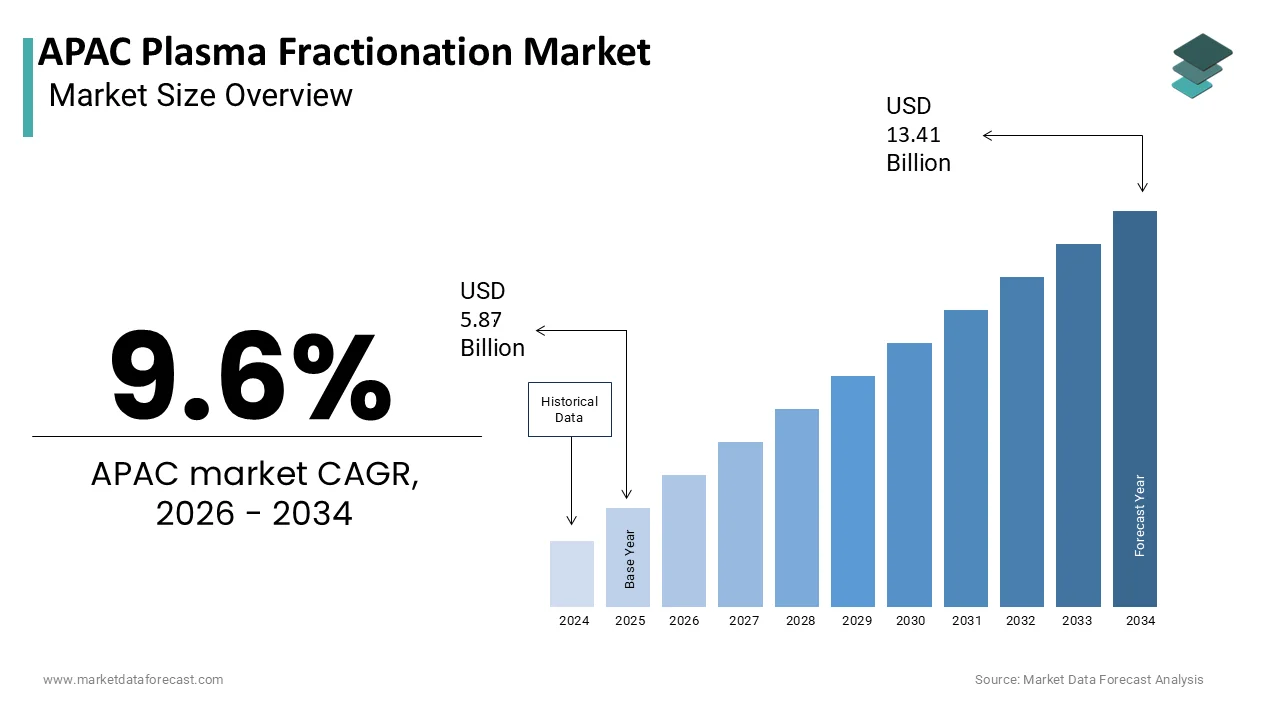
The APAC plasma fractionation market was valued at USD 5.87 billion in 2025, is estimated to reach USD 6.44 billion in 2026, and is projected to expand up to USD 13.41 billion by 2034, growing at a compound annual growth rate (CAGR) of 9.6% from 2026 to 2034. Driven by rising diagnosis rates of primary immunodeficiencies, chronic liver disease burdens, strategic government self-sufficiency initiatives, and advancements in chromatographic purification, the regional plasma protein sector continues to experience steady expansion.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 5.87 Billion
- 2026 Current Valuation: USD 6.44 Billion
- 2034 Forecast Valuation: USD 13.41 Billion
- Compound Annual Growth Rate (CAGR): 9.6% (2026–2034)
- Dominant Product Segment: Immunoglobulin Segment
- Fastest-Growing Product Segment: Protease Inhibitors (CAGR of 11.8%)
- Dominant Application Segment: Immunology Segment
- Fastest-Growing Application Segment: Neurology (CAGR of 12.4%)
- Dominant Country Market: China (32.1% share in 2025)
Core Market Drivers
- Primary Immunodeficiency Diagnoses: Accelerating clinical diagnosis rates driving lifelong demand for intravenous and subcutaneous immunoglobulin replacement therapies.
- Chronic Liver Disease & Aging: Growing geriatric populations and widespread chronic conditions (such as millions living with long-term hepatitis B infections) maintaining unavoidable human albumin consumption floors.
Primary Market Restraints & Challenges
- Raw Material Deficits: Insufficient domestic plasma collection volumes and cultural/regulatory barriers surrounding plasmapheresis creating structural supply caps.
- Pathogen & Workforce Vulnerabilities: Constant threats from emerging vector-borne pathogens requiring viral safety revalidations alongside acute shortages of specialized bioprocessing talent.
APAC Plasma Fractionation Market Segmentation Breakdown
| Segment Category | Leading Sub-Segment (2025 Base) | Fastest-Growing Sub-Segment (Forecast Period) |
|---|---|---|
| By Product | Immunoglobulin (Driven by essential utility in neurological, immunological, and hematological treatments) | Protease Inhibitors (CAGR of 11.8%; propelled by alpha-1 antitrypsin deficiency awareness and diagnosis) |
| By Application | Immunology (Anchored by lifelong replacement therapy protocols for primary immunodeficiencies) | Neurology (CAGR of 12.4%; driven by autoimmune neuropathies and pediatric autoimmune encephalitis) |
Major Industry Players Profiled
Top industry leaders shaping the Asia-Pacific plasma fractionation landscape include CSL Ltd., Grifols S.A., Baxalta Incorporated, Octapharma AG, Kedrion S.p.A., Bio Products Laboratory Ltd., Sanquin, China Biologic Products, Inc., Biotest AG, and Laboratoire Français du Fractionnement et des Biotechnologies (LFB).
 Download Free Sample Report
APAC Plasma Fractionation Market Size
The APAC Plasma Fractionation Market is projected to grow from USD 5.87 billion in 2025 to USD 6.44 billion in 2026 and reach USD 13.41 billion by 2034, registering a CAGR of 9.6% from 2026 to 2034.
Plasma fractionation is an industrial process that separates human blood plasma into its specific, useful protein components. By changing factors like temperature, acidity, and alcohol levels, scientists isolate vital elements like albumins, clotting factors, and antibodies to create life-saving medicines. This market is distinct within the regional healthcare landscape due to its dual nature as both a life saving medicine supply chain and a strategic national security asset heavily influenced by government policy and blood donation rates. According to the World Health Organization, more than 40 low- and middle-income countries globally, including several across Asia, rely entirely on imports for plasma-derived medicinal products due to a lack of domestic fractionation capacity. As per the World Health Organization, low-income nations suffer from chronic blood supply deficits, while high-income member states secure stable supply trends through voluntary non-remunerated donations that exceed an 85% benchmark globally. This definition encompasses not just commercial manufacturing but also the regulatory frameworks governing biological safety, donor compensation ethics, and strategic stockpiling mandates that vary drastically from highly regulated Japan to developing nations building domestic capacity.
MARKET DRIVERS
Rising Prevalence of Primary Immunodeficiency Disorders Driving Immunoglobulin Demand
The accelerating diagnosis rate of primary immunodeficiency disorders across developed nations in the region is a key driver for intravenous immunoglobulin consumption and subsequent fractionation capacity expansion, which fuels the growth of the Asia Pacific fractionation market. According to the Journal of Allergy and Clinical Immunology, primary antibody deficiency diseases impose severe, lifelong medical management burdens that require ongoing human-derived immunoglobulin replacement therapies. As per regional clinical research featured in BioSpace, long-term treatment protocols for chronic autoimmune and primary immunodeficiency disorders dictate stable monthly infusion doses to properly manage baseline patient health. According to sources, rapid population aging and shifting demographic structures are driving an expansion of national social safety net programs to handle rising systemic healthcare expenditures. The epidemiological visibility converts previously undiagnosed suffering into sustained pharmaceutical demand. Because immunoglobulins cannot be synthetically manufactured at scale, each new diagnosis permanently adds to the plasma processing burden, ensuring long term growth trajectories tied to diagnostic infrastructure maturity rather than transient market forces.
Aging Demographics and Chronic Liver Disease Burden Sustaining Albumin Utilization
Demographic aging and a high rate of chronic liver disease occur across specific regional subregions, which further contributes to the expansion of the Asia Pacific plasma fractionation market. This creates a strict, unavoidable demand for human albumin solutions in critical care and liver complication management. According to the United Nations World Population Prospects, rapid drops in fertility combined with extended lifespans are accelerating the demographic transition toward an older populace across key East Asian medical infrastructure networks. According to the World Journal of Gastroenterology, China carries a massive chronic disease burden with an estimated 86 million individuals currently living with long-term hepatitis B infections. As per PMC, low baseline concentrations of serum albumin correlate strongly with heightened long-term mortality risks and adverse physical outcomes among frail geriatric patient populations. The dual demographic and pathological pressure creates consumption floors resistant to cost containment measures because alternative synthetic colloids carry higher mortality risks in vulnerable populations according to regional clinical guidelines. Consequently, fractionators must maintain substantial albumin production capacity regardless of immunoglobulin margin attractiveness.
MARKET RESTRAINTS
Insufficient Domestic Plasma Collection Volumes Creating Raw Material Deficits
Chronic insufficiency of domestic plasma collection remains the most fundamental restraint, which limits the growth of the Asia Pacific fractionation market. This occurs despite substantial installed processing capacity. According to the World Health Organization, rising clinical burdens from chronic conditions across the Asia-Pacific region are driving up recurring institutional demand for plasma-derived medicinal therapies and blood-preparation components. As per the Ministry of Health of Indonesia, structural construction is progressing on a domestic plasma processing plant in Karawang, West Java, which is designed to process up to 600,000 litres of plasma annually. Cultural barriers to plasmapheresis donation, lack of compensated donor models permitted in many jurisdictions, and inadequate collection center infrastructure in rural areas perpetuate these deficits. Even wealthy nations like New Zealand rely entirely on Australian plasma imports due to insufficient domestic volumes. This raw material bottleneck means market growth is physically capped by collection logistics rather than demand signals, making supply chain security more critical than commercial expansion strategies for most regional players.
Stringent Regulatory Harmonization Gaps Impeding Cross Border Trade Efficiency
Regulatory fragmentation across jurisdictions in the region severely constrains the efficiency and expansion of the Asia Pacific plasma fractionation market. This prevents seamless cross-border plasma and product flows necessary to balance regional supply and demand. As per sources, manufacturing groups are transitioning to modern chromatography lines to substitute older cold-ethanol separation processes. According to the National Medical Products Administration, healthcare expansion targets are streamlining clinical access networks to speed up patient procurement pathways for sub-cutaneous immunoglobulins and domestic therapies. ASEAN Medical Device Directive progress remains slow for biologics, with individual member states maintaining separate dossier requirements duplicating administrative burdens. The regulatory silos prevent efficient allocation of plasma resources from surplus to deficit regions, artificially sustaining shortages alongside surpluses. Manufacturers face impossible choices between maintaining multiple country specific processes or accepting limited market access, suppressing potential economies of scale that could reduce therapy costs and improve patient access across the region.
MARKET OPPORTUNITIES
Strategic Government Investment in Domestic Self Sufficiency Programs
Governments across the region are pouring unprecedented investment into domestic plasma fractionation, which is expected to propel the Asia Pacific market. This surge is driven by a need to reduce import vulnerability and protect these medicines as vital national security assets. According to the Department of Pharmaceuticals of India, the national Production Linked Incentive Scheme allocates financial incentives across distinct pharmaceutical product categories to foster massive long-term domestic bio-pharmaceutical manufacturing investments. As per the Board of Investment of Thailand, top-tier specialized industrial technology and biological development projects can secure extensive corporate income tax holidays extending up to a maximum of 13 years. The policy interventions transform fractionation from purely commercial venture into public private partnership opportunity with de risked returns. Investors can leverage government commitments to secure favorable financing and guaranteed offtake agreements while contributing to national health security objectives, creating alignment between profit motives and public interest rarely seen in pharmaceutical sectors.
Technological Innovation in Chromatographic Purification Enhancing Yield Economics
The advancement of chromatographic purification technologies offers transformative opportunities for the Asia Pacific plasma fractionation market. This helps to improve fractionation economics by increasing protein yield from limited plasma supplies prevalent across the region. According to ScienceDirect, modern downstream chromatographic purification systems generate highly optimized protein recovery profiles when processing human-derived blood plasmas. As per sources, the CSL Behring facility located in Broadmeadows, Melbourne utilizes a $900 million infrastructure layout to process domestic plasma and supply vital therapeutic products under the national blood agreement. For plasma constrained markets, yield improvement offers more immediate return on investment than greenfield capacity expansion. Early adopters gain competitive advantages through superior unit economics enabling sustainable pricing in price sensitive public tenders while maintaining margins necessary for continued innovation investment.
MARKET CHALLENGES
Vulnerability to Pathogen Emergence and Viral Safety Validation Burdens
Persistent emergence of novel pathogens across the region creates ongoing operational uncertainty for fractionators in the Asia Pacific plasma fractionation market. Consequently, they must continuously validate viral safety against evolving threats while managing supply disruption risks. According to World Health Organization surveillance guidelines, newly emerging and vector-borne pathogens require blood centers to continually adapt clinical donor screening criteria to secure the viral safety of human blood systems. As per studies, severe seasonal outbreaks of the dengue virus across Southeast Asia present constant public health challenges that constrain seasonal whole blood and plasma donation yields inside municipal collection networks. Unlike synthetic pharmaceuticals, plasma derived products carry inherent biological variability making absolute sterility guarantees impossible despite robust manufacturing controls. Each emerging threat necessitates costly process revalidation and potential inventory quarantines disrupting just in time supply models. Fractionators must maintain redundant testing capabilities and buffer stocks against unpredictable disruptions, inflating operational costs and compressing margins in ways difficult to pass through to price regulated public health purchasers.
Workforce Specialization Gaps Limiting Advanced Manufacturing Scale Up
Severe shortage of specialized bioprocessing professionals across the region is a critical barrier to the Asia Pacific plasma fractionation market. This prevents optimal utilization of advanced fractionation technologies and limits capacity expansion velocity. As per research, manufacturing groups are transitioning to modern chromatography lines to substitute older cold-ethanol separation processes. According to the Singapore Economic Development Board, specialized capital frameworks and infrastructure investments are utilized to incentivize regional biomanufacturing facilities and advance domestic biotechnology innovation. As per sources, the commercial expansion of plasma therapies is accelerating the integration of modern collection, processing, and downstream isolation technologies. Unlike general biopharmaceutical skills, plasma fractionation expertise requires years of hands on experience with unique unit operations like cold ethanol precipitation and viral inactivation that cannot be rapidly taught through classroom instruction. This human capital deficit means even well funded facilities operate below design capacity due to staffing constraints, creating artificial ceilings on market growth independent of capital availability or regulatory approvals.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Product, Application, End User, and Region. |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered | India, China, Japan, South Korea, Australia, New Zealand, Thailand, Malaysia, Vietnam, Philippines, Indonesia, Singapore, Rest of APAC |
| Market Leaders Profiled |
|
SEGMENTAL ANALYSIS
By Product Insights
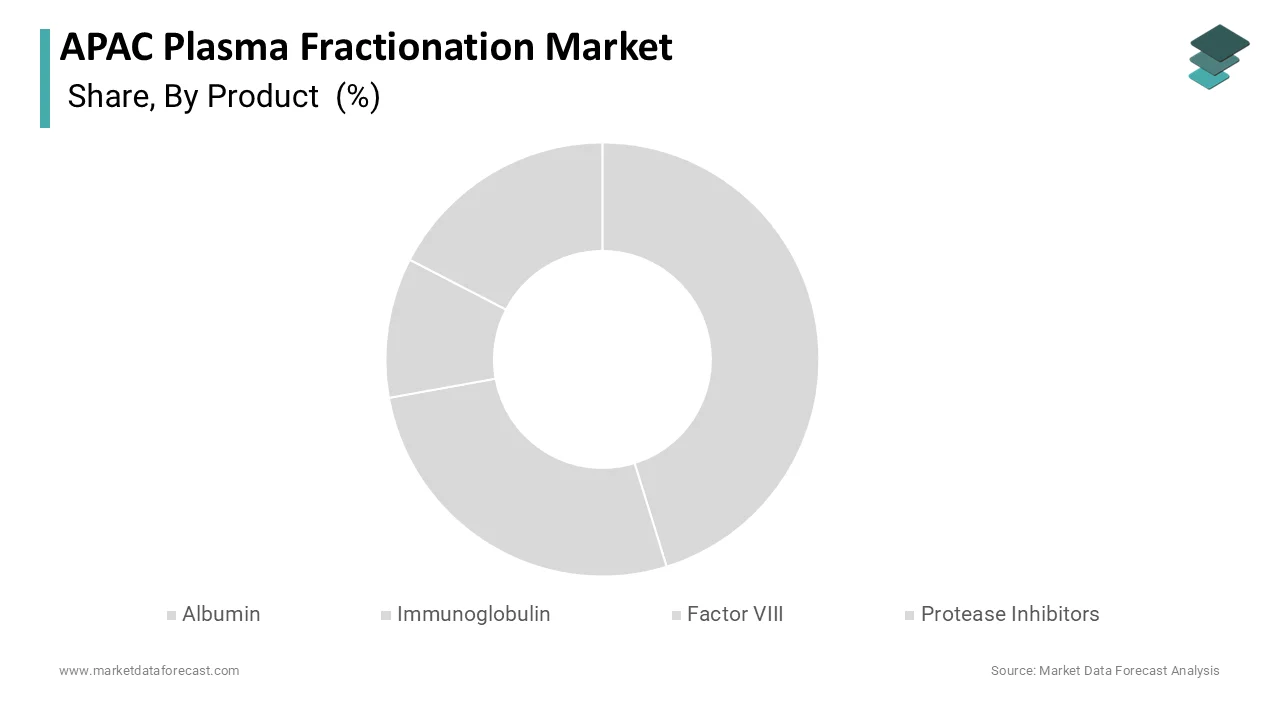
The immunoglobulin segment dominated the Asia Pacific Plasma Fractionation Market and accounted for a substantial share in 2025. This dominance of the segment was driven by its expanding therapeutic utility across neurological, immunological, and hematological conditions that collectively generate consumption volumes exceeding all other plasma proteins combined. According to studies, clinical demand for intravenous and subcutaneous immunoglobulins remains robust across the Asia-Pacific region due to their vital role in treating diverse neurological conditions and primary immunodeficiencies. As per sources advanced manufacturing groups are introducing high-efficiency chromatography processing lines to replace traditional cold-ethanol precipitation techniques. Unlike albumin which faces synthetic competition or coagulation factors limited to rare genetic disorders, immunoglobulin benefits from continuous label expansion into more prevalent acquired conditions, ensuring structural demand growth tied to diagnostic infrastructure maturation rather than static patient pools.
Immunoglobulin segment leadership is structurally reinforced by complete absence of recombinant or synthetic alternatives capable of replicating polyclonal antibody complexity required for immune modulation and pathogen neutralization. According to the International Union of Pure and Applied Chemistry, an individual immunoglobulin molecule consists of globulin-type proteins possessing specific antibody activity structured around light and heavy polypeptide chains. As per BioSpace, the continuous commercial expansion of the global intravenous immunoglobulin sector is driven by rising patient populations requiring targeted immunomodulatory treatments. This technological moat means every diagnosed patient permanently depends on plasma fractionation output with zero substitution elasticity regardless of price increases or supply constraints. India’s Central Drugs Standard Control Organization classifies immunoglobulin as essential medicine with mandatory government stockpiling requirements, creating guaranteed baseline procurement independent of market dynamics. This irreplaceability transforms immunoglobulin from commodity pharmaceutical into strategic biological resource where supply security concerns override cost considerations in procurement decisions across both public and private healthcare systems throughout the region.
The protease inhibitors segment is expected to exhibit a noteworthy CAGR of 11.8% during the forecast period owing to accelerating recognition of alpha 1 antitrypsin deficiency as underdiagnosed cause of chronic obstructive pulmonary disease and liver cirrhosis across Asia Pacific populations. According to Respirology, alpha-1 antitrypsin deficiency represents a prominent genetic risk factor that requires phenotype or genotype analysis to be differentiated from other chronic respiratory diseases. As per research, healthcare networks are implementing advanced screening and diagnostic technologies to optimize patient tracking for rare medical conditions. Unlike established products with saturated patient identification, protease inhibitors benefit from massive undiagnosed reservoir being systematically converted to treated population through improved clinician awareness and accessible genetic testing. Each new diagnosis initiates lifelong weekly infusions creating cumulative demand growth compounding annually as diagnostic penetration improves across diverse national healthcare systems with varying rare disease infrastructure maturity levels.
Accelerated protease inhibitor growth stems from progressive regulatory approvals and reimbursement expansions across previously underserved Asia Pacific jurisdictions removing historical access barriers. According to research, social safety net programs are being expanded to handle the rising systemic healthcare expenditures associated with specialized chronic therapies. According to the Singapore Economic Development Board, specialized capital frameworks and infrastructure investments are utilized to incentivize regional biomanufacturing facilities and advance domestic biotechnology innovation. The policy interventions transform protease inhibitors from niche luxury available only in wealthy nations to increasingly accessible standard of care across developing markets, driving growth rates exceeding mature product segments constrained by saturated patient identification.
By Application Insights
The immunology segment led the Asia Pacific Plasma Fractionation Market and captured a significant share in 2025. This leading position was segment was attributed to primary immunodeficiency disorders requiring lifelong immunoglobulin replacement therapy that generates predictable baseline demand unaffected by economic cycles or seasonal variations. According to studies, advanced manufacturing groups across the Asia-Pacific region are expanding high-efficiency chromatography lines to replace traditional cold-ethanol precipitation techniques. As per the Ministry of Health, Labour and Welfare of Japan, the national pharmaceutical reimbursement framework utilizes price revisions to handle healthcare expenditures while providing universal coverage for essential therapeutic treatments. Unlike acute indications with episodic treatment patterns, immunology applications create perpetual demand streams where each diagnosed patient represents permanent addition to fractionation throughput requirements, making this segment foundational to sustainable business models across regional manufacturers.
The leading position of this segment is bolstered by explosive growth in autoimmune neurological disorder treatments utilizing high dose immunoglobulin as first line or adjunctive therapy across diverse conditions. According to sources, advanced manufacturing entities are prioritizing continuous technology upgrades to secure highly optimized protein extraction profiles. As per BioSpace, the ongoing commercial expansion of the global intravenous immunoglobulin market is driven by an increasing cohort of target patient populations needing specific therapeutic regimens. The protocol expansions transform immunology from narrow replacement therapy domain into broad immunomodulatory platform addressing prevalent acquired conditions with substantially larger patient pools than rare genetic immunodeficiencies alone.
The neurology segment is projected to grow at CAGR of 12.4% from 2026 to 2034 due to accelerating recognition of treatable autoimmune neuropathies previously misdiagnosed as degenerative conditions without therapeutic options. As per studies, manufacturing groups are transitioning to modern chromatography lines to substitute older cold-ethanol separation processes. According to PMC, the deployment of human immunoglobulins remains vital across public health frameworks for the management of complex, rare neuroimmunological disorders. Each correctly diagnosed patient initiates high dose maintenance therapy consuming more immunoglobulin per kilogram than primary immunodeficiency replacement, amplifying volume impact of diagnostic improvements. This recognition wave converts previously hopeless progressive disability into manageable chronic condition, simultaneously improving patient outcomes and driving disproportionate fractionation demand growth.
Accelerated neurology segment growth also show emergence of pediatric autoimmune encephalitis as distinct treatable entity requiring prolonged immunoglobulin courses alongside conventional immunosuppression. As per sources, biopharmaceutical organizations employ specialized regulatory pathways to expedite the validation and clinical approval of specialized plasma proteins. According to research, healthcare networks are implementing advanced screening and diagnostic technologies to optimize patient tracking for rare medical conditions. Pediatric patients require weight based dosing escalating with growth, creating increasing per patient consumption over multiyear treatment courses. This newly recognized disease category adds entirely new patient cohort to neurology application segment independent of adult degenerative condition trends, contributing incremental growth vectors absent in mature therapeutic areas.
COUNTRY LEVEL ANALYSIS
China Plasma Fractionation Market Analysis
China was the top performer in Asia Pacific Plasma Fractionation Market and held a share of 32.1% in 2025. This supremacy of the Chinese market was propelled by massive domestic demand, substantial manufacturing capacity, and strategic government prioritization of plasma protein self sufficiency. According to the Ministry of Commerce of China, the 14th Five-Year Plan for Bioeconomy Development targets a multi-pronged expansion of domestic healthcare infrastructure, biotechnology innovation, and biological manufacturing sectors through 2025. As per sources, leading blood product enterprises such as Shanghai RAAS and Hualan Biological expanded their domestic collection infrastructure to help handle a national total of over 12,000 tonnes of plasma. Provincial governments offer land subsidies and tax incentives for new facilities meeting national self sufficiency targets under 14th Five Year Plan bioeconomy provisions. However, import dependency persists for specialized products like protease inhibitors and certain immunoglobulin formulations not yet domestically produced, creating dual track market with protected domestic segment and competitive import segment. China’s scale and policy driven development trajectory make it indispensable market anchor whose capacity expansion decisions significantly influence global plasma pricing and supply allocation dynamics.
Japan Plasma Fractionation Market Analysis
Japan was the next prominent country in the Asia-Pacific plasma fractionation market and accounted for a 24.8% share in 2025, because of the highest per capita consumption, sophisticated domestic manufacturing, and comprehensive universal coverage ensuring equitable access. According to the Ministry of Health, Labour and Welfare of Japan, the national plasma control framework oversees a domestic production system that yields approximately 5 million liters of plasma annually. As per the Ministry of Health, Labour and Welfare, the Japanese pharmaceutical reimbursement framework utilizes price revisions to handle national medical expenditures while providing universal health insurance coverage for essential plasma-derived treatments. As per the Japan Blood Products Organization, the Ministry of Health, Labour and Welfare collaborates with domestic manufacturers to improve domestic fractionation efficiency and national supply security. According to the Statistics Bureau of Japan, the demographic cohort aged 65 years and older reached 36.24 million individuals, constituting 29.3% of the total national population. However, strict donor eligibility criteria and prohibition of compensated donation limit collection growth potential despite rising clinical needs. Japan’s regulatory sophistication and quality standards establish regional benchmarks influencing harmonization efforts across neighboring countries pursuing similar self sufficiency objectives.
Australia Plasma Fractionation Market Analysis
Australia occupies a significant position in the Asia Pacific plasma fractionation market due to world-leading per capita plasma collection, an export-oriented fractionation model, and an innovative public-private partnership structure balancing commercial efficiency with national supply security. According to the Australian Red Cross Lifeblood, the voluntary, non-remunerated donation system successfully generated 721,924 litres of national plasma during the 2024 collection cycle. As per studies, the CSL facility located in Broadmeadows, Melbourne utilizes domestic plasma provided via a dedicated national contract to produce critical plasma-derived medicinal therapies for the local patient population. Therapeutic Goods Administration maintains rigorous but efficient regulatory framework with average approval timelines of several months for plasma products facilitating timely market access. Medicare universal coverage includes all clinically indicated plasma derived medicines with no patient copayments for public hospital administered therapies. However, geographic isolation creates logistics vulnerabilities during global supply disruptions despite domestic production capacity. Australia’s hybrid model demonstrates how medium sized populations can achieve both self sufficiency and commercial viability through strategic government contracting and operational excellence, providing template for other developed Asia Pacific nations seeking balanced approaches.
India Plasma Fractionation Market Analysis
India is expected to showcase a promising CAGR in the Asia Pacific plasma fractionation market owing to a massive untreated patient burden, expanding domestic manufacturing, and progressive policy reforms addressing historical access gaps. As per sources, manufacturing groups are transitioning to modern chromatography lines to substitute older cold-ethanol separation processes. Ayushman Bharat scheme indirectly stimulates demand by improving overall healthcare access and diagnostic infrastructure enabling identification of previously invisible patient populations. According to research, the network of more than 2,700 registered domestic blood centers collects roughly 10 to 11 million units of whole blood annually. Price controls on essential medicines compress margins limiting reinvestment capacity for technology upgrades. India’s combination of scale, policy momentum, and infrastructure gaps creates unique risk reward profile attracting both domestic champions and multinational investors seeking exposure to next decade’s largest growth story.
South Korea Plasma Fractionation Market Analysis
South Korea is also a key player in the Asia Pacific plasma fractionation market due to a strong domestic manufacturer, GC Pharma; comprehensive national health insurance coverage; and an active clinical research ecosystem, driving indication expansion. As per studies, GC Biopharma runs local operations to supply core immunoglobulins and plasma therapies to fulfill national therapeutic requirements. According to the Korean Health Insurance Review and Assessment Service, the national medical insurance database records continuous epidemiology tracking and rare disease monitoring to trace the long-term clinical development of peripheral neuropathies. Seoul National University and Asan Medical Center conduct internationally recognized neuroimmunology research generating local evidence supporting guideline updates and formulary expansions. However, aging population and low birth rate create long term donor base sustainability concerns despite current adequacy. South Korea’s integration of manufacturing, clinical research, and payer policy creates cohesive ecosystem supporting both domestic self sufficiency and regional export ambitions.
COMPETITIVE LANDSCAPE
Competition in Asia Pacific Plasma Fractionation Market exhibits pronounced stratification between multinational leaders dominating premium export segments and domestic champions capturing protected national markets through policy alignment and cost advantages. Global players leverage superior technology and regulatory credentials to serve import dependent nations lacking domestic capacity while domestic manufacturers benefit from government protectionism and preferential procurement in self sufficiency focused markets like China and India. Innovation competition centers on yield improvement and process efficiency rather than novel products due to mature therapeutic class and biological constraints. Geographic coverage capabilities often outweigh technological superiority given plasma collection limitations defining true competitive advantage. Regulatory navigation expertise creates durable moats as approval complexity favors established players with dedicated compliance infrastructure. Price competition intensifies in commodity albumin segments while specialty immunoglobulins command premiums tied to clinical differentiation and supply reliability. Competitive dynamics continue evolving as domestic manufacturers upgrade quality standards enabling export ambitions while multinationals localize production to maintain access amid rising protectionism. Currency volatility periodically reshuffles competitive positions by advantaging locally sourced products over imports during depreciation cycles creating temporal windows for domestic player advancement.
KEY MARKET PLAYERS
Some of the companies that are playing a dominating role in the Asia Pacific Plasma Fractionation Market include:
- CSL Ltd.
- Grifols S.A.
- Baxalta Incorporated
- Octapharma AG
- Kedrion S.p.A.
- Bio Products Laboratory Ltd.
- Sanquin
- China Biologic Products, Inc.
- Biotest AG
- Laboratoire Français du Fractionnement et des Biotechnologies (LFB)
TOP LEADING PLAYERS IN THE MARKET
- CSL Seqirus maintains significant involvement in the Asia Pacific Plasma Fractionation Market through integrated collection and fractionation operations spanning Australia and New Zealand with strategic export capabilities serving regional supply needs. Educational initiatives trained over five hundred clinicians across Southeast Asia on appropriate plasma protein utilization building prescriber confidence and therapeutic adoption. These multifaceted strategies reinforce CSL position as regional supply anchor supporting both national self sufficiency objectives and cross border trade flows throughout diverse Asia Pacific markets with varying infrastructure maturity levels.
- GC Pharma contributes substantially to Asia Pacific Plasma Fractionation landscape through vertically integrated Korean operations combining domestic plasma collection with advanced manufacturing capacity serving both local demand and regional export markets. Strategic collaborations with Seoul National University generated local clinical evidence supporting guideline updates for neurological indications expanding addressable patient populations beyond traditional immunodeficiency segments. Manufacturing process upgrades implemented multimodal chromatography platforms improving purity profiles meeting evolving pharmacopoeial standards across multiple jurisdictions simultaneously. These localized adaptation efforts demonstrate commitment to addressing diverse regional needs through flexible product portfolios and supply chain innovations tailored to specific national regulatory and clinical requirements.
- Shanghai RAAS strengthens its position in Asia Pacific Plasma Fractionation Market through dominant domestic Chinese manufacturing base ensuring affordable supply security for world’s largest plasma protein consumer market while expanding international footprint. The company upgraded Jiangxi production facility in late 2024 implementing continuous processing technology reducing batch cycle times by 35 percent and increasing throughput without proportional capital expenditure increase. Shanghai RAAS signed technology transfer agreements with Vietnamese manufacturers in 2024 enabling regional production expansion reducing logistics costs and currency exposure for Southeast Asian markets. Regulatory approvals obtained in eight ASEAN countries during 2024 opened new export channels leveraging competitive pricing advantages from scaled domestic operations. Research partnerships with Fudan University integrated proteomics analytics into process optimization improving yield consistency and reducing batch failures. Pricing strategies aligned with national volume based procurement programs ensure accessibility while maintaining sustainable margins through operational efficiencies. These strategic investments position Shanghai RAAS as emerging regional champion challenging multinational incumbents through cost leadership and progressively expanding quality credentials beyond domestic protected market.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players employ vertical integration strategies controlling plasma collection through fractionation to secure raw material supply in constrained markets. Companies invest heavily in chromatographic technology upgrades improving protein yields from limited plasma inputs enhancing unit economics. Regulatory harmonization efforts prioritize WHO prequalification and mutual recognition pathways accelerating multi country market access. Strategic government partnerships align commercial objectives with national self sufficiency priorities securing favorable policy treatment and guaranteed offtake. Clinical education programs build specialist competency and therapeutic adoption expanding addressable patient populations beyond historical niches. Geographic diversification establishes regional hubs buffering against single market volatility and enabling cross border supply balancing. Process innovation focuses on continuous manufacturing reducing batch variability and improving capacity utilization without greenfield investment. Portfolio expansion targets high growth orphan indications with premium pricing offsetting commodity albumin margin compression. Supply chain resilience investments include redundant testing capabilities and buffer stocks mitigating pathogen related disruption risks. Talent development initiatives partner with universities creating specialized workforce pipelines addressing chronic bioprocessing skill shortages across region.
MARKET SEGMENTATION
This research report on the APAC plasma fractionation market has been segmented and sub-segmented into the following categories.
By Product
- Albumin
- Immunoglobulin
- Factor VIII
- Protease Inhibitors
By Application
- Neurology
- Hematology
- Rheumatology
- Pulmonology
- Immunology
By End User
- Hospitals
- Clinical Laboratories
By Country
- India
- China
- Japan
- South Korea
- Australia
- New Zealand
- Thailand
- Malaysia
- Vietnam
- Philippines
- Indonesia
- Singapore
- Rest of APAC