- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$6.82 BnMarket Estimate, 2026
$7.21 BnMarket Forecast, 2034
$11.25 BnCAGR, 2026–2034
5.72%Executive Summary: Asia Pacific Silica Sand Market
- Market Scope: Comprehensive analysis of the Asia Pacific silica sand sector, detailing end-user segments, country profiles, market drivers, restraints, and competitive landscapes.
- Market Valuation: Valued at USD 6.82 billion in 2025, reaching USD 7.21 billion in 2026, and projected to expand to USD 11.25 billion by 2034, growing at a steady CAGR of 5.72% from 2026 to 2034.
- Primary Growth Drivers: Escalating demand from the glass manufacturing industry (particularly photovoltaic glass for solar panels), rapid urbanization boosting infrastructure construction, and expansion of hydraulic fracturing activities in oil and gas recovery.
Key Market Segment Metrics
| Category | Leading Segment (Base Position) | Fastest-Growing / High-Growth Segment |
|---|---|---|
| By End User | Glass Manufacturing (leading with a 36.1% market share in 2025, driven by flat, container, and photovoltaic glass) | Oil and Gas Recovery (predicted to grow at a CAGR of 9.04% due to expanding hydraulic fracturing and shale gas projects) |
| By Country / Region | China (largest regional market share in 2025, accounting for over 60% of global glass production and extensive automated mining infrastructure) | Japan & South Korea (exhibiting prominent CAGRs through high-purity silica sand adoption in advanced electronics and precision manufacturing) |
Major Market Players & Industry Landscape
Market Structure: Highly competitive landscape driven by established multinational corporations and niche regional players focusing on sustainable mining practices, R&D innovation, and strategic partnerships.
Key Companies: Sibelco, Chongqing Changjiang River Moulding Material Group Co. Ltd (CCRMM), JFE Mineral & Alloy Company Ltd, PUM Group, Mitsubishi Corporation, VRX Silica Ltd, Tochu Corporation, Mangal Minerals, Raghav Productivity Enhancers Limited, and Diatreme Resources Limited.
 Download Free Sample Report
Asia Pacific Silica Sand Market Size
The Asia Pacific silica sand market size was calculated to be USD 6.82 billion in 2025 and is anticipated to be worth USD 11.25 billion by 2034, from USD 7.21 billion in 2026, growing at a CAGR of 5.72% during the forecast period.

Silica sand is an important raw material and is used in various industries such as glass manufacturing and foundries to hydraulic fracturing and construction. Silica sand, composed primarily of quartz, is valued for its high purity, durability, and versatility, making it indispensable in industries that drive economic growth. The Asia-Pacific region accounts for a significant portion of global industrial production, with silica sand playing a pivotal role in sectors such as electronics, infrastructure development, and renewable energy. The rise of solar panel manufacturing has amplified the demand for high-purity silica sand, which is essential for producing photovoltaic glass. Rapid urbanization in the Asia Pacific region has led to an unprecedented surge in construction activities, creating immense demand for silica sand in concrete, mortar, and asphalt applications. With advancements in mining technologies enabling sustainable extraction practices, the Asia Pacific Silica Sand Market continues to expand, serving as a vital enabler of innovation and economic progress across multiple industries.
MARKET DRIVERS
Rising Demand in the Glass Manufacturing Industry
The escalating demand for glass products is one of the key factors driving the growth of the Asia Pacific Silica Sand Market. According to the International Glass Federation, the Asia Pacific region accounts for over 50% of global glass production, with countries like China and India leading large-scale manufacturing projects. Silica sand, being the primary raw material for glass production, is extensively used in flat glass, container glass, and specialty glass applications, aligning with regulatory mandates aimed at promoting green architecture and energy-efficient building practices. The increasing focus on renewable energy infrastructure is further boosting the regional market growth. The adoption of solar panels in the region is projected to grow at a promising CAGR over the next decade, which is likely to create significant opportunities for silica sand manufacturers. High-purity silica sand is critical for producing photovoltaic glass, which enhances the efficiency of solar panels. Additionally, stringent building codes enforced by governments, such as China’s Green Building Evaluation Standard, have accelerated the adoption of high-performance glass products. These factors not only cater to economic considerations but also align with global sustainability goals, thereby fueling the expansion of the silica sand market.
Expansion of Hydraulic Fracturing Activities
The rapid expansion of hydraulic fracturing activities in the Asia Pacific region has significantly bolstered the demand for silica sand used as proppants in oil and gas extraction. The region’s natural gas consumption is projected to grow by 30% over the next decade and this results in the immense demand for high-quality silica sand to enhance the efficiency of hydraulic fracturing operations. The rising adoption of unconventional energy sources, particularly shale gas that relies heavily on silica sand to maintain fissures in rock formations and facilitate the flow of hydrocarbons is also aiding the silica sand market growth in this region. The rising adoption of advanced fracturing technologies has increased the demand for high-purity silica sand formulations that minimize environmental impact. Moreover, as per the United Nations Environment Programme (UNEP), the shift toward cleaner energy sources has increased investments in gas exploration projects, further boosting the demand for silica sand. These innovations position silica sand as a transformative solution for modern energy production, ensuring both performance and sustainability.
MARKET RESTRAINTS
Stringent Environmental Regulations
The stringent environmental regulations governing the extraction and processing of silica sand is one of the major restraints of the Asia-Pacific silica sand market. The United Nations Environment Programme (UNEP) and regional authorities impose strict guidelines on permissible levels of dust emissions, water usage, and land rehabilitation, which are often mirrored by national policies. However, as per the Biotechnology Innovation Organization, the average time required to secure regulatory approval for new mining projects can exceed five years, accompanied by substantial operational expenditures. This prolonged timeline poses significant challenges for manufacturers aiming to meet the growing demand for silica sand while adhering to environmental standards. Moreover, discrepancies between national and international regulations often lead to fragmented compliance requirements, complicating distribution efforts. For example, Australia’s Environment Protection Authority imposes additional restrictions on mining activities near ecologically sensitive areas, creating hurdles for companies operating nationwide. Such inconsistencies deter investment in sustainable mining practices, stifling innovation and delaying the availability of high-quality silica sand products.
Volatility in Raw Material Availability
The volatility in raw material availability, particularly in regions prone to geological and logistical challenges is further impeding the expansion of silica sand market in Asia-Pacific. According to the World Bank, fluctuations in mining output have surged by 25% in recent years due to geopolitical tensions and supply chain disruptions. This instability creates challenges for silica sand manufacturers, who must navigate rising input costs while maintaining competitive pricing for their products. Such price volatility disproportionately affects small-scale producers who operate on tight margins and lack the resources to absorb sudden cost increases. Larger enterprises, though more resilient, also face pressure to balance input expenses against market dynamics. Additionally, the complexity of sourcing high-purity silica sand deposits often requires additional investments in exploration and extraction technologies, further inflating operational costs. These combined factors limit accessibility to high-quality silica sand, impeding its overall market penetration across diverse industrial sectors.
MARKET OPPORTUNITIES
Adoption of Sustainable Mining Practices
The adoption of sustainable mining practices due to the growing consumer demand for environmentally friendly products is one of the significant opportunities in the Asia-Pacific silica sand market. As per the United Nations Environment Programme (UNEP), the Asia Pacific region is projected to account for over 60% of global green product consumption by 2030, which is generating significant demand for silica sand sourced through eco-friendly methods. These sustainable practices not only reduce reliance on traditional mining techniques but also align with regulatory frameworks aimed at promoting circular economies. Simultaneously, the rise of regenerative practices presents a novel avenue for innovation. According to the studies, regenerative initiatives could sequester up to 1.5 gigatons of carbon dioxide annually, with sustainable silica sand mining serving as a cornerstone of these systems. For instance, low-impact mining technologies are effective in reducing greenhouse gas emissions during extraction, as reported by the University of Queensland. By diversifying into these emerging sectors, manufacturers can tap into rapidly expanding markets driven by sustainability goals and shifting consumer preferences, positioning themselves at the forefront of future-oriented industrial practices.
Growth in Renewable Energy Infrastructure
The advent of renewable energy infrastructure is another promising opportunity for the Asia Pacific Silica Sand Market. Silica sand is critical for producing photovoltaic glass, which enhances the efficiency of solar panels and supports the transition to clean energy. For example, advancements in nano-silica sand formulations enable manufacturers to achieve superior thermal and optical properties, directly impacting energy efficiency. The adoption of sustainable energy practices in the Asia-Pacific is growing, which is resulting in the rising demand for silica sand in wind turbine components and battery storage systems. These benefits not only cater to economic considerations but also align with consumer preferences for responsibly produced goods, thereby fueling the expansion of the silica sand market.
MARKET CHALLENGES
Resistance to the Adoption of New Technologies
The resistance to the adoption of new technologies exhibited by traditional miners entrenched in conventional practices is a major challenge to the Asia-Pacific silica sand market. As per surveys conducted by the Federation of Indian Chambers of Commerce and Industry (FICCI), nearly 40% of small-scale silica sand producers remain hesitant to adopt advanced extraction or processing technologies due to skepticism about their effectiveness or unfamiliarity with implementation processes. This reluctance is particularly pronounced among older generations who prioritize tried-and-tested methods over experimental approaches. Furthermore, cultural and regional disparities exacerbate this issue. For example, rural areas in Southeast Asia tend to have lower adoption rates compared to technologically progressive regions like Japan and South Korea, where large-scale operations dominate. Addressing these gaps necessitates tailored communication strategies that resonate with local contexts and priorities. Without overcoming this barrier, the full potential of advanced silica sand solutions cannot be realized, limiting their contribution to enhanced productivity and sustainability across the industrial value chain.
Concerns Over Environmental Impact and Regulation
Environmental concerns are further challenging the expansion of the Asia Pacific Silica Sand Market, especially regarding pollution and resource depletion. For instance, over 70% of industrial emissions in the region are attributed to mining activities, including silica sand extraction, prompting stricter regulations on chemical discharges and dust emissions. Traditional mining practices, despite their efficiency, are often scrutinized for their potential contribution to these issues if not managed responsibly. Such sentiments place immense pressure on manufacturers to develop low-impact alternatives while adhering to complex regulatory frameworks. For example, China’s Ministry of Ecology and Environment imposes strict limits on wastewater and air emissions, creating additional hurdles for companies operating nationwide. Additionally, misinformation spread via social media platforms amplifies public distrust, creating reputational risks for brands associated with controversial mining practices. To navigate these challenges effectively, industry players must invest in transparent marketing campaigns and engage directly with stakeholders to build trust and dispel misconceptions surrounding silica sand safety and functionality.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 5.72% |
| Segments Covered | By End User, And Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis; Segment-Level Analysis; DROC, PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | India, China, Japan, South Korea, Australia, New Zealand, Thailand, Malaysia, Vietnam, Philippines, Indonesia, Singapore, Rest Of Asia-Pacific |
| Market Leaders Profiled | Sibelco, Chongqing Changjiang River Moulding Material Group Co. Ltd (CCRMM), JFE Mineral & Alloy Company Ltd, PUM Group, Mitsubishi Corporation, VRX Silica Ltd, Tochu Corporation, Mangal Minerals, Raghav Productivity Enhancers Limited, Diatreme Resources Limited |
SEGMENTAL ANALYSIS
By End-User Insights
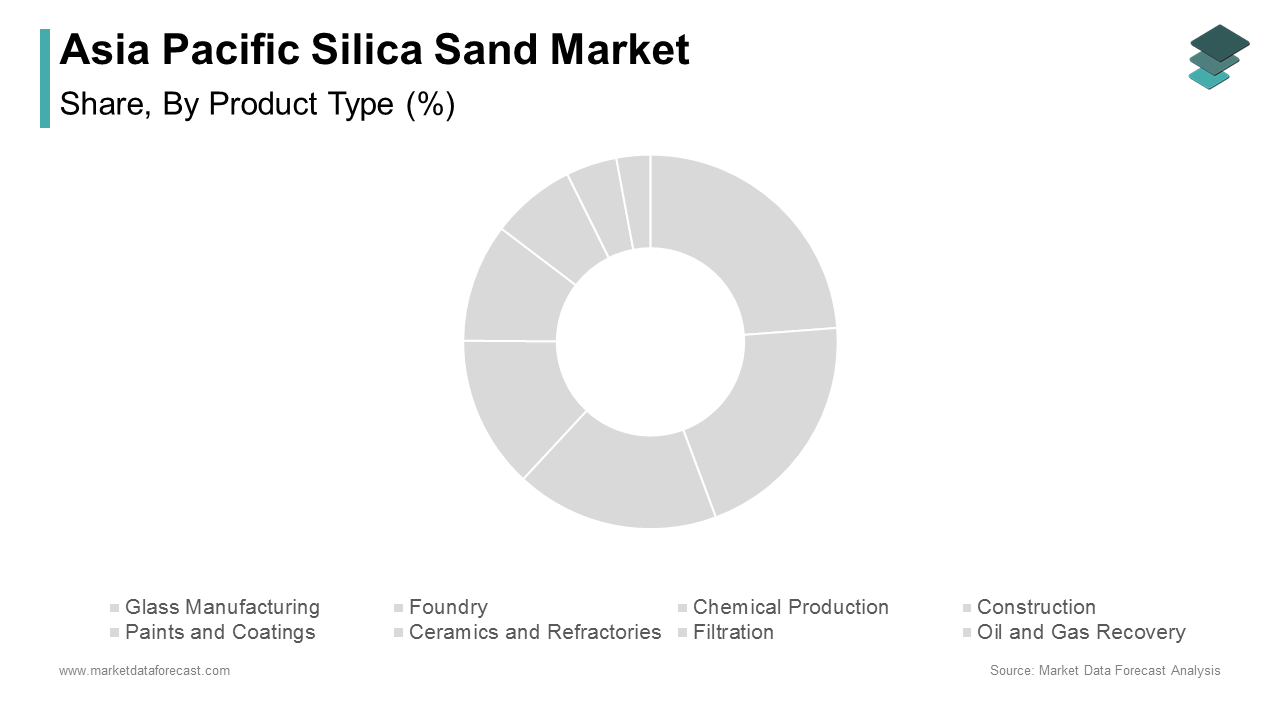
The glass manufacturing segment led the market by occupying a share of 36.1% of the regional market in 2025. The leading position of glass manufacturing segment in the Asia-Pacific market is driven by the region's booming glass production sector, which supplies materials for flat glass, container glass, and specialty glass applications such as solar panels and automotive windshields. According to the United Nations Industrial Development Organization (UNIDO), over 50% of global glass production occurs in the Asia Pacific region, which is generating immense demand for high-purity silica sand. The rising focus on renewable energy infrastructure is further boosting the dominance of glass manufacturing segment in the Asia-Pacific market. Over the next 10 years, the number of solar panel installations in the Asia-Pacific region are projected to grow promisingly and is likely to generate significant opportunities for silica sand manufacturers. High-purity silica sand is critical for producing photovoltaic glass, which enhances the efficiency of solar panels. Additionally, stringent building codes enforced by governments, such as China’s Green Building Evaluation Standard, have accelerated the adoption of energy-efficient glass products. These factors ensure that glass manufacturing remains the largest end-user industry in the market.
The oil and gas recovery segment is another major segment and is predicted to grow at a CAGR of 9.04% over the forecast period. Factors such as the increasing adoption of hydraulic fracturing techniques, particularly in shale gas extraction projects is primarily propelling the growth of the oil and gas recovery segment in this regional market. For example, countries like China and Australia are investing heavily in unconventional energy sources, which rely on silica sand as proppants to maintain fissures in rock formations and facilitate hydrocarbon flow. The rising demand for cleaner energy sources in this region is further aiding the expansion of the oil and gas recovery segment in the Asia-Pacific market. Moreover, as per the United Nations Environment Programme (UNEP), the shift toward reducing reliance on coal has increased investments in natural gas exploration projects, further boosting the demand for silica sand. These innovations position oil and gas recovery as a transformative force in the silica sand market, ensuring both performance and sustainability.
REGIONAL ANALYSIS
China had the largest share of the Asia Pacific silica sand market in 2025. The dominance of China in the Asia-Pacific market is driven by the Chinese vast industrial base that supports large-scale production of silica sand for diverse applications, including glass manufacturing, construction, and oil and gas recovery. China accounts for over 60% of global glass production, underscoring its critical role in the silica sand market. The presence of advanced mining technologies in China is further aiding the dominating position of China in the Asia-Pacific market. According to sources, more than 70% of Chinese silica sand producers utilize automated systems, enabling seamless integration of innovative extraction and processing methods. Additionally, stringent environmental regulations enforced by the Ministry of Ecology and Environment have accelerated the adoption of eco-friendly mining practices, ensuring compliance with global standards.
India is another promising regional segment for silica sand in the Asia Pacific region. The strong emphasis of India on sustainable practices has positioned it as a hub for eco-friendly silica sand solutions. For instance, over 60% of silica sand manufacturers in India have adopted green technologies to reduce carbon emissions and water pollution. The thriving construction and foundry industries in India are further propelling the silica sand market growth in India. For instance, the urban housing projects in India exceed $1 trillion annually, creating significant demand for silica sand in concrete and mortar applications. Additionally, government incentives for adopting renewable energy sources have spurred the use of silica sand in solar panel manufacturing, further bolstering the market's growth. These initiatives highlight India's commitment to balancing economic development with ecological responsibility.
Japan is anticipated to exhibit a prominent CAGR in the Asia-Pacific silica sand market over the forecast period. The focus of Japan on innovation and precision manufacturing has provided a fertile ground for high-purity silica sand used in advanced applications like electronics, ceramics, and refractories. According to the Japan External Trade Organization (JETRO), Japan's electronics industry exports exceed $200 billion annually, necessitating advanced silica sand materials to meet global quality standards. The growing adoption of specialty silica sand formulations in Japan that are facilitated by investments in R&D is further aiding the expansion of silica sand market in Japan. For instance, nano-silica formulations have gained traction in Japan due to their ability to enhance durability and aesthetic appeal. Additionally, efforts to modernize mining processes through government-funded programs have encouraged small-scale producers to invest in premium silica sand solutions, contributing to Japan's steady market expansion.
South Korea is predicted to exhibit a healthy CAGR in the Asia-Pacific silica sand market over the forecast period. As per the Korea International Trade Association (KITA), South Korea is witnessing gradual adoption of silica sand due to its growing focus on export-oriented industries. For instance, South Korea's semiconductor exports have surged by 15% annually, driven by investments in advanced silica sand formulations. The influx of foreign expertise and technology is also promoting the market growth in South Korea. According to the Korea Institute of Industrial Technology, partnerships with international organizations have introduced cost-effective silica sand solutions tailored to local conditions. These collaborations not only enhance productivity but also promote sustainable practices, laying the foundation for long-term market development.
Australia and New Zealand represent a niche yet emerging player in the Asia Pacific Silica Sand Market, contributing marginally to the overall share. As per the Australian Department of Industry, Science, Energy and Resources, the region's construction sector is undergoing transformation, with a focus on self-sufficiency and resilience against external shocks. Recent bushfires have underscored the need for fortified silica sand materials to mitigate production losses. A key driver of this progress is the adoption of bio-based silica sand mining, which safeguards environmental health during adverse weather conditions. The University of Queensland highlights that these products have increased energy efficiency by up to 20% in local buildings. Additionally, government subsidies aimed at revitalizing rural economies have incentivized builders to invest in advanced silica sand solutions, fostering incremental growth in the market.
LEADING PLAYERS IN THE ASIA PACIFIC SILICA SAND MARKET
Sibelco Asia
Sibelco Asia is a global leader in the Asia Pacific Silica Sand Market, renowned for its high-quality silica sand solutions tailored to meet the diverse needs of industries such as glass manufacturing, foundries, and construction. The company specializes in producing premium-grade silica sand with exceptional purity and consistency, making it indispensable for applications like solar panels and hydraulic fracturing. Sibelco’s commitment to sustainability has positioned it as a pioneer in adopting eco-friendly mining practices that align with stringent environmental regulations. By fostering partnerships with manufacturers and leveraging advanced extraction technologies, Sibelco continues to drive innovation and strengthen its leadership in the regional market.
Unimin Australia Limited
Unimin Australia Limited plays a pivotal role in the Asia Pacific Silica Sand Market by offering specialized silica sand products designed for niche applications like ceramics, refractories, and water filtration. The company focuses on developing sustainable and high-performance silica sand formulations that cater to evolving consumer preferences for green solutions. Unimin’s emphasis on reducing carbon footprints aligns with its efforts to promote circular economies, making its products a preferred choice for eco-conscious industries. By leveraging cutting-edge R&D capabilities, Unimin ensures its silica sand delivers consistent quality and performance, solidifying its reputation as an industry innovator.
PPG Industries Asia Pacific
PPG Industries Asia Pacific is a prominent player in the Asia Pacific Silica Sand Market, specializing in the production of advanced silica sand systems for paints, coatings, and chemical production. The company emphasizes sustainable sourcing practices and invests heavily in developing specialty formulations that enhance product durability and functionality. PPG’s vertically integrated business model allows it to maintain control over the entire supply chain, ensuring traceability and compliance with international standards. By prioritizing customer-centric solutions and investing in next-generation silica sand technologies, PPG continues to strengthen its position as a trusted partner for industrial manufacturers.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Strategic Acquisitions and Partnerships
Key players in the Asia Pacific Silica Sand Market have prioritized strategic acquisitions and partnerships to expand their product portfolios and strengthen their market presence. By acquiring smaller firms specializing in niche silica sand formulations or forming alliances with research institutions, these companies gain access to cutting-edge technologies and innovative solutions. Such collaborations enable them to address unmet needs in the industrial sector while enhancing their competitive edge. This strategy also facilitates entry into underserved markets, allowing companies to capitalize on untapped opportunities and diversify their revenue streams.
Investment in Sustainable Practices
Sustainability has emerged as a cornerstone of competitive strategy in the silica sand market. Leading companies are investing heavily in the development of eco-friendly mining practices that reduce environmental impact, improve resource efficiency, and align with regulatory standards. By focusing on reducing carbon emissions and promoting circular economies, these players position themselves as champions of sustainable industrial practices. Their commitment to environmental stewardship not only enhances brand loyalty but also ensures compliance with evolving global standards, reinforcing their leadership in the market.
Emphasis on Research and Development
R&D is a critical driver of innovation in the Asia Pacific Silica Sand Market. Key players are channeling significant resources into exploring novel formulations and advanced extraction processes that improve silica sand performance and application versatility. By staying at the forefront of technological advancements, these companies can introduce groundbreaking solutions tailored to specific industrial needs. This focus on innovation enables them to differentiate their offerings, meet the demands of modern manufacturing practices, and maintain a strong foothold in an increasingly competitive landscape.
KEY MARKET PLAYERS AND COMPETITION OVERVIEW
Major Players of the Asia Pacific Silica Sand Market include Sibelco, Chongqing Changjiang River Moulding Material Group Co. Ltd (CCRMM), JFE Mineral & Alloy Company Ltd, PUM Group, Mitsubishi Corporation, VRX Silica Ltd, Tochu Corporation, Mangal Minerals, Raghav Productivity Enhancers Limited, Diatreme Resources Limited
The Asia Pacific Silica Sand Market is characterized by intense competition, driven by the presence of established multinational corporations and emerging niche players. Companies strive to differentiate themselves through innovation, sustainability, and customer-centric strategies, creating a dynamic and rapidly evolving landscape. Leaders like Sibelco Asia, Unimin Australia Limited, and PPG Industries Asia Pacific dominate the market by leveraging their extensive R&D capabilities and global reach to deliver high-performance solutions. At the same time, smaller firms focus on specialized products that cater to specific industrial segments or address unique challenges such as toxicity and environmental impact. Regulatory pressures and shifting consumer preferences further intensify competition, compelling companies to adopt sustainable practices and transparent labeling. Collaborations, mergers, and acquisitions are common strategies used to consolidate market share and expand product portfolios. This competitive environment fosters continuous innovation, ensuring that the market remains responsive to the needs of both producers and consumers.
RECENT HAPPENINGS IN THE MARKET
- In April 2025, Sibelco Asia launched a new line of eco-friendly silica sand products designed to reduce environmental impact. This move aims to address growing concerns about pollution in the Asia Pacific region.
- In June 2023, Unimin Australia Limited partnered with a leading renewable energy company to develop high-purity silica sand for solar panel manufacturing. This collaboration underscores Unimin’s commitment to advancing sustainable energy practices through innovation.
- In January 2023, PPG Industries Asia Pacific acquired a startup specializing in nano-silica technology. This acquisition strengthens PPG’s ability to offer high-performance solutions for paints and coatings applications.
- In September 2022, Tata Chemicals introduced a range of low-emission silica sand extraction methods aimed at supporting the construction and infrastructure sectors. This initiative aligns with consumer preferences for durable and environmentally friendly products.
- In November 2022, CDE Global expanded its production facilities in India to increase the supply of high-purity silica sand. This expansion supports the company’s goal of meeting rising demand in the Asia Pacific Silica Sand Market.
MARKET SEGMENTATION
This research report on the Asia Pacific silica sand market has been segmented and sub-segmented based on end user, and region.
By End User
- Glass Manufacturing
- Foundry
- Chemical Production
- Construction
- Paints and Coatings
- Ceramics and Refractories
- Filtration
- Oil and Gas Recovery
- Other End-user Industries
By Region
- India
- China
- Japan
- South Korea
- Australia
- New Zealand
- Thailand
- Malaysia
- Vietnam
- Philippines
- Indonesia
- Singapore
- Rest of Asia-Pacific