- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$9.15 BnMarket Estimate, 2026
$10.37 BnMarket Forecast, 2034
$28.24 BnCAGR, 2026–2034
13.34%Asia Pacific Silk Market Size, Growth, Trends & Forecast (2026–2034)
The Asia Pacific silk market size was valued at USD 9.15 billion in 2025, reached USD 10.37 billion in 2026, and is projected to scale up to USD 28.24 billion by 2034, registering a compound annual growth rate (CAGR) of 13.34% during the forecast period from 2026 to 2034. Driven by rising disposable incomes, government-backed sericulture initiatives like India's Silk Samagra, and technological innovations in yield enhancement and medical-grade applications, the market continues to expand robustly across the region.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 9.15 Billion
- 2026 Current Valuation: USD 10.37 Billion
- 2034 Forecast Valuation: USD 28.24 Billion
- Compound Annual Growth Rate (CAGR): 13.34% (2026–2034)
- Leading Country Market: China (Dominant raw silk production, export volume, and infrastructure scale)
- Leading End-User Segment: Textile (Commanding major market share in luxury apparel and furnishings)
- Fastest-Growing End-User Segment: Cosmetics & Medical (Leveraging silk fibroin and sericin for healthcare and skincare)
- Leading Silk Type Segment: Mulberry Silk (Dominant foundation of the silk value chain)
- Fastest-Growing Silk Type Segment: Eri Silk (Driven by ethical "peace silk" and sustainable demand)
Core Market Drivers
- Rising Disposable Incomes: Expanding luxury consumption and fashion demand across China, India, and Japan, complemented by supportive government sericulture subsidies.
- Technological Advancements: Innovations in sericulture, disease-resistant silkworm strains, and mechanized reeling processes boosting output efficiency and quality.
Primary Market Restraints & Challenges
- High Production Costs: Labor-intensive mulberry cultivation, rearing, and harvesting costs creating a pricing disadvantage compared to synthetic fibers.
- Supply Concentration & Dominance: Heavy regional reliance on China and India exposing global supply chains to geopolitical shifts, trade frictions, or localized disruptions.
Asia Pacific Silk Market Segmentation Highlights
| Segment Category | Leading / Dominant Segment | Fastest-Growing / Prominent Segment |
|---|---|---|
| By End-User | Textile (Dominant share in apparel and luxury weaves) | Cosmetics & Medical (Biomaterials and skincare) |
| By Silk Type | Mulberry Silk (Substantial production share) | Eri Silk (High-growth ethical "peace silk") |
| By Country | China (Undisputed production and export leader) | India (Diverse heritage silks and tech upgrades) |
Major Industry Players Profiled
Key market participants shaping the Asia Pacific landscape include China Silk Corporation, Karnataka Silk Industries Corporation Limited (KSIC), Amsilk GmbH, Anhui Silk Co., Ltd., Sichuan Nanchong Liuhe (Group) Corp., Zhejiang Jiaxin Silk Corp., Ltd., Jiangsu Sutong Cocoon & Silk Co., Ltd., Gunze Limited, and Wensli Group Co., Ltd.
Asia Pacific Silk Market Size
The Asia Pacific silk market size was valued at USD 9.15 billion in 2025, and the Asia Pacific silk market is anticipated to reach a valuation of USD 28.24 billion by 2034 from USD 10.37 billion in 2026, with a CAGR of 13.34% during the forecast period.

The Asia Pacific Silk Market denotes the economic ecosystem of silk, from sericulture and raw cocoons to finished textiles, embedded deeply in fashion, heritage, and artisanal craft across nations such as China, India, Japan, Thailand, and Vietnam. The region leads globally not only in volume but in cultural importance: China and India together supply the majority of mulberry silk, a core raw material widely utilized in luxury, ceremonial, and heritage weaves. This market advances at the intersection of traditional prestige and modern demand for sustainable, high-end textiles.
MARKET DRIVERS
Rising Disposable Income Drives Luxury Silk Demand
As disposable incomes climb across several Asia Pacific economies, luxury consumption is expanding well beyond elite circles. Silk, perceived as the quintessence of luxury, benefits strongly from this wave, especially in fashion-forward markets like China, India, and Japan. In tandem, government support for sericulture, seen most notably in subsidies in India’s Silk Samagra initiative and intelligent mulberry cultivation plans in China, enhances production infrastructure and market readiness. Together, increasing purchasing power and public-sector support propel silk demand.
Technological Advancements Elevate Yield and Quality
Innovation in sericulture, ranging from better silkworm hybrids to mechanized reeling processes and disease-resistant strains, is boosting both output and quality. These improvements expand production scale and raise return per hectare while helping maintain supply amid labor constraints and supply-chain volatility. As production becomes more efficient, Asia Pacific producers can better meet escalating demand for fine silk fabrics, home textiles, and niche medical-grade applications.
MARKET RESTRAINTS
High Production Costs Compared to Synthetic Alternatives
Silk remains labor- and input-intensive. Maintaining sericulture infrastructures, mulberry cultivation, silkworm rearing, and delicate reeling operations contributes to elevated production costs, especially when compared to synthetic fibers that are cheaper and easier to scale. This cost disparity undercuts silk’s competitiveness in lower-priced segments, hindering expansion beyond luxury or artisanal markets.
Competition from Synthetic Fibres
Synthetic alternatives, particularly polyester and rayon, offer affordable, easy-to-produce substitutes for silk, sometimes mimicking its luster. Their lower cost, durability, and easy-care properties make them attractive to cost-conscious consumers and fast-fashion producers, diverting demand away from traditional silk and putting pressure on silk producers to justify premium pricing via heritage, sustainability, and craftsmanship narratives.
MARKET OPPORTUNITIES
Expansion into Medical and Technical Textile Applications
Silk’s exceptional biocompatibility and mechanical properties position it uniquely for high-growth applications in medical textiles, such as surgical sutures, tissue scaffolds, and cosmetic uses. As Asia Pacific scales its medical sector and invests in advanced health-tech, silk’s role in non-traditional verticals offers untapped diversification that may buffer traditional textile volatility.
Sustainable and Organic Silk Production
The global shift toward eco-friendly textiles is opening opportunities for organic and ethically produced silk. This includes low-chemical sericulture practices, traceability of origin, and artisanal craftsmanship. In regions like India’s GI-recognized silk clusters (e.g., Mysore and Arani), these attributes resonate strongly with conscious consumers, offering premium value and a clearer sustainability narrative.
MARKET CHALLENGES
China’s Global Dominance Limits Market Leverage
China controls a substantial share of global silk output and exports, reportedly 63.38% of natural silk products and over 46% of silk and satin exports, giving it pricing and scale advantages. Competing suppliers like India, while substantial, often face inferior economies of scale and lower global negotiating power, limiting both competitiveness and expansion abroad.
Logistical Vulnerability and Over-Centralization Risks
Asia Pacific’s silk production is heavily concentrated in a handful of countries, mainly China and India. This concentration exposes the supply chain to risks such as disease outbreaks, policy shifts, or infrastructural bottlenecks. For example, trade frictions or localized disruptions in China’s exports can ripple across the region, hampering consistent supply and affecting reliability for fashion and luxury brands that demand stable sourcing.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 13.34% |
| Segments Covered | By End-user, Silk Type, and Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | China, Japan, India, and South Korea |
| Market Leaders Profiled | Anhui Silk Co., Ltd. (China), Sichuan Nanchong Liuhe (Group) Corp. (China), Zhejiang Jiaxin Silk Corp., Ltd. (China), Jiangsu Sutong Cocoon & Silk Co., Ltd. (China), China Silk Corporation (China), Karnataka Silk Industries Corporation Limited (India), Tamil Nadu Handloom Weavers Co-operative Society Limited (India). |
SEGMENTAL ANALYSIS
By End-user Insights
The textile sector dominated the Asia-Pacific silk market by representing a dominant share of silk applications. Silk's unrivaled properties, luster, softness, thermal comfort, make it the fabric of choice for luxury garments, bridal sari, high-end fashion, and home textiles. Textiles also benefit from the scale of production across China and India and their entrenched garment industries.
The Cosmetics and medical applications segment is the fastest-growing silk end-user. Silk’s unique biochemical profile, especially silk fibroin and sericin, is leveraged in skincare (anti-aging serums) and biomedical scaffolds and sutures. This growth reflects both scientific advancement and increasing demand for sustainable, bio-friendly resources in healthcare and beauty sectors.
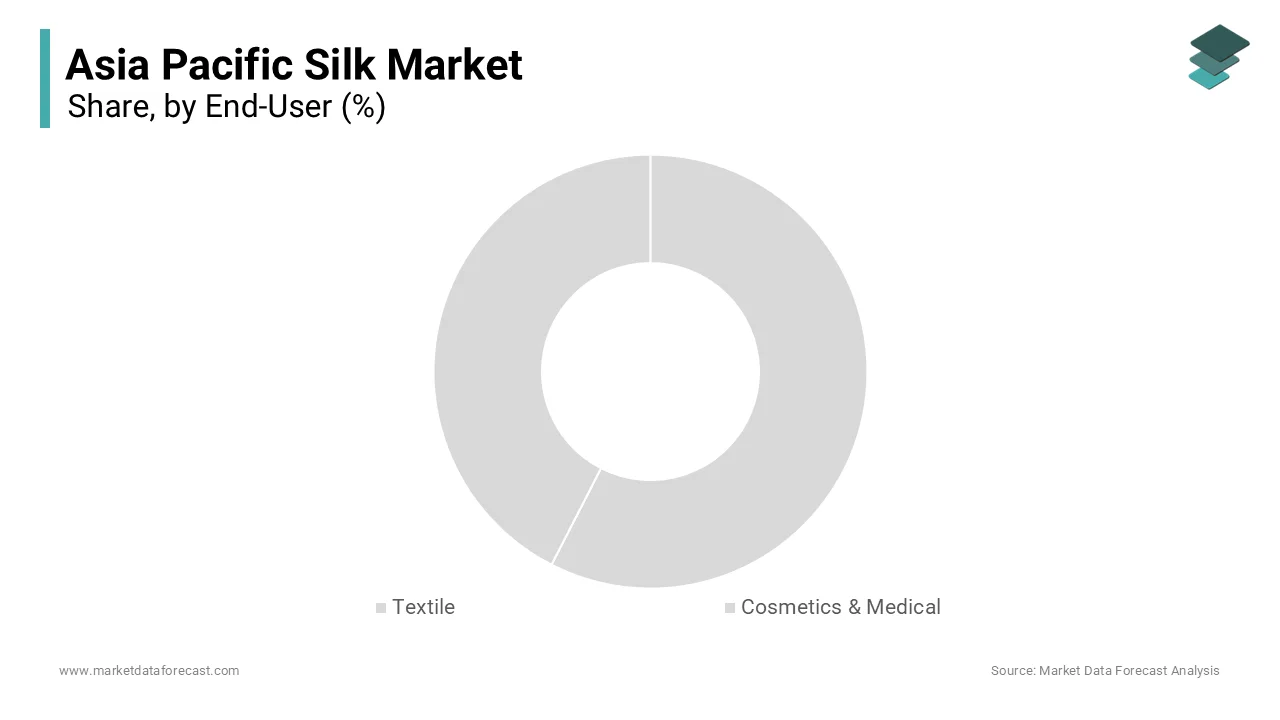
Its domination in textiles is attributed to the controlled cultivation of mulberry, ensuring consistent silk quality. This silk variety, derived from the domesticated Bombyx mori silkworm, is highly sought after in the fashion industry, contributing to the creation of high-end garments and accessories. The textile sector stands out as the cornerstone of the market, driven by the premium qualities of Mulberry Silk.
By Silk Type Insights
The mulberry silk segment is the dominant silk type in Asia-Pacific in 2025 by holding a substantial share of production due to its superior quality, strength, and sheen. Its widespread cultivation and integration into mainstream fashion and textiles makes it the foundation of the silk value chain. Its qualities include uniformity, high tensile strength, and dye affinity, which explain its premium positioning across apparel, accessories, and furnishings.
The Eri silk segment, also known as “peace silk,” is the fastest-growing silk type in terms of CAGR. Its ethical production, harvesting without harming the silkworm, resonates strongly with sustainability-focused markets. It also offers thermal properties ideal for year-round use and a soft, wool-like texture. Growing awareness of eco-conscious fashion and innovations in soft furnishing applications enhance its adoption trajectory.
REGIONAL ANALYSIS
China Silk Market Insights
China is both the undisputed powerhouse and innovation anchor in Asia-Pacific’s silk market, accounting for a substantial share of global raw silk production and exports. Its deeply integrated sericulture ecosystem, from mulberry plantations to finished textiles, enables economies of scale that are unmatched regionally. This depth supports domestic brands and drives global supply chains.
India Silk Market Insights
India plays a vibrant, complexity-rich role as the second-largest silk producer. It stands out for its diversity in silk types, mulberry, eri, tussar, and muga, offering rich heritage and silks with regional provenance. Innovations such as automated reeling units and the Silk Samagra initiative underscore India’s ramp-up in quality and rural value chains, while Kerala and Karnataka remain centers for output.
Japan Silk Market Insights
Japan remains a smaller but high-value player in Asia-Pacific silk, focusing on artisanal, precision-crafted products for luxury textiles and niche industrial uses. While production volumes are limited, Japanese silk brands command global prestige, backed by heritage textile traditions and technical excellence in fine weaving and finishing.
South Korea Silk Market Insights
South Korea is an emerging market characterized by technical textile innovation. Though production capacity is relatively modest, the country’s R&D strengths, especially in silk-related biomedical materials, position it as a future niche leader in functional and medical silk applications.
COMPETITIVE LANDSCAPE
The Asia Pacific Silk Market is characterized by a blend of traditional dominance and emerging innovation, creating an intensely competitive environment. Established producers in China and India lead through scale and heritage, supplying the bulk of raw silk and textiles for regional and international markets. Simultaneously, biotech-driven players are redefining the sector by introducing alternative applications in cosmetics, healthcare, and sustainable materials. Competition is heightened by the dual pressures of cultural demand for luxury silks and modern consumers’ expectations for ethical, traceable, and eco-conscious production. Regional governments support this competitive environment through subsidies, research programs, and sustainability initiatives. This convergence of legacy strengths and cutting-edge applications ensures that rivalry remains both dynamic and future-oriented in the Asia Pacific Silk Market.
KEY MARKET PLAYERS
The major key players in the Asia Pacific Silk Market are Anhui Silk Co., Ltd. (China), Sichuan Nanchong Liuhe (Group) Corp. (China), Zhejiang Jiaxin Silk Corp., Ltd. (China), Jiangsu Sutong Cocoon & Silk Co., Ltd. (China), China Silk Corporation (China), Karnataka Silk Industries Corporation Limited (India), Tamil Nadu Handloom Weavers Co-operative Society Limited (India), Suqian Dafa Silk Co., Ltd. (China), Jiangsu Lugang Culture Co., Ltd. (China), Gunze Limited (Japan), Silk Road Holding Group Co., Ltd. (China), Mysore Silk Factory (India), Wensli Group Co., Ltd. (China), Hangzhou Xiaoshan Silk Group Co., Ltd. (China), Osaka Silk Co., Ltd. (Japan), Sichuan Tianyu Silk Co., Ltd. (China), Thai Silk Co., Ltd. (Thailand), Jiangsu Huamao Textile Co., Ltd. (China), Shanghai Lianbang Textile Technology Co., Ltd. (China), and others.
TOP PLAYERS IN THE MARKET
- China Silk Corporation is a leading integrated producer in the Asia Pacific Silk Market, handling the entire supply chain from mulberry cultivation to luxury fabric exports. The company has invested heavily in advanced reeling technology and digital weaving solutions to meet global fashion demand. In 2025, it partnered with domestic fashion houses to create sustainable silk blends catering to eco-conscious consumers. By emphasizing both scale and innovation, China Silk Corporation strengthens its dominance across Asia and reinforces its exports to high-demand regions such as Japan and India while aligning with government initiatives for green textile development.
- Karnataka Silk Industries Corporation, based in India, plays a vital role in the Asia Pacific Silk Market by producing the globally recognized Mysore silk. The company integrates traditional craftsmanship with modern manufacturing practices, ensuring cultural preservation while meeting rising export demand. KSIC recently expanded its retail presence across Southeast Asia through collaborations with luxury boutiques. In 2025, the company introduced traceability measures, enabling consumers to verify authenticity through digital tagging. Such initiatives help KSIC tap into global markets while showcasing Indian silk heritage, positioning the brand strongly within the luxury apparel and accessories segments.
- Amsilk, a biotech innovator with strong activities in Asia, has made its mark by developing bioengineered silk proteins that cater to cosmetics, medical, and advanced material sectors. In Asia Pacific, the company collaborates with Japanese and South Korean medical firms to introduce silk-based biomaterials for tissue engineering and wound care. By focusing on sustainable biotech applications, Amsilk diversifies silk usage beyond textiles, helping accelerate demand in niche, high-value segments across the region.
TOP STRATEGIES USED BY KEY MARKET PLAYERS
Key participants in the Asia Pacific Silk Market employ a mix of traditional integration and modern innovation to strengthen their position. Vertical integration remains central, with companies like China Silk Corporation ensuring control over the entire supply chain from sericulture to finished fabric, reducing reliance on external vendors. Diversification into high-value segments, particularly cosmetics and biomedical applications, has become a vital growth strategy, as seen in Amsilk’s bioengineered silk expansion. Indian companies, such as KSIC, focus on brand heritage while embedding digital authenticity solutions to appeal to luxury consumers seeking traceability. Sustainability is another key lever, with firms emphasizing eco-friendly production methods and non-violent silk alternatives like eri silk to attract environmentally conscious buyers. Strategic collaborations with global fashion, medical, and cosmetic brands further reinforce competitiveness in an evolving, innovation-driven landscape.
RECENT HAPPENINGS IN THE MARKET
- In February 2025, China Silk Corporation, a leading textile company, introduced a digital weaving technology platform. This Asia Pacific Silk Market innovation is anticipated to enhance efficiency and reduce production waste, strengthening their sustainability commitments in the region.
- In May 2025, Karnataka Silk Industries Corporation, a government-owned enterprise, launched digital authenticity tags for Mysore silk products. This Asia Pacific Silk Market initiative is expected to improve consumer trust and boost global luxury sales.
- In July 2025, Amsilk GmbH, a biotech innovator, partnered with a Japanese skincare firm to co-develop fibroin-based cosmetic serums. This Asia Pacific Silk Market collaboration is aimed at broadening the application of silk proteins in personal care.
- In September 2024, China Silk Corporation expanded partnerships with Indian fashion houses for sustainable silk blends. This Asia Pacific Silk Market action is projected to diversify product offerings and strengthen cross-border collaboration.
- In November 2024, KSIC opened exclusive showrooms in Singapore and Bangkok. This Asia Pacific Silk Market expansion is intended to strengthen retail presence and connect with luxury-focused consumers across Southeast Asia.
MARKET SEGMENTATION
This research report on the Asia Pacific silk market has been segmented and sub-segmented based on the following categories.
By End-User
-
Textile
-
Cosmetics & Medical
By Silk Type
- Mulberry Silk
- Eri Silk
- Tussar Silk
- Others
By Country
-
China
-
Japan
-
India
-
South Korea