- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$11.06 BnMarket Estimate, 2026
$12.10 BnMarket Forecast, 2034
$24.83 BnCAGR, 2026–2034
9.40%Executive Summary: Global Automated Passenger Counting (APC) System Market
- Market Scope: Comprehensive global automated passenger counting system analysis covering transportation applications, counting technologies, vehicle end-uses, and regional expansion trends.
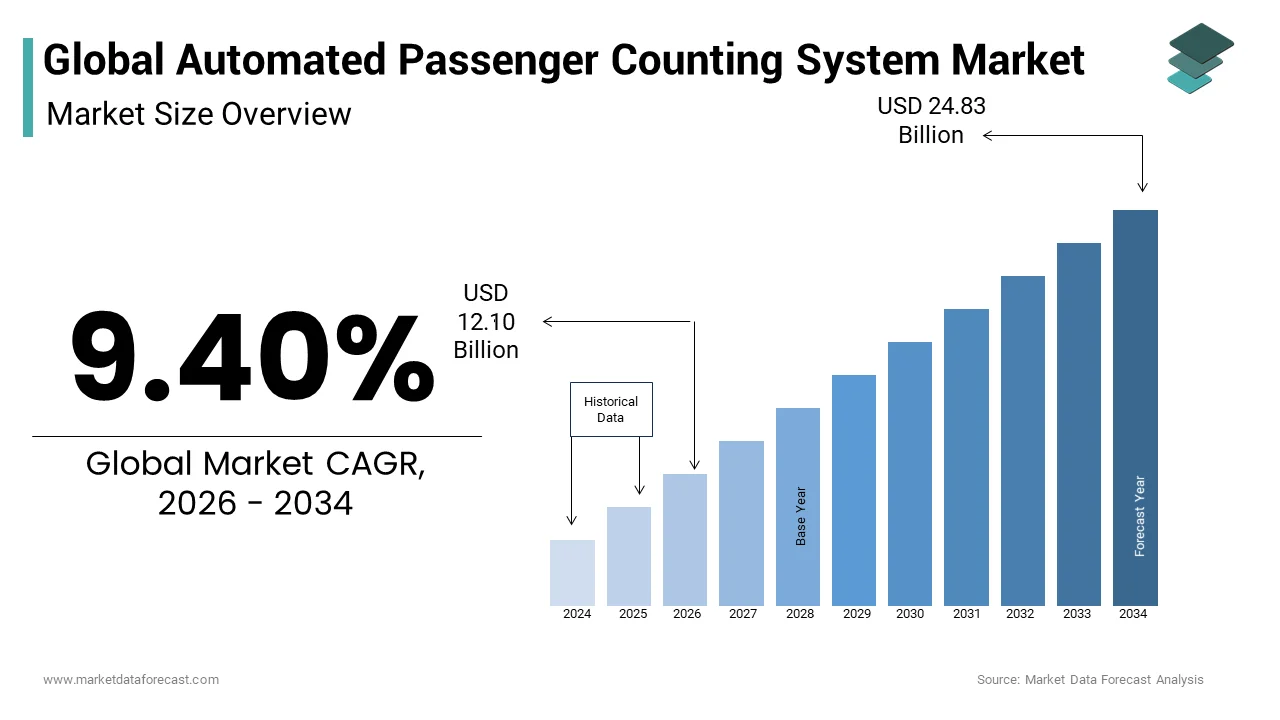
- Market Valuation: Valued at USD 11.06 billion (2025), estimated at USD 12.10 billion (2026), and projected to reach USD 24.83 billion by 2034, registering a stable CAGR of 9.40% (2026–2034).
- Primary Growth Drivers: Government regulations requiring fleet operators to report rider and location-wise customer data; economic advantages of optimizing high-traffic transit routes; and transit modernization initiatives. Restraints include a lack of infrastructure for customer information management systems and limited awareness of APC benefits in developing regions.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Application | Roadways segment (dominates majority market share due to widespread bus fleet tracking) | Roadways public transit networks undergoing digital fleet upgrades |
| By Technology | Stereoscopic vision (accounts for over 40% share, favored for high-volume accuracy unaffected by environmental lighting/heat) | Stereoscopic and Time-of-Flight sensor integrations |
| By End-Use | Buses / Business transit (holds majority share as buses remain the most common daily urban transport) | Ferries (fastest-growing segment driven by the global expansion of marine tourism and ferry vacation culture) |
| By Region | Asia-Pacific (projected to hold the largest market share backed by rapid urbanization and massive populations in China and India) | Asia-Pacific (highest regional CAGR driven by heavy investments in smart public transit infrastructure) |
Major Market Players & Market Structure
Market Structure: Highly competitive intelligent transportation systems (ITS) and sensor technology market featuring hardware manufacturers, software integrators, and telematics providers competing on counting precision, real-time data integration, and multi-modal transit compatibility.
Key Companies: Iris GmbH, Syncromatics Corp, HELLA Aglaia Mobile Vision GmbH, Eurotech S.p.A, Retail Sensing Ltd, Huawei Technology Co. Ltd, Clever Devices Ltd, Trapeze Group, DILAX Intelcom GmbH, Cisco Systems, and Siemens AG.
 Download Free Sample Report
Global Automated Passenger Counting System Market Size
The global automated passenger counting system market size was valued at USD 11.06 billion in 2025 and is anticipated to reach a valuation of USD 12.10 billion in 2026 and USD 24.83 billion by 2034, growing at a CAGR of 9.40%, from 2026 to 2034.
An Automated Passenger Counting (APC) system is an electronic technology that automatically counts how many people get on and off public transit vehicles like buses and trains. As per research, the automated passenger counting sector is expanding due to investments in transit optimisation and intelligent urban mobility infrastructure. According to the International Association of Public Transport, public transport networks bring cities to life by providing approximately 60 billion passenger journeys every year in Europe alone. Furthermore, as per the United Nations Department of Economic and Social Affairs World Urbanisation Prospects, 45 per cent of the world's population lives in cities, and 36 per cent live in towns, making a combined total of 81 per cent in urbanised areas, rather than 57%. This digital transformation turns standard transit fleets into intelligent data nodes, integrating infrared sensors, stereoscopic vision units, and real-time cellular transmitters to elevate operational efficiency while expanding the overall commercial valuation of the automated passenger counting system market across global transit corridors.
MARKET DRIVERS
Surge in Urbanisation and Public Transit Ridership
The escalating metropolitan population density is driving the widespread deployment of intelligent transit monitoring frameworks, which is among the key drivers of the automated passenger counting system market. The rapid expansion of global urban centres creates an unprecedented necessity for automated passenger counting solutions to manage overwhelming daily commuter volumes. According to the United Nations Department of Economic and Social Affairs, 55% of the world's population lives in urban areas today, a proportion projected to reach 68% by 2050. This demographic shift connects directly to the automated passenger counting system market by forcing municipal transit agencies to abandon manual data collection methods in favour of automated sensors that provide real-time occupancy metrics for overcrowded buses and trains. Additionally, according to the International Association of Public Transport, public transport networks bring cities to life by providing approximately 60 billion passenger journeys every year in Europe alone. Consequently, relentless urban growth acts as a fundamental catalyst, ensuring continuous technological procurement and steady revenue generation across international smart mobility supply sectors.
Implementation of Government Mandates for Transit Transparency
Strict regulatory frameworks and public funding stipulations are compelling operators to adopt precise ridership auditing tools, which fuels the expansion of the automated passenger counting system market. Governmental bodies worldwide continue to enforce stringent statutory requirements regarding public subsidy allocation and passenger accountability, compelling transit operators to integrate reliable counting architectures. According to the Federal Transit Administration, transit agencies must meet specific National Transit Database data requirements, such as reporting annual unlinked passenger trips and passenger miles travelled, to receive Federal Urbanised Area Formula Program grants. This regulatory requirement relates directly to the automated passenger counting system market by legally obligating transit authorities to replace legacy manual logging with high-accuracy infrared and stereoscopic counting units that satisfy government compliance standards. Furthermore, as per the European Commission Directorate-General for Mobility and Transport, Sustainable Urban Mobility Plans provide a framework for cities to monitor clean, safe, and integrated urban transport systems. As a result, statutory compliance rules accelerate market adoption, ensuring that transit operators invest continuously in certified counting hardware to secure vital operational subsidies and avoid financial penalties.
MARKET RESTRAINTS
High Capital Expenditure and Hardware Integration Costs
Prohibitive upfront procurement expenses and complex retrofitting requirements are restricting rapid adoption among smaller transit agencies, which hamper the growth of the automated passenger counting system market. Deploying cutting-edge optical sensors, time-of-flight cameras, and centralised data processing software across mixed vehicle fleets introduces severe financial hurdles that restrict rapid market penetration, particularly within municipal networks operating on constrained budgets. According to industry data, global municipal infrastructure spending faces widespread constraints, presenting financial challenges for subnational governments and municipal bodies aiming to fund capital infrastructure upgrades. This economic constraint relates directly to the automated passenger counting system market by delaying large-scale fleet modernisation projects, discouraging smaller bus operators from investing in high-end stereoscopic counting arrays. Additionally, as per studies, retrofitting legacy rolling stock with newly integrated digital systems often impacts transport asset maintenance planning due to associated labour demands and installation downtime. Consequently, high upfront capital requirements slow down the widespread adoption of next-generation counting technologies, forcing manufacturers to balance advanced hardware capabilities against strict municipal affordability thresholds.
Data Privacy Concerns and Strict Cybersecurity Vulnerabilities
Intense regulatory scrutiny over biometric data collection and the persistent threat of remote network intrusions hinder the expansion of the automated passenger counting system market. The heavy reliance on advanced optical video analytics and facial contour processing creates profound privacy and security obstacles that impede the seamless deployment of modern passenger monitoring mechanisms. According to sources, strict regulations surrounding public surveillance and biometric data processing impose comprehensive legal compliance requirements on technology vendors deploying public infrastructure. This regulatory friction connects directly to the automated passenger counting system market by triggering public pushback and stringent data protection audits that delay software deployment approvals in privacy-sensitive metropolitan regions. Furthermore, as per research, national efforts to secure critical infrastructure emphasise the rising frequency of digital threat vectors, ransomware, and network vulnerabilities targeting public systems. As a result, structural vulnerabilities in data transmission networks threaten system integrity, forcing industry participants to invest heavily in anonymous data processing algorithms and tamper-proof cryptographic defences.
MARKET OPPORTUNITIES
Expansion of Real-Time Passenger Information Systems
Rising commuter demand for live occupancy tracking is opening lucrative multimodal data integration channels, which are likely to propel the growth of the automated passenger counting system market. The rapid commercialisation of connected smartphone applications and real-time commuter communication platforms creates unprecedented avenues for advanced passenger counting data streams designed to improve urban travel experiences. According to sources, the share of passenger miles travelled in private cars will drop by about 15% points by 2035, while new paradigms like autonomous roboshuttles, public transport, and micro-mobility applications will change commuter choices. This technological transition accelerates the automated passenger counting system market because passenger information displays and mobile apps require live, highly accurate occupancy data feeds generated directly by automated counting sensors to inform waiting travellers of vehicle crowding levels. Furthermore, as per studies, public transit agencies upgrading to live occupancy broadcasting tools report notable positive shifts in commuter feedback and network visibility. Therefore, the expansion of traveller information systems opens lucrative revenue streams for sensor manufacturers capable of bundling real-time counting analytics with passenger display software.
Integration of Artificial Intelligence and Edge Computing
Advanced onboard machine learning processors are enabling hyper-accurate passenger classification and real-time data processing, which are expected to boost the expansion of the automated passenger counting system market. The incorporation of artificial intelligence algorithms and edge computing modules into onboard counting hardware revolutionises the analytical precision and operational reliability of modern public transit systems. According to sources, over two-thirds of enterprises will deploy edge AI by 2029, representing a massive shift from just 10% in 2025 as intelligence moves out of the data centre and into physical sites. This technological leap benefits the automated passenger counting system market by enabling sensors to process complex visual data locally, distinguishing human passengers from bulky luggage, bicycles, and strollers with significant accuracy. Moreover, as per research, edge-processed public transport analytics reduce cellular bandwidth requirements by executing artificial intelligence algorithms directly on the camera sensor to transmit coordinate tracking data rather than streaming raw video. Consequently, artificial intelligence integration empowers forward-thinking hardware manufacturers to capture high-margin contracts by offering intelligent counting solutions that eliminate traditional optical blind spots and algorithmic counting errors.
MARKET CHALLENGES
Vulnerability to Environmental Wear and Vandalism
Harsh onboard physical operating conditions and intentional equipment tampering threaten sensor durability. These challenges restrict the growth of the automated passenger counting system market. The heavy physical stress, thermal variation, and risk of intentional damage present in high-capacity public transport vehicles pose profound operational obstacles for delicate optical counting hardware. According to the American Public Transportation Association, annual maintenance expenses related to interior vehicle vandalism and equipment wear across North American transit fleets exceed hundreds of millions of dollars. This durability challenge relates directly to the automated passenger counting system market by forcing manufacturers to engineer heavily reinforced, impact-resistant sensor housings capable of withstanding constant vibration and physical abuse without compromising calibration. Furthermore, as per studies, deploying optical sensors in unconditioned rolling stock requires robust housing to protect delicate components from ambient dust accumulation and extreme thermal fluctuations. Consequently, physical resilience hurdles require massive capital reallocation toward ruggedised material science and protective casing development, straining the profit margins of specialised component producers.
Interoperability Deficits Across Legacy Transit Fleets
Fragmented software architectures and proprietary communication protocols hinder seamless fleet-wide data unification and ultimately impede the expansion of the automated passenger counting system market. The lack of standardised communication protocols across diverse vehicle generations creates severe integration bottlenecks that impede the centralised management of modern passenger counting deployments. According to sources, mitigating architectural differences between legacy bus networks and modern rail fleets is vital for ensuring seamless hardware and software interoperability. This architectural fragmentation connects directly to the automated passenger counting system market by forcing transit agencies to spend excessive engineering capital on custom middleware converters that bridge older vehicle networks with modern counting modules. Moreover, as per studies, system integration and software calibration represent notable execution phases that shape the overall deployment timeline of a municipal fleet conversion. Therefore, the absence of universal plug-and-play standards introduces immense engineering complexity and recurring configuration costs that hinder smooth market expansion for component suppliers.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 9.40% |
| Segments Covered | By Application, Technology, End-Use, and Region. |
|
Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Iris GmbH, Syncromatics Corp, HELLA Aglaia Mobile Vision GmbH, Eurotech S.p.A, Retail Sensing Ltd, Huawei Technology Co. Ltd, Clever Devices Ltd, Trapeze Group, DILAX Intelcom GmbH, Infidel Electronic Designers International Inc, Cisco Systems, Siemens AG, and Others. |
SEGMENT ANALYSIS
By Application Insights
Railways Segment
The railways segment dominated the automated passenger counting system market and accounted for a substantial share in 2025. This dominance of the segment was driven by the fact that heavy rail and commuter train networks handle massive, concentrated volumes of daily urban commuters requiring stringent occupancy tracking. According to the International Union of Railways, global rail networks carried 3.8 trillion passenger kilometres in 2023, establishing an enormous operational footprint that necessitates automated monitoring to manage platform congestion and timetable safety compliance. This massive transit volume relates directly to the automated passenger counting system market by forcing railway operators to deploy high-capacity counting sensors across extensive multi-car coaches to eliminate manual auditing errors. Additionally, as per the World Bank, infrastructure lending programs support extensive railway modernisation and urban transit projects across more than 20 countries, driving widespread adoption of integrated sensor networks. Consequently, heavy reliance on rail transport for mass urban mobility ensures that railways remain the primary revenue-generating application segment globally.
Airways Segment
The airways segment is estimated to register the fastest CAGR of 10.5% from 2026 to 2034. This rapid expansion of the segment is propelled by modern airports utilising advanced optical and thermal counting devices to monitor queue wait times, optimise passenger boarding bridges, and streamline terminal throughput. According to international aviation authorities, the airways segment experiences accelerated growth due to an intense industry-wide focus on elevating passenger flow efficiency, terminal security, and customised airport experiences. Furthermore, as per the International Air Transport Association, global air passenger demand expands over time to hit historic load factors, forcing airport authorities to invest heavily in real-time tracking analytics to mitigate bottlenecks. Therefore, the critical need for seamless security screening and automated terminal management propels the airways sector forward at the highest growth velocity.
By Technology Insights
Infrared Technology Segment
The infrared technology segment led the automated passenger counting system market and captured a significant share in 2025. This leading position of the segment was attributed to its proven reliability, cost-effectiveness, and low computational overhead during high-frequency boarding cycles. According to international transport technology bodies, infrared sensors provide established architectures for automated passenger counting systems to maintain reliability in varying transit environments. This dominant market positioning relates directly to the automated passenger counting system market by offering municipal fleet operators a dependable, budget-friendly hardware option that integrates easily with legacy vehicle electronics without requiring complex edge computing upgrades. Additionally, as per the Society of Automotive Engineers, specialised sensor guidelines support vehicle intelligence and occupant monitoring within public transit networks to manage passenger data compliance. Consequently, deep industry trust and low maintenance overhead preserve the leading status of infrared technology across traditional public transit networks.
Stereoscopic Vision Segment
The stereoscopic vision segment is the fastest-growing in the automated passenger counting system market, owing to its exceptional depth perception and high-precision analytical capabilities. According to public transit infrastructure guidelines, stereoscopic vision systems use depth perception to differentiate objects in dense environments, assisting operators in managing heavy vehicle passenger counts. This rapid technological adoption connects directly to the automated passenger counting system market by fulfilling the strict accuracy demands of smart city operators who require real-time heat mapping and detailed occupancy metrics. Furthermore, as per the IEEE Intelligent Transportation Systems Society, dense stereovision research offers techniques for real-time passenger flow extraction to localise and count commuters on transit lines. As a result, the superior data granularity provided by depth-sensing cameras drives their accelerated integration across next-generation public transport vehicles.
By End-Use Insights
Buses Segment Dominance
In 2025, the buses segment held the majority share in the automated passenger counting system market because urban bus fleets constitute the largest volume of operational public transit vehicles deployed globally. According to the International Association of Public Transport, global public transportation systems support billions of urban journeys annually, establishing a massive operational foundation for public transit vehicle management and tracking systems. This massive vehicle deployment relates directly to the automated passenger counting system market by creating a continuous, high-volume demand for retrofitted and factory-installed counting sensors designed to optimise fuel consumption and route frequency. Additionally, as per the American Public Transportation Association, forty per cent of industry respondents in transit fleet health assessments indicate that their bus fleets require the most immediate infrastructure investment. Consequently, the sheer ubiquity of urban bus networks secures their permanent dominance over alternative transit end-use categories.
Planes Segment
The planes segment is rapidly expanding in the automated passenger counting system market. This swift growth of the segment is fueled by commercial aviation's rapid digital transformation and strict cabin management requirements. According to the International Civil Aviation Organisation, global air traffic demand is projected to increase between 4.3% and 4.6% annually in revenue passenger kilometres, driving long-term system optimisation and strict safety criteria across the aviation sector. This rapid growth connects directly to the automated passenger counting system market because airline operators and aircraft manufacturers integrate smart optical sensors into modern cabins to monitor boarding efficiency, track seat utilisation, and improve in-flight service delivery. Furthermore, as per the International Air Transport Association, 85% of air passengers utilised automated immigration gates and self-service kiosks during their travel journey, reflecting an increasing preference for technological control over the transit experience. Therefore, the aviation sector's aggressive pursuit of operational automation drives exceptional growth rates across specialised aircraft sensor applications.
REGIONAL ANALYSIS
North America Market Analysis
North America was the top performer in the automated passenger counting system market and accounted for a 33.7% share in 2025. This prominence of the North American market was driven by mature technological infrastructure and early adoption of intelligent transit solutions. According to the Federal Transit Administration, competitive formula funding allocations support widespread mobility and technical innovations to enhance public transportation infrastructure across metropolitan transit agencies. This regional market status relates directly to the automated passenger counting system market by establishing stringent federal data-reporting mandates that compel local transit operators to install certified automated counting architectures. Additionally, as per the American Public Transportation Association, annual fleet database tracking compiles the physical bus and rail characteristics of over one hundred and fifty U.S. and Canadian transit agencies to capture the direction of municipal transit fleets. Consequently, high regional purchasing power and proactive government funding solidify North America as the primary revenue leader in the global landscape.
Europe Market Analysis
Europe is a rapidly expanding region in the automated passenger counting system market. This expansion of the European market was propelled by stringent carbon reduction targets and extensive public transport modernisation programs. According to the European Environment Agency, regional policy updates emphasise that the digitalisation of Europe's mobility systems can optimise transit logistics and support shared, collective transportation methods. This advanced market status connects directly to the automated passenger counting system market by legally obligating municipal transport providers across the European Union to optimise fleet energy efficiency through precise occupancy monitoring. Furthermore, as per studies, passenger cars remain the dominant mode of transport in the European Union, accounting for over seventy per cent of total passenger-kilometres across member states. As a result, strict regulatory compliance and visionary green-city policies ensure steady, high-value procurement cycles throughout European transit networks.
Asia-Pacific Market Analysis
Asia-Pacific holds a significant share in the automated passenger counting system market. This growth of the APAC market is fuelled by unprecedented demand for high-capacity passenger monitoring hardware capable of managing extreme commuter volumes in megacities. According to the United Nations Economic and Social Commission for Asia and the Pacific, several major cities in the region have launched mass transit projects, such as suburban metro and bus rapid transit lines, to reduce severe urban traffic congestion. Additionally, as per sources, global smart city frameworks utilise data generated from billions of connected Internet of Things devices to optimise public resources and enhance municipal services. Consequently, relentless urbanisation and large-scale public transportation construction make Asia-Pacific the most dynamic growth frontier for industry vendors.
Latin America Market Analysis
Latin America is a rising player in the automated passenger counting system market. Municipal transport digitisation and expanding bus rapid transit networks serve as the core factors of this growth. According to the Economic Commission for Latin America and the Caribbean, mass transit systems have expanded in recent years across several countries, but major urban gaps persist regarding travel accessibility, physical security, and overall network times. This transitional market status connects directly to the automated passenger counting system market by encouraging municipal authorities in key metropolitan hubs to adopt automated counting tools to prevent fare evasion and optimise fleet scheduling. Furthermore, as per research, national urban transport programs combine city allocations, fuel surcharges, and developmental loans to finance dedicated bus rapid transit corridors and associated fare collection assets. Therefore, the modernisation of urban bus networks across nations like Brazil and Mexico creates a steady pipeline of emerging commercial opportunities for sensor manufacturers.
Middle East and Africa Market Analysis
The Middle East and Africa region is an emerging region in the automated passenger counting system market, propelled by ambitious smart city megaprojects and heavy investments in modern rail networks. According to sources, nations within the Gulf Cooperation Council emphasise public investment in transport infrastructure, including road construction and regional transit frameworks. This emerging market status relates directly to the automated passenger counting system market by driving the installation of cutting-edge optical and infrared counting sensors in newly constructed metro systems and premium airport terminals. Additionally, as per studies, mobile broadband networks have expanded globally to put over 95% of regional populations within range of high-speed mobile signals. Consequently, strategic infrastructure investments in smart mobility hubs establish a strong foundation for long-term market expansion across the region.
COMPETITIVE LANDSCAPE
Competition within the global automated passenger counting system market remains intensely fierce, characterized by continuous technological innovation among established multinational hardware and software engineering firms. Industry incumbents constantly vie for dominance by racing to commercialize advanced stereoscopic and infrared counters that satisfy tightening municipal efficiency and regulatory reporting standards. While legacy technology providers leverage their deep-rooted vehicle integration experience and vast engineering reserves to scale global operations, agile regional competitors frequently introduce cost-effective sensor alternatives that challenge traditional market hierarchies. Price pressure remains a persistent competitive hurdle, forcing system suppliers to balance expensive research inputs and rigorous automotive compliance standards against the tight budgetary constraints of public transit agencies. Strategic consolidation, cross-border software acquisitions, and intensive collaborative ventures with urban mobility developers further define the competitive battlefield as firms strive to secure exclusive access to next-generation data analytics assets. Ultimately, long-term market survival demands continuous product refinement, stringent hardware durability, and the ability to adapt counting algorithms to fast-changing public transit environments.
KEY MARKET PLAYERS
Some of the market players dominate the automated passenger counting system market.
- Iris GmbH
- Syncromatics Corp
- HELLA Aglaia Mobile Vision GmbH
- Eurotech S.p.A
- Retail Sensing Ltd
- Huawei Technology Co. Ltd
- Clever Devices Ltd
- Trapeze Group
- DILAX Intelcom GmbH
- Infidel Electronic Designers International Inc
- Cisco Systems
- Siemens AG
Leading Market Contributors
- Eurotech SpA functions as a primary technology provider within the automated passenger counting system market by engineering high-performance embedded computers and certified vehicular data gateways. The company contributes significantly by supplying ruggedized processing hardware that aggregates real-time optical sensor inputs and transmits reliable passenger telemetry to municipal transit operators. To fortify its competitive standing, the organization directs substantial financial resources toward edge artificial intelligence computing and secure internet of things device management platforms. Furthermore, strategic technological collaborations allow Eurotech SpA to bundle its processing hardware directly with advanced passenger counting software ecosystems, cementing its reputation as a core enabler of smart public transportation networks.
- Iris GmbH shapes the global transit landscape by specializing in the continuous design and manufacturing of advanced infrared and time-of-flight passenger counting sensors. The company contributes extensively to international transit optimization by delivering highly accurate boarding metrics that replace traditional manual auditing methods for municipal bus and rail operators. To strengthen its position as an industry pioneer, Iris GmbH heavily invests in sophisticated object recognition algorithms and robust sensor hardware capable of operating reliably in harsh vehicle environments. Recent corporate actions involve expanding international production capacity and launching next-generation sensor iterations featuring enhanced data privacy safeguards designed to comply with strict regional regulatory frameworks.
- Dilax Intelcom GmbH delivers exceptional value to the smart mobility sector by offering comprehensive passenger counting hardware alongside intelligent data analytics software platforms. The company contributes profoundly to urban passenger flow management by transforming raw sensor logs into actionable mobility insights for large-scale transit networks. Strengthening its market presence, Dilax Intelcom GmbH continuously refines its proprietary business intelligence tools to support complex multimodal public transportation scheduling. Strategic maneuvers emphasize the development of cloud-connected data processing solutions and targeted regional service partnerships designed to streamline system deployment for expanding metropolitan transit authorities navigating modern urbanization demands.
Top Strategies Used By Key Market Participants
Key participants operating within the automated passenger counting system market deploy aggressive technological integration strategies to maintain competitive dominance amid rapid municipal modernization. Leading hardware and software developers prioritize heavy capital investments in research and development to engineer artificial intelligence powered optical sensors and edge computing modules that maximize counting accuracy. Furthermore, major industry players aggressively forge strategic distribution agreements with vehicle manufacturers and regional transit integrators to secure long-term supply contracts across expanding public transport fleets. Companies also utilize active portfolio diversification by introducing multi-technology sensor arrays combining stereoscopic vision and time-of-flight capabilities to capture specialized niche requirements. Regional localization serves as another prominent tactic, allowing top-tier corporations to mitigate complex supply chain vulnerabilities and optimize operational cost structures across developing international markets. Additionally, proactive cloud platform integration focusing on real-time data accessibility helps market leaders differentiate their offerings in an increasingly competitive landscape.
MARKET SEGMENTATION
This research report on the global passenger counting system market is segmented and sub-segmented into the following categories.
By Application
- Roadways
- Railways
- Airways
By Technology
- Stereoscopic Vision
- Infrared
- Time-of-Flight
- IP cameras
By End-Use
- Busses
- Trains
- Planes
- Ferries
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East and Africa