- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$17.12 BnMarket Estimate, 2026
$20.82 BnMarket Forecast, 2034
$99.52 BnCAGR, 2026–2034
21.60%Executive Summary: Global Automotive RADAR Market
- Market Scope: Comprehensive global automotive radar market analysis mapping application domains, frequency spectrums, vehicle classifications, regional manufacturing hubs, and advanced driver-assistance systems (ADAS) frameworks.
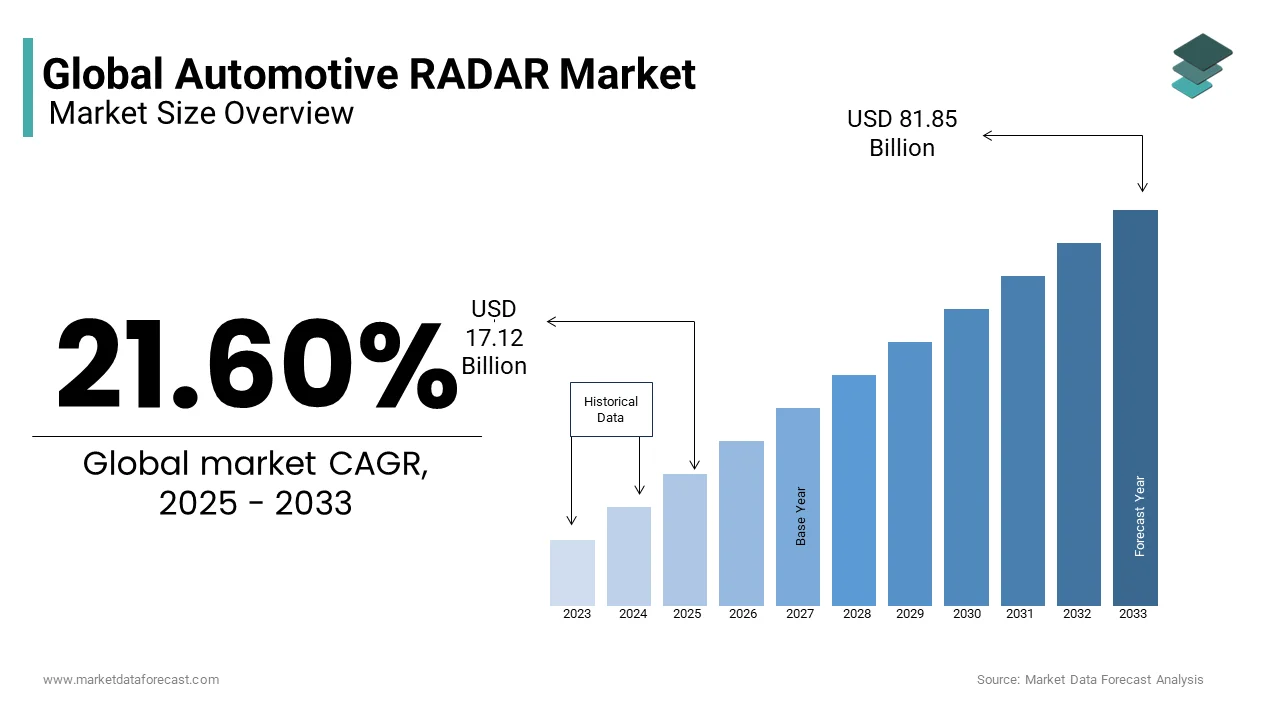
- Market Valuation: Valued at USD 17.12 billion in 2025, estimated at USD 20.82 billion in 2026, and projected to reach USD 99.52 billion by 2034, registering a CAGR of 21.60% from 2026 to 2034.
- Primary Growth Drivers: Escalating safety concerns while driving, automotive industry shifts toward autonomous and semi-autonomous vehicles, strict government safety mandates for automated emergency braking, and falling costs for vehicle electronics and semiconductor components. Primary constraints include the legal status and illicit aftermarket misuse of radar detectors in select regions.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Application | Adaptive Cruise Control (ACC) (highest market share due to extensive adoption across major markets like the U.S., Germany, and China) | Autonomous Emergency Braking (AEB) and Forward Collision Warning systems |
| By Frequency Type | 7X-GHz Systems (dominant category leveraging superior resolution and range capabilities for high-end ADAS) | Advanced multi-mode 77 GHz/79 GHz long-range sensor networks |
| By Vehicle Type | Passenger Vehicles (commanding greater market volume driven by safety awareness among mid-priced and luxury vehicle buyers) | Commercial Vehicles (triggered by logistics expansion, e-commerce fleet safety, and vehicle autonomy expectations) |
| By Region | Europe & North America (anchored by rigorous EU safety regulations and high R&D investments by German automakers) | Asia-Pacific (APAC) (fastest-growing due to rising income levels, premium vehicle demand, and expanding production in China and India) |
Major Market Players & Market Structure
Market Structure: Highly competitive global ecosystem comprising automotive Tier-1 suppliers and semiconductor giants collaborating through strategic partnerships and advanced radar system-on-chip (SoC) developments.
Key Companies: Robert Bosch GmbH, HELLA KGaA, Continental AG, Denso Corporation, Delphi Automotive PLC (Aptiv), Autoliv Inc., Valeo S.A., Infineon Technologies AG, and NXP Semiconductors N.V.
Global Automotive RADAR Market Size
The global automotive radar market size was valued at USD 17.12 billion in 2025 and is anticipated to reach USD 20.82 billion in 2026 to reach USD 99.52 billion by 2034, growing at a CAGR of 21.60% during the forecast period from 2026 to 2034.
Automotive radar includes a transmitter that sends the radio waves that connect an object to the receiver and therefore, the receiver operates the movement or the direction of the vehicle. The global automotive radar market is predicted to grow during the foreseen phase because the growing concern regarding security issues while driving the car will help to raise the market. Automakers are also shifting their focus from manual cars to autonomous cars, which will successively increase the automotive radar market.
Stringent government-favorable initiatives within the field of radar systems have adversities in the event of auto safety systems and are predicted to drive the widespread adaption of radar-based security systems over the foreseen phase. Moreover, the decline in the prices of vehicle electronics and developments in automotive engineering is determined to fuel the use of automotive radars. Its installation enables the exact detection of objects and secures better vehicle safety.
The main restraint for this market is the use of the RADAR detector, which is taken into account as illegal in certain countries. A RADAR sensor is often installed in an automobile during its production period, and these automobiles are often offered for a purchase that is acceptable in most countries, but if a RADAR detector is purchased separately by an individual, it is often misused and should result into accidents and loss of life. However, it's illegal in certain countries, and violation of an equivalent ends in fines, seizure of the device, or both.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 21.60% |
| Segments Covered | By Application, Frequency Type, Vehicle Type, and Region. |
| Various Analyses Covered | Global, Regional and Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Robert Bosch GmbH (Germany), HELLA KGaA (Germany), Continental AG (Germany), Denso Corporation (Japan), Delphi Automotive PLC (U.K.), Autoliv Inc. (Sweden), and Valeo S.A. (France), Infineon Technologies AG (Germany), NXP Semiconductors N.V, and Others. |
SEGMENT ANALYSIS
By Application Insights
The market share for ACC was the highest in 2024 due to the widespread adoption in prominent automotive markets, like the U.S., Germany, and China, among others. Additionally, the AEB segment is predicted to grow as one with the fastest CAGRs over the foreseen phase. Government initiatives, like the delicensing of radar frequencies and raised investment by automakers for the event of low-cost radar-based safety systems, are projected to boost growth over the foreseen phase.

By Frequency Insights
The RADAR of 7 X-GHz sensors is projected to steer the worldwide automotive radar market during the foreseen phase. The interest in the 7X-GHz segment is often attributed to the advantages offered by these sensors in various ADAS applications. 7X-GHz RADAR sensors are utilized in adaptive control, emergency braking systems, and collision avoidance systems, among others. The marketplace for these technologies is on the rise due to their better resolution and range capability.
2X-GHz frequency bands are mostly used for small-range software. It is available at a lower cost without any settlement in the high-end features.
By Vehicle Insights
The passenger Vehicle segment is predicted to grow at a faster rate than the commercial vehicles segment. The foremost factor driving the growth of this segment is the rising awareness regarding vehicle safety among mid-priced vehicle owners. Consistent with OICA, globally, the passenger vehicles segment witnessed a rise of 4.5% in 2016 compared to 2015. As passenger vehicles are steadily adopting the radar-based safety system, the global automotive radar market is projected to gain traction over the forecast period.
However, the increasing logistics industry and hiking e-commerce have targeted sales for commercial vehicles. The increasing consumer expectations for vehicle autonomy among commercial vehicles are additionally supposed to trigger the expansion of the segment.
REGIONAL ANALYSIS
North America Market Analysis
North America is showing substantial growth and is likely to continue this trend over the foreseen phase. Europe accounted for a notable part of the worldwide market in terms of value and is predicted to grow at a CAGR of 17.8% over the foreseen phase. This will be attributed to the EU Commission's rising stringency of auto safety norms. German automakers hold up to 70% of the premium vehicle production. However, the nation's automotive industry spends approximately 33% of its revenue on R&D development. Thus, the German automotive radar market is foreseen to record the most crucial share by 2025.
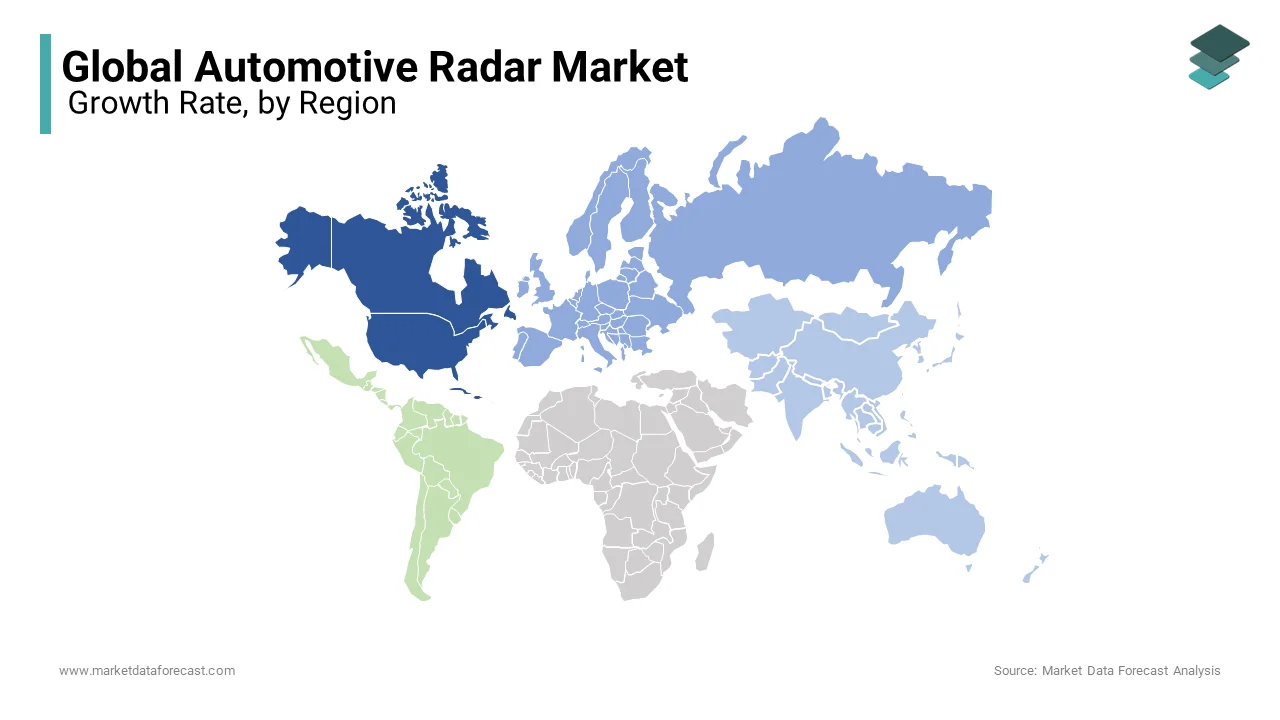
Compared to other regions, Asia-Pacific (APAC) is predicted to witness the fastest growth within the global automotive radar market over the foreseen phase. It's mainly because of the rising income in the developing countries of the APAC region, like India and China, which results in an increasing demand for premium vehicles.
KEY MARKET PLAYERS
Major players in the global market are
- Robert Bosch GmbH (Germany)
- HELLA KGaA (Germany)
- Continental AG (Germany)
- Denso Corporation (Japan)
- Delphi Automotive PLC (U.K.)
- Autoliv Inc. (Sweden)
- Valeo S.A. (France)
- Infineon Technologies AG (Germany)
- NXP Semiconductors N.V.
RECENT MARKET NEWS
- Bosch has introduced a replacement long-range radar sensor. Like its predecessors, it uses the 77-gigahertz frequency bandwidth. It's also additionally even more powerful, compact, and more cost-effective than its direct predecessor.
- This new (third-generation Long Range Radar) automotive radar sensor system from Robert Bosch GmbH will apply a chip from Infineon Technologies’ (Radar System IC) product family. Bosch introduced the LRR3 for adaptive controllers at ranges up to 250 m.
- Oculii and HELLA introduced a tactical Partnership to showcase the Radar Perception Platform That Scales from ADAS to Autonomous Driving – HELLA Ventures Becomes Investor. Oculii’s particular Virtual Space Imaging Application Technology fundamentally expands the angular resolution of a radar-phased array, significantly improving the security, reliability, and efficiency of autonomous vehicles.
MARKET SEGMENTATION
This market research report on the global automotive RADAR market is segmented and sub-segmented into the following categories.
By Application
- Adaptive Cruise Control (ACC)
- Autonomous Emergency Braking (AEB)
- Blind Spot Detection (BSD)
- Forward Collision Warning System
- Intelligent Park Assist
- ADAS Applications
By Frequency Type
- 2X-GHZ Systems
- 7X-GHZ Systems
By Vehicle Type
- Commercial Vehicles
- Economic Passenger Vehicle
- Luxury Passenger Vehicle
- Mid-Price Passenger Vehicle
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa