- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$25.67 BnMarket Estimate, 2026
$26.83 BnMarket Forecast, 2034
$38.15 BnCAGR, 2026–2034
4.50%Executive Summary: Global Automotive Shielding Market
- Market Scope: Comprehensive global automotive shielding market analysis covering shielding types, heat application zones, vehicle categories, regional leadership frameworks, and thermal/EMI management metrics.
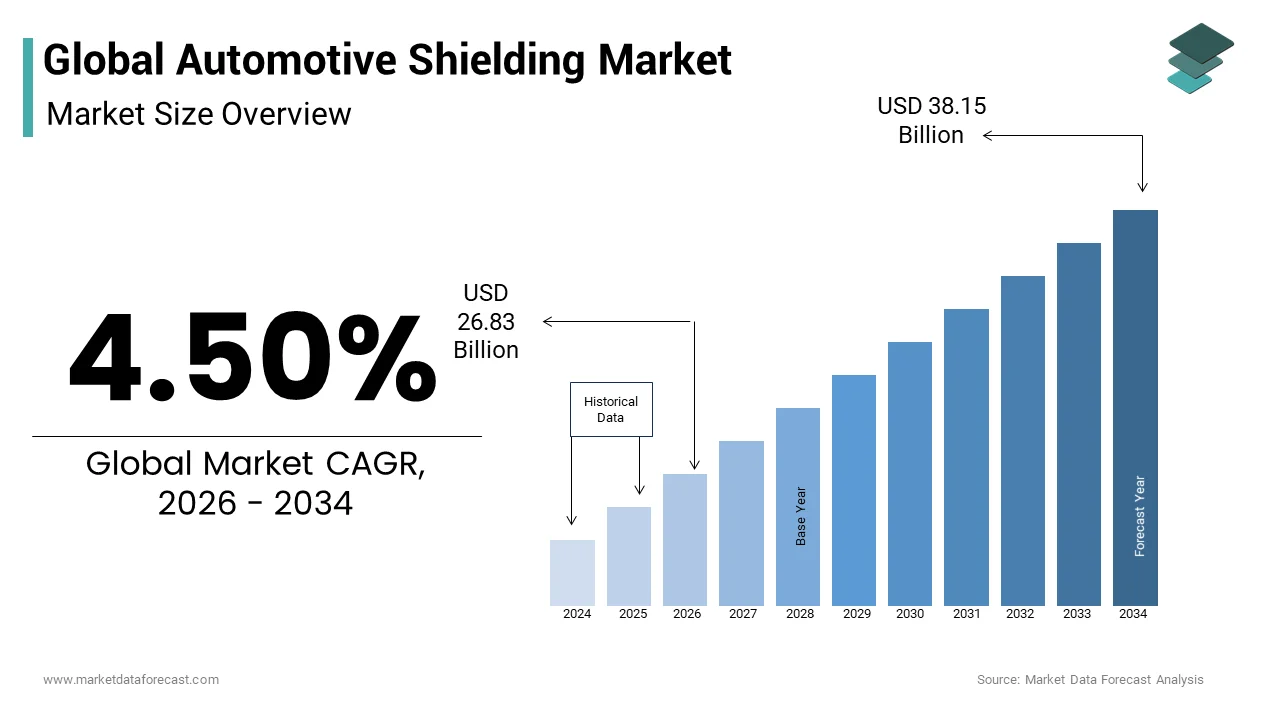
- Market Valuation: Valued at USD 25.67 billion (2025), estimated at USD 26.83 billion (2026), and projected to reach USD 38.15 billion by 2034, registering a CAGR of 4.50% (2026–2034).
- Primary Growth Drivers: Surging integration of advanced electronic systems and infotainment in modern vehicles, rising popularity of lightweight and fuel-efficient cars, strict government environmental regulations forcing engine downsizing and turbocharging, and the proliferation of electric and hybrid vehicles requiring robust electromagnetic interference (EMI) shielding. Restraints include high maintenance costs, potential shield degradation under harsh environmental conditions, and the added overall vehicle weight and expense.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Shielding Type | Heat shielding (dominates due to critical requirements in exhaust, undercarriage, and internal combustion engine compartments) | Electromagnetic Interference (EMI) shielding driven by EV adoption and dense electronic circuitry |
| By Heat Application | Turbocharger and engine compartments (lead in protecting components, boosting power, and lowering under-hood temperatures) | Fuel tank and battery management shielding for hybrid/electric platforms |
| By Vehicle Type | Passenger cars (occupy the largest share driven by rising urbanization, living standards, and strict emission regulations) | Commercial and connected mobility vehicles featuring advanced V2I/V2V communication architectures |
| By Region | Asia-Pacific (dominates globally due to rapid automotive industry expansion in China and India, plus smart transport projects in Japan) | Europe (steady growth backed by stringent emission mandates and strict safety feature requirements) |
Major Market Players & Market Structure
Market Structure: Highly competitive global automotive component landscape featuring specialized thermal insulation firms and material science corporations competing on weight reduction, packaging efficiency, high-temperature resistance, and collaborative lightweight composite innovations.
Key Companies: Federal-Mogul, Laird PLC, Morgan Advanced Materials, Dana Incorporated, Henkel AG & Company, The 3M Company, Kitagawa Iron Works Co. Ltd., Tech-Etch Inc., and Marian Inc.
Global Automotive Shielding Market Size
The global automotive shielding market size was valued at USD 25.67 billion in 2025 and is anticipated to reach a valuation of USD 26.83 billion in 2026 and USD 38.15 billion by 2034, growing at a CAGR of 4.50%, from 2026 to 2034.
Introduction to the Automotive Shielding Market
Automotive shielding is the use of specialized physical barriers and insulating layers in vehicles to protect sensitive parts, electronic systems, and the vehicle body from extreme heat and electromagnetic interference. As modern vehicles integrate increasingly complex electronic architectures, the necessity for robust shielding solutions becomes paramount to ensure operational reliability and passenger comfort. As per the International Electrotechnical Commission, the adoption of harmonized electromagnetic compatibility validation procedures is expanding across connected vehicle platforms to manage complex multi-frequency radiated emissions and immunity pre-certification engineering. Also, as per the Society of Automotive Engineers, global automotive electromagnetic compatibility standards dictate strict emission and immunity limits under frameworks like SAE J551 and SAE J1113 to protect vehicle networks from radio disturbances. These points prove that shielding keeps electric cars safe and performing at their best. The proliferation of autonomous driving technologies further amplifies demand as lidar, radar, and camera systems require pristine signal environments to function accurately. Shielding materials such as aluminum foils, conductive polymers, and metallic meshes serve as barriers against external interference while containing internal emissions. Regulatory bodies globally mandate strict electromagnetic compatibility standards, forcing manufacturers to adopt comprehensive shielding strategies. This regulatory landscape, combined with technological complexity, drives continuous innovation in lightweight and high efficiency shielding solutions tailored for next-generation mobility platforms.
MARKET DRIVERS
Proliferation of Electric Vehicle Powertrains
The rapid adoption of electric vehicles directly accelerates the growth of the automotive shielding market. This is due to the intense electromagnetic fields generated by high-voltage battery packs and inverters. Apart from these, as per the International Energy Agency, global electric car sales accelerated rapidly to reach approximately 14 million units, demonstrating robust sustained year-on-year growth across key automotive markets. Each electric vehicle utilizes high power traction motors and charging systems that emit broad spectrum electromagnetic interference capable of disrupting nearby electronic components if left unshielded. According to the Institute of Electrical and Electronics Engineers, specialized traction inverters and power conversion topologies are increasingly integrated to manage thermal stress and mitigate high-voltage electromagnetic interference inside modern electric powertrains. The technical requirement establishes a direct correlation between electric vehicle production volumes and shielding material consumption. Manufacturers must integrate shielding into battery enclosures, motor housings and cable assemblies to meet international electromagnetic compatibility standards. Failure to adequately shield these components can lead to system malfunctions, reduced range and safety hazards. Consequently, original equipment manufacturers prioritise advanced shielding solutions that offer high attenuation performance while minimizing weight penalties. The transition away from internal combustion engines is a primary factor behind the market expansion. This is because every new electric platform introduces unique shielding challenges that demand innovative material science approaches.
Integration of Advanced Driver Assistance Systems
The widespread implementation of advanced driver assistance systems creates substantial demand for precision shielding to protect sensitive sensors from electromagnetic interference, which, in turn, contributes to the automotive shielding market expansion. Moreover, according to the National Highway Traffic Safety Administration, a new federal motor vehicle safety standard mandates that manufacturers install automatic emergency braking and advanced pedestrian safety technologies on all new light vehicles. These sensors operate at high frequencies and are highly susceptible to external electromagnetic noise, which can cause false readings or system failures with potentially catastrophic consequences. According to the Society of Automotive Engineers, conditional automation frameworks define strict operational safety boundaries where the human driver must remain prepared to intervene upon a system request. The operational necessity drives the adoption of high performance shielding materials around sensor housings and processing units to ensure signal integrity. Automotive manufacturers invest heavily in testing and validation protocols to verify shielding effectiveness under various real-world conditions. The complexity of sensor fusion algorithms further increases the need for clean electromagnetic environments to prevent data corruption. As per the International Energy Agency, the mass deployment of electric vehicle platforms drives significant changes in automotive supply chains, accelerating global component demand for high-density electronic modules and battery management infrastructure. This technological trajectory ensures sustained growth in the shielding sector as safety and reliability remain non negotiable priorities for consumers and regulators alike.
MARKET RESTRAINTS
Weight Constraints and Fuel Efficiency Regulations
Strict fuel efficiency and emissions regulations impose severe weight constraints that hamper the automotive shielding market growth. These constraints limit the use of traditional heavy metal shielding materials in automotive applications. Moreover, as per the U.S. Environmental Protection Agency, a rule setting new multi-pollutant standards for light-duty vehicles sold from 2027 through 2032 is projected to reduce fleet greenhouse gas emissions by about 11% per year. Traditional shielding materials such as steel and thick aluminum sheets add significant weight to vehicle structures thereby conflicting with lightweighting objectives essential for meeting regulatory targets. According to studies, adding 100 kilograms of mass to an electric vehicle reduces its operational energy efficiency by 0.15 to 0.25 kilometers per kilowatt-hour. The technical contradiction forces engineers to seek alternative lightweight materials such as conductive plastics and thin film coatings, which often come with higher costs and complex manufacturing requirements. The development of these advanced materials requires extensive research and validation, slowing down adoption rates compared to conventional solutions. Manufacturers face difficult trade-offs between electromagnetic compatibility compliance and overall vehicle efficiency metrics. Inadequate shielding can lead to regulatory non compliance while excessive weight impacts performance ratings and consumer appeal. This balancing act restricts market growth by limiting the addressable volume of traditional shielding products and demanding continuous innovation in material science that many suppliers struggle to deliver at scale.
High Costs of Advanced Shielding Materials
The elevated cost of advanced shielding materials is a major barrier to widespread adoption, particularly in cost-sensitive vehicle segments within the automotive shielding market. According to the American Chemistry Council, overall speciality chemical manufacturing output contracted by 3.2% amid prolonged demand stagnation across key industrial end-use markets. The cost increase directly impacts vehicle bill of materials, forcing original equipment manufacturers to scrutinise shielding expenditures more closely during design phases. As per the Society of Motor Manufacturers and Traders, automotive manufacturers face intensifying profitability challenges from loss-making retail discounts and rising compliance costs under zero-emission vehicle mandates. Such substitutions may compromise electromagnetic compatibility performance, leading to potential field failures and warranty claims. Small and medium-sized suppliers struggle to absorb these cost pressures, resulting in market consolidation where only large players with economies of scale survive. The high initial investment required for developing and testing new shielding solutions further discourages innovation among smaller firms. Automakers facing margin compression may delay adoption of next-generation shielding technologies, opting instead for proven but less efficient legacy solutions. This financial dynamic restrains market expansion by limiting the penetration of high-performance materials and slowing the transition toward optimised lightweight shielding architectures across the global vehicle fleet.
MARKET OPPORTUNITIES
Development of Lightweight Conductive Composites
The emergence of lightweight conductive composites opens new pathways for the growth of the automotive shielding market. This development addresses both electromagnetic compatibility and weight reduction needs. In addition, as per the American Chemistry Council, using carbon fiber reinforced polymer composites for mixed-material vehicle designs could reduce the weight of specific automotive components by 50% to 75%. This weight savings directly contributes to improved fuel efficiency and extended electric vehicle range, aligning with global regulatory trends and consumer preferences. According to the American Chemistry Council, thermoplastic polyolefins represent approximately 60% of commercially available engineering thermoplastics utilised across modern industrial operations. The materials allow for complex geometries and integrated designs that simplify assembly processes and reduce part counts. Automotive manufacturers are increasingly exploring these composites for battery enclosures, sensor housings, and cable shielding applications where weight savings are critical. The ability to mold these materials into intricate shapes enables designers to optimize space utilization within compact vehicle architectures. As production volumes increase, manufacturing costs for these advanced composites are expected to decline, making them viable for broader market segments. This technological evolution opens new revenue streams for material suppliers who can offer tailored solutions that meet stringent performance and weight criteria. The shift toward composite shielding represents a transformative opportunity to redefine industry standards and capture value in a rapidly evolving automotive landscape.
Expansion of 5G Connectivity and V2X Communication
The rollout of 5G connectivity and vehicle-to-everything communication systems create new opportunities for specialized shielding solutions to manage high-frequency electromagnetic interference, which is anticipated to boost the growth of the automotive shielding market. Besides.As per the Global System for Mobile Communications Association, collaborative cellular technology strategies prioritize optimized millimeter-wave radio spectrum usage alongside next-generation network architecture to deliver reliable automated services. This frequency range is significantly higher than previous generations, necessitating new material formulations and design approaches to handle millimetre-wave propagation characteristics. According to the Institute of Electrical and Electronics Engineers, the IEEE 802.3bw standard establishes physical layer specifications for 100 Mbps bidirectional communication over unshielded twisted-pair cabling to restrict emissions within automotive networks. Shielding solutions must therefore provide superior isolation for antennas, modems and processing units to maintain communication integrity. Automotive manufacturers are integrating dedicated shielding layers into roof modules, bumpers and interior panels to support these advanced connectivity features. The growing emphasis on smart city infrastructure and connected mobility services further amplifies demand for robust shielding architectures. Suppliers who develop specialized materials for 5G applications can command premium pricing and establish long term partnerships with technology focused automakers. This technological shift transforms shielding from a passive protective measure into an active enabler of next-generation mobility services, offering substantial growth potential for innovators in the field.
MARKET CHALLENGES
Complexity of Electromagnetic Compatibility Testing
The increasing complexity of electromagnetic compatibility testing procedures remains a serious impediment for manufacturers in the automotive shielding market. It is equally challenging for vehicle integrators. As per the International Organization for Standardization, the deployment of global automotive safety regulations establishes rigorous testing rules for high-voltage battery enclosures, increasing structural evaluation demands across vehicle engineering departments. These enhanced requirements demand sophisticated testing facilities and specialised expertise that many suppliers lack, leading to bottlenecks in product development cycles. Moreover, as per the Society of Automotive Engineers, global harmonisation efforts for heavy-duty vehicle validation rules are encountering critical friction due to divergent technical criteria between North American, European, and Asian transport testing frameworks. Inconsistent interpretation of standards across different testing laboratories further complicates the validation process, creating uncertainty for manufacturers. Shielding solutions that pass initial tests may fail under real-world conditions due to unforeseen interactions with other vehicle systems or external infrastructure. This unpredictability forces companies to engage in iterative redesigns and retesting, inflating development budgets. The lack of harmonised global standards means that shielding designs must be customised for different markets, reducing economies of scale. Manufacturers struggle to balance thorough validation with aggressive launch schedules, leading to potential quality issues post-launch. This testing burden challenges the market by raising barriers to entry and slowing the adoption of innovative shielding technologies that require extensive verification before commercial deployment.
Supply Chain Volatility for Raw Materials
Persistent volatility in the supply of critical raw materials, such as copper, aluminium, and rare earth elements, disrupts the stability of the automotive shielding market. According to the United States Geological Survey, the domestic building wire sector alone consumes 20% of the total U.S. copper supply, exposing infrastructure manufacturing directly to highly volatile raw material pricing cycles. The price swing directly impacts the cost structure of shielding manufacturers, who rely on stable input prices to maintain competitive bidding for automotive contracts. Besides, as per the International Aluminum Institute, primary aluminum manufacturers face escalating market friction as global carbon accounting initiatives squeeze the operational profitability of traditional smelters. Such disruptions force shielding suppliers to either absorb margin erosion or pass costs to automakers, risking contract losses in a highly competitive environment. Long lead times for specialised materials exacerbate the problem, making just-in-time inventory management difficult and increasing working capital requirements. Automakers demand fixed pricing agreements that suppliers cannot honor amidst volatile commodity markets, leading to contractual disputes and relationship strain. The reliance on single source suppliers for niche materials further increases vulnerability to disruptions. Diversifying supply chains requires significant investment and qualification time, leaving manufacturers exposed in the interim. This supply chain fragility challenges the market by introducing financial uncertainty and operational risks that hinder long-term planning and investment in capacity expansion.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 4.50% |
| Segments Covered | By Shielding, Heat Application, Vehicle Type, and Region. |
|
Various Analyses Covered | Global, Regional, and Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Federal-Mogul, Laird PLC, Morgan Advanced Materials, Ag, Dana Incorporated, Henkel AG & Company, The 3M Company, Kitagawa Iron Works Co. Ltd., Tech-Etch Inc., Marian Inc., and Others. |
SEGMENTAL ANALYSIS
By Shielding Insights
Electromagnetic Interference Shielding
In 2025, the electromagnetic interference shielding segment held the majority share of the automotive shielding market because of the exponential increase in electronic content within modern vehicles. Moreover, as per the Institute of Electrical and Electronics Engineers, the proliferation of advanced driver-assist architectures drives a clear industrial transition toward high-speed automotive Ethernet networking to process massive in-vehicle sensor data streams. The high density of electronics creates a non-negotiable demand for EMI shielding materials such as conductive foils, metal meshes and coated plastics across every vehicle subsystem. According to the Society of Automotive Engineers, automotive radar modules utilizing the 76 to 81 gigahertz spectrum encounter stricter international standardization mandates to ensure absolute operational frequency consistency across active traffic zones. It directly correlates with market dominance, as each additional sensor or communication module requires dedicated shielding protection. Regulatory bodies globally enforce strict electromagnetic compatibility standards that mandate rigorous testing and certification of all electronic components before vehicle approval. Failure to meet these standards results in costly recalls and brand damage, forcing manufacturers to prioritise high-quality EMI shielding. The transition toward software-defined vehicles further amplifies this need, as over-the-air updates and continuous data transmission rely on pristine signal environments. Consequently, EMI shielding remains the foundational layer of vehicle electronic architecture, ensuring reliability and compliance in an increasingly connected automotive landscape.
Stringent global regulations governing electromagnetic compatibility drive the sustained dominance of EMI shielding by making it a legal requirement rather than an optional feature. The United Nations Economic Commission for Europe enforces Regulation No 10, which mandates that all vehicles sold in member states must demonstrate immunity to external electromagnetic disturbances and limit their own emissions to specified thresholds. Compliance with this regulation requires extensive use of shielding materials around sensitive electronics such as engine control units, infotainment systems, and safety sensors. Besides, as per the National Highway Traffic Safety Administration, a newly implemented federal safety mandate requires the uniform deployment of electronic automatic emergency braking systems across all light-duty consumer fleets. The regulatory frameworks create a baseline demand for EMI shielding that scales directly with vehicle production volumes regardless of economic cycles. Manufacturers cannot bypass these requirements without facing market exclusion or severe penalties. The complexity of meeting multiple regional standards simultaneously forces automakers to adopt robust shielding strategies that exceed minimum requirements to ensure global homologation. This regulatory pressure ensures that EMI shielding remains a critical component in vehicle design, driving consistent investment in advanced materials and testing protocols to maintain compliance and consumer trust.
Heat Shielding
The heat shielding segment is anticipated to witness the fastest CAGR of 6.2% during the forecast period owing to the thermal management challenges posed by electric vehicle batteries and high performance powertrains. Besides, as per the International Energy Agency, the global manufacturing sector is aggressively expanding its supply chain infrastructure to meet surging gigawatt-hour requirements for vehicle electrification platforms. The temperature sensitivity necessitates the integration of advanced heat shielding materials such as aerogels, ceramic fibers and reflective foils around battery modules and power electronics. According to the Society of Automotive Engineers, heavy-duty commercial vehicle research focuses on mitigating immediate collision fires through rigid material design standards governing protective under-chassis structural steel barriers. These safety imperatives drive rapid adoption of high performance thermal barriers that can withstand extreme conditions while maintaining lightweight properties. As electric vehicle production scales globally, the demand for specialised heat shielding solutions grows proportionally outpacing traditional applications. Manufacturers are investing heavily in developing multifunctional materials that provide both thermal insulation and structural support to optimise space utilisation. This technological evolution positions heat shielding as a key enabler of electric vehicle safety and performance, fueling its accelerated growth trajectory in the automotive sector.
The critical need for precise thermal management in electric vehicle battery systems is propelling the expansion of this market segment. As per the United States Department of Energy, the integration of advanced active cooling plates inside lithium-ion assemblies is expanding to minimise thermal degradation and optimise everyday fleet operational safety. Achieving this precision requires advanced heat shielding materials that isolate individual cells from thermal spikes while facilitating efficient heat dissipation to cooling systems. According to the United States Department of Energy, solid-state electrolyte development programs prioritize resolving severe material interface resistance to unlock high-rate electrical charging capabilities in consumer vehicle cells. These technical requirements drive innovation in heat shielding materials that offer superior thermal resistance and mechanical durability under varying operational conditions. Automakers are increasingly integrating heat shielding into battery pack designs to meet warranty obligations and performance guarantees promised to consumers. The shift toward ultra-fast charging infrastructure further intensifies thermal loads on battery systems, creating urgent demand for materials that can handle transient heat spikes without compromising integrity. This convergence of performance, safety and longevity requirements establishes heat shielding as an indispensable component in electric vehicle architecture, driving sustained growth and investment in this segment.
By Application Insights
Engine Shielding
The engine shielding segment remained the largest in 2025 and occupied a commanding share of the automotive shielding market. This supremacy of the segment was credited to the enduring prevalence of internal combustion engines in the global vehicle fleet and the intense thermal loads they generated. In addition, as per the International Organization of Motor Vehicle Manufacturers, global automotive manufacturing factories accelerated production outputs to exceed 96 million total units annually, driven by expansion across major Asian regional hubs. Modern downsized turbocharged engines operate at higher temperatures and pressures to meet efficiency standards, generating significant heat that must be managed to protect surrounding components and ensure passenger comfort. According to the Society of Automotive Engineers, modern powertrain engineering initiatives enforce standardized testing methodologies for determining component thermal stability limits across light-duty platforms. These extreme conditions drive continuous demand for high-temperature-resistant materials such as aluminised steel, ceramics and composite wraps. Regulatory emissions standards also require precise thermal management to ensure catalytic converters reach optimal operating temperatures quickly, reducing cold start emissions. This regulatory driver reinforces the necessity of engine shielding as a critical component in emissions control systems. While electric vehicles gain traction, the sheer volume of internal combustion vehicles ensures that engine shielding remains the dominant application segment for the foreseeable future, supported by ongoing efficiency improvements and stricter emissions norms.
The imperative to reduce vehicle emissions drives the dominance of engine shielding by ensuring catalytic converters reach and maintain optimal operating temperatures for efficient pollutant conversion. Besides, as per the United States Environmental Protection Agency, a finalized multi-pollutant rule sets strict new emission caps for passenger fleets sold between 2027 and 2032 to cut overall greenhouse gases. Heat shielding plays a crucial role in this process by retaining exhaust heat within the system and directing it toward the catalyst rather than dissipating it into the engine bay. According to the European Automobile Manufacturers Association, regional industrial groups warn that implementing the rigid secondary Euro 7 legislative guidelines will dramatically raise vehicle compliance costs for logistics providers. These environmental regulations create a direct link between shielding performance and regulatory compliance, making it a non-negotiable element of powertrain design. Failure to adequately shield exhaust components can result in failed emissions tests and vehicle recall costs. As emissions limits tighten, the complexity and effectiveness of engine shielding solutions must increase to support after treatment systems. This regulatory pressure ensures sustained demand for high performance engine shielding materials that contribute to cleaner air and compliance with global environmental goals.
Battery Management Shielding
The battery management shielding segment is on the rise and is expected to be the fastest growing segment in the market by witnessing a CAGR of 7.5% from 2026 to 2034. This quick surge is propelled by the explosive growth of electric vehicle production and the critical need for thermal and electrical protection. According to the International Energy Agency, the global electric vehicle fleet is projected to exceed 500 million units by 2035 under current Stated Policies Scenario growth metrics. Each electric vehicle battery pack requires comprehensive shielding to protect cells from thermal runaway, external impacts and electromagnetic interference from high-voltage components. Apart from these, as per the Society of Automotive Engineers, automotive thermal engineering teams integrate multi-layered insulation arrays to mitigate cell degradation and enforce narrow battery operational limits during high-load charging. The technical necessity drives the adoption of advanced shielding materials such as phase change materials, aerogels and conductive composites that offer multi functional protection. Automakers are investing heavily in modular battery designs that integrate shielding directly into the pack structure to optimise weight and space efficiency. The increasing energy density of next-generation batteries further amplifies the need for robust shielding to manage higher thermal loads and prevent catastrophic failures. This convergence of safety performance and regulatory requirements positions battery management shielding as the primary growth engine in the automotive shielding market.
Strict safety regulations governing high-voltage systems in electric vehicles accelerate the adoption of battery management shielding to prevent electrical hazards and thermal incidents. The United Nations Global Technical Regulation No 20 mandates that electric vehicle battery systems must withstand severe mechanical and thermal abuse without posing a risk of fire or electric shock to occupants. Compliance with this regulation requires extensive use of shielding materials to isolate high voltage components from the vehicle chassis and passenger compartment. As per the National Highway Traffic Safety Administration, a newly enacted safety standard dictates that electric powertrains show no visible post-crash fire or explosion propagation within a one-hour observation period. These safety standards force manufacturers to integrate multi layer shielding solutions that provide both electrical insulation and thermal protection. The increasing frequency of fast charging infrastructure also raises thermal stresses on battery systems, necessitating enhanced shielding to manage heat buildup during rapid energy transfer. Automakers must validate shielding performance through rigorous testing protocols to certify vehicle safety and gain market access. This regulatory framework creates a mandatory demand for high-performance battery shielding materials, driving innovation and investment in this rapidly expanding segment to ensure consumer confidence and regulatory compliance.
By Vehicle Insights
Passenger Cars
The passenger cars segment dominated the automotive shielding market and accounted for a substantial share in 2025. This dominance of the segment was driven by its high production volumes and increasing integration of advanced electronic and thermal management systems. Moreover, as per the International Organization of Motor Vehicle Manufacturers, global passenger car production surpassed 60 million units, maintaining its status as the single largest production category within the global automotive assembly sector. Modern passenger vehicles are equipped with numerous electronic features such as infotainment systems, advanced driver assistance sensors and connectivity modules that require effective electromagnetic interference shielding to function reliably. According to the Society of Automotive Engineers, modern vehicular physical electrical system architectures are experiencing rapid optimization to replace heavy traditional point-to-point analog wiring bundles with lightweight multiplexed digital network backbones. The high electronic content creates a proportional demand for EMI shielding materials across every vehicle subsystem. Additionally the shift toward electric passenger cars introduces new thermal management challenges requiring heat shielding for battery packs and power electronics. Consumer expectations for comfort and safety further drive the adoption of acoustic and thermal shielding to reduce noise and maintain optimal cabin temperatures. The sheer scale of passenger car production combined with increasing technological complexity ensures its continued leadership in the automotive shielding market.
Growing consumer demand for enhanced comfort and connectivity features in passenger cars drives the widespread adoption of automotive shielding solutions to ensure seamless performance. According to J.D. Power, in-vehicle infotainment systems represent the leading driver of initial quality demerits across the entire automotive sector, heavily penalizing brand satisfaction scores via recurrent software crashes and phone-mirroring dropouts. Achieving this level of performance requires robust electromagnetic interference shielding to protect sensitive communication modules and sensors from internal and external noise sources. In addition, as per the Consumer Technology Association, the escalating concentration of multi-band wireless communications in smart ecosystems is accelerating the global deployment of dynamic cellular network architectures to handle regional radio frequency constraints. The noisy electromagnetic environment necessitates advanced shielding solutions to maintain signal integrity for GPS navigation, Bluetooth connectivity and cellular data transmission. Automakers respond by integrating high-performance shielding materials into vehicle architectures to deliver a premium user experience free from glitches or dropouts. The competitive nature of the passenger car market forces manufacturers to differentiate through technology and comfort, making effective shielding a critical enabler of brand reputation and customer satisfaction. This consumer-driven demand ensures sustained growth in the shielding market as vehicles become increasingly connected and feature-rich.
Light Commercial Vehicles
The light commercial vehicles segment is likely to experience the fastest CAGR of 5.8% over the forecast period due to the expansion of e-commerce and last-mile delivery services. Also, as per the International Transport Forum, total global freight transport activity will expand more than 2.5-fold under existing long-term infrastructure trajectories, creating significant macrochallenges for municipal clean freight networks. The surge in usage leads to higher mileage and more intensive operating conditions, requiring durable shielding solutions to protect electronic systems and manage thermal loads. According to the Society of Automotive Engineers, heavy commercial vehicle engineering programs utilize standardized hardware parameters to govern electrical propulsion isolation requirements across commercial distribution medium-duty applications. The transition creates new demand for battery shielding and high voltage component protection tailored to the specific duty cycles of commercial vehicles. Unlike passenger cars, light commercial vehicles often operate in stop-and-go traffic, generating significant thermal stress on powertrains and braking systems. Effective shielding is essential to maintain vehicle reliability and minimise downtime, which is critical for commercial operators. The combination of fleet electrification and increased utilization rates positions light commercial vehicles as a high growth segment for automotive shielding suppliers.
The rapid electrification of last mile delivery fleets serves as a primary driver for the accelerated growth of shielding solutions in the light commercial vehicle segment. According to the International Energy Agency, the global supply chain for electric light commercial fleets is scaling to support rapid electrification across target commercial urban logistics delivery structures. Each electric delivery van requires comprehensive shielding for its battery pack, motor, and power electronics to ensure safety and reliability during frequent stop-start operations. As per the International Council on Clean Transportation, zero-emission heavy-duty transit corridors encounter operational resistance from severe grid charging infrastructure deficiencies rather than vehicle-internal thermal management constraints. The operational intensity demands robust shielding materials that can withstand repeated thermal cycling without degradation. Logistics companies prioritise vehicle uptime and total cost of ownership, making reliable shielding a critical factor in procurement decisions. The shift toward autonomous delivery robots and drones further expands the scope of shielding applications in the commercial sector. These emerging technologies require miniaturised yet highly effective shielding solutions to protect sensitive electronics in compact form factors. This technological evolution drives innovation and growth in the light commercial vehicle shielding market.
REGIONAL ANALYSIS
North America Market Analysis
North America occupies a noteworthy position in the automotive shielding market. The region’s market is known for its strong regulatory frameworks and high adoption of electric vehicles. Also, as per the United States Environmental Protection Agency, newly finalised light-duty greenhouse gas standards restrict fleetwide average carbon dioxide exhaust emissions to accelerate national electric vehicle deployment metrics. According to the Alliance for Automotive Innovation, major car manufacturers are aggressively localising secondary battery extraction and electronic assembly infrastructure to mitigate critical execution and grid network supply risks. The investment surge creates a robust market for advanced shielding technologies that meet rigorous safety and performance criteria. The presence of major technology companies in the region also accelerates the integration of connected and autonomous features requiring sophisticated shielding to manage complex electronic architectures. Supply chain localization initiatives further support market growth by encouraging domestic production of shielding materials to reduce dependency on imports. The region’s focus on sustainability and innovation ensures continued demand for lightweight and eco-friendly shielding solutions. Strong collaboration between automakers and material suppliers fosters rapid development and deployment of next-generation shielding technologies. This dynamic ecosystem positions North America as a leader in high-value automotive shielding applications.
Europe Market Analysis
Europe followed closely behind in the automotive shielding market and captured a major share in 2025. This growth of the European market was fuelled by aggressive electrification targets and strict environmental regulations. As per the European Commission, updated regulatory reviews propose lowering the 2035 zero-emission car mandate down to a 90% emissions reduction target to accommodate plug-in hybrids. According to the European Automobile Manufacturers Association, the total volume of operational battery-electric public transport infrastructure reached approximately 3 million passenger vans, trucks, and buses deployed across regional logistics sectors. Strict REACH regulations govern the use of hazardous substances in shielding materials, pushing manufacturers toward sustainable and recyclable alternatives. The region’s strong emphasis on circular economy principles encourages the development of shielding solutions that facilitate end-of-life vehicle recycling. European automakers are also leaders in autonomous driving technology requiring advanced EMI shielding for high frequency sensors and communication systems. The presence of renowned material science research institutions supports innovation in lightweight and high performance shielding materials. Collaborative projects between industry and academia accelerate the commercialisation of new technologies. This regulatory and technological leadership ensures Europe remains a key market for premium automotive shielding solutions.
Asia Pacific Market Analysis
Asia Pacific was the leading as well as the quickest growing region in the automotive shielding market in 2025. This leading position of the APAC market was attributed to its dominant vehicle production base and rapid electrification. The China Association of Automobile Manufacturers reports that China produced over 30 million vehicles in 2023, accounting for nearly half of global output and generating massive demand for shielding components. The region’s aggressive push toward electric mobility, led by government subsidies and infrastructure investment, drives substantial consumption of battery and thermal shielding materials. According to the Japan Automobile Manufacturers Association, regional value chains aggressively scale the export deployment of multi-propulsion electrified platforms to satisfy global greenhouse gas reduction targets. Rapid urbanisation and rising disposable incomes in emerging economies such as India and Southeast Asia boost passenger car sales, further expanding the shielding market. Local manufacturing capabilities are expanding to meet domestic demand and reduce costs, with many global suppliers establishing production facilities in the region. The presence of major electronics manufacturers also facilitates the integration of advanced shielding technologies into vehicle designs. Government initiatives to improve air quality and reduce emissions reinforce the need for effective thermal and emissions control shielding. This combination of scale innovation and policy support positions Asia Pacific as the central hub for automotive shielding growth.
Latin America Market Analysis
Latin America expands gradually in the automotive shielding market due to regional production hubs and evolving regulatory landscapes. Besides, as per the Brazilian National Association of Vehicle Manufacturers, nationwide automotive assembly lines completed a total of 2.324 million vehicles, experiencing a minor production contraction of 1.9 percen. The region’s gradual adoption of flex fuel and hybrid technologies creates specific shielding requirements for diverse powertrain configurations. Environmental regulations are tightening in major markets such as Mexico and Chile, prompting automakers to upgrade shielding solutions to meet emissions and safety standards. According to the Inter-American Development Bank, regional automotive systems face accelerating micro-mobility integration alongside expanding commercial urban fleet electrification to replace traditional carbon-intensive powertrains. The transitional phase creates opportunities for shielding suppliers to introduce cost effective solutions tailored to local market conditions. Local content requirements in some countries encourage domestic production of shielding materials, fostering regional supply chain development. Economic volatility and currency fluctuations pose challenges, but the long-term trend toward vehicle modernisation supports market growth. Strategic partnerships between global suppliers and local manufacturers help navigate regulatory and economic complexities. This evolving landscape offers potential for steady expansion as the region integrates into global automotive trends.
Middle East and Africa Market Analysis
The Middle East and Africa region is expected to grow steadily in the automotive shielding market during the forecast period owing to luxury vehicle demand and emerging manufacturing initiatives. Moreover, as per the Gulf Cooperation Council Standardization Organization, a unified regional framework establishes specific technical standards for electric vehicles to govern battery energy storage protection and passenger shock safety metrics across member states. According to public industrial economic development initiatives, regional energy enterprises are rapidly scaling high-speed highway charging hubs to support a target market milestone where electric options comprise 50% of all operating consumer cars. In addition, as per African automotive industrial metrics, urban transit networks are experiencing rapid expansion in motorcycle taxi fleets and entry-level compact passenger models to meet growing personal mobility demand. Harsh climatic conditions in the region necessitate robust thermal shielding to protect vehicle components from extreme heat and dust. Luxury and premium vehicle segments, which have higher electronic content and shielding requirements, remain strong in Gulf markets. Local manufacturing initiatives in countries such as Morocco and South Africa are attracting global automakers who bring advanced shielding technologies with them. The region’s focus on sustainability and smart city development also supports the adoption of connected and electric vehicles. While currently smaller in scale, the market is poised for growth as infrastructure and regulatory frameworks mature.
COMPETITIVE LANDSCAPE
The automotive shielding market features intense competition among global material science leaders and specialized component manufacturers vying for contracts with major original equipment manufacturers. Large multinational corporations leverage their extensive research and development capabilities to offer innovative lightweight and multi functional shielding solutions that address complex thermal and electromagnetic challenges. These firms compete on technical performance regulatory compliance and ability to integrate seamlessly into vehicle architectures rather than price alone. Regional players often focus on niche applications or specific vehicle segments where they possess deep local knowledge and established supply chains. Competition is further intensified by the rapid transition to electric vehicles which requires new shielding technologies for battery packs and high voltage systems. Companies differentiate themselves through superior material science expertise rapid prototyping capabilities and robust global supply networks. Regulatory pressures drive continuous innovation in sustainable and recyclable shielding materials forcing all participants to invest in green technologies. Consolidation trends see larger firms acquiring specialized boutiques to gain access to proprietary technologies or regional market access. This dynamic environment rewards agility technical expertise and customer centricity while penalizing those unable to adapt to evolving safety and environmental standards in the automotive sector.
KEY MARKET PLAYERS
These are some of the major key players of the global automotive shielding market.
- Federal-Mogul
- Laird PLC
- Lydall Inc
- ElringKlinger AG
- Dana Incorporated
- Morgan Advanced Materials
- Ag, Dana Incorporated
- Henkel AG & Company
- The 3M Company
- Kitagawa Iron Works Co., Ltd.
- Tech-Etch Inc.
- Marian Inc.
Top Players In The Market
- Lydall Inc stands as a premier provider of thermal and acoustic insulation solutions specifically engineered for the automotive sector. The company specializes in designing custom heat shields and noise barriers that protect sensitive vehicle components from extreme temperatures and vibration. Recent strategic initiatives include expanding its manufacturing footprint in North America to support local original equipment manufacturers with faster delivery times. Lydall invests heavily in research to develop lightweight composite materials that meet stringent fuel efficiency standards without compromising protection levels. Their collaboration with major automakers focuses on integrating shielding directly into vehicle platforms during the design phase. This proactive approach ensures optimal performance and cost efficiency for clients. By prioritizing innovation in material science and maintaining rigorous quality control, Lydall strengthens its reputation as a trusted partner for high performance automotive shielding needs globally.
- ElringKlinger AG leverages its extensive expertise in sealing and shielding technologies to deliver advanced solutions for both conventional and electric vehicles. The company produces high precision heat shields and battery protection systems that ensure safety and reliability in modern powertrains. ElringKlinger recently expanded its production capabilities in Asia to cater to the growing demand for electric vehicle components in key markets. The firm focuses on developing multi functional shielding materials that offer thermal insulation and electromagnetic interference protection simultaneously. Strategic partnerships with leading battery manufacturers allow ElringKlinger to integrate its shielding solutions early in the development process. This integration enhances system efficiency and reduces overall weight. By combining engineering excellence with sustainable manufacturing practices, ElringKlinger reinforces its position as a critical supplier in the evolving automotive landscape.
- Dana Incorporated provides comprehensive thermal management and shielding solutions that address the complex needs of modern automotive architectures. The company offers a wide range of heat shields and acoustic barriers designed to improve vehicle efficiency and passenger comfort. Dana recently launched new product lines focused on electric vehicle battery thermal management utilizing advanced aerogel and composite technologies. These innovations help maintain optimal battery temperatures while reducing overall system weight. The company actively collaborates with global automakers to co develop customized shielding solutions that meet specific performance criteria. Dana also emphasizes sustainability by incorporating recycled materials into its shielding products. Through continuous investment in technology and global supply chain optimization, Dana ensures it remains at the forefront of automotive shielding innovation and reliability.
Top Strategies Used By Key Market Participants
Key players in the automotive shielding market primarily focus on product innovation and strategic geographic expansion to maintain competitive advantage. Companies invest significantly in research and development to create lightweight and multi functional shielding materials that meet strict emissions and safety regulations. Developing composites that offer both thermal and electromagnetic protection allows suppliers to provide integrated solutions that reduce vehicle weight and complexity. Simultaneously firms expand their manufacturing presence in high growth regions such as Asia Pacific to serve local original equipment manufacturers more effectively. This localization strategy reduces logistics costs and improves supply chain resilience. Collaborations with automakers during the early design phases enable suppliers to integrate shielding solutions seamlessly into vehicle platforms. Sustainability initiatives drive the adoption of recyclable and bio based materials aligning with global environmental goals. These combined strategies ensure companies remain agile and responsive to the rapidly changing demands of the automotive industry.
MARKET SEGMENTATION
This research report on the global automotive shielding market is segmented and sub-segmented into the following.
By Shielding
- Heat
- Electromagnetic Interference
By Heat Application
- Engine
- Turbocharger
- Battery Management
- Fuel Tank
By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East and Africa