- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$1.02 BnMarket Estimate, 2026
$1.14 BnMarket Forecast, 2034
$2.81 BnCAGR, 2026–2034
11.94%Executive Summary: Global Carbon Fiber Reinforced Thermoplastic Composites (CFRTP) Market
- Market Scope: Comprehensive global market breakdown covering application sectors, raw materials (polyacrylonitrile and petroleum pitch), and regional market dynamics for high-strength, recyclable thermoplastic composites.
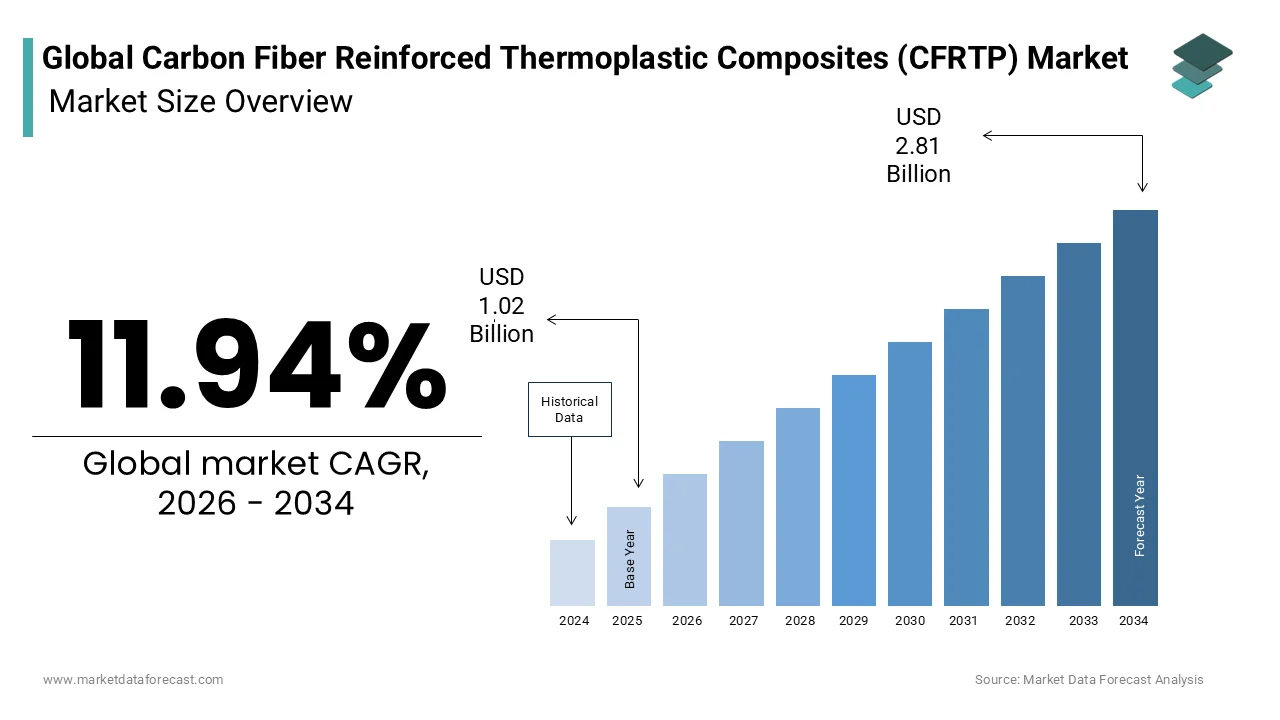
- Market Valuation: Valued at USD 1.02 billion (2025), estimated at USD 1.14 billion (2026), and projected to reach USD 2.81 billion by 2034, registering a CAGR of 11.94% (2026–2034).
- Primary Growth Drivers: Rising consumer and regulatory focus on vehicle fuel efficiency and emission reduction, increased demand for lightweight metal alternatives (steel/aluminum) in aerospace and automotive industries, and the inherent weldability and recyclability of CFRTP.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing / Key Segment Trends |
|---|---|---|
| By Raw Material | Polyacrylonitrile (PAN) (heavily preferred due to superior mechanical properties and high strength-to-weight ratio) | Polyacrylonitrile (predicted to expand at the highest CAGR during the forecast period over petroleum pitch) |
| By Application | Automotive & Aerospace (major revenue drivers utilizing CFRTP for weight reduction and structural integrity) | Automotive and Aerospace Sectors (projected to experience the quickest development alongside wind turbines and marine) |
| By Region | North America (anchored by major aircraft producers like Boeing and domestic manufacturing initiatives) | Europe (fastest-growing industry driven by stringent vehicle emission regulations and major automotive investments) |
Major Market Players & Market Structure
Market Structure: Highly strategic and competitive global landscape characterized by vertical integrations, acquisitions (such as Toray's acquisition of TenCate Advanced Composites), and high-volume commercial applications (e.g., General Motors implementing Teijin's Sereebo CFRTP).
Key Companies: Solvay S.A., Royal Ten Cate N.V., Teijin Limited, Toray Industries, Inc., SGL Group, Celanese Corporation, Covestro AG, PolyOne Corporation, PlastiComp, Inc., and Aerosud.
 Download Free Sample Report
Global Carbon Fiber Reinforced Thermoplastic Composites (CFRTP) Market Size
The global carbon fiber reinforced thermoplastic composites (CFRTP) market was valued at USD 1.02 billion in 2025 and is expected to reach USD 2.81 billion by 2034 from USD 1.14 billion in 2026, growing at a CAGR of 11.94%.
Carbon Fiber Reinforced Thermoplastic Composites (CFRTP) are advanced, super-strong materials made by mixing incredibly stiff carbon fibers with a meltable plastic base. The carbon fibers act like steel bars to give the material massive strength, while the plastic acts like the concrete to hold everything together. In the past, most carbon fiber was mixed with thermoset plastics (like epoxy glue). Once those are baked and set, they can never be melted again. CFRTP uses thermoplastics instead, which gives it massive advantages, including super-fast production, recyclability, resistance to dings and dents, and ease of repair. As per studies, Carbon Fiber Reinforced Thermoplastic Composites (CFRTP) require specific, localized heating cycles above the polymer's melting point to consolidate layers, differing from traditional thermoset curing processes. Europe commands a leading regional footprint due to stringent regulatory frameworks and robust automotive manufacturing ecosystems that prioritize eco-friendly production methods. According to the National Institutes of Health (NIH) scientific literature, carbon-fiber-reinforced thermoplastics inherently offer high toughness, short manufacturing cycle times, and recyclability compared to their thermoset counterparts. Market participants increasingly favor these thermoplastics for their unique reprocessability, positioning the sector for sustained expansion across mobility, clean energy, and industrial domains. This structural evolution addresses critical demands for energy efficiency without compromising mechanical integrity, thereby reshaping traditional engineering supply chains worldwide.
MARKET DRIVERS
Surging Demand for Lightweight Electric Vehicle Platforms
Automotive electrification is a major primary driver for the Carbon Fiber Reinforced Thermoplastic Composites (CFRTP) Market. This is because manufacturers require extensive weight reduction to maximize battery efficiency and driving range. According to sources, electric vehicle manufacturers are increasingly incorporating lightweight composite battery enclosures and structural elements to increase vehicle range and reduce overall curb weight. This directly impacts the market by shifting consumption patterns away from heavy metals toward high performance polymers that enable rapid press-molding cycles and shorter takt times. Furthermore, as per studies, structural integration of lightweight materials helps reduce the environmental footprint and operational costs of transportation systems across major industrial regions. This metric reflects how mass production demands for electric mobility accelerate material adoption across Tier-1 automotive supply chains, compensating for heavier battery weights by shaving crucial kilograms off structural body panels, chassis components, and interior passenger safety elements.
Accelerating Commercial Aircraft Production Ramp-ups
Aerospace production recovery is also a major factor fuelling the growth of the Carbon Fiber Reinforced Thermoplastic Composites (CFRTP) Market. This occurs as major airframe builders increase single-aisle manufacturing rates to clear extensive delivery backlogs. According to research, the aerospace and defense sector represents a major consumer of advanced fiber-reinforced composites due to the strict demand for high strength-to-weight ratios in airframe construction. This concentration correlates directly with the market by sustaining continuous demand for lightweight secondary structures that reduce overall aircraft fuel burn and lower lifetime carbon emissions. Additionally, as per sources, global commercial aviation fleet renewals are primarily driven by the transition toward highly fuel-efficient and lower-emission aircraft models to optimize airline operating expenses. This statistical expansion highlights the critical reliance of modern aerospace manufacturing on advanced composite materials for long-term operational efficiency, damage tolerance, and compliance with increasingly stringent civil aviation environmental targets globally.
MARKET RESTRAINTS
High Initial Capital Investment and Specialized Processing Equipment
Prohibitive capital expenditure requirements are a key restraint for the Carbon Fiber Reinforced Thermoplastic Composites (CFRTP) market. This limitation exists because automated placement cells and high-temperature presses impose severe entry barriers for smaller participants. As per sources, the high capital expenditure required for automated machinery, such as compression presses and advanced fiber placement tools, limits the adoption of carbon fiber reinforced thermoplastic composites among smaller manufacturers. This financial barrier directly suppresses broad market penetration by limiting large-scale processing capabilities to well-capitalized tier-one conglomerates. Moreover, according to research, high raw material costs and complex thermal processing requirements act as primary technical restraints that delay the widespread implementation of thermoplastic composites. This metric demonstrates how steep infrastructure expenses delay production scaling in emerging manufacturing regions, forcing companies to carefully balance heavy upfront outlays against uncertain medium-term volume commitments from downstream original equipment manufacturers.
Stiff Competition from Traditional Thermoset Composites
An established preference for conventional thermosetting materials is one of the major impediments to the growth of the Carbon Fiber Reinforced Thermoplastic Composites (CFRTP) market. This resistance stems from their deeply entrenched supply chains and the lower raw material baseline of epoxy-based systems. As per research, traditional thermoset polymer matrices remain highly dominant in structural composite components due to long-established manufacturing practices and mature supply chains. This market dominance directly challenges thermoplastic growth by forcing new market entrants to justify higher initial resin expenses to prospective industrial buyers. Furthermore, according to studies, legacy structural component designs are predominantly optimized for thermosetting systems, requiring lengthy recertification protocols for alternative thermoplastic replacements. This structural inertia constrains rapid market conversion despite the superior recycling benefits and out-of-autoclave processing speeds offered by high performance thermoplastic polymer matrices.
MARKET OPPORTUNITIES
Expansion into Renewable Energy and Wind Turbine Infrastructure
The growing deployment of utility-scale wind energy projects is a major opportunity for the expansion of the Carbon Fiber Reinforced Thermoplastic Composites (CFRTP) market. This commercial potential expands as engineers seek lighter and longer turbine blades to capture optimal wind currents. As wind turbine rotor diameters expand past 150 meters to increase power generation, the high stiffness-to-weight ratio and fatigue resistance of fiber-reinforced polymer composites ensure long-term structural reliability under cyclic loading in harsh marine environments. This sector expansion directly correlates with the market by opening high-volume revenue streams outside traditional aerospace and automotive domains. Additionally, according to research, the long-term adoption of utility-scale wind energy infrastructure drives a stable demand expansion for advanced polymer composites, reinforcing the technological and commercial viability of recyclable blade designs. As turbine rotor diameters continue to stretch past 150 meters, the exceptional stiffness-to-weight ratio of these advanced thermoplastics ensures reliable operation in harsh offshore environments where conventional materials experience fatigue degradation.
Integration of Automated High-Rate Manufacturing Technologies
The adoption of advanced automated processing techniques offers a strong opening for the expansion of the Carbon Fiber Reinforced Thermoplastic Composites (CFRTP) Market. This potential is driven by automated fiber placement and rapid stamp molding, which drastically reduce cycle times. According to studies, compression and stamp molding processes utilize rapid thermal processing to achieve the short cycle times and reduced takt times required for high-volume automotive and commercial production components. This technological integration directly benefits the market by closing the cost gap with traditional metal fabrication through minimized manual labor and high repeatability. Furthermore, as per sources, innovations in high-speed automated fiber placement and automated tape laying provide the necessary throughput and part consistency to secure large-scale commercial automotive contracts. By streamlining consolidation steps and utilizing scrap recycling loops, fabricators can achieve unprecedented throughput levels that satisfy aggressive cost-per-part targets set by global original equipment manufacturers.
MARKET CHALLENGES
High Raw Material Cost of Carbon Fiber Precursors
Expensive precursor materials are a major obstacle for the Carbon Fiber Reinforced Thermoplastic Composites (CFRTP) Market. This economic challenge remains unresolved as polyacrylonitrile and advanced thermoplastic resins carry a much higher price tag than standard metals. As per research, carbon fiber reinforced composite components are significantly more expensive to manufacture than traditional structural steels, presenting a high cost penalty for large-scale mass-market commercial production. This pricing disparity directly undermines broader market expansion by pricing out budget-restricted applications that could otherwise benefit from lightweighting. Additionally, as per sources, high feedstock volatility accounts for persistent margin compression among downstream part fabricators, complicating long-term pricing stability across the global supply chain. Addressing these feedstock cost hurdles requires concerted investment in alternative low-cost precursors and bio-derived polymer matrices that can deliver comparable performance without excessive raw material overhead.
Complex Interfacial Bonding and End-of-Life Recycling Complexities
Technical difficulties associated with matrix-fiber separation hold back the expansion of the Carbon Fiber Reinforced Thermoplastic Composites (CFRTP) market. This issue intensifies as stringent environmental regulations penalize non-recyclable structural waste. According to European Union, the complex structural composition of polymer matrix composites presents significant technological challenges for high-purity carbon fiber reclamation at the end of a vehicle's life cycle. Moreover, as per studies, unoptimized end-of-life processing solutions restrict sustainable market scaling, forcing material scientists to prioritize the rapid development of novel recyclable vitrimer resins and alternative low-cost precursors. Overcoming these interfacial bonding barriers is vital for unlocking closed-loop material streams that satisfy both ecological mandates and demanding structural performance specifications.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 11.94% |
| Segments Covered | By Product Type, Raw Material, Application, and Region. |
|
Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Solvay S.A. (Belgium), Royal Ten Cate N.V. (Netherlands), Teijin Limited (Japan), Toray Industries, Inc. (Japan), SGL Group (Germany), Celanese Corporation (U.S.), Covestro AG (Germany), PolyOne Corporation (U.S.), PlastiComp, Inc. (U.S.), and Aerosud (South Africa), and others. |
SEGMENT ANALYSIS
By Product Type Insights
The continuous carbon fiber segment dominated the carbon fiber reinforced thermoplastic composites (CFRTP) market and accounted for a substantial share in 2025. This dominance of the segment was driven by its supreme structural load bearing capabilities and exceptional mechanical strength parameters. According to studies, the continuous fiber classification provides uncompromised tensile strength and stiffness vital for high-stress structural applications. As per sources, continuous fiber reinforced thermoplastics are increasingly utilized to fuel structural upgrades across transportation sectors. This market supremacy is heavily driven by intense engineering demands for weight reduction in modern engineering where metal replacement is mandatory. As per the International Organization of Motor Vehicle Manufacturers (OICA), global vehicle production reached 96.4 million units in 2025, showing a resilient consumer base for lightweight structural materials. The relation between this high production volume and the market is that automakers increasingly turn to continuous carbon fiber thermoplastics to shave off structural weight without sacrificing passenger safety. Furthermore, according to research, automated tape placement and continuous stamping technologies are used to compress component manufacturing cycle times to support mass production requirements. This processing speed breakthrough is tied to market growth because it eliminates the historical bottleneck of slow curing times associated with thermoset alternatives.
On the other hand, the short carbon fiber segment is predicted to witness the highest CAGR of 10.5% during the forecast period. This rapid expansion is propelled by cost efficiency and design flexibility, allowing manufacturers to utilize existing injection machinery while incorporating recycled carbon fiber streams. According to studies, short fiber compounds integrate smoothly into traditional injection molding equipment, permitting the fabrication of complex geometries with minimal tooling modifications. As per sources, injection molded short fiber segments are adopted across complex under-the-hood automotive parts and electronics enclosures. According to research, regional regulatory targets mandate substantial increases in secondary raw material utilization to meet circular economy goals. The relation between this regulatory push and the market is that short carbon fiber compounds readily accept recycled shredded fibers, offering a sustainable and economical alternative to virgin continuous filaments. Additionally, as per studies, global electrical and electronics device production creates high-velocity demand for thin-walled, highly rigid short fiber thermoplastic housings. This surge connects directly to market acceleration because consumer electronics require high thermal conductivity and electromagnetic shielding properties found uniquely in short carbon fiber reinforced matrices.
By Raw Material Insights
The polyacrylonitrile based carbon fiber segment led the carbon fiber reinforced thermoplastic composites (CFRTP) market and captured a significant share in 2025. This leading position of the segment was attributed to its mature supply chain and superior tensile performance. According to research, polyacrylonitrile-based raw materials occupy a major structural role as a leading precursor for high-performance carbon fiber production. As per sources, polyacrylonitrile serves as the foundational precursor for a vast majority of structural-grade carbon fibers because it delivers a predictable carbonization yield and high molecular orientation. This market leadership is sustained by rigorous aerospace qualification standards that specify polyacrylonitrile precursors for critical flight structures. According to studies, the worldwide commercial aircraft order backlog has climbed to a historic high of more than 17,000 aircraft, signaling sustained multi-year manufacturing demand for advanced structural materials. The relation between this aviation backlog and the market is that strict aerospace certifications mandate the proven reliability of polyacrylonitrile based thermoplastic composites over unproven alternatives. Moreover, as per research, optimizations in thermal stabilization ovens are actively being developed to compress the energy consumption profile of the precursor conversion phase. This production efficiency improvement ties directly to market dominance by lowering raw material acquisition costs for major thermoplastic compounders.
The petroleum-pitch-based raw material segment is the fastest-expanding in the carbon fiber reinforced thermoplastic composites (CFRTP) market. This swift growth is fueled by the unique physical properties of pitch-based carbon fibers, which exhibit near-zero thermal expansion coefficients essential for precision instruments. According to studies, pitch-based variants provide distinctive engineering advantages due to their exceptionally high thermal conductivity and ultra-high modulus performance characteristics. As per sources, deployment of high-temperature thermal management systems and specialized spacecraft structures requires advanced components capable of operating in extreme orbital environments. According to NASA official financial records, the annual agency budget enacted for fiscal year 2026 stands at $24.4 billion, funding structural space exploration programs and composite panel deployments. The relation between these space programs and the market is that satellite booms and antenna reflectors rely entirely on the dimensional stability provided by pitch based thermoplastic systems. Furthermore, as per research, isotropic and anisotropic pitch precursors are regularly utilized to meet strict structural specifications in industrial furnace components and electrode assemblies. This industrial integration fuels market acceleration because pitch materials offer a lower cost carbon source derived from petroleum refinery residues compared to specialized acrylic polymers.
By Application Insights
The aerospace and defense segment was the largest in 2025 and occupied a commanding share of the global carbon fiber reinforced thermoplastic composites (CFRTP) market. This supremacy of the segment was supported by the necessity for optimal fuel efficiency and structural resilience under extreme thermal and mechanical operating conditions. According to studies, the aerospace segment secures a substantial portion of advanced composite deployments due to demanding structural parameters. As per sources, substituting metal alloys with advanced carbon fiber components in aircraft structures reduces overall vehicle weight and increases efficiency. According to the International Air Transport Association (IATA), commercial air carriers consume approximately 90 billion gallons of jet fuel annually, putting structural and regulatory pressure on airlines to minimize aircraft weight. The relation between this massive fuel consumption and the market is that every pound eliminated via thermoplastic composite adoption directly reduces operational emissions and carrier expenses. Additionally, as per the Boeing 2026 Commercial Market Outlook (CMO), operators are forecasted to require nearly 44,000 new commercial airplanes over the next two decades to support sustained air travel demand. This manufacturing pipeline ensures sustained market dominance as modern aircraft designs incorporate weldable thermoplastic composites to speed up fuselage assembly lines.
The automotive segment exhibits the highest growth rate within the carbon fiber reinforced thermoplastic composites (CFRTP) market. This quick surge is driven by the urgent requirement to offset heavy lithium-ion battery pack weight with ultra-lightweight structural vehicle frames. According to research, vehicle electrification trends are shifting structural design priorities toward lightweight, integrated component configurations. As per studies, rapid global adoption of electric vehicles is reshaping automotive architecture and requiring optimized component materials. According to documentation tracked by the European Automobile Manufacturers' Association (ACEA), fleet-average regulatory mandates require a 37.5% reduction in carbon dioxide emissions for new passenger cars by 2030 relative to baseline reference standards. The relation between these strict emission caps and the market is that automakers must deploy high performance thermoplastic composites in battery enclosures and crash management systems to hit compliance thresholds. Moreover, as per sources, automated compression molding presses can form thermoplastic structural parts inside compressed cycle times to support automated assembly lines. This manufacturing breakthrough drives market acceleration because it allows tier-one automotive suppliers to meet high volume assembly line demands economically.
REGIONAL ANALYSIS
North America Carbon Fiber Reinforced Thermoplastic Composites Market Analysis
North America was the top performer in the carbon fiber reinforced thermoplastic composites (CFRTP) market and accounted for a 35.6% share in 2025. This prominence of the regional market was propelled by a massive aerospace defense complex and advanced manufacturing infrastructure. According to studies, North America hosts major aerospace prime contractors and materials research facilities that implement high-performance resin systems in structural assemblies. Market status across the United States and Canada is characterized by aggressive industrial automation and high tier research spending directed toward advanced structural materials. As per the United States Department of Defense (DoD) financial allocations, the federal budget request for aircraft procurement and related systems stands at approximately $68.3 billion, funding tactical aircraft modernization and advanced component integration. The relation between these defense investments and the market is that military procurement heavily subsidizes the scaling of advanced thermoplastic tape placement facilities and automated manufacturing cells. Furthermore, according to sources, collaborative grant initiatives foster joint engineering projects between academic research institutions and commercial advanced composite manufacturers. This intellectual property generation anchors market leadership by continuously upgrading domestic processing capabilities and reducing scrap rates.
Europe Carbon Fiber Reinforced Thermoplastic Composites Market Analysis
Europe was positioned second in the carbon fiber reinforced thermoplastic composites (CFRTP) market and captured a significant share in 2025. his regional presence was supported by stringent environmental laws and prominent luxury automotive engineering hubs. According to research, Europe represents a prominent regional market for advanced structural materials due to its dense concentration of aerospace and automotive original equipment manufacturers. Market status throughout Germany, France, and the United Kingdom reflects an intense focus on circular economy compliance and closed loop recycling frameworks. As per studies, industrial waste disposal mandates impose rigorous conditions and escalating financial charges on the landfilling of non-recyclable composite components. The relation between this environmental policy and the market is that thermoplastic composites can be repeatedly melted and reshaped, giving European manufacturers a direct compliance advantage over thermoset materials. Additionally, according to the European Environment Agency (EEA), regional automotive fleet regulations mandate an eventual transition to 100% zero-emission new passenger car sales, driving deep structural redesigns of vehicle architectures. This regulatory shift accelerates market expansion as German automotive giants integrate stampable thermoplastic organosheets into mass market electric vehicle body structures.
Asia Pacific Carbon Fiber Reinforced Thermoplastic Composites Market Analysis
Asia Pacific is the fastest-growing region in the carbon fiber reinforced thermoplastic composites (CFRTP) market because of rapid industrialization and booming automotive manufacturing. According to sources, the Asia-Pacific region exhibits a high volume of composite material manufacturing to meet demands across consumer electronics, infrastructure, and heavy industrial applications. Market status in nations like China, Japan, and South Korea is defined by massive investments in factory automation, electronics fabrication, and domestic electric vehicle supply chains. As per the China Association of Automobile Manufacturers (CAAM), annual automotive production in China has reached 34.53 million units, establishing the nation as the single largest automotive manufacturing pool globally. The relation between this immense manufacturing volume and the market is that local tier-one suppliers are rapidly installing high capacity thermoplastic compression molding lines to supply domestic electric vehicle brands. Furthermore, according to studies, state agencies provide structured research and development support to elevate deep tech capabilities in advanced materials and industrial software. This government backing drives market momentum by establishing regional self sufficiency in polyacrylonitrile precursor production and lowering dependency on foreign composite imports.
Latin America Carbon Fiber Reinforced Thermoplastic Composites Market Analysis
Latin America is also a key player in the carbon fiber reinforced thermoplastic composites (CFRTP) market due to localized automotive assembly growth and expanding renewable energy installations. According to research, manufacturing output for specialized technical applications in Latin America remains concentrated around established industrial corridors in Brazil and Mexico. Market status across the region is characterized by steady foreign direct investments from North American and European automotive conglomerates establishing regional manufacturing plants. As per the Economic Commission for Latin America and the Caribbean (ECLAC), total foreign direct investment (FDI) inflows into Latin America and the Caribbean reached $194.23 billion, financing diversified economic activities including manufacturing and energy infrastructure. The relation between these capital investments and the market is that incoming multinational original equipment manufacturers bring advanced lightweighting specifications, increasing local demand for durable thermoplastic components. Moreover, according to the Brazilian Wind Energy Association (ABEEólica), steady domestic wind project expansions require consistent inputs of durable engineering materials for large-scale structural assemblies. This renewable energy expansion accelerates market traction as regional manufacturers adopt pultruded thermoplastic profiles for wind turbine blade reinforcement.
Middle East and Africa Carbon Fiber Reinforced Thermoplastic Composites Market Analysis
The Middle East and Africa region is expected to grow notably in the carbon fiber reinforced thermoplastic composites (CFRTP) market from 2026 to 2034 owing to aggressive infrastructure diversification and offshore energy investments. According to studies, composite and structural polymer processing installations in the Middle East and Africa cater to long-term architectural and industrial piping infrastructure requirements. Market status in nations such as Saudi Arabia and the United Arab Emirates revolves around post oil economic transitions and large scale industrial scaling under national vision programs. As per sources, non-oil industrial sectors are expanding across regional economies as state initiatives prioritize investments in domestic structural manufacturing and advanced supply chains. The relation between this industrial diversification and the market is that local petrochemical complexes are investing heavily in downstream carbon fiber and thermoplastic polymer production joint ventures. Additionally, according to research, planned clean energy deployment across the region drives long-term demand for high-strength environmental encasements and specialized structural mountings. This clean energy push directly supports market development as asset operators require corrosion resistant thermoplastic composite piping and structural frames capable of withstanding harsh desert and marine environments.
COMPETITIVE LANDSCAPE
The global competitive landscape of the carbon fiber reinforced thermoplastic composites market is characterized by intense rivalry among established multinational chemical giants and specialized composite fabricators. Competition centers around material performance metrics, processing speeds, recyclability credentials, and cost effectiveness as industries increasingly transition away from traditional thermoset resins and heavy metals. Established enterprises leverage their extensive distribution networks and deep technical expertise to secure long term supply agreements with prominent aerospace and automotive original equipment manufacturers. Smaller innovative firms and startup entities challenge traditional market leaders by introducing disruptive manufacturing techniques, automated preforming solutions, and novel bio based or recycled thermoplastic matrices. Regional market dynamics also influence competitive strategies, prompting global players to establish localized manufacturing and recycling facilities to comply with stringent environmental regulations and reduce delivery lead times. Continuous investments in proprietary resin chemistry and digital engineering tools remain essential differentiators for participants striving to capture expanding opportunities in electric vehicles and next generation commercial aircraft programs.
KEY MARKET PLAYERS
The major key players in the global carbon fiber reinforced thermoplastic composites (CFRTP) market are
- Solvay S.A. (Belgium)
- Royal Ten Cate N.V. (Netherlands)
- Teijin Limited (Japan)
- Toray Industries, Inc. (Japan)
- SGL Group (Germany)
- Celanese Corporation (U.S.)
- Covestro AG (Germany)
- PolyOne Corporation (U.S.)
- PlastiComp, Inc. (U.S.)
- Aerosud (South Africa)
Top Players in the Market
- Toray Industries serves as a foundational pillar within the global carbon fiber reinforced thermoplastic composites market, supplying high performance prepregs and woven laminates to major aerospace and automotive manufacturers. The company contributes extensively through advanced polymer research and large scale production facilities that ensure stable supply chains for structural components. To strengthen its market position, Toray Advanced Composites completed the NCAMP qualification for high performance thermoplastic composite materials in December 2025. Furthermore, in April 2026, Toray Advanced Composites expanded qualifications for high performance low melt polyetherketone ketone composite material systems to capture broader structural engineering contracts. These proactive manufacturing milestones solidify its competitive standing across global supply networks.
- Hexcel Corporation acts as a premier developer of lightweight structural materials, delivering specialized carbon fiber reinforcements and engineered resin matrices tailored for demanding mobility applications. Its primary market involvement centers on providing advanced thermoplastic prepregs that enable faster cycle times and enhanced recyclability for industrial clients. To reinforce its commercial standing, Hexcel focuses on collaborative engineering partnerships with tier one original equipment manufacturers to optimize composite part fabrication. The enterprise continuously upgrades its manufacturing infrastructure and expands technical support centers across North America and Europe to accelerate customer specific product adoption. Through targeted investments in sustainable recycling technologies and high speed production lines, Hexcel maintains its competitive edge within the rapidly evolving lightweight materials ecosystem.
- Mitsubishi Chemical Group operates as a major vertically integrated participant in the carbon fiber reinforced thermoplastic composites domain, offering comprehensive material solutions from precursor fibers to finished thermoplastic laminates. The company contributes significantly by engineering specialized resin formulations and carbon fiber grades optimized for high volume industrial manufacturing and structural replacement. To strengthen its market position, Mitsubishi Chemical leverages strategic research initiatives aimed at improving the cost efficiency and environmental profile of thermoplastic composite production. The corporation actively engages in joint development agreements with automotive and aerospace pioneers to deploy recyclable thermoplastic structures. These strategic actions enhance its operational footprint and address growing regulatory demands for sustainable high performance engineering materials.
Top strategies used by the key market participants
Key market participants deploy aggressive vertical integration strategies to control raw material supply chains, ensuring consistent quality and mitigating price volatility associated with precursor inputs. Leading manufacturers heavily invest in advanced research and development partnerships with academic institutions and aerospace primes to accelerate the commercialization of fast curing thermoplastic prepregs. Companies increasingly focus on automated manufacturing technologies such as automated tape placement and robotic laser assisted fiber placement to reduce component fabrication cycle times for automotive assembly lines. Strategic mergers and geographic expansions allow major players to establish localized production hubs, directly serving regional demand and bypassing international logistics bottlenecks. Furthermore, key industry stakeholders emphasize sustainability by developing closed loop recycling methods that reclaim carbon fibers from production scrap without degrading mechanical performance parameters.
MARKET SEGMENTATION
This research report on the global carbon fiber reinforced thermoplastic composites (CFRTP) market has been segmented and sub-segmented based on application, raw material, and region.
By Product Type
- Continuous
- Long & Short
By Raw Material
- Polyacrylonitrile
- Petroleum pitch
By Application
- Aerospace
- Automotive
- Marine
- Wind turbine
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- The Middle East and Africa