- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$6.31 BnMarket Estimate, 2026
$8.27 BnMarket Forecast, 2034
$72.19 BnCAGR, 2026–2034
31.1%Executive Summary: Global Cognitive Assessment and Training Market
- Market Scope: Comprehensive global cognitive assessment and training market analysis covering assessment types, components, application verticals, corporate/clinical uses, and regional adoption frameworks.
- Market Valuation: Valued at USD 6.31 billion (2025), estimated at USD 8.27 billion (2026), and projected to reach USD 72.19 billion by 2034, registering a remarkable CAGR of 31.1% (2026–2034).
- Primary Growth Drivers: Rapidly aging global population leading to higher prevalence of dementia and neurological disorders, increased awareness of brain health and mental fitness, technological advances in healthcare, and the widespread adoption of computerized testing tools in clinical trials and corporate recruitment.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Assessment Type | Pen & Paper-based Assessment (accounted for the dominant share of the worldwide market) | Hosted and Biometrics Assessment Solutions (expanding rapidly due to digitalization and remote healthcare trends) |
| By Component | Solutions Segment (accounts for a notable revenue share spanning evaluation, data management, and reporting tools) | Services Segment (driven by increasing training, implementation support, and expert consulting needs) |
| By Application | Clinical Trials (major segment accounting for a considerable portion of global revenue in research validation) | Brain Training & Corporate Learning (surging due to heightened focus on employee mental performance and mental fitness) |
| By Vertical | Education Sector (registered the most substantial chunk of the global market share through academic evaluations) | Healthcare and Pharmaceuticals (accelerating due to early neurological disorder screening and clinical research demands) |
| By Region | North America (market leader driven by a broad base of elderly patients, advanced research, and high healthcare spending) | Asia-Pacific (fastest-growing regional market driven by expanding digital education and rising aging demographics) |
Major Market Players & Market Structure
Market Structure: Highly competitive global landscape featuring prominent medical, tech, and research entities competing on clinical validation, software accuracy, AI/cognitive computing integrations, and strategic partnerships for neurological disease treatments.
Key Companies: Cambridge Cognition Ltd., Cogstate Ltd., MedAvante Inc., ProPhase LLC, Neurocog Trials Inc., Quest Diagnostics Inc., Eresearchtechnology Inc., and Gompf Brackets Inc.
 Download Free Sample Report
Global Cognitive Assessment and Training Market Size
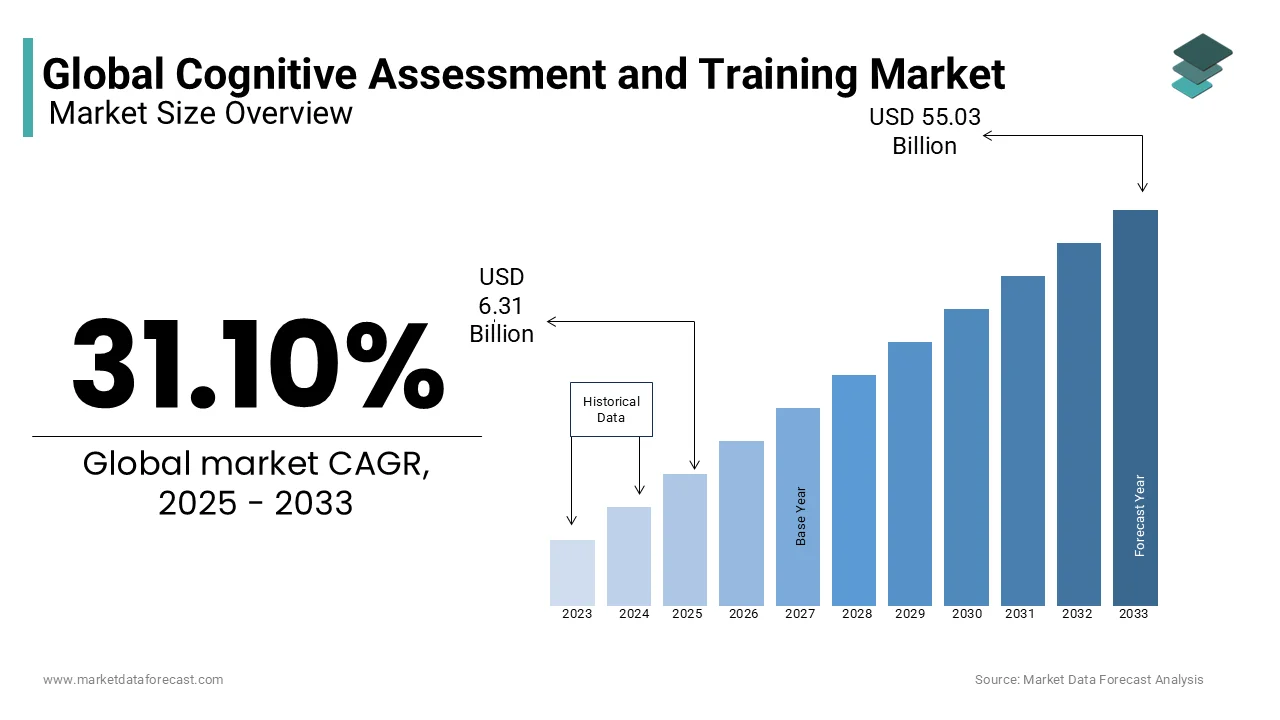
The global cognitive assessment and training market was valued at USD 6.31 billion in 2025. The market is estimated at USD 8.27 billion in 2026 and is projected to reach USD 72.19 billion by 2034, growing at a CAGR of 31.1% from 2026 to 2034.
Cognitive assessment and training is a combined process of measuring how well your brain works and then using targeted exercises to improve those mental skills. This domain integrates neuroscience-based software with clinical protocols to support individuals suffering from cognitive decline, traumatic brain injuries, or neurodevelopmental disorders. According to the World Health Organization, more than 55 million people worldwide are living with dementia, and this number is estimated to rise to 139 million by 2050. This demographic shift creates an unprecedented demand for early detection tools and non-pharmacological interventions to manage cognitive health. Furthermore, as per the Alzheimer's Association, about one in nine people aged 65 and older has Alzheimer's dementia. These statistics demonstrate the severe burden on healthcare systems and families, driving the adoption of automated cognitive screening tools. Consequently, healthcare providers and technology developers are prioritizing the creation of accessible, evidence-based training programs that can delay symptom progression and improve quality of life. The integration of these tools into routine clinical care and home-based settings marks a significant transformation in how cognitive health is managed, fostering a robust ecosystem for innovative digital therapeutics and assessment technologies.
MARKET DRIVERS
Rising Prevalence of Neurodegenerative Disorders and Aging Population
The escalating global prevalence of neurodegenerative conditions directly fuels the demand for advanced solutions in the cognitive assessment and training market. As life expectancy increases worldwide, the incidence of age-related cognitive impairments such as Alzheimer’s disease and mild cognitive impairment rises correspondingly. According to the United Nations Department of Economic and Social Affairs, the global population aged 65 years and older is expected to more than double from 761 million in 2021 to 1.6 billion by 2050. This demographic expansion creates a vast pool of individuals requiring regular cognitive monitoring and intervention to maintain independence. Additionally, as per the Lancet Commission on dementia prevention, intervention, and care, up to 45% of dementia cases could be delayed or prevented by fully addressing 14 lifestyle risk factors. This scientific consensus encourages healthcare systems to invest in proactive training programs. Clinicians increasingly rely on digital assessment tools to detect subtle changes in cognitive function earlier than traditional methods allow. Early identification enables timely initiation of training regimens that can slow disease progression and reduce long-term care costs. The growing awareness among caregivers and patients about the benefits of cognitive stimulation further accelerates adoption. Consequently, the pressing need to manage the health of an aging population sustains strong demand for reliable and effective cognitive assessment and training technologies across clinical and home care settings.
Integration of Digital Therapeutics into Mainstream Healthcare
The formal recognition and integration of digital therapeutics into standard medical practice significantly propels the growth of the cognitive assessment and training market. Regulatory bodies and insurance providers are increasingly acknowledging the clinical efficacy of software-based interventions for treating cognitive deficits. According to the Food and Drug Administration, prescription digital therapeutic devices have been cleared for treating attention deficit hyperactivity disorder (ADHD) in both pediatric and adult groups. The regulatory validation builds trust among physicians and encourages them to prescribe these tools as part of comprehensive treatment plans. Furthermore, as per the National Institute for Health and Care Excellence, digitally enabled therapies utilizing cognitive behavioral therapy (CBT) methods are recommended with clinician support for treating adults with depression and anxiety disorders. The endorsement facilitates reimbursement pathways, making these solutions more accessible to patients. Healthcare providers are also integrating these platforms into electronic health records, allowing for seamless monitoring of patient progress and data-driven adjustments to therapy. The ability to deliver personalized training protocols remotely enhances patient adherence and engagement. As clinical evidence accumulates, more hospitals and clinics are adopting these technologies to improve patient outcomes and operational efficiency. This shift towards value-based care models that prioritize preventive and manageable interventions ensures sustained investment in cognitive digital health solutions.
MARKET RESTRAINTS
Lack of Standardized Clinical Validation and Regulatory Fragmentation
The absence of universally accepted clinical validation standards and fragmented regulatory frameworks impede the expansion of the cognitive assessment and training market. This hinders the widespread adoption of cognitive assessment and training products. Many digital solutions enter the market with limited peer-reviewed evidence supporting their efficacy, leading to skepticism among healthcare professionals. According to the Journal of the American Medical Association, only a small fraction of available cognitive training apps have undergone rigorous randomized controlled trials to prove their clinical benefit. This lack of robust scientific backing makes it difficult for clinicians to recommend specific products with confidence. Additionally, regulatory requirements vary significantly across different regions, creating compliance challenges for developers seeking global market access. As per European Union Medical Device Regulation (EU MDR) guidelines, the European Union expressly captures standalone software within its device definitions, while the Food and Drug Administration (FDA) applies the device definition with statutory exclusions for several lower-risk software functions. This regulatory uncertainty increases development costs and time to market for innovators. Healthcare institutions are often reluctant to invest in solutions that may not meet future regulatory standards or receive reimbursement approval. The inconsistency in validation metrics also confuses consumers, who struggle to distinguish between evidence-based tools and entertainment-focused applications. Consequently, the lack of harmonized standards and clear regulatory pathways restricts market growth and limits the integration of these technologies into mainstream healthcare practices.
High Costs and Limited Reimbursement Coverage
Significant financial barriers and inadequate reimbursement policies inhibit the growth of the cognitive assessment and training market. This restricts the accessibility of cognitive assessment and training solutions for many patients. Most insurance providers do not fully cover the costs of digital cognitive training programs, viewing them as optional wellness tools rather than essential medical treatments. According to sources, coverage for digital mental health apps and cognitive therapies remains inconsistent, with many health insurance plans excluding these digital health services from their standard benefits packages. This lack of financial support places the burden of cost on patients, who may find subscription fees prohibitive over the long term. Additionally, the high initial investment required for healthcare facilities to implement comprehensive cognitive assessment platforms limits their adoption in resource-constrained settings. Small clinics and rural hospitals often lack the budget to purchase advanced software and train staff on its use. The out-of-pocket expense discourages continuous usage, which is critical for achieving therapeutic benefits. Without consistent revenue streams from reimbursements, developers face challenges in sustaining innovation and lowering prices. This financial disconnect between the proven clinical value of these tools and their payment models creates a significant barrier to entry. Thus, the limited affordability and reimbursement support constrain market expansion and prevent equitable access to cognitive health resources for broader populations.
MARKET OPPORTUNITIES
Expansion into Corporate Wellness and Occupational Health Programs
The rising focus on workplace well-being and productivity drives growth for the cognitive assessment and training market. This expansion is occurring explicitly within the global corporate sector. Companies are increasingly recognizing that cognitive fitness is crucial for maintaining high performance, reducing errors, and preventing burnout among workers. According to the World Health Organization, an estimated 12 billion working days are lost every year to depression and anxiety. Cognitive training programs can help employees enhance focus, memory, and decision-making skills, leading to improved job performance and reduced absenteeism. Furthermore, as per a study by the Society for Human Resource Management Foundation, 78% of employers indicate they offer or plan to offer mental health benefits, while 68% of HR professionals wish to integrate mental health and resiliency workshops into their schedules. The trend drives demand for enterprise-level platforms that can assess and train large workforces efficiently. Corporations are willing to invest in these solutions as part of their talent retention and development strategies. The ability to provide scalable, data-driven insights into employee cognitive health allows companies to tailor interventions and measure return on investment. Partnerships between cognitive tech providers and corporate wellness platforms create new distribution channels and revenue streams. Hence, the corporate sector represents a lucrative and expanding market for cognitive assessment and training solutions beyond traditional clinical settings.
Advancements in Artificial Intelligence and Personalized Medicine
The integration of artificial intelligence and machine learning technologies opens new pathways for enhancing the precision and effectiveness of cognitive assessment and training in the global market. AI algorithms can analyze vast amounts of user data to identify subtle patterns in cognitive performance that human observers might miss. According to studies, artificial intelligence-driven diagnostic systems have shown the ability to predict or detect signs of early-stage dementia significantly earlier and with high diagnostic precision compared to standard, standalone screening methods. The enhanced accuracy allows for more targeted and personalized training interventions that address specific cognitive deficits. Furthermore, machine learning models can adapt training difficulty in real time based on individual progress, ensuring optimal engagement and therapeutic benefit. This level of personalization increases user adherence and improves long term outcomes. The ability to predict cognitive decline trajectories enables proactive interventions before significant impairment occurs. Developers are leveraging these technologies to create dynamic platforms that evolve with the user’s needs. The combination of big data analytics and neuroscience provides deeper insights into brain plasticity and recovery mechanisms. Therefore, the application of AI in cognitive health opens new avenues for innovation, enabling the development of highly effective, personalized digital therapeutics that can revolutionize patient care and prevention strategies.
MARKET CHALLENGES
Data Privacy and Security Concerns
The handling of sensitive neurological and personal data is a major challenge to the cognitive assessment and training market. This is due to stringent privacy regulations and security risks. Cognitive assessments generate detailed profiles of an individual’s mental capabilities, which are highly sensitive and vulnerable to misuse if breached. According to the General Data Protection Regulation in Europe, strict requirements are imposed on the collection and processing of health data, requiring robust encryption and explicit consent mechanisms. Non-compliance can result in severe penalties and loss of consumer trust. Additionally, as per the HIPAA Journal, cyberattacks on healthcare organizations globally increased by 45% in November and December of 2020 compared to the previous month. Patients are often concerned about how their cognitive data is stored, shared, and used by third parties. Ensuring end-to-end security while maintaining usability is technically complex and costly for developers. Any data breach can have devastating consequences for users, including discrimination in employment or insurance. Consequently, maintaining the highest standards of data privacy and security is critical but challenging, requiring continuous investment in cybersecurity infrastructure and transparent data governance policies to protect user trust and comply with evolving legal frameworks.
User Adherence and Engagement Drop-off
Maintaining long-term user adherence and engagement remains a serious hurdle for platforms in the cognitive assessment and training market. This limits their clinical effectiveness. Cognitive training requires consistent and prolonged practice to yield measurable benefits, yet many users discontinue usage after the initial novelty wears off. According to the Journal of Medical Internet Research, dropout rates for digital health interventions can exceed 50% within the first few weeks of use. This lack of sustained engagement prevents users from achieving the necessary dosage of training to induce neuroplastic changes. Gamification elements are often employed to boost motivation, but their effectiveness varies widely among different demographic groups. Older adults, who are primary beneficiaries, may find complex digital interfaces frustrating or difficult to navigate. Additionally, the lack of immediate visible results can discourage continued use. Healthcare providers struggle to monitor adherence remotely and intervene when users drop off. The challenge is compounded by the need to balance therapeutic rigor with user-friendly design. Without high adherence rates, the clinical validity of these tools is compromised, making it difficult to demonstrate value to payers and providers. Thus, improving user retention through intuitive design, social support, and personalized feedback is a critical hurdle that developers must overcome to ensure the real-world impact of cognitive training solutions.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Assessment Type, Component, Application, Vertical, and Region. |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Cambridge Cognition Ltd., Cogstate Ltd., MedAvante Inc., ProPhase LLC, Neurocog Trials Inc., Pearson Clinical Assessment, Quest Diagnostics Inc., ProPhase LLC, Eresearchtechnology Inc., CogniFit, and Gompf Brackets Inc. |
SEGMENTAL ANALYSIS
By Assessment Type Insights
The hosted assessments segment dominated the Cognitive Assessment and Training Market and accounted for a substantial share in 2025. This dominance of the segment was driven by its unparalleled ability to deliver standardized testing across geographically dispersed populations without physical infrastructure constraints. The shift toward telehealth and remote monitoring has made cloud-based platforms the default choice for clinicians and researchers seeking efficient data collection. According to studies, healthcare providers are increasingly deploying virtual care and digital applications to facilitate clinical intake and patient evaluations, supporting a growing demand for hosted assessment systems that integrate with electronic health records. This widespread adoption is further fueled by the need for large-scale normative data collection, which is only feasible through centralized cloud architectures. Additionally, as per sources, using remote digital platforms for cognitive monitoring and brain health screeners can mitigate long-term dropout rates and support patient engagement profiles within ongoing clinical aging studies. This underscores the critical role of hosted solutions in maintaining research continuity and reducing dropout rates. Healthcare systems prefer these platforms because they eliminate the logistical burdens of scheduling physical appointments and managing paper records. The ability to update test batteries instantly ensures all users access the latest validated protocols simultaneously. Hence, the operational efficiency and scalability of hosted assessments sustain their market leadership as digital health becomes entrenched in standard care pathways.
The superior standardization and data integrity offered by hosted assessments reinforce their dominant position over traditional pen and paper methods in the cognitive evaluation landscape. Digital platforms automatically enforce testing protocols, eliminating administrator bias and scoring errors that frequently plague manual assessments. According to research, transitioning from manual testing to standardized, computerized cognitive tools reduces procedural administration variability to ensure highly comparable datasets across separate research sites. This level of precision is essential for clinical trials and multi-center research where data consistency determines regulatory approval. Furthermore, as per studies, hosted databases and centralized data systems improve accuracy and lower transcription or clerical data entry errors within multi-center clinical studies compared to legacy manual recording. This dramatic improvement in data quality accelerates analysis timelines and enhances the reliability of study outcomes. Researchers and clinicians value the automated reporting features that provide immediate feedback and longitudinal tracking capabilities. The security protocols embedded in reputable hosted platforms also address growing concerns about patient privacy and data protection compliance. As regulatory bodies increasingly demand rigorous evidence of test validity and reliability, the inherent standardization of hosted solutions makes them the preferred modality. This technical superiority ensures continued dominance as the market matures toward evidence-based digital diagnostics.
The biometrics assessment segment is anticipated to witness the fastest CAGR of 18.5% from 2026 to 2034. Stakeholders are seeking objective physiological markers to complement subjective behavioral testing. Traditional cognitive tests rely heavily on self-report and performance metrics, which can be influenced by motivation, fatigue, or cultural factors. Biometric modalities such as eye tracking, electroencephalography, and voice analysis provide direct windows into neural processing that bypass these confounding variables. According to sources, integrating biological markers such as plasma or neuroimaging indices alongside standard cognitive screening protocols enhances the diagnostic accuracy and tracking capability for early-stage mild cognitive impairment. This enhanced precision drives demand from pharmaceutical companies and research institutions developing targeted therapeutics. Additionally, as per research, financial backing for digital health innovations and digital biomarker validation platforms has grown significantly to support early neurodegenerative disease intervention solutions. The non-invasive nature of modern biometric sensors makes them suitable for repeated measurements in naturalistic settings. Clinicians appreciate the ability to detect subtle neurological changes before they manifest as overt cognitive deficits. This predictive capability aligns perfectly with the shift toward preventive medicine and early intervention strategies. Therefore, the convergence of sensor technology and neuroscience fuels exceptional growth in biometric assessments as they promise more reliable and actionable insights into brain health.
The miniaturization of biosensors and their integration into consumer wearable devices accelerate the adoption of biometric cognitive assessments beyond specialized laboratory settings. Smartwatches, headbands, and mobile peripherals now capture high-fidelity physiological data that was previously restricted to clinical environments. According to sources, a significant percentage of adults across developed markets own and wear personal smart devices capable of capturing real-time physiological metrics related to general wellness. This massive installed base creates an immediate distribution channel for biometric assessment applications. Furthermore, as per research, consumer-oriented sensor configurations and portable electroencephalogram (EEG) technologies have achieved higher signal alignment with clinical-grade systems when evaluating specific neural markers. This validation bridges the gap between research tools and everyday wellness products. Developers leverage existing hardware ecosystems to reduce barriers to entry and lower costs for end users. The continuous passive data collection enabled by wearables provides richer datasets than episodic clinic visits. This ecological momentary assessment approach captures cognitive fluctuations in real-world contexts. As algorithms improve at extracting cognitive insights from noisy consumer sensor data, the utility of these platforms expands rapidly. Consequently, the democratization of biometric sensing technology drives the fastest-growing segment by making advanced cognitive monitoring accessible to mainstream populations.
By Component Insights
In 2025, the solutions segment held the majority share in the Cognitive Assessment and Training Market because it represents the primary value delivery mechanism that customers purchase and utilize daily. Software platforms and licensed applications form the foundation upon which all cognitive interventions are built and delivered. According to research, software licensing and subscription fees constitute a substantial portion of recurring revenue for solutions vendors in the digital health sector compared to variable consulting services. This revenue concentration reflects the central role of solutions in meeting end-user needs. Healthcare providers and educational institutions prioritize acquiring robust, validated platforms that can be deployed immediately to serve patients or students. Additionally, as per studies, vendors offering holistic, software-driven solutions achieve higher customer retention profiles than providers delivering isolated tech support or specialized medical consulting services. This stickiness arises because the software becomes embedded in clinical workflows or learning curricula. The scalability of software solutions allows vendors to serve millions of users without proportional cost increases. Continuous updates and feature enhancements keep the product relevant and valuable over time. Customers view the solution as a capital asset that generates ongoing returns through improved outcomes. Consequently, the intrinsic utility and recurring value of software solutions ensure their dominance as the primary market component.
The substantial investment required to obtain regulatory clearance and clinical validation for cognitive solutions creates high barriers to entry that protect leading solution providers. Achieving Food and Drug Administration clearance or CE marking requires years of rigorous testing and significant financial commitment that few new entrants can sustain. As per sources, designing, clinically evaluating, and securing regulatory authorization for a Class II medical software application or digital therapeutic presents significant commercial infrastructure and development costs. This capital intensity consolidates market share among established players with deep pockets. Furthermore, according to research, evidence-based digital therapeutics that have undergone rigorous clinical trial testing command stronger market positioning and premium pricing over alternative wellness applications lacking validation. Payers and providers are willing to pay more for solutions with proven efficacy and regulatory backing. The extensive clinical data generated during validation also serves as a competitive moat that is difficult to replicate. Vendors leverage their regulatory status to secure formulary placements and reimbursement codes. This institutional endorsement reinforces market leadership. As regulations tighten globally, the advantage of having cleared solutions grows stronger. Consequently, the regulatory and validation assets associated with leading solutions cement their dominant position by creating sustainable competitive advantages that pure service providers cannot match.
The services segment is on the rise and is expected to be the fastest-growing segment in the market, witnessing a CAGR of 16.2% during the forecast period. Organizations require specialized expertise to successfully implement and optimize complex digital solutions. Purchasing software is only the first step; realizing its full value requires configuration, training, integration, and ongoing support. According to studies, a large portion of operational digital health implementation failures are driven by corporate change management challenges and insufficient end-user training workflows rather than baseline software errors. This statistic drives demand for professional services that ensure successful adoption. Additionally, as per sources, implementing comprehensive training architectures alongside new corporate health software deployments supports workforce adoption metrics and tool utilization rates. Service providers fill critical gaps in client capabilities, enabling them to extract maximum value from their software investments. The complexity of integrating cognitive tools with existing electronic health records and learning management systems necessitates specialized technical services. As solutions become more sophisticated, the need for expert guidance increases proportionally. Vendors are expanding service offerings to create recurring revenue streams beyond software licenses. Consequently, the essential role of services in bridging the gap between technology purchase and realized outcomes fuels their rapid expansion as the market matures.
The increasing demand for customized and personalized cognitive interventions drives exceptional growth in the services segment as off-the-shelf solutions often fail to meet specific organizational or patient needs. Different clinical populations, educational contexts, and corporate environments require tailored protocols and content adaptations. According to research, a substantial proportion of institutional medical purchasers look for system configuration and custom operational services when integrating novel screening applications into their clinics. This preference reflects the recognition that one-size-fits-all approaches yield suboptimal outcomes. Furthermore, as per studies, adaptive cognitive training systems configured to an individual patient's specific baseline performance metrics demonstrate improved clinical efficacy relative to standardized, non-adaptive training models. Service providers possess the domain expertise to adapt solutions while maintaining scientific validity. They conduct needs assessments, modify content libraries, and configure adaptive algorithms to match specific user profiles. The consulting aspect of these services helps organizations align cognitive programs with strategic objectives. As evidence mounts for personalized approaches, demand for expert customization grows. Vendors respond by building dedicated professional services teams and partner ecosystems. Consequently, the shift toward precision cognitive health creates sustained demand for high-value services that transform generic software into targeted interventions, driving the fastest growth in this component segment.
By Application Insights
The clinical trials segment led the Cognitive Assessment and Training Market and captured a significant share in 2025. This leading position of the segment was attributed to massive pharmaceutical industry investment in neurodegenerative disease drug development. Sponsors require sensitive, reliable cognitive endpoints to demonstrate therapeutic efficacy in Alzheimer’s, Parkinson’s, and other CNS disorders. According to PhRMA, its member companies invested $102.3 billion in R&D in 2021, and its members' spending accounted for most of the estimated $122.2 billion spent by the entire U.S. biopharmaceutical industry on R&D in 2020. This enormous funding flows directly to cognitive assessment vendors providing validated trial endpoints. Additionally, as per research, standardized cognitive assessments serve as key metrics across a broad percentage of Phase III clinical trials investigating potential therapeutics for dementia and Alzheimer's disease. This ubiquity makes cognitive testing indispensable infrastructure for drug development. The high stakes of clinical trials justify premium pricing for validated, regulatory-accepted assessment tools. Sponsors prioritize vendors with established track records and global deployment capabilities. The need for centralized data management and real-time monitoring further entrenches leading platforms. As the pipeline of CNS drugs expands, so does demand for cognitive assessment services. Consequently, the deep integration of cognitive testing into pharmaceutical R&D sustains its market leadership through consistent, high-value contracts that are relatively insulated from economic downturns.
The stringent regulatory requirements for cognitive endpoints in clinical trials reinforce the dominance of this application segment by favoring established, validated assessment platforms. Regulatory agencies like the Food and Drug Administration and European Medicines Agency demand rigorous evidence of endpoint sensitivity, reliability, and clinical meaningfulness. According to studies, using uniform cognitive testing standards and qualified assessment tools supports regulatory review pathways for central nervous system drug approvals. This regulatory gatekeeping creates a strong preference for vendors whose tools have prior acceptance history. Furthermore, as per sources, utilizing validated and qualified cognitive endpoints assists in capturing accurate therapeutic data during clinical trial evaluations for neurodegenerative diseases. Sponsors are unwilling to jeopardize billion-dollar drug programs by experimenting with unproven assessment methods. The extensive documentation and audit trails provided by leading platforms satisfy regulatory scrutiny. Vendors invest heavily in maintaining qualification status and updating norms. This regulatory moat protects incumbents from disruption. As guidelines evolve, established vendors adapt quickly while new entrants face lengthy qualification processes. Consequently, the regulatory ecosystem around clinical trial endpoints creates a stable, high-barrier market where validated solutions maintain dominance through compliance excellence and historical precedent.
The corporate learning segment is likely to experience the fastest CAGR of 19.3% between 2026 and 2034. This growth occurs as organizations recognize cognitive fitness as a critical driver of productivity and innovation. In knowledge-intensive economies, employee cognitive performance directly impacts business outcomes. According to the World Economic Forum's Future of Jobs Report, 50% of all employees will need reskilling by 2025 as the adoption of technology increases. This workforce transformation drives corporate investment in cognitive training programs. Additionally, as per sources, a significant percentage of international enterprise organizations have integrated cognitive skill development pathways and adaptive thinking benchmarks into their workplace learning systems. Companies view cognitive training as essential for maintaining competitive advantage in rapidly changing markets. The measurable ROI of improved focus, decision-making, and problem-solving justifies budget allocation. Unlike clinical applications constrained by reimbursement, corporate spending is discretionary and responsive to business needs. The scalability of digital platforms enables enterprise-wide deployment. Vendors are developing B2B specific products with analytics dashboards for HR leaders. As remote work increases, the importance of self-directed learning, and demand grows. Consequently, the alignment of cognitive training with strategic workforce development initiatives fuels exceptional growth in this non-clinical application segment.
The integration of cognitive training with broader talent management and performance systems accelerates growth in the corporate learning segment by embedding cognitive development into existing HR workflows. Organizations prefer solutions that connect seamlessly with learning management systems, performance reviews, and career development platforms. According to research, consolidated learning software systems yield increased user completion and employee engagement rates compared to disconnected, standalone training applications. This interoperability reduces friction and increases program participation. Furthermore, as per studies, modern organizational talent strategies increasingly utilize cognitive ability data to guide workforce succession mapping and promotional reviews. This institutionalization transforms cognitive training from an optional perk to a core talent strategy. Vendors respond by building APIs and pre-configured integrations with major HR tech platforms. The data generated feeds into people analytics, demonstrating correlation between cognitive fitness and business KPIs. This evidence-based approach secures executive sponsorship and budget continuity. As organizations adopt skills-based operating models, cognitive capabilities become quantifiable assets. Consequently, the convergence of cognitive science and human capital management creates powerful tailwinds for corporate learning applications, driving the fastest growth as cognitive training becomes embedded in organizational DNA.
By Vertical Insights
The healthcare segment remained the largest in 2025 and occupied a commanding share of the cognitive assessment and training market. This supremacy of the segment was supported by the fundamental clinical necessity of cognitive evaluation in diagnosing and managing neurological conditions. Cognitive impairment is a core symptom across numerous diseases requiring systematic assessment. According to a Government Accountability Office (GAO) report, utilization of Medicare’s "cognitive assessment and care plan services" tripled between 2018 and 2022, but the actual volume remains heavily underutilized, with a maximum of only 2.4% of eligible traditional beneficiaries receiving the dedicated service. This reflects entrenched clinical practice patterns. Additionally, as per research, standard brief cognitive diagnostic batteries and structured tools are widely recommended by professional groups for assessing symptoms of cognitive decline. This professional consensus creates non-discretionary demand. The aging population ensures sustained patient volumes. Reimbursement coverage for cognitive screening under Medicare and private insurance provides stable revenue streams. Healthcare systems integrate cognitive tools into routine primary care and specialty clinics. The regulatory pathway for medical devices is well established in this vertical. Vendors prioritize healthcare due to higher willingness to pay and longer contract cycles. Clinical validation requirements create barriers that protect incumbents. As value-based care emphasizes outcomes measurement, cognitive metrics gain importance. Consequently, the combination of clinical mandate, demographic trends, and payment infrastructure sustains healthcare’s market leadership despite slower growth rates compared to emerging verticals.
The unprecedented aging of global populations and rising burden of chronic neurological diseases fundamentally anchor healthcare as the leading vertical for cognitive assessment and training. Demographic shifts create structural demand that transcends economic cycles. According to the United Nations Population Division, the global population aged 65 years and older is projected to reach 1.6 billion by 2050. This cohort carries an exponentially higher risk of cognitive disorders. Additionally, as per a study supported by the World Health Organization, neurological conditions have risen to become the leading cause of overall ill health and disability globally, accounting for over 440 million disability-adjusted life years (DALYs) in 2021. This disease burden necessitates systematic cognitive monitoring and intervention. Healthcare systems bear primary responsibility for managing this population health challenge. Government initiatives targeting dementia prevention allocate substantial funding to cognitive health programs. The chronic nature of cognitive conditions requires long term engagement with assessment and training tools. Unlike episodic acute care, cognitive health involves continuous relationships. This lifetime value per patient supports sustainable business models. Public health campaigns increase awareness and screening uptake. Consequently, the inexorable demographic and epidemiological trends ensure healthcare remains the foundational vertical, providing stable base load demand that supports innovation and market maturation across all segments.
The business vertical segment is expected to exhibit a noteworthy CAGR of 20.1% over the forecast period. This expansion is anticipated as organizations increasingly recognize cognitive capabilities as strategic capital rather than soft skills. In the knowledge economy, employee cognitive performance directly correlates with innovation, decision quality, and adaptability. According to sources, rapid implementation of advanced reasoning models and agentic AI systems has made close to 60 percent of current workforce hours theoretically automatable. This economic reality drives corporate investment in cognitive optimization. Additionally, as per research, enterprise upskilling programs targeting advanced intellectual frameworks help optimize institutional performance. This performance linkage justifies significant budget allocation. Unlike healthcare constrained by reimbursement cycles, business spending responds dynamically to competitive pressures. The talent war intensifies focus on cognitive differentiation. Organizations use cognitive assessments for hiring, development, and team composition. Training programs target executive function, creativity, and resilience. The measurable impact on KPIs enables clear ROI demonstration. Vendors develop enterprise-grade platforms with business-specific analytics. As automation handles routine tasks, uniquely human cognitive skills gain premium value. Consequently, the reframing of cognition as business-critical infrastructure fuels exceptional growth in this vertical.
The integration of cognitive assessment into leadership development and succession planning accelerates growth in the business vertical as organizations seek data-driven approaches to talent management. Traditional leadership selection relies heavily on subjective judgment and past performance, which poorly predicts future potential in volatile environments. Cognitive assessments provide objective measures of learning agility, strategic thinking, and decision-making under uncertainty. According to sources, structured behavioral assessments are heavily used by enterprise firms to identify executive leadership tracks. The adoption reflects recognition that cognitive capacity determines leadership ceiling. Additionally, as per research, verifying candidate problem-solving skills supports professional placement accuracy. The predictive validity drives procurement decisions. Organizations use cognitive training to develop next-generation leaders systematically. The alignment with succession planning ensures sustained engagement beyond initial assessment. Executive coaching integrates cognitive insights for personalized development. Board-level interest in leadership pipeline quality secures budget approval. As business complexity increases, the premium on cognitive leadership grows. Consequently, the institutionalization of cognitive science in talent strategy creates powerful, self-reinforcing growth dynamics in the business vertical.
REGIONAL ANALYSIS
North America Cognitive Assessment and Training Market Analysis
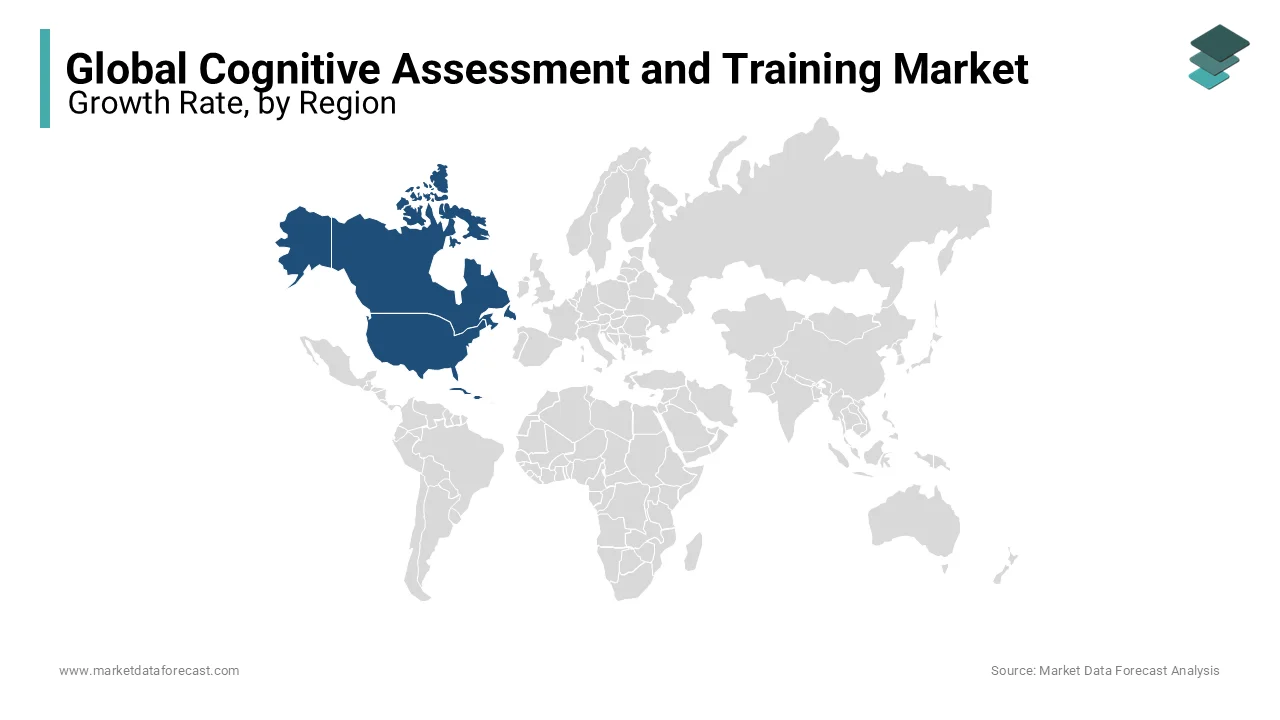
North America was the top performer in the Cognitive Assessment and Training Market and accounted for a substantial share in 2025. This dominance of the North American market was driven by advanced healthcare infrastructure, strong regulatory frameworks, and high digital health adoption. The region's revenue supremacy is primarily attributable to the rapid clinical deployment of cognitive systems and favorable reimbursement policies. According to data from the Centers for Medicare & Medicaid Services (CMS) analyzed by the Kaiser Family Foundation, Medicare provides coverage to more than 65 million beneficiaries nationwide, under which coverage for annual wellness visits, cognitive assessments, and care planning services are made available. This policy support creates predictable demand. Additionally, as per the National Institutes of Health (NIH) Research, Condition, and Disease Categorization (RCDC) retrospective reporting system, the actual research funding recorded for the Neurosciences category in FY 2023 was $11.87 billion, while the dedicated budget for the NIH BRAIN Initiative in FY 2023 was $680 million (comprising $230 million in base funding and $450 million via the 21st Century Cures Act). The presence of leading technology companies and academic medical centers fosters innovation. High awareness of cognitive health among consumers drives direct-to-consumer adoption. Corporate wellness programs are most mature in this region. Venture capital investment in digital cognitive health remains concentrated here. Regulatory clarity from the Food and Drug Administration reduces commercialization risk. The aging baby boomer population ensures sustained clinical demand. Consequently, North America’s combination of payment infrastructure, research funding, and technological maturity sustains its market leadership while setting global standards for validation and best practices.
Europe Cognitive Assessment and Training Market Analysis
Europe was positioned second in the Cognitive Assessment and Training Market and captured a significant share in 2025. This position of the European market was propelled by strong public healthcare systems, rigorous regulatory standards, and growing digital health initiatives. The region demonstrates high adoption in clinical research and public health screening programs supported by government funding. According to the European Commission, the European Partnership for Brain Health (EP BrainHealth) under the Horizon Europe framework was launched with an estimated total co-funded budget of approximately 500 million Euros. This investment drives development and validation of cognitive tools. Additionally, as per sources, pan-European patient advocacy networks actively lobby member states to establish unified national dementia strategies that incorporate standardized early cognitive screening. The policy alignment creates standardized demand across diverse healthcare systems. The General Data Protection Regulation shapes product development toward privacy by design. Public payer systems enable broad population access once tools are approved. Academic collaborations are extensive. The aging population mirrors North American demographics. However, fragmented national markets and varying reimbursement policies slow uniform adoption. Digital health infrastructure varies significantly between Western and Eastern Europe. Despite these challenges, Europe’s strong research base and public health orientation sustain its significant market position. Consequently, Europe represents a mature but complex market where regulatory compliance and public sector partnerships are key success factors.
Asia Pacific Cognitive Assessment and Training Market Analysis
Asia Pacific is rapidly expanding within the cognitive assessment and training market because of fast digitalization, large aging populations, and increasing healthcare investment. Countries like Japan, China, South Korea, and Australia are aggressively adopting digital cognitive health solutions to address demographic challenges. According to the Asian Development Bank, the population of older persons aged 60 and above across Asia and the Pacific is projected to triple between 2010 and 2050 to reach close to 1.3 billion people. This demographic tsunami creates urgent demand for scalable cognitive interventions. Additionally, as per studies, the Japanese government allocates substantial annual budgetary resources toward long-term care and proactive medical monitoring frameworks to address age-related cognitive decline. Government initiatives accelerate market development. High smartphone penetration enables mobile-first cognitive health solutions. Cultural acceptance of technology facilitates adoption. Private healthcare sectors in India and Southeast Asia are expanding rapidly. However, regulatory frameworks remain nascent in many countries. Reimbursement pathways are limited outside developed markets. Language and cultural adaptation requirements increase localization costs. Despite these barriers, the sheer scale of unmet need and government commitment drive exceptional growth. Consequently, Asia Pacific offers the highest growth potential as digital cognitive health solutions address massive demographic challenges at unprecedented scale.
Latin America Cognitive Assessment and Training Market Analysis
Latin America is an emerging player within the Cognitive Assessment and Training Market due to growing awareness, expanding private healthcare, and increasing digital connectivity. Brazil, Mexico, Chile, and Colombia lead regional adoption driven by urban middle-class demand and private hospital networks. According to research, the reported burden and prevalence of chronic noncommunicable and neurodegenerative diseases across the Americas have steadily trended upward over recent decades. This rising disease burden creates clinical demand. As per studies, international regional development banks allocate targeted loan and grant funding to modernize digital infrastructure, telecommunications, and clinical systems throughout Latin America. This funding improves foundational capacity for cognitive tool deployment. Private insurers begin covering cognitive assessments in select markets. Mobile health adoption is high due to smartphone penetration. Academic institutions conduct local validation studies. However, public healthcare systems remain underfunded. Regulatory pathways are unclear in most countries. Economic volatility affects discretionary spending. Language localization for Portuguese and Spanish is essential. Despite challenges, the region’s young, tech-savvy population and growing chronic disease burden create long-term opportunity. Consequently, Latin America represents a nascent but promising market where private sector leadership and mobile-first strategies drive initial adoption.
Middle East and Africa Cognitive Assessment and Training Market Analysis
The Middle East and Africa region is a developing frontier in the cognitive assessment and training market. Gulf Cooperation Council countries show advanced adoption, while sub-Saharan Africa remains nascent. Wealthy Gulf nations invest heavily in healthcare modernization and digital health as part of economic diversification strategies. According to official Saudi Vision 2030 Health Sector Transformation Program announcements, the kingdom allocated over 65 billion dollars (approx. SAR 250 billion) to its comprehensive national healthcare restructuring and privatization program through 2030, which spans whole-system infrastructure rather than digital cognitive health alone. The government-led investment creates immediate market opportunities. As per studies, millions of individuals across the African continent live with neurological conditions, with significant treatment gaps remaining due to limited specialized healthcare personnel and clinical screening resources. This massive treatment gap represents long-term potential. South Africa and Nigeria show emerging private sector interest. Mobile health platforms offer leapfrog opportunities. However, infrastructure limitations, low health literacy, and funding constraints severely limit current adoption. Regulatory frameworks are largely absent. Cultural stigma around cognitive disorders persists. International NGOs and development agencies fund pilot programs. Despite current limitations, demographic trends and government commitments in key markets suggest future growth. Consequently, the Middle East and Africa region presents a bifurcated opportunity set where wealthy Gulf states offer near-term commercial prospects while broader African markets require long term development approaches focused on accessibility and affordability.
COMPETITIVE LANDSCAPE
The competition in the Cognitive Assessment and Training Market is characterized by a mix of established psychometric publishers and agile digital health startups striving to offer validated and engaging solutions. Major players leverage their extensive libraries of standardized tests and strong relationships with clinical professionals to maintain dominance in the healthcare sector. These vendors compete on the basis of scientific rigor, regulatory compliance, and integration capabilities with electronic health records. Smaller niche firms differentiate themselves by offering innovative gamified experiences and mobile-first designs that appeal to direct consumers and corporate clients. The market sees frequent collaborations between technology providers and neuroscience researchers to enhance product validity and expand clinical indications. Strategic alliances with pharmaceutical companies are crucial for securing long term contracts in the clinical trials segment. Customer retention relies heavily on demonstrating measurable cognitive improvements and high user adherence rates. Price competition is moderate in the clinical sector due to the high value placed on validated diagnostics but intensifies in the consumer wellness segment where many free or low-cost alternatives exist. The entry of new competitors with advanced artificial intelligence capabilities challenges traditional vendors to accelerate their digital transformation efforts. Overall, the competitive landscape drives continuous innovation in assessment accuracy and training effectiveness, ensuring robust options for diverse user needs across healthcare education and business sectors.
KEY MARKET PLAYERS
The leading companies operating in the global cognitive assessment and training market include:
- Cambridge Cognition Ltd.
- Cogstate Ltd.
- MedAvante Inc.
- ProPhase LLC
- NeuroCog Trials Inc.
- Pearson Clinical Assessment
- Quest Diagnostics Inc.
- eResearchTechnology Inc.
- CogniFit
- Gompf Brackets Inc.
TOP PLAYERS IN THE MARKET
- Pearson Clinical Assessment significantly contributes to the Cognitive Assessment and Training Market by providing gold-standard psychometric tools that are widely recognized for their reliability and validity in clinical settings. The company leverages its extensive library of established cognitive tests such as the WAIS and WMS to maintain a dominant position among healthcare professionals. Recent actions include the digital transformation of its flagship assessments into secure cloud-based platforms that enable remote administration and automated scoring. This strategic shift allows clinicians to conduct evaluations efficiently while maintaining strict data security standards required by healthcare regulations. Pearson actively collaborates with research institutions to continuously validate its digital tools against traditional methods, ensuring ongoing clinical relevance. The company also invests heavily in training programs for psychologists and neuropsychologists to ensure proper interpretation of complex cognitive data. By combining legacy trust with modern technology, Pearson strengthens its market position as an essential partner for accurate diagnostic evaluation. Their focus on evidence-based practice ensures that healthcare providers rely on their solutions for critical decision-making processes regarding patient care and treatment planning.
- CogniFit plays a pivotal role in the Cognitive Assessment and Training Market by offering scientifically validated digital platforms designed for both individual users and healthcare professionals. The company specializes in brain training programs that target specific cognitive domains such as memory, attention, and processing speed using adaptive algorithms. Recent efforts involve expanding its B2B offerings to corporate wellness programs and educational institutions, thereby diversifying its revenue streams beyond clinical settings. CogniFit actively partners with universities and research centers to publish peer-reviewed studies demonstrating the efficacy of its training protocols. This commitment to scientific rigor builds trust among medical practitioners who prescribe their solutions for patients with mild cognitive impairment. The platform utilizes gamification elements to enhance user engagement and adherence, which is critical for long term therapeutic success. CogniFit also integrates with wearable devices to provide holistic insights into brain health. By focusing on accessibility and personalization, the company enables widespread adoption of cognitive training tools. Their continuous innovation in algorithm design ensures that training difficulty adjusts dynamically to user performance, maximizing cognitive benefits.
- Cambridge Cognition strengthens its presence in the Cognitive Assessment and Training Market through its specialized focus on high-precision digital endpoints for pharmaceutical clinical trials. The company provides sensitive and reliable cognitive testing batteries that are essential for measuring drug efficacy in neurodegenerative diseases such as Alzheimer’s and Parkinson’s. Recent actions include the development of fully remote assessment capabilities that allow participants to complete tests at home, reducing burden and improving recruitment rates. Cambridge Cognition actively collaborates with major pharmaceutical companies to tailor assessment protocols for specific therapeutic targets, ensuring regulatory acceptance. The company emphasizes data quality and standardization, which are critical for successful trial outcomes and regulatory approval. Their platform supports multiple languages and cultural adaptations, facilitating global multicenter trials. Cambridge Cognition also invests in advanced analytics tools that help researchers identify subtle cognitive changes earlier in the disease process. By positioning itself as a critical infrastructure provider for drug development, the company secures long-term contracts with industry leaders. Their expertise in regulatory science ensures that clients navigate complex approval pathways successfully.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the Cognitive Assessment and Training Market primarily employ strategic partnerships with academic and research institutions to validate their products and build scientific credibility. Companies frequently collaborate with universities to conduct randomized controlled trials that demonstrate clinical efficacy, which is essential for gaining trust from healthcare providers and regulators. This approach allows vendors to publish peer-reviewed evidence that supports marketing claims and facilitates reimbursement approvals. Another major strategy involves expanding into adjacent markets such as corporate wellness and education to diversify revenue sources beyond traditional clinical applications. Vendors develop tailored versions of their platforms for employee cognitive fitness and student learning enhancement, thereby accessing larger customer bases. Additionally, companies focus on integrating artificial intelligence and machine learning to personalize training protocols and improve user engagement. These technologies enable dynamic difficulty adjustment and predictive analytics that enhance therapeutic outcomes. Marketing efforts emphasize ease of use and remote accessibility to appeal to consumers seeking convenient mental health solutions. By combining scientific validation with technological innovation and market diversification, key participants effectively strengthen their competitive positions and drive sustainable growth in the evolving cognitive health landscape.
MARKET SEGMENTATION
This research report on the global cognitive assessment and training market has been segmented and sub-segmented based on the assessment type, component, application, vertical, and region.
By Assessment Type
-
Pen & Paper Based Assessment
-
Hosted Assessment
-
Biometrics Assessment
By Component
-
Solutions
-
Services.
By Application
-
Clinical Trials
-
Classroom Learning
-
Corporate Learning
-
Brain Training
-
Research
By Vertical
-
Education
-
Healthcare
-
Business
-
Sports
-
Defense
-
Pharmaceuticals
By Region
-
North America
-
The United States
-
Canada
-
Rest of North America
-
-
Europe
-
The United Kingdom
-
Spain
-
Germany
-
Italy
-
France
-
Rest of Europe
-
-
The Asia Pacific
-
India
-
Japan
-
China
-
Australia
-
Singapore
-
Malaysia
-
South Korea
-
New Zealand
-
Southeast Asia
-
-
Latin America
-
Brazil
-
Argentina
-
Mexico
-
Rest of LATAM
-
-
The Middle East and Africa
-
Saudi Arabia
-
UAE
-
Lebanon
-
Jordan
-
Cyprus
-