- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$399 MnMarket Estimate, 2026
$408.9 MnMarket Forecast, 2034
$498.3 MnCAGR, 2026–2034
2.50%Executive Summary: Converting Paper Market
- Market Scope: Comprehensive global converting paper market analysis covering application sectors, pulp types, regional leadership frameworks, bioeconomy solutions, and e-commerce packaging drivers.
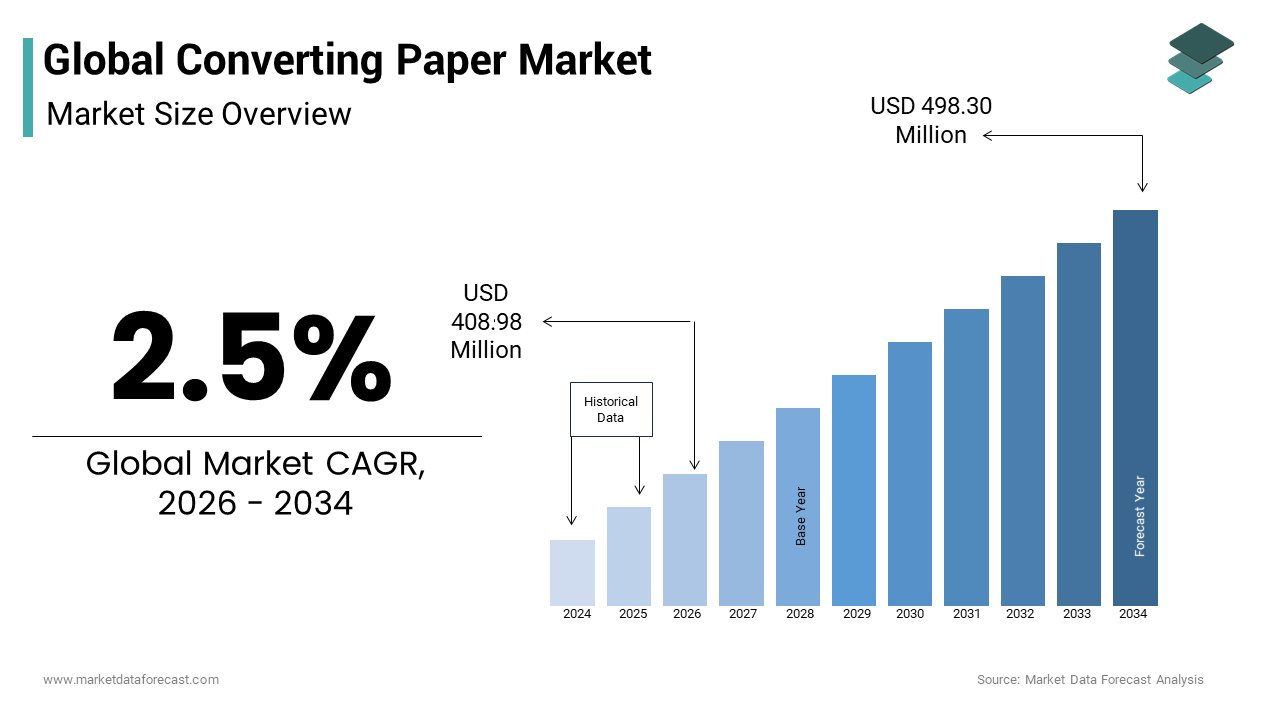
- Market Valuation: Valued at USD 399 million (2025), estimated at USD 408.98 million (2026), and projected to reach USD 498.30 million by 2034, registering a modest CAGR of 2.5% (2026–2034).
- Primary Growth Drivers: Rising demand for print media, increasing e-commerce penetration boosting cost-effective packaging, and growing usage of sanitary and tissue papers for personal hygiene.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (Position) | Fastest-Growing Segment |
|---|---|---|
| By Application | Packaging Sector (held the largest revenue share globally for carton, corrugated, and flexible paper) | Coated Paper & Tissue Products (experiencing significant growth due to enhanced durability and hygiene needs) |
| By Pulp Type | Chemical Wood Pulp (most common pulp type used in writing and printing sheets) | Bio-based Alternative Solutions (scaling up to support circular bioeconomy targets) |
| By Region | North America (predicted to lead the global market due to personal hygiene and tissue demand) | Asia Pacific (developing market driven by China and India's expanding packaging industries) |
Major Market Players & Market Structure
Market Structure: Competitive global paper and packaging landscape featuring major forestry and converting corporations focusing on resource efficiency, carbon reduction, and healthcare sector supply chain resilience.
Key Companies: Georgia-Pacific Corp, Weyerhaeuser Corp, Kimberly-Clark Corp, Stora Enso, UPM, SCA, BillerudKorsnäs, Oji Paper, Nippon Unipac Holding, Burgo Group, and Canfor Corp.
 Download Free Sample Report
Global Converting Paper Market Size
The global converting paper market size was valued at USD 399 million in 2025 and is anticipated to reach a valuation of USD 408.98 million in 2026 and USD 498.30 million by 2034, growing at a CAGR of 2.5% from 2026 to 2034.
The converting paper is the industrial processes that transform raw paper rolls into finished consumer and industrial products such as tissue packaging labels and specialized technical papers. The middle class in emerging countries has led to a 30% increase in demand for packaged goods over the last decade, which directly drives the need for converted paper packaging solutions. Furthermore, the United Nations Environment Programme states that single use plastics regulations in over 60 countries have accelerated the substitution of plastic items with paper based alternatives creating a structural shift in material preference. In the hygiene sector, the World Health Organization notes that improved sanitation access has increased global tissue consumption by 15% annually in developing regions.
MARKET DRIVERS
Surging E-Commerce Activities Drive Demand For Protective Paper Packaging
The exponential growth of online retail, particularly in the packaging segment is fuelling the growth of the converting paper market. As consumers increasingly shift from brick and mortar stores to digital platforms, the volume of shipped goods has skyrocketed necessitating robust and sustainable packaging solutions. According to the United Nations Conference on Trade and Development, global e-commerce sales reached 26.7 trillion dollars in recent years representing a significant portion of total retail transactions. This surge in parcel delivery creates an immense demand for corrugated boxes void fillers and protective wraps, which are predominantly made from converted paper products. As per the Environmental Protection Agency, corrugated cardboard accounts for nearly 80% of all packaging materials used in e-commerce shipments due to its durability and recyclability. Additionally, major retailers such as Amazon and Alibaba have committed to eliminating single use plastics from their supply chains by 2025, further accelerating the adoption of paper based alternatives like molded pulp inserts and paper tape.
Stringent Global Regulations On Single Use Plastics Accelerate Material Substitution
Governmental policies and international agreements aimed at reducing plastic pollution are compelling industries to replace synthetic materials with paper-based alternatives that is leveraging the growth of the converting paper market. Regulatory frameworks worldwide are imposing bans taxes and extended producer responsibility schemes on single use plastics, which directly benefits the Converting Paper Market. According to the European Commission, the Single Use Plastics Directive mandates a reduction in the consumption of specific plastic items by 50% by 2026, driving manufacturers to seek viable paper substitutes for items such as straws cutlery and food containers. In North America, several states in the United States and provinces in Canada have implemented strict bans on plastic bags and foam containers leading to a 40% increase in demand for paper shopping bags and food service wrappers, as noted by the Natural Resources Defense Council. Additionally, the circular economy principles embedded in these regulations favor paper due to its high recycling rates and biodegradability.
MARKET RESTRAINTS
Volatility In Raw Material Prices And Supply Chain Disruptions
The fluctuating costs of raw materials, particularly wood pulp and recycled fiber, which is hindering the growth of the converting paper market. Price instability in these inputs directly impacts profit margins and operational planning for converters who often operate on thin margins. According to the Forest Products Laboratory, global pulp prices have experienced volatility of up to 30% in recent years due to factors such as energy costs labor shortages and geopolitical tensions. Additionally, the availability of recycled fiber is inconsistent with the Institute of Scrap Iron and Steel reporting that contamination rates in recycled paper streams have increased by making processing more expensive and less efficient. Supply chain disruptions exacerbated by global logistics challenges further complicate procurement leading to delays and inventory shortages. The freight costs remain elevated compared to pre pandemic levels increasing the landed cost of imported pulp and finished paper rolls. These economic pressures force converters to frequently adjust pricing, which can strain customer relationships and reduce competitiveness against alternative materials.
Environmental Concerns Regarding Water And Energy Consumption In Processing
Despite being perceived as a sustainable alternative to plastic the paper converting industry faces scrutiny regarding its environmental footprint, particularly in terms of water and energy usage. The environmental concerns regarding water and energy consumption in processing is restricting the growth of the converting paper market. The conversion process involves various stages, including coating printing and drying, which require substantial resources and generate wastewater. According to the United Nations Industrial Development Organization, the paper industry is one of the largest industrial consumers of water accounting for approximately 9% of global industrial water withdrawals. This high water intensity raises concerns in regions facing water scarcity prompting stricter regulatory limits on discharge and usage. The paper mills and converting facilities must invest heavily in wastewater treatment technologies to meet compliance standards, which increases capital and operational expenditures. Additionally, the carbon footprint of the converting process is significant with the pulp and paper sector consumes about 6% of global industrial energy. These environmental challenges necessitate continuous investment in cleaner technologies and efficiency improvements, which can be financially burdensome for smaller converters limiting their ability to compete in an increasingly eco-conscious cosnumers.
MARKET OPPORTUNITIES
Expansion Of Bio Based And Compostable Paper Products Creates New Verticals
The development of advanced bio based and compostable paper products by addressing the demand for fully sustainable packaging solutions is creating new opportunities for the growth of the converting paper market. Innovations in barrier coatings and material science now allow paper to replace plastic in applications previously considered impossible such as liquid packaging and grease resistant food wrappers. Converters are increasingly adopting water based and plant derived coatings that maintain the recyclability and compostability of paper products, while providing necessary functionality. The new barrier technologies can extend the shelf life of fresh produce using paper based wraps reducing food waste, while maintaining sustainability. Additionally, the rise of home composting initiatives has created demand for certified compostable paper products that break down safely in domestic environments. The Compost Manufacturing Alliance reports that the number of certified compostable paper products has doubled in the last three years indicating strong market acceptance. Brands are leveraging these innovations to enhance their sustainability credentials appealing to environmentally conscious consumers.
Growth In Hygiene And Healthcare Sectors Drives Demand For Specialized Tissue Products
The expanding hygiene and healthcare sectors through increased demand for specialized tissue and medical paper products that is also to level up new opportunities for the growth of the converting paper market. Rising health awareness and aging populations in developed and developing nations are driving consistent growth in the consumption of facial tissues toilet paper and medical wipes. The global access to basic sanitation services has improved significantly with billions of people gaining access to improved toilets, which directly increases tissue consumption. The United Nations Department of Economic and Social Affairs projects that the global population aged 65 and older will double by 2050 leading to higher demand for adult incontinence products and medical hygiene papers. Additionally, the post pandemic era has instilled lasting habits of enhanced personal hygiene with the Centers for Disease Control and Prevention reporting a permanent increase in the use of disposable hygiene products. Converters are responding by developing ultra soft strong and hypoallergenic tissue products that meet the specific needs of sensitive skin and medical applications.
MARKET CHALLENGES
Complexity Of Recycling Infrastructure Limits Closed Loop Efficiency
The effectiveness of paper recycling is hindered by the complexity and inconsistency of global recycling infrastructure, which poses a significant challenge for the growth of the converting paper market. While paper is highly recyclable, the presence of mixed materials such as plastics, adhesives, and inks in converted products complicates the recycling process. This inefficiency reduces the yield of usable recycled fiber increasing costs for converters who rely on recycled content to meet sustainability goals. Many municipal recycling facilities lack the advanced sorting technology required to separate complex converted paper products such as laminated cups or waxed boxes. Consequently, these items often end up in landfills, as recyclable leading to consumer confusion and reputational risk for brands. The lack of standardized labeling and collection systems across different regions further exacerbates the problem. Without a unified and efficient recycling infrastructure the circular economy potential of converted paper products remains unrealized. This challenge requires significant investment in both product design for recyclability and infrastructure upgrade, which places a financial burden on the industry and slows the transition to a fully sustainable model.
Regulatory Fragmentation Regarding Food Contact Safety Standards
The diverse and often conflicting regulatory landscapes regarding food contact safety standards is also to Converting Paper Market. Different regions have varying limits for chemical migration from paper packaging into food products, which complicates global trade and compliance. According to the World Trade Organization, discrepancies in food safety regulations act as non-tariff barriers affecting billions of dollars in paper packaging exports annually. For example, the European Union has strict restrictions on mineral oils and perfluorinated compounds in food contact paper while other regions may have different or less stringent limits. The United States Food and Drug Administration requires rigorous testing and documentation for any new substances used in paper converting processes which can delay product launches and increase costs. The non-compliance with food contact regulations is one of the leading causes of product recalls in the packaging sector. Additionally frequent updates to regulatory lists require constant monitoring and adaptation by converters. The Global Food Safety Initiative notes that keeping up with changing chemical regulations is one of the top challenges for packaging manufacturers. Failure to comply can result in shipment rejections fines and loss of market access.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 2.5% |
| Segments Covered | By Paper, Plup, Application, and Region. |
| Various Analyses Covered | Global, Regional, & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Georgia-Pacific Corp (US), Weyerhaeuser Corp (US), Kimberly-Clark Corp (US), Stora Enso (Finland), UPM (Finland), SCA (Sweden), BillerudKorsnäs (Sweden), Oji Paper (Japan), Nippon Unipac Holding (Japan), Burgo Group (Italy), Canfor Corp (Canada) and Others. |
SEGMENTAL ANALYSIS
By Paper Insights
The uncoated paper segment was accounted in holding 44.3% of the global converting paper market share in 2025 due to its widespread application in packaging tissue products and industrial uses where high gloss is not required. Additionally, the hygiene sector relies heavily on uncoated tissue papers for toilet rolls and facial tissues with the improved sanitation access has driven a 20% increase in tissue consumption in developing nations. The lower production costs associated with skipping the coating process allow manufacturers to offer competitive pricing which is crucial for high volume low margin products. Furthermore, the recyclability of uncoated paper is superior to coated variants as it does not contain clay or polymer layers that complicate processing. The uncoated paper has a recycling rate making it the preferred choice for companies aiming to meet sustainability targets. These factors ensure that uncoated paper remains the backbone of the converting industry supporting essential daily needs and logistics operations globally.
The coated paper segment is projected to register a fastest CAGR of 4.8% during the forecast period with the rising demand for high-quality printing and premium packaging solutions. This rapid growth is fueled by the need for superior printability and visual appeal in marketing materials luxury packaging and publication sectors. The global advertising industry, which spends over 600 billion dollars annually relies on coated paper to deliver vibrant images and sharp text that capture consumer attention. In the packaging sector, coated paperboard is increasingly used for cosmetic and pharmaceutical packaging where aesthetics influence purchasing decisions. Additionally, advancements in coating technologies have improved the sustainability profile of coated papers by reducing the amount of chemical additives required. The new eco-friendly coatings are enabling coated papers to be more easily recycled addressing previous environmental concerns. These innovations combined with the enduring value of high-quality print media drive the accelerated adoption of coated paper in specialized applications.
By Pulp Insights
The chemical wood pulp segment was accounted in holding 34.8% of the converting paper market share in 2025 owing to its superior strength brightness and purity, which are essential for high-quality paper products. The extensive use of chemical pulp in tissue printing and writing papers where performance characteristics are paramount. The growing middle class in Asia Pacific is driving demand for premium tissue products, which require chemical pulp to achieve softness and absorbency. Additionally, the publishing industry relies on chemical pulp for high brightness printing papers that offer excellent ink holdout and opacity. The chemical pulp mills have improved their energy efficiency in the last decade making them more economically viable despite higher initial processing costs. The versatility of chemical pulp allows it to be bleached to various degrees of brightness catering to diverse application needs from white office paper to brown packaging liners.
The recycled pulp segment is swiftly emerging at a fastest CAGR of 5.2% during the forecast period with the global sustainability mandates and circular economy initiatives. According to the Environmental Protection Agency, the recycling rate for paper and paperboard in the United States reached 68% in recent years providing an abundant supply of raw material for recycled pulp production. As per the European Union Circular Economy Action Plan mandates that all packaging must be reusable or recyclable by 2030, which significantly boosts demand for recycled content in converting operations. Additionally, the cost advantage of recycled pulp compared to virgin chemical pulp makes it an attractive option for price sensitive applications like corrugated medium and tissue cores.
By Application Insights
The hygiene paper segment was accounted in holding 45.3% of the converting paper market share in 2025 with the universal demand for personal care products and improving global sanitation standards. The population growth urbanization and heightened health awareness, which have made tissue products essential household items. The United Nations Department of Economic and Social Affairs projects that the global population will reach 8.5 billion by 2030 creating a larger base of consumers for hygiene products. Additionally, the aging population in developed countries drives demand for adult incontinence products, which utilize specialized hygiene papers. The premium tissue segment is expanding rapidly as consumers seek softer and stronger products. Manufacturers are responding by investing in advanced converting lines that produce multi ply and lotion infused tissues.
The overall Printing and Writing Paper segment is likely to witness a fastest CAGR of 1.5% during the forecast period with the specialized educational and professional needs. The demand for high quality uncoated free sheet paper for textbooks and official records remains stable in emerging economies, where digital infrastructure is still developing. Additionally, the packaging industry utilizes printing paper for labels and tags, which are essential for product identification and branding. Furthermore, the rise of personalized direct mail marketing has created a niche demand for high quality printing paper that offers superior tactile engagement compared to digital ads. The response rates for physical mail remain higher than email in certain demographics supporting continued use of converting paper for targeted campaigns.
REGIONAL ANALYSIS
Asia Pacific Converting Paper Market Analysis
Asia Pacific was the largest contributor in the global converting paper market by accounting 42.3% of share in 2025 with the rapid industrialization and a massive consumer base. China and India are the primary engines of this growth with China being the world largest producer and consumer of paper products. The rising disposable income in the region has led to increased consumption of packaged foods and hygiene products which require converted paper solutions. The middle class in Asia is expected to reach 1.7 billion people by 2030 further boosting demand for retail packaging and tissue products. Additionally, the expansion of e commerce platforms like Alibaba and Flipkart has surged the demand for corrugated packaging. Government initiatives such as Make in India and China Belt and Road Initiative support infrastructure development including paper mills and converting facilities.
North America Converting Paper Market Analysis
North America was the largest contributor of the global converting paper market by accounting for 38.9% of the share in 2025 with the high technological adoption and strict sustainability standards. The United States is a major contributor with a well-established infrastructure for paper recycling and converting. The shift towards e-commerce has driven demand for corrugated boxes with the United States Postal Service reporting an increase in package volume annually. Canada also contributes significantly with its strong forestry sector providing high quality virgin pulp for premium tissue and printing papers. The Environmental Protection Agency enforces strict regulations on waste management which encourages the use of recycled content in converting operations. Major retailers like Walmart and Amazon have set ambitious sustainability goals requiring suppliers to use certified sustainable paper packaging.
Europe Converting Paper Market Analysis
Europe was ranked second by holding 33.2% of the global converting paper market share in 2025 with its rigorous environmental regulations and commitment to circular economy practices. The European Union Green Deal aims to make Europe the first climate neutral continent by 2050 driving significant changes in the paper industry. Countries like Germany, Sweden, and Finland are leaders in producing high quality recycled pulp and converted paper products. The European Commission Single Use Plastics Directive has accelerated the substitution of plastic packaging with paper based alternatives boosting demand for converted paper cups bags and containers. Consumer awareness regarding sustainability is high in Europe with European consumers are willing to pay more for sustainable products. This preference drives brands to invest in premium eco-friendly paper packaging. Additionally, the region is a hub for innovation in barrier coatings that enable paper to replace plastic in food contact applications. These regulatory and consumer driven trends position Europe as a pioneer in sustainable converting paper solutions.
Latin America Converting Paper Market Analysis
Latin America converting paper market growth is esteemed to have a prominent growth opportunities during the forecast period with the increasing domestic consumption and strong export capabilities in pulp and paper. Brazil and Chile are the key players in the region with Brazil being a major exporter of eucalyptus pulp, which feeds both domestic and international converting industries. The expansion of retail chains and e commerce platforms like Mercado Libre has boosted the need for corrugated packaging. Additionally, government policies in countries like Mexico and Colombia are promoting recycling and waste management initiatives, which support the use of recycled fiber in converting. The region benefits from abundant forestry resources allowing for cost effective production of virgin pulp.
Middle East And Africa Converting Paper Market Analysis
The Middle East and Africa converting paper market growth is driven by urbanization and government investments in industrial diversification. Saudi Arabia and the United Arab Emirates are leading this trend with significant projects aimed at reducing reliance on oil revenues by developing manufacturing sectors. The Saudi Vision 2030 initiative includes plans to develop local paper and packaging industries to meet domestic demand and reduce imports. In Africa, South Africa and Egypt are the largest contributors with growing demand for tissue and packaging papers driven by retail expansion. The rise of modern retail formats and e commerce in urban centers is increasing the need for branded packaging solutions. Additionally, improving sanitation access in sub Saharan Africa is driving demand for hygiene papers although penetration rates remain low compared to global averages.
COMPETITIVE LANDSCAPE
The competition in the Converting Paper Market is characterized by intense rivalry among established global giants and specialized regional converters. Companies compete primarily on product quality sustainability credentials and cost efficiency. The market features a mix of large integrated producers with extensive supply chains and niche players focusing on specific applications like luxury packaging or medical papers. Innovation serves as the key differentiator with leaders continuously launching eco-friendly alternatives to plastic packaging. Price competition remains moderate as customers prioritize reliability and compliance with environmental regulations over initial cost savings. Strategic alliances and joint ventures are common as firms seek to combine complementary technologies and expand geographic reach. The entry of new players with disruptive digital printing technologies poses a challenge to incumbents requiring constant adaptation and improvement. Intellectual property protection plays a crucial role as companies safeguard their proprietary coating formulations and converting processes. Customer retention strategies including comprehensive technical support and flexible production capabilities are essential for maintaining market share.
KEY MARKET PARTICIPANTS
Major Key Players in the Global Converting Paper Market are
- Georgia-Pacific Corp (US)
- Weyerhaeuser Corp (US)
- International Paper Company
- Kimberly-Clark Corp (US)
- Essity AB
- WestRock Company
- Stora Enso (Finland)
- UPM (Finland)
- SCA (Sweden)
- BillerudKorsnäs (Sweden)
- Oji Paper (Japan)
- Nippon Unipac Holding (Japan)
- Burgo Group (Italy)
- Canfor Corp (Canada).
Top Players In The Market
- International Paper Company is a global leader in fiber-based packaging and pulp products with extensive converting capabilities. The company specializes in producing corrugated packaging containerboard and cellulose fibers that serve diverse industries worldwide. International Paper has recently invested heavily in modernizing its converting facilities to enhance efficiency and reduce environmental impact. The organization focuses on sustainable innovation by developing recyclable and compostable packaging solutions that meet evolving regulatory standards. International Paper strengthens its market position through strategic acquisitions of regional converting assets to expand its geographic footprint. Their commitment to circular economy principles drives the development of advanced barrier coatings for food service applications.
- Essity AB is a leading global hygiene and health company that plays a significant role in the tissue converting segment of the paper market. The company produces a wide range of consumer and professional hygiene products including toilet paper facial tissues and kitchen towels. Essity has recently launched innovative product lines featuring ultra soft textures and enhanced absorbency using sustainable fiber sources. The organization emphasizes resource efficiency by implementing water saving technologies in its converting operations. Essity strengthens its market presence by expanding its distribution networks in emerging markets where hygiene awareness is growing. Their focus on brand building and consumer education helps drive demand for premium tissue products. Additionally, Essity collaborates with retailers to develop private label solutions that offer high quality at competitive prices.
- WestRock Company is a major provider of sustainable paper and packaging solutions with robust converting operations across multiple continents. The company offers a comprehensive portfolio of corrugated packaging folding cartons and specialty papers. WestRock has recently introduced advanced digital printing capabilities for short run packaging which allows for greater customization and faster time to market. The organization is committed to reducing its carbon footprint by investing in renewable energy and recycling infrastructure. WestRock strengthens its market position through partnerships with global brands to design innovative packaging that enhances shelf appeal. Their integrated supply chain model ensures consistent quality and reliability for customers. Additionally, WestRock actively participates in industry initiatives promoting responsible forestry and circular economy practices.
Major Strategies Used By Key Market Participants
Key players in the Converting Paper Market employ several strategic approaches to maintain competitive advantage and drive growth. Product innovation remains a primary strategy with companies investing heavily in research and development to create sustainable and functional paper solutions. These advancements include bio-based barriers and improved recyclability which attract environmentally conscious customers. Strategic partnerships and collaborations are also prevalent as firms join forces with technology providers and retailers to accelerate product development. Expansion into emerging markets represents another critical strategy where companies establish local converting facilities to cater to rising demand in Asia Pacific and Latin America. Mergers and acquisitions enable organizations to broaden their product portfolios and access new customer segments efficiently. Additionally, key participants focus on operational excellence by implementing digital technologies and automation to reduce costs and improve efficiency.
MARKET SEGMENTATION
This research report on the global converting paper market has been segmented and sub-segmented based on the paper, pulp, applicatipon, and region.
By Paper
- Coated
- Uncoated
By Pulp
- Mechanical Wood Pulp
- Semi-chemical Pulp
- Chemical Wood Pulp
- Non-wood Pulp
- Recycled Pulp
By Application
- Newsprint
- Hygiene Paper
- Printing Paper
- Writing Paper
- Others
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- The Middle East and Africa