- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$30.29 BnMarket Estimate, 2026
$32.85 BnMarket Forecast, 2034
$62.91 BnCAGR, 2026–2034
8.46%Global Drive-by-Wire Market Report: Size, Share, Trends & Forecast (2026–2034)
- Market Scope: Comprehensive global evaluation of the drive-by-wire market spanning applications (throttle, steer, shift, brake, park-by-wire), sensor types, hardware components, vehicle classes (passenger, commercial, electric, off-highway), and regional adoption metrics.
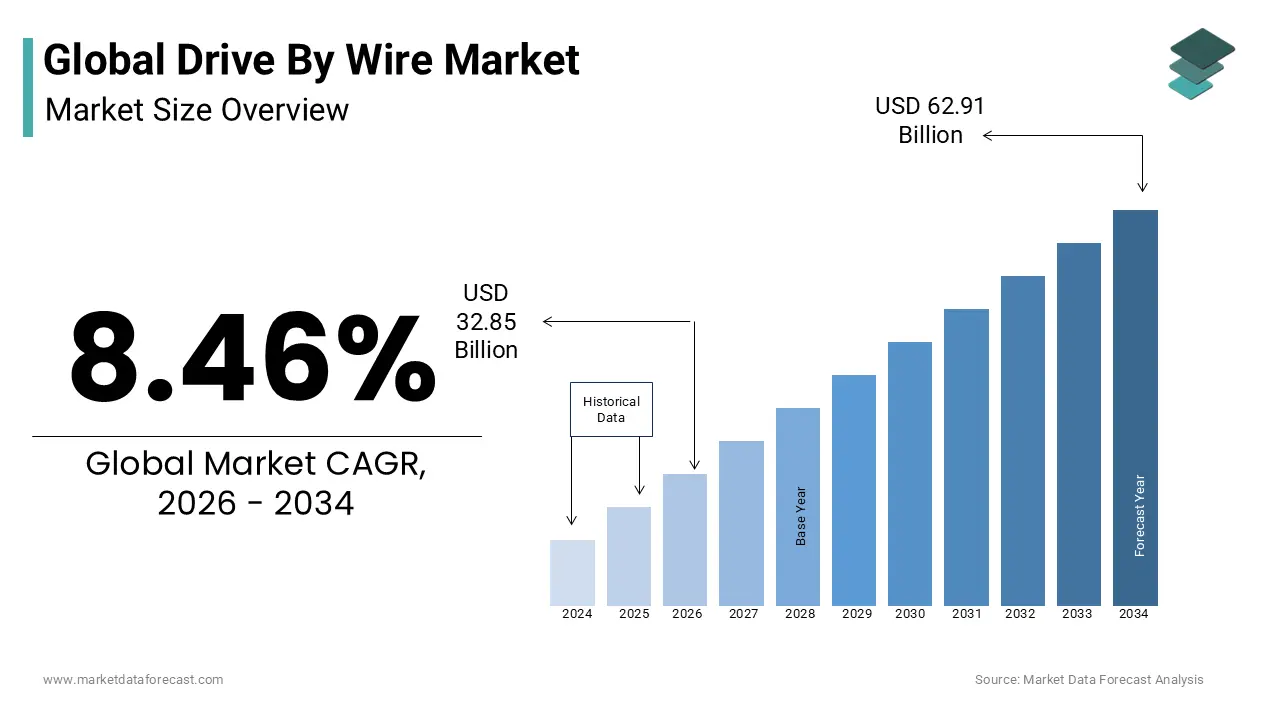
- Market Valuation: Valued at USD 30.29 billion in 2025, estimated at USD 32.85 billion in 2026, and projected to reach USD 62.91 billion by 2034, growing at a steady CAGR of 8.46% during the forecast period from 2026 to 2034.
- Primary Growth Drivers: Rapid expansion of autonomous vehicle development, rising integration of connected automotive infrastructure, and the continuous industry push toward vehicle weight reduction, enhanced fuel efficiency, and lower emissions.
Key Global Drive-by-Wire Market Segment Metrics (2026–2034)
| Category | Leading Segment / Position | Fastest-Growing / Prominent Trend |
|---|---|---|
| By Component | Electronic Control Unit / ECU (dominates market value due to essential utility across every drive-by-wire application) | Electromechanical Actuators & Feedback Motors (expanding rapidly alongside advanced steer-by-wire architecture) |
| By Vehicle Type | Passenger Cars (captures largest volume and value share backed by rising consumer preference for luxury and smart tech) | Electric & Autonomous Vehicles (witnessing surging deployment as electronic control systems replace mechanical linkages) |
| By Region | North America (leads global market share anchored by high consumer awareness, advanced R&D, and autonomous testing) | Asia-Pacific (projected as a high-growth region driven by rapid economic development and automotive manufacturing in China, Japan, and India) |
Major Global Drive-by-Wire Companies & Competitive Landscape
Market Structure: A highly competitive global sector dominated by leading tier-1 automotive suppliers focusing on redundant electronic architectures, acquisition of safe autonomous driving platforms (such as Schaeffler's Space Drive), and lightweight actuator integration.
Key Companies: Robert Bosch, Continental AG, ZF Friedrichshafen, Infineon, Nexteer, CTS, Ficosa, Kongsberg, Hitachi Automotive, and Curtiss-Wright.
 Download Free Sample Report
Global Drive By Wire Market Size
The global drive-by-wire market size was valued at USD 30.29 billion in 2025 and is anticipated to reach a valuation of USD 32.85 billion in 2026 and USD 62.91 billion by 2034, growing at a CAGR of 8.46%, from 2026 to 2034.
Introduction to Drive by Wire Market
Drive-by-wire technology is a fundamental shift in automotive control systems, replacing traditional mechanical linkages with electronic interfaces. This innovation enables precise vehicle management through electrical signals rather than physical cables or hydraulic systems. According to the European Commission, the European Union's General Safety Regulation mandates that all new motor vehicles sold as of 7 July 2024 include advanced driver assistance systems to improve road safety. As per the International Organization of Motor Vehicle Manufacturers (OICA), global vehicle production reached 93.5 million units in 2023. According to sources, electronic throttle control has become a standard subsystem in the majority of modern automobiles to optimize airflow, fuel economy, and emissions. These facts illustrate how regulatory frameworks and manufacturing trends converge to establish drive by wire as an essential component of contemporary automotive engineering. The transition from mechanical to electronic controls facilitates enhanced safety features and improved fuel efficiency while reducing vehicle weight and complexity. This technological evolution aligns with broader industry goals of electrification and autonomous driving capabilities making drive by wire systems indispensable for future mobility solutions across passenger and commercial vehicle segments.
MARKET DRIVERS
Electrification of Vehicle Platforms Accelerates Adoption
The rapid electrification of global vehicle fleets is fueling the expansion of the drive-by-wire market. This acceleration is driven by the fact that electric vehicles inherently depend on electronic control systems to achieve optimal performance. According to the International Energy Agency (IEA), global electric car sales neared 14 million units in 2023, accounting for around 18% of all cars sold. This massive shift toward electrified transportation necessitates sophisticated electronic architectures that seamlessly integrate with drive by wire technologies for throttle braking and steering functions. As per research, battery electric vehicles use electronic drive systems and electronic throttle pedals rather than conventional mechanical linkages. Electric powertrains operate most efficiently when paired with precise electronic controls that can modulate power delivery instantaneously based on driver input and road conditions. Drive by wire systems enable this level of precision by translating accelerator pedal positions into digital signals that motor controllers interpret without delay. The absence of internal combustion engines in electric vehicles removes the need for complex mechanical throttle bodies further simplifying the integration of wire based control systems. Automakers recognize that drive by wire technology reduces component count and assembly time while improving energy management capabilities essential for maximizing electric vehicle range. The correlation between rising electric vehicle adoption and drive by wire implementation demonstrates how powertrain transformation drives demand for electronic control solutions across the automotive industry.
Autonomous Driving Development Drives Technological Integration
The advancement of autonomous driving technologies propels the drive-by-wire market. This expansion is necessitated by self-driving vehicles, which require total electronic control over vehicle dynamics, eliminating human mechanical intervention. According to SAE International, Level 4 and Level 5 automated driving systems perform the entire dynamic driving task, including lateral steering and longitudinal acceleration and braking, without expecting a human driver to take over. As per reports, numerous pilot and testing deployments for autonomous driving technologies have been active across Europe, driving the adoption of electronic-by-wire controls. Autonomous systems process sensor data and make driving decisions in milliseconds necessitating instantaneous response from vehicle control systems that only electronic interfaces can provide. Mechanical linkages introduce latency and variability that compromise the precision required for autonomous navigation and obstacle avoidance maneuvers. Drive by wire technology eliminates these limitations by enabling direct communication between autonomous driving computers and vehicle actuators ensuring consistent and predictable responses. As per the National Highway Traffic Safety Administration (NHTSA), highly automated vehicles operate without direct driver input for steering, acceleration, and braking, with safety guidance emphasizing fail-safe operation and redundant critical architectures. As automakers invest billions in autonomous vehicle development the requirement for reliable drive by wire systems becomes non negotiable for achieving full self driving capabilities. This technological dependency ensures sustained growth in drive by wire adoption as autonomous vehicle programs expand globally and progress through various development stages toward commercial deployment.
MARKET RESTRAINTS
High Development and Validation Costs Restrain Market Penetration
High costs associated with research, testing, and certification are significant restraints to the drive-by-wire market. These considerable front-end expenses are mandatory for manufacturers before deploying safety-critical systems. According to sources, developing automotive-grade X-by-wire systems requires significant engineering investment across hardware design, software engineering, and multi-tier testing validation. The complexity of ensuring fail safe operation demands rigorous validation processes that extend development timelines and increase overall project costs significantly. As per the International Organization for Standardization, safety-critical electronic systems like drive-by-wire must comply with the ISO 26262 functional safety standard, which governs the entire development lifecycle through risk assessments and redundancy verification. These stringent requirements compel manufacturers to conduct millions of test cycles under varying conditions to prove system reliability before receiving regulatory approval for production use. Small and medium sized automotive suppliers often lack the financial resources to undertake such intensive development programs limiting market competition and slowing innovation pace. According to studies, the extensive software validation and physical testing required for safety-critical vehicle control components represent a large portion of development budgets and pose a substantial entry barrier. High initial investments discourage smaller manufacturers from entering the market resulting in limited supplier options and reduced price competition. These financial constraints restrict the widespread adoption of drive by wire technology particularly in cost sensitive vehicle segments where manufacturers prioritize affordability over advanced electronic features.
Cybersecurity Vulnerabilities Create Implementation Hesitation
Growing cybersecurity concerns hamper the growth of the drive-by-wire market. This is because electronic control systems present potential attack vectors that malicious actors could exploit to compromise vehicle safety. According to research, software-defined and connected vehicles experience a growing volume of cybersecurity threats, making critical control architectures high-priority targets for risk mitigation. The United Nations Economic Commission for Europe established UN Regulation 155 requiring all new vehicles to implement robust cybersecurity management systems to protect against unauthorized access to electronic controls. Drive by wire systems transmit control commands through digital networks making them susceptible to hacking attempts that could manipulate steering braking or acceleration without driver consent. As per reports, cybersecurity vulnerabilities within connected vehicle ecosystems have escalated rapidly in recent years, driving stricter industry compliance frameworks. Manufacturers must invest substantially in encryption protocols intrusion detection systems and secure communication channels to safeguard drive by wire architectures from potential breaches. These additional security measures increase system complexity and development costs while extending time to market for new vehicle platforms. Consumer confidence remains fragile as high profile cybersecurity breaches receive extensive media coverage causing hesitation among buyers regarding fully electronic control systems. The automotive industry faces ongoing challenges in balancing connectivity benefits with security requirements creating uncertainty that slows aggressive drive by wire deployment strategies across various vehicle categories.
MARKET OPPORTUNITIES
Integration with Advanced Driver Assistance Systems Presents Growth Potential
Merging drive-by-wire technology with advanced driver assistance systems generates substantial industry opportunities for the global market. This synergy concurrently optimizes vehicle safety and overall operational performance. According to studies, automated emergency braking systems utilizing electronic actuation generally deliver enhanced braking responsiveness compared to purely mechanical configurations. As per the Alliance for Automotive Innovation, over 90% of new cars sold today are equipped with advanced driver assistance system features such as automatic emergency braking. Drive by wire systems enable precise modulation of vehicle dynamics that advanced driver assistance algorithms depend upon for effective collision avoidance lane keeping and adaptive cruise control operations. The synergy between these technologies allows manufacturers to offer enhanced safety packages that appeal to increasingly safety conscious consumers willing to pay premium prices for superior protection features. Automotive engineers can optimize drive by wire parameters specifically for advanced driver assistance applications improving response times and accuracy beyond what mechanical systems can achieve. According to research, crash avoidance technologies and automated braking interventions significantly reduce rear-end collisions under real-world conditions. This proven safety benefit creates compelling marketing advantages that drive consumer demand and justify higher vehicle pricing. Regulatory bodies worldwide are mandating more advanced safety features. Consequently, the opportunity for drive-by-wire manufacturers expands substantially through partnerships with advanced driver assistance system developers seeking compatible electronic control platforms.
Expansion into Commercial Vehicle Applications Opens New Markets
Expanding drive-by-wire technology into the commercial vehicle sector offers considerable growth potential for the global market. This expansion is driven by heavy-duty trucks, buses, and construction machinery increasingly relying on electronic controls to optimize safety and fuel efficiency. According to studies, the expanding global commercial vehicle fleet continues to adopt advanced electronic control architectures to comply with emissions rules and improve fleet fuel efficiency. As per research, heavy-duty commercial vehicles increasingly implement electronic braking and engine management systems to improve fuel economy and meet stricter emissions limits. Commercial vehicles benefit significantly from drive by wire technology through improved fuel economy precise load handling capabilities and enhanced driver comfort during extended operating hours. Electronic controls allow fleet operators to implement predictive maintenance programs by monitoring system performance data continuously identifying potential issues before they cause costly breakdowns. According to sources, replacing mechanical linkages with electronic-by-wire controls can lower overall fleet maintenance expenses by eliminating mechanical linkages subject to physical wear. Construction and agricultural equipment manufacturers recognize that drive by wire enables remote operation capabilities essential for hazardous environment applications where human operators face safety risks. The versatility of drive by wire systems across diverse commercial applications creates multiple revenue streams for technology providers beyond passenger vehicle markets. Escalating commercial vehicle electrification directly increases the demand for integrated electronic control systems. As a result, drive-by-wire technology serves as a foundational element for next-generation transportation efficiency and sustainability.
MARKET CHALLENGES
Regulatory Compliance Complexity Challenges Standardization Efforts
Divergent regulatory requirements across different regions challenge the drive-by-wire market. This is due to the fact that manufacturers must navigate varying certification standards and approval processes that complicate global product deployment. According to sources, international automotive electronics compliance often requires navigating regional regulatory differences, forcing manufacturers to manage multiple configurations for different global markets. As per studies, securing localized type approval and regulatory certification across different jurisdictions adds complexity and extends the commercial timeline for deploying new drive-by-wire platforms. According to research, securing localized type approval and regulatory certification across different jurisdictions adds complexity and extends the commercial timeline for deploying new drive-by-wire platforms. These fragmented regulatory landscapes prevent economies of scale that would otherwise reduce production costs and accelerate technology adoption across global vehicle platforms. Manufacturers must maintain dedicated compliance teams for each region investing resources in understanding and meeting unique documentation testing and certification requirements that vary considerably between jurisdictions. The lack of harmonized international standards creates uncertainty regarding future regulatory changes potentially rendering current designs obsolete if requirements shift unexpectedly. Small volume manufacturers struggle particularly with compliance burdens lacking the resources to manage multiple regulatory frameworks simultaneously. This regulatory fragmentation discourages innovation as companies prioritize meeting existing requirements over developing next generation features that might face uncertain approval pathways in key markets.
Supply Chain Disruptions Impact Component Availability
Ongoing supply chain disruptions are a major impediment to the drive-by-wire market. This instability exists because these systems require specialized semiconductors and electronic modules that remain highly sensitive to global shortages. According to sources, global semiconductor supply chain disruptions during the 2021–2023 shortage caused lead times to exceed 40 weeks for critical automotive-grade controllers. As per studies, widespread automotive electronic component volatility and chip availability constraints throughout 2023 directly caused production backlogs and delayed vehicle deliveries worldwide. Drive by wire systems require high reliability semiconductors capable of operating under extreme temperature variations and vibration conditions limiting the number of qualified suppliers who can meet automotive quality standards. This concentrated supplier base creates single points of failure where disruptions at one manufacturing facility cascade through entire automotive production networks causing widespread delays. According to research, component supply bottlenecks during 2023 limited manufacturing throughput and depressed the optimal capacity utilization of electronic tier suppliers globally. Geopolitical tensions and trade restrictions further complicate supply chains by limiting access to critical materials and manufacturing facilities in certain regions. Automotive manufacturers face difficult decisions between maintaining production volumes with reduced feature sets or delaying vehicle launches until complete drive by wire systems become available. These supply chain uncertainties force companies to hold larger inventory buffers increasing working capital requirements and reducing overall operational efficiency throughout the drive by wire value chain.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 8.46% |
| Segments Covered | By Application, Sensor, Component, Vehicle Type, and Region. |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Robert Bosch (Germany), Continental AG (Germany), ZF Friedrichshafen (Germany), Infineon (Germany), Nexteer (US), CTS (US), Ficosa (Spain), Kongsberg (Switzerland), Hitachi Automotive (Japan), and Curtiss-Wright (US), and Others. |
SEGMENTAL ANALYSIS
By Application Insights
Throttle by Wire
The throttle-by-wire segment dominated the drive-by-wire market in 2025. This dominance of the segment was supported by its status as the first electronic control system to achieve widespread commercial adoption across global automotive platforms. According to sources, electronic throttle control has effectively replaced conventional cable-driven mechanisms in the overwhelming majority of modern passenger vehicles. As per studies, removing mechanical throttle linkages minimizes physical routing constraints within the engine bay, which helps streamline vehicle layout configuration. This early adoption created established supply chains and standardized engineering practices that make throttle by wire the most cost effective and reliable entry point for manufacturers transitioning from mechanical to electronic controls. The technology enables precise fuel air mixture management essential for meeting stringent emissions regulations imposed by environmental agencies worldwide. As per research, high-precision electronic throttle body actuation allows for optimized air-fuel ratios, supporting compliance with strict regional tailpipe emissions rules. Automakers benefit from reduced warranty claims associated with throttle cable wear and tear while gaining flexibility in pedal placement design for improved ergonomics. The maturity of throttle by wire technology ensures high reliability rates that build consumer confidence in electronic control systems paving the way for adoption of more complex drive by wire applications such as steer by wire and brake by wire in future vehicle generations.
Strict global emissions regulations favor throttle-by-wire dominance. Such systems excel since electronic control enables the precise engine management necessary for minimizing pollutant output during various driving conditions. According to sources, modern statutory vehicle emissions standards necessitate highly responsive air intake modulation architectures to minimize transient combustion emissions. As per studies, real driving emissions testing protocols demand precise, closed-loop coordination between intake airflow, exhaust gas recirculation, and exhaust aftertreatment components. Throttle by wire systems process this data in milliseconds allowing engine control units to optimize combustion efficiency dynamically reducing harmful emissions without compromising performance. According to reports, electronic throttle modulation controls rapid air-delivery fluctuations during transient driving operations, mitigating sudden spikes in tailpipe emissions. Mechanical throttle linkages introduce latency and inconsistency that prevent engines from maintaining optimal air fuel ratios during rapid load changes leading to incomplete combustion and increased pollution. Throttle by wire eliminates these limitations by providing direct digital communication between driver input and engine management systems ensuring consistent performance under all operating conditions. This regulatory pressure ensures that throttle by wire remains mandatory for all new vehicle platforms securing its position as the largest application segment within the drive by wire market indefinitely.
Steer by Wire
The steer-by-wire technology segment is predicted to witness the highest CAGR of 18.5% from 2026 to 2034. This rapid growth is propelled by the technology's ability to enable revolutionary vehicle design possibilities and autonomous driving capabilities. According to sources, steer-by-wire system integration is expanding on modern electric vehicle architectures, though broad commercial adoption remains low compared to electric power steering. As per studies, decoupling the mechanical connection between the steering wheel and front axle allows software-defined steer-by-wire setups to vary steering ratios based on real-time vehicle velocity. This technology eliminates the mechanical steering column creating additional cabin space for advanced infotainment systems and improving crash safety by removing potential intrusion hazards during frontal collisions. According to research, removing the traditional physical steering column and intermediate shafts alters structural configurations, which can reduce overall mass and open up internal space. Automakers invest heavily in steer by wire development because it enables customizable steering feel profiles that can be adjusted electronically for different driving modes appealing to consumers seeking personalized driving experiences. As per reports, electronic steering interfaces simplify integration with advanced active safety systems like automated parking and lane tracking assistance. As consumer acceptance grows and regulatory frameworks evolve to accommodate fully electronic steering the steer by wire segment will experience accelerated adoption rates surpassing all other drive by wire applications in terms of growth velocity.
Autonomous vehicle integration requirements drive steer-by-wire growth. This trend arises as self-driving systems require direct electronic control over steering angles without mechanical interference or human override limitations. According to sources, highly automated driving platforms require highly precise lateral control and rapid response times to execute automated maneuvers safely using localized sensor fusion data. As per studies, because control in steer-by-wire is transmitted purely through electrical signals, implementations rely heavily on backup systems and redundancy strategies derived from aviation safety practices to handle critical primary faults. Mechanical steering columns introduce friction backlash and latency that compromise the accuracy required for autonomous navigation particularly during emergency avoidance situations where split second decisions determine safety outcomes. According to sources, electronic steering actuators execute continuous, minor track path corrections faster and with lower mechanical variation than conventional hydraulic power systems. Steer by wire allows autonomous driving computers to modulate steering torque and angle independently of driver input enabling smooth coordinated movements that enhance passenger comfort during automated journeys. This technological compatibility makes steer by wire indispensable for automakers pursuing full self driving capabilities ensuring sustained investment and rapid deployment across premium vehicle platforms initially before expanding to mass market segments as costs decline and reliability improves through accumulated operational data.
By Sensor Insights
Throttle Position Sensor
The throttle position sensor segment led the drive-by-wire market and captured a significant share in 2025. This market leadership stems from the requirement that every electronic throttle control system relies on multiple redundant sensors to guarantee safe and accurate operation under all conditions. As per the Society of Automotive Engineers each throttle by wire module incorporates at least two throttle position sensors providing cross verification of pedal input signals to prevent single point failures that could cause unintended acceleration. According to sources, millions of throttle position sensors are manufactured and distributed globally across passenger, commercial, and industrial vehicle networks annually to facilitate modern engine management. These sensors offer mature technology with proven reliability records exceeding 15 years of service life under extreme temperature and vibration conditions making them the preferred choice for manufacturers prioritizing long term durability. As per studies, standard drive-by-wire control platforms configure fault-management software to trigger a restricted fail-safe operation whenever signal variance limits between tracking sensors are exceeded. As per research, throttle position components occupy a significant segment of the structural drive-by-wire sensor replacement space due to high default deployment volumes across historic manufacturing lifecycles. Established manufacturing processes and economies of scale keep unit costs low while maintaining high profit margins for suppliers who dominate this mature segment through longstanding relationships with original equipment manufacturers. The critical safety role of throttle position sensors ensures they remain indispensable components regardless of advancements in other drive by wire technologies securing their market leadership position indefinitely.
Mandatory redundancy standards drive throttle position sensor domination. This requirement is dictated by safety regulations that mandate multiple independent sensors to validate throttle input signals and prevent catastrophic failures from individual component malfunctions. According to reviews, sensor redundancy patterns embedded within electronic control setups minimize potential uncommanded acceleration malfunctions caused by isolated primary sensor degradation. Each sensor operates on different physical principles providing complementary data that engine control units compare continuously detecting anomalies instantly and initiating protective measures such as limp home modes that limit engine power while maintaining basic drivability. As per research, electronic drive sensors must undergo compliance verification for electromagnetic compatibility (EMC) to operate reliably near high-voltage traction inverters and motors. This regulatory requirement forces manufacturers to install multiple sensors per vehicle multiplying total addressable market volume significantly beyond what single sensor architectures would generate. The complexity of validating redundant sensor systems creates high barriers to entry for new competitors protecting incumbent suppliers who possess extensive testing facilities and certification expertise. These factors combine to sustain throttle position sensor market leadership through regulatory compulsion rather than optional feature adoption ensuring stable demand regardless of economic fluctuations.
Handwheel Angle Sensor
The handwheel angle sensors segment is estimated to register the fastest CAGR of 16.2% during the forecast period. This projected expansion is fuelled by the fact that these sensors are essential components for steer-by-wire and advanced driver assistance systems requiring precise steering input measurement. According to sources, handwheel angle tracking architectures are projected to see increased volume requirements as driver assistance programs like lane holding become widespread. As per studies, high safety marks heavily reward active safety systems like Electronic Stability Control (ESC), which relies explicitly on continuous steering wheel position and angle tracking inputs to monitor driver intent. These sensors enable sophisticated vehicle dynamics control algorithms that adjust braking and torque distribution individually at each wheel maintaining stability during slippery conditions or aggressive cornering situations. According to reports, standardized electronic stability testing calculations use linear regression to compute steering metrics rounded to the nearest 0.1 degrees to accurately parse intentional control tracking. As per studies, leveraging higher precision angle monitoring infrastructure provides lane tracking modules with more reliable input data to mitigate accidental drift. As autonomous driving capabilities expand the demand for highly accurate steering input measurement grows exponentially ensuring handwheel angle sensors experience exceptional growth rates surpassing all other sensor categories within the drive by wire ecosystem.
Advanced driver assistance system proliferation drives handwheel angle sensor growth. This expansion occurs as these systems require continuous, precise measurement of steering wheel position to interpret driver intent and coordinate vehicle responses effectively. According to research, an increasing percentage of newly designed consumer vehicles roll off production lines equipped with lane-keeping infrastructure that processes localized steering vectors. As per sources, international safety programs continuously adjust their active lane-keep evaluation metrics to challenge sensor suites under a broader mix of highway edge-case conditions. These sensors provide critical data for predictive steering assistance systems that anticipate driver actions based on handwheel movement patterns enabling smoother more natural interactions between human operators and automated controls. According to studies, advanced driver monitoring and driver assistance technologies utilize multi-axis tracking data to better determine intentional directional changes. As regulatory bodies worldwide mandate more sophisticated driver monitoring and assistance features the requirement for precise handwheel angle measurement becomes non negotiable for vehicle certification. This regulatory pressure combined with consumer demand for enhanced safety features ensures sustained growth in handwheel angle sensor adoption across all vehicle segments from economy cars to luxury SUVs driving exceptional market expansion throughout the forecast period.
By Component Insights
Electronic Control Unit
In 2025, the electronic control units segment held the majority share in the drive-by-wire market because it serves as the central processing hub that interprets sensor inputs and generates actuator commands for all wire-based control systems. According to sources, drive-by-wire vehicles employ localized electronic control units to process dynamic sensor feedback and operate independent vehicle systems over high-speed vehicle networks. As per reports, billions of integrated microcontrollers and electronic control modules are delivered annually to support widespread automotive assembly demands across various segments. These units incorporate powerful microprocessors capable of executing complex control algorithms in real time ensuring precise vehicle response to driver inputs while maintaining safety through continuous self diagnostics and fault detection. The International Organization for Standardization mandates that electronic control units meet rigorous electromagnetic compatibility standards ensuring reliable operation in electrically noisy environments filled with motors inverters and wireless communication devices. As per studies, processing nodes and electronic control modules represent a high percentage of the structural hardware expenses in electronic control integration. Established semiconductor partnerships and software development expertise create significant barriers to entry protecting incumbent suppliers who possess proprietary algorithms and validation methodologies. The centrality of electronic control units in drive by wire architectures ensures they remain the largest component segment driven by increasing vehicle electrification and automation trends that demand more sophisticated processing capabilities.
The trend toward centralized vehicle architecture drives electronic control unit domination. This transition is fueled by automakers consolidating distributed functions into domain controllers and zone controllers that require more powerful integrated processing units. According to reviews, vehicle manufacturing platforms are increasingly transitioning toward zone-based structures that consolidate dozens of traditional domain-specific electronic control units into centralized, high-performance computing centers. The Society of Automotive Engineers states that centralized architectures enable over the air software updates that modify drive by wire control parameters remotely allowing manufacturers to improve performance fix bugs and add features after vehicle sale extending product lifecycle value. These powerful electronic control units process data from multiple sensors simultaneously enabling coordinated vehicle dynamics control that optimizes traction stability and efficiency across all drive by wire subsystems collectively. According to sources, consolidating vehicle decision-making into high-speed high-performance computing nodes minimizes regional networking propagation delays across complex sub-circuits. Automakers benefit from reduced wiring harness weight and complexity when consolidating functions into fewer high performance electronic control units lowering material costs and improving assembly efficiency. This architectural evolution ensures electronic control units remain central to drive by wire systems while evolving in capability to handle increasing computational demands from autonomous driving and connectivity features driving sustained market leadership.
Actuator
The actuators segment is anticipated to witness the fastest CAGR of 17.8% between 2026 and 2034 due to its role in physically executing control commands by converting electrical signals into mechanical motion for throttle, steering, and braking functions. According to research, localized electromechanical and electrohydraulic actuator volume requirements are scaling upward alongside the long-term expansion of electrified braking and steering systems. The European Automobile Manufacturers Association indicates that each steer by wire system requires at least two redundant actuators providing backup steering capability if primary systems fail ensuring compliance with functional safety standards. These actuators incorporate advanced motor technologies such as brushless direct current motors offering high torque density efficiency and reliability essential for safety critical applications where failure is not acceptable. According to sources, fast-acting electronic control actuators allow for agile chassis tuning and stabilization maneuvers under dynamic driving conditions. As per reports, electronic brake actuation systems build line pressure faster than conventional vacuum-assisted hydraulic loops, delivering highly consistent deceleration patterns. As drive by wire technology expands beyond throttle control into steering and braking domains the demand for sophisticated actuators grows exponentially driving exceptional growth rates surpassing all other component categories within the market.
Brake by wire system adoption drives actuator growth because these systems replace hydraulic master cylinders with electromechanical actuators that generate braking force directly at each wheel independently. According to sources, complete brake-by-wire systems utilize electronic actuators at individual wheel ends, coupled with secondary emergency hardware, to meet strict regulatory split-circuit rules. The European New Car Assessment Programme highlights that brake by wire enables regenerative braking coordination in electric vehicles optimizing energy recovery while maintaining consistent pedal feel through actuator controlled pressure modulation. These actuators allow individual wheel braking control enhancing electronic stability program effectiveness by applying precise braking force where needed most during skid recovery or cornering situations. According to research, precise high-speed wheel-slip modulation over slippery surfaces assists safety logic in maximizing tire-to-road friction thresholds. As electric vehicle production accelerates brake by wire becomes standard equipment due to its compatibility with regenerative braking systems and reduced maintenance requirements eliminating brake fluid changes and master cylinder servicing. This transition from hydraulic to electromechanical braking creates massive demand for high reliability actuators driving exceptional growth rates as manufacturers scale production to meet rising electric vehicle volumes globally.
REGIONAL ANALYSIS
North America Market Analysis
North America held the second-largest position in the drive-by-wire market in 2025. This position was supported by the strong adoption of advanced automotive technologies and supportive regulatory frameworks encouraging innovation. As per the National Highway Traffic Safety Administration (NHTSA), the United States established Federal Motor Vehicle Safety Standard (FMVSS) No. 126 to require electronic stability control (ESC) systems on vehicles with a gross vehicle weight rating of 10,000 pounds or less under a long-standing historic implementation. According to sources, North American vehicle manufacturers are allocating substantial research and development capital toward testing and integrating steer-by-wire and brake-by-wire technologies onto next-generation electric vehicle structural architectures. The region benefits from established semiconductor manufacturing capabilities and strong partnerships between technology companies and traditional automakers accelerating drive by wire integration timelines significantly. Consumer preference for large vehicles such as trucks and sport utility vehicles drives demand for drive by wire systems that improve fuel efficiency and handling characteristics in heavier platforms. As per reports, commercial transport operations adopt integrated electronic control systems to improve powertrain management and optimize driver control inputs during long-haul driving. Government incentives for electric vehicle adoption further stimulate drive by wire market growth as these vehicles inherently require electronic control systems for optimal performance. The presence of major technology hubs in Silicon Valley and Detroit fosters innovation ecosystems where drive by wire startups collaborate with established manufacturers developing next generation solutions. This combination of regulatory support technological expertise and consumer demand ensures North America maintains its leadership position in drive by wire market adoption and innovation throughout the forecast period.
Europe Market Analysis
Europe plays a crucial role in the drive by wire market owing to stringent environmental regulations and aggressive electrification targets that necessitate advanced electronic control systems. According to the European Commission the Fit for 55 package mandates 55 % reduction in carbon dioxide emissions by 2030 compared to 1990 levels forcing automakers to adopt drive by wire technologies that optimize energy efficiency in electric and hybrid vehicles. As per sources, European vehicle platforms continue to show notable growth in the validation and deployment of steer-by-wire architectures across newly introduced passenger vehicle platforms. Strong emphasis on vehicle safety through Euro NCAP ratings encourages adoption of drive by wire systems that enable advanced driver assistance features required for five star certifications. As per reports, regional cybersecurity organizations collaborate with supply-chain stakeholders to establish threat-mitigation protocols protecting vehicle control systems from external network interventions. Germany France and Sweden host major automotive research centers where universities collaborate with industry partners advancing drive by wire technology through joint development programs. Consumer awareness regarding environmental sustainability drives preference for electric vehicles that utilize drive by wire extensively creating robust domestic demand. The region benefits from skilled engineering workforce and established supply chains supporting high quality drive by wire component manufacturing. Regulatory harmonization across European Union member states simplifies certification processes enabling faster market introduction of innovative drive by wire solutions. These factors combine to position Europe as a global leader in drive by wire technology development and adoption setting standards that influence markets worldwide.
Asia Pacific Market Analysis
Asia-Pacific was the dominant as well as the fastest-growing region in the drive-by-wire market in 2025. This prominence was fueled by massive vehicle production volumes and rapid electric vehicle adoption, particularly in China and India. According to the China Association of Automobile Manufacturers (CAAM), electric and new energy vehicle sales in China reached 9.49 million units in 2023, which accounted for roughly 60% of all electric vehicle sales worldwide. As per studies, advanced hybrid vehicle designs implement electronic-by-wire controls to manage powertrain transitions seamlessly between internal combustion engines and electric battery motors. South Korea hosts major semiconductor manufacturers supplying critical electronic components for drive by wire systems ensuring stable supply chains for regional automakers. Government policies in India promoting electric vehicle adoption through subsidies and infrastructure development accelerate drive by wire market growth as manufacturers localize production to meet domestic demand. The Asia Pacific region benefits from cost competitive manufacturing capabilities enabling affordable drive by wire system production for mass market vehicles. Rising middle class populations with increasing disposable incomes drive demand for vehicles with advanced features including drive by wire enabled safety and convenience technologies. Regional governments invest heavily in smart city initiatives that require connected autonomous vehicles dependent on drive by wire architectures for safe operation. Collaboration between Asian technology companies and traditional automakers fosters innovation in drive by wire solutions tailored for regional market preferences. This combination of production scale policy support and technological advancement positions Asia Pacific as the primary growth engine for the global drive by wire market.
Latin America Market Analysis
Latin America is an emerging region in the drive by wire market due to gradual adoption driven primarily by imported vehicles featuring advanced technologies from global manufacturers. According to research, major automotive associations monitor production across Latin American corridors as factories increase their assembly capacity for flex-fuel and localized alternative energy platforms. As per sources, high-volume automotive manufacturing facilities operate as crucial supply hubs delivering complex electronic vehicle architectures to international markets. Economic constraints limit domestic demand for premium vehicles with advanced drive by wire features however government incentives for electric vehicle adoption in Chile Colombia and Costa Rica stimulate gradual market expansion. Regional automakers prioritize cost effective solutions importing drive by wire components from established global suppliers rather than developing local manufacturing capabilities. Infrastructure challenges including limited charging networks hinder electric vehicle adoption slowing drive by wire market growth compared to other regions. Consumer preference for durable reliable vehicles with proven technologies slows acceptance of newer drive by wire systems perceived as complex and expensive to maintain. However increasing awareness regarding fuel efficiency and emissions reduction drives gradual shift toward vehicles with electronic control systems. Regional trade agreements facilitate technology transfer and investment from global automakers establishing production facilities with modern drive by wire capabilities. These factors suggest steady but moderate growth in Latin American drive by wire market as economic conditions improve and infrastructure develops supporting broader electric vehicle adoption.
Middle East and Africa Market Analysis
The Middle East and Africa region is a nascent landscape within the drive-by-wire market, owing to luxury vehicle imports and gradual infrastructure development in select countries. As per reports, localized procurement trends demonstrate a high distribution of premium vehicle packages equipped with integrated, digital chassis management controls within affluent regional markets. According to the South African Automotive Masterplan (SAAM), the national automotive industrial roadmap outlines strategic frameworks to transition domestic manufacturing towards a dual platform that includes electric vehicle (EV) production by 2035. Limited domestic automotive manufacturing capabilities in most African countries restrict drive by wire market growth to imported vehicles serving affluent urban populations. Government initiatives in United Arab Emirates promoting smart mobility and autonomous vehicle testing create favorable conditions for drive by wire technology demonstration and eventual adoption. Extreme climate conditions in the region require drive by wire components capable of operating reliably in high temperatures influencing supplier product specifications and validation requirements. Infrastructure development including charging stations and smart roads progresses slowly limiting electric vehicle adoption and consequently drive by wire market expansion. However increasing investment in renewable energy projects and sustainable transportation initiatives signals long term commitment to modernizing vehicle fleets. Regional partnerships with global automakers facilitate technology transfer and local assembly operations gradually building domestic capabilities. These factors suggest gradual but promising growth in Middle East and Africa drive by wire market as economic diversification efforts and infrastructure investments mature over the coming decade.
COMPETITIVE LANDSCAPE
The competition in the drive by wire market features intense rivalry among established tier one suppliers and emerging technology specialists vying for dominance in electronic control systems. Major players leverage extensive engineering resources and longstanding relationships with global automakers to secure long term contracts for throttle steering and braking components. New entrants focus on niche innovations such as advanced steer by wire algorithms or compact actuator designs challenging incumbents with specialized solutions. Competitive dynamics shift toward software capabilities as manufacturers differentiate through over the air update features and customizable driving modes enabled by sophisticated control logic. Price pressure remains significant particularly in high volume segments forcing companies to optimize manufacturing processes and achieve economies of scale. Intellectual property disputes occasionally arise regarding patented sensor technologies and communication protocols highlighting the value of proprietary innovations. Collaboration between competitors becomes common in pre competitive research areas such as cybersecurity standards and functional safety frameworks reducing individual development burdens. Supply chain reliability emerges as a critical competitive factor with companies investing in diversified sourcing strategies to mitigate component shortages. Customer service and technical support quality influence purchasing decisions as automakers seek partners capable of rapid problem resolution during vehicle development phases. This complex competitive environment demands continuous innovation strategic agility and robust operational excellence to sustain market relevance and growth.
KEY MARKET PLAYERS
These are the market players that are dominating the global drive-by-wire market
- Robert Bosch (Germany)
- Continental AG (Germany)
- ZF Friedrichshafen (Germany)
- Infineon (Germany), Nexteer (US)
- CTS (US)
- Ficosa (Spain)
- Kongsberg (Switzerland)
- Hitachi Automotive (Japan)
- Curtiss-Wright (US).
Top Players In The Market
- Bosch maintains a dominant presence through its comprehensive portfolio of electronic control units and actuators for throttle and brake systems. The company recently expanded its semiconductor production capabilities to ensure stable supply chains for critical drive by wire components. Bosch collaborates extensively with major automakers to develop integrated safety architectures that meet stringent global regulatory standards. Its investment in artificial intelligence enhances predictive maintenance features for electronic steering systems improving reliability and customer satisfaction. The firm continuously innovates in sensor fusion technologies enabling precise vehicle dynamics control essential for autonomous driving applications. Bosch also focuses on cybersecurity solutions protecting drive by wire networks from potential digital threats ensuring robust system integrity. These strategic initiatives reinforce its leadership position by delivering high quality reliable components that support the transition toward electrified and automated mobility solutions globally.
- Continental AG strengthens its market position by advancing steer by wire technology with redundant architectures for enhanced safety and performance. The company recently partnered with leading electric vehicle manufacturers to integrate its advanced steering modules into next generation platforms. Continental invests heavily in software defined vehicle solutions allowing over the air updates for drive by wire parameters improving functionality post sale. Its development of compact lightweight actuators supports vehicle weight reduction goals crucial for extending electric vehicle range. The firm emphasizes functional safety compliance meeting ISO 26262 standards ensuring reliable operation under all driving conditions. Continental also expands its testing facilities validating drive by wire systems under extreme environmental scenarios guaranteeing durability. These efforts demonstrate its commitment to innovation and quality establishing strong relationships with automakers seeking cutting edge electronic control solutions for future mobility needs.
- ZF Friedrichshafen drives market growth through its innovative brake by wire systems that eliminate hydraulic components for improved efficiency. The company recently launched a new generation of electromechanical braking actuators offering faster response times and better integration with regenerative braking. ZF collaborates with technology firms to develop cloud based diagnostics for drive by wire systems enabling real time monitoring and maintenance. Its focus on modular designs allows automakers to customize configurations for different vehicle segments reducing development costs. ZF also invests in sustainable manufacturing processes minimizing environmental impact while producing high precision electronic components. The firm actively participates in industry consortia shaping standards for autonomous driving interfaces ensuring compatibility across platforms. These strategic actions highlight its dedication to technological advancement and sustainability positioning ZF as a key enabler of next generation automotive control systems worldwide.
Top Strategies Used By Key Market Participants
Key players in the drive by wire market prioritize strategic partnerships with semiconductor manufacturers to secure stable supplies of critical microcontrollers and sensors. Companies invest heavily in research and development focusing on functional safety compliance and cybersecurity measures to protect electronic control systems from vulnerabilities. Many firms pursue vertical integration by acquiring specialized software developers enhancing their capabilities in algorithm design and over the air update functionalities. Automakers collaborate closely with tier one suppliers co developing customized drive by wire solutions tailored for specific electric vehicle platforms. Participants emphasize modular architecture designs allowing scalable implementation across various vehicle segments from compact cars to heavy duty trucks. Industry leaders actively engage in standardization bodies influencing global regulations for electronic steering and braking systems ensuring harmonized requirements. Companies also expand testing facilities validating components under extreme conditions to prove reliability and build customer confidence. Strategic alliances with technology startups accelerate innovation in artificial intelligence applications for predictive maintenance and adaptive control strategies. These approaches enable participants to maintain competitive advantages through technological superiority supply chain resilience and regulatory alignment in the evolving automotive landscape.
MARKET SEGMENTATION
This research report on the global drive-by-wire market is segmented and sub-segmented into the following categories.
By Application
- Throttle-by-wire
- Steer-by-wire
- Shift-by-wire
- Brake-by-wire
- Park-by-wire
By Sensor
- Throttle pedal sensor
- Throttle position sensor
- Pinion angle sensor
- Handwheel angle sensor
- Gear shift position sensor
- Park sensor
- Brake pedal sensor
By Component
- Electronic control unit
- Engine control module
- Actuator
- Feedback motor
- Parking pawl
- Electronic throttle control module
- Electronic transmission control unit
By Vehicle Type
- Passenger cars
- Commercial Vehicle
- Electric Vehicle
- Off-Highway Vehicle
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East and Africa