- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
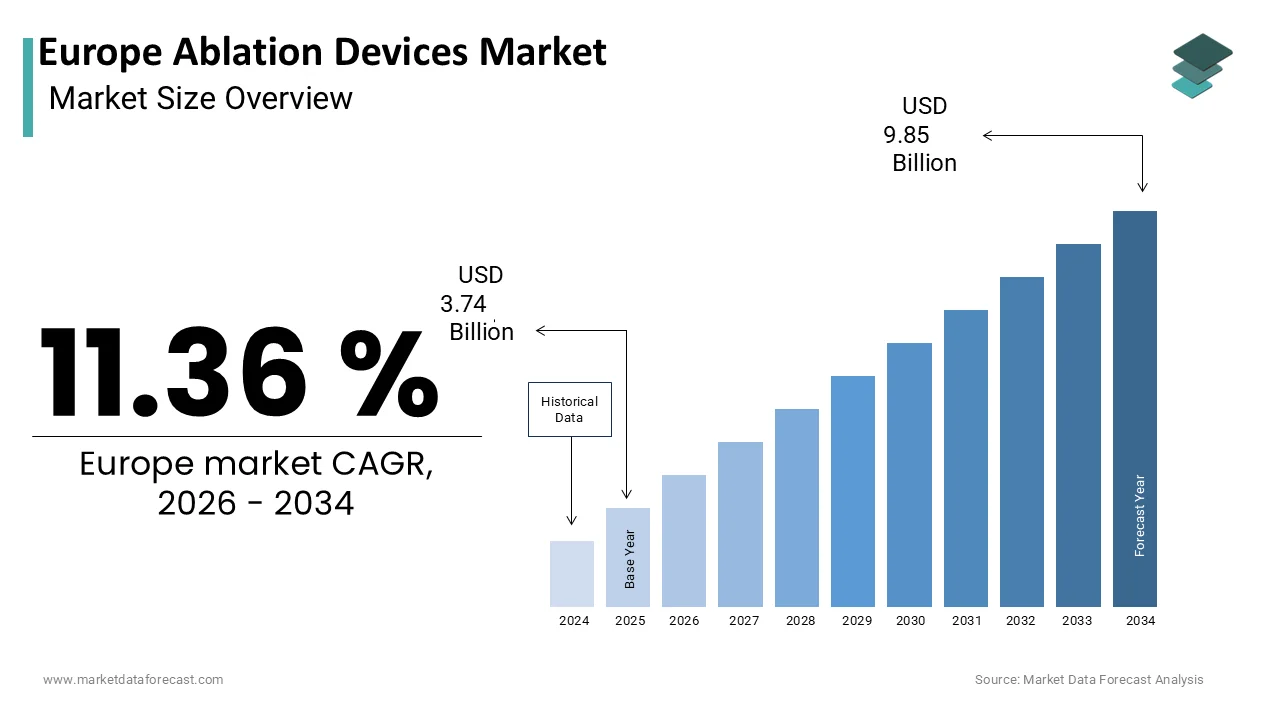
Market Size, 2025
$3.74 BnMarket Estimate, 2026
$4.17 BnMarket Forecast, 2034
$9.85 BnCAGR, 2026–2034
11.36%Europe Ablation Devices Market Size
The europe ablation devices market Size was valued at USD 3.74 billion in 2025, is expected to have a 11.36 % CAGR from 2026 to 2034, and be worth USD 9.85 billion by 2034 from USD 4.17 billion in 2026.
The ablation devices are a specialized medical technology dedicated to the precise destruction of abnormal tissue through thermal, electrical, or chemical means. These devices are predominantly employed in cardiology for arrhythmia management, oncology for tumor ablation, and gynecology for treating uterine fibroids. The clinical adoption of ablation technologies has evolved significantly due to their minimally invasive nature and capacity to reduce hospital stays.
MARKET DRIVERS
Rising Prevalence of Cardiac Arrhythmias Drives Demand for Ablation Devices
The rising prevalence of cardiac arrhythmias is amplifying the growth of the Europe ablation devices market. According to the European Heart Network, atrial fibrillation affects nearly 2% of the general population in Europe, with prevalence escalating to over 10 percent among individuals aged 80 and above. Catheter ablation has emerged as a first-line therapy for symptomatic atrial fibrillation unresponsive to pharmacological management, with the European Society of Cardiology recommending it for eligible patients based on robust clinical evidence. National registries such as the German Ablation Registry document a consistent year-on-year increase in ablation procedures, reporting over 55,000 catheter ablations performed in Germany alone in 2025.
Expanding Applications in Oncology Augment Market Growth
The therapeutic scope of ablation devices has broadened considerably beyond cardiology into interventional oncology for the management of inoperable solid tumors, which is another factor propelling the growth of the Europe ablation devices market. As per the International Agency for Research on Cancer, Europe accounted for approximately 3.9 million new cancer cases in 2025, with liver, kidney, and lung malignancies representing significant portions amenable to local ablation. Image-guided tumor ablation offers a viable alternative for patients ineligible for surgical resection due to comorbidities or tumor location.
MARKET RESTRAINTS
Stringent Regulatory Pathways Impede Timely Market Entry
The rigorous regulatory framework established under the European Union Medical Device Regulation 2017/745 is restraining the growth of the European ablation devices market. As per the European Commission, the transition to this regulation has extended conformity assessment timelines by an average of nine to twelve months compared to the previous Medical Device Directive. Manufacturers must now demonstrate comprehensive clinical evidence, including post-market surveillance data and risk management documentation, which disproportionately affects small and medium-sized enterprises lacking dedicated regulatory infrastructure. The innovative ablation technologies often experience prolonged commercialization cycles, which are limiting patient access and dampening investment incentives.
Reimbursement Uncertainties Limit Procedural Adoption
The inconsistent reimbursement policies are a significant barrier to the widespread utilization of ablation procedures, which is hindering the growth of the European ablation devices market. As per the European Observatory on Health Systems and Policies, only 14 of the 27 European Union member states provide explicit and stable reimbursement codes for complex ablation interventions such as ventricular tachycardia substrate modification. Moreover, the absence of harmonized health technology assessment criteria across Europe results in divergent coverage decisions, fragmenting market access and complicating commercial planning for device manufacturers.
MARKET OPPORTUNITIES
Integration of Artificial Intelligence Presents Strategic Expansion Avenues
The integration of artificial intelligence with ablation platforms is enhancing the procedural precision and workflow efficiency across European electrophysiology and interventional oncology suites, which is greatly influencing the growth of the European ablation devices market. Companies are increasingly embedding machine learning algorithms into ablation consoles to predict arrhythmia recurrence based on real-time impedance and temperature data, thereby personalizing energy delivery. Regulatory bodies have responded proactively, with the European Medicines Agency establishing a dedicated digital health task force to streamline AI-based device evaluations.
Expansion of Ambulatory Care Models Creates New Access Points
The structural shift toward outpatient and day case procedures in healthcare systems is an additional factor to fuel the growth of the European ablation devices market in the coming years. Ablation procedures, particularly for atrial fibrillation using cryoballoon technology, have demonstrated suitability for same-day discharge with complication rates below 2 percent according to the European Heart Rhythm Association. This model reduces hospital bed occupancy and lowers per-procedure costs by an estimated 18 percent, as documented by the European Health Management Association. Device manufacturers are responding with compact, user-friendly systems optimized for outpatient environments, including single-use catheters that mitigate reprocessing burdens.
MARKET CHALLENGES
Workforce Shortages Constrain Procedural Scalability
The persistent deficit of trained interventional specialists capable of performing complex ablation procedures is hampering the growth of the European ablation devices market. According to the European Society of Cardiology, there is a shortfall of approximately 1,800 electrophysiologists across the European Union, with the most acute gaps in Eastern and Southern Europe. This scarcity directly limits procedural capacity, as each electrophysiologist typically performs between 150 and 200 ablations annually, far below the estimated demand driven by rising arrhythmia prevalence.
Technological Obsolescence Risk Due to Rapid Innovation Cycles
The accelerated pace of innovation in ablation technology introduces significant obsolescence risk for healthcare providers and manufacturers alike, complicating capital planning and clinical adoption strategies. As per the European Patent Office, filings related to ablation energy delivery systems increased by 22 percent annually between 2020 and 2023. These next-generation modalities promise superior safety profiles and reduced procedure times, but render existing radiofrequency and cryoablation infrastructure partially redundant. The rapid emergence of pulsed field ablation, which selectively targets myocardial tissue without thermal injury, has already prompted early adopters in Sweden and Belgium to retrofit labs within three years of initial setup. This compression of technology life cycles strains public procurement budgets and discourages long-term commitments to specific platforms. Moreover, clinicians must continuously retrain to maintain proficiency across evolving systems, which is creating operational friction.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Technology, Application, End-use, and Country. |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis; DROC, PESTLE Analysis, Porter's Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Country Covered | UK, Germany, Italy, France, Spain, Sweden, Denmark, Poland, Switzerland, Netherlands, Rest of Europe. |
| Market Leader Profiled | Boston Scientific Corporation, CONMED Corporation, AngioDynamics, AtriCure, Inc.c, Bausch & Lomb Incorporated |
SEGMENT ANALYSIS
By Technology Insights
The radiofrequency segment was the largest by accounting for 42.3% of the Europe ablation devices market share in 2025, with the well-established clinical efficacy, extensive regulatory approvals, and broad applicability across cardiology and oncology. Radiofrequency energy delivers controlled thermal injury with precision, making it the gold standard for catheter ablation in atrial fibrillation. The widespread availability of trained operators and integration with 3D electroanatomic mapping systems further entrench radiofrequency technology in routine clinical practice. Reimbursement stability across Germany, France, and the United Kingdom also supports sustained adoption, with national coding systems consistently covering radiofrequency ablation procedures for both cardiac and hepatic indications.
The cryoablation devices segment is lucratively growing with an expected CAGR of 11.3% throughout the forecast period, with the procedural simplicity and safety advantages of cryoballoon technology, particularly in paroxysmal atrial fibrillation. As per the German Cardiac Society, a 28% year-on-year increase in cryoablation procedures between 2021 and 2023. Regulatory momentum has also favored adoption, with the European Commission granting breakthrough designation to next-generation cryoballoon systems featuring real-time temperature monitoring in 2025.
By Application Insights
The cardiology segment accounted in holding 58.2% of the Europe ablation devices market share in 2025, owing to the rising burden of cardiac arrhythmias, particularly atrial fibrillation, which affects more than 11 million people across the region, as stated by the European Society of Cardiology. Catheter ablation has transitioned from a last resort therapy to a first-line intervention for symptomatic patients, supported by Class I recommendations in the 2020 ESC Guidelines. Moreover, public health initiatives such as the EU-funded AFFECT trial have demonstrated that early ablation reduces stroke risk by 32 percent compared to rate control, reinforcing its preventive value.
The oncology segment is likely to grow with an expected CAGR of 12.1% during the forecast period, with the expanding role of image-guided tumor ablation in managing early-stage and oligometastatic cancers, especially in patients unfit for surgery. The International Agency for Research on Cancer estimates that over 1.2 million new cases of liver, kidney, and lung cancers diagnosed annually in Europe are potentially amenable to local ablation. Technological advances such as multi-tined expandable electrodes and microwave systems capable of treating tumors up to 5 centimeters have broadened clinical applicability.
By End-use Insights
The hospitals segment was the largest by capturing a significant share of the European ablation devices market in 2025, with the complex infrastructure requirements of ablation procedures, including hybrid operating rooms, advanced imaging modalities, and intensive care backup, which are predominantly available in tertiary care hospitals. In Germany, over 90 percent of cardiac ablations occur in university-affiliated hospitals equipped with dedicated electrophysiology labs, as reported by the German Hospital Federation.
The ambulatory surgical centers segment is expected to register a CAGR of 13.8% during the forecast period, with the healthcare system reforms prioritizing cost containment and patient convenience, particularly for low-risk ablation procedures. According to the Organisation for Economic Co-operation and Development, ambulatory settings now handle over 60 percent of all minimally invasive interventions in Denmark and the Netherlands, with cryoballoon ablation for atrial fibrillation increasingly performed as a same-day discharge procedure. Single-use ablation catheters and compact generator systems have further enabled procedural migration by eliminating reprocessing needs and reducing space requirements.
COUNTRY LEVEL ANALYSIS
Germany Ablation Devices Market Analysis
Germany was the largest contributor by holding 22.3% of the European ablation devices market share in 2025, with its dense network of over 300 certified electrophysiology centers and robust public reimbursement under the G-DRG system, which fully covers both radiofrequency and cryoablation for atrial fibrillation. The German Cardiac Society recorded more than 62,000 cardiac ablation procedures in 2025, the highest in Europe, supported by a standardized two-year fellowship program that graduates over 120 new electrophysiologists annually. Additionally, the Federal Joint Committee’s 2021 decision to include ablation in the national atrial fibrillation care pathway has institutionalized its use across primary and secondary care.

United Kingdom Ablation Devices Market Analysis
The United Kingdom held 16.2% of the Europe ablation devices market share in 2025. The NHS Long Term Plan’s commitment to reducing atrial fibrillation-related stroke has accelerated investment in ablation infrastructure, with £120 million allocated between 2021 and 2025 for electrophysiology lab upgrades. In oncology, the UK’s Cancer Drugs Fund has facilitated access to microwave ablation systems for lung metastases, with 28 specialized centers now offering the procedure. Workforce expansion is also underway, with Health Education England approving 40 additional electrophysiology training posts in 2023.
France Ablation Devices Market Analysis
The French ablation devices market is expected to have a significant CAGR during the forecast period, with the centralized care delivery through 45 regional arrhythmia reference centers designated under the National Strategy for Cardiovascular Diseases 2021–2025. However, cryoablation adoption is accelerating, supported by favorable assessments from the Haute Autorité de Santé,é which recognized its superiority in paroxysmal atrial fibrillation. Public procurement through the Union des Groupements d’Achats Publics ensures cost-effective device access across public hospitals.
Italy Ablation Devices Market Analysis
Italy's ablation devices market is expected to have a prominent CAGR in the coming years. The National Health Service provides full reimbursement for ablation in symptomatic atrial fibrillation, though delays persist in Southern regions due to workforce shortages. Italy has emerged as a key adopter of pulsed field ablation, with early clinical trials underway in Milan and Rome under the auspices of the Italian Arrhythmia Registry.
Spain Ablation Devices Market Analysis
The Spanish ablation devices market is expected to have prominent growth opportunities in the coming years. The market is anchored in major university hospitals in Madrid, Barcelona, and Valencia, which collectively perform over 25,000 ablation procedures annually. Spain exhibits strong growth in cryoablation, with a 31 percent increase in usage between 2021 and 2023 as per the Spanish Society of Cardiology, driven by shorter procedural times and favorable outcomes in elderly patients.
COMPETITIVE LANDSCAPE
The Europe ablation devices market features intense competition among multinational medtech leaders and agile innovators vying for clinical and commercial influence. Established players such as Johnson & Johnson, Medtronic,c, and Boston Scientific dominate through vertically integrated platforms combining mapping systems, ablation catheters,e r,s and data analytics. These companies leverage decades of electrophysiology expertise, strong hospital relationships, and extensive training networks to maintain loyalty in high-volume centers. Simultaneously, emerging firms specializing in pulsed field ablation and irreversible electroporation are disrupting the status quo with novel mechanisms that promise enhanced safety and efficiency. Regulatory complexity, reimbursement fragmentation,n and workforce constraints create both barriers and opportunities, shaping a dynamic, competitive landscape. Companies that successfully navigate Europe’s heterogeneous healthcare ecosystems through localized strategies, clinical validation,n and workflow integration are best positioned to capture sustainable growth amid rising procedural demand and technological evolution.
KEY MARKET PLAYERS
Key players operating in the Europe ablation devices market profiled in this report are
- Boston Scientific Corporation,
- CONMED Corporation,
- AngioDynamics,
- AtriCure,.Inc,
- Bausch & Lomb Incorporated,
- Biotronik SE & Co. KG,
- Elekta AB,
- Olympus Corporation,
- Varian,
- Medtronic plc,
- Ethicon, Inc.,
- Abbott Laboratories
- Alcon Laboratories
TOP LEADING PLAYERS IN THE MARKET
- Johnson & Johnson maintains a prominent presence in the Europe ablation devices market through its Biosense Webster subsidiary, which specializes in electrophysiology and cardiac ablation technologies. The company has significantly advanced catheter ablation with its CARTO 3 mapping system and ThermoCool SmartTouch catheter, enabling precise lesion delivery. In recent years, Johnson & Johnson has expanded its European footprint by launching next-generation pulsed field ablation platforms across Germany, France, and the United Kingdom. The company also collaborates with leading European cardiac centers to conduct clinical trials and train electrophysiologists with its commitment to innovation and education in the region.
- Medtronic is a key contributor to the Europe ablation devices market, offering a comprehensive portfolio that spans cardiac cryoablation and radiofrequency systems. Its Arctic Front cryoballoon platform remains widely adopted for atrial fibrillation treatment across Western and Northern Europe. To strengthen its position, Medtronic has invested in real-world evidence generation through registries like the European Cryoablation Registry and introduced AI-enhanced mapping features in its Amplifi system. The company also established a dedicated training academy in the Netherlands to support physician adoption of its latest ablation technologies, reflecting its focus on clinical support and workflow integration in European healthcare settings.
- Boston Scientific plays a vital role in the Europe ablation devices market with its RHYTHMIA HDx mapping system and IntellaNav family of ablation catheters. The company emphasizes technological differentiation through high-resolution mapping and contact force sensing capabilities. Boston Scientific accelerated the commercialization of its pulsed field ablation system in select European countries following CE Mark approval. It also deepened partnerships with university hospitals in Italy and Sweden to validate novel ablation protocols.
MARKET SEGMENTATION
This research report on the europe ablation devices market has been segmented and sub-segmented into the following categories.
By Technology
- Radiofrequency Devices
- Laser/Light Ablation
- Ultrasound Devices
- Cryoablation Devices
- Others
By Application
- Cardiology
- Oncology
- Ophthalmology
- Gynecology
- Urology
- Cosmetic Surgery
- Others
By End-use
- Hospitals
- Ambulatory Surgical Centers
- Others
By Country
- UK
- France
- Spain
- Germany
- Italy
- Russia
- Sweden
- Denmark
- Switzerland
- Netherlands
- Turkey
- Czech Republic
- Rest of Europe