- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
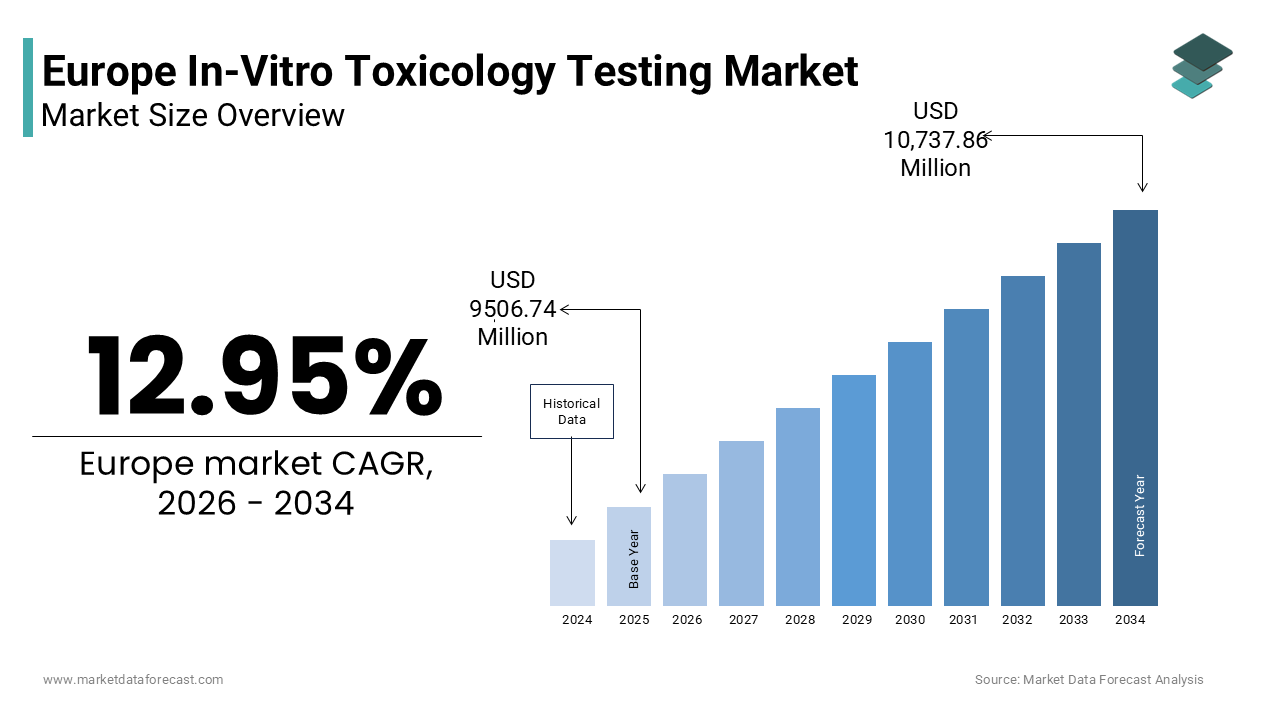
Market Size, 2025
$9506.74 MnMarket Estimate, 2026
$10,737.86 MnMarket Forecast, 2034
$28,445.11 MnCAGR, 2026–2034
12.95%Executive Summary: European In-Vitro Toxicology Testing Market
- Market Scope: Comprehensive European in-vitro toxicology testing market analysis covering products, types, toxicity endpoints & tests, methods, technologies, industries, and country-level landscapes.
- Market Valuation: Valued at USD 9,506.74 million in 2025, estimated at USD 10,737.86 million in 2026, and projected to reach USD 28,445.11 billion by 2034, registering a compound annual growth rate (CAGR) of 12.95% from 2026 to 2034.
- Primary Growth Drivers: Increasing chronic diseases, growing aging population, technological advancements, strict anti-animal testing regulations and bans by European governments, and favorable policies in drug discovery. Key market restraints include high technology costs and a general lack of awareness regarding in-vitro toxicology testing utilization.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Product | Assays (commanded the largest market share in 2025 due to widespread use in early-stage compound screening) | Services & Reagents (expanding rapidly driven by outsourced contract research and labware demand) |
| By Method | In-Silico Method (estimated to command the largest market share in 2025 supported by computational prediction models) | Cellular Assays (experiencing high traction due to improved physiological relevance and accuracy) |
| By Industry | Cosmetics & Household Products (expected to account for the largest share in 2025 backed by animal testing bans) | Pharmaceutical (growing strongly driven by early drug discovery toxicity identification and cost reduction goals) |
| By Country / Region | Germany (estimated to account for the largest market share in Europe in 2025 supported by advanced healthcare infrastructure) | France (projected to grow at the highest CAGR during the forecast period backed by robust research and regulatory alignment) |
Major Market Players & Market Structure
Market Structure: Highly competitive life sciences and toxicology testing market featuring major global analytical testing laboratories and specialized providers focusing on non-animal testing technologies, OMICS integration, and advanced computational platforms.
Key Companies: Covance, Inc. (LabCorp), Agilent Technologies, Inc., Bio-Rad Laboratories, Inc., Eurofins Scientific SE, General Electric Company, BioReliance, Inc., Charles River Laboratories International, Inc., Thermo Fisher Scientific, Inc., Catalent, and Cyprotex.
 Download Free Sample Report
European In-Vitro Toxicology Testing Market Size
The europe In-vitro toxicology testing market size was valued at USD 9506.74 million in 2025 and is anticipated to reach USD 10,737.86 million in 2026 from USD 28,445.11 billion by 2034, growing at a CAGR of 12.95% during the forecast period from 2026 to 2034.
In-vitro toxicology testing is the practice of checking if chemical substances, drugs, or products are harmful by using isolated cells or tissues in a lab instead of live animals. This market is pivotal in facilitating the transition away from traditional animal testing aligning with stringent ethical standards and regulatory mandates across the European Union. As per the European Commission, around 9 million animals are recorded annually for experimental and scientific procedures across the EU and Norway. According to the European Chemicals Agency, approximately 25,000 chemical substances are registered in the central public database under the REACH regulation. The market is characterized by advanced technological adoption including three dimensional cell cultures and organ on chip systems which provide superior predictive accuracy for human health outcomes. Regulatory bodies such as the European Medicines Agency actively promote the integration of these non animal methods into standard testing protocols. Consequently the Europe In-Vitro Toxicology Testing Market serves as a critical enabler of compliant sustainable and scientifically robust safety evaluation strategies supporting both industrial innovation and public health protection across the continent.
MARKET DRIVERS
Stringent Legislative Bans on Animal Testing for Cosmetics and Chemicals
The comprehensive legislative framework prohibiting animal testing for cosmetic ingredients and restricting it for industrial chemicals is one of the major factors driving the Europe in-vitro toxicology testing market. According to the European Commission, the full marketing ban on animal-tested cosmetics has been active since 2013, driving global personal care brands to adopt non-animal methods to access the European single market. As per statistics compiled by Humane World for Animals, 45 countries have prohibited cosmetics animal testing, accelerating international industry alignment toward alternative toxicology workflows. The regulatory mandate directly influences market dynamics because companies must utilize approved in vitro assays such as those for skin irritation and eye corrosion to access the European market. The Organization for Economic Co operation and Development has validated numerous in vitro test guidelines which are accepted by EU regulators providing a clear pathway for compliance. Furthermore the REACH regulation encourages the use of alternative methods whenever possible to minimize animal use for industrial chemicals. These legal requirements ensure a steady and growing demand for in vitro toxicology services and products as compliance becomes a non negotiable prerequisite for market entry and product sustainability in the region.
High Pharmaceutical R&D Expenditure and Drug Safety Prioritization
Substantial investment in pharmaceutical research and development is coupled with the critical need for early identification of drug toxicity, which further propels Europe in-vitro toxicology testing market. This combination significantly drives the demand for advanced in vitro testing models in the region. According to the European Federation of Pharmaceutical Industries and Associations, the pharmaceutical sector in Europe scales up its research and development investments to over 55 billion euros annually. As per the National Center for Biotechnology Information archives, an average of 90% of drug candidates entering clinical trials fail during subsequent phase studies due to a lack of clinical efficacy or unmanageable toxicity. The high failure rate creates a strong economic incentive for pharmaceutical companies to adopt in vitro human cell based assays that offer better predictive accuracy for human responses thereby reducing costly late stage attritions. The integration of patient derived cells and induced pluripotent stem cells allows for tailored toxicity profiling that supports the development of targeted therapies. Regulatory initiatives such as the Innovative Medicines Initiative further support the development of new approach methodologies. This combination of financial pressure to improve R&D efficiency and regulatory encouragement for human relevant data ensures sustained growth in the in vitro toxicology testing market as companies seek to de risk their pipelines and accelerate time to market for new therapeutics.
MARKET RESTRAINTS
Complexity in Replicating Systemic Physiological Interactions
The inherent scientific challenge in replicating the complex systemic interactions of a whole living organism is a significant restraint on the Europe in-vitro toxicology testing market. It is difficult to mimic these metabolic processes using isolated cell or tissue models. According to the National Institutes of Health, the integration of microfluidics and multi-organ-on-a-chip platforms mimics complex physiological networks like the liver-kidney axis to refine predictions of systemic toxicity and metabolic clearance. The limitation directly impacts market confidence as regulatory bodies remain cautious about accepting in vitro data for complex endpoints like carcinogenicity and reproductive toxicity without corroborative evidence from other methods. The lack of vascularization and proper blood flow in static cell cultures further restricts the ability to model distribution and clearance of toxicants accurately. Consequently many companies hesitate to rely solely on in vitro methods for final safety assessments leading to continued dependence on animal testing for comprehensive risk evaluation. This scientific gap necessitates ongoing investment in more sophisticated models such as organ on chip systems which are currently expensive and not yet fully standardized. Until these technological hurdles are overcome, the perceived reliability gap will restrain broader adoption. This will limit the market potential for in vitro solutions in critical regulatory decision-making processes.
High Initial Investment Costs and Technical Expertise Shortages
The substantial financial investment required for setting up advanced in vitro testing laboratories and the shortage of skilled professionals are major barriers to the expansion of the Europe in-vitro toxicology testing market. This trend is particularly true for small- and medium-sized enterprises. As per the European Commission, substantial multi-year funding has been allocated toward alternatives to animal testing. As per the European Society of Toxicology In Vitro, international scientists and regulatory professionals are expanding the application of 3D microphysiological systems and computational approaches to shift toxicology toward non-animal safety assessments. The skills gap directly affects market penetration as companies struggle to find qualified personnel to operate sophisticated equipment and interpret complex data sets accurately. The high operational costs associated with maintaining sterile conditions sourcing high quality primary cells and validating new assays further strain budgets. Small contract research organizations often lack the resources to invest in these advanced capabilities forcing them to rely on outsourced services which may delay project timelines. Additionally the rapid pace of technological change means that equipment and protocols become obsolete quickly requiring continuous reinvestment. These financial and human resource constraints limit the ability of many potential users to adopt in vitro methods independently thereby slowing down overall market growth and restricting access to these advanced testing solutions for smaller players in the pharmaceutical and chemical industries.
MARKET OPPORTUNITIES
Advancements in Organ on Chip and Three Dimensional Culture Technologies
Emerging technologies such as organ-on-chip systems and advanced three-dimensional cell cultures offer transformative opportunities for the Europe in-vitro toxicology testing market. These pave the way for enhancing its predictive power and applicability in the region. According to the Wyss Institute at Harvard University, human organs-on-chips microdevices mimic the complex structural, biochemical, and mechanical microenvironments of living organs to serve as an accurate, human-relevant alternative to conventional cell cultures and animal models. As per the European Commission under its regional framework initiatives, public and private programs are accelerating multi-million euro investments into New Alternative Methodologies (NAMs) to progressively reduce and replace reliance on animal testing within biotech and medical pipelines. The technological evolution directly benefits the in vitro toxicology market by enabling the study of complex toxicological endpoints such as organ specific toxicity and drug drug interactions in a controlled setting. These systems allow for real time monitoring of cellular responses providing dynamic data that static assays cannot capture. Pharmaceutical companies are increasingly partnering with technology providers to integrate these platforms into their early drug discovery workflows to identify toxic liabilities earlier. Regulatory agencies are beginning to recognize the value of these advanced models through pilot programs and collaborative initiatives. This convergence of engineering biology and data science creates a lucrative opportunity for market players to offer premium high value testing services that bridge the gap between simple cell assays and whole animal studies.
Integration of Artificial Intelligence and Computational Toxicology
The integration of artificial intelligence and machine learning with in vitro data unlocks potential to enhance predictive accuracy and reduce the need for extensive experimental testing in the European market. According to the European Centre for the Validation of Alternative Methods procedural guidelines, modern chemical hazard evaluations rely on a structured modular approach that systematically assesses predictive capacity and performance standards to harmonize non-animal safety testing. As per the American Chemical Society inside the Journal of Chemical Information and Modeling, machine learning workflows and molecular descriptors are increasingly integrated to predict chemical mutagenicity and build accurate compound categories prior to regulatory laboratory testing. The synergy directly expands the market by offering hybrid solutions that combine experimental data with predictive analytics providing faster and more cost effective risk assessments. Companies can leverage these tools to screen vast libraries of chemicals efficiently identifying potential hazards before committing to resource intensive in vitro testing. The ability to model complex dose response relationships and mixture effects using AI further enhances the utility of in vitro data for regulatory submissions. Regulatory bodies are increasingly open to accepting read across and quantitative structure activity relationship data supported by robust in vitro evidence. This digital transformation enables service providers to offer comprehensive toxicology packages that include both experimental and computational components. By adopting AI-driven platforms, market participants can differentiate their offerings. This allows them to address the growing demand for rapid and scalable safety assessment solutions in the chemical and pharmaceutical sectors.
MARKET CHALLENGES
Lack of Global Harmonization in Regulatory Acceptance
The absence of globally harmonized regulatory standards for accepting in vitro toxicology data creates significant uncertainty, which holds back the expansion of the Europe in-vitro toxicology testing market. This complicates the commercialization of products for companies operating in multiple jurisdictions. According to the International Council for Harmonisation, unified technical guidelines are implemented across the United States, Europe, and Japan to actively prevent the duplication of animal testing and enhance global safety data acceptability. As per the World Health Organization, global regulatory authorities are expanding international collaboration to eliminate fragmented product approval pipelines and harmonize non-clinical safety testing standards. The fragmentation directly challenges market growth as companies must navigate a complex array of varying requirements increasing time and costs associated with product registration. Manufacturers often face situations where an in vitro method accepted in Europe is rejected elsewhere forcing them to maintain parallel testing strategies using both animal and non animal methods. The lack of mutual recognition agreements for alternative methods hinders the global scalability of in vitro solutions. Efforts to harmonize standards are ongoing but progress is slow due to differing scientific opinions and regulatory cultures. This inconsistency discourages investment in new in vitro technologies as companies fear that their data may not be accepted in key export markets. Until greater alignment is achieved, the market will continue to face headwinds from regulatory fragmentation. This fragmentation limits the full potential of in vitro toxicology testing as a universal replacement for animal studies.
Limited Scope for Complex Toxicological Endpoints
Current in vitro models struggle to adequately address complex toxicological endpoints, which inhibits the expansion of the Europe in-vitro toxicology testing market. These endpoints include developmental neurotoxicity, immunotoxicity, and chronic carcinogenicity, which require long-term observation and systemic interaction. According to the European Chemicals Agency June 2026 report, in vitro methods dominate skin and eye irritation testing under REACH, while complex endpoints like repeated-dose toxicity face validation challenges. As per a review in the Archives of Toxicology, research labs utilize tiered workflows and concentration-time-effect models to address chronic exposure risks without vertebrate animals. The limitation directly challenges the market as regulators and industry stakeholders remain reliant on animal studies for these critical endpoints ensuring that in vitro methods cannot yet fully replace traditional testing for comprehensive risk assessment. The inability to model the blood brain barrier effectively or simulate long term immune responses restricts the applicability of in vitro tests for neurological and autoimmune diseases. Developing models that can sustain cell viability and function over extended periods remains a significant scientific hurdle. Additionally the lack of standardized protocols for long term in vitro studies creates variability in data quality and reproducibility. These scientific constraints mean that in vitro toxicology testing is often viewed as a complementary tool rather than a standalone solution for comprehensive safety evaluation. Overcoming these limitations requires substantial research investment and innovation which poses a persistent challenge to market expansion and broader regulatory acceptance.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 12.95% |
| Segments Covered | By Product, Type, Toxicity Endpoints & Tests, Method, Technology, Industry and Region |
| Various Analyses Covered | Global, Regional and Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | UK, France, Spain, Germany, Italy, Russia, Sweden, Denmark, Switzerland, the Netherlands, Turkey, the Czech Republic, and the Rest of Europe. |
| Market Leaders Profiled | Covance, Inc. (A subsidiary of LabCorp) (U.S.), Agilent Technologies, Inc. (U.S.), Bio-Rad Laboratories, Inc. (U.S.), Eurofins Scientific SE (Luxembourg), General Electric Company (U.S.), BioReliance, Inc. (U.S.), Charles River Laboratories International, Inc. (U.S.), Thermo Fisher Scientific, Inc. (U.S.), Catalent (U.S.) and Cyprotex (U.K.). |
SEGMENTAL ANALYSIS
By Product Insights
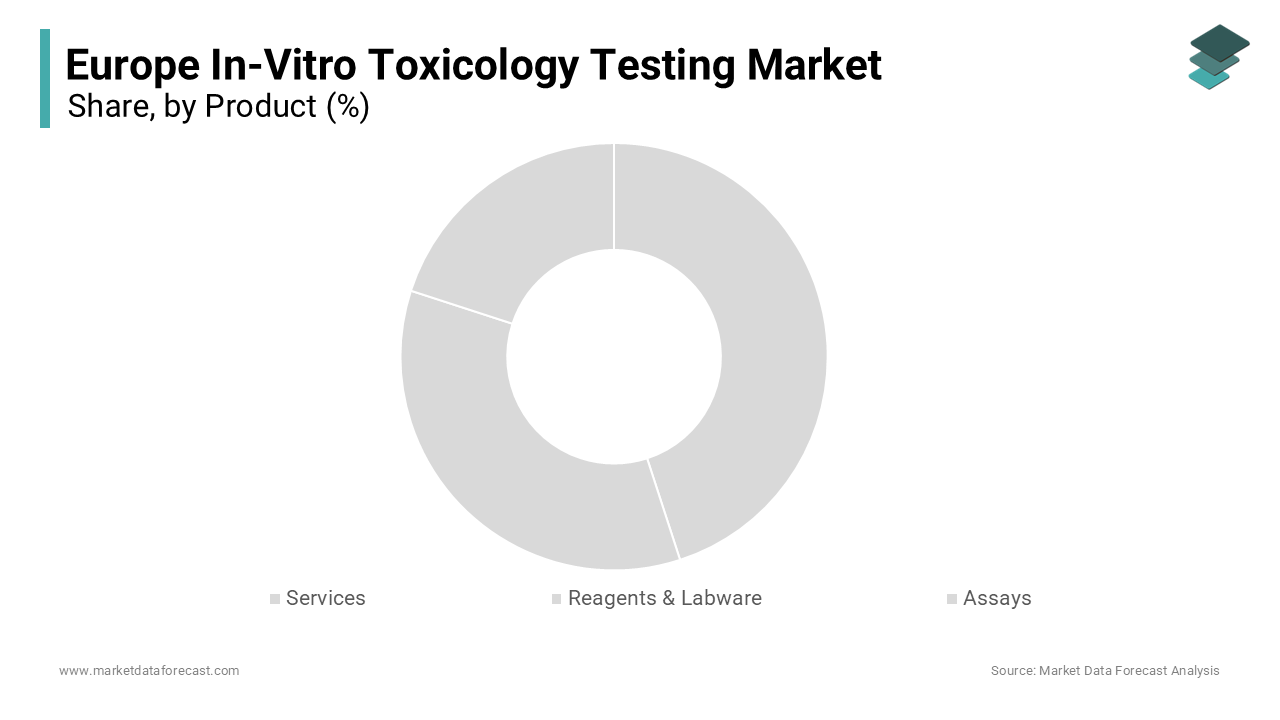
The services segment dominated the Europe In-Vitro Toxicology Testing Market and accounted for a substantial share in 2025. This dominance of the segment was driven by the increasing tendency of pharmaceutical and chemical companies to outsource complex testing requirements to specialized contract research organizations. According to the European Federation of Pharmaceutical Industries and Associations, pharmaceutical companies in Europe scale up collaborations with contract research organizations to outsource non-clinical toxicology workflows and manage rising drug discovery expenditures. As per the Association of Clinical Research Organizations, contract research operations see sustained demand across regional teams to deploy compliance-driven protocols that align with shifting transnational safety regulations. The shift directly drives market expansion as service providers invest in advanced technologies and hire skilled personnel to meet client needs. Outsourcing allows sponsors to focus on core competencies such as drug design while leveraging the operational efficiency of external partners. The complexity of new modalities such as cell and gene therapies requires specialized testing capabilities that many internal labs lack. Service providers offer flexible engagement models ranging from full project management to specific assay execution catering to diverse client preferences. This strategic alignment between sponsors and service providers ensures sustained growth in the services segment as the industry seeks agility and expertise in navigating evolving regulatory landscapes across the continent.
The growing complexity of global regulatory requirements for chemical and drug safety assessments is fueling rapid growth in consulting and interpretation services within the market. According to the European Medicines Agency, companies seeking central market entry for pharmaceutical products navigate specialized centralized evaluation pathways to secure uniform therapeutic authorizations. As per the European Chemicals Agency, prolonged risk assessment and registration cycles can introduce timeline extensions due to gaps or delivery delays in applicant technical submittals. These challenges create a strong demand for service providers who can navigate regulatory pathways and ensure data integrity for submissions under REACH and CLP regulations. Consultants help companies design testing strategies that align with current guidelines reducing the risk of rejection and rework. The integration of new approach methodologies into regulatory frameworks requires specialized knowledge that many internal teams lack. Service providers offer training and support to help clients adopt these new methods effectively. Additionally the need for independent third party validation of in vitro methods drives demand for accredited testing services. This regulatory burden ensures that the services segment will continue to grow at an accelerated pace as companies seek to mitigate compliance risks and accelerate time to market through expert partnership.
The reagents and labware segment is anticipated to witness the fastest CAGR of 8.5% between 2026 and 2034 due to the rapid adoption of advanced three dimensional cell culture models and organ on chip systems. According to the European Commission, dedicated funding initiatives actively channel capital into developing highly biomimetic non-animal testing structures to modernise regional biotechnology and health platforms. As per structural publications inthe Journal of Tissue Engineering and Regenerative Medicine, research groups deploy three-dimensional spheroid models and advanced biomaterials such as hyaluronic acid or chitosan to recreate tissue microenvironments more closely than conventional monolayer cultures. The technological evolution directly benefits the market by creating a consistent need for specialized consumables that are not interchangeable with traditional two dimensional culture supplies. Moreover, the transition to more sophisticated models requires precise control over cellular microenvironments necessitating premium reagents with defined compositions. Manufacturers are responding by developing kits specifically designed for organoid and tissue engineering applications. The reproducibility of experimental results depends heavily on the quality of these reagents encouraging researchers to invest in validated products. Consequently this segment grows rapidly as the scientific community shifts toward more predictive and human relevant testing platforms that rely on advanced material science.
The increasing emphasis on standardization and quality control in in vitro testing is accelerating the demand for certified reagents and specialized labware. According to the Organization for Economic Co-operation and Development, global testing frameworks offer mutually recognized non-animal methodologies that allow international laboratories to coordinate compliance evaluations across cross-border markets. As per procedure updates via the European Centre for the Validation of Alternative Methods, scientific committees optimize chemical hazard evaluations by implementing unified performance standards and modular validation checks to ensure non-animal test reproducibility. The regulatory pressure directly influences market dynamics as laboratories must source materials that meet rigorous specifications to maintain accreditation and regulatory acceptance. The variability in biological responses can be minimized by using high consistency reagents reducing the risk of experimental failure. Suppliers who provide certificates of analysis and batch to batch consistency gain a competitive advantage in this quality driven market. Additionally the rise of automated high throughput screening systems requires labware with precise dimensions and optical properties compatible with robotic handlers. This technical requirement further boosts demand for specialized consumables. Consequently the reagents and labware segment expands rapidly as the industry prioritizes data reliability and operational efficiency in safety assessment workflows.
By Type Insights
The ADME testing segment led the Europe In-Vitro Toxicology Testing Market and captured a significant share in 2025. This leading position of the segment was attributed to its critical role in determining the pharmacokinetic profile and potential toxicity of drug candidates early in the development process. According to the European Medicines Agency, poor pharmacokinetics and toxicity profiles remain primary triggers for clinical failures, accounting for nearly 40% of unsuccessful drug development pipelines. As per data inside the Journal of Pharmaceutical Sciences, discovery teams routinely integrate automated, high-throughput in vitro screening of ADME attributes like solubility, permeability, and metabolic stability during lead optimization before selecting candidate molecules for animal study. Understanding how a drug is absorbed distributed metabolized and excreted is essential for predicting human dosage and potential drug drug interactions. In vitro models such as hepatocyte cultures and permeability assays provide valuable insights into these processes without the need for animal studies. Regulatory agencies require comprehensive ADME data for investigational new drug applications making this testing mandatory for market entry. Consequently the segment remains dominant as it serves as a gatekeeper for drug development pipelines ensuring that only viable candidates proceed to expensive clinical phases.
The widespread adoption of advanced liver cell culture models for metabolism studies significantly contributes to the dominance of the ADME segment. According to the European Association for the Study of the Liver, investigators are expanding the deployment of human-induced pluripotent stem cell-derived lineages inside three-dimensional matrix capsules to detect complex patient-specific mutations and metabolic phenotypes. As per the Journal of Hepatology, labs utilize advanced three-dimensional engineered tissue platforms to simulate accurate physiological contractility and capture complex intracellular lipid metabolic fluxes under structural stress conditions. The advancements directly impact market dynamics by providing scalable and consistent sources of human liver cells for ADME testing. In addition, the ability to maintain metabolic activity in vitro for extended periods allows for the study of chronic exposure effects and enzyme induction. Three dimensional spheroid cultures further enhance physiological relevance by mimicking the tissue architecture of the liver. These improved models increase confidence in in vitro predictions reducing the need for confirmatory animal studies. Pharmaceutical companies are increasingly relying on these advanced systems to screen for metabolic liabilities such as reactive metabolite formation which can cause liver injury. The continuous improvement in cell model fidelity ensures that ADME testing remains the cornerstone of preclinical safety assessment driving sustained demand for related products and services.
The toxic substance segment is emerging as the fastest-growing type owing to stringent global regulations requiring comprehensive safety data for industrial chemicals and consumer products registered under REACH. According to the European Chemicals Agency, there are an estimated 350,000 distinct chemicals and chemical mixtures on the global market today, while over 26,600 chemical items are tracked locally within the central regional registry framework. As per the European Commission, the regional REACH regulation imposes structural assessment obligations on substances distributed above 1 tonne annually, which drives laboratories to continually evaluate non-animal alternative approaches to achieve compliance. The regulatory pressure directly translates to market growth as manufacturers seek efficient ways to comply with data requirements. The shift away from animal testing for industrial chemicals is particularly pronounced in Europe where alternatives are legally preferred. In vitro methods for skin corrosion eye irritation and sensitization are now standard requirements for chemical registration. The sheer volume of substances needing evaluation creates a sustained pipeline of testing projects. Additionally the classification labeling and packaging regulation requires specific hazard data that can only be generated through validated in vitro assays. This regulatory mandate ensures that the toxic substance segment will continue to expand rapidly as companies strive to maintain market access for their chemical portfolios in compliance with global safety standards.
Growing consumer awareness regarding product safety and environmental impact is driving brands to proactively test for toxic substances using advanced in vitro methods. According to the European Consumer Organisation, 73% of consumers report a readiness to pay higher prices for products with proven environmental sustainability metrics. As per sources, consumer brand goods with a demonstrated, verified corporate commitment to sustainability grow their annual retail sales more than 4% globally. The consumer demand directly influences corporate strategies prompting companies to go beyond minimum regulatory requirements to ensure product purity and safety. In vitro testing allows for the detection of trace contaminants and impurities that may pose health risks even at low levels. Brands use these data points in marketing campaigns to build trust and differentiate themselves in competitive markets. The rise of clean beauty and green chemistry initiatives further amplifies the need for sensitive toxicity screening. Companies are investing in proprietary in vitro panels to assess the safety of novel ingredients before launch. This proactive approach to risk management ensures that the toxic substance segment will experience accelerated growth as businesses prioritize brand reputation and consumer trust in an increasingly informed marketplace.
By Toxicity Endpoints & Tests
In 2025, the dermal toxicity segment held the majority share in the European in-vitro toxicology testing market because of mandatory regulatory requirements for assessing skin irritation, corrosion, and sensitization for cosmetics and industrial chemicals. According to the European Union Reference Laboratory for Alternatives to Animal Testing, GLP-certified laboratories routinely deploy reconstructed human epidermis (RhE) models like EpiDerm and EPISKIN-SM to evaluate skin irritation within regulatory conformity dossiers. As per the European Chemicals Agency, registered industrial substances face a 90% decline in new in vivo animal testing for skin and eye irritation endpoints due to the broad regulatory application of validated in vitro methods. The regulatory acceptance directly drives market dominance as companies must utilize these specific assays to ensure product safety and legal market access. The high prevalence of skin contact with consumer products makes dermal safety a primary concern for manufacturers. The availability of standardized protocols and commercial kits for dermal testing facilitates easy adoption by laboratories. Furthermore the cosmetic industry’s complete ban on animal testing relies entirely on these in vitro dermal models for safety assessment. Consequently this segment remains the largest contributor to market revenue as it serves as a fundamental requirement for a wide range of consumer and industrial products.
The continuous launch of new consumer products including cosmetics personal care items and household cleaners significantly contributes to the dominance of the dermal toxicity segment. According to the European Commission, personal care products introduced to the EU internal market must comply with a complete animal testing ban, requiring a non-animal safety profile before consumer retail distribution. As per the European Chemicals Agency, commercial formulations containing industrial mixtures must integrate structural hazard profiling and route-specific corrections to evaluate human dermal exposure risks accurately. The high volume of product introductions directly influences market dynamics by creating a steady and recurring demand for dermal toxicity assays. Manufacturers often reformulate existing products to improve performance or reduce environmental impact requiring retesting of dermal safety profiles. The short lifecycle of many consumer goods means that testing is a continuous process rather than a one time event. In vitro dermal tests offer rapid turnaround times allowing companies to accelerate product development cycles. This operational efficiency makes them the preferred choice for high throughput screening in the fast moving consumer goods sector. Consequently the dermal toxicity segment maintains its leadership position driven by the relentless pace of innovation and product renewal in the consumer market.
The genotoxicity testing segment is on the rise and is expected to be the fastest growing segment in the market by witnessing a CAGR of 9.2% from 2026 to 2034. This swift expansion of the segment is propelled by its critical role in identifying potential carcinogens and mutagens early in the development process. According to the International Agency for Research on Cancer monograph evaluation framework, chemical carcinogens are systematically categorized by screening their performance against 10 key biological characteristics, including an agent's explicit genotoxic capacity. As per the European Food Safety Authority, food ingredient submittals must execute a mandatory Tier 1 core toxicology screening that prioritizes New Approach Methodologies (NAMs) to flag potential mutagenic alerts. The regulatory requirement directly drives market expansion as companies seek to eliminate compounds with DNA damaging potential before they reach later stages of development. In vitro genotoxicity tests such as the Ames test and micronucleus assay are cost effective and rapid allowing for high throughput screening of large chemical libraries. The ability to detect genetic damage early reduces the risk of costly late stage failures and regulatory rejections. Advances in molecular biology have improved the sensitivity and specificity of these assays making them more reliable. Consequently this segment grows rapidly as it serves as a crucial filter in the safety assessment pipeline for various industries.
The integration of advanced molecular biology techniques such as next generation sequencing and high content imaging is accelerating the adoption of genotoxicity testing. According to Environmental Health Perspectives, a standard in vitro testing battery combines the bacterial reverse mutation assay (OECD TG 471) and the micronucleus assay (OECD TG 487) to map gene mutations and structural chromosome damage. As per research, laboratory technicians actively transition toward advanced air-liquid interface systems and complex cell co-cultures to capture primary and secondary non-animal genotoxic mechanisms. The technological evolution directly benefits the market by offering more comprehensive and predictive data that regulators value. These advanced techniques allow for the identification of biomarkers associated with genotoxic stress enabling earlier and more accurate detection. Pharmaceutical and chemical companies are adopting these sophisticated methods to enhance their safety profiles and support regulatory submissions. The ability to mechanistically understand genotoxic effects helps in designing safer molecules. Regulatory agencies are increasingly open to data generated from these advanced in vitro systems. Consequently the genotoxicity segment expands rapidly as it leverages cutting edge science to provide superior safety assessments that protect human health and ensure regulatory compliance.
By Industry Insights
The pharmaceutical segment was the largest in 2025 and occupied a commanding share of the Europe In-Vitro Toxicology Testing Market. This supremacy of the segment was supported by substantial research and development investments and stringent regulatory requirements for drug safety. As per the European Medicines Agency, applicants submit standardized preclinical data packets to verify safety profiles, while a specialized pilot framework handles the voluntary submission of New Approach Methodologies (NAMs).The regulatory mandate directly drives market dominance as pharmaceutical companies cannot proceed to clinical trials without robust safety data. The high cost of drug development encourages the use of in vitro models for early screening to identify toxic liabilities and reduce attrition rates. In vitro tests offer human relevant data that improves the predictability of clinical outcomes. The complexity of new biologics and small molecules requires specialized testing capabilities that in vitro platforms provide. Consequently the pharmaceutical segment remains the largest consumer of in vitro toxicology services and products driven by the critical need to ensure drug safety and efficacy.
The growing focus on personalized medicine and targeted therapies significantly contributes to the leadership of the pharmaceutical segment. According to the European Alliance for Personalised Medicine, healthcare stakeholders are accelerating the rollout of next-generation sequencing (NGS) guidelines across multiple countries to refine targeted tumor treatments. As per the Journal of Translational Medicine, investigators utilize patient case data and long-term immunomodulatory monitoring to evaluate severe cytokine release syndrome and manage therapeutic drug interventions. The clinical approach directly influences market dynamics as pharmaceutical companies seek to understand individual variations in drug response and toxicity. In vitro platforms enable the testing of drugs on cells with specific genetic backgrounds providing insights into potential adverse events in susceptible subgroups. This capability is crucial for optimizing dosing and minimizing risks in personalized treatment plans. Regulatory agencies encourage the use of these advanced models to support label claims for targeted therapies. Consequently the pharmaceutical segment maintains its leading position by leveraging in vitro toxicology to drive innovation in personalized healthcare and improve patient outcomes.
The cosmetics and household products segment is likely to experience the fastest CAGR of 10.5% during the forecast period. This rapid growth of the segment is fuelled by the strict ban on animal testing in the European Union and rising ethical consumerism. As per the European Commission, personal care products sold within the region must completely bypass animal testing models to meet mandatory regulatory compliance thresholds. The regulatory and consumer pressure directly drives market expansion as companies seek validated non animal tests to ensure product safety and market access. The household products sector is also facing increasing pressure to demonstrate safety without animal testing leading to broader adoption of in vitro methods for irritancy and sensitization. The availability of OECD validated in vitro tests for these endpoints facilitates compliance. Consequently this segment grows rapidly as it aligns with both legal mandates and societal values promoting ethical and sustainable business practices.
The trend toward natural and organic ingredients in cosmetics and household products is fueling rapid growth in the in vitro toxicology testing market. According to the European Organic Certifiers Council, control bodies cooperate across cross-border networks to coordinate certification frameworks and maintain standard compliance for organic agricultural derivatives. As per the Soil Association, consumer beauty and wellbeing formulations require formal certification symbols to verify that every stage of the raw ingredient production supply chain has been checked. The variability directly benefits the market by creating a need for extensive in vitro testing to characterize the safety profile of each batch of natural extract. In vitro models allow for the assessment of complex mixtures that are common in natural products. Manufacturers use these tests to verify the absence of allergens and irritants in raw materials. The claim of being natural does not exempt products from safety regulations making testing essential. Consequently the cosmetics and household products segment expands rapidly as the industry innovates with natural formulations that require thorough scientific validation to ensure consumer safety and regulatory compliance.
COUNTRY ANALYSIS
Germany In-Vitro Toxicology Testing Market Analysis
Germany was the top performer in the Europe In-Vitro Toxicology Testing Market and accounted for a substantial share in 2025. This prominence of the German market was driven by its robust pharmaceutical and chemical industries and strong regulatory framework. According to the German Federal Ministry of Education and Research, institutional funding initiatives since 1980 have allocated around 200 million euros to support more than 620 distinct projects developing alternative non-animal methodologies. As per the German Chemical Industry Association, Germany maintains the single largest chemical processing footprint in Europe, generating nearly 30% of total Eurozone chemical market revenues. The presence of leading contract research organizations and academic institutions fosters innovation in alternative testing methods. Strict adherence to EU regulations ensures high standards for safety assessment. The country’s focus on sustainability and green chemistry further promotes the use of in vitro toxicology. This combination of industrial strength and scientific excellence ensures that Germany remains the dominant force in the regional market setting trends for technology adoption and regulatory compliance.
France In-Vitro Toxicology Testing Market Analysis
France followed closely behind in the Europe in-vitro toxicology testing market and captured a significant share in 2025. This position of the French market was supported by its strong cosmetics industry and commitment to animal welfare. According to the European Commission, personal care companies selling within Europe must replace animal testing entirely with non-animal alternatives to distribute their formulations inside the single market. As per the French National Institute of Health and Medical Research, domestic laboratories are accelerating the development of specialized three-dimensional organoids, microfluidic models, and complex in vitro microphysiological systems under nationwide 3R initiatives. The government actively supports research into organ on chip technologies and other advanced in vitro models. The high concentration of cosmetic manufacturers drives consistent demand for dermal toxicity and sensitization tests. Regulatory agencies in France work closely with industry to validate new methods. This supportive ecosystem ensures that France remains a key hub for in vitro toxicology innovation particularly in the cosmetics sector influencing global best practices.
United Kingdom In-Vitro Toxicology Testing Market Analysis
The United Kingdom maintains a strong position in the European market despite Brexit. This stability is driven by its world-class research infrastructure and pharmaceutical sector. As per the Chemical Industries Association, cross-border trade between the UK and the European Union relies on independent hazard frameworks following the implementation of post-Brexit national regimes. According to the Association of the British Pharmaceutical Industry, biopharmaceutical teams actively scale up early-stage industry-academic collaborations to leverage advanced automated cell cultures and innovative molecular screening technologies. The presence of renowned universities and research centers fosters innovation in new approach methodologies. The UK government has committed to ending animal testing for cosmetics and is exploring similar bans for other sectors. This progressive stance encourages the adoption of in vitro methods. The strong intellectual property framework protects innovations in testing technologies. Consequently, the UK remains a vital market for in vitro toxicology services contributing significantly to regional growth and scientific advancement.
Italy In-Vitro Toxicology Testing Market Analysis
Italy maintains a noteworthy share of the Europe in-vitro toxicology testing market due to its significant cosmetics and pharmaceutical industries. According to Cosmetica Italia, Italian manufacturing labs dominate the continental personal care market by producing 67% of all cosmetic makeup consumed across Europe. As per the National Center for Biotechnology Information databases, approximately 90% of prospective pharmaceutical candidate molecules enter a downward trend and fail during human clinical test phases due to safety or efficacy constraints. The country has a strong tradition in chemical manufacturing which contributes to the demand for REACH compliant testing. Government initiatives to support innovation in biotechnology are fostering the adoption of advanced in vitro models. The presence of specialized laboratories and contract research organizations enhances local capacity. Cultural emphasis on quality and safety in personal care products drives brand investment in rigorous testing. This dynamic environment ensures that Italy continues to grow as an important market for in vitro toxicology solutions in Southern Europe.
Spain In-Vitro Toxicology Testing Market Analysis
Spain exhibits steady growth in the Europe in-vitro toxicology testing market owing to its expanding pharmaceutical and chemical sectors. According to the European Medicines Agency, regulatory teams follow centralized or mutual recognition procedures to introduce certified medicinal products uniformly across Spain and the wider single market. As per the Spanish Chemical Industry Federation, industrial manufacturing complexes funnel capital investments into sustainable fillers, enhanced lifecycle safety, and eco-compatible polymers. The presence of multinational pharmaceutical companies with research facilities in Spain contributes to market demand. Government support for scientific research and innovation fosters the development of local expertise in alternative testing. The growing cosmetics industry also drives demand for dermal toxicity tests. Economic recovery and increased healthcare spending further support market growth. This positive trajectory ensures that Spain remains a key contributor to the European market with increasing capacity and capability in in vitro toxicology.
COMPETITIVE LANDSCAPE
The competition in the Europe In-Vitro Toxicology Testing Market is characterized by intense rivalry among global contract research organizations and specialized technology providers who strive to differentiate through scientific innovation and service quality. Major competitors focus on developing integrated platforms that combine experimental data with computational modeling to offer comprehensive safety assessment solutions. Price competition is moderate as clients prioritize regulatory acceptance and data reliability over cost savings due to the critical nature of safety evaluations. Intellectual property protection plays a crucial role as firms patent unique cell lines and assay protocols to secure exclusive rights and prevent imitation. Collaborative efforts between manufacturers and regulatory bodies are increasingly common to establish standardized guidelines for new approach methodologies. The market sees frequent product launches driven by advancements in stem cell technology and microfluidics. Companies must continuously innovate to stay relevant as scientific understanding of toxicity mechanisms evolves. Customer service and technical support including training and consultation have become key differentiators that influence purchasing decisions. The competitive landscape is further shaped by consolidation activities where larger entities acquire niche innovators to broaden their capabilities. This dynamic environment requires constant adaptation and strategic foresight to maintain leadership positions and capture growing demand for ethical and efficient testing solutions globally.
KEY MARKET PLAYERS
Companies dominating European In-Vitro Toxicology Market include
- Covance, Inc. (A subsidiary of LabCorp) (U.S.)
- Agilent Technologies, Inc. (U.S.)
- Bio-Rad Laboratories, Inc. (U.S.)
- Eurofins Scientific SE (Luxembourg)
- General Electric Company (U.S.)
- BioReliance, Inc. (U.S.)
- Charles River Laboratories International, Inc. (U.S.)
- Thermo Fisher Scientific, Inc. (U.S.)
- Catalent (U.S.)
- Cyprotex (U.K.)
Top Players in the Europe In-Vitro Toxicology Testing Market
Charles River Laboratories International Inc
Charles River Laboratories International Inc plays a pivotal role in the Europe In-Vitro Toxicology Testing Market by offering comprehensive preclinical safety assessment services that integrate advanced in vitro models. The company leverages its extensive European network to provide standardized testing solutions for pharmaceutical and chemical clients seeking regulatory compliance. Recent actions include the expansion of its early discovery capabilities through the acquisition of specialized cell biology firms to enhance organ on chip offerings. Charles River actively invests in developing human relevant three dimensional culture systems that improve predictive accuracy for drug induced liver injury. Their strategic focus on digital data integration allows clients to access real time results and analytics streamlining decision making processes. By prioritizing innovation in alternative methods Charles River strengthens its position as a trusted partner for companies aiming to reduce animal testing while maintaining rigorous safety standards in drug development pipelines across Europe.
Eurofins Scientific SE
Eurofins Scientific SE contributes significantly to the market through its extensive portfolio of bioanalytical and toxicology testing services supported by a vast laboratory network across Europe. The company specializes in high throughput screening and customized in vitro assays that cater to diverse industry needs including cosmetics and agrochemicals. Recent initiatives involve the launch of novel genotoxicity testing platforms that utilize automated imaging technologies to enhance sensitivity and throughput. Eurofins actively collaborates with regulatory bodies to validate new approach methodologies ensuring their services meet evolving international standards. They have expanded their capacity for complex in vitro models such as reconstructed human epidermis for skin safety assessments. By focusing on operational excellence and technological advancement Eurofins maintains a competitive edge and drives adoption of efficient non animal testing solutions that help clients accelerate product launches and ensure consumer safety across multiple sectors in the region.
Merck KGaA
Merck KGaA is a leading provider of life science tools and services that supports the Europe In-Vitro Toxicology Testing Market with high quality reagents cell lines and assay kits. The company enables researchers to conduct precise and reliable toxicity studies using its advanced portfolio of products designed for in vitro applications. Recent actions include the introduction of innovative three dimensional cell culture matrices and stem cell derived hepatocytes that mimic human physiology more accurately. Merck actively partners with academic institutions and contract research organizations to promote best practices in in vitro toxicology. They invest heavily in research and development to create user friendly kits that simplify complex testing protocols. By providing essential building blocks for in vitro research Merck strengthens its market position and empowers scientists to develop safer chemicals and pharmaceuticals through robust and reproducible testing methodologies throughout Europe.
Top Strategies Used by Key Market Participants
Key players in the Europe In-Vitro Toxicology Testing Market primarily employ strategic mergers and acquisitions to expand their service portfolios and gain access to proprietary technologies. Companies actively invest in research and development to create novel three dimensional cell culture models and organ on chip systems that offer higher physiological relevance. Strategic partnerships with academic institutions and regulatory agencies facilitate the validation of new approach methodologies ensuring broader acceptance and compliance. Manufacturers focus on geographic expansion by establishing laboratories in key European hubs to capture growing demand from local pharmaceutical and chemical industries. Digital transformation strategies involve integrating artificial intelligence and machine learning algorithms to analyze complex toxicological data and improve predictive accuracy. Continuous investment in automation and high throughput screening technologies enhances operational efficiency and reduces turnaround times for clients. These multifaceted strategies enable companies to maintain competitive advantages and drive sustainable growth in a rapidly evolving regulatory and scientific landscape.
MARKET SEGMENTATION
This research report on the European In-Vitro Toxicology Testing Market has been segmented and sub-segmented into the following categories.
By Product
- Services
- Reagents & Labware
- Assays
By Type
- ADME
- Toxic Substance
- Dose
By Toxicity Endpoints & Tests
- Dermal Toxicity
- Genotoxicity
- Carcinogenicity
By Technology
- OMICS Technologies
- Cell Culture Technology
By Method
- Cellular Assays
- In-Silico Method
By Industry
- Cosmetics & Household Products
- Pharmaceutical
By Country
- UK
- France
- Spain
- Germany
- Italy
- Russia
- Sweden
- Denmark
- Switzerland
- Netherlands
- Turkey
- Czech Republic
- Rest of Europe