- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$2.14 BnMarket Estimate, 2026
$2.28 BnMarket Forecast, 2034
$3.76 BnCAGR, 2026–2034
6.47%Executive Summary: Europe Lung Cancer Therapeutics Market
- Market Scope: Comprehensive regional analysis of the European lung cancer therapeutics market covering treatment types, country-level breakdowns, precision medicine adoption, and oncology R&D trends.
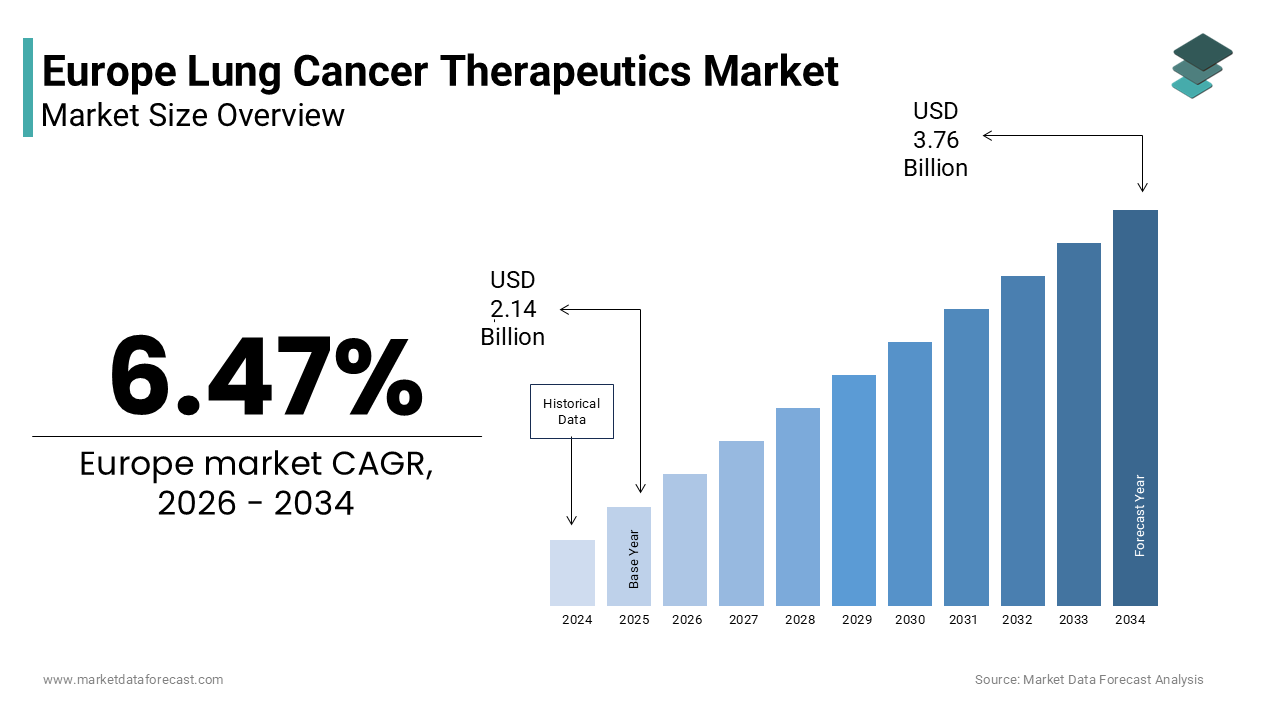
- Market Valuation: Valued at USD 2.14 billion in 2025, estimated at USD 2.28 billion in 2026, and projected to reach USD 3.76 billion by 2034, registering a steady CAGR of 6.47% from 2026 to 2034.
- Primary Growth Drivers: Increasing prevalence of lung cancer driven by tobacco smoking and aging populations; rising demand for targeted therapies and precision medicine; and substantial government funding for novel oncology drug development.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment / Position | Segment Details / Breakdown |
|---|---|---|
| By Treatment Type | Chemotherapy, Radiotherapy & Target/Other Drugs (Abraxane, Avastin, Crizotinib, Gefitinib, etc.) | Targeted therapies and precision medicine lead growth dynamics due to rising clinical preference, while standard chemotherapy and external/internal beam radiotherapy maintain baseline therapeutic shares. |
| By Country / Region | United Kingdom (Leading Market) & Germany (High-Growth Market) | The UK dominates via a high patient population base, while Germany displays strong expansion backed by advanced healthcare infrastructure and high R&D investments. Additional coverage includes France, Spain, Italy, Russia, Sweden, Denmark, Switzerland, Netherlands, Turkey, and Czech Republic. |
Major Market Players & Market Structure
Market Structure: Highly competitive pharmaceutical landscape driven by multinational oncology leaders focusing on targeted drug discovery, clinical trials, and regulatory approvals.
Key Companies: Boehringer Ingelheim GmbH, Hoffmann-La Roche, Pfizer Inc., GlaxoSmithKline, Eli Lilly and Company, Agennix AG, AstraZeneca plc, and Sanofi-Aventis.
Europe Lung Cancer Therapeutics Market Size
The Europe lung cancer therapeutics market size was valued at USD 2.14 billion in 2025 and is anticipated to reach USD 2.28 billion in 2026 from USD 3.76 billion by 2034, growing at a CAGR of 6.47% during the forecast period from 2026 to 2034.
Lung cancer therapeutics refers to the entire spectrum of medical treatments, drugs, and interventions used to treat, manage, and eliminate lung cancer. This specialised sector integrates targeted therapies, immunotherapies, and conventional chemotherapy regimens to address one of the leading causes of cancer-related mortality in the region. As per the European Commission, an estimated 319,000 new cases of lung cancer are diagnosed annually in the European Union, driving a continuous demand for advanced therapeutic treatments. According to the World Health Organisation, lung cancer remains a premier medical priority because it accounts for nearly 20% of all cancer deaths across Europe. Demographic shifts toward an ageing population further exacerbate disease incidence as age remains a primary risk factor for malignancy development. Healthcare systems in countries such as Germany, France, and the United Kingdom are increasingly prioritising early detection programs and personalised medicine approaches to improve patient survival rates. The integration of molecular diagnostics into clinical practice enables oncologists to select therapies based on specific genetic mutations, thereby enhancing treatment efficacy. Regulatory frameworks established by the European Medicines Agency facilitate the rapid approval of novel agents while ensuring safety standards. Consequently, the market is characterized by robust research and development activities aimed at overcoming drug resistance and improving quality of life for patients undergoing long term treatment protocols.
MARKET DRIVERS
Rising Prevalence of Smoking and Environmental Pollutants Drives Disease Incidence
The persistently high prevalence of smoking combined with increasing exposure to environmental pollutants is propelling the European lung cancer therapeutics market. According to the European Respiratory Society, tobacco smoking is linked to about 85% of lung cancer cases in Western countries, illustrating its role as the dominant risk driver. This substantial user base creates a continuous pipeline of patients requiring medical intervention ranging from early stage surgical resection to advanced systemic therapies. Furthermore, as per the European Environment Agency, exposure to fine particulate matter causes over 300,000 premature deaths annually across the European Union, demonstrating the extensive public health impact of ambient air pollution. The correlation between particulate matter exposure and lung tissue damage accelerates tumour formation in both smokers and nonsmokers, thereby expanding the total addressable patient population. Governments are implementing stricter anti-smoking legislation and air quality controls, yet the lag effect means that disease incidence will remain elevated for decades. This sustained burden ensures a steady demand for innovative therapeutics that can address complex cases arising from long-term exposure to carcinogens. Pharmaceutical companies respond by developing drugs that target mutations commonly associated with smoking-induced cancers such as KRAS and EGFR alterations. The demographic reality of an ageing smoker population further intensifies the need for effective treatments that can manage comorbidities alongside cancer progression.
Advancements in Precision Medicine and Biomarker Testing Enhance Treatment Efficacy
The rapid advancement of precision medicine and the widespread adoption of biomarker testing significantly drive the Europe Lung Cancer Therapeutics Market. This enables tailored therapeutic interventions. According to the European Society for Medical Oncology, clinical guidelines explicitly dictate routine molecular testing for advanced non-small cell lung cancer to identify targetable biomarkers, which drives personalized precision oncology interventions. The diagnostic precision allows clinicians to prescribe targeted tyrosine kinase inhibitors that demonstrate superior response rates compared to traditional chemotherapy, thereby improving overall survival outcomes. Additionally, as per the German Cancer Society, genomic eligibility criteria determine when germline testing is performed via next-generation sequencing, ensuring that high-risk individuals receive standardised, quality-controlled hereditary cancer evaluations. The ability to match specific drugs to individual genetic profiles reduces trial-and-error prescribing and minimises unnecessary side effects. This shift toward personalized care encourages healthcare providers to adopt newer therapeutic agents that offer better tolerability and efficacy. Reimbursement policies in countries like France and Italy are increasingly covering biomarker tests, which removes financial barriers for patients. The continuous discovery of new biomarkers expands the range of treatable patient subsets, creating niche markets for specialised drugs. Consequently, the synergy between diagnostic capabilities and therapeutic availability fuels market growth as more patients become eligible for targeted treatments.
MARKET RESTRAINTS
High Cost of Novel Immunotherapies and Targeted Agents Restricts Accessibility
The exorbitant cost of novel immunotherapies and targeted agents is a major barrier to the European lung cancer therapeutics market. This limits broad patient access to advanced lung cancer treatments in the region. According to the European Federation of Pharmaceutical Industries and Associations, oncology drug spending remains tightly regulated across member states to ensure that high-cost innovative treatments do not compromise the long-term sustainability of public healthcare budgets. The high price point forces payers to implement strict eligibility criteria and prior authorisation processes, which delay treatment initiation for many patients. Furthermore, as per the Organisation for Economic Co-operation and Development, health spending on cancer is projected to rise by up to 84% across member nations by 2050 due to population ageing and improving patient survival rates. The financial toxicity associated with these treatments leads to nonadherence and discontinuation, particularly among elderly patients with fixed incomes. Healthcare systems struggle to balance the introduction of innovative but expensive drugs with the need to maintain equitable access for all citizens. Budget impact assessments often result in restricted formulary listings limiting the availability of the latest therapeutic options in certain regions. Pharmaceutical manufacturers face pressure to justify pricing through value-based agreements, which can be complex and time-consuming to negotiate. These economic barriers prevent the full realisation of clinical benefits for the entire patient population, thereby restraining market expansion despite the proven efficacy of these advanced therapies.
Stringent Regulatory Approval Processes Delay Market Entry
The stringent regulatory approval processes enforced by the region’s health authorities significantly delay the launch of new lung cancer therapeutics, which slows down the expansion of the Europe lung cancer therapeutics market. According to the European Medicines Agency, the standard evaluation timeline for a centralized marketing authorization application requires a formal 210-day active review period by the Committee for Medicinal Products for Human Use. The prolonged timeline postpones patient access to potentially life saving treatments and reduces the effective patent protection period for innovators. Furthermore, as per the Association of the British Pharmaceutical Industry, local health technology assessment delays often stall patient access to newly authorised cancer treatments while individual nations negotiate pricing and clinical value parameters. The complexity of navigating diverse national health technology assessment bodies creates fragmented market access strategies that increase operational costs for developers. Companies must tailor their clinical trial designs to meet varying evidentiary standards across different countries, which slows down the launch process. The uncertainty surrounding pricing and reimbursement negotiations further discourages rapid commercialisation efforts. Delays in market entry mean that patients continue to rely on older, less effective therapies for extended periods. This regulatory burden also impacts the return on investment for research and development activities, potentially reducing the incentive for companies to pursue innovative lung cancer treatments. The cumulative effect of these procedural hurdles restricts the speed at which new therapeutic options become available to the European patient population.
MARKET OPPORTUNITIES
Expansion of Combination Therapy Approaches Creates New Avenues
The expanding use of combination therapy approaches opens new pathways for growth in the European Lung Cancer Therapeutics Market. This enhances clinical outcomes and extends treatment lines. According to the International Association for the Study of Lung Cancer, first-line combination regimens pairing immunotherapy with chemotherapy consistently demonstrate superior overall survival benefits across advanced lung cancer demographics compared to standard chemotherapy alone. This enhanced efficacy encourages oncologists to adopt multi drug regimens as standard of care for first line and subsequent treatment settings. Additionally, as per the French National Cancer Institute, collaborative international networks validate pathology standards to ensure uniform classifications for complex thoracic malignancies across European treatment facilities. The ability to target multiple pathways simultaneously reduces the likelihood of drug resistance and prolongs disease control. Pharmaceutical companies are investing heavily in developing compatible drug pairs and conducting large-scale phase III trials to validate these combinations. The success of these regimens creates demand for higher volumes of therapeutics as patients remain on treatment for longer durations. Reimbursement bodies are increasingly recognising the value of combination therapies in improving long-term survival, which supports broader coverage. This trend also fosters collaborations between companies to co-develop complementary agents. The strategic shift toward combination treatments thus drives market expansion by increasing the complexity and volume of therapeutic interventions required for optimal patient management.
Growing Focus on Early Detection and Screening Programs Increases Patient Pool
The growing focus on early detection and screening programs across the region creates a substantial opportunity for the Europe lung cancer therapeutics market. This identifies patients at earlier, more treatable stages. According to the European Commission, targeted funding initiatives support low-dose computed tomography screening implementation to standardise early detection protocols and reduce health inequalities across member states. Early-stage detection allows for curative interventions, including surgery and adjuvant targeted therapies, which were previously reserved for advanced disease. Furthermore, as per the British Thoracic Society, accredited clinical guidelines structure the active follow-up, risk stratification, and radiological management of pulmonary nodules detected during thoracic imaging. The identification of earlier-stage diseases increases the demand for adjuvant and neoadjuvant therapies, which are gaining regulatory approval based on recent clinical trial successes. These treatments aim to eliminate micrometastases and prevent recurrence, extending the therapeutic journey for patients who might otherwise have been untreated until late-stage progression. Healthcare systems are integrating screening results with multidisciplinary tumour boards to ensure rapid referral and treatment initiation. This proactive approach shifts the paradigm from palliative care to curative intent, driving demand for a broader range of therapeutic options. The expansion of screening infrastructure thus directly correlates with increased utilisation of lung cancer therapeutics across various disease stages.
MARKET CHALLENGES
Complexity of Managing Immune-Related Adverse Events Poses Clinical Challenges
The complexity of managing immune-related adverse events associated with modern immunotherapies is a severe obstacle to the European lung cancer therapeutics market. According to the European Society for Medical Oncology, the clinical presentation and severity of immune-related toxicities require structured diagnostic grading to determine when to interrupt checkpoint inhibitor therapies or initiate corticosteroid administration. The severe side effects necessitate hospitalisation and the use of high-dose corticosteroids, which can compromise the anticancer efficacy of the treatment. Furthermore, as per the German Society for Haematology and Medical Oncology, cross-disciplinary position statements establish critical baseline parameters and cardiovascular monitoring strategies for patients undergoing modern targeted cancer therapies. Oncologists often hesitate to prescribe immunotherapies to elderly patients or those with pre-existing autoimmune conditions due to the risk of exacerbating underlying diseases. This caution limits the potential patient population for these highly effective drugs. The need for multidisciplinary care involving pulmonologists, endocrinologists and gastroenterologists adds logistical burdens to healthcare systems already facing staffing shortages. Patients may discontinue treatment prematurely due to intolerable side effects, leading to disease progression. Addressing these safety concerns requires extensive training and resource allocation, which many institutions struggle to provide. Consequently, the management of adverse events remains a critical barrier to optimising the full therapeutic potential of immunotherapies in clinical practice.
Limited Access to Molecular Diagnostics in Rural Areas Hinders Personalised Care
The limited access to molecular diagnostics in rural and underserved areas of the region hinders the effective implementation of personalized lung cancer care, which is a major challenge to the Europe lung cancer therapeutics market. According to the European Reference Network for Rare Lung Diseases, cross-border clinical networks optimize rare patient care by connecting expert centers to securely share highly specialized medical knowledge across the European Union. The diagnostic gap prevents oncologists in these areas from prescribing targeted therapies that require specific genetic confirmation, thereby forcing reliance on less effective empirical treatments. As per the Spanish Society of Medical Oncology, multi-society clinical practice guidelines standardize diagnostic frameworks to ensure unified management criteria for targeted solid tumor treatments nationwide. The delays can lead to disease progression during the waiting period, reducing the window of opportunity for effective intervention. The disparity in diagnostic infrastructure creates inequities in treatment outcomes across the continent. Healthcare providers in resource-limited settings often lack the expertise to interpret complex genomic reports, further complicating decision-making. Reimbursement policies for molecular testing vary significantly between regions, creating financial barriers for local laboratories. This fragmentation undermines the goal of uniform high quality care for all lung cancer patients. Bridging this diagnostic divide requires substantial investment in laboratory infrastructure and telemedicine solutions to connect remote clinics with central expertise. These gaps must be addressed. Until then, a significant portion of the patient population will remain unable to benefit from advances in precision medicine.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 6.47% |
| Segments Covered | By Treatment Type and Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis; Segment-Level Analysis; DROC, PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | United Kingdom, France, Spain, Germany, Italy, Russia, Sweden, Denmark, Switzerland, the Netherlands, Turkey, and the Czech Republic |
| Market Leaders Profiled | Boehringer Ingelheim GmbH, Hoffman-La Roche, Pfizer Inc., GlaxoSmithKline, Eli Lilly and Company, Agennix AG, AstraZeneca plc, and Sanofi-Aventis. |
SEGMENTAL ANALYSIS
By Treatment Type Insights
The Other Drugs segment dominated the European lung cancer therapeutics market and accounted for a substantial share in 2025. This segment has surpassed traditional chemotherapy due to its ability to offer personalized treatment options with improved survival outcomes and reduced toxicity profiles. Moreover, this segment includes targeted therapies and immunotherapies such as Abraxane, Avastin, Crizotinib, Docetaxel, and Gefitinib. The dominance of the Other Drugs segment is mainly driven by the superior clinical efficacy and significant survival benefits demonstrated in recent large scale clinical trials across Europe. According to the European Society for Medical Oncology, the development of specialized genetic testing panels guides the clinical deployment of appropriate molecularly targeted inhibitors for eligible advanced lung adenocarcinoma cohorts. The substantial improvement in disease control encourages oncologists to prioritize these agents as first line treatments for patients with actionable mutations. Furthermore as per the National Institute for Health and Care Excellence, clinical value thresholds mandate rigorous cost-effectiveness analyses for newly authorized immuno-oncology treatments prior to their formal integration into public health service pathways. The compelling clinical data points validate the therapeutic value of newer agents leading to their widespread integration into national treatment guidelines. Healthcare providers are increasingly shifting away from cytotoxic drugs that offer limited long term benefits in favor of molecules that target specific genetic drivers of tumor growth. The ability of these drugs to induce durable responses and improve quality of life makes them the preferred choice for both clinicians and patients. Consequently the proven track record of enhanced survival and disease management solidifies the leading market position of this segment as the standard of care continues to evolve toward precision oncology.
The continuous expansion of regulatory approvals and broadening indications for targeted therapies and immunotherapies significantly contributes to the market leadership of the Other Drugs segment. According to the European Medicines Agency, the centralized approval of authorized biosimilars expands patient access to anti-angiogenic oncology regimens while lowering financial barriers within national health infrastructure. The regulatory momentum ensures that a larger proportion of the diagnosed population can benefit from advanced therapeutic options thereby increasing prescription volumes. Additionally, as per the German Federal Joint Committee, early benefit assessments demand robust evidence of added therapeutic value before new medical interventions receive favorable statutory health insurance reimbursement status. The inclusion of these drugs in national formularies removes financial barriers for hospitals and patients facilitating higher adoption rates. Pharmaceutical companies actively pursue label expansions through post marketing studies which further legitimizes the use of these agents in diverse clinical scenarios. The availability of multiple lines of therapy within this segment allows for sequential treatment strategies that prolong patient survival. As diagnostic capabilities improve and more patients are identified as candidates for targeted interventions the demand for these specialized drugs continues to outpace traditional modalities. This dynamic regulatory and reimbursement landscape supports the sustained dominance of the Other Drugs segment in the European market.
The radiotherapy segment is anticipated to witness the fastest CAGR of 9.8% between 2026 and 2034 owing to technological advancements and its critical role in multimodal treatment strategies. In addition, the rapid growth of this segment is fueled by significant technological advancements that enhance precision and minimize damage to surrounding healthy tissues. According to the European Society for Radiotherapy and Oncology, international survey data reveal extensive clinical adoption of stereotactic body radiation therapy for diverse thoracic malignancies alongside significant procedural variability across global delivery centers. The technological evolution allows for the effective treatment of tumors located in complex anatomical regions where surgery is not feasible thereby expanding the treatable patient population. Furthermore as per the French National Cancer Institute, clinical guidelines actively promote targeted physical activity interventions to mitigate cancer-related fatigue and sustain functional performance during active therapeutic regimens. The ability to spare critical organs such as the heart and lungs reduces long term complications making radiotherapy a more attractive option for elderly patients and those with comorbidities. Healthcare systems are investing heavily in upgrading infrastructure to support these advanced modalities recognizing their value in improving overall care quality. The integration of image guided radiotherapy ensures real time adjustment of radiation beams accounting for patient movement and tumor shrinkage. These innovations transform radiotherapy from a palliative measure into a curative intent treatment for early stage lung cancer. Consequently the enhanced safety profile and therapeutic precision drive the accelerated adoption of radiotherapy services across the region.
The integration of radiotherapy into multimodal treatment protocols alongside systemic therapies drives its rapid growth in the Europe Lung Cancer Therapeutics Market. According to the International Association for the Study of Lung Cancer, concurrent chemoradiotherapy represents a critical therapeutic option for fit elderly individuals aged 70 years or older presenting with advanced thoracic disease. The synergistic effect enhances tumor control and improves overall survival rates compared to either modality used alone. Additionally as per the British Thoracic Society, standardized multi-professional care path management structures clinical surveillance and symptom palliation protocols to enhance the quality of life for advanced cancer patient cohorts. The role of radiotherapy in managing oligometastatic disease is also expanding with studies showing that ablative radiation to limited metastatic sites can prolong survival. Clinicians are increasingly relying on radiation oncologists to coordinate care plans that maximize the benefits of systemic drugs while controlling local disease progression. The establishment of multidisciplinary tumor boards ensures that radiotherapy is considered at every stage of decision making. Reimbursement policies supporting combined modality treatments further encourage the utilization of radiation services. As the understanding of radiation induced immune modulation grows its combination with immunotherapies creates new opportunities for enhancing anti tumor responses. This strategic integration ensures that radiotherapy remains an indispensable component of comprehensive lung cancer care driving its robust growth trajectory.
COUNTRY ANALYSIS
United Kingdom Lung Cancer Therapeutics Market Analysis
The United Kingdom holds a prominent position in the Europe lung cancer therapeutics market because of its centralized healthcare system and a strong emphasis on evidence-based medicine. According to Cancer Research UK, lung cancer remains the leading cause of cancer death in the United Kingdom, accounting for approximately 32,800 deaths annually. The National Health Service prioritizes access to innovative treatments through the Cancer Drugs Fund which has facilitated the uptake of newer targeted therapies and immunotherapies. Furthermore as per the National Institute for Health and Care Excellence, health technology appraisals mandate strict cost-effectiveness criteria before clinical guidance incorporates advanced checkpoint inhibitor regimens into the National Health Service framework. The UK is also a hub for clinical trials attracting global pharmaceutical companies to test novel agents in its diverse patient population. The implementation of the Optimal Personalised Care After Treatment program supports survivors in managing long term effects enhancing the overall value of therapeutic interventions. Government initiatives to reduce smoking rates continue to impact future incidence but the current burden sustains high treatment demand. The presence of world class research institutions fosters innovation and collaboration with industry partners. These factors combine to maintain the UK as a key market for lung cancer therapeutics in Europe.
France Lung Cancer Therapeutics Market Analysis
France occupies a significant share in the Europe Lung Cancer Therapeutics Market. The country’s position is supported by a robust healthcare infrastructure and proactive national cancer strategies. According to the French National Cancer Institute, lung cancer represents a premier epidemiological challenge, accounting for approximately 50,000 new diagnoses across France each year. The country has implemented early detection pilots that are increasing the diagnosis of early stage diseases suitable for curative therapies including surgery and adjuvant treatments. Furthermore as per the French Ministry of Solidarity and Health, formal early access authorization protocols regulate when innovative oncology medications are distributed prior to finalized national pricing negotiations. France is a leader in adopting precision medicine approaches with widespread availability of molecular testing in university hospitals. The strong presence of pharmaceutical manufacturing and research facilities encourages local development of therapeutic agents. Patient associations play a vital role in advocating for access to new treatments influencing policy decisions. The integration of telemedicine in oncology care improves follow up and management of side effects. These structural strengths enable France to maintain a dynamic and growing market for lung cancer therapeutics.
Germany Lung Cancer Therapeutics Market Analysis
Germany led the Europe lung cancer therapeutics market and captured a significant share in 2025. This leading position of the German market was attributed to its advanced medical technology and high healthcare expenditure. According to the German Cancer Society, quality-assured certified lung cancer centers supply primary treatment infrastructure for over 40% of newly diagnosed respiratory malignancy patients annually across Germany. The country boasts one of the highest densities of certified cancer centers in Europe ensuring that patients receive multidisciplinary care according to strict quality standards. Furthermore as per the Federal Joint Committee, early benefit assessments evaluate whether a newly introduced pharmaceutical delivers an additional therapeutic benefit over established standard comparative treatments. Germany is at the forefront of implementing personalized medicine with extensive use of next generation sequencing in routine clinical practice. The strong industrial base supports the local production and distribution of pharmaceutical products. High patient awareness and physician engagement drive the adoption of latest treatment guidelines. The aging population contributes to rising incidence rates sustaining market growth. Collaborative research projects between universities and industry accelerate the translation of scientific discoveries into clinical applications. These factors solidify Germany's leading position in the regional market.
Italy Lung Cancer Therapeutics Market Analysis
Italy also maintains a substantial position in the Europe lung cancer therapeutics market due to its strong focus on clinical research, despite regional variations in healthcare delivery. According to the Italian Association of Medical Oncology, evidence-based management guidelines standardize therapeutic workflows across regional multidisciplinary tumor boards to reduce clinical variability in metastatic non-small cell lung cancer care. The country has seen increased adoption of immunotherapies following positive reimbursement decisions by the National Health Service. Furthermore as per the Italian Ministry of Health, national regulatory provisions restructure therapeutic continuity parameters to align territorial health assets with specialized clinical infrastructure during ongoing institutional health reforms. Italy participates actively in European clinical trials providing access to experimental therapies for many patients. The presence of renowned cancer research institutes fosters innovation and expertise in thoracic oncology. Public awareness campaigns regarding smoking cessation are gradually impacting incidence trends but the existing patient pool remains large. Economic constraints sometimes delay the introduction of new drugs compared to northern European countries yet the overall market remains robust. The integration of palliative care with active treatment enhances quality of life for advanced stage patients. These dynamics contribute to the steady performance of the therapeutics market in Italy.
Spain Lung Cancer Therapeutics Market Analysis
Spain is a growing player in the Europe Lung Cancer Therapeutics market, driven by improved healthcare accessibility and an increasing focus on precision oncology. According to the Spanish Society of Medical Oncology, the accelerating incidence of lung cancer among women establishes it as the third most frequent malignancy in this demographic, trailing only breast and colorectal cancers. The country has implemented national strategies to reduce waiting times for diagnostic tests and treatment initiation improving overall care efficiency. Furthermore, as per the Ministry of Health of Spain, newly updated joint national strategy protocols govern how advanced molecular testing is incorporated uniformly within public healthcare diagnostic portfolios. Spain is becoming a preferred location for international clinical trials due to its experienced investigators and regulatory efficiency. The adoption of digital health tools facilitates remote monitoring and management of treatment related adverse events. Patient advocacy groups are influential in shaping access policies and promoting equitable care. The economic recovery has allowed for increased healthcare spending supporting the acquisition of advanced technologies. Collaboration with pharmaceutical companies ensures that new treatments reach the market promptly. These developments position Spain as a key contributor to the regional market growth.
COMPETITIVE LANDSCAPE
The competitive landscape of the Europe Lung Cancer Therapeutics Market is characterized by intense rivalry among global pharmaceutical giants and emerging biotechnology firms striving for leadership in precision oncology. Major companies compete vigorously on the basis of clinical efficacy safety profiles and innovative mechanisms of action to differentiate their products. The market witnesses frequent launches of new targeted therapies and immunotherapies driven by rapid advancements in molecular biology and genetics. Patent expirations for older drugs have led to an influx of biosimilars and generics increasing price competition and forcing innovators to continuously upgrade their portfolios. Strategic alliances and mergers are common as companies seek to broaden their therapeutic offerings and enter new market segments. Regulatory harmonization across Europe facilitates faster market entry but also intensifies competition as more players gain access to the region. Companies are increasingly focusing on value based pricing models and patient support services to retain loyalty. The presence of strong national healthcare systems means that payers exert significant influence on market dynamics demanding proof of superior clinical and economic value. This environment drives constant innovation and strategic agility among market participants.
KEY MARKET PLAYERS
A few of the notable companies operating in the Europe Lung Cancer Therapeutics Market include
- Boehringer Ingelheim GmbH
- Hoffman-La Roche
- Pfizer Inc.
- GlaxoSmithKline
- Eli Lilly and Company
- Agennix AG
- AstraZeneca plc
- Sanofi-Aventis.
Key Market Players Analysis
Roche Holding AG
Roche Holding AG maintains a leading position in the Europe Lung Cancer Therapeutics Market through its extensive portfolio of targeted therapies and immunotherapies. The company actively collaborates with European research institutions to develop personalized medicine solutions tailored to specific genetic mutations found in lung cancer patients. Recently Roche expanded its manufacturing capabilities in Switzerland to ensure a stable supply of critical oncology drugs across the continent. This strategic investment enhances supply chain resilience and reduces delivery times for hospitals. The company also launched digital health platforms that assist clinicians in interpreting complex genomic data facilitating more accurate treatment decisions. By integrating diagnostics with therapeutics Roche provides comprehensive solutions that improve patient outcomes. These initiatives demonstrate the companys commitment to innovation and its pivotal role in advancing precision oncology throughout Europe.
Pfizer Inc
Pfizer Inc plays a significant role in the Europe Lung Cancer Therapeutics Market by offering a diverse range of targeted kinase inhibitors and immunotherapies. The company has strengthened its market presence by securing approvals for new indications of its existing drugs in multiple European countries. Recently Pfizer initiated several large scale clinical trials in Germany and France to evaluate combination therapies for advanced non small cell lung cancer. These studies aim to establish new standards of care and expand treatment options for patients with resistant tumors. The company also partnered with local healthcare providers to offer patient support programs that improve adherence and manage side effects effectively. Pfizer continues to invest in research and development to discover novel biomarkers and therapeutic targets. These efforts reinforce its reputation as a key innovator driving progress in lung cancer treatment across the region.
Bristol Myers Squibb
Bristol Myers Squibb contributes significantly to the Europe Lung Cancer Therapeutics Market through its pioneering work in immuno oncology and checkpoint inhibitors. The company has established strong collaborations with academic centers to explore the efficacy of its therapies in various clinical settings. Recently Bristol Myers Squibb received positive reimbursement decisions in several major European markets enabling broader patient access to its flagship immunotherapy agents. The company also implemented educational initiatives for oncologists to enhance understanding of immune related adverse event management. By focusing on real world evidence generation Bristol Myers Squibb demonstrates the long term benefits of its treatments to healthcare payers. The company continues to expand its pipeline with next generation immunotherapies designed to overcome resistance mechanisms. These strategic actions solidify its position as a trusted partner in the fight against lung cancer in Europe.
Top Strategies Used by Key Market Participants
Key players in the Europe Lung Cancer Therapeutics Market primarily employ strategic collaborations and continuous innovation to maintain their competitive edge. Companies frequently partner with academic institutions and research organizations to accelerate the development of novel therapies and validate clinical outcomes. This approach facilitates access to cutting edge scientific knowledge and diverse patient populations for clinical trials. Another major strategy involves securing favorable reimbursement agreements through robust health economic data demonstrating the cost effectiveness of new treatments. Manufacturers also focus on expanding their diagnostic capabilities to enable precise patient selection for targeted therapies. Additionally firms are investing in digital health solutions to support clinicians in treatment decision making and patient monitoring. These strategies collectively enhance market penetration and ensure sustainable growth in a highly regulated environment.
MARKET SEGMENTATION
This research report on the Europe Lung Cancer Therapeutics Market is segmented and sub-segmented into the following categories:
By Treatment Type
- Chemotherapy
- Cisplatin
- Taxol
- Navelbine
- Camptosar
- Alimta
- Radiotherapy
- External Beam
- Internal Beam
- Systemic
- Other Drugs
- Abraxane
- Avastin
- Crizotinib
- Docetaxel
- Gefitinib
By Country
- UK
- France
- Spain
- Germany
- Italy
- Russia
- Sweden
- Denmark
- Switzerland
- Netherlands
- Turkey
- Czech Republic
- Rest of Europe