- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$2.22 BnMarket Estimate, 2026
$2.29 BnMarket Forecast, 2034
$2.97 BnCAGR, 2026–2034
3.29%Executive Summary: Europe Neurotherapeutics Market
- Market Scope: Regional assessment of the European neurotherapeutics market evaluating treatment categories (neurologic drugs and devices), disorder types, clinical distribution channels, and country-level dynamics.
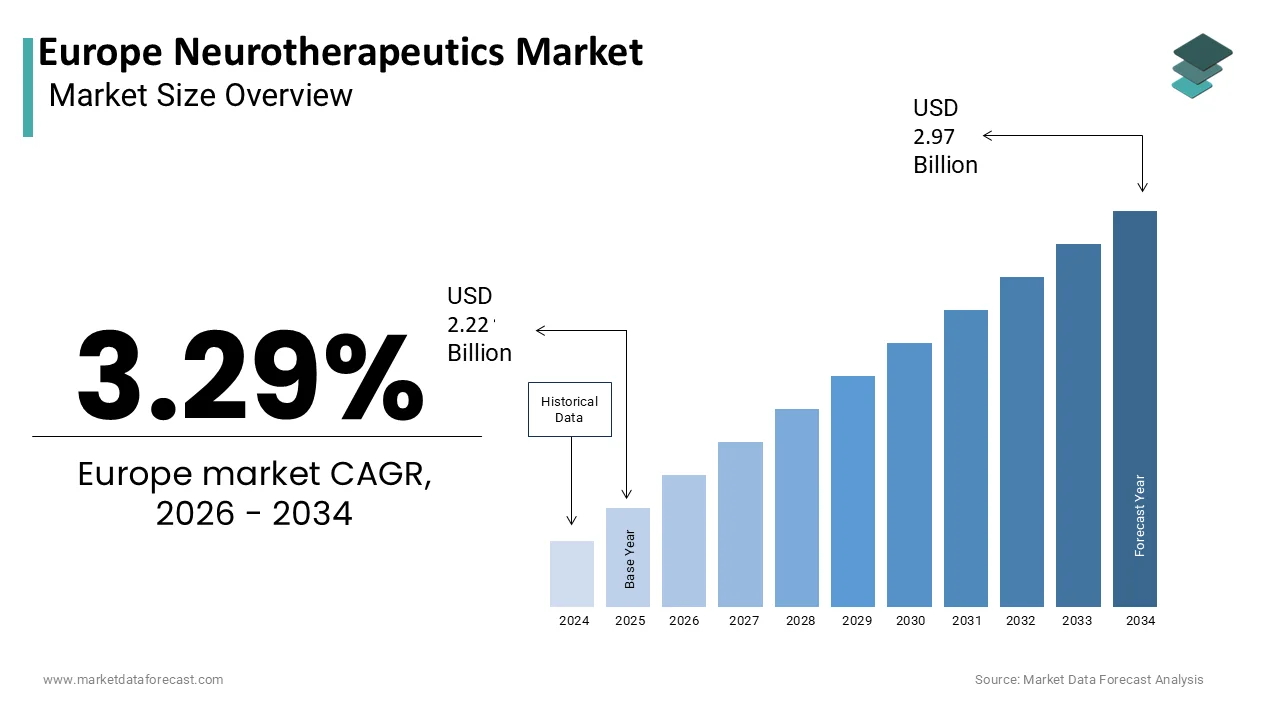
- Market Valuation: Valued at USD 2.22 billion in 2025, expanding to USD 2.29 billion in 2026, and projected to reach USD 2.97 billion by 2034, registering a steady CAGR of 3.29% from 2026 to 2034.
- Primary Growth Drivers: High and rising prevalence of neurological disorders (epilepsy, Parkinson's disease, Alzheimer's, brain tumors, and chronic pain); increasing geriatric demographic vulnerability; and technological advancements in wireless, rechargeable neurostimulation systems.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment / Core Focus | Fastest-Growing / Key Segments |
|---|---|---|
| By Treatment | Neurologic Drugs (oral administration & injections providing foundational pharmaceutical care for chronic CNS/PNS conditions) | Neurologic Devices (Deep Brain Stimulators, VNS, and ECT gaining stronger clinical evidence and adoption over standard drug therapies) |
| By Disorders | Central Nervous System (CNS) Disorders (capturing the largest share due to widespread conditions like epilepsy, Alzheimer's, and Parkinson's) | Peripheral & Autonomous Nervous System Disorders (experiencing steady demand alongside chronic pain management) |
| By Distribution Channel | Hospitals & Specialized Neurotherapeutic Centres (primary hubs for surgical device implantations, diagnostics, and long-term treatment) | Clinics & Clinical Research Organizations (expanding through outpatient care and active clinical trials) |
| By Country | United Kingdom (held the largest market share owing to favorable reimbursement policies and high CNS disease incidences) | Germany (projected to grow at the highest CAGR driven by rising mental health disorders, advanced healthcare infrastructure, and rising R&D) |
Major Market Players & Market Structure
Market Structure: Highly competitive medical device and pharmaceutical ecosystem featuring major global healthcare corporations specializing in neurostimulation hardware and advanced neurological medications.
Key Companies: Abbott Laboratories, Inc., Becton, Dickinson and Company, Novartis AG, Pfizer, Inc., Johnson & Johnson, Biogen, Inc., GlaxoSmithKline, Inc., AstraZeneca plc, Sanofi-Aventis, Spiegelberg, Stryker, Covidien, Medtronic, GE Healthcare, and Merck & Co.
Europe Neurotherapeutics Market Size
The Europe Neurotherapeutics Market is projected to grow from USD 2.22 billion in 2025 to USD 2.29 billion in 2026 and reach USD 2.97 billion by 2034, registering a CAGR of 3.29% during the forecast period from 2026 to 2034.
Neurotherapeutics refers to the broad field of developing and applying medical treatments, interventions, and specialized technologies designed to cure, manage, or repair disorders affecting the human nervous system. Unlike traditional neurology, which often focuses primarily on diagnosing and providing palliative or symptom-suppressing care for conditions like Alzheimer's, Parkinson's, stroke, and psychiatric illnesses, neurotherapeutics targets the underlying cellular, molecular, or electrical mechanisms of the nervous system to restore normal function. This market is critical for addressing the growing burden of neurological conditions, which significantly impact quality of life and healthcare systems across the continent. As per the World Health Organisation Regional Office for Europe, neurological disorders rank as the third leading cause of disability-adjusted life years in the European Union, representing 13.3% of total healthy years lost. According to the European Brain Council, approximately 165 million people in Europe live with a brain disorder, accelerating direct and indirect healthcare costs across the continent. As per Eurostat data, the proportion of individuals aged 65 and older in the European Union is projected to reach 29.4% by 2050, accelerating demand for long-term elderly healthcare infrastructures. Regulatory frameworks under the European Medicines Agency prioritize accelerated assessment pathways for innovative neurotherapies addressing unmet medical needs. This regulatory support fosters rapid development of novel mechanisms such as monoclonal antibodies and gene therapies. The market definition extends beyond traditional small molecules to include advanced biologics, digital therapeutics, and neuromodulation devices, reflecting a holistic approach to neurological care.
MARKET DRIVERS
Rising Prevalence of Neurodegenerative Diseases Due to Ageing Population
The demographic shift toward an ageing society is a key driver of the European neurotherapeutics market. This factor amplifies the incidence of neurodegenerative conditions and consequent demand for effective neurotherapeutics. According to the United Nations Department of Economic and Social Affairs, the number of people aged 65 years or older in Europe is projected to increase by 48% by 2050, expanding the potential demographic vulnerable to age-related cognitive decline. The Global Burden of Disease Study indicates that Alzheimer’s disease and other dementias rank as the third leading cause of death in high-income European countries, following an upward shift from historical baselines. This epidemiological trend necessitates robust therapeutic interventions to manage symptoms and slow disease progression. Healthcare systems are adapting by integrating specialised neurology services and expanding access to disease-modifying therapies. The chronic nature of these conditions requires long-term treatment regimens, ensuring sustained demand for pharmaceutical products. Governments are prioritising national dementia strategies which include funding for research and improved care pathways. This demographic reality compels pharmaceutical companies to invest heavily in developing treatments that address the root causes of neurodegeneration rather than just symptomatic relief. The inevitability of age-related cellular decline ensures a steady baseline of new cases driving continuous market growth.
Increased Investment in Neuroscience Research and Development
Substantial financial commitment from both the public and private sectors toward neuroscience research has accelerated discoveries, which in turn fuels the growth of the European neurotherapeutics market. This leads to the development of novel neurotherapeutic agents. As per the European Commission's Horizon Europe program, over 93.5 billion euros have been allocated for the entire research framework spanning 2021 to 2027, scaling funding opportunities for international scientific collaboration. The European Federation of Pharmaceutical Industries and Associations reveals that neuroscience clinical trial timelines face potential delays of six to twelve months due to evolving regulatory implementation complexities across Europe. Also, the investments facilitate the exploration of complex mechanisms such as neuroinflammation,n protein aggregation, and synaptic dysfunction, leading to breakthrough therapies. Collaborative initiatives between academic institutions and biotechnology firms enhance knowledge sharing and reduce development timelines. Regulatory incentives such as orphan drug designation for rare neurological conditions encourage investment in niche areas with high unmet needs. The success of recent approvals for Alzheimer’s disease modifiers has renewed confidence in the field, attracting further capital. This vibrant ecosystem supports the translation of scientific discoveries into clinical applications. Consequently, the pipeline of potential neurotherapeutics continues to expand, offering hope for patients with previously untreatable conditions.
MARKET RESTRAINTS
High Failure Rates in Clinical Trials for CNS Disorders
The central nervous system is inherently complex, and preclinical models have significant limitations, which restrict the expansion of the Europe neurotherapeutics market. As a result, neurotherapeutic candidates suffer from exceptionally high failure rates during clinical development. According to Nature Reviews Drug Discovery, late-stage Phase 3 clinical trial terminations have doubled over the past decade, driven primarily by corporate strategic shifts and portfolio reprioritisations rather than new scientific or clinical evidence. Studies by the Tufts Centre for the Study of Drug Development indicate that the average cost to bring a generic or newly approved prescription medicine to market is approximately 2.6 billion dollars, reflecting an increasing financial requirement for modern therapeutic pipelines. These financial risks discourage smaller biotechnology firms from entering the space, limiting diversity in the pipeline. Many failures stem from inadequate target validation or poor blood-brain barrier penetration, leading to a lack of efficacy in human subjects despite promising animal data. The subjective nature of neurological endpoints such as cognitive scores introduces variability,lity complicating statistical analysis. Regulatory agencies require robust evidence of clinical meaningfulness, which is difficult to demonstrate in progressive diseases. This high-risk environment leads to conservative investment strategies and consolidation among larger players who can absorb losses. Thus, the pace of innovation is slowed as companies prioritize safer indications over high-risk, high-reward neurological targets.
Stringent Reimbursement and Health Technology Assessment Criteria
Rigorous health technology assessment processes in countries in the region often delay or restrict reimbursement for new neurotherapeutics in the European market. This happens because authorities cite insufficient evidence of cost-effectiveness compared to existing standards. As per the European Observatory on Health Systems and Policies, individual patient co-payments and out-of-pocket expenses vary significantly across member states based on disease severity, age brackets, and household income levels. Research from the Office of Health Economics shows that the introduction of early disease-modifying therapies can reduce long-term annual medical expenditures by preventing relapses and delaying disability progression. This uncertainty creates barriers to patient access, particularly for high-priced disease-modifying therapies. Manufacturers must engage in complex price negotiations and managed entry agreements to secure coverage, reducing potential revenue. Variations in assessment criteria between countries like Germany, France, and the United Kingdom fragment the market, requiring tailored value dossiers for each jurisdiction. The emphasis on budget impact limits adoption of expensive innovations even when clinical benefit is established. Small patient populations for rare neurological disorders further complicate economic evaluations. These reimbursement hurdles force companies to balance pricing strategies with accessibility goals. Hence, market penetration is slower than anticipated, affecting return on investment and future research funding.
MARKET OPPORTUNITIES
Advancements in Biomarker Discovery and Precision Medicine
The identification of specific biological markers for neurological diseases enables stratification of patient populations for targeted therapies, which are expected to propel the expansion of the European neurotherapeutics market. This, in turn, improves clinical trial success rates and treatment efficacy. According to the Alzheimer’s Association international conference proceedings, the introduction of high-precision blood tests tracking p-tau217 allows for the identification of at-risk, asymptomatic individuals up to a decade before clinical symptom onset. The European Society for Medical Oncology emphasizes that liquid biopsy applications focus primarily on tracking circulating tumor DNA and evaluating molecular responses to advance personalized therapeutic selections for cancer patients. These diagnostic advancements facilitate early intervention before irreversible neuronal damage occurs, expanding the window for therapeutic benefit. Pharmaceutical companies are integrating companion diagnostics into development programs, ensuring that drugs are tested in responsive populations. Regulatory agencies support this approach by accepting surrogate endpoints based on biomarker changes, accelerating approval timelines. The shift toward precision medicine reduces waste in healthcare spending by avoiding ineffective treatments. This technological evolution opens new revenue streams for combined diagnostic therapeutic packages. Clinicians gain confidence in prescribing novel agents when supported by objective biological data. Therefore, the integration of biomarkers represents a transformative opportunity to redefine neurological care standards.
Expansion of Digital Therapeutics and Remote Monitoring Solutions
The integration of digital health technologies with traditional pharmacotherapy offers significant opportunities to enhance patient engagement and monitor disease progression in real time, which is anticipated to accelerate the expansion of the European neurotherapeutics market. As per the Digital Health Coalition Europe, digital health initiatives scale patient access to clinical education frameworks and remote specialist networks across diverse cross-border healthcare systems. Studies by the European Innovation Partnership on Active and Healthy Ageing indicate that regional healthcare ecosystems leverage digital infrastructure innovations to scale independent living models for aging demographics. These digital solutions provide continuous data streams that complement intermittent clinical assessments, offering a more comprehensive view of disease trajectory. Pharmaceutical companies are partnering with tech firms to develop integrated platforms that support medication adherence and lifestyle modifications. Payers are increasingly recognising the value of digital interventions in reducing overall care costs. Regulatory frameworks for software as a medical device are maturing, facilitating market entry. This convergence of digital and pharmaceutical domains creates holistic care models. Patients benefit from empowered self-management while clinicians gain actionable insights. This trend expands the definition of neurotherapeutics beyond pills to include comprehensive digital ecosystems.
MARKET CHALLENGES
Blood-Brain Barrier Penetration Limitations
The blood-brain barrier poses a formidable physiological challenge to the European neurotherapeutics market. It prevents many potential neurotherapeutic molecules from reaching their target sites in the central nervous system. According to the Journal of Controlled Release, various advanced tactics, including lipidization, prodrug chemical modifications, and nanoparticle-based formulations, are being actively engineered to assist therapeutic compounds in crossing the blood-brain barrier. Research from the National Institutes of Health indicates that the blood-brain barrier excludes approximately 98% of small-molecule drugs and nearly all large biomolecules, creating a prominent bottleneck in the clinical pipeline for central nervous system therapies. This barrier necessitates complex formulation strategies such as nanoparticle carriers, receptor-mediated transport, or invasive delivery methods, which increase development complexity and cost. Failure to achieve adequate brain concentrations results in therapeutic inefficacy despite potent in vitro activity. Researchers struggle to balance permeability with safety to avoid neurotoxicity from off-target exposure. Recent advances in focused ultrasound and intranasal delivery show promise but remain experimental. The lack of reliable non-invasive delivery platforms hinders the translation of promising laboratory findings into clinical practice. This physiological hurdle remains one of the most significant bottlenecks in neurodrug development. Overcoming it requires interdisciplinary collaboration between materials science, pharmacology,y and neuroscience.
Stigma and Underdiagnosis of Neurological Conditions
Social stigma associated with mental and neurological disorders leads to significant underdiagnosis and delayed treatment initiation, which constrains the expansion of the European neurotherapeutics market. This delay ultimately undermines the effectiveness of available neurotherapeutics. As per the European Platform Against Depression, cross-border clinical trial networks are expanding infrastructure to standardise biomarkers and optimise early intervention frameworks for individuals at risk of cognitive decline. The World Health Organisation indicates that the estimated treatment gap in European countries averages 45% for major depression and 40% for bipolar disorder, driving a continuous strain on regional psychiatric support structures. This lack of early engagement reduces the potential market for preventive and disease-modifying therapies. Misconceptions about disease inevitability or shame associated with cognitive decline discourage family members from advocating for medical evaluation. Primary care physicians may lack training to recognise early signs, leading to missed opportunities for intervention. Public awareness campaigns are making progress, but cultural barriers persist in certain demographics. Underdiagnosis distorts epidemiological data, complicating resource planning and drug development targeting. Pharmaceutical companies face challenges in educating both patients and providers to overcome these barriers. Addressing stigma is essential to unlocking the full potential of neurotherapeutic innovations.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Treatment, Distribution Channels, and Region |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered | UK, France, Spain, Germany, Italy, Russia, Sweden, Denmark, Switzerland, Netherlands, Turkey, Czech Republic, Rest of Europe |
| Market Leaders Profiled |
|
SEGMENTAL ANALYSIS
By Treatment Type Insights
The neurologic drugs segment remained the largest in 2025 and occupied a commanding share of the European Neurotherapeutics Market. This prominence of the segment was supported by its status as the first line of defence for managing chronic neurological conditions such as epilepsy, Parkinson’s disease, and multiple sclerosis. The widespread availability of oral formulations and established clinical guidelines ensure their pervasive use across healthcare settings.
The prevalence of neurologic drugs is firmly rooted in their inclusion as standard of care in major European clinical practice guidelines, which dictate treatment algorithms for neurological disorders. According to the European Academy of Neurology guidelines updated in 2023, the pharmacological selection process for treating focal epilepsy prioritises monotherapy regimens utilising third-generation anti-seizure medications over polytherapy setups to minimise adverse drug interactions. Studies by the European Medicines Agency indicate that conditional marketing authorisation procedures are being heavily utilised to fast-track small-molecule candidates targeting orphan neurological conditions across European markets. These drugs offer non-invasive administration routes, primarily oral, which enhances patient compliance and reduces the burden on healthcare infrastructure compared to surgical or device-based therapies. The extensive real-world evidence supporting their efficacy and safety profiles gives physicians confidence in prescribing them across diverse patient demographics. Furthermore, the ability to titrate doses allows for personalised management of symptoms, which is critical in progressive neurological diseases. This entrenched position ensures that neurologic drugs maintain the largest share of therapeutic expenditure despite the emergence of novel technological alternatives. The familiarity with these agents among general practitioners and specialists alike sustains high prescription volumes, ensuring market leadership.
Comprehensive reimbursement coverage for essential neurologic medications across European national health systems drives their widespread adoption and accessibility for patients. As per the European Observatory on Health Systems and Policies, individual member states face growing structural budget constraints due to expanding public expenditures on novel, high-cost orphan drugs and targeted biological therapies. Research from the Commonwealth Fund reveals that national universal health coverage frameworks in high-income European nations actively reduce socioeconomic disparities in baseline care access by implementing unified, tax-financed healthcare delivery infrastructures. This financial accessibility removes economic barriers that might otherwise prevent patients from initiating or continuing treatment. Public healthcare systems prioritize cost-effective pharmacological interventions over expensive procedural alternatives for initial management, creating a stable demand base. The predictability of reimbursement encourages pharmaceutical manufacturers to maintain robust supply chains and invest in generic production, which further lowers costs and expands access. In countries like Germany and France, statutory health insurance schemes cover the majority of neurotherapeutic costs, ensuring that price is not a prohibitive factor for the majority of the population. This supportive financial environment solidifies the position of neurologic drugs as the cornerstone of neurological care delivery across the continent.
The neurologic devices segment is on the rise and is expected to be the fastest-growing segment in the market, witnessing a CAGR of 11.2% from 2026 to 2034. This rapid expansion is propelled by advancements in neuromodulation technologies and increasing acceptance of device-based therapies for drug-resistant conditions.
The increasing incidence of medication-refractory neurological disorders such as drug-resistant epilepsy and treatment-resistant depression is a primary factor accelerating the adoption of neurologic devices. According to the International League Against Epilepsy, clinical definitions for drug-resistant epilepsy require a patient to fail two appropriately chosen and tolerated anti-seizure medication trials before exploring surgical or device-based alternative therapies. The European Society for Psychiatry indicates that inpatient psychiatric wards are increasing their adoption of non-invasive brain stimulation protocols to enhance clinical management safety for severe behavioural crises. These devices offer a mechanism of action distinct from pharmaceuticals, providing hope for patients who have exhausted conventional options. Clinical evidence demonstrating significant improvement in quality of life and symptom reduction for these difficult-to-treat populations drives physician referrals. Regulatory approvals for new indications such as obsessive-compulsive disorder and chronic pain further expand the utility of these devices. The ability to adjust stimulation parameters noninvasively allows for personalised therapy optimization. As awareness of these alternatives grows among both clinicians and patients, the uptake of neurologic devices is accelerating, rapidly outpacing the mature drug market.
Innovations in device design focusing on miniaturization, wireless connectivity, and minimally invasive implantation techniques are significantly enhancing patient acceptance and clinical outcomes. As per the Journal of Neural Engineering, recent implementations of closed-loop deep brain stimulation architectures utilize adaptive real-time local field potential feedback to track shifting disease states. Studies by the Medical Device Coordination Group show that manufacturers of high-risk medical hardware face strict clinical evidence evaluation barriers under the fully enforced European Medical Devices Regulation framework. These advanced devices reduce surgical risks and recovery times, making them attractive options for elderly patients who may not be candidates for major surgery. Wireless charging and remote programming capabilities enhance convenience, allowing patients to manage their therapy at home. Integration with digital health platforms enables continuous monitoring and data collection, facilitating proactive care management. The shift toward outpatient procedures for device implantation reduces hospital stay costs and resource utilisation. These technological improvements lower the barrier to entry for both providers and patients. Consequently, the neurologic devices segment is experiencing robust growth as it transitions from a niche salvage therapy to a mainstream treatment option for various neurological conditions.
By Distribution Channel Insights
In 2025, the hospitals segment held the majority share in the European Neurotherapeutics Market because of their role as primary centers for diagnosis, acute care, and complex treatment administration for severe neurological conditions.
Hospitals serve as the central hub for managing acute neurological events such as stroke, traumatic brain injury, and status epilepticus requiring immediate access to specialised equipment and multidisciplinary teams. According to the European Stroke Organization and Stroke Alliance for Europe, a primary goal under the Action Plan for Stroke in Europe is to ensure that 90% or more of all acute stroke patients across the region are treated within dedicated stroke units. Research from the European Hospital and Healthcare Federation indicates that national hospital systems are actively restructuring resource allocation models to integrate decentralised community services with central medical hubs. The concentration of neurologists, neurosurgeons, and specialized nursing staff in hospital settings ensures that patients receive comprehensive care adhering to strict clinical protocols. Hospitals are also the primary sites for initiating high-risk therapies such as immunosuppressants for multiple sclerosis or implantation of neurostimulators. The availability of advanced diagnostic imaging such as MRI and CT scans within hospital campuses facilitates rapid diagnosis and treatment initiation. This integrated infrastructure makes hospitals indispensable for the management of severe neurological disorders. Consequently, the majority of high-value neurotherapeutics are dispensed through hospital pharmacies, ensuring controlled administration and immediate clinical support.
National reimbursement policies in many European countries favour institutional care for high-cost neurotherapies, ensuring that hospitals remain the primary distribution channel for expensive biologics and devices. As per the German Institute for the Hospital Remuneration System, diagnosis-related group payment structures heavily incentivize specialized German clinics to reduce the average length of stay per inpatient admission to maximize overall throughput capacity. The French National Authority for Health shows that the Transparency Committee systematically implements health technology assessments to determine the therapeutic value and absolute reimbursement eligibility of newly launched medications. Also, the regulatory framework directs patient flow to hospitals rather than outpatient clinics for initial treatment phases. Public funding for hospital-based care ensures that financial barriers do not prevent access to critical therapies. Hospitals negotiate bulk purchasing agreements with manufacturers, securing favourable pricing and consistent supply. The administrative capacity of hospitals to handle complex billing and insurance claims further supports their dominance. Patients benefit from coordinated care plans managed by hospital-based case managers. These structural and financial incentives reinforce the position of hospitals as the leading distribution channel for neurotherapeutics across Europe.
The clinics segment is likely to experience the fastest CAGR of 9.5% during the forecast period owing to the shift toward outpatient care and management of chronic stable neurological conditions.
Healthcare systems across Europe are increasingly promoting outpatient care models to reduce hospital congestion and lower overall healthcare costs, driving growth in clinic-based neurotherapeutic distribution. According to the Organisation for Economic Co-operation and Development, public healthcare frameworks are expanding ambulatory care coordination models to minimize unnecessary acute hospital admissions for chronic baseline illnesses. Studies in the European Primary Care Monitor indicate that local general practitioners face a rising administrative tracking burden due to complex modern reporting standards across regional practices. Clinics offer convenient access for routine follow-ups, medication adjustments, and administration of subcutaneous or intramuscular injections such as monoclonal antibodies for migraine prevention. The decentralised nature of clinics reduces travel burdens for patients, particularly in rural areas. General practitioners and community neurologists are empowered to manage stable patients, freeing hospital resources for acute cases. This decentralisation improves patient satisfaction and adherence to long-term treatment plans. The expansion of private clinic networks in countries like Spain and Italy further accelerates this trend. As more therapies become suitable for outpatient administration, the role of clinics in the neurotherapeutics market continues to expand rapidly.
The integration of digital health tools in clinic settings enhances the capability of outpatient providers to manage neurological patients effectively, driving growth in this distribution channel. As per the European Digital Health Observatory, cross-border public healthcare policies promote digital interoperability frameworks to streamline patient record sharing between distinct primary care networks. Research from the British Medical Journal shows that the adoption of remote digital video consultations across rural primary care providers expands geographic access to targeted subspecialty consultations. These digital tools allow clinicians to monitor patients in real time, adjusting therapies promptly without requiring frequent physical visits. Clinics are well positioned to adopt these technologies due to their smaller size and agility compared to large hospitals. Patients appreciate the convenience of virtual check-ins combined with periodic in-person assessments. This hybrid model supports the management of chronic conditions such as multiple sclerosis and Parkinson’s disease in a community setting. The ability to provide personalised, attentive care in a less intimidating environment enhances patient engagement. Consequently, clinics are becoming preferred destinations for ongoing neurological care, fueling their rapid growth as a distribution channel.
COUNTRY LEVEL ANALYSIS
Germany Neurotherapeutics Market Analysis
Germany dominated the European Neurotherapeutics Market and accounted for a substantial share in 2025. The country’s dominance in the regional market was driven by its advanced healthcare infrastructure, high healthcare expenditure, and a strong focus on research and development. According to the Federal Statistical Office of Germany, the domestic healthcare system expanded its total clinical headcount to 4.5 practicing physicians per 1,000 inhabitants, stabilizing baseline emergency and elective care availability across the nation. The German Research Foundation indicates that the central funding body allocated an annual institutional budget of 3.6 billion euros to support more than 30,000 international scientific research projects. Also, the statutory health insurance system provides comprehensive coverage for neurotherapeutics, ensuring high patient adherence and minimal financial barriers. Germany serves as a key launch market for new neurotherapies due to its efficient regulatory processes and large patient population. The presence of major pharmaceutical manufacturers supports local clinical trials and early access programs. Strong patient advocacy groups influence policy decisions prioritising neurological health. The ageing population further drives demand for treatments targeting dementia and Parkinson’s disease. These factors combine to maintain Germany’s leadership position in the regional market.
United Kingdom Neurotherapeutics Market Analysis
The United Kingdom followed closely behind in the European neurotherapeutics market in 2025. It was propelled by a centralised National Health Service that dictates treatment pathways and reimbursement decisions. As per the National Institute for Health and Care Excellence, rigorous health technology assessments guide the adoption of new neurotherapies, ensuring long-term cost-effectiveness across the National Health Service framework. Studies by NHS Digital show that neurology referral timelines continue to experience severe delays, with less than 60% of registered patients successfully starting their specialised treatments within the standard 18-week constitutional target window. The UK is a hub for clinical research, with numerous academic centres participating in global trials for Alzheimer’s and multiple sclerosis. Government initiatives such as the Dementia Mission aim to accelerate diagnosis and treatment, improving market dynamics. Despite budget constraints, the NHS prioritizes high-impact therapies, ensuring access to essential treatments. The presence of leading biotechnology firms in Cambridge and London fosters innovation. Patient registries provide valuable real-world data supporting evidence-based decision-making. These elements sustain the UK’s prominent role in the European neurotherapeutics landscape.
France Neurotherapeutics Market Analysis
France exhibits a strong landscape in Europe neurotherapeutics market. This presence is supported by a universal healthcare system and a strong emphasis on neurological research and patient care. According to the French National Authority for Health, the national early access program allows patients immediate treatment options with innovative, unauthorized therapeutic drugs before market approval is formally completed. Research from the French Brain Council indicates that neurological conditions impose a significant socio-economic footprint across France, accelerating annual therapeutic delivery demands across all regions. The country hosts leading research institutes such as the Institut du Cerveau, which contribute to groundbreaking discoveries in neurodegeneration. Public hospitals play a central role in delivering complex treatments while private clinics handle chronic management. Government policies promote equitable access to care across regions, reducing geographic disparities. High patient awareness and advocacy drive demand for newer treatments. The pharmaceutical industry benefits from favourable pricing negotiations and a stable regulatory environment. These factors ensure steady growth and innovation in the French neurotherapeutics market.
Italy Neurotherapeutics Market Analysis
Italy experiences steady growth in the Europe neurotherapeutics market due to an aging population and the increasing focus on neurological care modernization. As per the Italian National Institute of Statistics, the proportion of individuals aged 65 and older exceeds 23%, accelerating long-term age-related therapeutic infrastructure upgrades across the nation. The Italian Society of Neurology shows that updated intersocietal clinical protocols prioritize early biomarker-based screening to optimize patient enrollment in targeted specialist centers. Regional healthcare variations exist, but national guidelines ensure a standard of care across the country. Public funding supports research collaborations with European partners, enhancing clinical trial participation. The government is investing in digital health infrastructure to improve remote monitoring and outpatient care. Patient associations play a vital role in advocating for better services and reimbursement. Economic challenges persist, but commitment to healthcare sustainability ensures continued market development. These dynamics position Italy as a key contributor to the European market.
Spain Neurotherapeutics Market Analysis
Spain shows promising growth potential in the European neurotherapeutics market, owing to universal healthcare coverage and expanding neurological services. According to the Spanish Society of Neurology, persistent clinical time constraints remain a major limiting factor for incorporating proactive brain health promotion strategies within standard patient visits. Studies by the Ministry of Health indicate that total public financial healthcare expenditure across the autonomous regions expands continuously to optimize standard outpatient disease care delivery frameworks. The country is implementing national strategies for dementia and Parkinson’s disease, enhancing early diagnosis and treatment. Regional autonomous communities manage healthcare delivry , leading to varied implementation speeds but overall broad access. Participation in international research networks facilitates early access to investigational drugs. Patient advocacy is strong, influencing policy and resource allocation. Medical tourism services also contribute to specialized care demand. These factors create a dynamic and accessible market environment conducive to growth.
COMPETITIVE LANDSCAPE
The competitive landscape of the Europe Neurotherapeutics Market is characterized by intense rivalry among established pharmaceutical giants and emerging biotechnology firms striving for therapeutic innovation. Major participants continuously invest in research and development to introduce novel mechanisms of action such as antisense oligonucleotides and gene therapies that offer potential cures for rare neurological disorders. This drive for innovation results in frequent clinical trial initiations and regulatory submissions targeting previously untreatable conditions. Companies also compete through strategic acquisitions and licensing agreements aiming to broaden their product portfolios and access cutting-edge technologies. Digital integration plays a crucial role as firms leverage real-world data to optimize treatment protocols and demonstrate value to health technology assessment bodies. Regulatory compliance remains a significant differentiator, with companies navigating diverse national reimbursement frameworks to ensure market access. Price competition is moderated by value-based pricing models focusing on clinical outcomes rather than cost alone. Brand reputation and clinical support significantly influence prescribing decisions, creating loyalty among neurologists. The market sees continuous evolution as biosimilars enter the space,e challenging originators to innovate further, er ensuring dynamic and progressive competition across the continent.
KEY MARKET PLAYERS
Some of the companies that are playing a dominating role in the Europe Neurotherapeutics Market include:
- Abbott Laboratories, Inc.
- Becton, Dickinson and Company
- Novartis AG
- Pfizer, Inc.
- Johnson & Johnson
- Biogen, Inc.
- GlaxoSmithKline, Inc.
- AstraZeneca plc
- Sanofi-Aventis
- Spiegelberg
- Stryker Corporation
- Covidien
- Medtronic plc
- GE HealthCare
- Merck & Co., Inc.
TOP PLAYERS IN THE MARKET
- Roche Holding AG maintains a prominent position in the European neurotherapeutics sector through its robust portfolio of disease-modifying therapies for multiple sclerosis and Alzheimer’s disease. The company actively invests in research to develop novel monoclonal antibodies targeting neuroinflammation and amyloid pathology. Recent initiatives include advancing lecanemab approval processes across major European markets to address early-stage Alzheimer’s disease. Roche collaborates with academic institutions to validate digital biomarkers enhancing precision medicine applications. Their strategic focus on integrated diagnostics and therapeutics improves patient stratification and treatment outcomes. This commitment to innovation and comprehensive care solutions solidifies their reputation as a trusted partner for healthcare providers seeking advanced neurological treatments.
- Biogen Inc demonstrates strong market engagement through its leadership in developing therapies for multiple sclerosis and spinal muscular atrophy. The company emphasizes clinical excellence by conducting large-scale trials across Europe to validate efficacy in diverse populations. Recent actions involve launching next-generation oral formulations for multiple sclerosis to improve patient convenience and adherence. They have strengthened distribution networks by partnering with local logistics providers, ensuring timely delivery of temperature-sensitive biologics. Investment in gene therapy platforms facilitates development of curative options for rare neurological disorders. Their agile approach to regulatory changes enables rapid market entry for novel therapies, positioning them as a responsive leader in European neurology care.
- Novartis AG leverages its scientific heritage to deliver innovative neurotherapeutics,s includingsphingosine-1-phosphatee receptor modulators and calcitonin gene-related peptide inhibitors. The company focuses on developing treatments that slow disease progression in multiple sclerosis and prevent migraine attacks. Recent developments include expanding manufacturing capacity in Switzerland to ensure consistent supply of critical neurologic drugs. They actively engage with payers to demonstrate value through real-world evidence supporting reimbursement decisions. Strategic alliances with technology firms foster innovation in digital therapeutics for cognitive health. Their dedication to scientific rigor and patient centricity ensures sustained growth and reinforces their status as a key contributor to advancing neurological care standards throughout Europe.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the Europe Neurotherapeutics Market primarily employ strategic partnerships and pipeline diversification to maintain competitive advantage. Companies invest heavily in collaborations with academic research centers to identify novel targets and validate biomarkers essential for precision medicine. This focus on scientific discovery allows them to develop differentiated therapies addressing unmet medical needs in neurodegeneration. Simultaneously, firms expand manufacturing capabilities within Europe to mitigate supply chain risks and ensure compliance with local regulations. These investments facilitate rapid response to demand fluctuations and regulatory requirements. Additionally, manufacturers prioritize health economics outcomes research to demonstrate value to payers,s securing favorable reimbursement terms. Such multifaceted strategies enable companies to navigate complex regulatory landscapes effectively while strengthening brand loyalty among clinicians and patients across European healthcare systems.
MARKET SEGMENTATION
This research report on the European neurotherapeutics market has been segmented and sub-segmented into the following categories.
By Treatment
-
Neurologic drugs
- Oral administration
- Injections
- Neurologic devices
- Electroconvulsive Therapy (ECT)
- Vagus Nerve Stimulation (VNS)
- Transcranial magnetic stimulation
- Deep Brain Stimulator
By Disorders
- Central Nervous System (CNS) Disorders
- Peripheral Nervous System (PNS) Disorder
- Autonomicus Nervous System (ANS) Disorders
By Distribution channels
- Hospitals
- Neurotherapeutic Centre
- Clinical research organizations
- Clinics
By Country
- UK
- France
- Spain
- Germany
- Italy
- Russia
- Sweden
- Denmark
- Switzerland
- Netherlands
- Turkey
- Czech Republic
- Rest of Europe