- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
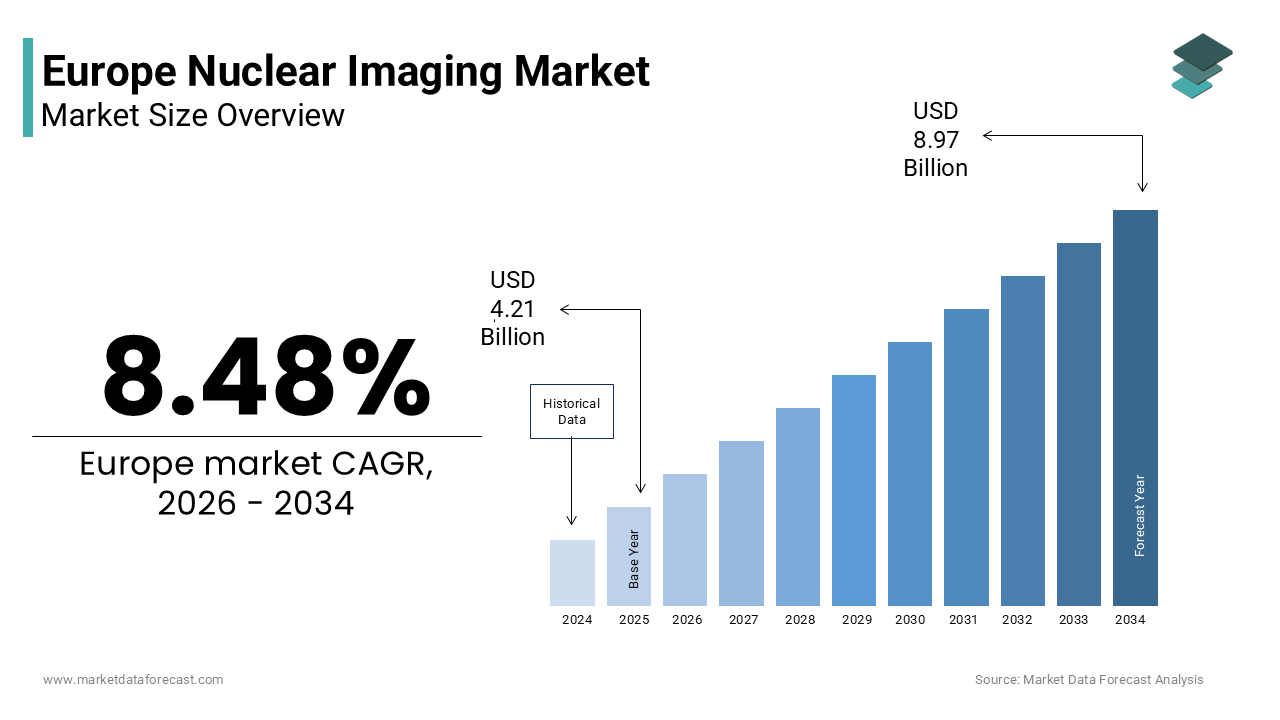
$4.21 BnMarket Estimate, 2026
$4.57 BnMarket Forecast, 2034
$8.97 BnCAGR, 2026–2034
8.48%Executive Summary: Europe Nuclear Imaging Market
- Market Scope: Comprehensive European nuclear imaging market analysis covering product types, clinical applications, end-user settings, country-level frameworks, and technological/diagnostic adoption drivers.
- Market Valuation: Valued at USD 4.21 billion (2025), estimated at USD 4.57 billion (2026), and projected to reach USD 9.00 billion by 2034, registering a robust CAGR of 8.48% (2026–2034).
- Primary Growth Drivers: Rising incidences of cancer and cardiac ailments, increased emphasis on personalized medicine, rapid shift from standalone to hybrid imaging modalities, and advancements in radiotracers and data-integrated systems. Key market constraints include the short shelf-life of radiopharmaceuticals, high device costs, continuous reimbursement cuts, and a lack of specialized nuclear imaging expertise.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Product | Standalone PET and SPECT nuclear imaging systems (historical baseline market share) | Hybrid nuclear imaging systems (driven by multi-modality integration advantages) |
| By Application | Oncology (led clinical application workflows for tumor monitoring and drug response management) | Cardiology and advanced neurological disorder imaging applications |
| By End-User | Hospitals (represented the primary deployment setting for high-end nuclear equipment) | Specialized diagnostic centers and research facilities |
| By Country | Germany (accounted for the largest regional market share in Europe, followed by France and the UK) | Switzerland, Poland, Denmark, and Sweden (projected to witness high growth rates) |
Major Market Players & Market Structure
Market Structure: Highly competitive European market landscape featuring major international medical technology corporations and radiopharmaceutical innovators competing intensely on spatial resolution, hybrid systems, and advanced data integration.
Key Companies: Mallinckrodt plc, Siemens Medical Solutions, Hitachi Medical Corporation, Medtronic Inc., General Electric Co. (Healthcare Division), IBA Group, Positron Corporation, Philips Medical Systems, Naviscan, Toshiba Medical Systems Corporation, Carestream Health, Lantheus Medical Imaging Inc., Cardinal Health Inc., and Bayer AG.
 Download Free Sample Report
Europe Nuclear Imaging Market Size
The Europe nuclear imaging market size was valued at USD 4.21 billion in 2025 and is anticipated to reach USD 4.57 billion in 2026 from USD 9.00 billion by 2034, growing at a CAGR of 8.48% during the forecast period from 2026 to 2034.
According to the European Association of Nuclear Medicine, over 3 million nuclear medicine procedures are performed annually across major European healthcare systems, reflecting widespread clinical adoption. As per data from the World Health Organization, cancer and cardiovascular diseases account for approximately 45% of all deaths in the European region, necessitating precise functional assessment for effective management. These statistics underscore the vital role of nuclear imaging in early disease detection, staging, and treatment monitoring. The market dynamics are heavily influenced by an aging demographic, as the risk of chronic conditions increases significantly with age. Advanced radiopharmaceuticals such as fluorodeoxyglucose have become standard protocols in leading oncology centers for tumor metabolism evaluation. The integration of hybrid systems combining PET or SPECT with CT or MRI enhances diagnostic accuracy substantially. Regulatory frameworks governed by the European Medicines Agency strictly evaluate radioisotope safety and efficacy, ensuring patient protection. This rigorous oversight shapes the competitive landscape while driving innovation in tracer development and detector technology tailored to complex clinical needs across the continent.
MARKET DRIVERS
Rising Prevalence of Oncological and Cardiovascular Disorders
The escalating burden of cancer and heart disease across European nations is a key factor propelling the Europe nuclear imaging market growth due to the indispensable role of functional imaging in diagnosis. Oncology remains the largest application area, where positron emission tomography is crucial for staging, detecting metastasis, and assessing response to therapy. According to the European Cancer Information System, there were approximately 2.7 million new cancer cases diagnosed in the European Union in 2022, with a significant portion requiring advanced imaging for accurate staging. This high volume of diagnoses creates sustained demand for PET scanners and associated radiotracers. Similarly, cardiovascular diseases remain a leading cause of mortality, necessitating precise assessment of myocardial perfusion and viability. The European Society of Cardiology states that cardiovascular diseases affect over 85 million people in Europe, driving the need for non-invasive diagnostic tools like SPECT. Healthcare providers prioritize these imaging modalities because they offer superior sensitivity in detecting early-stage abnormalities compared to traditional methods. Hospitals invest heavily in nuclear medicine departments to handle the increasing patient load efficiently. The ability of nuclear imaging to guide personalized treatment plans reduces unnecessary interventions and improves patient outcomes. This clinical utility ensures consistent procurement of equipment and isotopes. As the aging population grows, the incidence of these chronic conditions will rise further, supporting continuous market growth and technological advancement in diagnostic capabilities.
Technological Advancements in Hybrid Imaging Systems
Breakthroughs in hybrid imaging technologies fundamentally transform the diagnostic landscape in Europe by combining functional nuclear data with high-resolution anatomical details, which further fuels the regional market expansion. The integration of PET with CT or MRI and SPECT with CT allows clinicians to correlate metabolic activity with structural anomalies precisely. According to the European Journal of Nuclear Medicine and Molecular Imaging, hybrid PET-CT systems have improved diagnostic accuracy by 30% in oncology cases compared to standalone PET scanners. This technological evolution drives hospitals to upgrade their infrastructure with state-of-the-art multimodality systems. The enhanced spatial resolution and reduced scan times offered by modern detectors improve patient throughput and comfort. Digital detector technologies have further increased sensitivity, enabling lower radiation doses while maintaining image quality. Scientific studies published by the European Association of Nuclear Medicine report that digital PET scanners can reduce scan time by up to 50%, facilitating higher patient volume in busy clinics. This efficiency is highly valued in healthcare settings facing resource constraints. Regulatory approvals for new hybrid systems facilitate their commercialization, enabling wider access for healthcare providers. The shift towards precision medicine requires detailed molecular mapping, which hybrid systems provide effectively. As awareness of these advanced capabilities grows among radiologists and oncologists, the demand for sophisticated imaging hardware continues to rise, reinforcing the market expansion trajectory.
MARKET RESTRAINTS
High Costs Associated with Equipment and Radiopharmaceuticals
The substantial financial burden associated with acquiring and maintaining nuclear imaging infrastructure is a significant restraint, limiting accessibility and market penetration in certain European regions. Positron emission tomography and SPECT scanners require significant capital investment, often exceeding 2 million euros per unit depending on configuration and features. As per the European Health Management Association, the operational costs, including cyclotron maintenance, radiotracer synthesis, and specialized staff salaries, adds considerably to the total expense. This high expense places immense pressure on public healthcare systems and private hospitals already grappling with budget constraints. Reimbursement policies vary significantly across European countries, creating disparities in patient access to advanced nuclear imaging procedures. Many national health insurance schemes do not fully cover newer radiopharmaceuticals, forcing patients to bear out-of-pocket expenses or rely on limited private coverage. This financial barrier discourages the widespread adoption of cutting-edge diagnostic tools, particularly in Eastern and Southern European nations where healthcare funding remains restricted. Hospitals may hesitate to install new systems due to uncertain return on investment, leading to supply chain inconsistencies. Additionally, the short half-life of many radioisotopes necessitates complex logistics and just-in-time delivery, which increases costs. These financial challenges restrict market growth by limiting the number of facilities able to afford premium imaging solutions, thereby slowing the uptake of advanced technologies despite their proven clinical benefits.
Stringent Regulatory Requirements for Radioisotope Handling
Rigorous regulatory requirements imposed by European authorities create substantial delays and hurdles for manufacturers and healthcare providers involved in the nuclear imaging sector. The production, transport, and administration of radioactive materials are subject to strict safety protocols enforced by agencies such as the European Atomic Energy Community and national regulators. The European Atomic Energy Community reports that compliance with radiation safety standards requires extensive documentation, regular inspections, and specialized training for personnel, which increases operational complexity. This prolonged timeline increases administrative costs and delays the introduction of new radiopharmaceuticals to the market. Small and medium-sized enterprises often struggle to navigate the complex regulatory landscape due to limited resources and expertise compared to larger multinational corporations. The requirement for secure storage and disposal of radioactive waste further adds to the operational burden, maintaining compliance throughout the product lifecycle. Variations in regulations across different European countries complicate the supply chain, requiring manufacturers to adapt to diverse legal frameworks. This fragmentation increases logistical costs and slows down market entry, particularly for novel tracers with short half-lives. The uncertainty surrounding regulatory approvals discourages some investors from funding early-stage radiopharmaceutical innovations, limiting the pipeline of new products. Consequently, the market experiences slower introduction of advanced diagnostic agents, reducing competition and keeping prices elevated. Providers must balance innovation with compliance, ensuring that all practices meet stringent safety standards.
MARKET OPPORTUNITIES
Expansion of Theranostics and Personalized Medicine
The emerging field of theranostics, which combines diagnostic imaging with targeted radionuclide therapy is a significant opportunity for enhancing patient care and expanding market reach in Europe. This approach allows clinicians to use the same molecular target for both imaging and treatment, ensuring that therapy is delivered only to patients who are likely to respond. According to the European Association of Nuclear Medicine, theranostic applications in prostate cancer and neuroendocrine tumors have improved treatment outcomes by 40% in recent clinical trials. This success drives demand for specific radiopharmaceuticals such as lutetium-177 and gallium-68 labeled compounds. Hospitals are increasingly establishing dedicated theranostics units to manage these complex workflows. The growing penetration of genomic profiling supports the identification of suitable candidates for theranostic interventions. Insurance providers increasingly recognize the cost-saving potential of personalized therapy, leading to broader coverage for these procedures. Manufacturers of radiopharmaceuticals can integrate diagnostic and therapeutic offerings, creating new revenue streams. Collaborations between pharmaceutical companies and imaging device manufacturers drive innovation in this space, developing paired agents for seamless clinical use. As regulatory frameworks evolve to accommodate theranostic products, the market stands to benefit from increased efficiency, improved outcomes, and expanded access to targeted treatments, particularly for rare and aggressive cancers.
Growing Adoption in Neurological Disorders and Alzheimer’s Disease
The increasing focus on early detection and management of neurological disorders offers substantial opportunities for the Europe nuclear imaging market, particularly in the context of Alzheimer’s disease and dementia. Advances in amyloid and tau protein imaging tracers enable clinicians to diagnose Alzheimer’s disease before significant cognitive decline occurs. As per the European Brain Council, early diagnosis using PET imaging can delay disease progression by 20% through timely intervention and lifestyle modifications. This capability drives demand for specialized neuroimaging protocols and tracers such as florbetapir and flortaucipir. Pharmaceutical companies develop companion diagnostics alongside new Alzheimer’s therapies to identify patients most likely to benefit from treatment, enhancing efficacy. The integration of artificial intelligence algorithms assists in analyzing brain scans to identify subtle patterns of neurodegeneration, supporting clinical decision-making. Hospitals invest in high-resolution PET scanners capable of detailed brain imaging, creating demand for specialized software and services. Patient advocacy groups promote the benefits of early detection, encouraging greater awareness and adoption among healthcare providers. Regulatory bodies support this trend by approving new tracers for neurological indications, fostering innovation in the sector. The ability to offer precise diagnosis differentiates providers in a competitive market, attracting patients seeking optimized care experiences. As the global population ages, the prevalence of dementia rises, driving the need for advanced diagnostic tools.
MARKET CHALLENGES
Shortage of Skilled Nuclear Medicine Professionals
The scarcity of trained healthcare professionals specializing in nuclear medicine poses a significant challenge to the Europe nuclear imaging market. Nuclear imaging requires multidisciplinary expertise, including nuclear medicine physicians, radiologists, technologists, and radiochemists, who possess specific skills in handling radioactive materials and interpreting complex functional images. According to the European Society of Nuclear Medicine, there is a deficit of approximately 15% in certified nuclear medicine technologists in major European healthcare markets, leading to increased workload and potential delays in patient care. This shortage stems from inadequate training programs, limited residency positions, and high burnout rates among existing staff due to the technically demanding nature of the field. The complexity of operating hybrid systems and synthesizing radiopharmaceuticals necessitates continuous education and skill development, which many healthcare systems fail to provide adequately. Without sufficient trained personnel, hospitals struggle to maintain optimal staffing levels, resulting in longer wait times and reduced access to specialized services, particularly in rural areas. The lack of standardized training curricula across different European countries further exacerbates the issue, creating disparities in care quality and professional competency. Recruitment efforts face challenges due to the niche nature of nuclear medicine and the radiation safety concerns associated with the job. This workforce gap limits the capacity of healthcare facilities to handle the increasing volume of imaging requests. Addressing this challenge requires coordinated efforts from educational institutions and policymakers to expand training opportunities.
Supply Chain Vulnerabilities for Radioisotopes
Disparities in the production and distribution of medical radioisotopes create significant barriers to reliable service delivery and hinder market stability in Europe. Most medical isotopes, such as molybdenum-99 and technetium-99m, are produced in a limited number of aging nuclear reactors globally, making the supply chain highly vulnerable to disruptions. The European Atomic Energy Community indicates that unplanned shutdowns of major reactors have caused supply shortages affecting up to 30% of nuclear medicine procedures in affected regions during peak crisis periods. This inconsistency complicates scheduling for healthcare providers who must cancel or reschedule patient appointments due to lack of tracers. Hospitals encounter operational inefficiencies when dealing with unpredictable supply, leading to wasted resources and patient dissatisfaction. The short half-life of these isotopes means they cannot be stockpiled, requiring just-in-time delivery, which is susceptible to logistical delays. The lack of diversified production sources within Europe discourages investment in alternative production methods, such as accelerator-based isotope generation. Policymakers struggle to ensure supply security, leading to periodic crises that disrupt patient care. This fragmented landscape impedes the widespread adoption of routine nuclear imaging procedures, slowing market growth and limiting patient access. Efforts to establish regional production facilities face technical and economic hurdles, delaying progress towards a more resilient supply chain. Until greater redundancy is achieved, the market will continue to experience volatility.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 8.48% |
| Segments Covered | By Diagnostic Technologies, Application, End User and Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | UK, France, Spain, Germany, Italy, Russia, Sweden, Denmark, Switzerland, the Netherlands, Turkey, the Czech Republic, and the Rest of Europe. |
| Market Leaders Profiled | Mallinckrodt plc, Siemens Medical Solutions, Hitachi Medical Corporation, Medtronic Inc., General Electric Co. (Healthcare Division), IBA Group, Positron Corporation, Philips Medical Systems, Naviscan, Toshiba Medical Systems Corporation, Carestream Health, Lantheus Medical Imaging Inc., Cardinal Health Inc., and Bayer AG. |
SEGMENTAL ANALYSIS
By Diagnostic Technologies Insights
The hybrid nuclear imaging systems segment led the market with 61.7% of the regional market share in 2025. The dominance of hybrid imaging systems segment in the European market can be credited to their superior diagnostic accuracy and ability to provide comprehensive anatomical and functional data in a single session and its proven ability to correlate metabolic activity with precise anatomical structures, significantly reducing diagnostic errors. According to the European Journal of Nuclear Medicine and Molecular Imaging, hybrid PET-CT systems have improved diagnostic specificity by 35% in oncology staging compared to standalone modalities, allowing for more accurate treatment planning. This statistical evidence underscores the critical role hybrid systems play in minimizing false positives and negatives, which is essential for patient safety. Healthcare providers prioritize these systems because they eliminate the need for separate scans, reducing patient exposure to radiation and saving time. The integration of CT or MRI with PET or SPECT provides a complete picture of disease extent, which is vital for surgical planning and radiation therapy mapping. Clinical guidelines from major European medical societies recommend hybrid imaging as the gold standard for many cancers, ensuring consistent demand. Hospitals invest in these high-cost systems to maintain competitive advantage and attract referrals. The ability to detect smaller lesions and assess response to therapy earlier drives adoption. As clinical protocols evolve to favor precision medicine, the reliance on hybrid imaging grows. This widespread endorsement ensures that hybrid systems remain the cornerstone of modern nuclear medicine departments, supporting their leading market position through sustained procurement and replacement cycles.
However, the standalone PET nuclear imaging segment represents the fastest-growing segment in the Europe nuclear imaging market and is expected to showcase a CAGR of 7.4% over the forecast period owing to the breakthroughs in digital detector technology that offer superior sensitivity and resolution without the need for CT integration. As per the European Association of Nuclear Medicine, digital PET scanners have increased lesion detectability by 25% compared to analog systems, enabling earlier diagnosis of subtle metabolic changes. This technological leap attracts specialized centers focusing on neurology and cardiology, where high-resolution functional data is paramount. Standalone systems are often more affordable than hybrid counterparts, making them accessible to smaller clinics and research institutions. The modular nature of standalone PET allows for easier upgrades and maintenance, extending the lifecycle of the equipment. Clinicians value the pure functional data provided by standalone PET for specific applications such as myocardial viability assessment, where anatomical correlation is less critical. The reduced complexity of standalone systems lowers the barrier to entry for facilities new to nuclear medicine. Regulatory approvals for new digital PET models have expanded the range of available options, driving competition and innovation. Pharmaceutical companies support this growth by developing tracers specifically optimized for high-sensitivity PET detection. The focus on quantitative accuracy in research settings further drives demand for standalone units. As awareness of digital benefits spreads, the adoption of standalone PET accelerates. This trend is supported by the growing emphasis on precision diagnostics in specialized medical fields.
By Application Insights
The oncology segment dominated the market by holding 54.6% of the regional market share in 2025. The growth of the oncology segment in the European market is attributed to the critical role of nuclear imaging in cancer diagnosis, staging, and treatment monitoring and the indispensable role of nuclear imaging in accurately staging cancer and monitoring therapeutic response. According to the European Cancer Information System, there were approximately 2.7 million new cancer cases diagnosed in the European Union in 2022, with a majority requiring advanced imaging for initial assessment. This high volume of diagnoses creates sustained demand for PET and SPECT procedures, particularly using fluorodeoxyglucose. Oncologists rely on nuclear imaging to distinguish between benign and malignant lesions, guiding biopsy and surgical decisions. The ability to detect distant metastases early prevents unnecessary surgeries and optimizes treatment plans. Serial imaging allows clinicians to assess tumor response to chemotherapy or radiation therapy, enabling timely adjustments. National cancer guidelines in countries like Germany and France recommend nuclear imaging for various malignancies, including lung, breast, and lymphoma, ensuring standardized usage. The high reimbursement rates for oncology imaging procedures support financial viability for healthcare providers. Patients benefit from non-invasive monitoring, which reduces the need for exploratory surgeries. The growing incidence of cancer due to aging and lifestyle factors ensures a steady pipeline of patients. Pharmaceutical companies develop companion diagnostics alongside new cancer drugs, further integrating nuclear imaging into care pathways. This deep integration cements oncology as the primary driver of the nuclear imaging market. The continuous development of tumor-specific tracers expands the scope of applications. Thus, the segment remains robust and central to market dynamics.
However, the neurology segment is the fastest-growing application segment in the Europe nuclear imaging market and is estimated to witness a CAGR of 8.4% over the forecast period owing to the increasing global burden of neurodegenerative diseases such as Alzheimer’s disease, Parkinson’s disease, and dementia. As per the World Health Organization, over 55 million people currently live with dementia worldwide, with nearly 10 million new cases every year affecting a significant portion of the European population. This demographic trend creates an urgent need for early and accurate diagnostic tools to differentiate between various forms of dementia. Nuclear imaging with specific tracers allows for the visualization of amyloid plaques and tau tangles, which are hallmarks of Alzheimer’s disease. Early diagnosis enables timely intervention and participation in clinical trials for disease-modifying therapies. Healthcare systems are prioritizing cognitive health assessments, leading to increased referral for brain imaging. The aging population in developed countries further amplifies this demand. Public awareness campaigns reduce stigma and encourage individuals to seek evaluation for memory loss. Insurance coverage for amyloid PET scans is expanding in several European regions, facilitating access. The ability to rule out other causes of cognitive decline adds value to the diagnostic process. Neurologists rely on these images to confirm diagnoses and manage patient expectations. This clinical necessity drives the adoption of nuclear imaging in neurology practices. The segment grows as diagnostic criteria evolve to include biomarker evidence. The focus on early detection supports sustained market expansion.
By End User Insights
The hospitals segment held a dominant position in the European market with 65.9% of the European market share in 2025 due to their capacity to handle complex cases, integrate imaging with multidisciplinary care andtheir ability to integrate nuclear imaging seamlessly into multidisciplinary care teams involving oncologists, cardiologists, and surgeons. According to the European Federation of National Associations of Orthopaedics and Traumatology, coordinated care is emphasized, which hospitals are best positioned to provide through centralized imaging departments. This integration ensures that imaging results are immediately available for treatment planning and decision-making. Hospitals have the resources to maintain cyclotrons or partner with nearby production facilities, ensuring steady supply of short-lived isotopes. The presence of specialized nuclear medicine physicians and technologists ensures high-quality image acquisition and interpretation. Complex cases often require immediate follow-up with other diagnostic modalities, which hospitals can provide onsite. This convenience improves patient flow and reduces delays in care. Academic medical centers within hospital systems drive innovation and adopt new technologies early. Teaching programs ensure a steady supply of trained professionals. Hospitals also benefit from economies of scale in purchasing equipment and supplies. The reputation of major hospitals attracts patients seeking advanced care. Insurance contracts often favor hospital-based services due to negotiated rates. This structural advantage sustains the leading position of hospitals. The comprehensive nature of hospital care supports high-volume imaging. Thus, hospitals remain the primary hub for nuclear imaging services.
On the other hand, the diagnostic centers segment is the fastest-growing end user segment in the Europe nuclear imaging market and is predicted to register a CAGR of 9.4% over the forecast period owing to the global healthcare trend towards outpatient and ambulatory care settings. As per the European Observatory on Health Systems and Policies, outpatient procedures have increased by 20% in recent years as payers seek to reduce costs associated with hospital stays. Diagnostic centers offer lower overhead costs and faster service, making them attractive to patients and insurers. These centers specialize in imaging services, allowing for focused expertise and efficient workflows. Patients prefer the convenience and shorter wait times offered by standalone diagnostic facilities. The rise of consumer-driven healthcare encourages individuals to seek transparent pricing and convenient locations. Diagnostic centers often operate with extended hours, accommodating working professionals. The flexibility of these centers allows for quicker adoption of new technologies without bureaucratic hurdles. Partnerships with referring physicians ensure a steady stream of patients. Insurance networks increasingly include independent diagnostic centers to expand provider options. The focus on patient experience drives investment in comfortable environments and customer service. This market dynamic supports the rapid growth of the segment. As healthcare systems decentralize, diagnostic centers capture a larger share of routine imaging. The segment benefits from agility and customer-centric models. Thus, diagnostic centers emerge as a key growth engine.
COUNTRY ANALYSIS
Germany Nuclear Imaging Market Analysis
Germany led the market with 27.4% of the European market share in 2025 and is expected to maintain its leading position throughout the forecast period due to the robust healthcare investments, high adoption rates of advanced imaging and its advanced healthcare infrastructure and high adoption of innovative technologies. The country is a pioneer in integrating hybrid imaging and theranostics into standard care protocols. According to the German Society of Nuclear Medicine, Germany has one of the highest densities of PET-CT scanners in Europe, with over 300 units installed nationwide. This high adoption drives demand for advanced imaging devices and radiopharmaceuticals. The country's strong regulatory framework ensures rapid access to new therapies. Germany has a large aging population, contributing to high incidence rates of cancer and neurological disorders. Health insurance coverage is comprehensive, allowing patients to access expensive treatments like amyloid PET scans. The government invests heavily in cancer research, supporting innovation. Major pharmaceutical companies have headquarters in Germany, fostering local development. The focus on precision medicine drives the use of molecular imaging. Public awareness campaigns promote early detection, increasing diagnosis rates. The market is mature, with high competition among providers. Germany serves as a hub for clinical trials, attracting global investment. The emphasis on multidisciplinary care ensures optimal patient management. These factors combine to make Germany a stable and growing market with a focus on technological advancement and high standards of care.
UK Nuclear Imaging Market Analysis
The UK is projected to witness steady, value-driven market growth over the coming years owing to its centralized National Health Service and focus on cost-effective care. The NHS plays a pivotal role in determining treatment pathways through guidelines issued by the National Institute for Health and Care Excellence. As per the British Nuclear Medicine Society, the UK performs over 500,000 nuclear medicine procedures annually, with a growing shift towards hybrid imaging. This volume creates steady demand for diagnostic products. The UK is increasingly adopting multiparametric MRI and PET for diagnosis, reducing unnecessary biopsies. The Prostate Cancer UK charity drives awareness and funding for research. Brexit has introduced some regulatory changes, but the UK continues to align with international standards. The market faces pressure to reduce costs, leading to increased use of generic radiopharmaceuticals. Telemedicine is being integrated into follow-up care, improving efficiency. The aging population contributes to rising incidence rates. Access to new drugs can be delayed due to health technology assessments. However, the commitment to equitable care ensures broad access. The UK market is characterized by structured pathways and evidence-based decision-making. Innovation is supported through academic partnerships. The focus on value-based healthcare shapes procurement strategies. The market remains stable with gradual adoption of new technologies.
France Nuclear Imaging Market Analysis
France is anticipated to experience robust expansion over the upcoming years due to the strong government-backed healthcare frameworks, a high emphasis on clinical excellence and its robust healthcare system and emphasis on high-quality care. The French healthcare system provides comprehensive coverage for cancer treatments, ensuring high accessibility. According to the French Society of Nuclear Medicine, France has a high density of nuclear medicine departments, facilitating early diagnosis and treatment. The country is a leader in theranostics and focal therapies for cancer. France attracts medical tourists seeking advanced care. The National Authority for Health regulates drug pricing and reimbursement, ensuring affordability. The aging population in France drives demand for nuclear imaging services. Research institutions in France are active in developing new biomarkers and tracers. The cultural emphasis on patient choice allows for diverse treatment options. Public hospitals and private clinics compete on quality and service. The market is characterized by high adoption of innovative diagnostics. Government initiatives support cancer prevention and early detection. The integration of care networks improves coordination. France's strong pharmaceutical industry contributes to local innovation. Regulatory processes are efficient, facilitating market entry. The focus on aesthetic and functional outcomes drives demand for advanced imaging techniques. The market remains dynamic with steady growth driven by technological adoption and high patient expectations.
COMPETITIVE LANDSCAPE
The competition in the Europe Nuclear Imaging Market is characterized by a mix of established multinational corporations and specialized niche players striving for innovation and market presence. Leading companies compete primarily on technological superiority clinical evidence and integrated solution offerings rather than price alone due to the capital intensive nature of the sector. The market sees intense rivalry in the hybrid imaging segment where continuous research and development drive differentiation. Companies invest significantly in head to head clinical trials to demonstrate superiority or non inferiority against existing standards of care. Regulatory hurdles create barriers to entry ensuring that only high quality products reach the market but also slowing down the introduction of new competitors. Strategic acquisitions are common as firms seek to fill gaps in their pipelines particularly in radiopharmaceuticals and software analytics. The presence of strong local manufacturers in countries like Germany adds to the competitive dynamics offering regionally tailored solutions. Customer loyalty is built through robust training programs and after sales support for healthcare providers. The shift towards value based healthcare encourages competition based on overall patient outcomes and cost effectiveness. Emerging technologies such as total body PET scanners attract new entrants increasing the pace of innovation. This dynamic environment fosters continuous improvement in care standards benefiting patients across Europe.
KEY MARKET PLAYERS
A few of the prominent companies operating in the European nuclear imaging market include
- Mallinckrodt plc
- Siemens Medical Solutions
- Hitachi Medical Corporation
- Medtronic Inc.
- General Electric Co. (Healthcare Division)
- IBA Group
- Positron Corporation
- Philips Medical Systems
- Naviscan
- Toshiba Medical Systems Corporation
- Carestream Health
- Lantheus Medical Imaging Inc.
- Cardinal Health Inc.
- Bayer AG
Top Players in the Europe Nuclear Imaging Market
Siemens Healthineers AG
Siemens Healthineers AG is a global leader in medical technology with a strong presence in the Europe Nuclear Imaging Market through its advanced hybrid imaging systems. The company focuses on developing digital PET CT and SPECT CT solutions that integrate artificial intelligence to enhance diagnostic precision and workflow efficiency. Recent initiatives include launching next generation detectors that offer higher sensitivity and reduced scan times for patients. Siemens actively collaborates with research institutions to validate new clinical applications and tracers. The company invests heavily in service infrastructure ensuring reliable support for healthcare providers across Europe. By prioritizing innovation and user centric design Siemens strengthens its reputation as a trusted partner in molecular imaging. Its commitment to sustainability drives the development of energy efficient systems. This strategic focus allows the company to address evolving clinical needs and support healthcare systems in delivering high quality care. Siemens remains dedicated to advancing precision medicine through technological excellence and comprehensive solutions tailored to the specific requirements of nuclear medicine departments across European healthcare facilities.
GE Healthcare
GE Healthcare is a prominent player in the European market specializing in nuclear imaging hardware and radiopharmaceutical supply chains. The company is renowned for its broad portfolio of PET and SPECT systems designed for oncology cardiology and neurology applications. GE Healthcare emphasizes integrated solutions that combine imaging devices with software analytics and tracer chemistry. Recent actions include expanding its theranostics capabilities through strategic partnerships with pharmaceutical companies. The company engages in extensive educational programs for technologists and physicians to promote best practices in nuclear medicine. GE Healthcare also focuses on digital transformation integrating cloud based tools for remote monitoring and data management. Its strong distribution network ensures wide availability of products in both public and private healthcare settings. By listening to clinical feedback the company continuously refines its offerings to better serve the nuclear medicine community. GE Healthcare stands out for its dedication to improving patient outcomes through innovative science and accessible technology that enhances the quality of diagnostic services across Europe.
Philips Healthcare
Philips Healthcare is a key contributor to the Europe Nuclear Imaging Market with a comprehensive range of digital PET CT systems and smart imaging platforms. The company leverages its expertise in image reconstruction algorithms and artificial intelligence to create solutions that optimize clinical workflow and image quality. Philips recently expanded its portfolio with advanced quantitative tools that support personalized treatment planning in oncology. The company partners with healthcare providers to implement value based care models that improve efficiency and patient satisfaction. Philips invests in research and development to discover new applications for nuclear imaging in neurological and cardiovascular diseases. Its global reach and local presence in European markets allow for tailored solutions that address regional healthcare needs. The company is committed to sustainability and social responsibility ensuring ethical manufacturing practices. Philips also supports patient advocacy groups raising awareness about early detection and advanced diagnostics. Through innovation and collaboration Philips continues to set high standards in nuclear imaging providing reliable and effective solutions for healthcare professionals and patients alike in the European market landscape.
Top Strategies Used by Key Market Participants
Key players in the Europe Nuclear Imaging Market employ several strategic approaches to maintain competitiveness and drive growth. Product innovation remains a primary strategy with companies investing heavily in research and development to create advanced digital detectors and artificial intelligence driven software. These innovations focus on improving image resolution reducing radiation dose and accelerating scan times which are critical concerns for patient safety and throughput. Strategic partnerships and collaborations with pharmaceutical firms facilitate the co development of theranostic agents and companion diagnostics enabling personalized treatment decisions. Companies also prioritize regulatory compliance navigating the stringent requirements of the European Medicines Agency to ensure timely market access. Expansion of service networks enhances customer loyalty through predictive maintenance and remote support. Digital health integration is another major strategy with firms developing cloud based platforms for data sharing and collaborative diagnosis. This approach reduces hospital burden and improves clinical decision making. Educational initiatives targeting healthcare professionals help promote awareness of new technologies and guidelines. Sustainability efforts are increasingly important with companies adopting eco friendly manufacturing processes to meet environmental standards. These combined strategies enable key participants to address evolving market demands and strengthen their position in the competitive European landscape.
MARKET SEGMENTATION
This research report on the European Nuclear Imaging Market has been segmented & sub-segmented into the following categories:
By Diagnostic Technologies
- Standalone PET Nuclear Imaging
- Standalone SPECT Nuclear Imaging
- Hybrid Nuclear Imaging
By Application
- Oncology
- Cardiology
- Neurology
- Others
By End-User
- Hospitals
- Diagnostic Centers
- Research Centers
By Country
- UK
- France
- Spain
- Germany
- Italy
- Russia
- Sweden
- Denmark
- Switzerland
- Netherlands
- Turkey
- Czech Republic
- Rest of Europe