- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$1.79 BnMarket Estimate, 2026
$2.06 BnMarket Forecast, 2034
$6.32 BnCAGR, 2026–2034
15.02%Europe Single-Use Medical Device Reprocessing Market Size, Trends, and Forecast (2026–2034)
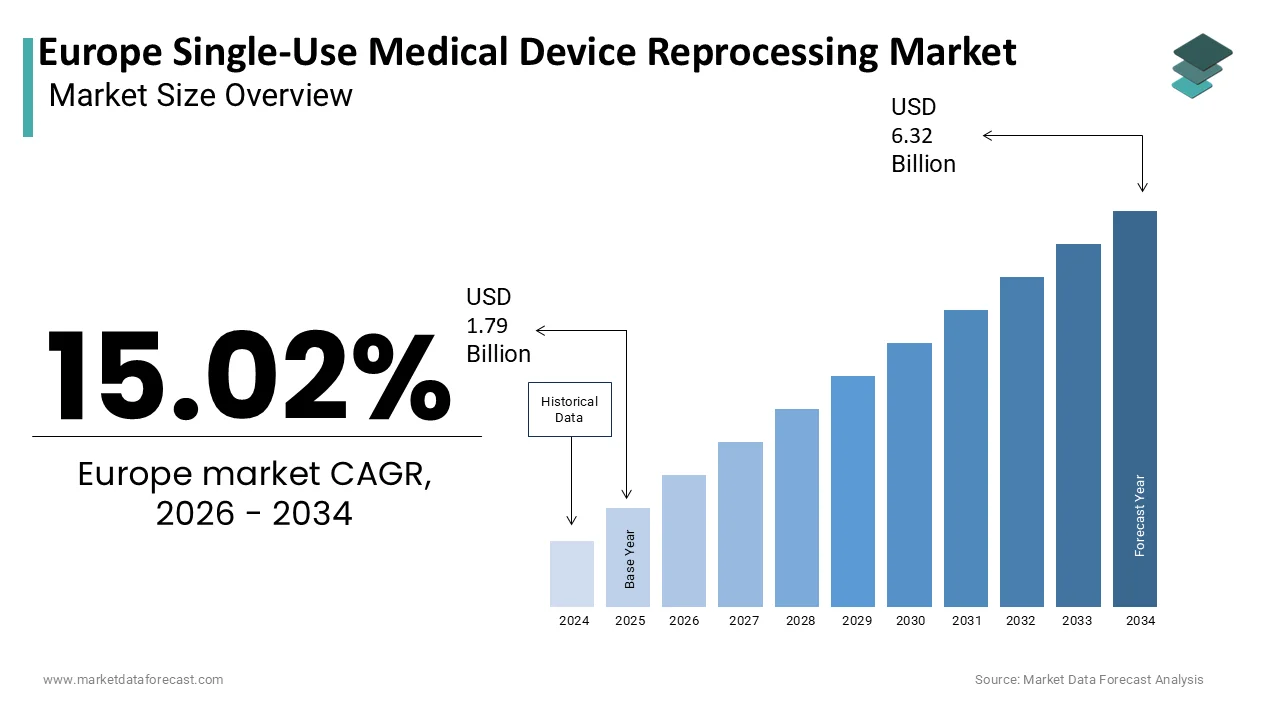
The Europe Single-Use Medical Device Reprocessing Market size was valued at USD 1.79 billion in 2025, stands at USD 2.06 billion in 2026, and is anticipated to reach USD 6.32 billion by 2034, expanding at a compound annual growth rate (CAGR) of 15.02% during the forecast period from 2026 to 2034. Growth is heavily driven by stringent EU Medical Device Regulation compliance frameworks, persistent healthcare budget constraints across public health systems, and aggressive European Union environmental sustainability mandates accelerating circular economy adoption.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 1.79 Billion
- 2026 Current Valuation: USD 2.06 Billion
- 2034 Forecast Valuation: USD 6.32 Billion
- Forecast Period: 2026–2034
- Compound Annual Growth Rate (CAGR): 15.02% (2026–2034)
- Dominant Class I Device Segment: Pulse Oximeter Sensors
- Fastest-Growing Class I Segment: Sequential Compression Sleeves (16.1% CAGR)
- Dominant Class II Device Segment: Electrophysiological Cardiac Catheters
- Fastest-Growing Class II Segment: Laparoscopic Graspers (18.2% CAGR)
- Dominant End User Segment: Hospitals
- Fastest-Growing End User Segment: Ambulatory Surgery Centres (21.7% CAGR)
- Leading Country Market: Germany (26.5% share in 2025)
Core Market Drivers
- Healthcare Budget Pressures: Austerity frameworks force hospital procurement departments to reduce consumable expenditures while maintaining surgical throughput.
- Environmental Sustainability Mandates: European Green Deal policies and national circular economy regulations make reprocessing essential for public tender eligibility.
Primary Market Restraints & Challenges
- OEM Opposition & Compliance Costs: Strategic resistance from original manufacturers through proprietary designs, alongside high MDR conformity investment barriers.
- Regulatory Fragmentation: Cross-border divergence in national MDR implementations creating operational complexity for pan-European operators.
Europe Single-Use Medical Device Reprocessing Market Segmentation Breakdown
| Segment Category | Largest / Dominant Segment | Fastest-Growing / Key Highlight |
|---|---|---|
| By Class I Devices | Pulse Oximeter Sensors | Sequential Compression Sleeves (16.1% CAGR) |
| By Class II Devices | Electrophysiological Cardiac Catheters | Laparoscopic Graspers (18.2% CAGR) |
| By End User | Hospitals | Ambulatory Surgery Centres (21.7% CAGR) |
| By Country | Germany (26.5% share) | United Kingdom, France, and Italy |
Major Industry Players Profiled
Key corporations shaping the European single-use medical device reprocessing market include Hygia, Centurion Medical Products Corporation, Medline Renewal, Midwest Reprocessing Center, NEscientific, ReNu Medical, SterilMed, Stryker Sustainability Solutions, Inc., SureTek Medical, and Vanguard AG.
Europe Single-Use Medical Device Reprocessing Market Size
The Europe Single-Use Medical Device Reprocessing Market is projected to grow from USD 1.79 billion in 2025 to USD 2.06 billion in 2026 and reach USD 6.32 billion by 2034, registering a CAGR of 15.02% from 2026 to 2034.
Single-use medical device reprocessing is the cleaning, testing, fixing, and cleaning again of a tool meant for one patient. Facilities do this to make the tool safe to use a second time on another patient. This domain operates under the stringent framework of the European Union Medical Device Regulation, which classifies reprocessed single-use devices as new devices requiring full conformity assessment and CE marking before recirculation. According to Eurostat, current healthcare expenditure in the European Union reached 10.0% of gross domestic product (GDP) in 2023, reflecting a long-term upward trend in healthcare spending per inhabitant across all member states since 2014. As per the European Commission, the European Union generates approximately 6 million tonnes of medical waste annually, with new regulatory proposals targeting a 25% waste reduction by 2030 across member states. The definition of this market has evolved from informal hospital-based practices to a highly formalised third-party reprocessing industry governed by harmonised technical standards and post-market surveillance requirements. Reprocessors must now demonstrate equivalence to original manufacturer specifications through rigorous validation protocols covering cleaning, disinfection, sterilisation, and functional testing. This regulatory maturation distinguishes the European landscape from other global regions by embedding reprocessing within the same legal and quality framework as virgin device manufacturing, thereby establishing it as a legitimate component of sustainable healthcare delivery rather than merely a cost containment measure.
MARKET DRIVERS
Healthcare Budget Constraints Necessitate Cost Optimisation Strategies
Persistent financial pressures within regional public healthcare systems accelerate the growth of the European single-use medical device reprocessing market. This serves as the primary economic factor for adopting reprocessed single-use medical devices as viable alternatives to virgin products. According to the Organisation for Economic Co-operation and Development, health spending per capita across EU member states increased by an average annual rate of 1.6% between 2019 and 2022, with growth heavily influenced by post-pandemic economic stabilisation and inflation adjustments. National health services in countries operate under strict austerity frameworks where procurement departments face mandates to reduce consumable expenditures annually without reducing procedural volumes. Reprocessed devices typically offer price reductions compared to original equipment manufacturer pricing, enabling hospitals to maintain surgical throughput despite constrained budgets. As per the Association of Medical Device Reprocessors, the integration of regulated medical device remanufacturing into hospital procurement systems reduces supply chain expenses while yielding substantial financial returns for national healthcare providers. These systemic fiscal realities transform reprocessing from an optional sustainability initiative into a mandatory operational strategy for financially stressed institutions seeking to balance clinical demand with limited public funding allocations across ageing populations requiring increasing medical interventions.
Environmental Sustainability Mandates Accelerate Circular Economy Adoption
European Union environmental legislation and institutional sustainability commitments further boost the expansion of the European single-use medical device reprocessing market. These mandates create powerful regulatory tailwinds, driving healthcare facilities toward reprocessed device adoption as part of broader decarbonization strategies. According to the European Commission, the Waste Framework Directive sets general and specific recycling provisions across member states to drive circular transformations and material efficiency across manufacturing supply chains. As per the National Health Service, the NHS Net Zero Supplier Roadmap proportionately extends Carbon Reduction Plan mandates to cover all new procurements starting in April 2024. According to the French Ministry of Ecological Transition, France's circular economy rules restrict the use of various short-lived commercial plastic goods to enforce nationwide material conservation and waste avoidance targets. These policy frameworks convert environmental objectives into enforceable procurement criteria, making reprocessing compliance essential for maintaining eligibility for public tenders and demonstrating alignment with European Green Deal principles governing sustainable public spending.
MARKET RESTRAINTS
Original Manufacturer Opposition Creates Supply Chain Barriers
Strategic resistance from original equipment manufacturers significantly constrains the expansion of the European single-use medical device reprocessing market. This occurs through contractual restrictions, intellectual property enforcement, and deliberate design modifications that prevent third-party reprocessing. According to the Association of Medical Device Reprocessors, original equipment manufacturers employ aggressive contracting tactics and ambiguity to restrict hospital procurement of third-party reprocessed single-use medical devices. Original manufacturers frequently update device designs with proprietary connectors, embedded RFID tags, or software locks specifically engineered to prevent compatibility with third-party reprocessing validation protocols, effectively obsolescing existing reprocessor investments. As per the European Commission, the enforcement of Article 17 under Regulation (EU) 2017/745 establishes strict safety and quality standards for the regional reprocessing of single-use medical devices across member states. These coordinated opposition strategies exploit information asymmetries and contractual leverage to maintain pricing power, limiting actual market penetration well below theoretical potential established by a favourable regulatory environment and demonstrated clinical equivalence.
Regulatory Compliance Costs Create High Entry Barriers
Achieving Medical Device Regulation conformity for reprocessed single-use devices requires substantial financial and technical resources, which inhibits the growth of the European single-use medical device reprocessing market. Consequently, market participation is restricted to well-capitalised operators capable of enduring multi-year certification processes. As per the European Medicines Agency, the agency manages distinct scientific consultations for high-risk medical device categories to evaluate data on auxiliary substances and ensure public health protection. According to the European Parliament, transitional timelines under the Medical Device Regulation protect patient access to vital care categories by providing essential extensions for conformity assessments. Post-market surveillance obligations require continuous investment in vigilance reporting, trend analysis, and periodic safety update reports, generating recurring high annual costs per certified product line. These escalating compliance thresholds create an oligopolistic market structure where only large multinational reprocessors can achieve sufficient scale to amortise regulatory investments, limiting competitive dynamics and innovation diversity despite growing demand signals from healthcare purchasers.
MARKET OPPORTUNITIES
Expansion Into Complex Surgical Device Categories
Technological advancements in reprocessing validation methodologies unlock potential for the European single-use medical device reprocessing market. These developments enable market expansion beyond traditional low-risk devices into high-value, complex surgical instruments previously considered unsuitable for safe reuse. According to the British Standards Institution, international standards specify structural verification constraints for information provided by manufacturers to confirm proper processing across diverse clinical devices. As per the Association of Medical Device Reprocessors, independent life cycle assessment reports demonstrate that utilising remanufactured laparoscopic and energy-driven tools helps public medical systems safely lower material acquisition costs and greenhouse gas footprints. Cardiovascular electrophysiology mapping catheters with integrated sensors represent a particularly attractive opportunity segment. Robotic surgery instrument reprocessing emerges as the next. These technological breakthroughs expand the total addressable market beyond commodity devices into premium segments where margin structures support sustainable business models despite higher validation complexity and regulatory scrutiny requirements.
Public Procurement Policy Alignment With Circular Economy Goals
Evolving regional public procurement frameworks increasingly mandate circular economy criteria, which is expected to drive the expansion of the European single-use medical device reprocessing market. This creates structured demand channels for reprocessed medical devices through government purchasing power. According to the European Commission, new updates under the Ecodesign for Sustainable Products Regulation establish mandatory green public procurement criteria that integrate environmental award weights within standard bidding selections. As per the German Federal Ministry of Health, legal updates across the domestic health infrastructure regulate the quality and distribution protocols required for hospital-level single-use device management. These policy mechanisms convert abstract sustainability commitments into enforceable purchasing requirements, creating predictable demand streams independent of individual hospital budget cycles and establishing reprocessing as the default option rather than an exception in publicly funded healthcare systems.
MARKET CHALLENGES
Cross-Border Regulatory Fragmentation Despite Harmonisation Efforts
Persistent divergence in the national implementation of the Medical Device Regulation holds back the growth of the European single-use medical device reprocessing market. This creates operational complexity for reprocessors seeking pan-European market access despite a nominally harmonised regulatory framework. According to the European Commission, Regulation (EU) 2017/745 permits individual member states to regulate or completely opt out of the reprocessing of single-use medical devices within their domestic health borders. As per the French National Agency for Medicines and Health Products Safety, domestic health institutions must fully comply with state-level protocols to record and monitor structural metrics for single-use diagnostic assets. Belgium and the Netherlands interpret post-market surveillance frequency requirements differently, forcing reprocessors to maintain parallel vigilance systems, increasing compliance costs for cross-border operators. These implementation variations undermine single market principles, fragmenting addressable volume and preventing economies of scale necessary to justify regulatory investments, particularly for smaller device categories where national market size alone cannot support compliance costs.
Clinical Acceptance and Liability Perception Gaps
Enduring scepticism among clinicians and hospital risk managers regarding reprocessed device safety creates adoption barriers independent of regulatory approval status or demonstrated clinical equivalence, which in turn limits the expansion of the Europe single use medical device reprocessing market. As per the European Society of Cardiology, clinical guidelines for cardiovascular medicine emphasise rigorous safety data collection across electrophysiology laboratories to track long-term health outcomes. According to the European Commission, the execution of Article 17 safety clauses transfers full legal manufacturer accountability to external entities that choose to remanufacture commercial clinical inventory. Professional society guidelines in orthopaedics and neurosurgery continue recommending virgin devices as standard of care despite the absence of comparative safety data, disadvantaging reprocessed alternatives in clinical decision-making. These perceptual barriers require sustained education efforts and transparent outcome reporting to overcome, representing a human factor challenge more resistant to resolution than technical or regulatory obstacles limiting market realisation despite a favourable policy environment.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Class I Devices, Class II Devices, End User, and Region. |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered | UK, France, Spain, Germany, Italy |
| Market Leaders Profiled | Hygia, Centurion Medical Products Corporation |
SEGMENTAL ANALYSIS
By Class I Devices Insights
The pulse oximeter sensors segment dominated the Europe single-use medical device reprocessing market and accounted for a substantial share in 2025. This dominance of the segment was driven by its ubiquitous application in perioperative care, emergency medicine, and intensive care units, where continuous monitoring is mandatory. According to Eurostat, hospital discharge data highlight that millions of inpatients undergo surgical procedures across EU member states annually, sustaining a continuous demand for baseline monitoring infrastructure. According to the European Society of Anaesthesiology and Intensive Care, standard clinical guidelines for post-anaesthesia care dictate that each patient must be kept under continuous clinical observation with physiological parameters measured at regular intervals. Unlike sequential compression sleeves or tourniquet cuffs, which are procedure-specific, pulse oximeters serve diagnostic, therapeutic, and monitoring functions across virtually every clinical department, maximizing the addressable patient population. This universal applicability combined with low unit cost and simple reprocessing protocols creates high-throughput economics enabling third-party reprocessors to achieve profitable scale even at significant discounts to original manufacturer pricing, sustaining segment leadership through volume-driven business models.
Mature technical standards and extensive clinical evidence base for pulse oximeter sensor reprocessing minimise perceived risk and accelerate procurement approval compared to newer Class I device categories. According to the British Standards Institution, BS EN ISO 80601-2-61 establishes particular requirements for the basic safety and essential performance of pulse oximeter equipment used in medical environments. According to the German Federal Institute for Drugs and Medical Devices, medical institutions are legally permitted to utilise validated reprocessed medical devices provided they conform to stringent national risk assessments and conformity assessment procedures. Regulatory familiarity reduces legal review timelines from an average of 6 months for novel devices to 4 weeks for sensors leveraging existing precedent. This accumulated institutional knowledge creates a self-reinforcing adoption cycle where early adopter experiences validate safety assumptions for subsequent purchasers, lowering decision-making friction and cementing segment dominance through path dependency rather than superior economic value alone.
The sequential compression sleeves segment is estimated to register the fastest CAGR of 16.1% from 2026 to 2034 due to intensified venous thromboembolism prophylaxis protocols and sustainability-focused procurement policies. According to the European Centre for Disease Prevention and Control, healthcare-associated infections and related complications present persistent patient safety challenges in acute care hospitals, driving institutional focus on standard prophylaxis protocols. According to the National Institute for Health and Care Excellence, guideline NG89 provides evidence-based recommendations on reducing the risk of venous thromboembolism in patients admitted to hospital, including the appropriate deployment of mechanical prophylaxis. Ageing demographics amplify demand. These converging clinical mandates, demographic trends, and favourable reimbursement create structural growth tailwinds exceeding broader market averages, positioning sequential compression sleeves as the primary Class I expansion driver through the forecast period.
Enhanced recovery after surgery programs increasingly incorporate sequential compression sleeves as standard care elements, creating bundled demand streams that favour reprocessed devices for cost efficiency. According to the European Enhanced Recovery After Surgery Society, perioperative pathways for major abdominal, orthopaedic, and gynaecological interventions demonstrate improved patient recovery when standardised clinical components are uniformly adopted. According to the Dutch Healthcare Authority, quality indicator sets and hospital financing structures are periodically adjusted to align healthcare provider performance with national safety and clinical quality benchmarks. Ambulatory surgery centre expansion further accelerates adoption, as same-day discharge protocols require patient education on home use, creating a secondary market for reprocessed sleeves distributed through outpatient pharmacies. This integration into standardised care pathways transforms sleeves from optional adjuncts into mandatory consumables with demand elasticity near zero, ensuring sustained growth velocity independent of budget cycles or clinician variability.
By Class II Devices Insights
In 2025, the electrophysiological cardiac catheters segment held the majority share in the European single-use medical device reprocessing market, because of exceptional unit economics, where reprocessing savings substantially outweigh validation costs and perceived risks. According to the European Heart Rhythm Association, specialised mapping and ablation catheter equipment requires substantial hospital infrastructure and capital investment across high-volume electrophysiology centres. As per the Spanish Agency of Medicines and Medical Devices, post-market surveillance systems systematically trace medical device performance and vigilance reporting to maintain European conformity and patient safety standards. Unlike lower-cost Class II devices where savings fail to justify regulatory investment, electrophysiology catheters offer sufficient margin structure to support sophisticated reprocessing infrastructure and ongoing clinical validation studies. This economic imperative, combined with demonstrated safety equivalence, creates a defensible market position resistant to competitive pressure from original manufacturers attempting to recapture volume through modest price reductions.
Rising atrial fibrillation prevalence across ageing European populations drives sustained procedural volume growth, creating an expanding demand foundation for reprocessed electrophysiology catheters. According to the European Society of Cardiology, clinical survey registries emphasise that the healthcare burden of atrial fibrillation is expanding across European populations, requiring comprehensive long-term care management. According to the European Heart Rhythm Association, hospital procedure volumes for cardiovascular rhythm interventions have shown consistent growth, leading to expanded deployment of clinical staff and therapeutic infrastructure. Technological advances in pulmonary vein isolation techniques reduced procedure times but increased catheter consumption per case as multi-electrode mapping systems require dedicated diagnostic and therapeutic catheters. This epidemiological expansion ensures reprocessed catheter demand grows independently of broader surgical volume trends, creating a specialised growth corridor insulated from general market cyclicality and supporting sustained segment leadership through demographic inevitability rather than temporary policy incentives.
The laparoscopic graspers segment is anticipated to witness the fastest CAGR of 18.2% during the forecast period, owing to accelerating minimally invasive surgery adoption across general, gynecologic, and urologic specialities. According to the European Association for Endoscopic Surgery, clinical consensus recommendations advocate for the optimised deployment of minimally invasive techniques in abdominal surgery to improve patient recovery pathways. According to Surgical Endoscopy, surgical instrument utilisation audits highlight that standardised operating room workflows reduce equipment wastage and streamline standard mechanical grasper preparation. Robotic surgery platform expansion further amplifies demand as da Vinci and Hugo systems require proprietary grasping instruments, with replacement costs making reprocessing economically compelling despite technical complexity. This convergence of procedural migration, technological platform dependencies, and validated cost savings creates a growth trajectory significantly exceeding mature electrophysiology catheter segment positioning laparoscopic graspers as primary Class II expansion engine through forecast horizon.
Maturation of laparoscopic instrument set configurations facilitates streamlined reprocessing logistics, reducing turnaround times and inventory costs compared to heterogeneous device categories. According to Zentralblatt für Chirurgie, medical device optimisation programs in large academic medical centres focus on administrative and procurement adjustments to handle rising instrument volumes. According to the Austrian Society for Sterile Supply Services, harmonised quality management frameworks govern technical guidelines for sterilising and maintaining high-quality surgical instrumentation across sterile processing facilities. The operational standardisation transforms laparoscopic graspers from custom reprocessing challenges into commoditised service offerings with predictable economics, encouraging adoption among hospitals previously deterred by logistical complexity. Network effects emerge as shared best practices reduce learning curves, accelerating diffusion beyond early adopter institutions into mainstream surgical practice.
By End User Insights
The hospitals segment led the European single-use medical device reprocessing market and captured a significant share in 2025. This concentration reflects the fundamental reality that complex surgical interventions requiring expensive single-use devices occur predominantly in acute care settings with operating theatres, catheterisation labs, and intensive care units. According to Eurostat, hospital infrastructure statistics indicate that acute care beds and inpatient facilities are distributed across all EU member states to handle varying regional surgical demands. Teaching hospital status correlates strongly with reprocessing adoption, as academic centres possess research infrastructure for conducting internal validation studies and clinical staff familiar with evidence-based evaluation of alternative devices. Emergency departments and trauma centres generate additional non-elective demand unaffected by budget-driven procedure cancellations, ensuring stable baseline consumption. This structural concentration of high-value procedural activity makes hospitals irreplaceable market anchors regardless of ambulatory sector growth trajectories.
Existing hospital sterile services departments provide foundational infrastructure that reduces incremental investment required for reprocessing program implementation compared to standalone facilities. According to the European Committee for Standardisation, EN ISO 13485 specifies comprehensive quality management system criteria for organisations involved in the life-cycle of medical devices. According to the French Ministry of Health and Prevention, sterilisation practices in healthcare facilities are strictly governed by public health regulations to minimise infectious risks during surgical interventions. Staff competency in decontamination, sterilisation, and quality assurance transfers directly to reprocessing workflows, minimising training investments and change management resistance. This infrastructure leverage creates a natural competitive advantage for hospital end users versus ambulatory centres lacking equivalent capabilities, reinforcing segment dominance through operational readiness rather than volume alone.
The ambulatory surgery centres segment is on the rise and is expected to be the fastest-growing segment in the market, witnessing a CAGR of 21.7% between 2026 and 2034. This swift expansion of the segment is fuelled by intense margin pressures and specialised procedural focus aligning perfectly with reprocessing economics. According to the European Association for Ambulatory Surgery, the transition of surgical procedures from traditional inpatient settings to day surgery clinics is expanding across European healthcare networks to increase throughput. According to Eurostat, European healthcare provider expenditure trends reflect varying operational margins across regional clinical facilities due to differing national reimbursement rates. Payer contracts increasingly tie reimbursement to value metrics,s rewarding ASCs demonstrating sustainable practices through bonus payments or preferred network status. Unlike hospitals balancing diverse stakeholder interests, ASC physician owners make rapid procurement decisions aligned with direct financial incentives, accelerating adoption cycles. This combination of economic urgency, operational focus, and decision-making agility positions ASCs as a primary growth vector despite smaller absolute market share.
ASC specialisation in discrete procedure categories enables optimised reprocessing workflows that overcome traditional barriers related to device heterogeneity and low-volume inefficiency. According to the British Association of Day Surgery, clinical benchmarking criteria encourage the optimisation of specialised surgical sets for short-stay procedures to reduce operational complexities. According to the Dutch Healthcare Authority, specialised clinics and ambulatory centres must adhere to universal national quality and safety frameworks regarding medical device traceability and patient safety. Focused device portfolios enable deeper staff expertise, reducing error rates and improving reprocessing consistency, building confidence among surgeons sceptical of reused instruments. This operational alignment between ASC business model and reprocessing requirements creates adoption velocity exceeding hospitals despite regulatory frameworks originally designed for larger institutions.
COUNTRY LEVEL ANALYSIS
Germany Single Use Medical Device Reprocessing Market Analysis
Germany was the top performer in the European single-use medical device reprocessing market, securing a share of 26.5% in 2025. This prominence of the German market was propelled by the world’s most mature regulatory framework, established under the Medizinprodukte-Betreiberverordnung, which provided legal certainty for reprocessing decades before EU Medical Device Regulation harmonisation, enabling domestic industry development and clinical acceptance. According to the German Federal Joint Committee, medical device regulations for inpatient facilities allow for bundled case-based reimbursement through the national Diagnosis-Related Groups system rather than establishing isolated guaranteed payment pipelines for specific product variations. According to the GKV-Spitzenverband, statutory health insurance funding prioritises standard quality, medical necessity, and structural price negotiation updates across public healthcare providers to secure patient care. Domestic reprocessors including Vanguard AG and Resterile GmbH benefit from first-mover advantages and established relationships with acute care hospitals, creating network effects difficult for foreign entrants to replicate. Strong engineering tradition supports sophisticated validation capabilities meeting stringent TÜV certification requirements. This confluence of regulatory maturity, payer support, industrial capacity and clinical integration creates a self-reinforcing ecosystem maintaining German market leadership despite harmonisation efforts elsewhere.
United Kingdom Single Use Medical Device Reprocessing Market Analysis
United Kingdom follows closely behind in the European single-use medical device reprocessing market because of centralised NHS procurement power and aggressive net-zero sustainability mandates driving adoption. According to the National Institute for Health and Care Excellence, technology appraisal TA892 provides evidence-based guidance on the clinical effectiveness and appropriate use of mosunetuzumab for treating relapsed or refractory follicular lymphoma. As per the Department of Health and Social Care, national net-zero strategies encourage individual NHS trusts to lower greenhouse gas emissions through localised clinical model optimisation and waste management practices. Post-Brexit regulatory divergence allows the UK MHRA to establish independent reprocessing classifications, potentially accelerating approvals versus EU MDR timelines, creating a competitive advantage for domestic reprocessors. Centralised procurement through NHS Supply Chain enables volume aggregation supporting dedicated reprocessing contracts unachievable in fragmented systems. This combination of policy enforcement, clinical validation and centralised purchasing creates distinctive UK market dynamics separate from continental European patterns.
France Single Use Medical Device Reprocessing Market Analysis
France holds a significant share of the European single-use medical device reprocessing market due to strong state direction through anti-waste legislation and public hospital modernisation initiatives. According to the French National Authority for Health, evaluation metrics for surgical devices establish safety performance criteria and clinical utility scores required for public health coverage and medical resource optimisation. As per the French Hospital Federation, institutional assessments highlight that public healthcare establishments require significant structural transition funding to implement comprehensive medical equipment circular economy frameworks. Domestic champion SteriCycle benefits from government-backed innovation funding and preferential access to public hospital networks supporting national industrial policy objectives. Regional health agencies coordinate cross-hospital device collection, enabling volume thresholds for economically viable reprocessing in rural areas. This state-led approach combining regulatory mandates, financial incentives and industrial support creates a distinctive French market trajectory driven by top-down policy implementation rather than bottom-up economic optimisation.
Italy Single Use Medical Device Reprocessing Market Analysis
Italy grew steadily in the European single-use medical device reprocessing market owing to regional healthcare autonomy, creating heterogeneous adoption patterns across northern and southern regions. According to regional health guidelines, Lombardy and Emilia-Romagna healthcare networks enforce strict localised sanitation and sterilisation compliance audits to optimise hospital material management and safeguard surgical workflows. According to the Italian National Institute of Health, clinical evidence databases and technology assessments provide scientific evaluation models to assist regional networks in optimising cardiovascular care delivery systems. National recovery fund allocations include circular economy healthcare projects targeting southern catch-up. Fragmented regional procurement prevents national volume aggregation, limiting negotiating power versus multinational original manufacturers. This north-south divide creates a dual-speed market requiring differentiated commercial strategies and highlighting the role of interregional solidarity mechanisms in achieving national policy objectives.
Spain Single Use Medical Device Reprocessing Market Analysis
Spain is another key player in the regional market. However, its growth is constrained by austerity legacies but accelerated by recent sustainability legislation and professional society endorsements. According to the Ministry of Health official bulletin, Royal Decree 192/2023 establishes updated national regulatory frameworks for the manufacturing, conformity assessment, and clinical evaluation of medical devices inside Spain. As per the Spanish Society of Cardiology, evidence-based recommendations highlight that electrophysiology centres must adhere to standardised safety certifications and optimal structural specifications for cardiac ablation procedures. Budget constraints persist, with Andalusia and Extremadura regions still operating under fiscal recovery plans limiting capital investment despite a favourable policy environment. Private hospital groups Quirónsalud and Vithas lead adoption in elective surgery segments where margin sensitivity exceeds the public sector. This tension between progressive policy and constrained finances creates an uneven adoption landscape requiring flexible financing models and phased implementation approaches tailored to regional fiscal capacity.
COMPETITIVE LANDSCAPE
Competition within the European single-use medical device reprocessing market exhibits moderate intensity, characterized by an oligopolistic structure among multinational reprocessors alongside specialized regional operators and original manufacturer programs. Barriers to entry remain substantial due to Medical Device Regulation conformity costs, notified body capacity constraints, and clinical validation requirements, limiting new entrant threats despite favorable policy tailwinds. Incumbents differentiate through regulatory expertise, geographic coverage, clinical evidence portfolios,s and digital capabilities rather than price competition alone,ne preserving margins in complex device categories. Original manufacturer opposition through contractual restrictions, design modifications, and patent litigation creates asymmetric competitive dynamics favoring vertically integrated players with IP ownership. National market fragmentation prevents true pan-European competition, requiring country-specific strategies and local presence, increasing operational complexity versus consolidated markets. Customer concentration in public hospital systems enhances buyer leverage,e enabling aggressive tender negotiations favoring vendors offering comprehensive solutions and sustainability credentials. Competitive intensity varies significantly by device category, with electrophysiology catheters experiencing feature-based rivalry, while commodity Class I devices face increasing commoditization and margin compression. This bifurcated landscape rewards companies balancing regulatory excellence,e operational scale, le and clinical trust while punishing those unable to adapt to a harmonized yet locally implemented European regulatory framework reshaping competitive dynamics through 2030.
KEY MARKET PLAYERS
Some of the companies that are playing a dominating role in the Europe Single-Use Medical Device Reprocessing Market include:
- Hygia
- Centurion Medical Products Corporation
- Medline Renewal
- Midwest Reprocessing Center
- NEscientific
- ReNu Medical
- SterilMed
- Stryker Sustainability Solutions, Inc.
- SureTek Medical
- Vanguard AG
TOP LEADING PLAYERS IN THE MARKET
- Vanguard AG maintains significant influence across the European single-use medical device reprocessing landscape through comprehensive third-party services covering electrophysiology catheters, laparoscopic instruments,s and ultrasound probes. The company contributes extensively by operating CE-certified reprocessing facilities in Germany, France,e and Spain, serving over 800 hospitals with validated devices meeting Medical Device Regulation requirements. Its investment in digital traceability platforms enables real-time device tracking and post-market surveillance compliance,ce enhancing customer confidence. Strategic partnerships with regional distributors extend geographic reach into underserved Eastern European markets. Clinical validation studies published in peer-reviewed journals document safety equivalence, supporting procurement approvals. These initiatives reinforce operational reliability and regulatory leadership without relying on market share metrics to demonstrate sustained competitive advantage throughout diverse European healthcare systems navigating complex compliance environments.
- Steris plc plays a pivotal role in the European reprocessing ecosystem through integrated sterile services and device reprocessing solutions leveraging existing hospital infrastructure relationships. The company contributes regionally by offering bundled reprocessing and sterilization management contracts,s reducing administrative burden for healthcare facilities transitioning from virgin to reprocessed devices. Educational programs targeting perioperative staff address clinical acceptance barriers through hands-on training and safety data transparency. Supply chain integration with existing Steris service networks creates cross-selling opportunities and customer retention advantages. These platform-centric strategies differentiate offerings from standalone reprocessors while creating switching costs through procedural integration, strengthening long-term positioning across European markets.
- Stryker Corporation has established a substantial presence in European reprocessing through original manufacturer reprocessing programs for proprietary orthopedic and surgical devices, maintaining control over the device lifecycle. The company contributes uniquely by offering factory-certified reprocessing for Stryker-branded instruments, ensuring compatibility and performance guarantees that third-party reprocessors cannot match for patented designs. Regulatory expertise from original manufacturing accelerates CE marking for reprocessed variants, leveraging existing technical documentation. Sustainability reporting integrates reprocessed device carbon savings into corporate ESG disclosures, aligning with customer environmental targets. This vertical integration strategy captures value across the entire device lifecycle while defending intellectual property against third-party competition, creating a defensible market position distinct from independent reprocessor business models.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the European single-use medical device reprocessing market employ multifaceted strategic approaches to navigate complex regulatory environments and heterogeneous national healthcare systems. Regulatory excellence serves as a foundational strategy, with companies investing heavily in Medical Device Regulation conformity assessment,t notified body relationships, and post-market surveillance systems to maintain CE marking validity across evolving requirements. Geographic expansion through facility investments and local partnerships addresses fragmented national markets where proximity reduces logistics costs and demonstrates commitment to regional sustainability objectives. Clinical evidence generation through sponsored studies and real-world outcome registries builds acceptance among skeptical clinicians and risk-averse procurement committees demanding proof beyond regulatory minimums. Digital traceability integration enhances transparency and compliance while creating data assets supporting continuous improvement and customer reporting obligations. Vertical integration strategies differ between independent reprocessors expanding service portfolios and original manufacturers reclaiming device lifecycles through certified reprocessing programs protecting intellectual property. Strategic alliances with group purchasing organizations and national health services secure volume commitments enabling scale economics necessary to justify regulatory investments. Portfolio rationalization focuses resources on high-margin, complex devices where validation barriers protect margins versus commoditized categories facing price pressure. These interconnected strategies collectively address fundamental market dynamics where regulatory compliance, clinical trust,t and operational efficiency increasingly determine competitive success across diverse European jurisdictions.
MARKET SEGMENTATION
This research report on the Europe Single-Use Medical Device Reprocessing Market is segmented and sub-segmented into the following categories.
By Class I Devices
- Sequential Compression Sleeves
- Tourniquet Cuffs
- Pulse Oximeter Sensors
By Class II Devices
- Microdebriders
- Cautery Electrodes
- Laparoscopic Graspers
- Scissors
- Forceps
- Scalpels
- Orthopedic Blades
- Drill Bits
- External Fixation Clamps
- Electrophysiological Cardiac Catheters
By End-User
- Hospitals
By Country
- UK
- France
- Spain
- Germany
- Italy
- Russia
- Sweden
- Denmark
- Switzerland
- Netherlands
- Turkey
- Czech Republic
- Rest of Europe