- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$7.73 BnMarket Estimate, 2026
$8.36 BnMarket Forecast, 2034
$15.72 BnCAGR, 2026–2034
8.21%Executive Summary: Global Fiber Food Ingredients Market
- Market Scope: Comprehensive global analysis of the fiber food ingredients market covering product types, application segments, regional adoption landscapes, and preventive health-driven consumer trends.
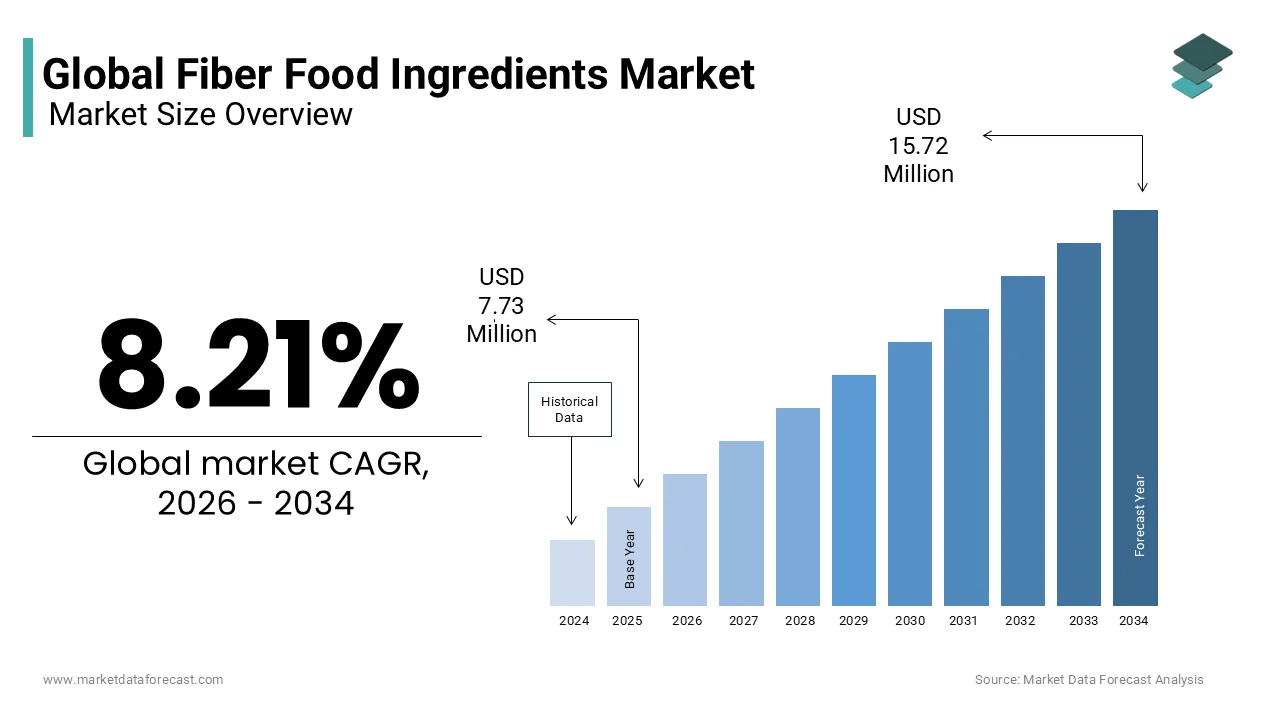
- Market Valuation: Valued at USD 7.73 billion (2025), estimated at USD 8.36 billion (2026), and projected to reach USD 15.72 billion by 2034, registering a strong CAGR of 8.21% (2026–2034).
- Primary Growth Drivers: Rising consumer awareness of healthy diets, popularity of prebiotics and functional foods, and the efficacy of dietary fibers in preventing gastrointestinal illnesses, obesity, cardiovascular diseases, and diabetes. Key operational factors include increasing demand for weight management solutions, preventive healthcare transitions, and innovative product formulations with enhanced taste and quality.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Type | Soluble Fiber / Inulin (occupied largest revenue share driven by usage as a flavor-enhancing additive and fat/sugar substitute) | Insoluble Dietary Fiber (projected to experience the fastest growth driven by functional food consumption and dietary shifts) |
| By Application | Food and Beverages (dominated with over 44% of global sales supported by breakfast cereals and functional foods) | Dietary Supplements & Functional Foods (expanding rapidly due to rising preventive healthcare adoption) |
| By Region | North America (held the largest market share led by the U.S. and high popularity of functional ingredients and dietary supplements) | Asia Pacific (expected to grow at the highest CAGR due to expanding populations, disposable incomes, and health awareness) |
Major Market Players & Market Structure
Market Structure: Highly competitive global ingredients market featuring major life science, food tech, and agricultural processing corporations competing on product stability, functional efficacy, and Clean-Label innovations.
Key Companies: The Ingredion and Ingredion Idea Labs, Cargill Incorporated, SunOpta Inc., Tate and Lyle, Nexira, Jiangsu Huachang (Group) Co. Ltd., Roquette, Archer Daniels Midland Company, Lonza Group, Grain Millers Inc., FutureCeuticals, KFSU LTD Australia, Cosucra Groupe Warcoing, Sudzucker, BarnDad Innovative Nutrition, Grain Processing Corporation, and Unipektin Ingredients.
 Download Free Sample Report
Global Fiber Food Ingredients Market Size
The global fiber food ingredients market size was valued at USD 7.73 billion in 2025 and is expected to reach USD 15.72 billion by 2034 from USD 8.36 billion in 2026. The market's promising CAGR for the predicted period is 8.21%.
Fiber food ingredients are a diverse array of soluble and insoluble dietary fibers derived from plant sources, such as cereals, fruits, vegetables, and legumes that are incorporated into processed foods to enhance nutritional profiles and functional properties. As per the World Health Organization, less than 5% of adults globally consume the recommended daily intake of 400 grams of fruits and vegetables, which creates a critical public health gap that fiber enrichment aims to address through fortified food products. According to the United States Department of Agriculture, only 10% of Americans meet the federal guidelines for vegetable consumption, while 23% meet fruit recommendations, indicating a widespread reliance on supplemented nutrition sources. This market serves as a vital bridge between inadequate natural dietary habits and necessary physiological requirements for digestive health and metabolic regulation. Manufacturers utilize these ingredients to improve texture, water retention, and shelf stability in baked goods, beverages, and dairy alternatives while simultaneously boosting fiber content. The sector is defined by its dual role in providing both technological functionality for food formulators and essential health benefits for consumers seeking to mitigate risks associated with chronic diseases linked to low-fiber diets.
MARKET DRIVERS
Escalating Global Prevalence of Lifestyle-Related Diseases
The increasing global burden of lifestyle-related diseases, such as type 2 diabetes, obesity, and cardiovascular disorders directly propels the fiber food ingredients market expansion by driving demand for functional food solutions that support metabolic health. According to the International Diabetes Federation, approximately 537 million adults were living with diabetes in 2021, and this number is projected to rise to 643 million by 2030, creating an urgent need for dietary management tools, including high-fiber interventions. The World Heart Federation reports that cardiovascular diseases remain the leading cause of death globally, accounting for an estimated 17.9 million deaths annually, which reinforces the medical community's recommendation for increased soluble fiber intake to lower cholesterol levels. These alarming statistics compel food manufacturers to reformulate existing products with added fibers, such as inulin, beta-glucan, and psyllium, to help consumers manage blood sugar spikes and lipid profiles without drastic dietary changes. Regulatory bodies worldwide are increasingly mandating clearer nutritional labeling, which highlights fiber content and encourages product innovation. Consumers actively seek out fortified options as preventive measures against these prevalent conditions, making fiber-enriched snacks, breads, and beverages essential components of modern therapeutic diets aimed at reducing long-term healthcare burdens.
Stringent Government Regulations and Nutritional Guidelines
Government mandates and updated nutritional guidelines further fuels the fiber food ingredients market growth by legally requiring or strongly encouraging the inclusion of dietary fiber in staple food products to combat national health crises. As per the European Food Safety Authority, new regulations implemented in recent years require specific health claims regarding fiber and digestive health to be substantiated by rigorous scientific evidence, which has led to a surge in validated fiber ingredient applications across the EU food sector. The United States Food and Drug Administration updated its definition of dietary fiber to include seven isolated and synthetic non-digestible carbohydrates that have beneficial physiological effects in humans, thereby expanding the range of approved ingredients for food fortification. These regulatory shifts force manufacturers to comply with stricter nutritional standards or risk losing market access and consumer trust. Public health campaigns in countries like Canada and Australia explicitly promote fiber consumption as a key strategy for weight management and disease prevention, which translates into higher retail demand for compliant products. Food processors respond by integrating cost-effective fiber solutions into mass-market items, such as pasta, cereals, and ready-to-eat meals, to meet these legal and social expectations, ensuring consistent volume growth for ingredient suppliers who provide compliant and scientifically backed fiber sources.
MARKET RESTRAINTS
Sensory Alterations and Textural Compromises in End Products
The inherent tendency of fiber additives to alter taste, texture, and mouthfeel restrains the fiber food ingredients market expansion by causing consumer rejection of fortified products despite their health benefits. According to the Institute of Food Technologists, high levels of insoluble fiber can create gritty or sandy textures in baked goods and beverages, which significantly reduces repeat purchase rates among sensory-sensitive demographics. The Journal of Food Science notes that soluble fibers like inulin can impart unwanted sweetness or aftertastes when used in high concentrations while also affecting the viscosity and stability of liquid formulations, leading to phase-separation issues. These technical challenges force food scientists to limit the amount of fiber they can add without compromising the overall eating experience, which caps the potential nutritional enhancement of many products. Manufacturers must invest heavily in complex masking agents and advanced processing techniques to mitigate these sensory defects, which increases production costs and time to market. Consumers often perceive fiber-enriched products as inferior in quality compared to their traditional counterparts, leading to lower brand loyalty. Until formulation technologies advance to fully neutralize these negative sensory impacts, a significant portion of the market will remain hesitant to adopt high-fiber alternatives regularly.
High Production Costs and Supply Chain Volatility
The elevated cost of extracting and purifying specialized fiber ingredients impedes the fiber food ingredients market expansion by making them prohibitively expensive for mass-market food applications where price sensitivity is high. As per the Food and Agriculture Organization of the United Nations, climate change-induced droughts reduced global cereal yields by 10% in 2022, which drove up raw material costs for grain-based fibers, such as wheat bran and oat beta-glucan. The International Trade Centre reports that logistics disruptions and energy price fluctuations increased the processing costs for fiber extraction facilities by 15% in the past two years, further squeezing manufacturer margins. These economic pressures prevent small- and medium-sized food companies from adopting premium fiber ingredients, forcing them to rely on cheaper but less effective alternatives or skip fortification entirely. High-purity fibers required for clear beverages and delicate dairy products command premium prices that cannot always be passed on to cost-conscious consumers. Supply chain inconsistencies also lead to availability issues, which disrupt production schedules for large-scale manufacturers. Consequently, many brands opt to maintain existing formulations rather than risk price hikes or supply shortages associated with specialized fiber sourcing, limiting the overall penetration of high-quality fiber ingredients in the broader food industry.
MARKET OPPORTUNITIES
Expansion of Plant-Based and Alternative Protein Foods
The rapid expansion of the plant-based food sector is a major opportunity for the fiber food ingredients market because meat and dairy alternatives inherently require texturizers and binders that fiber sources can effectively provide. According to the Good Food Institute, global sales of plant-based foods reached 8.1 billion dollars in 2022, with meat alternatives accounting for the largest share, creating a substantial demand for ingredients that mimic animal protein structures. The Plant-Based Foods Association states that 40% of American consumers now actively try to incorporate more plant-based meals into their diets, which drives manufacturers to use pea fiber, citrus fiber, and bamboo fiber to improve moisture retention and bite in vegan burgers and nuggets. These fibers not only serve functional roles in binding water and fat, but also boost the nutritional profile of products that are sometimes criticized for being highly processed. By positioning fiber ingredients as essential structural components rather than just nutritional additives, suppliers can secure long-term contracts with fast-growing alternative protein brands. This synergy allows fiber producers to diversify their client base beyond traditional bakery and cereal sectors into the dynamic and high-investment realm of plant-based innovation, where performance and clean-label attributes are equally valued.
Development of Prebiotic Functional Beverages
The growing consumer interest in functional beverages offers a significant opportunity for the fiber food ingredients market through the integration of prebiotic fibers that support gut health in drinkable formats. As per the Beverage Marketing Corporation, the global functional beverage market is expected to grow at a compound annual growth rate of 7.5% through 2025, driven by demand for drinks that offer specific health benefits beyond hydration. The International Scientific Association for Probiotics and Prebiotics highlights that resistant dextrin and inulin are among the most studied prebiotic fibers for promoting beneficial gut bacteria growth, which makes them ideal candidates for clear water enhancers and juices. Manufacturers can leverage these soluble fibers to create low-calorie, high-fiber drinks that appeal to health-conscious consumers seeking convenient ways to improve digestive wellness without consuming bulky solid foods. Innovations in fiber solubility allow for seamless integration into carbonated waters and teas without affecting clarity or taste, opening new product categories. This trend aligns with the broader wellness movement, where gut health is increasingly linked to immunity and mental well-being. By targeting the beverage sector, fiber ingredient suppliers can tap into a high-frequency consumption category that offers greater volume potential than occasional snack or meal replacements.
MARKET CHALLENGES
Regulatory Heterogeneity Across Global Markets
The lack of harmonized global regulations regarding the definition and approval of dietary fiber sources challenges the fiber food ingredients market by creating complex compliance barriers for multinational food manufacturers. According to the Codex Alimentarius Commission, different member countries maintain varying standards for what constitutes a dietary fiber, with some recognizing only naturally occurring plant fibers while others include synthetic analogs, leading to inconsistent labeling requirements. The European Union maintains a strict positive list of approved fiber sources for health claims, whereas the United States allows a broader range of isolated fibers under its updated nutrition facts panel rules, creating confusion for exporters. This regulatory fragmentation forces companies to develop region-specific formulations and packaging, which increases operational complexity and costs. Ingredients approved in one market may be banned or restricted in another, requiring extensive legal review and reformulation efforts before launch. Such uncertainties delay product introductions and discourage smaller ingredient suppliers from entering international markets. Manufacturers must constantly monitor changing legislative landscapes to avoid costly recalls or labeling errors, which diverts resources from innovation. Until global standards converge, the market will continue to face inefficiencies that hinder the seamless flow of fiber ingredients across borders and limit the scalability of universal product platforms.
Consumer Skepticism Regarding Ultra-Processed Foods
Growing consumer skepticism toward ultra-processed foods challenges the fiber food ingredients market expansion because many isolated fiber additives are perceived as artificial or unnatural despite their plant origin. According to the Clean Label Project, 65% of shoppers actively avoid products with long ingredient lists or unfamiliar chemical-sounding names, which negatively impacts the acceptance of purified fiber extracts like polydextrose or maltodextrin. The Hartman Group reports that 58% of consumers prefer whole food sources of nutrition over fortified processed items, believing that natural integrity offers superior health benefits compared to isolated compounds. This perception creates a marketing dilemma for brands that use high-tech fiber ingredients to boost nutritional value while trying to maintain a clean-label image. Consumers often misinterpret terms like chicory root extract or acacia gum as industrial additives rather than natural plant derivatives, leading to distrust. Food manufacturers face pressure to remove these ingredients even if they provide proven health benefits, resulting in reformulation struggles. Overcoming this educational gap requires significant investment in consumer communication to explain the safety and efficacy of isolated fibers. Without successful narrative shifting, the market risks stagnation as clean-label trends continue to prioritize minimal processing over functional fortification.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 8.21% |
| Segments Covered | By Type, Application, and Region |
| Various Analyses Covered | Global, Regional and Country Level Analysis; Segment-Level Analysis; DROC; PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Ingredion Incorporated, Cargill Incorporated, SunOpta Inc., Tate & Lyle, Nexira, Jiangsu Huachang (Group) Co. Ltd., Roquette, Archer Daniels Midland Company, Lonza Group, Grain Millers Inc., FutureCeuticals, KFSU LTD Australia, Cosucra Groupe Warcoing, Südzucker, BarnDad Innovative Nutrition, Grain Processing Corporation, and Unipektin Ingredients |
SEGMENTAL ANALYSIS
By Type Insights
The insoluble fibers segment accounted for 54.9% of the global market share in 2025 and is estimated to maintain their position as the leading segment in the fiber food ingredients market throughout the forecast period owing to the widespread availability of low-cost agricultural byproducts, such as wheat bran, corn hulls, and oat husks. According to the United States Department of Agriculture, global wheat production reached 780 million metric tons in 2023, which generates substantial volumes of bran residue that serves as a primary source for insoluble fiber extraction at minimal processing costs. As per the Food and Agriculture Organization of the United Nations, cereal grain processing industries produce over 150 million tons of fibrous byproducts annually, providing a consistent and economical supply chain for manufacturers. This abundance allows food producers to incorporate insoluble fibers into mass-market products like whole grain breads and cereals without significantly impacting final retail prices. The functional properties of insoluble fibers, such as water absorption and bulk enhancement, are well understood by formulators who rely on them to improve texture and shelf life in baked goods. Regulatory acceptance of these traditional fiber sources is universal across major markets, reducing compliance barriers. Consumers recognize terms like wheat bran and cellulose as natural ingredients, which supports steady demand in clean-label formulations. The segment benefits from established extraction technologies that require less energy and chemical input compared to soluble fiber isolation, making it the preferred choice for high-volume industrial applications where cost efficiency is paramount.
On the other end, the soluble fiber segment represents the fastest-growing category and is expected to exhibit a CAGR of 7.7% over the forecast period owing to its unique ability to form gels and provide specific metabolic health benefits that appeal to modern consumers. As per the International Scientific Association for Probiotics and Prebiotics, clinical studies confirming the cholesterol-lowering effects of beta-glucan and psyllium have led to approved health claims in over 40 countries, which directly stimulates manufacturer adoption in heart-healthy product lines. The European Food Safety Authority notes that approvals for soluble fiber-related health claims increased by 25% in the last five years, encouraging brands to reformulate snacks and beverages with ingredients like inulin and resistant dextrin. Soluble fibers offer superior technological functionality, including fat replacement and moisture retention, which is critical for the expanding plant-based meat alternative sector. These ingredients help mimic the mouthfeel of animal fats while adding nutritional value, creating a dual benefit for product developers. The rise of personalized nutrition trends further boosts demand as soluble fibers are increasingly linked to gut microbiome modulation and improved immune response. Manufacturers invest in advanced purification techniques to produce clear and taste-neutral soluble fibers suitable for transparent beverages and dairy alternatives. This innovation opens new application avenues beyond traditional bakery items, allowing the segment to capture higher-value niches in the functional food landscape.
By Application Insights
The bakery segment held 43.4% of the global market share in 2025. The dominance of bakery segment in the global market can be credited to their structural compatibility with fibrous additives. According to the American Bakers Association, the United States bakery industry generated 46 billion dollars in sales in 2023, with whole grain and multigrain products accounting for 35% of total volume, indicating strong consumer preference for fiber-rich staples. The National Association of Wheat Growers reports that 90% of commercial bakeries now offer at least one high-fiber product line to meet dietary guidelines and consumer expectations for healthier options. Insoluble fibers such as wheat bran and oat fiber are easily integrated into dough formulations where they enhance water retention and extend shelf life by slowing staling processes. This technical benefit reduces waste for retailers and improves profit margins for manufacturers. Consumers perceive bakery items as daily essentials, making them more likely to accept fiber-fortified versions as part of their routine diet rather than as specialized health products. Regulatory mandates in several European countries requiring minimum fiber content in certain bread categories further secure this segment's leadership. The widespread availability of fiber-enriched flour blends simplifies the formulation process for artisanal and industrial bakers alike, ensuring consistent market penetration across diverse geographic regions and economic segments.
However, the dietary supplements segment exhibits the fastest growth and is predicted to register a CAGR of 8.8% over the forecast period as consumers increasingly turn to concentrated fiber powders and capsules to address digestive health concerns without altering their regular diets. According to the Council for Responsible Nutrition, 77% of US adults reported using dietary supplements in 2023, with digestive health products representing one of the top three categories by sales growth. The National Institutes of Health states that public awareness campaigns linking fiber intake to reduced risks of colon cancer and type 2 diabetes have driven a 20% increase in fiber supplement purchases over the past three years. This segment benefits from the convenience factor as busy professionals prefer quick solutions over preparing high-fiber meals. Innovations in delivery formats, such as chewable gummies and dissolvable sticks, make fiber supplementation more appealing to younger demographics who traditionally avoid pill-based supplements. Direct-to-consumer brands leverage digital marketing to educate users on the benefits of specific fiber types like psyllium husk and acacia fiber for gut regularity and satiety management. The rise of telehealth and personalized nutrition apps also contributes to growth by recommending specific fiber dosages based on individual health data. This targeted approach creates loyal customer bases willing to pay premium prices for high-purity and clinically studied fiber ingredients in supplement forms.
REGIONAL ANALYSIS
North America Fiber Food Ingredients Market Analysis
North America had 36.7% of the global market share in 2025 and is likely to maintain its dominant position and experience steady market expansion over the next few years due to the robust consumer demand, continuous product innovation, high consumer awareness of digestive health and stringent regulatory support for nutritional labeling. According to the Centers for Disease Control and Prevention, only 5% of US adults consume the recommended daily amount of fiber, which has prompted aggressive industry initiatives to fortify staple foods with isolated fiber ingredients. The Dietary Guidelines for Americans explicitly recommend increasing fiber intake to 25 to 38 grams per day, creating a clear target for food manufacturers to meet through product innovation. The region benefits from a mature infrastructure for ingredient sourcing and advanced processing technologies that enable the production of high-purity soluble and insoluble fibers. Major food corporations headquartered in the US and Canada lead global trends in launching fiber-enriched snacks and beverages. Consumer willingness to pay premiums for functional benefits supports the growth of premium fiber ingredients derived from novel sources like chicory root and baobab. The presence of key market players and robust research institutions fosters continuous innovation in fiber application technologies. Retailers actively promote high-fiber products through dedicated health aisles and educational signage, further driving adoption. The market is characterized by high competition among ingredient suppliers who differentiate through sustainability credentials and clean-label certifications to appeal to discerning North American shoppers.
Europe Fiber Food Ingredients Market Analysis
Europe is projected to experience steady, regulation-driven growth over the coming years, supported by an increasing emphasis on sustainability and preventative nutrition. As per the European Commission, the EU Farm to Fork Strategy aims to reduce the environmental impact of food production while promoting healthier diets, which encourages the use of locally sourced, fiber-rich agricultural byproducts. The European Society for Clinical Nutrition and Metabolism reports that 60% of Europeans consider digestive health a top priority, influencing their purchasing decisions for fiber-fortified foods and supplements. Northern European countries like Germany and the UK lead in consumption of whole-grain breads and cereals, while Southern Europe shows growing interest in functional beverages containing soluble fibers. The region enforces rigorous standards for health claims requiring scientific substantiation, which ensures high quality and efficacy of fiber ingredients used in commercial products. Manufacturers focus on sustainable sourcing and organic certification to align with consumer values regarding environmental responsibility. The prevalence of private-label brands offering affordable fiber-enriched options increases market accessibility across different income levels. Collaborative research between universities and industry partners drives innovation in extracting fibers from underutilized crops such as hemp and flax. This scientific backing strengthens consumer trust and supports steady market growth despite economic fluctuations affecting discretionary spending on premium health products.
Asia Pacific Fiber Food Ingredients Market Analysis
The Asia Pacific region is expected to witness the fastest regional growth over the next few years owing to the rapid urbanization, rising middle-class disposable incomes and increasing prevalence of lifestyle-related diseases. According to the World Health Organization, the number of people with diabetes in the Western Pacific Region doubled from 1980 to 2014, reaching 148 million, which drives demand for low-glycemic index foods enriched with soluble fibers. The Asian Development Bank notes that the middle-class population in Asia is expected to reach 1.7 billion by 2030, creating a massive consumer base for premium functional foods and dietary supplements. Countries like China, Japan, and India are witnessing a shift from traditional high-carbohydrate diets to balanced nutrition plans that include fiber-fortified snacks and beverages. Local manufacturers are investing in extraction facilities to process regional crops such as rice bran, bamboo, and konjac into high-value fiber ingredients. Government initiatives in countries like Singapore and Australia promote public health campaigns focusing on fiber intake to combat obesity. The e-commerce boom facilitates access to niche fiber products for consumers in remote areas. Cultural preferences for natural and herbal remedies align well with plant-based fiber ingredients, enhancing acceptance. The market is fragmented but consolidating as multinational ingredient suppliers establish local partnerships to navigate regulatory complexities and distribution challenges in diverse Asian markets.
Latin America Fiber Food Ingredients Market Analysis
Latin America is anticipated to show moderate and resilient growth over the upcoming years, driven by evolving dietary habits and expanding food processing industries. According to the Pan American Health Organization, non-communicable diseases account for 75% of deaths in the region, prompting governments to implement front-of-package warning labels that highlight low fiber content in processed foods. The Economic Commission for Latin America and the Caribbean reports that food processing exports grew by 6% in 2023, indicating stronger integration into global supply chains that require standardized fiber-enriched ingredients. Brazil and Mexico lead regional consumption due to large populations and increasing adoption of western dietary habits, including breakfast cereals and packaged snacks. Local agriculture provides abundant raw materials, such as sugarcane bagasse and corn husks, which are being converted into value-added fiber ingredients for domestic use and export. Economic volatility affects purchasing power, yet basic staple fortification remains a priority for public health programs. Urban consumers show greater willingness to try functional beverages and supplements containing imported premium fibers. Distribution networks are expanding into rural areas, improving access to fortified products. Regional trade agreements facilitate the movement of fiber ingredients between countries, allowing brands to scale operations. The market is driven by a combination of regulatory pressure and consumer education initiatives that highlight the importance of dietary fiber for long-term health.
Middle East and Africa Fiber Food Ingredients Market Analysis
The Middle East and Africa region is expected to experience gradual market development over the next few years, propelled by expanding health initiatives and rising awareness of metabolic health. The Middle East and Africa region shows nascent development in the Fiber Food Ingredients Market constrained by varying levels of economic development, but supported by rising obesity rates and government health initiatives. According to the World Health Organization, obesity rates in the Eastern Mediterranean Region have tripled since 1975, creating an urgent need for dietary interventions, including increased fiber consumption to manage weight and metabolic health. The African Union reports that urbanization rates are increasing by 3.5% annually, leading to dietary shifts toward processed foods that are often low in natural fiber, creating a gap for fortified alternatives. South Africa and the United Arab Emirates lead market adoption due to higher income levels and exposure to global health trends. Local manufacturers are beginning to incorporate date palm fiber and other regional plant sources into traditional products to enhance nutritional value. Import dependence remains high for specialized soluble fibers due to limited local processing capabilities. Religious and cultural dietary practices influence product acceptance, with halal certification being crucial for market entry. Government subsidies for basic food items sometimes exclude fortified products, limiting affordability for lower-income groups. However, growing awareness among the middle class and expatriate communities drives demand for premium fiber-enriched imports. Infrastructure improvements in logistics and cold chain storage are gradually enabling wider distribution of perishable, fiber-rich products across the region.
COMPETITIVE LANDSCAPE
The competitive landscape of the fiber food ingredients market et features a mix of large multinational corporations and specialized niche players competing on innovation and quality. Major agribusinesses leverage their extensive supply chains to offer cost effective bulk fiber ingredients while specialty firms focus on high value added products with proven health benefits. Competition intensifies as companies strive to differentiate through unique fiber sources such as baobab or hemp which appeal to clean label trends. Regulatory compliance remains a critical factor with firms investing in scientific validation to support health claims and gain market access. Price pressure from private label alternatives forces established brands to justify premiums through superior functionality and service. Strategic alliances with food manufacturers facilitate joint development of innovative products that meet evolving consumer preferences. Geographic expansion into Asia and Latin America offers growth potential but requires navigation of complex regulatory environments. Sustainability credentials increasingly influence purchasing decisions prompting companies to adopt eco friendly processing methods. The market remains dynamic with continuous entry of new players introducing novel ingredients that challenge traditional dominance. Success depends on balancing cost efficiency with innovation and maintaining strong relationships with key industry stakeholders.
Key Market Players
Some of the key players in the global fiber food ingredients market are
- Ingredion Incorporated
- Cargill Incorporated
- SunOpta Inc.
- Tate & Lyle
- Nexira
- Jiangsu Huachang (Group) Co. Ltd.
- Roquette
- Archer Daniels Midland Company
- Lonza Group
- Grain Millers Inc.
- FutureCeuticals
- KFSU LTD Australia
- Cosucra Groupe Warcoing
- Südzucker
- BarnDad Innovative Nutrition
- Grain Processing Corporation
- Unipektin Ingredients
Top Players in the Market
- Cargill Incorporated leverages its vast global agricultural network to supply a diverse portfolio of fiber ingredients including wheat bran and corn fiber. The company focuses on sustainable sourcing practices that appeal to environmentally conscious food manufacturers seeking reliable raw material supplies. Recent initiatives involve expanding production capacity for soluble corn fiber to meet rising demand in beverage and dairy applications. Cargill invests heavily in research and development to create customized fiber solutions that improve texture and stability in processed foods. Their technical support teams work closely with clients to optimize formulation processes ensuring seamless integration of fiber ingredients. By prioritizing supply chain transparency and traceability Cargill strengthens trust among major food brands. The company also engages in strategic partnerships with local farmers to secure high quality crop residues for fiber extraction. This vertical integration allows Cargill to maintain consistent product quality while reducing costs. Their commitment to innovation drives the development of novel fiber sources that offer enhanced functional benefits for next generation food products.
- Ingredion Incorporated stands as a leader in specialty fiber ingredients offering advanced solutions such as resistant starches and chicory root fibers. The company emphasizes scientific validation of health benefits to support regulatory approvals and consumer confidence in their products. Recent actions include launching new prebiotic fiber blends designed specifically for gut health applications in snacks and supplements. Ingredion collaborates with academic institutions to conduct clinical studies that demonstrate the efficacy of their fiber ingredients in managing blood sugar levels. Their global footprint enables them to serve multinational clients with consistent quality standards across different regions. The company also focuses on clean label trends by providing natural fiber options that replace synthetic additives in food formulations. Ingredion’s customer centric approach involves co creation projects where they develop tailored solutions for specific market needs. This strategy helps them retain key accounts and expand into emerging categories like plant based meats. Their investment in digital tools enhances supply chain efficiency and customer engagement.
- Tate and Lyle PLC specializes in premium soluble fibers such as PROMITOR Soluble Corn Fiber which are widely used in low calorie and high fiber applications. The company distinguishes itself through rigorous quality control and proven health claims supported by extensive clinical data. Recent efforts involve expanding manufacturing facilities in Asia to better serve growing markets in China and India. Tate and Lyle actively promotes the benefits of soluble fiber for weight management and digestive health through educational campaigns targeting both consumers and professionals. They partner with leading food brands to innovate new product formats such as fiber enriched beverages and bars. The company prioritizes sustainability by optimizing water and energy usage in their production processes. Tate and Lyle also explores alternative raw materials to diversify their supply base and reduce dependency on single crops. Their focus on high value added products allows them to command premium pricing while delivering superior functional performance. This strategic positioning reinforces their reputation as a trusted partner for health focused food innovation.
Top Strategies Used by Key Market Participants
Key players in the Fiber Food Ingredients Market et primarily focus on product innovation to develop novel fiber sources with enhanced functional and health properties. Companies invest heavily in research and development to create clean label ingredients that meet consumer demand for natural and transparent formulations. Strategic acquisitions allow firms to expand their geographic reach and diversify their product portfolios with specialized fiber types. Partnerships with academic institutions help validate health claims through clinical studies which supports regulatory approvals and marketing efforts. Sustainability initiatives are central to corporate strategies as brands seek to reduce environmental impact and appeal to eco conscious buyers. Expansion into emerging markets provides growth opportunities as rising middle classes adopt healthier dietary habits. Digital transformation improves supply chain efficiency and customer engagement through data driven insights. Collaborative projects with food manufacturers enable co creation of customized solutions that address specific formulation challenges. These combined strategies help companies maintain competitive advantages and drive long term growth in a dynamic market environment.
MARKET SEGMENTATION
This research report on the global fiber food ingredients market has been segmented and sub-segmented based on type, application & region.
By Type
- Insoluble Fibers
- Soluble Fibers
By Application
- Food and Beverage
- Dairy
- Bakery
- Confectionery
- Dietary Supplements
- Poultry
- Seafood
- Meat
- Ready-To-Eat Products
- Beverages
- Pharmaceuticals
By Region
- North America Europe
- Asia Pacific
- Europe
- Latin America
- Middle East and Africa