- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$14.04 BnMarket Estimate, 2026
$15.23 BnMarket Forecast, 2034
$29.26 BnCAGR, 2026–2034
8.50%Executive Summary: Global Fishmeal and Fish Oil Market
- Market Scope: Comprehensive global analysis of the fishmeal and fish oil market covering raw material sources, downstream applications, livestock segments, and regional market behaviors.
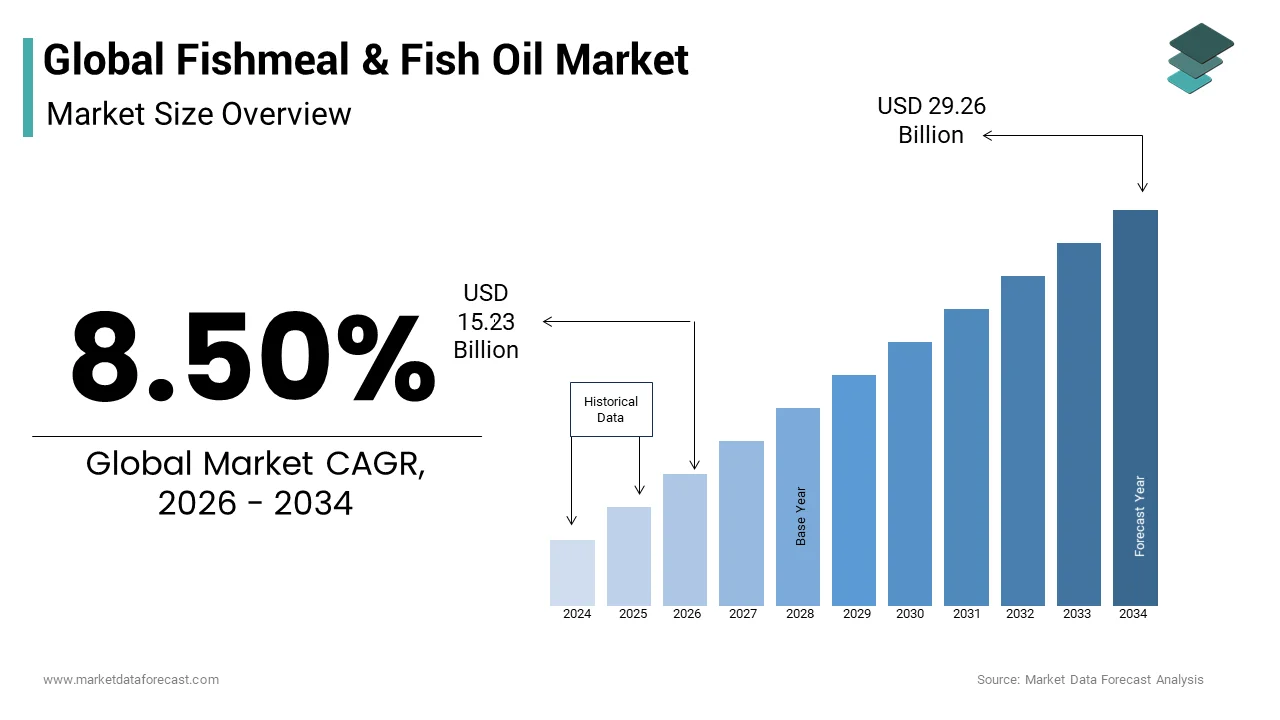
- Market Valuation: Valued at USD 14.04 billion in 2025, reaching USD 15.23 billion in 2026, and projected to scale up to USD 29.26 billion by 2034, growing at a robust CAGR of 8.5% from 2026 to 2034.
- Primary Growth Drivers: Rapid expansion of global aquaculture production requiring high-protein feeds, rising consumption of omega-3 dietary supplements for humans, and increased focus on animal feed efficiency and disease immunity.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Source | Salmon and trout (accounting for high market revenue valued at USD 2,362.5 million in 2025 due to intensive global aquaculture farming) | Marine fish and crustaceans (expanding through specialized species harvesting for targeted EPA and DHA extraction) |
| By Application | Aquaculture and aquatic feeds (commanding the core share as a prime high-protein additive replacing terrestrial feed) | Pharmaceuticals & human nutritional supplements (surging with the rising popularity of omega-3 capsules and health products) |
| By Livestock | Aquatic animals (representing the biggest segment in 2025 by enhancing feed efficiency and reducing wastewater pollutant levels) | Swine and poultry sectors (growing steadily with specialized low-calorie, high-performance feed formulations) |
| By Region / Country | Asia-Pacific (ruling the market in 2025 driven by heavy aquaculture production in China, India, Vietnam, and Thailand) | North America & Latin America (expanding significantly as major exporters of LC-omega-3 rich marine resources and high-grade fish oil) |
Major Market Players & Market Structure
Market Structure: Highly competitive global marine ingredient market dominated by specialized fishery conglomerates, aquaculture feed suppliers, and biotechnology enterprises focused on sustainable sourcing and human-grade nutritional refining.
Key Companies: FMC Corporation, Austevoll Seafood ASA, Croda International Plc., Oceana Group Limited, and Omega Protein Corporation.
 Download Free Sample Report
Global Fishmeal and Fish Oil Market Size
The global fishmeal and fish oil market size was valued at USD 14.04 billion in 2025 and is anticipated to reach a valuation of USD 15.23 billion in 2026 and USD 29.26 billion by 2034, growing at a CAGR of 8.5%, from 2026 to 2034.
Current Introduction and Definition of the Fishmeal and Fish Oil Market
The fishmeal and fish oil are the industrial processing of small pelagic forage fish and aquaculture byproducts into nutrient dense protein meals and omega 3 rich lipid concentrates essential for global food security systems. These marine ingredients are irreplaceable functional components in aquafeed livestock rations and nutraceuticals due to their unique amino acid profiles and long chain polyunsaturated fatty acids that synthetic alternatives cannot fully replicate. The global aquaculture production reached 130.9 million tonnes in 2022 with fed species accounting for 70% of output creating structural demand for high-quality marine proteins, as per the study. As per the World Health Organization, minimum daily intake of 250 milligrams of EPA and DHA for cardiovascular health. As per the study, ocean warming has shifted forage fish distributions poleward by an average of 60 kilometers per decade altering raw material availability patterns independent of fishing pressure.
MARKET DRIVERS
Aquaculture Expansion in Carnivorous Species Production
The exponential growth of carnivorous aquaculture species including salmon, shrimp, and marine finfish, creates non-discretionary demand for fishmeal and fish oil, as these animals require specific marine derived nutrients for optimal growth reproduction and immune function. The aquaculture expansion in carnivorous species production is accelerating the growth of the fishmeal and fish oil market. According to data monitored via the OECD-FAO Agricultural Outlook, global farmed Atlantic salmon production experienced a steady expansion, reaching 2.87 million metric tonnes by 2023. As per the decades of research into plant based substitutes, the inclusion rate of marine ingredients in premium salmon diets has stabilized rather than declined because complete replacement compromises fillet texture pigmentation and omega 3 content valued by consumers. This biological dependency creates inelastic demand where feed formulators must secure marine ingredients regardless of price volatility because formulation changes risk catastrophic production losses.
Nutraceutical and Pharmaceutical Omega 3 Demand Growth
The human health applications for long chain omega 3 fatty acids, as clinical evidence supporting cardiovascular cognitive and anti-inflammatory benefits is additionally leveraging the growth of the fishmeal and fish oil market. According to the study, over 28% of US adults consumed omega 3 supplements in 2024 representing 72 million consumers spending 2.4 billion dollars annually on products where fish oil constitutes 85% of active ingredient sources. Data from the European Food Safety Authority confirms that health claims for EPA and DHA regarding the maintenance of normal blood pressure, triglyceride levels, and brain function have been scientifically validated, enabling marketing authorization across 27 EU member states. Infant formula manufacturers increasingly add DHA to match breast milk composition with WHO recommendations driving annual consumption of 12000 tonnes of refined fish oil specifically processed to meet stringent contaminant limits. This human health dimension decouples portion of fish oil demand from commodity feed cycles creating stable premium pricing tier insulated from aquaculture volume fluctuations and enabling processors to capture higher margins through specialized refining capabilities.
MARKET RESTRAINTS
Finite Wild Catch Quotas and Ecosystem Limits
The global fishmeal and fish oil production faces hard ceiling imposed by maximum sustainable yield thresholds of forage fish stocks preventing supply expansion despite rising prices and technological advances in processing efficiency. The finite wild catch quotas and ecosystem is limiting the growth of the fishmeal and fish oil market. According to the study, global landings of reduction grade pelagics peaked at 32 million tonnes in 1994 and have averaged 18 to 20 million tonnes annually since 2010 reflecting biological limits rather than market conditions. As per Peru’s Ministry of Production, anchoveta catch quotas fluctuated between 2.5 and 5.5 million tonnes per season from 2020 to 2024 based on IMARPE stock assessments demonstrating how single species variability in world’s largest fishery creates systemic supply uncertainty affecting global pricing and availability. Unlike agricultural commodities where acreage and yields can expand through investment marine capture fisheries operate within fixed ecological boundaries making supply fundamentally unresponsive to price signals and creating permanent scarcity condition that constrains market growth regardless of demand trajectory.
Competition from Alternative Protein and Lipid Sources
The rapid commercialization of microbial single cell proteins algal oils and insect meals provides functional, particularly in price sensitive feed segments and sustainability conscious consumer is also declining the growth of the fishmeal and fish oil market. According to the study, global production capacity for microbial proteins reached 450000 tonnes annually with companies like Calysta and KnipBio achieving price parity with premium fishmeal at 1800 dollars per tonne, while offering consistent year round supply unaffected by seasonal fishing quotas. Plant protein concentrates from soy wheat and pea have improved digestibility through enzymatic processing reducing fishmeal inclusion rates in tilapia and catfish feeds from 30% to under 10% over past decade, according to survey. This substitution pressure intensifies during fishmeal price spikes when alternative economics improve accelerating permanent formulation shifts that do not reverse when marine ingredient prices decline creating structural demand erosion beyond cyclical competition.
MARKET OPPORTUNITIES
Byproduct Valorization from Seafood Processing Waste
The recovery of heads frames viscera and trimmings from seafood processing plants without additional fishing pressure is ascribed to fuel the growth of the fishmeal and fish oil market. According to the study, approximately 38 million tonnes of seafood processing byproducts are generated annually worldwide with only 25% currently utilized for human food or ingredient production leaving substantial volume available for rendering into marine proteins and lipids. Norwegian seafood industry recovered 180000 tonnes of byproducts for fishmeal and oil production in 2024, national marine ingredient output and generating 280 million dollars in additional revenue from waste streams previously disposed at cost, as per the research. The valorization pathway aligns economic incentives with environmental compliance creating win scenarios, where processors monetize regulatory obligations while expanding marine ingredient supply base independent of wild catch constraints.
Emerging Countries in Pet Food and Functional Feeds
The premium pet food and specialized animal nutrition present high margin, where marine ingredient functionality justifies price premiums and consumers actively seek omega-3 enriched products for companion animal health benefits. Emerging countries in pet food and functional feeds are additionally to elevate the growth of the fishmeal and fish oil market. As per the study, 68% of US dog owners and 54% of cat owners purchase supplements containing fish oil for joint skin and coat health creating direct consumer pull for marine omega 3s independent of feed manufacturer specifications. Equine and racing pigeon nutrition countries increasingly incorporate fish oil for anti-inflammatory and cognitive benefits with UK horseracing industry consuming 2500 tonnes annually, according to the recent data. These diversified end uses reduce market concentration risk in commodity aquafeed, while capturing value from consumer willingness to pay for perceived health benefits enabling processors to allocate limited marine ingredient supplies toward highest margin applications during periods of raw material scarcity.
MARKET CHALLENGES
Environmental Contaminants and Food Safety Compliance
Accumulation of persistent organic pollutants heavy metals and microplastics in marine ecosystems creates escalating testing costs regulatory barriers and consumer trust issues that is a major challenge for the growth of the fishmeal and fish oil market. The mercury concentrations in North Atlantic blue whiting increased between 2015 and 2024, correlating with changing prey distributions and bioaccumulation dynamics forcing processors to implement more frequent batch testing and selective sourcing protocols that fragment supply chains and increase logistics complexity. Microplastic contamination detected in some of commercial fishmeal samples tested by University of Exeter researchers in 2024, raises emerging concern as analytical methods improve and regulatory thresholds develop potentially creating new compliance burden before industry establishes mitigation standards. These food safety challenges require continuous capital investment in purification technology analytical capabilities and supply chain verification diverting resources from productive capacity expansion, while creating asymmetric barriers favoring large integrated operators over smaller producers lacking scale to absorb compliance costs.
Geopolitical Supply Concentration and Trade Vulnerability
The extreme geographic concentration of fishmeal and fish oil production in few countries creates systemic vulnerability to political instability trade disputes currency fluctuations and regulatory changes that disrupt global supply chains independent of biological stock conditions. The geopolitical supply concentration and trade vulnerability is also to decline the growth of the fishmeal and fish oil market. According to IFFO Marine Ingredients Organisation, Peru and Chile together account for 45% of global fishmeal production and 55% of fish oil exports meaning El Nino events or policy shifts in these two nations create immediate worldwide supply shocks and price volatility affecting all downstream users. According to the data, 68% of Chinese fishmeal imports originate from Peru creating bilateral dependency where Peruvian export tax adjustments or Chinese tariff retaliations in trade disputes cause immediate procurement disruptions for world’s largest consumer market impacting millions of tonnes of aquafeed production. Currency depreciation in producing countries like Peru where sol lost 18% against dollar in 2024 that creates unpredictable cost structures for international buyers hedging exposure through complex financial instruments adding transaction costs and counterparty risks. This geopolitical fragility contrasts sharply with diversified agricultural commodity supply bases and forces strategic stockpiling vertical integration and supplier diversification strategies that tie up capital and reduce operational flexibility for participants navigating inherently unstable supply landscape concentrated in politically and climatically volatile regions.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 8.5% |
| Segments Covered | By Source, Application, Livestock, and Region |
| Various Analyses Covered | Global, Regional, & Country Level Analysis; Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | FMC Corporation (U.S.), Austevoll Seafood ASA (Norway), Croda International Plc. (U.K.), Oceana Group Limited (South Africa), Omega Protein Corporation (U.S.), and Others. |
SEGMENTAL ANALYSIS
By Source Insights
The marine fish segment was accounted in holding 32.4% of the fishmeal and fish oil market share in 2025 due to established industrial reduction fisheries and superior nutrient density. The massive scale of dedicated reduction fisheries operating under long standing management frameworks that provide consistent raw material volumes unmatched by byproduct or aquaculture waste streams. According to the study, global landings of small pelagic fish for non-food purposes averaged 18.5 million tonnes annually between 2020 and 2024 with Peruvian anchoveta alone contributing 6 to 8 million tonnes depending on El Nino cycles creating foundational supply base for entire industry. Decades of infrastructure investment in port facilities processing plants and logistics networks in Peru Chile Denmark and United States create economies of scale that newer byproduct recovery operations cannot replicate keeping unit costs competitive, despite rising regulatory compliance expenses. This combination of biological abundance established supply chains and unmatched nutritional profile ensures marine fish maintains segment leadership even as sustainability concerns drive diversification toward alternative sources that currently lack capacity to displace primary reduction fisheries at global scale.
The salmon and trout segment is projected to witness a fastest CAGR of 14.8% throughout the forecast period with the expanding aquaculture production circular economy mandates and valorization technology improvements. The direct correlation between farmed salmonid harvest volumes and byproduct generation creating predictable supply expansion independent of wild catch fluctuations or quota constraints limiting traditional marine fish sources. Chilean salmon industry invested 85 million dollars in byproduct valorization plants between 2022 and 2024 responding to Aquaculture Stewardship Council certification requirements mandating zero waste discharge and full utilization of harvested biomass. Unlike wild fisheries subject to environmental variability salmon farming operates on predictable production schedules enabling forward contracting and capacity planning that reduces supply uncertainty for downstream users.
By Livestock Application Insights
The aquatic animals segment held a dominant share of the global fishmeal and fish oil market in 2025 due to biological dependency on marine derived nutrients for optimal growth health and product quality. The physiological requirement of carnivorous and omnivorous aquatic species for specific amino acids taurine cholesterol and long chain omega 3 fatty acids that plant based alternatives cannot fully provide without synthetic supplementation or performance tradeoffs. According to FAO State of World Fisheries and Aquaculture 2024 fed aquaculture production increased with salmonids marine finfish and shrimp. Unlike terrestrial livestock that evolved to thrive on plant-based diets, aquatic species retain rigid ancestral nutritional dependencies from marine food webs, creating an inelastic demand where feed formulators must secure marine ingredients regardless of market price volatility.
The pet food and companion animal nutrition segment is likely to grow at a fastest CAGR of 11.2% throughout the forecast period with the humanization trends premiumization and functional health positioning in companion animal care. The escalating consumer willingness to spend on pet health and wellness translating into demand for marine omega 3s and proteins positioned as functional ingredients supporting joint cognitive skin and coat health benefits validated by veterinary science and marketing claims. According to the study, global premium pet food sales reached 52 billion dollars in 2024 with marine sourced ingredients featured as key differentiators in grain free limited ingredient and veterinary therapeutic diets. As per the data, 72% of US dog owners and 58% of cat owners purchase omega 3 supplements or foods specifically for joint mobility and dermatological health creating direct consumer pull for fish oil independent of feed manufacturer specifications or cost optimization considerations. Veterinary prescription diets for osteoarthritis renal disease and allergic dermatitis increasingly incorporate therapeutic doses of EPA and DHA with Royal Canin Hill’s and Purina Pro Plan veterinary lines, according to Packaged Facts 2024 assessment.
By Industrial Application Insights
The animal feed segment was the largest by holding a dominant share of the global fishmeal and fish oil market due to irreplaceable nutritional functionality across multiple livestock sectors. The biological necessity of marine derived nutrients for optimal animal performance health and product quality creating inelastic demand that persists. According to Rabobank Animal Protein Outlook 2024, global aquafeed production reached 58 million tonnes consuming 4.1 million tonnes of fishmeal and 1.7 million tonnes of fish oil, while swine and poultry starter feeds utilized additional 800000 tonnes of fishmeal for gut health and immune development in young animals. Poultry broiler starter rations incorporating fishmeal demonstrate enhanced feathering uniformity and reduced leg problems. Unlike fertilizer or pharmaceutical applications where marine ingredients compete with synthetic alternatives animal feed sector values complex matrix of amino acids fatty acids micronutrients and bioactive compounds that cannot be replicated through blending isolated nutrients creating systemic dependency embedded in decades of nutritional research and formulation practice.
The pharmaceutical and nutraceutical applications segment is esteemed to grow at a fastest CAGR of 13.6% throughout the forecast period with the clinical evidence expansion regulatory approvals and aging population health needs. The accumulating clinical trial data validating therapeutic efficacy of prescription grade omega 3s for cardiovascular metabolic and neurological conditions expanding addressable patient populations beyond general wellness supplementation. As per the ClinicalTrials.gov, registry shows 340 active clinical trials investigating EPA and DHA for Alzheimer’s depression diabetic retinopathy and inflammatory bowel disease as of 2024, representing pipeline expansion that could unlock additional billion-dollar indications if phase III endpoints are met. Aging demographics in Japan, Europe, and North America increase prevalence of chronic conditions responsive to omega 3 therapy with WHO projecting 2.1 billion people over age 60 by 2030, creating structural demand tailwind independent of discretionary supplement spending cycles.
REGIONAL ANALYSIS
Asia Pacific Fishmeal And Fish Oil Market Analysis
Asia Pacific was the largest contributor in the global fishmeal and fish oil market by accounting for 48.3% of share in 2025 with the dominant aquaculture production concentrated feed manufacturing base and growing middle class protein demand. According to study, Asia Pacific aquaculture output reached 68.4 million tonnes in 2024 with fed species requiring 3.2 million tonnes of fishmeal and 1.3 million tonnes of fish oil annually representing consumption volumes 3 times larger than any other region. However, regional supply deficit creates price vulnerability and currency exposure during El Niño induced Peruvian quota reductions triggering panic buying and inventory hoarding behaviors that amplify volatility.
Latin America Fishmeal And Fish Oil Market Analysis
Latin America was ranked second by holding 22.2% of the global fishmeal and fish oil market share in 2025 with the dual role as world’s primary marine ingredient producer through Peruvian and Chilean reduction fisheries and significant aquaculture consumer through expanding salmon and shrimp industries. Brazilian tilapia and shrimp farming expansion to 850000 tonnes combined output in 2024, drives additional 180000 tonnes of fishmeal demand met through domestic byproduct recovery and Paraguayan river fish imports, as per the study. Regional climate vulnerability remains acute, as evidenced by the 2023 El Niño event which slashed Peruvian anchoveta biomass by 40% and triggered immediate emergency quota cuts alongside global commodity price spikes.
Europe Fishmeal And Fish Oil Market Analysis
Europe fishmeal and fish oil market was ranked second by accounting for 11.3% of the share in 2025 with the premium aquaculture focus stringent sustainability standards and advanced byproduct valorization infrastructure rather than primary reduction fishery dominance. Premium positioning of European salmon and trout in global markets enables absorption of higher ingredient costs associated with certification and traceability requirements creating stable demand for compliant suppliers, while excluding uncertified sources regardless of price advantage.
North America Fishmeal And Fish Oil Market Analysis
North America fishmeal and fish oil market growth is likely to grow with an anticipated CAGR in next coming years with activity concentrated in US menhaden reduction fishery Canadian salmon aquaculture and growing pet food and nutraceutical demand segments. Menhaden fishery operates under interstate commission management with state level caps creating political tension between reduction industry and recreational fishing conservation groups influencing quota allocations independent of biological stock assessments. Trade disputes with Canada over softwood lumber occasionally spill into seafood tariffs creating temporary supply disruptions but USMCA framework provides dispute resolution mechanisms limiting prolonged market access barriers. Region’s diversified end use base provides resilience against single sector downturns, while regulatory stability attracts long term investment in byproduct recovery and omega 3 refining capacity.
Middle East and Africa Fishmeal And Fish Oil Market Analysis
Middle East and Africa fishmeal and fish oil market growth is driven by the aquaculture expansion and selective Gulf State investments in food security. Gulf Cooperation Council states including Saudi Arabia and UAE invested in aquaculture projects between 2020 and 2024, as part of food security diversification strategies creating new demand centers but lacking domestic marine ingredient production capacity forcing import dependency. Currency volatility in Egypt South Africa and Morocco creates procurement uncertainty and inflationary pressures on feed costs limiting aquaculture expansion pace despite favorable climate and fundamentals. Infrastructure deficits in cold chain processing and port logistics constrain byproduct recovery efficiency leaving significant valorization potential unrealized across region’s growing seafood processing sector.
COMPETITIVE LANDSCAPE
Competition in the fishmeal and fish oil market features stratified rivalry between large, integrated Peruvian and Chilean producers, specialized Nordic and North American operators, and emerging byproduct valorization companies, each pursuing distinct paths toward value creation and risk mitigation. Integrated reduction fishery players compete on scale, cost efficiency, and certification breadth, leveraging decades of infrastructure investment and quota access to dominate commodity volumes, while facing ecological and regulatory constraints limiting growth. Specialized operators in Norway, Denmark, Canada, and the United States differentiate through product quality, functional specifications, and niche market focus, serving pet food, nutraceutical, and pharmaceutical segments where technical performance outweighs price sensitivity, creating defensible margins. Byproduct recovery companies gain share through circular economy alignment, predictable supply tied to aquaculture growth, and traceability advantages, appealing to sustainability-conscious buyers seeking alternatives to wild-caught ingredients.
KEY MARKET PLAYERS
The fishmeal and fish oil market is enhanced and competitive, with countless players. It is dominated by different players, depending upononir core abilities. The central members in this market are
- FMC Corporation (U.S.)
- Copeinca SAC
- TASA (Tecnológica de Alimentos SA)
- Austevoll Seafood ASA (Norway)
- Croda International Plc. (U.K.)
- Oceana Group Limited (South Africa)
- Omega Protein Corporation (U.S.).
Top Players In The Market
- Copeinca SAC maintains extensive involvement in the fishmeal and fish oil market as one of Peru’s largest integrated marine ingredient producers operating multiple processing plants along the Pacific coast with dedicated anchoveta reduction facilities. Copeinca strengthened market position by achieving Marine Stewardship Council certification for anchoveta sourcing enabling access to premium European and Asian buyers requiring verified sustainability credentials. Recent actions include expanding byproduct recovery capacity at salmon processing partnerships in southern Chile diversifying raw material base beyond wild catch dependency. These initiatives demonstrate commitment to operational excellence and supply chain resilience creating competitive advantages through quality differentiation and regulatory compliance that transcend commodity pricing cycles, while positioning company to capture value from circular economy trends reshaping global marine ingredient procurement standards.
- TASA contributes significantly to the fishmeal and fish oil market as Peru’s leading exporter and technological innovator operating six production facilities with combined annual capacity exceeding 400000 tonnes of fishmeal and 120000 tonnes of fish oil. The company recently launched ProFish branded specialty ingredients targeting pet food and nutraceutical segments with customized particle sizes oxidation stability specifications and traceability documentation meeting stringent customer requirements beyond commodity feed grades. TASA strengthened market position by implementing blockchain enabled traceability platform providing real time vessel tracking processing parameters and laboratory certificates to buyers enhancing transparency and trust in supply chain integrity. Recent actions include acquiring minority stake in Norwegian byproduct processor securing access to high quality salmon waste streams and diversifying geographic sourcing away from El Niño vulnerable Peruvian waters.
- Omega Protein Corporation plays vital role in fishmeal and fish oil market as North America’s primary menhaden reduction operator managing vertically integrated fleet harvesting and four processing facilities along US Atlantic and Gulf coasts producing food grade and industrial marine ingredients. Omega Protein strengthened position by expanding direct sales relationships with major pet food manufacturers and nutraceutical brands bypassing commodity traders to capture higher margins through technical service and customized formulation support. Recent actions, include investing in menhaden stock assessment research partnerships with academic institutions supporting science based quota management that ensures long term resource sustainability and regulatory stability.
Top Strategies Used By Key Market Participants
Key players in the fishmeal and fish oil market employ vertical integration strategies, controlling fishing fleets, processing facilities, and distribution networks to secure raw material access, ensure quality consistency, and capture margin across the value chain, rather than relying on spot market purchases subject to quota volatility and price spikes. Companies pursue sustainability certification, including MSC, ASC, and MarinTrust, to maintain market access in regulated jurisdictions and meet corporate procurement mandates from multinational feed manufacturers, retailers, and brand owners requiring verified, responsible sourcing documentation. Geographic diversification, through investments in multiple countries and hemispheres, reduces exposure to regional ecological shocks like El Niño or regulatory changes affecting single fishery dependence, enabling continuous supply assurance for contract customers. Product differentiation, via specialized refining, encapsulation, and functional ingredient development, targets premium segments in pet food, nutraceuticals, and pharmaceuticals, where performance attributes justify price premiums over commodity feed grades, insulating revenues from volume-driven competition. Strategic partnerships with aquaculture producers and seafood processors secure byproduct supply streams independent of wild catch quotas, while aligning with circular economy narratives valued by ESG-focused investors and consumers. Technological investment in low-temperature processing, enzymatic hydrolysis, and analytical capabilities improves yield, quality, and contaminant removal, creating competitive moats through proprietary know-how difficult for new entrants to replicate without substantial capital and validation timelines.
MARKET SEGMENTATION
This global fishmeal and fish oil market research report is segmented and sub-segmented into the following categories.
By Source
- Salmon and Trout
- Marine Fish
- Crustaceans
- Tilapia
- Carps
By Application
- Aquaculture and Aquatic Feeds
- Animal Feed, Fertilizers
- and Pharmaceuticals
By Livestock
- Aquatic Animals
- Swine
- Poultry
- Cattle
- Pets
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East and Africa