- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$35.51 BnMarket Estimate, 2026
$36.61 BnMarket Forecast, 2034
$46.74 BnCAGR, 2026–2034
3.10%Executive Summary: Global Hydronic Control Market
- Market Scope: Comprehensive market assessment of the global hydronic control sector, analyzing equipment categories (actuators, valves, control panels, flow controllers), installation types (new installation vs. retrofit/modernization), end-user sectors (residential, commercial, industrial), and regional dynamics across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa.
- Market Valuation: Valued at USD 35.51 billion in 2025, reaching USD 36.61 billion in 2026, and projected to expand up to USD 46.74 billion by 2034, growing at a steady CAGR of 3.10% throughout the forecast period from 2026 to 2034.
- Primary Growth Drivers: Escalating global construction boom and rapid urbanization (particularly across APAC and the Middle East), stricter low-carbon and zero-carbon building energy-efficiency regulations, and rising demand for optimized HVAC operations in large commercial and industrial facilities.
Key Market Segment Metrics
| Category | Leading Segment (Base Year Position) | Fastest-Growing / High-Impact Segment |
|---|---|---|
| By Equipment & Installation | Valves & Actuators / New Installations (dominant baseline shares anchored by essential fluid regulation, BMS system interfacing, and early-stage building design integration) | Flow Controllers & Retrofit Installations (high-impact segments driven by green building upgrades, district heating efficiencies, and modernization IoT rollouts) |
| By Sector & Region | Commercial & Industrial Sectors / North America & APAC (leading baseline volumes driven by high baseline energy consumption in large facilities and robust urban construction activity) | Residential Sector & Middle East / Africa (fast-expanding areas propelled by public-private infrastructure partnerships and government-backed energy conservation mandates) |
Major Market Players & Market Structure
Market Structure: Highly competitive global landscape featuring prominent HVAC, automation, and fluid control conglomerates focusing on pressure-independent control valves, compact motorized actuators, and smart building integration.
Key Companies: Danfoss, Schneider Electric, Siemens, Johnson Controls, IMI, Caleffi S.p.a., GIACOMINI S.P.A., BELIMO Holding AG, Flamco, Spirotech BV, Honeywell International Inc., CAREL INDUSTRIES S.p.A., Grainger, Inc., Oventrop GmbH & Co. KG, Reflex Winkelmann GmbH, and Controlled Hydronics Inc.
Global Hydronic Control Market Size
The global hydronic control market size was valued at USD 35.51 billion in 2025 and is anticipated to reach USD 36.61 billion in 2026 to reach USD 46.74 billion by 2034, growing at a compound annual growth rate (CAGR) of 3.10% during the forecast period from 2026 to 2034.

In heating and cooling systems, Hydronics refers to the use of a liquid heat-transfer medium. Water, glycol, or mineral oil are commonly used as working fluids. Steam and hot-water radiators are two of the oldest and most prevalent forms. A hydronic system may comprise both a chilled and a heated water loop to offer both heating and air conditioning in large-scale commercial buildings, such as high-rise and campus facilities, as in the past.
Efforts are being undertaken all across the world to preserve energy and conserve our planet's resources. The public's knowledge of environmental issues has risen dramatically in recent years. The competition to become more energy efficient is a major motivator, particularly in the new construction industry, where low-carbon legislation is being implemented. The push to attain zero-carbon buildings and households is projected to increase shortly, indicating the hydronic control market's tremendous development potential. Various new laws are being enacted across the world to encourage the adoption of energy-efficient devices.
To guarantee that the hydronic control systems work smoothly and have a longer life period, trained and competent employees are necessary for maintenance and repair. Trained professionals are also required to monitor and enhance the building's systems infrastructure. Furthermore, consumers have issues with proprietary building automation software since these systems can only be repaired by the system vendor's own service experts. Because of the scarcity of such professionals in emergency situations, building owners are hesitant to use hydronic control systems, limiting the market's growth.
MARKET DRIVERS
Hydronic systems are the mainstay of the hydronic controls business. The rise in the building industry throughout the world is driving up demand for hydronic controls.
The rapid urbanization of APAC's emerging countries has resulted in a tremendous need for hydronic controls. For example, in India, planned initiatives linked to smart cities, bullet trains, and infrastructure development are fueling the expansion of the hydronic systems and controls market. The market for hydronic systems is driven by population increase and urbanization, and the market for hydronic controls follows suit.
The Middle East's construction sector is being boosted by an increasing number of public-private partnership (PPP) projects. The development of the Tarif International Airport in Saudi Arabia is a perfect example of a PPP project, as it entails the construction of an airport capable of handling 5 million people per year. Several development projects are underway in Qatar in preparation for the FIFA World Cup in 2022. Construction projects in the UAE that were put on hold owing to the global economic crisis have now been completed. As a result of the construction boom, demand for hydronic systems is increasing, propelling the hydronic controls industry forward.
MARKET RESTRAINTS
The hydronic sector is expected to develop at a breakneck pace, but trained personnel are needed at all stages of the value chain. To perform effectively and avoid failure, hydronic systems require delicate tweaking and specific manufacturing of parts during installation. If the installation is not done by a competent professional, the end-user will either have to spend more money on repairs in the long run or the system will not work effectively. The system is projected to incur increased expenditures as a result of the need for trained manpower. Hydronic equipment installation prices in residential, commercial, and industrial applications are determined by a variety of factors. For example, in a residential application, the cost of installing all hydronic equipment is determined by the size of the home, the kind of equipment, and the equipment's SEER value. As a result, the hydronic control market's adoption and expansion are hampered by the need for experienced workers, as well as high installation prices.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 3.10% |
| Segments Covered | By Equipment, Installation Type, Sector, and Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Danfoss, Schneider Electric, Siemens, Johnson Controls, IMI, Caleffi S.p.a., GIACOMINI S.P.A., BELIMO Holding AG, Flamco, Spirotech BV, Honeywell International Inc., IMI plc, CAREL INDUSTRIES S.p.A., Grainger, Inc., Oventrop GmbH & Co. KG, Reflex Winkelmann GmbH, Controlled Hydronics Inc., and Memmert and Others. |
SEGMENTAL ANALYSIS
By Equipment Insights
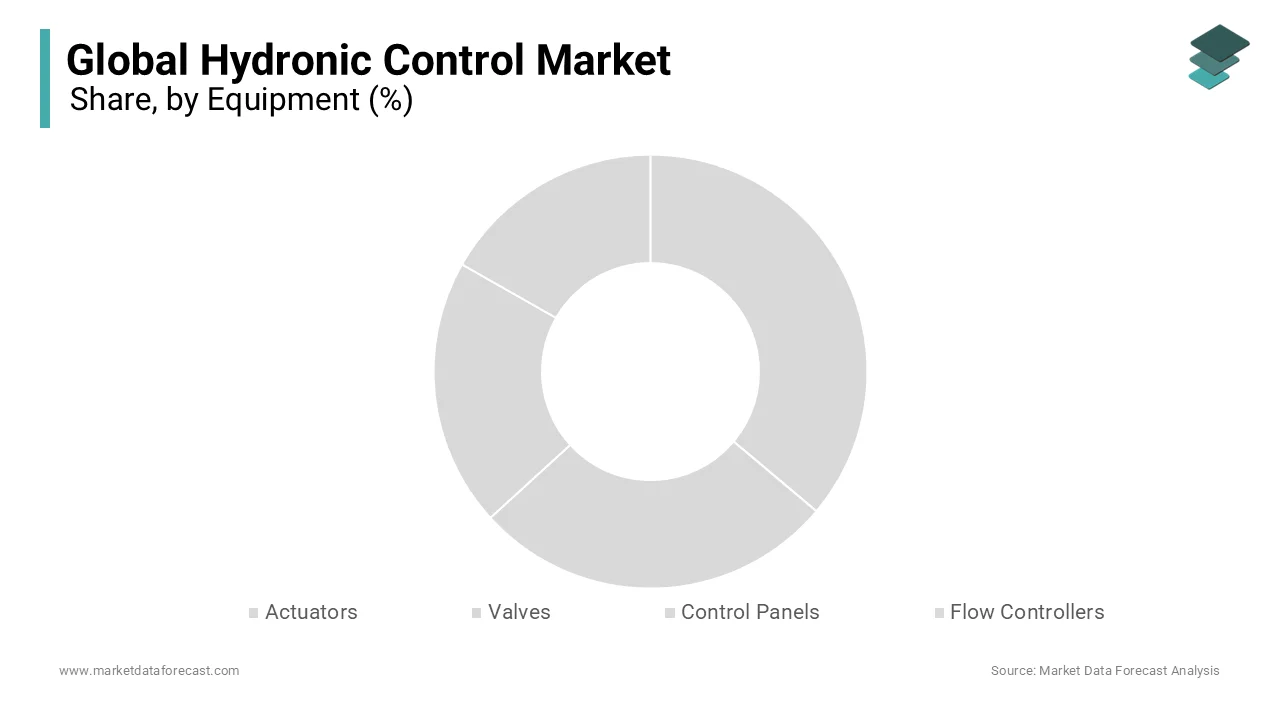
The actuators act as an interface between the mechanical system and the hydraulic control system. This device receives signals from the controllers and consequently controls valves and dampers in the hydraulic system. Through the building management system (BMS) and bus communication, the actuators can be accessed remotely. This saves time during the installation and commissioning of the system. The flow controller ensures that the correct flow is directed to the correct location to increase the efficiency of the hydraulic system. Automatic flow controllers are mainly used in district heating systems. The controller closes when the flow rate exceeds its preset position. These attributes translate into a high growth rate of the flow controllers during the forecast period.
By Installation Insights
The new facility offers advantages over renovations for the implementation of hydraulic control solutions at an early stage. The benefits help reduce the operating cost required to implement hydraulic control solutions. Upgrading new equipment to an old system is called an upgrade. The green building initiative and the measures taken to reduce the negative environmental effects caused by old hydraulic control systems are leading to the adoption of hydraulic controls in renovations. The adoption of IoT and smart technologies supports the growth of modernization facilities.
By Sector Insights
The industrial sector includes manufacturing and processing facilities. Energy consumption in industries is greater than that of residential or commercial installations; however, a significant amount of energy in industrial plants is used to process and manufacture machinery. Adopting hydraulic controls can help drive hydraulic systems efficiently while increasing business productivity. Through the use of hydraulic controls in warehouses, production areas, administrative offices, control rooms, and distribution centers, the water temperature can be maintained by industry standards. HVAC devices, such as air conditioners, consume almost 50% of the total energy supplied to a residential building. To achieve energy efficiency in a residential building, hydronic systems must be optimally managed. Various hydraulic control equipment, such as actuators, valves, relays, sensors, and thermostats, allows efficient use of energy. Hydronic and HVAC systems are assumed to consume a significant amount of energy for residential applications; thus, governments formulate regulations and act to promote the use of hydraulic controls.
REGIONAL ANALYSIS
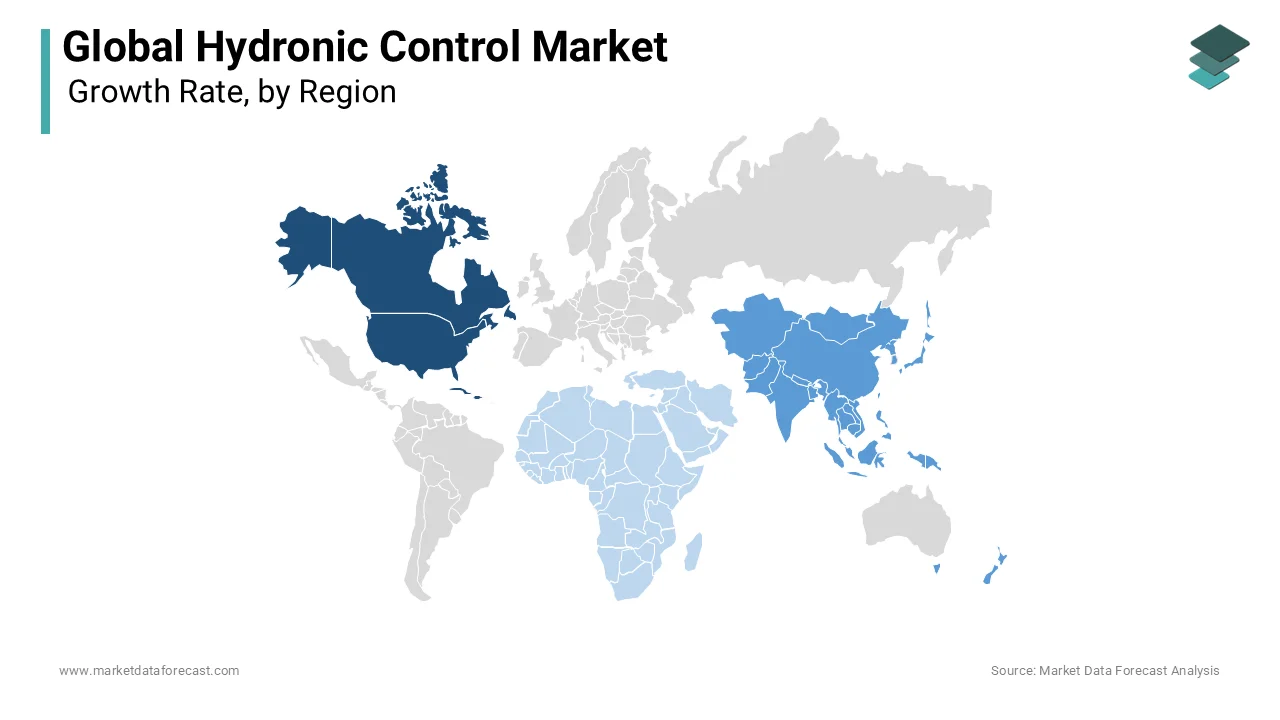
North America dominates the market for hydraulic drives due to the increasing growth of advanced infrastructure and the construction of residential and commercial buildings in this region. Among these regions, the Asia-Pacific could be the dominant region in the global hydraulic drives market due to the growth of the construction business in the region. In addition, increasing development and construction activities in developing countries in the Middle East and Africa are driving demand for hydraulic control and are likely to drive market growth.
KEY MARKET PLAYERS
Major Key Players in the Global Hydronic Control Market are
- Danfoss
- Schneider Electric
- Siemens
- Johnson Controls
- IMI
- Caleffi S.p.a
- GIACOMINI S.P.A
- BELIMO Holding AG
- Flamco
- Spirotech BV
- Honeywell International Inc
- CAREL INDUSTRIES S.p.A
- Grainger, Inc
- Oventrop GmbH & Co. KG
- Reflex Winkelmann GmbH
- Controlled Hydronics Inc.
RECENT MARKET NEWS
- The new Compact Axial VP140 arrangement pressure-free control valve adds to the current line of ball valve models by offering a small valve size with very powerful execution for long existence of exact and autonomous control of the pressure.
- Siemens presents another line of best-in-class actuators for small valves.
- Schneider Electric, the global specialist in energy management and automation, today announced the debut of Pressure Independent Balancing and Control Valves (PIBCV) in North America to enhance valve functionality and temperature control in buildings.
- Danfoss has reported its association with Hydronic Technology, Inc., which will give the provinces of Louisiana and Mississippi educated deals and administration regarding the Danfoss hydronic comfort controls portfolio.
MARKET SEGMENTATION
This research report on the global hydronic control market has been segmented and sub-segmented based on equipment, installation type, sector, and region.
By Equipment
- Actuators
- Valves
- Control Panels
- Flow Controllers
- Others
By Installation Type
- New Installation
- Retrofit Installation
By Sector
- Residential
- Commercial
- Industrial
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East and Africa