- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$21.94 BnMarket Estimate, 2026
$24.92 BnMarket Forecast, 2034
$69.13 BnCAGR, 2026–2034
13.6%Global Industrial Robotics Market Size, Share & Growth Analysis (2026–2034)
- Market Scope: Comprehensive global industry analysis covering structural robot types (Articulated, Cartesian, SCARA, Cylindrical), multi-industry deployment verticals, government-backed automation incentives, and smart manufacturing advancements.
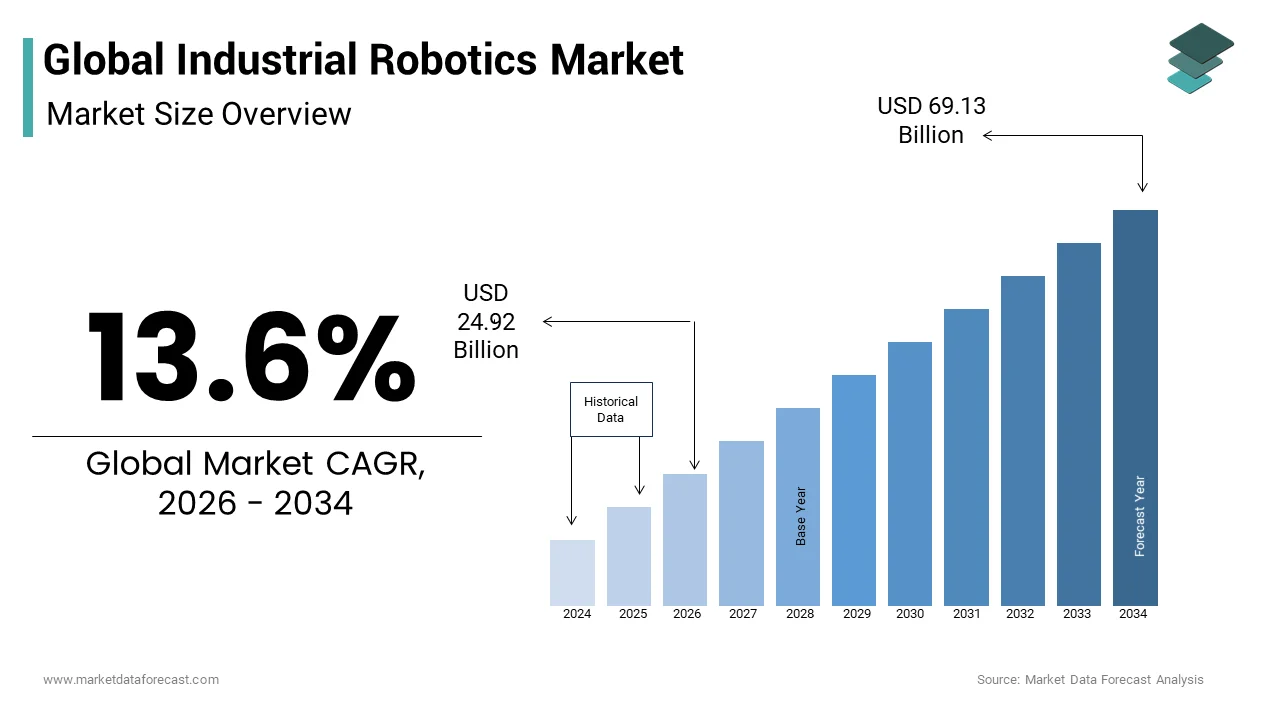
- Market Valuation: Valued at USD 21.94 billion in 2025, estimated at USD 24.92 billion in 2026, and projected to reach USD 69.13 billion by 2034, growing at a robust compound annual growth rate (CAGR) of 13.6% during the forecast period.
- Primary Growth Drivers: Public-private manufacturing initiatives (such as the ARM Institute and production-linked incentives), rapid integration of AI and machine vision with Industry 4.0, and rising automation demands across the automotive and electronics sectors.
Global Industrial Robotics Market Segment Metrics (2026–2034)
| Market Category | Leading Market Segment (2025 Position) | Fastest-Growing / High-Potential Segment |
|---|---|---|
| By Type | Articulated Robots (leads revenue share owing to multi-axis flexibility, payload capacity, and high adaptability in welding and heavy handling) | Cylindrical Robots (projected to record the fastest growth trajectory over the forecast horizon) |
| By End-User Industry | Automotive & Electrical/Electronics (traditionally anchor deployment volume due to high demand for precision assembly and quality control) | Food & Beverages (scaling up rapidly through streamlined sorting, packaging, and high-speed processing lines) |
| By Region | Asia-Pacific (dominates global revenue backed by early technology adoption, strong financial backing, and strategic government directives like "Made in China") | Latin America, Middle East & Africa / LAMEA (emerging as high-potential growth regions due to expanding industrial infrastructure) |
Major Industrial Robotics Manufacturers & Market Structure
Market Structure: Highly consolidated high-tech manufacturing sector dominated by international automation conglomerates competing on proprietary controller software, AI-driven precision, collaborative safety systems (cobots), and strategic cross-border acquisitions.
Key Market Leaders Profiled: Kuka AG, Kawasaki Heavy Industries Ltd, Fanuc Corporation, ABB Ltd, Denso Corporation, Mitsubishi Electric Corporation, Rockwell Automation Inc., Bosch GmbH, Yaskawa Electric Corporation, and Toshiba Corporation.
Global Industrial Robotics Market Size
The global industrial robotics market size was valued at USD 21.94 billion in 2025 and is anticipated to reach USD 24.92 billion in 2026, and to reach USD 69.13 billion by 2034, growing at a CAGR of 13.6% during the forecast period from 2026 to 2034.
An industrial robot is a mechanical device that is programmed to execute activities connected to industrial production automatically. These robots can be reprogrammed, and the program may be altered as many times as needed, depending on the application. Industrial robots aid in improving productivity while lowering costs and generating high-quality goods in automation applications. Drive, end-effector, robotic manipulators, sensors, and controls make up the majority of industrial robots. The robotic controller is the robot's brain that assists in issuing commands. Microphones and cameras in robot sensors keep the robot aware of the industrial surroundings. The robotic manipulator is the robot's arm that assists it in moving and positioning, while the end effectors assist in interacting with the workpieces. Collaborative, cartesian, SCARA, cylindrical, and articulated robots are five types of robots used in industry. The degree of freedom of movement, size requirements, and payload capacity all influence the type of robot chosen. Industrial robots aid in the optimization of production processes for a healthy and efficient outcome. These features further increase the Industrial Robotics Market growth.
MARKET DRIVERS
The primary driver fueling the global industrial robotics market is government initiatives and public–private partnerships to lessen the impact of COVID-19. The Advanced Robotics for Manufacturing (ARM) Institute is a public-private collaboration that aims to boost American manufacturers' competitiveness by cooperating and creating new robotics solutions.
It is funded by the US Department of Defense. The institution has requested speedy and high-impact robotics projects to provide the quick response required for the COVID-19 pandemic. The Indian government has granted a Rs 1.45 trillion incentive package by extending the production-linked incentive (PLI) plan to eleven industrial sectors, with a particular focus on the car and vehicle component industries. As part of its China exit program, the Japanese government has set aside USD 221 million in subsidies for Japanese enterprises to relocate to India and other locations. The French government has provided financial assistance to businesses by guaranteeing the repayment of certain qualifying loans up to USD 358 billion under its State Guarantee scheme. To combat the consequences of the COVID-19 outbreak, Indonesia launched two stimulus packages. The first package, worth $725 million, was announced in February 2020, while the second, at $8 billion, was announced in March 2020. The second stimulus package was introduced to safeguard the economy and small and medium-sized businesses (SMEs), notably in the manufacturing sector. The increased use of automation in the automobile production process, as well as the integration of AI and digitalization, is driving up demand for industrial robots in the industry.
MARKET RESTRAINTS
A robotic automation project can be challenging, particularly for companies that have never completed one before. Not only is a large financial investment necessary for the robot itself, but also for its integration, programming, and maintenance. A bespoke integration may be necessary in some circumstances, which will increase the total expenses. Due to a shortage of space and infrastructure, robot deployment may not always be practicable. Because SMEs are often involved in low-volume production, obtaining a return on investment (ROI) can be challenging.
The difficulty is demonstrated by the presence of enterprises with seasonal or variable production schedules. Fast-changing consumer tastes will necessitate regular robot retraining since items are changed on average once a year. Over-automation can sometimes be problematic. Compared to its Japanese competitors, the US automobile industry began with a higher level of mechanization. Cost overruns arose when product lines and consumer demand altered over time, and many robots became obsolete or obsolete. A company's operating costs may not always be reduced by replacing human personnel.
A collaborative robot system can range in price from $3,000 to $100,000. A commercial robotic system might cost anything from $15,000 to $150,000. Automation is an expensive investment for SMEs, especially when they are involved in low-volume manufacturing, due to the cost of industrial robots, integration fees, and peripherals such as end-effectors and vision systems. Therefore, these factors further decrease the global Industrial Robotics Market size.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 13.6% |
| Segments Covered | By Type, End-user Industry, and Region |
|
Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
|
Market Leaders Profiled | Ericsson, Kuka AG, Kawasaki Heavy Industries Ltd, Fanuc Corporation, ABB Ltd, Denso Corporation, Mitsubishi Electric Corporation, Rockwell Automation, Inc, Bosch GmbH, Yaskawa Electric Corporation, Toshiba Corporation |
SEGMENTAL ANALYSIS
By Type Insights
The articulated segment led the Industrial Robotics Market in terms of revenue in 2020. However, the cylindrical segment is predicted to develop at the fastest CAGR throughout the forecast period. The electrical and electronics category led the market in 2020, according to the industry, while the food and drinks segment is predicted to grow at the fastest rate shortly. In terms of revenue, the materials handling category dominated the market in 2020; however, the painting & dispensing sector is expected to grow at the fastest rate during the forecast period. Asia-Pacific generated the most revenue in 2020, while LAMEA is expected to grow at the fastest rate over the projection period.
By End-user Industry Insights
The fastest-growing category is electrical and electronics, with growth expected to accelerate throughout the evaluation period in the Industrial Robotics Market. Furthermore, the automobile sector has been vying to become the largest end-user of Industrial Robots. The hardware sector has embraced the use of mechanical robots since quality and accuracy are two of the most important aspects of an electronic production facility. The rising range of activities that robots can accomplish, notably in the assembly of electronic equipment and components, is one of the main reasons why electrical and electronic is the largest market for Industrial Robots.
REGIONAL ANALYSIS
The Industrial Robotics market was dominated by the Asia Pacific, followed by Europe and North America. Market development is likely to be fueled by high and early adoption of breakthrough technologies in countries like India and China. Because of its strong financial position, it can make major expenditures in cutting-edge equipment and technology to maintain smooth company operations. The Chinese government's "Made in China 2025" plan aims to increase the competitiveness of Chinese businesses through automation.
North America is anticipated to hold a steady CAGR in the global industrial robotics market during the forecast period because of the introduction of Industry 4.0. On the other hand, Europe is trying to exhibit significant growth in the global industrial robotics market, owing to the manufacturers who are working on collaborative robots.
KEY MARKET PLAYERS
Major Key Players in the Global Industrial Robotics Market are
- Kuka AG
- Kawasaki Heavy Industries Ltd
- Fanuc Corporation
- ABB Ltd
- Denso Corporation
- Mitsubishi Electric Corporation
- Rockwell Automation, Inc.
- Bosch GmbH
- Yaskawa Electric Corporation
- Toshiba Corporation
RECENT MARKET NEWS
- Yaskawa Electric Corporation purchased more shares of Doolim-Yaskawa Co., Ltd. in January 2022 to expand its sealing system and robotic painting businesses.
- ABB announced the purchase of ASTI Mobile Robotics Group (ASTI) in July 2021, expanding its robotics and automation capabilities and becoming the first to offer a comprehensive profile for the next generation of flexible automation.
MARKET SEGMENTATION
This research report on the global industrial robotics market has been segmented and sub-segmented based on type, end-user industry, and region.
By Type
- Articulated
- Cartesian
- SCARA
- Cylindrical
- Others
By End-user Industry
- Automotive
- Electrical & Electronics
- Chemical Rubber & Plastics
- Machinery
- Food & Beverages
- Others
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- The Middle East and Africa