- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$562.3 MnMarket Estimate, 2026
$595.6 MnMarket Forecast, 2034
$943.6 MnCAGR, 2026–2034
5.92%Executive Summary: Latin America Champagne Market
- Market Scope: Comprehensive Latin America champagne market analysis covering grape varieties, product types, distribution channels, flavor profiles, and country-level leadership frameworks.
- Market Valuation: Valued at USD 562.35 million (2025), estimated at USD 595.64 million (2026), and projected to reach USD 943.64 million by 2034, registering a robust CAGR of 5.92% (2026–2034).
- Primary Growth Drivers: Rising economic growth in developing economies, growing cultural acceptance of alcohol consumption, increased penetration of premium bars and lounge cultures catering to affluent clientele, and the introduction of diverse flavored champagnes (such as fruity, candy, and nutty variants).
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Grape Used | Pinot Noir and Pinot Meunier (primarily used black grapes for authentic champagne production) | Chardonnay (driven by high demand for white-grape luxury blends) |
| By Type | Prestige Cuvee (representing luxury offerings for upscale social environments) | Rosé Champagne (surging in popularity across social gatherings) |
| By Distribution Channel | Supermarkets/Hypermarkets (anticipated to hold a relatively high share in retail sales) | Online Stores (contributing significantly to market expansion over the forecast period) |
| By Flavour | Brut (identified as the most popular style today with low sugar levels and dry taste) | Fruity Flavours (including apple, pear, citrus, and strawberry variants gaining widespread consumer traction) |
| By Region / Country | Brazil and Mexico (leading consumer markets within Latin America) | Argentina and Rest of Latin America (expanding through rising investments, tourism, and growing retail networks) |
Major Market Players & Market Structure
Market Structure: Competitive regional landscape featuring prominent global champagne houses and beverage conglomerates competing on brand prestige, distribution reach in luxury hospitality, and diverse flavor portfolios.
Key Companies: Moët Hennessy USA, LANSON-BCC, Vranken - Pommery Monopole, Champagne Laurent-Perrier S.A.S, Pernod Ricard, Rémy Cointreau, Centre Vinicole Champagne Nicolas Feuillatte, Martel, Louis Roederer, and Taittinger.
 Download Free Sample Report
Latin America Champagne Market Size
The Latin America champagne market size was valued at USD 562.35 million in 2025 and is projected to reach USD 943.64 million by 2034 from USD 595.64 million in 2026, growing at a CAGR of 5.92%.
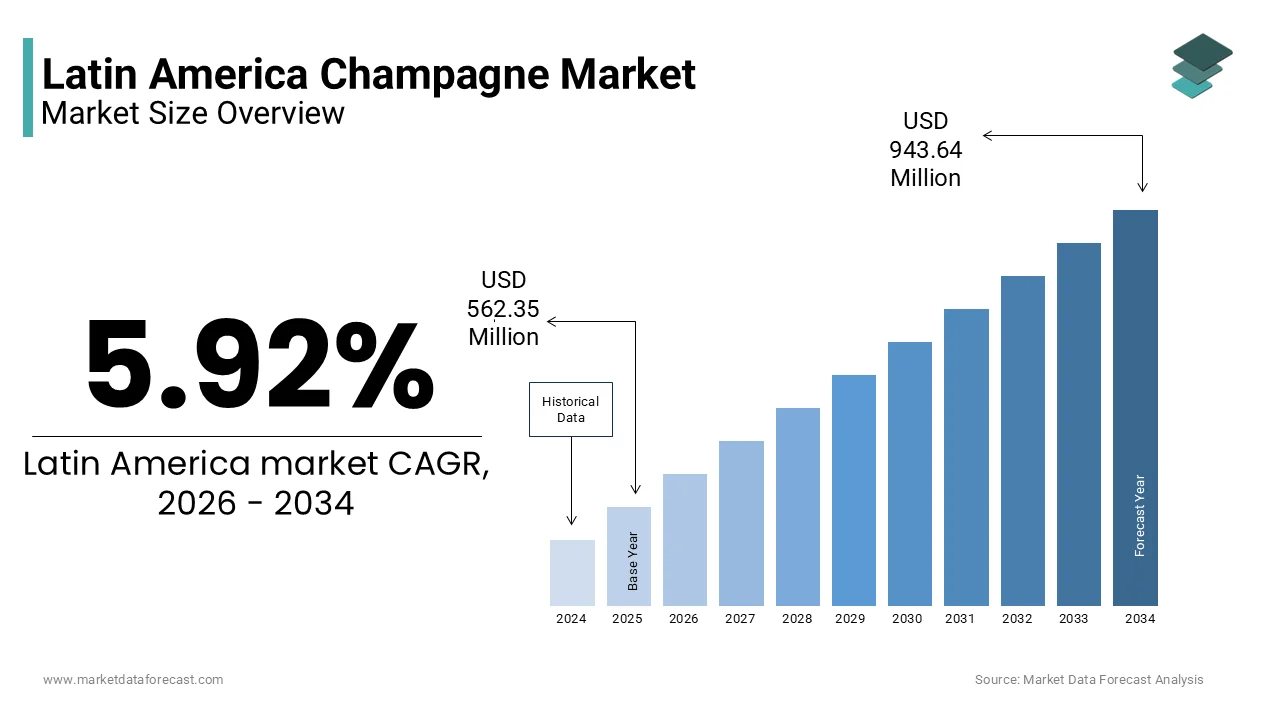
The Latin America champagne market comprises the importation and consumption of protected designation of origin sparkling wines from the Champagne region of France within countries such as Brazil, Mexico, and Argentina. According to the Comité Champagne, exports to Latin America reached 1.2 million bottles in 2024, reflecting a steady demand for premium celebratory beverages among affluent urban populations. This market is distinct due to its strong cultural association with festivities and social gatherings rather than daily consumption habits. According to the World Tourism Organization, international tourist arrivals in major destinations like Cancun and Rio de Janeiro exceeded pre-pandemic levels in 2024, driving significant on-premise sales in luxury hotels and resorts. The definition encompasses strict adherence to French appellation laws, which limits supply and maintains exclusivity. Regulatory frameworks vary across nations, with some imposing high tariffs that restrict accessibility to elite segments. The market dynamics are heavily influenced by currency fluctuations and economic stability, which affect purchasing power for imported luxury goods. Distributors focus on building relationships with high-end retail chains and hospitality groups to ensure product visibility and availability in key metropolitan areas where disposable income supports premium beverage choices.
MARKET DRIVERS
Rising Urban Affluence Expands Consumer Base for Premium Goods
Rising urban affluence expands the consumer base for premium goods, which drives the Latin America champagne market expansion primarily. According to the Economic Commission for Latin America and the Caribbean, the middle class in the region has grown to include over 150 million people who possess greater disposable income for non-essential items. This demographic shift creates a larger pool of potential buyers who view champagne as a symbol of status and success during social milestones. According to the United Nations Human Settlements Programme, urbanization rates in countries like Colombia and Peru have surpassed 75%, leading to greater exposure to global lifestyle trends and international brands. Urban dwellers are more likely to frequent venues where champagne is served and have easier access to specialized retail outlets. The desire to emulate global consumption patterns drives demand for authentic champagne over local sparkling alternatives. Financial inclusion initiatives also enable smoother transactions for high-value purchases, thereby removing barriers to entry for aspiring consumers who wish to participate in the luxury beverage culture prevalent in major cities.
Thriving Hospitality Sector Stimulates On-Premise Consumption
The thriving hospitality sector stimulates on-premise consumption, which significantly promotes the Latin America champagne market growth through increased demand in hotels, restaurants, and bars. According to the Inter-American Development Bank, investment in tourism infrastructure in countries like Mexico and the Dominican Republic grew by 12% in 2024, enhancing the capacity of luxury accommodations to serve premium beverages. High-end establishments prioritize champagne on their wine lists to attract affluent tourists and local elites seeking exclusive dining experiences. According to the World Travel and Tourism Council, the contribution of travel and tourism to the GDP of Brazil reached 8% in 2024, reflecting robust spending on hospitality services, including fine dining and beverage pairings. This economic impact translates directly into higher orders for champagne in upscale venues catering to international visitors. Hotel chains and resort groups invest in extensive wine cellars and sommelier services to enhance guest satisfaction, which further stimulates demand for prestigious labels. The prestige associated with champagne aligns perfectly with the aspirational nature of luxury travel, making it an indispensable component of the high-end hospitality offering in key destinations across the region.
MARKET RESTRAINTS
High Import Tariffs and Taxation Inflate Retail Prices
High import tariffs and taxation inflate retail prices hampers the expansion of the Latin America champagne market by making the product inaccessible to all but the wealthiest consumers. According to the World Customs Organization, average import duties on alcoholic beverages in countries like Brazil and Argentina exceed 100% of the product value to protect local industries and generate revenue. These excessive taxes make champagne a prohibitively expensive luxury item that limits mass-market adoption. According to the International Monetary Fund, fiscal policies in several Latin American nations impose additional excise taxes and value-added taxes on alcohol, which compound the final cost to the consumer. The resulting high-price points suppress volume growth and restrict market penetration to ultra-premium segments. Distributors struggle to maintain viable business models when a significant portion of the retail price consists of taxes rather than product value. Currency devaluation in some economies further exacerbates the cost burden for importers who must pay suppliers in stable currencies like the euro or dollar. This financial pressure restricts the ability of brands to invest in marketing and distribution infrastructure, thereby stifling market development.
Economic Volatility Disrupts Purchasing Power and Demand
Economic volatility disrupts purchasing power and demand, which severely restrains the Latin America champagne market by creating uncertainty for both importers and consumers. According to the World Bank, inflation rates in countries like Venezuela and Argentina have reached double digits in recent years, eroding household savings and reducing discretionary spending. This economic instability forces consumers to prioritize essential goods over luxury items like champagne, leading to declined sales volumes. According to the Central Bank of Brazil, exchange rate fluctuations against the euro have increased import costs by 15% in 2024, making it difficult for distributors to maintain stable pricing strategies. Sudden price increases can dampen consumer demand and lead to inventory accumulation if sales do not meet expectations. The unpredictability of economic conditions discourages long-term investment in brand building and market expansion activities. Importers may reduce their product ranges or switch to cheaper alternatives to mitigate risk, thereby limiting the availability of premium champagne brands. This economic fragility undermines the reliability of the supply chain and threatens the sustainability of businesses operating in the luxury beverage sector.
MARKET OPPORTUNITIES
Expansion of E-Commerce Platforms Enhances Accessibility
The expansion of e-commerce platforms enhances accessibility, which is a significant opportunity for the Latin America champagne market by reaching consumers beyond traditional retail hubs. According to the United Nations Conference on Trade and Development, e-commerce sales in Latin America grew by 20% annually as internet penetration and smartphone usage increase among urban populations. Online retailers specializing in gourmet foods and beverages can reach consumers in remote areas where physical stores do not stock premium champagne. According to the Inter-American Development Bank, digital payment adoption in the region has doubled in the last five years, enabling seamless online shopping experiences for tech-savvy consumers. Digital platforms allow brands to provide detailed product information and pairing suggestions that educate buyers and enhance engagement. Home delivery services overcome logistical challenges associated with transporting fragile glass bottles by utilizing specialized packaging and courier networks. The ability to compare prices and read reviews empowers consumers to make informed decisions and discover new brands. E-commerce also enables targeted marketing campaigns that reach specific demographics interested in luxury lifestyles, thereby driving conversion rates.
Growing Wine Culture Educates Consumers on Quality
The growing wine culture educates consumers on quality, which creates an opportunity for the Latin America champagne market to differentiate itself from lower-quality sparkling wines. According to the International Organisation of Vine and Wine, wine consumption per capita in countries like Uruguay and Chile has increased by 5% annually as consumers develop more sophisticated palates. This trend drives interest in understanding the differences between méthode traditionnelle champagnes and other sparkling wines. According to the Sommelier Association of Latin America, educational programs and wine festivals in major cities have raised awareness about the heritage and production methods of authentic champagne. Informed consumers are more willing to pay premium prices for products that offer superior quality and authenticity. Brands can leverage this knowledge gap by organizing tasting events and masterclasses that highlight the unique characteristics of their offerings. The association of champagne with expertise and refinement enhances its appeal among aspiring connoisseurs. This educational approach builds long-term loyalty and encourages repeat purchases as consumers seek to expand their sensory experiences.
MARKET CHALLENGES
Complex Logistics and Infrastructure Deficiencies Increase Costs
Complex logistics and infrastructure deficiencies increase costs challenges the Latin America champagne market by demanding sophisticated supply chain management to maintain product quality. According to the World Bank Logistics Performance Index, many countries in the region rank low in infrastructure quality due to inadequate transportation networks and inconsistent electricity supply for refrigeration. Champagne requires strict temperature control during storage and transit to prevent spoilage and preserve flavor profiles, which is difficult to guarantee in regions with frequent power outages. According to the Pan American Health Organization, supply chain disruptions in remote areas result in higher transportation costs and longer delivery times compared to global averages. Distributors must invest heavily in specialized vehicles and warehousing facilities equipped with climate control systems to meet industry standards. These capital expenditures raise operational costs, which are ultimately passed on to consumers in the form of higher prices. The risk of product damage during handling and transport further reduces profit margins and increases insurance premiums. Inadequate road networks in rural areas limit market reach to major urban centers, thereby restricting growth potential.
Competition from Local Sparkling Wines Limits Market Share
Competition from local sparkling wines limits market share and challenges the Latin America champagne market growth by offering cheaper alternatives with similar sensory profiles. According to the International Organisation of Vine and Wine, countries like Brazil and Argentina produce millions of liters of sparkling wine annually using traditional methods that appeal to price-sensitive consumers. These local products benefit from lower production costs and the absence of import tariffs, making them significantly more affordable than imported champagne. According to the Brazilian Wine Institute, domestic sparkling wine sales have grown by 10% annually as consumers seek value for money in the celebratory beverage category. The quality of local sparkling wines has improved significantly, narrowing the gap with entry-level champagnes in terms of taste and presentation. Marketing campaigns by local producers emphasize national pride and support for domestic industries, which resonates with patriotic consumers. This strong competition forces champagne brands to justify their higher price points through superior branding and exclusivity. Without clear differentiation, champagne risks losing relevance among mainstream consumers who prioritize affordability over prestige.
 REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 5.92% |
| Segments Covered | By Grape Used, Type, Distribution Channel, Flavour, and Region |
| Various Analyses Covered | Global, Regional, & Country Level Analysis; Segment-Level Analysis; DROC; PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | Latin America include Brazil, Argentina, Mexico, and the Rest of Latin America |
| Market Leaders Profiled | Moët Hennessy USA, LANSON-BCC, Vranken - Pommery Monopole, Champagne Laurent-Perrier S.A.S, Pernod Ricard, Rémy Cointreau, Centre Vinicole Champagne Nicolas Feuillatte, Martel, Louis Roederer, Taittinger |
SEGMENTAL ANALYSIS
By Grape Used Insights
The pinot noir segment led the market by holding the dominant share of the Latin American market share in 2025 because it provides the essential structure and body required for blends that appeal to local palates accustomed to robust flavors. According to the Comité Champagne, Pinot Noir constitutes approximately 38% of total vineyard plantings in the Champagne region, ensuring consistent supply for export markets, including Latin America. This dominance is driven by the grape's ability to impart red fruit notes and aging potential, which aligns with the preference for full-bodied sparkling wines in countries like Argentina and Brazil.
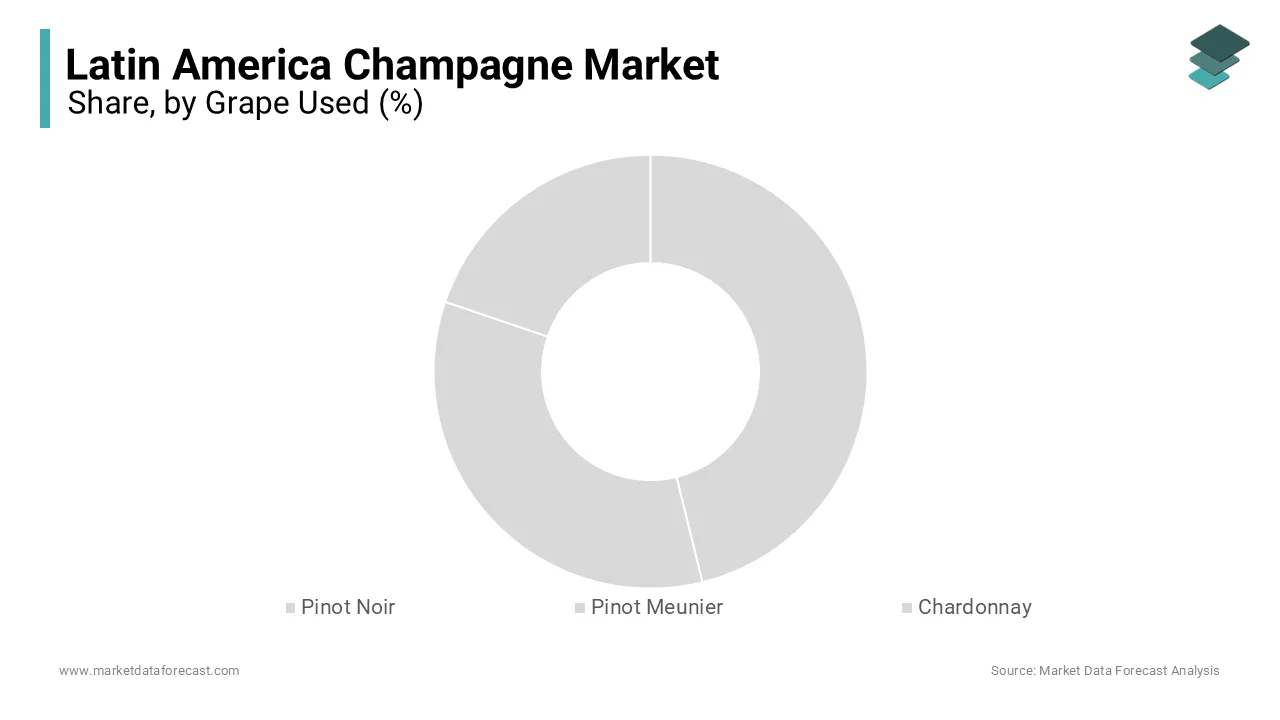
According to the International Organisation of Vine and Wine, global consumption of Pinot Noir dominant champagnes has remained stable with a 2% annual increase in premium segments, reflecting its enduring popularity among connoisseurs. The versatility of Pinot Noir allows producers to create both powerful non-vintage blends and elegant rosés, thereby catering to diverse consumer preferences across different demographic groups within the region. Distributors prioritize this variety because it forms the base of iconic brands that drive volume sales in duty-free outlets and luxury hotels. Its recognition as a noble grape variety enhances the perceived value of the final product, which justifies premium pricing in competitive retail environments.
By Type Insights
The prestige cuvée segment led the market by capturing 41.1% of the Latin American market share in2025 because it serves as the ultimate status symbol for high-net-worth individuals and corporate gifting in the region. According to the Luxury Institute, prestige champagne sales in Latin America accounted for 40% of total champagne revenue in 2024, reflecting the strong preference for top-tier brands among affluent consumers. This segment dominates because it aligns with the cultural importance of displaying wealth and success through exclusive products in social and business settings. According to the Mexican Business Magazine, corporate expenditure on luxury gifts in Mexico City increased by 8% in 2024, with prestige champagnes being a preferred choice for client appreciation and executive rewards. The limited production and high price point of these cuvées create an aura of exclusivity that appeals to consumers seeking differentiation from mass-market options. Hotels and fine dining establishments prominently feature prestige labels to attract discerning patrons who associate these brands with superior quality and service. The strong brand equity of houses like Dom Pérignon and Krug ensures consistent demand despite economic fluctuations, as loyal customers view these purchases as investments in social capital.
REGIONAL ANALYSIS
Brazil Market Analysis
Brazil dominated the market by capturing 36.9% of the regional market share in 2025 and is likely to maintain robust growth and stable expansion over the next few years due to a sophisticated consumer base and a strong culture of celebration. According to the Brazilian Wine Institute, the country imports over 400,000 bottles of champagne annually, driven by demand in major metropolitan areas like São Paulo and Rio de Janeiro. The vibrant nightlife and extensive hospitality sector create robust opportunities for premium beverage sales in upscale venues. According to the Central Bank of Brazil, despite currency fluctuations, the affluent segment continues to spend on luxury goods, including champagne for social gatherings and corporate events. The presence of international hotel chains and fine dining restaurants ensures wide availability and visibility for major brands. Local distributors have established efficient supply chains that cater to both retail and on-premise channels. The growing middle class in urban centers is increasingly exposed to global trends, which drives interest in authentic champagne over local sparkling alternatives. Government regulations on alcohol sales are relatively stable, providing a predictable operating environment for importers. The market benefits from a strong wine culture that values quality and origin, thereby supporting sustained growth for premium imports.
Mexico Market Analysis
Mexico is expected to experience accelerated development and rising luxury consumption in the coming years owing to its proximity to the United States and a thriving tourism industry. According to the Mexican Ministry of Tourism, international visitor arrivals exceeded 30 million in 2024, contributing to high demand for luxury beverages in resort destinations like Cancun and Los Cabos. The country’s large expatriate community and affluent urban population in Mexico City support steady consumption of premium champagnes. According to the National Institute of Statistics and Geography, household spending on alcoholic beverages has increased by 5% annually, reflecting growing disposable income among the upper class. Duty-free shops at major airports serve as key distribution channels for travelers seeking tax-exempt purchases. Local distributors focus on building relationships with high-end hotels and restaurants to secure prime placement on wine lists. The cultural affinity for celebrations and festivals creates seasonal spikes in demand, particularly during holidays and wedding seasons. Regulatory frameworks allow for straightforward importation, which encourages brands to launch new products and marketing campaigns. Mexico serves as a strategic hub for distributing champagne to neighboring Central American countries, with the fastest-growing regional CAGR projected at 8.2% for the coming years.
COMPETITIVE LANDSCAPE
The competition in the Latin America Champagne Market is characterized by intense rivalry among established French houses vying for dominance in luxury hospitality and retail sectors. Major players leverage their global brand equity to secure prime shelf space in duty free outlets and upscale supermarkets in countries like Brazil and Mexico. Smaller boutique producers compete by offering unique vintage selections and personalized services that appeal to discerning connoisseurs seeking exclusivity. Price competition is less significant than brand prestige and perceived quality which drive purchasing decisions among high net worth individuals. Distributors play a critical role by navigating complex regulatory environments and ensuring consistent supply despite logistical challenges. Marketing efforts focus on creating aspirational narratives that resonate with local cultural values and international tourism trends. The limited number of legal markets concentrates competition in specific hubs where brands must differentiate through superior service and innovative engagement strategies. This dynamic environment requires continuous adaptation to maintain relevance and drive growth.
KEY MARKET PLAYERS
Some of the key players in the Latin America champagne market are
- Moët Hennessy USA
- LANSON-BCC
- Vranken - Pommery Monopole
- Champagne Laurent-Perrier S.A.S
- Pernod Ricard
- Rémy Cointreau
- Centre Vinicole Champagne Nicolas Feuillatte
- Martel
- Louis Roederer
- Taittinger
Top Players in the Market
- Moët Hennessy Louis Vuitton maintains a dominant presence through its portfolio of iconic brands including Moët and Chandon and Dom Pérignon. The company leverages its extensive distribution network to ensure wide availability in luxury hotels and duty free shops across Brazil and Mexico. Recent initiatives focus on experiential marketing such as hosting exclusive tasting events in São Paulo and Mexico City to engage high net worth individuals. They invest heavily in digital platforms to reach younger affluent consumers who prefer online purchasing options. By partnering with local hospitality groups they secure prime placement in fine dining establishments. Their commitment to sustainability appeals to environmentally conscious buyers in the region. This strategic approach reinforces brand prestige and drives consistent demand for their premium offerings in key markets.
- Pernod Ricard strengthens its position in the Latin America Champagne Market through its ownership of prestigious labels like Perrier Jouët and Mumm. The company focuses on building strong relationships with distributors in major urban centers to expand reach and visibility. They recently launched targeted advertising campaigns during major tourism seasons to attract international visitors and local elites. Pernod Ricard emphasizes the heritage and craftsmanship of its champagnes to differentiate from competitors in a crowded marketplace. They also support local sommelier training programs to enhance product knowledge among service staff in high end venues. This educational approach helps drive sales in restaurants and bars. Their agile supply chain management ensures consistent stock levels despite logistical challenges in the region. These efforts collectively enhance brand visibility and consumer loyalty.
- Lanson BCC contributes significantly to the market with its diverse range of champagnes including Lanson and Charles Heidsieck. The company targets niche segments by offering unique vintage collections that appeal to connoisseurs in Argentina and Chile. They have recently expanded their presence in upscale retail stores by providing specialized display units and promotional materials. Lanson BCC collaborates with luxury event planners to feature their products at high profile gatherings and corporate functions. Their focus on quality and tradition resonates with consumers seeking authentic experiences and historical depth. The company also invests in sustainable viticulture practices which align with global trends and local values. By maintaining close contact with local partners they adapt quickly to changing consumer preferences. This responsiveness helps them capture growth opportunities in emerging urban centers.
Top Strategies Used by Key Market Participants
Key players in the Latin America Champagne Market primarily employ experiential marketing strategies to build brand loyalty among affluent consumers. Companies organize exclusive tasting events and masterclasses in luxury hotels and private clubs to educate customers about the heritage and quality of their products. Strategic partnerships with high end hospitality groups ensure prominent placement on wine lists and menus in fine dining establishments. Distributors focus on strengthening relationships with duty free operators at major airports to capture transit passenger spending. Digital engagement through social media influencers helps reach younger demographics who value visual appeal and lifestyle association. Brands also emphasize sustainability and ethical sourcing to appeal to environmentally conscious buyers in the region. Limited edition releases create urgency and exclusivity which drives immediate sales. These combined efforts help maintain premium positioning and stimulate demand in a competitive landscape.
MARKET SEGMENTATION
This is the research report on the Latin America champagne market is segmented, and sub segmented into following categories
By Grape Seed
- Pinot Noir
- Pinot Meunier
- Chardonnay
By Type
- Prestige Cuvee
- Blanc de Noirs
- Blanc de Blancs
- rosé champagne.
By Distribution Channel
- Supermarkets/Hypermarkets
- Specialty Stores
- Online Stores
By Flavour
- Brut
- Fruity Flavour
By Region
- Argentina
- Brazil
- Mexico
- Rest of the Latin America