- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$3.59 BnMarket Estimate, 2026
$3.82 BnMarket Forecast, 2034
$6.31 BnCAGR, 2026–2034
6.48%Executive Summary: Latin America Food Additives Market
- Market Scope: Comprehensive regional analysis of the Latin American food additives market, detailing product types, sourcing methods, application sectors, consumer behavior trends, and country-level profiles.
- Market Valuation: Valued at USD 3.59 billion in 2025, reaching USD 3.82 billion in 2026, and projected to expand to USD 6.31 billion by 2034, growing at a steady CAGR of 6.48% from 2026 to 2034.
- Primary Growth Drivers: Increasing disposable incomes among a growing middle class, rising shift toward convenience and processed foods, and government initiatives promoting agricultural and industrial production output.
Key Market Segment Metrics
| Category | Leading Segment (Base Position) | Fastest-Growing / High-Growth Segment |
|---|---|---|
| By Type | Flavors (Accounts for the largest market share, followed closely by the sweeteners segment) | Emulsifiers, Hydrocolloids & Functional Additives (Driven by growing importance for texture and shelf-life extension) |
| By Application | Beverages (Accounted for the largest share of food additive demand across the region) | Sauces, Dressings, Spices & Condiments (Projected to be the fastest-growing application segment) |
| By Source | Synthetic Additives (Traditional high-volume staples meeting widespread mass market processing demands) | Natural Additives (Accelerating due to consumer health awareness and clean-label preferences) |
| By Region | Brazil & Mexico (Leading national hubs driving high regional CAGR and functional ingredient adoption) | Argentina & Chile (Expanding regional markets supported by favorable trade frameworks and government production incentives) |
Major Market Players & Industry Landscape
Market Structure: Balanced between multinational food ingredient giants and growing regional processing networks, navigating consumer demand for convenience alongside health concerns regarding synthetic additives.
Key Companies: E.I. DuPont, Archer Daniels Midland Company, Cargill, Incorporated, CHR. Hansen Holding A/S, Kerry Group Plc, and BASF SE.
 Download Free Sample Report
Latin America Food Additives Market Size
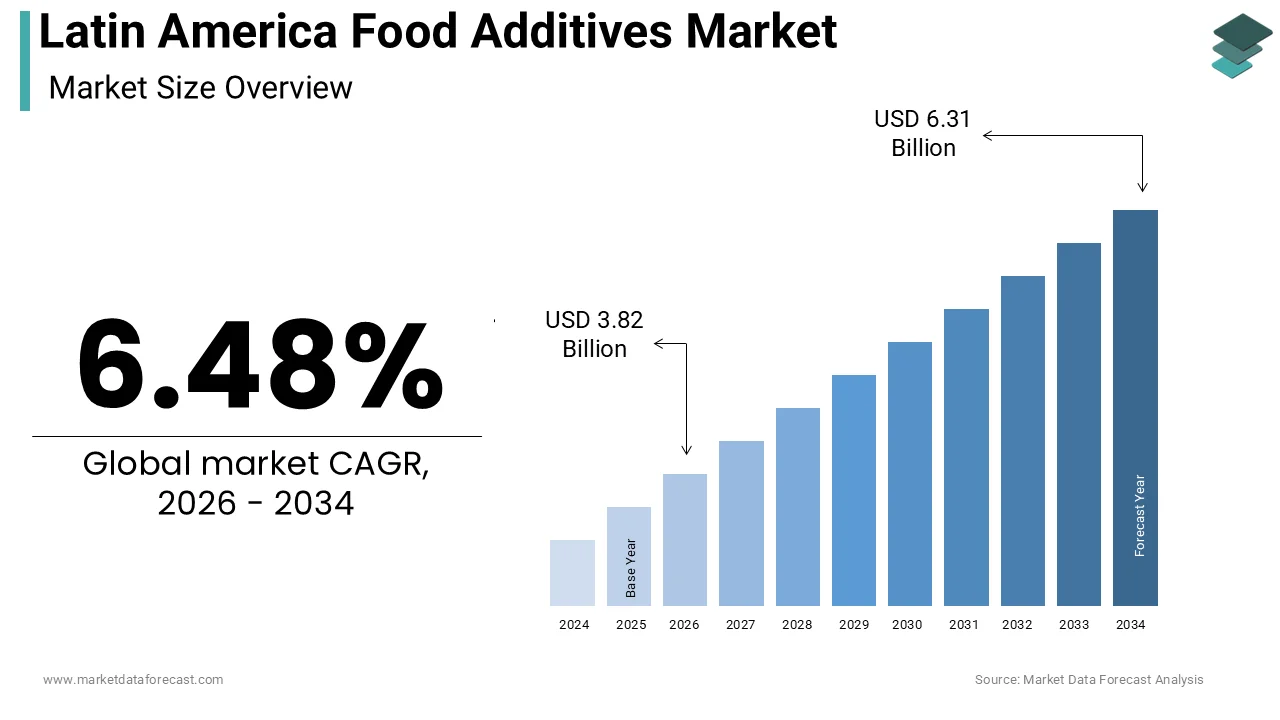
The size of the Latin America food additives market was calculated to be USD 3.59 billion in 2025 and is anticipated to be worth USD 6.31 billion by 2034 from USD 3.82 billion in 2026, growing at a CAGR of 6.48% during the forecast period.
Food additives are substances added to industrial or processed foods during production, packaging, or storage to improve safety, keep them fresh longer, or change their taste, texture, and appearance. This market is intrinsically linked to the region's expanding food processing industry, which serves a rapidly urbanizing population with evolving dietary habits. According to sources, the food processing sector in Latin America has experienced continuous expansion driven by increasing urbanization and a rising demand for convenience and processed foods. As per reports, economic integration efforts and modernizing regulatory frameworks continue to influence intra-regional trade patterns of packaged food items across Latin American countries. These dynamics create a robust foundation for additive consumption as manufacturers strive to meet consumer expectations for quality and consistency. The prevalence of tropical climates necessitates effective preservation solutions to prevent spoilage during distribution across vast distances. Consequently, the market evolves in tandem with agricultural output and industrial capabilities, ensuring that additives play a critical role in maintaining food security and reducing waste throughout the supply chain.
MARKET DRIVERS
Rapid Urbanization and Lifestyle Changes
Rapid urbanization and lifestyle changes propel the Latin America food additives market. This shifts consumer preferences toward convenient and ready-to-eat food products that require functional ingredients for stability and appeal. As per the World Bank, the urban population in Latin America exceeds 80%, with millions moving to cities where time constraints limit home cooking opportunities. This demographic shift drives demand for packaged snacks, frozen meals, and beverages that rely on preservatives, emulsifiers, and flavor enhancers to maintain quality during storage and transport. As per research, overall consumer expenditure allocations toward processed food categories are continually evolving across major Latin American markets. Manufacturers utilize additives to extend shelf life and ensure consistent taste and texture, which are crucial for brand loyalty in competitive retail environments. The proliferation of modern supermarkets and hypermarkets further amplifies this trend by providing extensive shelf space for branded processed items. Consumers associate vibrant colors and appealing textures with freshness and quality, influencing purchasing decisions. The need for efficient production processes to meet high-volume demand also favors the use of additives that streamline manufacturing. This structural change in consumption patterns ensures sustained growth for the food additives sector as it supports the convenience-driven lifestyle of urban populations.
Expansion of Food Processing Industry
The expansion of the food processing industry boosts the Latin America food additives market. This growth increases the volume of raw agricultural commodities converted into value-added products requiring functional enhancement. According to studies, investments in regional agricultural and food production units are influenced by government modernization plans and evolving export opportunities. This industrial growth necessitates the use of additives such as anti-caking agents, stabilizers, and acidity regulators to ensure product consistency and compliance with international safety standards. As per sources, thermal processing methodologies rely heavily on precise ingredient configurations to safeguard nutritional and organoleptic properties. Manufacturers rely on these ingredients to differentiate their products in global markets where visual appeal and texture are key competitive factors. The rise of local brands competing with multinational corporations further drives innovation in additive applications to create unique product profiles. Export-oriented industries, particularly in the dairy and meat sectors, utilize additives to meet stringent regulatory requirements in destination markets. This industrial maturation creates steady demand for high-quality additives that support large-scale production efficiency. The integration of advanced technologies in processing plants also facilitates the use of specialized additives for novel food formats. This driver ensures long-term viability for suppliers who can provide reliable and compliant solutions.
MARKET RESTRAINTS
Stringent Regulatory Frameworks
Stringent regulatory frameworks restrict the Latin America food additives market. These frameworks impose complex compliance requirements that increase operational costs and limit the use of certain synthetic ingredients. As per research, several countries in Latin America continue to update and modernize their food safety and labeling laws to strengthen controls over ingredients and additives. These regulations often ban or restrict specific synthetic colors and preservatives due to health concerns, forcing manufacturers to reformulate products using natural alternatives. According to studies, compliance costs and administrative burdens tend to fall disproportionately on small and medium-sized enterprises due to mandatory testing and framework changes. This financial burden hinders market entry for smaller players who lack resources for rigorous quality control measures. The variability in regulations across different countries within the region creates fragmentation, complicating cross-border trade and distribution strategies. Manufacturers must navigate a patchwork of national laws, which delays product launches and increases administrative overhead. Consumer skepticism toward chemical-sounding ingredients further complicates market acceptance of regulated synthetic additives. Retailers often prefer clean label products to avoid potential backlash, reducing shelf space for items containing restricted additives. This regulatory uncertainty discourageslong-termm investment in synthetic additive production facilities. Consequently, the market faces headwinds as it transitions toward compliant but potentially less efficient alternatives.
Economic Volatility and Currency Fluctuations
Economic volatility and currency fluctuations hamper the Latin America food additives market. These economic hurdles create unpredictable cost structures for manufacturers relying on imported raw materials and specialized ingredients. According to sources, high exchange rate volatility and domestic currency depreciation in specific Latin American economies drive up the overall costs of imported industrial inputs and goods. These fluctuations squeeze profit margins for local producers who often lack the bargaining power to secure fixed-price contracts with international suppliers. As per reports, heavy reliance on imported agricultural inputs and specialized food items leaves regional economies highly exposed to external price shocks and global supply vulnerabilities. When local currencies weaken against the US dollar, the cost of imported enzymes and preservatives rises sharply, forcing manufacturers to either absorb losses or increase product prices. Higher prices can reduce demand, particularly in price-sensitive segments such as basic staples and bulk ingredients. Small and medium enterprises are disproportionately affected as they cannot hedge against currency risks or stockpile inventory. This instability discourages investment in local production capabilities, perpetuating reliance on volatile imports. The lack of domestic sourcing options for high-purity additives limits supply chain resilience. Manufacturers struggle to plan long-term strategies amidst such economic uncertainty, hindering market stability and growth.
MARKET OPPORTUNITIES
Rising Demand for Natural and Organic Ingredients
The rising demand for natural and organic ingredients presents an opportunity for the Latin America food additives market. This shift enables premium positioning for brands utilizing plant-based and clean-label solutions. As per research, consumer preferences for transparency and minimal formulation continue to alter the demand trajectory for organic packaged categories. This trend drives adoption of natural additives such as beetroot extract, turmeric, and rosemary extract, which are perceived as safer and healthier alternatives to synthetic counterparts. According to studies, naturally derived antimicrobial metabolites are increasingly utilized in animal-derived food products to inhibit bacterial spoilage and extend shelf life. Manufacturers can leverage this preference to differentiate their products on crowded retail shelves and command higher price points. Local agricultural abundance provides a sustainable source for these natural ingredients, reducing dependency on imports and supporting rural economies. Governments are promoting organic farming initiatives which align with the sourcing needs of natural additive producers. Certification bodies are streamlining processes for natural additives, making it easier for companies to validate their claims. The opportunity extends to export markets where Latin American producers can supply unique botanical extracts to global food companies. Investment in research to improve the efficacy of natural agents can further bridge the performance gap with synthetics. This shift toward naturals creates a niche for innovative and sustainable solutions.
Innovation in Functional and Fortified Foods
Innovation in functional and fortified foods provides a key growth area for the Latin America food additives market. This development addresses specific health concerns through targeted nutritional enhancement. According to sources, nutritional deficiencies affecting major demographics stimulate the adoption of public fortification strategies for common food staples. Food additives such as vitamins, minerals, and amino acids are essential for enriching these products without altering taste or texture significantly. As per reviews, institutional and public fortification systems have contributed positively to long-term population health indicators. Manufacturers are developing specialized blends that combine multiple functional ingredients to address issues like anemia and vitamin D deficiency. The growing fitness culture in urban centers also drives demand for protein-enriched snacks and beverages requiring stabilizers and texturizers. Local research institutions are collaborating with industry players to develop cost-effective fortification methods using locally available nutrients. This collaboration accelerates commercialization and reduces reliance on expensive imported technologies. The ability to customize formulations for specific demographic groups such as children and the elderly opens new revenue streams. Manufacturers benefit from the positive public health impact, which enhances brand reputation and loyalty. This alignment with health goals ensures sustained growth and innovation in the functional food segment.
MARKET CHALLENGES
Supply Chain Disruptions and Logistics Issues
Supply chain disruptions and logistics issues challenge the Latin America food additives market. These operational difficulties cause delays and increase costs for the distribution of perishable and sensitive ingredients. According to sources, infrastructure deficits in regional transportation and storage systems frequently generate significant post-harvest losses for agricultural supply chains. These inefficiencies affect the availability and quality of natural extracts such as fruit pigments and essential oils, which are sensitive to temperature and humidity. As per reports, port congestion and administrative customs bottlenecks at major maritime shipping hubs can significantly prolong lead times and impact manufacturer production timelines. Small and medium enterprises face particular difficulties in managing inventory levels amidst such unpredictability, leading to stockouts or excess waste. The lack of cold chain infrastructure in remote areas limits the reach of temperature-sensitive additives, affecting market penetration in rural regions. Manufacturers must invest in redundant supply sources and larger safety stocks, which ties up capital and increases operational costs. Geopolitical tensions and trade policy changes further exacerbate supply chain fragility, affecting import-dependent ingredients. The volatility in freight rates adds another layer of financial uncertainty for exporters and importers. Addressing this challenge requires significant investment in logistics infrastructure and digital tracking systems. Without improved reliability, the market remains vulnerable to external shocks.
Limited Technical Expertise and Awareness
Limited technical expertise and awareness impede the growth of the Latin America food additives market. This knowledge gap hinders the effective application and optimization of advanced functional ingredients among local processors. According to research, only a limited proportion of small and medium-sized food enterprises maintain specialized internal research and engineering departments to manage advanced material formulation. This skills gap leads to inconsistent product quality and inefficient use of expensive ingredients, resulting in higher production costs. As per reviews, modern vocational curricula often fall short in allocating sufficient instructional time to specialized technical sub-disciplines, leaving students misaligned with industrial hiring demands. Manufacturers often struggle with issues such as improper dispersion stability problems and interaction with other ingredients leading to customer complaints and product recalls. The lack of localized technical support from global suppliers further exacerbates this problem, as remote assistance may not address region-specific formulation challenges. Companies must rely on expensive external consultants or import finished products, missing out on value addition opportunities. This limitation slows down innovation and restricts the range of applications for specialized additives. The challenge is particularly acute for artisanal and traditional food producers who lack access to modern processing knowledge. Without adequate technical knowledge, these businesses cannot compete effectively with larger players. Addressing this gap requires significant investment in education and collaborative research initiatives.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 6.48% |
| Segments Covered | By Type, Source, Application, and Region |
| Various Analyses Covered | Global, Regional, & Country-Level Analysis; Segment-Level Analysis; DROC; PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | Brazil, Mexico, Argentina, Chile And Rest Of Latin America |
| Market Leaders Profiled | E.I. DuPont, Archer Daniels Midland Company, Cargill, Incorporated, CHR. Hansen Holding A/S, Kerry Group Plc, and BASF SE |
SEGMENTAL ANALYSIS
By Type Insights
The preservatives segment dominated the Latin America food additives market and accounted for a substantial share in 2025. This dominance was driven by the critical need for extending shelf life in tropical climates and underdeveloped cold chain infrastructure. One of the major factors behind this standing was a combination of environmental and logistical realities, rather than mere consumer preference.
High ambient temperatures and humidity levels across the region propel the demand for preservatives by making them indispensable for preventing microbial growth and food spoilage during storage and distribution. According to the Food and Agriculture Organization of the United Nations, the Latin America and Caribbean region loses 12% of its food from post-harvest up to, but excluding, the retail stage. Preservatives such as sodium benzoate, sorbates, and nitrates act as a chemical barrier against this degradation, ensuring that processed foods remain safe for consumption over extended periods. As per sources, the structural shelf life and safety of perishable categories like dairy and meat are highly dependent on preservation interventions within tropical climate settings. This necessity drives volume sales across all food categories from artisanal breads to industrial beverages. Manufacturers prioritize cost-effective synthetic preservatives because they offer reliable protection at low dosages, which is crucial for mass market products where price sensitivity is high. The lack of universal refrigeration in rural retail outlets further cements the reliance on these additives. Consequently, preservatives remain the backbone of food safety and availability in the region.
Infrastructure limitations regarding cold storage and transport boost the preservatives segment by creating a structural dependency on chemical stabilization to bridge logistical gaps. According to sources, logistics and transport infrastructure gaps for temperature-controlled commodities subject vulnerable transit operations to ambient regional conditions. This deficit forces manufacturers to formulate products with higher levels of antimicrobial agents to withstand temperature abuse without compromising safety or quality. As per reports, systematic enhancements in regional refrigeration and cold chain operations are vital structural drivers for mitigating regional food waste. Industrial bakeries and beverage producers rely heavily on these additives to maintain distribution networks that span thousands of kilometers across diverse climatic zones. The economic cost of building comprehensive cold chain infrastructure remains prohibitive for many small and medium enterprises, making chemical preservation the only viable option for market expansion. Regulatory bodies acknowledge this reality by permitting specific preservative limits that account for regional logistical challenges. This infrastructural gap ensures sustained and high-volume demand for preservation technologies across the entire supply chain.
The enzymes segment is projected to register the highest CAGR of 6.8% in the Latin America food additives market due to industrial efficiency demands and clean label processing trends.
The drive for manufacturing efficiency and cost optimization accelerates the adoption of enzymes by enabling processors to improve yields, reduce processing times, and lower energy consumption. According to research, the deployment of catalytic enzymes like amylases and proteases alters output dynamics during starch conversion and refining procedures. These biocatalysts allow manufacturers to convert raw materials more completely, reducing waste and maximizing value from agricultural inputs. As per studies, the utilization of enzymatic mechanisms during clarifying procedures improves overall operational flow rates and processing cycles compared to purely manual techniques. In an environment of volatile input prices and thin margins, such efficiency gains are critical for profitability. Enzymes also facilitate the use of lower-grade raw materials by upgrading their functional properties, which further enhances cost effectiveness. The baking industry utilizes xylanases to improve dough stability and volume, allowing for reduced flour usage per unit. This economic rationale drives rapid adoption across diverse sectors, including brewing, dairy, and animal feed. As competition intensifies, manufacturers increasingly view enzymes not as optional additives but as essential tools for maintaining competitiveness and sustainability.
The classification of enzymes as processing aids rather than ingredients fuels their rapid growth by allowing manufacturers to achieve technical functionality without declaring them on final product labels. According to sources, processing aids and enzymes that are rendered inactive or removed during production are generally subject to specific regulatory labeling exemptions across international frameworks. This regulatory advantage enables brands to simplify ingredient lists while still benefiting from advanced textural and shelf life improvements. As per reports, reformulation within commercial baking sectors shows an increasing reliance on enzyme technologies to address clean label criteria and eliminate texturizing agents. Consumers perceive enzyme-treated foods as less processed even though the technology is sophisticated. This perception allows premium positioning without sacrificing performance. Manufacturers can replace synthetic additives like azodicarbonamide with enzymatic solutions, maintaining product quality while enhancing label appeal. The trend extends to dairy, where lactase enables lactose-free products without adding extra ingredients. This dual benefit of functionality and transparency makes enzymes the preferred solution for modernizing formulations. The alignment with both regulatory frameworks and consumer preferences ensures sustained high growth rates for this segment.
By Source Insights
The synthetic source segment led the Latin America food additives market and captured a significant share in 2025. This leading position was attributed to superior cost efficiency and consistent performance in industrial applications.
The affordability of synthetic additives propels their market leadership by enabling manufacturers to produce affordable food products for price-sensitive consumers across the region. According to the Economic Commission for Latin America and the Caribbean (ECLAC), poverty in Latin America fell to 27.3% in 2023, leaving over 27% of the population below the poverty line. According to sources, artificial dyes, flavors, and structural stabilizers carry lower production and sourcing expenditures than organic equivalents. According to reports, shifting production formulation from synthetic to natural extract inputs yields significantly higher overall raw material expenses. This economic reality dictates formulation choices in high-volume categories like soft drinks, candies, and snacks. Local manufacturers operating on thin margins rely on synthetics to maintain competitive pricing while meeting basic quality standards. The established global supply chains for synthetic chemicals ensure stable availability and predictable pricing, unlike agricultural-based naturals subject to harvest volatility. Retailers also favor lower-priced items to drive foot traffic and volume sales. Consequently, synthetic additives remain dominant in serving the broad base of the consumer pyramid despite growing premiumization trends at the top.
The superior stability and consistency of synthetic additives boost their dominance by ensuring reliable performance across varying processing conditions and long shelf lives. According to research, chemically synthesized color and flavor molecules exhibit highly stable performance characteristics under fluctuating thermal and environmental processing conditions. This reliability is crucial for large-scale industrial production where consistency defines brand integrity and consumer trust. As per studies, synthetic preservation chemicals reliably extend commercial shelf-stability timelines compared to organic compounds. Manufacturers cannot risk product recalls or quality failures due to additive variability, especially in export markets with strict standards. The predictability of synthetic ingredients simplifies quality control protocols and reduces testing costs. In beverage applications, synthetic sweeteners provide consistent sweetness profiles without the metallic aftertaste or stability issues sometimes associated with natural high-intensity sweeteners. This technical superiority makes synthetics the default choice for complex formulations requiring precise functional attributes. Until natural technologies match this level of reliability, synthetics will continue to dominate industrial applications where performance cannot be compromised.
The natural source segment is experiencing the fastest CAGR of 7.2%, owing to health consciousness and regulatory shifts toward cleaner ingredients.
Rising health awareness among urban middle-class consumers accelerates the adoption of natural additives by creating demand for products perceived as safer and more wholesome. According to sources, an increasing percentage of health-conscious shoppers look for the exclusion of artificial ingredients on commercial food packages. This behavioral shift drives reformulation efforts across premium and mainstream segments as brands seek to retain health-conscious shoppers. As per reports, industry demand for botanical colorants such as annatto and turmeric is expanding inside functional beverage segments. Consumers associate natural sources with fewer side effects and better nutritional alignment, reinforcing purchasing decisions. Social media and influencer marketing amplify these perceptions, making clean label a powerful differentiator. Retailers respond by expanding shelf space for natural products and promoting them through dedicated health sections. The trend is particularly strong among millennials and Gen Z who prioritize transparency and sustainability. Manufacturers leverage this willingness to pay premiums to offset higher sourcing costs of natural ingredients. This demographic-driven demand creates a sustainable growth trajectory independent of broader economic fluctuations.
Government initiatives and evolving regulatory standards fuel the rapid growth of natural additives by incentivizing cleaner formulations and restricting certain synthetic compounds. According to sources, several Latin American countries, including Chile, Peru, Mexico, Brazil, Uruguay, Argentina, and Colombia, have implemented mandatory front-of-pack nutrition warning labels for food products exceeding specific nutritional thresholds. Conversely, regulatory bodies are streamlining approval processes for natural extracts derived from regional biodiversity, encouraging local innovation. As per reports, regulatory compliance filings for botanical and biological food components show changing volume trends following updated modifications to natural product classification rules. These policy signals guide R&D investments toward natural solutions as companies anticipate future restrictions on synthetics. Public procurement programs for school meals increasingly mandate natural ingredients, creating guaranteed demand volumes. International trade agreements also favor natural products, aligning with global clean label standards and facilitating exports. Manufacturers view the natural transition as strategic risk management against regulatory obsolescence. The alignment of public health policy with industry innovation creates a supportive ecosystem for natural additive growth. This regulatory push ensures that natural segment expansion is structurally embedded rather than merely cyclical.
By Application Insights
In 2025, the beverages segment held the majority share in the Latin American food additives market because of high per capita consumption and the category's inherent reliance on additives for flavor, color, and preservation.
The exceptionally high volume of beverage consumption across Latin America drives dominant demand for additives by creating massive throughput requirements for sweeteners, colors, and preservatives. According to the Pan American Health Organization, per capita consumption of sugar-sweetened beverages in Mexico exceeds 160 liters annually, representing one of the highest rates globally. This sheer volume translates directly into substantial additive usage, as every liter requires precise dosing of multiple functional ingredients. According to sources, fluid matrices and high volume demands drive a substantial portion of overall additive usage within the beverage processing industry. Carbonated soft drinks, juices, and bottled waters are dietary staples consumed daily by all age groups, ensuring consistent baseline demand. The hot climate further amplifies consumption patterns, increasing turnover and replenishment frequency. Manufacturers optimize formulations for high-speed bottling lines, requiring additives that perform reliably at industrial scales. Private label expansion also contributes to volume growth as retailers introduce affordable beverage options. This volumetric dominance makes beverages the primary anchor for the entire additives market regardless of shifting trends in other categories.
The technical complexity of beverage formulations boosts additive demand by requiring specialized ingredients to maintain stability, appearance, and taste throughout shelf life. As per reports, complex liquid emulsion matrices are prone to physical degradation, requiring texturizing stabilizers and acidulants to control sedimentation. According to research, typical carbonated soft drink recipes utilize multiple combined functional compounds to preserve uniform appearance, acidity levels, and structural quality. Natural juices require antioxidants to prevent browning and preservatives to inhibit yeast growth, while sports drinks need electrolytes and flavor masking agents. This multifunctional necessity drives higher additive intensity per unit compared to solid foods. Innovation in functional beverages adds further layers of complexity, with proteins, fibers, and probiotics requiring additional stabilization systems. Manufacturers cannot compromise on sensory attributes, as visual clarity and taste consistency define brand success. The rise of low-sugar and zero-calorie variants introduces new challenges requiring high-intensity sweeteners and mouthfeel enhancers. This technical dependency ensures that beverages remain the most additive-intensive application segment, sustaining market leadership through continuous formulation evolution.
The convenience foods segment is expected to exhibit a noteworthy CAGR of 6.5% from 2026 to 2034. This growth is propelled by urbanization and changing household dynamics.
Rapid urbanization and shrinking household sizes accelerate demand for convenience foods by creating a structural need for ready-to-eat and easy-to-prepare meal solutions. According to the World Bank, annual urban population growth rates are approximately 1.4% in Colombia and 1.5% in Peru, with changing household structures shifting consumer meal prep behavior. This demographic shift drives sales of frozen meals, instant noodles, and prepared sauces, which rely heavily on additives for texture, flavor, and shelf stability. As per research, household consumption allocations for processed, quick-preparation food formats continue to expand rapidly within dense metropolitan areas. Young professionals and students form the core consumer base seeking quick nutritious options without culinary effort. Retailers expand frozen and chilled sections to capture this demand, increasing product variety and accessibility. Manufacturers innovate with ethnic flavors and healthier profiles to broaden appeal beyond traditional fast food associations. The pandemic accelerated this trend, normalizing home consumption of prepared meals. This lifestyle transformation creates sustained growth momentum for convenience foods and consequently their requisite additives.
Continuous product diversification and quality enhancement fuel rapid growth by expanding convenience foods beyond basic sustenance into premium and health-oriented segments. As per studies, product introductions within ready-to-serve food segments increasingly emphasize added functional attributes, premium profiles, and clean-label formulations. These premium offerings require sophisticated additive systems to replicate restaurant-quality textures and flavors in packaged formats. Modified starches, hydrocolloids, and flavor enhancers enable creamy sauces, tender proteins, and fresh-tasting vegetables after reheating. As per sources, pre-packaged convenience products continue to capture an increasingly dominant market share of total grocery retail volume across Latin American markets. Manufacturers invest in clean label additives to overcome historical perceptions of processed food as unhealthy. Plant-based and gluten-free convenience options open new niches requiring specialized texturizers and binding agents. This upward migration in quality and variety attracts higher-income consumers, widening the addressable market. The convergence of convenience with health and indulgence trends ensures robust growth trajectories for additive suppliers supporting this dynamic segment.
REGIONAL ANALYSIS
Brazil Food Additives Market Analysis
Brazil remained the largest Latin American food additives market and occupied a commanding share in 2025. This prominence was supported by its vast agricultural base and sophisticated food processing industry. As per reports, Brazil represents a massive share of agricultural and livestock production in Latin America, fueling extensive domestic utilization of processing ingredients. The tropical climate necessitates extensive use of preservatives and antioxidants to protect perishable goods during long-distance distribution across continental territories. According to research, investment flows into the food processing sector continue to expand, supported by strategic initiatives aimed at expanding value-added exports. This industrial maturity drives demand for advanced enzymes and processing aids in biofuel, starch, and sweetener production. Brazil's diverse consumer base spans from price-sensitive mass market to premium health-conscious segments requiring full-spectrum additive solutions. Local production of citrus and tropical fruits supports natural color and flavor extraction industries, reducing import dependency. Regulatory harmonization with Mercosur partners facilitates cross-border trade, amplifying market scale. The presence of multinational ingredient manufacturers fosters technology transfer and innovation. These factors combine to make Brazil the undisputed leader shaping regional trends and supply dynamics.
Mexico Food Additives Market Analysis
Mexico was positioned second in the Latin America food additives market in 2025. This position was driven by strong integration with North American supply chains and vibrant domestic consumption. According to studies, the food and beverage processing subsector constitutes a major pillar of industrial economic output and manufacturing activity across the country. Proximity to the United States enables access to advanced additive technologies and facilitates export-oriented production meeting FDA standards. As per sources, market demand for prepared and convenience foods is heavily influenced by rapid urban growth and shifts in household labor participation. This shift boosts demand for emulsifiers, stabilizers, and flavor systems in prepared meals and snacks. Mexico's position as a major soda and beer producer sustains high-volume demand for sweeteners, colors, and preservatives. Government front-of-package labeling regulations are accelerating reformulation toward natural ingredients, creating growth opportunities for clean label suppliers. Strong retail infrastructure supports widespread distribution of processed foods. Cultural affinity for bold flavors drives innovation in seasoning and spice additives. These dynamics position Mexico as a critical growth engine and innovation hub within the regional market.
Argentina Food Additives Market Analysis
Argentina is the fastest-growing regional market despite macro volatility due to its strong agro-industrial sector and export-focused food processing capabilities. According to reports, Argentina is a leading international supplier of agricultural derivatives, requiring strict quality control measures to maintain cargo integrity during transport. The temperate climate reduces some preservation needs compared to tropical regions, but long export transit times necessitate high-performance antioxidants and stabilizers. As per research, the commercial viability of international value-added food shipments relies heavily on meeting the specific regulatory standards of importing economic blocs. Domestic consumption remains resilient despite economic volatility, with staple foods like bread and pasta sustaining baseline additive demand. Local production of wheat and corn supports domestic manufacturing of starches and gluten. Government policies promoting non-traditional exports encourage diversification into functional foods and beverages. The wine industry expansion drives demand for enological additives and processing aids. Economic challenges prompt efficiency-seeking behavior favoring cost-effective synthetic solutions alongside a growing natural segment. These factors maintain Argentina's relevance as a specialized supplier and consumer market.
Chile Food Additives Market Analysis
Chile is a stable Latin American food additives market, owing to high regulatory standards and premium product orientation. According to studies, agricultural oversight systems emphasize rigorous ingredient and input standards to safeguard access to competitive global markets. The country's strong fruit export industry drives demand for postharvest treatments coatings, and preservation technologies to maintain quality during ocean freight. As per sources, commercial output for clean-label and minimally formulated food items has been growing continuously to track evolving consumer preferences. High disposable incomes support premiumization trends, driving demand for natural colors, flavors, and functional additives in dairy and beverages. The salmon aquaculture industry creates specialized demand for feed additives and processing aids. A stable economic environment attracts foreign investment in specialty ingredient distribution. Consumer awareness of health and sustainability is among the highest in the region, influencing formulation choices. Mining sector prosperity supports institutional food service demand. These elements position Chile as a leader in quality standards and natural ingredient adoption despite smaller absolute market size.
COMPETITION OVERVIEW
The competition in the Latin America Food Additives Market is characterized by a mix of global multinational corporations and emerging local suppliers vying for dominance through innovation and service excellence. Large international players leverage their extensive research capabilities and established distribution networks to offer high-quality synthetic and natural solutions. They focus on building strong technical support networks to assist manufacturers with complex formulation challenges specific to tropical climates. Local players compete by providing cost-effective alternatives and leveraging deep understanding of regional culinary traditions and ingredient characteristics. The market sees intense rivalry in the natural segment as consumer preference shifts toward clean label and plant-based additives. Regulatory variations across countries create barriers to entry but also opportunities for specialized compliance services. Price sensitivity in staple food segments drives competition on cost efficiency, while premium sectors emphasize quality and sustainability. Collaborations between international firms and local entities facilitate knowledge transfer and market adaptation. The presence of numerous small-scale distributors adds fragmentation but also fosters innovation in niche applications. Overall the competitive landscape demands continuous adaptation to changing consumer preferences, regulatory requirements, and technological advancements to sustain growth and profitability in this diverse region.
KEY MARKET PLAYERS
Major Key Players in the Latin America Food Additives Market include
- E.I. DuPont
- Archer Daniels Midland Company
- Cargill Incorporated
- CHR. Hansen Holding A/S
- Kerry Group Plc
- BASF SE
Top Strategies Used by Key Market Participants
Key players in the Latin America Food Additives Market employ localization strategies to adapt products to regional tastes and climatic conditions. Companies invest heavily in technical service centers to provide hands-on formulation support for local manufacturers. Strategic partnerships with agricultural cooperatives ensure sustainable sourcing of raw materials and reduce supply chain risks. Product diversification is a common approach, with firms developing both synthetic and natural options to cater to varying consumer segments. Manufacturers focus on regulatory compliance by aligning formulations with strict safety standards in major economies like Brazil and Mexico. Sustainability initiatives drive innovation in eco-friendly packaging and energy-efficient production methods. Digital platforms facilitate remote consultation and order management, improving customer experience and efficiency. Educational programs target small-scale producers to increase awareness of additive benefits and proper usage techniques. Mergers and acquisitions enable companies to consolidate expertise and expand geographic footprint efficiently. These combined approaches ensure sustained competitiveness and growth in a dynamic market environment.
Leading Players in the Market
- Ingredion Incorporated serves as a leading provider of ingredient solutions with a strong presence in the Latin America Food Additives Market. The company leverages its extensive portfolio of starches, sweeteners, and texturants to support local food manufacturers in Brazil and Mexico. Recent actions include expanding its application center in São Paulo to provide customized formulation support for regional clients. This expansion allows Ingredion to address specific tropical climate challenges related to product stability and shelf life. The corporation focuses on sustainable sourcing of raw materials from local farmers, enhancing supply chain resilience. Ingredion collaborates with regulatory bodies to ensure compliance with evolving food safety standards across the region. Its investment in clean label technologies helps brands meet consumer demand for transparent ingredients. These strategic initiatives strengthen its position as a trusted partner for innovation and quality. Ingredion's continuous engagement with industry stakeholders drives adoption of advanced functional ingredients.
- Cargill Incorporated contributes significantly to the Latin America Food Additives Market through its integrated supply chain and diverse product offerings. The entity provides essential additives such as emulsifiers, preservatives, and natural colors derived from agricultural commodities. Recent actions involve upgrading its production facilities in Argentina to increase capacity for specialty oils and lecithin. This upgrade enables Cargill to serve the growing demand for plant-based ingredients in the dairy and bakery sectors. The company emphasizes digital tools that help customers optimize formulation efficiency and reduce waste. Cargill partners with local distributors to enhance market reach in remote areas of Central America. Its commitment to sustainability aligns with regional environmental goals, attracting eco-conscious brands. The firm's technical expertise supports small and medium enterprises in improving product quality. These efforts reinforce Cargill role as a key enabler of food security and industrial growth.
- DSM Firmenich plays a pivotal role in the Latin America Food Additives Market by combining nutrition science with flavor and fragrance expertise. The company offers innovative solutions including natural colors, enzymes, and fortification blends tailored to regional dietary needs. Recent actions include launching a new line of heat-stable natural pigments specifically designed for baked goods in tropical climates. This launch addresses common challenges related to color fading during high-temperature processing. DSM Firmenich invests in research collaborations with universities in Chile and Colombia to develop novel bio-based additives. The company provides comprehensive regulatory support, helping clients navigate complex labeling requirements. Its focus on health and wellness drives demand for functional ingredients in beverages and snacks. DSM Firmenich's strong local presence ensures rapid response to customer needs and market trends. This strategic alignment fosters long-term partnerships and sustained market relevance.
MARKET SEGMENTATION
This research report on the Latin America food additives market has been segmented and sub-segmented based on type, source, application, and region.
By Type
- Acidulants
- Anti-Caking Agents
- Colors
- Emulsifiers
- Enzymes
- Flavors
- Hydrocolloids
- Preservatives
- Sweeteners
By Source
- Natural
- Synthetic
By Application
- Bakery & Confectionery
- Beverages
- Convenience Foods
- Dairy & Frozen Desserts
- Spices & Condiments
- Sauces & Dressings
By Region
- Brazil
- Mexico
- Argentina
- Chile
- Rest of Latin America