- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$8 BnMarket Estimate, 2026
$10.08 BnMarket Forecast, 2034
$64.04 BnCAGR, 2026–2034
26%Global Micro Data Center Market Size, Growth, Trends & Forecast (2026-2034)
The global micro data center market was valued at USD 8 billion in 2025, is predicted to reach USD 10.08 billion in 2026, and is projected to scale up to USD 64.04 billion by 2034, registering a compound annual growth rate (CAGR) of 26% during the forecast period from 2026 to 2034. Driven by the rising demand for energy-efficient edge computing, rapid 5G deployment, and the need for self-contained, prefabricated IT infrastructure, the market continues to expand aggressively worldwide.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 8.00 Billion
- 2026 Current Valuation: USD 10.08 Billion
- 2034 Forecast Valuation: USD 64.04 Billion
- Compound Annual Growth Rate (CAGR): 26.0% (2026-2034)
- Dominant Application Segment: Edge Computing (led by accelerated demand for instant, low-latency data access)
- Dominant Rack Unit Segment: 20 RU to 40 RU (holding major market share and dominance throughout the forecast period)
- Dominant Organization Size: Large Enterprises (led by high power consumption needs and carbon footprint management)
- Dominant Vertical Segment: BFSI (banking, financial services, and insurance holding the major market share)
- Dominant Region: Asia Pacific (propelled by IoT adoption and edge computing advancements, closely followed by North America and Europe)
Core Market Drivers
- Edge Computing Expansion: Growing requirement for localized data processing near the data source to minimize latency and bandwidth costs.
- 5G Deployment & Digitalization: Rollout of high-speed 5G networks across North America and Europe, alongside booming SME expansion and smart urbanization in APAC and MEA.
- Cost-Effective Prefabrication: Reduced capital expenditure and deployment time compared to traditional brick-and-mortar data center construction.
Primary Market Restraints & Challenges
- Lack of Awareness & Complexities: Limited awareness regarding micro data centers and technical challenges in implementing high-performance computing.
- Remote Management Difficulties: Complexities involved in monitoring, cooling, and securing infrastructure deployed at distributed or remote branch locations.
Global Micro Data Center Market Segmentation Breakdown
| Segment Category | Leading Sub-Segment | Growth & Trend Highlights |
|---|---|---|
| By Application | Edge Computing | Instant data centers and remote office/branch office (ROBO) setups also scale steadily. |
| By Rack Unit | 20 RU to 40 RU | Accompanied by Up to 20 RU and Above 40 RU configurations for varied enterprise capacities. |
| By Organization Size | Large Enterprises | Small and medium-sized enterprises (SMEs) represent a rapidly growing adopter base. |
| By Verticals | BFSI | IT & Telecom, Healthcare, Government & Defense, Retail, and Manufacturing follow closely. |
| By Region | Asia Pacific | North America and Europe hold strong shares, with steady growth in Latin America and MEA. |
Major Industry Players Profiled
Key global market participants shaping the micro data center landscape include Schneider Electric SE, Vertiv Co., Eaton Corporation, Hewlett Packard Enterprise, Huawei Technologies Limited, IBM Corporation, NVIDIA Corporation, Rittal GmbH & Co. Kg, Edgemicro, EdgePresence, Panduit Corporation, and Smart Edge Data Centers Limited.
 Download Free Sample Report
Global Micro Data Center Market Size
The global micro data center market was worth USD 8 billion in 2025. The global market is predicted to reach USD 10.08 billion in 2026 and USD 64.04 billion by 2034, growing at a CAGR of 26% during the forecast period.
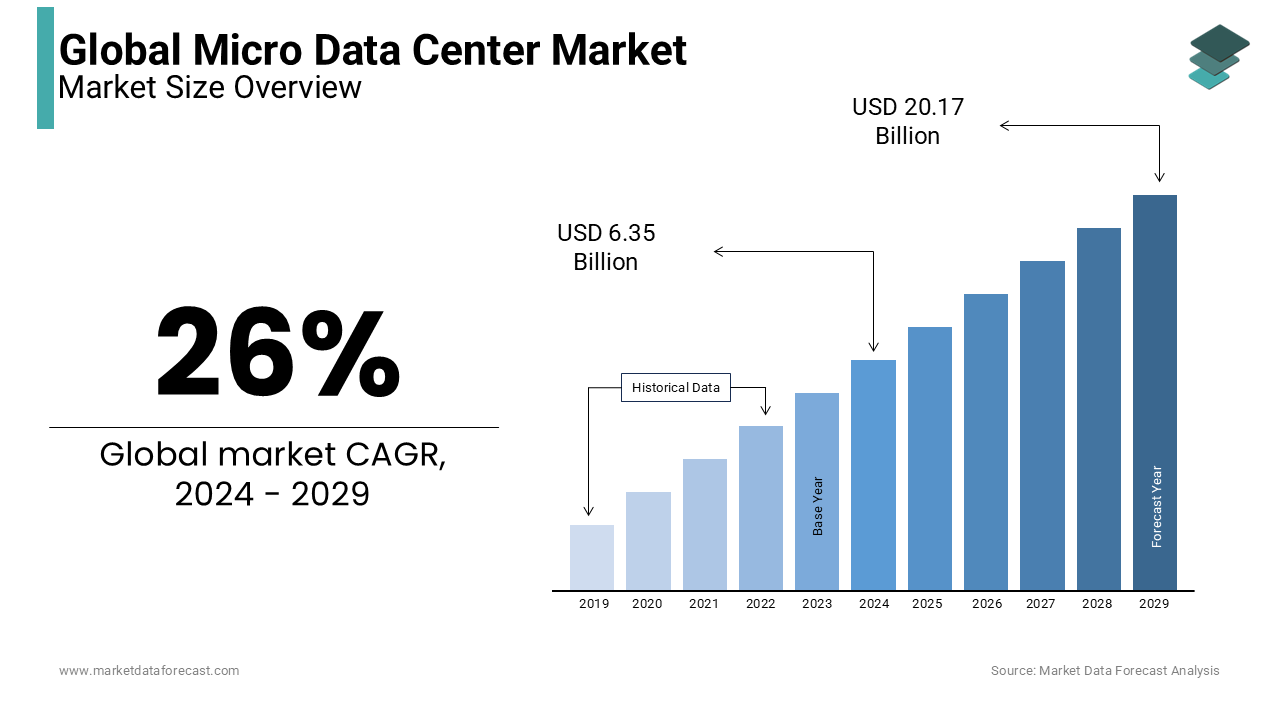
The micro data center is nothing but a self-contained infrastructural design that was achieved by integrating the storage, processing, and networking modules that are required to run indoor as well as outdoor applications in a secure computing environment, whereas these micro data centers are available in standardized prefabricated sizes that enable the data center owners to save their capital investment and the time needed in building those data centers by the traditional approach in which the size and flexibility features of the micro data centers make them ideal for use in some of the applications such as instant data centers, remote office and branch office and also edge computing.
MARKET DRIVERS
The growing demand for high-performing, energy-efficient, cost-effective data center solutions is expected to play an essential role in the growth of the micro data center market across the globe.
Another factor is the growing demand for edge micro data centers in several industry verticals, which influence the growth of the Micro Data Center market during the forecast period. Deployment and commercialization of 5g network connectivity in the Europe region and North America and the rise in the number of SMEs in the Asia Pacific region are some of the major driving factors that promote the growth of the revenue rate of the Micro Data Center market during the forecast period. Furthermore, the flourishing telecommunication sector in South America and the rise in urbanization and digitalization in MEA are other major growth-supporting factors in the Micro Data Center market.
MARKET RESTRAINTS
Lack of awareness is one of the important barriers to market growth. Challenges in implementing high-performance computing act as an important deterrent to the growth of the Micro Data Center market. Monitoring and management challenges at remote locations are also major restraints that hinder the growth of the microdata center market.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 26% |
| Segments Covered | By Application, Rack Unit, Organization Size, Verticals, and Region |
|
Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
|
Market Leaders Profiled | Eaton Corporation, Hewlett-Packard Enterprise, Huawei Technologies Limited, IBM Corporation, Edgemicro, EdgePresence, NVIDIA Corporation, Smart Edge Data Centers Limited, Panduit Corporation, Rittal GmbH & Co. Kg, Schneider Electric SE, Vertiv Co., Attom Technology, and Others. |
SEGMENTAL ANALYSIS
By Application Insights
The edge computing segment held the prominent share and is predicted to remain at the forefront throughout the forecast period due to the accelerated demand for instant data. Access to data anytime and anywhere, edge computing, and micro data centers are becoming more abundant and also increasingly vulnerable. This application also has the potential to prevent such issues from arising as the physical infrastructure, which is located to the source data.

By Rack Unit Insights
The Micro Data Center Market is divided into up to 20 RU, 20 RU to 40 RU, and above 40 RU. The 20 RU to 40 RU segment holds the major share of the market, and this segment is expected to hold dominance during the forecast period.
By Organization Size Insights
The Micro Data Center Market is divided into small and medium-sized enterprises and large enterprises. Among these segments, the large-sized enterprises segment held the prominent share, and it is predicted to remain at the forefront in the upcoming years since these enterprises face various issues related to higher power consumption and higher carbon footprint.
By Verticals Insights
The Micro Data Center Market is divided into IT and telecommunication, BFSI, media and entertainment, healthcare, government and defense, retail, manufacturing, and other verticals such as energy, education, transportation, and logistics. The BFSI segment holds the major share of the market and is expected to hold dominance during the forecast period.
REGIONAL ANALYSIS
The Asia Pacific region holds a prominent share of the market due to factors such as the rising adoption of advanced technologies, such as the Internet of Things and edge computing. The region is expected to hold dominance during the forecast period. North America is also expected to increase market growth due to the growing demand for edge micro data centers in several industry verticals. Europe is also expected to increase its market value in the upcoming years, followed by the Asia Pacific region and North America. Latin America is likely to have steady growth opportunities in the foreseeable years. The Middle East and Africa are projected to have a slow growth rate during the forecast period.

KEY MARKET PARTICIPANTS
The major companies operating in the global micro data center market include Eaton Corporation, Hewlett-Packard Enterprise, Huawei Technologies Limited, IBM Corporation, Edgemicro, EdgePresence, NVIDIA Corporation, Smart Edge Data Centers Limited, Panduit Corporation, Rittal GmbH & Co. Kg, Schneider Electric SE, Vertiv Co., and Attom Technology.
RECENT MARKET HAPPENINGS
-
Schneider Electric launched a cooling solution for edge and micro data centers in March 2020. This new solution aims to make cooling more efficient and ultimately reduce operational costs.
-
Vertiv company has introduced a new software named Vertiv Environet Alert, which brings enterprise-level infrastructure monitoring and management capabilities to micro data centers and edge facilities.
MARKET SEGMENTATION
This research report on the global micro data center market is segmented and sub-segmented based on application, rack unit, organization size, verticals, and region.
By Application
-
Instant Data Center
-
Remote Office And Branch Office
-
Edge Computing
By Rack Unit
-
Up to 20 RU
-
20 RU to 40 RU
-
Above 40 RU
By Organization Size
-
Small And Medium-Sized Enterprises
-
Large Enterprises
By Verticals
-
IT and Telecommunication
-
BFSI
-
Media And Entertainment
-
Healthcare
-
Government And Defense
-
Retail
-
Manufacturing
-
Others
By Region
-
North America
-
The United States
-
Canada
-
Rest of North America
-
-
Europe
-
The United Kingdom
-
Spain
-
Germany
-
Italy
-
France
-
Rest of Europe
-
-
The Asia Pacific
-
India
-
Japan
-
China
-
Australia
-
Singapore
-
Malaysia
-
South Korea
-
New Zealand
-
Southeast Asia
-
-
Latin America
-
Brazil
-
Argentina
-
Mexico
-
Rest of LATAM
-
-
The Middle East and Africa
-
Saudi Arabia
-
UAE
-
Lebanon
-
Jordan
-
Cyprus
-