- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$13.72 BnMarket Estimate, 2026
$14.39 BnMarket Forecast, 2034
$21.03 BnCAGR, 2026–2034
4.86%Executive Summary: Middle East and Africa Dehydrated Food Market
- Market Scope: Regional analysis of the Middle East and Africa (MEA) dehydrated food market covering product types, natural/organic classifications, drying technologies, applications, and country-level breakdowns.
- Market Valuation: Valued at USD 13.72 billion in 2025, estimated at USD 14.39 billion in 2026, and projected to reach USD 21.03 billion by 2034, registering a steady CAGR of 4.86% from 2026 to 2034.
- Primary Growth Drivers: Hectic urban lifestyles, demanding work cultures, and extended commuting hours in Tier 1 cities driving demand for ready-to-eat and quick-prep foods; prolonged shelf-life benefits without requiring refrigeration; and technological advancements in vacuum, air, and spray drying.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment / Position | Segment Details / Breakdown |
|---|---|---|
| By Type | Dehydrated Vegetables, Dehydrated Fruits, Dehydrated Meat Products & Dehydrated Dairy Products | Dehydrated vegetables experience surging demand due to improved preservation, long shelf life, and ease of home cooking. |
| By Nature | Organic & Conventional | Conventional products capture major volume, while organic lines grow steadily with health-conscious consumer trends. |
| By Technology | Spray Drying (Revenue Leader), Freeze Drying, Vacuum Drying & Drum Drying | Spray drying accounts for the majority of revenue share, followed closely by freeze drying for moisture reduction and nutrient preservation. |
| By Application | Food Product Manufacturers, Food Service & Retail, & Household | Widespread adoption across commercial food processing and household convenience cooking. |
| By Country / Region | UAE, Israel, KSA, South Africa & Egypt | Saudi Arabia and Israel lead regional demand expansion through expanding urban populations and high convenience food adoption. |
Major Market Players & Market Structure
Market Structure: Competitive global food and ingredient landscape shaped by major multinational food conglomerates and processing corporations driving strategic acquisitions (e.g., Symrise's acquisition of I.D.F. and A.D.F.).
Key Companies: Nestlé SA, Ajinomoto Co. Inc., Nissin Food Holdings Co. Ltd., House Foods Corp, Ting Hsin International Group, General Mills Inc., Kraft Foods Inc., and Unilever China Ltd.
Middle East and Africa Dehydrated Food Market Size
The Middle East and Africa dehydrated food market size was valued at USD 13.72 billion in 2025 and is projected to reach USD 21.03 billion by 2034 from USD 14.39 billion in 2026, growing at a CAGR of 4.86%.
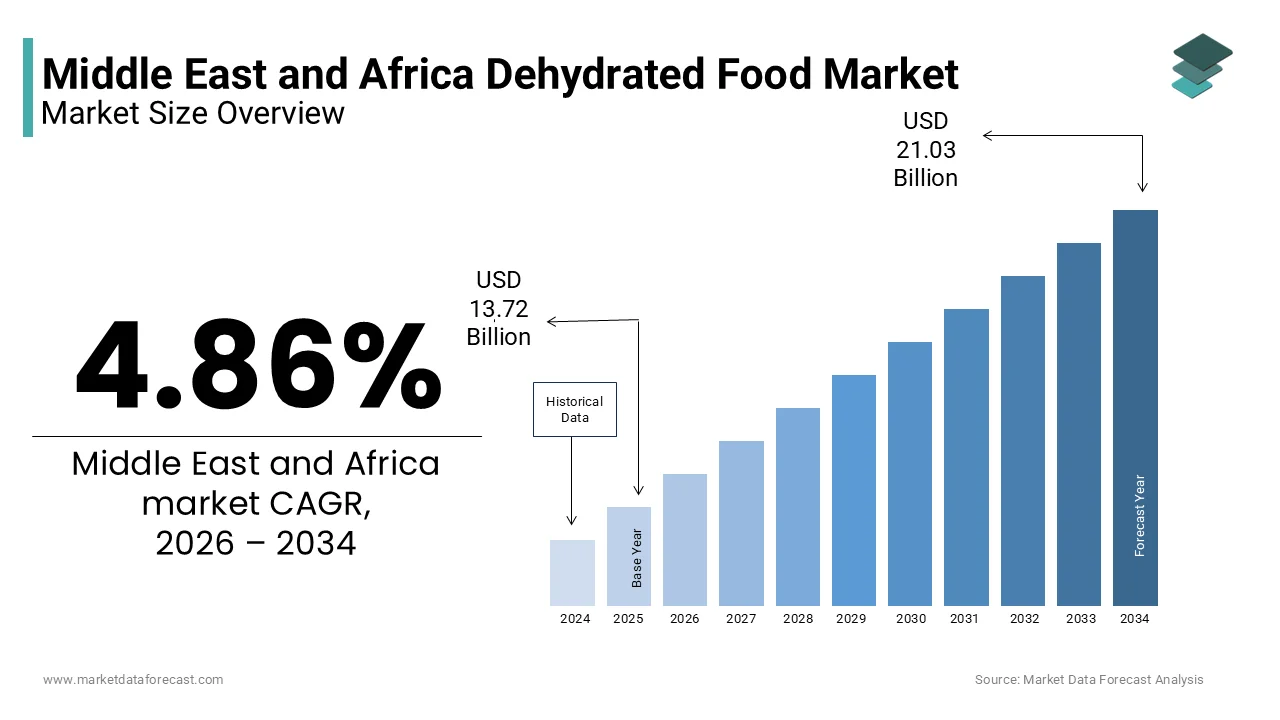
The dehydrated food is the processing preservation and distribution of moisture removed agricultural products, including fruits, vegetables, herbs, and ready to eat meals. This dual role in commercial retail sectors driven by urbanization and humanitarian applications aimed at combating food insecurity. These developments align with national strategies to reduce food waste and enhance supply chain resilience against climate induced disruptions within the evolving agricultural landscape of the Middle East and Africa.
MARKET DRIVERS
Rapid Urbanization Drives Demand for Convenient Shelf Stable Foods
The rapid urbanization is driving the growth of the Middle East and Africa dehydrated food market. This shift directly correlates with market growth, as urban dwellers with busy lifestyles prioritize convenience and ease of preparation over traditional cooking methods that require fresh ingredients. Such lifestyle changes create a robust consumer base for packaged dehydrated products that offer long shelf life and minimal storage requirements. Consequently, the structural transformation of society from rural to urban acts as a primary driver that sustains consistent demand for dehydrated food items across retail channels in the Middle East and Africa Dehydrated Food Market.
Food Security Initiatives Promote Dehydration for Waste Reduction
The food security initiatives promote dehydration for waste reduction is accelerating the growth of the Middle East and Africa dehydrates food market. As per the Food and Agriculture Organization, approximately 14% of all food produced globally is lost between harvest and retail levels with higher rates in developing regions due to lack of cold chain infrastructure. Governments in countries like Kenya and Egypt are subsidizing drying equipment for smallholder farmers to convert seasonal gluts into stable products that can be sold year-round. Therefore, the strategic imperative to minimize waste and ensure food availability during lean seasons drives institutional and commercial adoption of dehydration technologies.
MARKET RESTRAINTS
High Energy Costs Increase Production Expenses
The high energy costs increase production expenses is restricting the growth of the Middle East and Africa dehydrated food market. According to the International Energy Agency, electricity prices in several Sub Saharan African countries are among the highest globally relative to income levels with industrial tariffs averaging 0.20 dollars per kilowatt hour, which significantly impacts energy intensive dehydration processes. Thermal drying methods require substantial heat input making operational costs prohibitive for small and medium sized enterprises that lack access to affordable renewable energy sources. The inflation in fuel costs has risen by 25% in recent years, further squeezing margins for processors who rely on diesel generators in areas with unreliable grid power. Such financial pressures limit the scalability of production and force many operators to use less efficient traditional sun drying methods which compromise quality and hygiene standards.
Limited Consumer Awareness of Nutritional Benefits
The limited consumer awareness of nutritional benefits is hindering the growth of the Middle East and Africa dehydrated food market. As per the World Health Organization, misconceptions about processed foods persist in many African communities where dehydrated products are often perceived as inferior or lacking in nutrients compared to fresh alternatives. This cultural bias limits market penetration particularly among older demographics who trust traditional food preparation methods and view dehydration as a sign of poverty or scarcity rather than innovation. Without proper understanding consumers may hesitate to pay premium prices for dehydrated goods despite their convenience and safety benefits.
MARKET OPPORTUNITIES
Expansion of Export Markets for Dried Herbs and Spices
The expansion of export for dried herbs and spices is ascribed to foster the growth of the Middle East and dehydrated food market. This international interest creates lucrative opportunities for regional processors who can leverage geographical indication and traditional farming practices to differentiate their products in premium markets. The value added agro exports generate higher revenue than raw commodities providing strong economic incentives for local companies to invest in certification and packaging. By meeting international quality standards producers can access stable long-term contracts that reduce dependence on volatile domestic areas. Therefore, the rising global appreciation for ethnic flavors presents a transformative opportunity for stakeholders to expand their reach beyond local borders and enhance profitability in the Middle East and Africa Dehydrated Food Market.
Growth in Humanitarian and Emergency Relief Supply Chains
The growth in humanitarian and emergency relief supply chains is additionally to leverage the growth of the Middle East and Africa dehydrated food market. Humanitarian agencies prefer dehydrated foods because they are easy to transport store and prepare in resource constrained environments offering a cost-effective solution for large scale feeding operations. The United Nations High Commissioner for Refugees estimates that annual procurement of specialized nutritional products exceeds 500 million dollars with dehydrated fortified blends being a key component of ration packs. This institutional purchasing power provides a reliable revenue stream for manufacturers who can meet strict quality and safety requirements. Hence, the persistent need for disaster response and refugee support generates a distinct opportunity stream for dehydrated food suppliers targeting the non-government organization and government aid sectors within the region.
MARKET CHALLENGES
Climate Change Impacts Raw Material Availability
The climate changes is directly impacting on the raw materials availability that is to impede the growth of the Middle East and Africa dehydrated food market. This volatility threatens the consistency of supply chains as farmers struggle to maintain production levels needed for continuous industrial processing. As per the World Meteorological Organization, extreme weather events have increased in frequency, over the past decade disrupting planting schedules and causing sudden shortages of raw materials. Such unpredictability leads to price spikes and production delays which can damage buyer relationships and contract reliability for processors. Thus, climate variability represents a systemic challenge that threatens the stability of input supplies and requires significant investment in resilient agricultural practices and diversified sourcing strategies.
Inadequate Cold Chain and Logistics Infrastructure
The inadequate cold chain and logistics infrastructure is additionally to hinder the growth of the Middle east and Africa dehydrated food market. As per the study, only 10% of perishable goods in Sub Saharan Africa are transported using temperature controlled logistics leading to significant quality degradation even before processing begins. While dehydration removes moisture the initial collection and transport of fresh produce to processing plants require efficient handling to prevent spoilage and contamination. The poor road networks increase transit in rural areas, exposing raw materials to heat and humidity that accelerate deterioration. This inefficiency increases costs for processors who must sort and discard damaged inputs reducing overall yield and profitability. Therefore, logistical bottlenecks act as a major challenge that hinders the efficiency of the supply chain and limits the ability of manufacturers to source high quality raw materials consistently across the region.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 4.86% |
| Segments Covered | By Type, Nature, Technology, Application, and Region. |
| Various Analyses Covered | Global, Regional, and Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | South Africa, Ethiopia, Kenya, Egypt, Sudan, rest of MEA |
| Market Leaders Profiled | Al Dahra Agricultural Company, Nestlé SA, Ajinomoto Co. Inc., Nissin Food Holdings Co. Ltd., National Food Products Company, House Foods Corp., Ting Hsin International Group, General Mills Inc., Kraft Foods Inc., Unilever China Ltd., and Tiger Brands Limited |
SEGMENTAL ANALYSIS
By Type Insights
The dehydrated vegetables segment was the largest by holding 46.3% of the Middle East and Africa Dehydrated Food Market share in 2025 due to their extensive use in traditional cuisines instant soup mixes and ready to eat meals across the region. This deep culinary integration creates consistent baseline demand as households and food manufacturers require reliable supplies of dehydrated vegetables to maintain authentic flavors without the spoilage risks associated with fresh produce. The urbanization has increased consumption of processed foods in major cities,where time constrained consumers prefer pre-prepared ingredients that reduce cooking time. Such lifestyle shifts amplify the utility of dehydrated vegetables in both home kitchens and commercial food production.
The dehydrated fruits segment is projected to register a fastest CAGR of 7.8% during the forecast period driven by rising health consciousness and the popularity of natural snacks among urban consumers. Dehydrated fruits provide a natural source of energy without added preservatives or sugars making them an ideal choice for health aware individuals including children and athletes. The Global Wellness Institute reports that the healthy snacking market in Africa has grown, as retailers expand their offerings of dried mangoes bananas and dates to meet this demand. Such behavioral changes drive significant retail growth as supermarkets and convenience stores dedicate more shelf space to premium dried fruit products.
By Nature Insights
The conventional segment was the largest by holding 59.1% of the Middle East and Africa Dehydrated Food Market share in 2025 due to its affordability widespread availability and established supply chains. According to the World Bank, approximately 40% of the population in Sub Saharan Africa lives below the poverty line making price the primary determinant in food purchasing decisions for most households. Conventional dehydrated foods are significantly cheaper than organic alternatives because they do not incur the high costs associated with certification specialized farming practices and limited yield volumes. The Food and Agriculture Organization states that conventional drying methods using solar or basic mechanical dryers are accessible to smallholder farmers who produce the bulk of raw materials for the local market. This accessibility ensures a steady supply of low cost products that meet the basic nutritional needs of large populations.
The organic segment is likely to exhibit a fastest CAGR of 9.2% from 2026 to 2034 with the increasing health awareness among affluent urban consumers and rising demand for chemical free products in export. According to the survey conducted in major Gulf cities, many consumers actively seek out organic labeled foods due to concerns about pesticide residues and long term health impacts. This growing awareness is particularly strong among younger demographics and expatriate communities, who are willing to pay premium prices for certified organic dehydrated snacks and ingredients. The exposure to agricultural chemicals is a significant public health concern in developing regions prompting educated consumers to opt for safer alternatives. Retailers in countries like the UAE and South Africa are responding by expanding their organic sections and partnering with certified suppliers to meet this niche but lucrative demand.
By Application Insights
The food service and retail segment held a dominant share of the Middle East and Africa Dehydrated Food Market in 2025 due to the extensive network of supermarkets hotels restaurants and cafes that serve as primary distribution channels for consumer-packaged goods. These retail formats offer a wider variety of packaged goods compared to traditional goods, allowing manufacturers to showcase premium dehydrated fruits vegetables and meal kits to a broader audience. The rising middle class incomes in urban centers are driving foot traffic to these stores, where consumers prefer the hygiene and consistency of packaged items. Such retail expansion provides a platform for product visibility and consumer education about the benefits of dehydration.
The household segment is esteemed to witness a fastest CAGR of 6.5% during the forecast period owing to the changing lifestyle patterns and increased home cooking trends, following global health crises. Consumers are seeking convenient ingredients that simplify meal preparation without compromising on nutrition leading to higher purchases of dehydrated vegetables and fruits for daily use. The home cooked meals are perceived as healthier and safer prompting families to stock pantries with shelf stable items that reduce frequent shopping trips. This behavioral shift drives retail sales of consumer sized packages of dehydrated goods directly to households. Dehydrated foods are ideal for home storage because they occupy minimal space and last for months or years without refrigeration.
REGIONAL ANALYSIS
United Arab Emirates Market Analysis
The United Arab Emirates was the largest contributor in the Middle East and Africa Dehydrated Food Market by holding 28.3% of the share in 2025 driven by high disposable incomes and a strong culture of health consciousness among its diverse population. This regulatory framework supports premium pricing and encourages international brands to enter the market with high quality offerings. Additionally, the government’s National Food Security Strategy promotes local innovation in food technology including dehydration to reduce reliance on imports. These factors combine to make the UAE a lucrative hub for premium dehydrated food distributors seeking to target affluent consumers in the Gulf region.
Israel Market Analysis
Israel dehydrated food market was next by holding 19.8% of share in 2025 with the strong research and development capabilities and a focus on innovative agricultural solutions. The exports of dehydrated herbs and specialty vegetables reached record levels in 2023, driven by demand from European and North American countries for premium quality ingredients. Domestically, health conscious consumers prefer organic and non-GMO dehydrated options, which are widely available in supermarkets and health food stores. Additionally, the military and emergency services utilize dehydrated meals for field operations driving steady institutional demand.
Saudi Arabia Market Analysis
Saudi Arabia dehydrated food market growth is expected to have significant opportunities throughout the forecast period with the emphasize healthier lifestyles and food security. The Ministry of Environment Water and Agriculture reports that investments in local date processing facilities have increased by 20% supporting the production of high quality dehydrated dates for both domestic consumption and export. Furthermore the rising prevalence of lifestyle diseases has prompted public health campaigns encouraging the use of natural dried fruits and vegetables as alternatives to sugary snacks. These developments position Saudi Arabia as a key growth engine for the regional dehydrated food industry with strong government support for local production.
South Africa Market Analysis
South Africa occupies a strategic position in the Middle East and Africa Dehydrated Food Market due to its well developed retail infrastructure and strong agricultural export base. The manufacturing sector contributes significantly to the economy with food processing being a major component that utilizes dehydration to extend the shelf life of perishable crops. The rise of health focused retail chains has expanded availability of packaged dehydrated snacks to local consumers. Additionally, government incentives for agro-processing have encouraged value addition allowing farmers to sell branded products rather than raw commodities.
Egypt Market Analysis
Egypt dehydrated food growth is likely to grow with the large-scale production of conventional dehydrated vegetables and herbs for both domestic use and export. According to the Central Agency for Public Mobilization and Statistics, agricultural exports generated substantial revenue in 2023 with dehydrated crops playing a key role due to their low transport costs and long shelf life. Domestic demand is also rising as urban consumers become more aware of the convenience offered by packaged dehydrated ingredients. Government support through subsidies and technical assistance helps farmers manage production costs effectively. These dynamics position Egypt as a major supplier of affordable dehydrated foods to both regional neighbors and global markets.
COMPETITIVE LANDSCAPE
The competition in the Middle East and Africa dehydrated food market is characterized by a mix of large multinational corporations and localized agricultural processors who compete on price quality and brand recognition. Established players leverage their extensive distribution networks and marketing resources to dominate modern retail channels and secure contracts with institutional buyers. Meanwhile smaller regional firms often focus on niche products or traditional drying methods where they can offer authentic flavors at lower costs. Competitors increasingly emphasize sustainability and health benefits as key differentiators to appeal to educated urban consumers. Strategic collaborations with farmers and investment in processing infrastructure are common, as companies seek to secure stable supplies and improve product quality.
KEY MARKET PLAYERS
Some of the key players in the Middle East and Africa dehydrated food market are
- Al Dahra Agricultural Company
- Nestlé SA, Ajinomoto Co. Inc.
- Nissin Food Holdings Co. Ltd.
- National Food Products Company
- House Foods Corp
- Ting Hsin International Group
- General Mills Inc.
- Kraft Foods Inc
- Unilever China Ltd
- Tiger Brands Limited
Top Players in the Market
- Al Dahra Agricultural Company maintains a strong presence in the Middle East and Africa Dehydrated Food Market through its extensive portfolio of dried alfalfa dates and vegetable products. The company focuses on sustainable agricultural practices and advanced processing technologies to ensure high quality outputs for domestic and export markets. Recently, Al Dahra expanded its production facilities in Egypt to increase capacity for dehydrated onions and garlic which are essential staples in regional cuisine. This strategic expansion allows the company to meet growing demand from food manufacturers and retailers, while reducing reliance on imports.
- National Food Products Company contributes significantly to the Middle East and Africa Dehydrated Food Market by offering a wide range of branded dried fruits vegetables and instant meal solutions. The company actively promotes health and wellness through innovative product formulations that cater to changing consumer preferences for convenient and nutritious options. NFPC recently launched a new line of organic dehydrated snacks targeting health-conscious urban consumers in the Gulf Cooperation Council countries. This product innovation aligns with rising awareness of healthy eating habits and expands its customer base beyond traditional retail channels. Additionally, the firm partnered with local farmers to secure consistent supply of high quality raw materials ensuring product consistency and supporting community development.
- Tiger Brands Limited serves as a key player in the Middle East and Africa Dehydrated Food Market leveraging its strong distribution network and diverse brand portfolio to reach consumers. The company specializes in affordable dehydrated soup mixes seasoning blends and dried vegetable packs that are staples in many households. Tiger Brands invested in upgrading its manufacturing processes in South Africa to improve energy efficiency and reduce environmental impact. This sustainability focus helps the company comply with stricter regulatory standards and appeal to environmentally conscious buyers.
Top Strategies Used by Key Market Participants
Key players in the Middle East and Africa Dehydrated Food Market primarily employ vertical integration and product innovation to strengthen their competitive positions. Companies focus on controlling the supply chain from farm to fork to ensure quality consistency and cost efficiency, while minimizing postharvest losses. Another major strategy involves developing value added products such as organic snacks and ready to eat meals that cater to health-conscious urban consumers seeking convenience. Manufacturers also invest in advanced drying technologies like freeze drying to preserve nutrients and enhance flavor profiles thereby differentiating their offerings from conventional alternatives. Additionally, firms expand their geographic reach by establishing partnerships with local distributors and retailers in emerging markets to improve accessibility.
MARKET SEGMENTATION
This research report on the Middle East and Africa dehydrated food market has been segmented and sub-segmented into the following categories.
By Type
- Dehydrated Meat Products
- Dehydrated Vegetables
- Dehydrated Fruits
- Dehydrated Dairy Products
By Nature
- Organic
- Conventional
By Technology
- Spray Drying
- Freeze Drying
- Vacuum Drying
- Drum Drying
By Application
- Food Product Manufacturers
- Food Service & Retail
- Household
By Country
- UAE
- Israel
- KSA
- South Africa
- Egypt