- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$579.26 millionMarket Estimate, 2026
$589.52 millionMarket Forecast, 2034
$678.35 millionCAGR, 2026–2034
1.77%Executive Summary: Middle East and Africa Hemophilia Management Market
- Market Scope: Comprehensive Middle East and Africa (MEA) hemophilia management market analysis covering disorder types, therapeutic drug classes, country-level leadership frameworks, and key genetic health drivers.
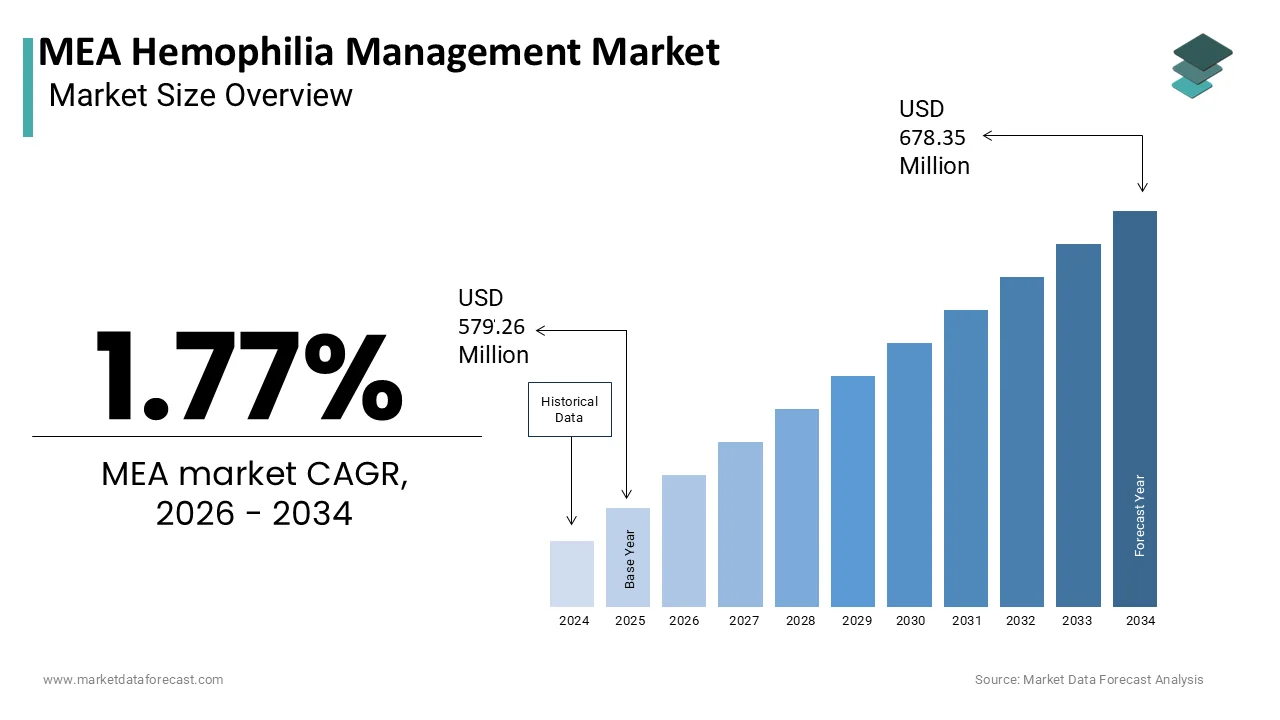
- Market Valuation: Valued at USD 579.26 million (2025), estimated at USD 589.52 million (2026), and projected to reach USD 678.35 million by 2034, registering a steady CAGR of 1.77% (2026–2034).
- Primary Growth Drivers: Increasing prevalence of genetic hemophilia disorders, favorable health insurance and awareness programs, rising healthcare spending, and growing adoption of technologically advanced recombinant factor replacement therapies. Key market restraints include high treatment prices, poor healthcare awareness in parts of Africa, strict regulatory approval processes, and the presence of counterfeit drugs.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Type | Hemophilia A (dominant genetic subtype representing the majority of reported regional bleeding disorders) | Hemophilia B (expanding with targeted recombinant factor treatments) |
| By Drug Class | Octocog alfa (standard recombinant factor VIII coagulation therapy favored by physicians) | Nonacog alfa & Advanced Biologics (scaling with increased R&D and new pharmaceutical product launches) |
| By Country / Region | Saudi Arabia / KSA (dominant regional market share backed by high disposable incomes, recombinant factor availability, and reimbursement policies) | Israel & Egypt (experiencing significant growth through advanced clinical trial funding and tech-driven treatment adoption) |
Major Market Players & Market Structure
Market Structure: Highly competitive pharmaceutical landscape featuring major global biotechnology leaders and specialized rare-disease enterprises competing on recombinant product expansion, clinical trials, and regional healthcare partnerships.
Key Companies: Biogen, Baxter International Inc., Pfizer Inc., Bayer Pharma AG, Novo Nordisk A/S, Grifols International SA, CSL Behring, Octapharma, and Swedish Orphan Biovitrum AB.
 Download Free Sample Report
MEA Hemophilia Management Market Size
The MEA Hemophilia Management Market is projected to grow from USD 579.26 million in 2025 to USD 589.52 million in 2026 and reach USD 678.35 million by 2034, registering a CAGR of 1.77% from 2026 to 2034.
Hemophilia management is a comprehensive medical and lifestyle approach used to prevent, treat, and control bleeding episodes in people with hemophilia. This field addresses the critical need for factor replacement therapies, prophylactic regimens, and emerging gene therapies to prevent hemorrhagic complications. According to the World Federation of Hemophilia, only about 8% of the globally expected hemophilia population is identified in Africa and 42% in the Eastern Mediterranean and Western Pacific regions, with diagnosed patients in Africa receiving limited treatment coverage. This disparity highlights the urgent requirement for expanded access and infrastructure development. As per Cureus, consanguineous marriages in Saudi Arabia are heavily associated with an elevated risk of autosomal recessive rare blood disorders (RBDs), though there is a documented lack of specific epidemiological evidence linking consanguinity directly to higher-than-global averages of X-linked hemophilia. Such epidemiological realities drive government investment in specialised care centres. Regulatory bodies in Gulf Cooperation Council countries are streamlining approvals for novel non-factor therapies to improve patient outcomes. Patient advocacy groups actively collaborate with healthcare providers to enhance awareness and adherence. The integration of telemedicine supports remote monitoring for patients in underserved areas. These factors collectively shape a market transitioning from basic crisis management to comprehensive preventive care models across diverse economic landscapes.
MARKET DRIVERS
Government Initiatives for Rare Disease Awareness and Screening
Aggressive government mandates for rare disease screening and newborn testing propel the MEA Hemophilia Management Market. This facilitates early diagnosis and intervention. National health strategies in several Middle Eastern countries prioritise the identification of genetic disorders to reduce long-term healthcare burdens. According to the United Arab Emirates Ministry of Health and Prevention, the National Neonatal Screening Program covers newborn infants to detect select genetic, endocrine, metabolic, and enzyme disorders early, though the universal protocol does not screen for congenital bleeding disorders like hemophilia. The proactive approach ensures timely initiation of prophylactic therapy, preventing severe joint damage. The Saudi Human Genome Program targeted the sequencing of 100,000 human genomes to identify genetic mutations predisposing the population to inherited and rare genetic diseases to support preventive counselling and personalised care. Early detection reduces emergency hospitalisations and associated costs, making preventive care economically viable for public health systems. Government-funded registries provide accurate epidemiological data guiding resource allocation and policy formulation. Public awareness campaigns reduce social stigma, encouraging families to seek medical help. Insurance mandates in some Gulf countries require coverage for rare diseases, ensuring financial accessibility. These top-down initiatives create a structured environment for market growth. They establish a foundation for sustained demand for advanced therapeutic options.
Increasing Prevalence Due to Consanguinity
The high rate of consanguineous marriages in the region strongly fuels the growth of the MEA Hemophilia Management Market. This sustains a large patient pool requiring lifelong treatment. Cultural practices involving marriage between close relatives significantly increase the incidence of X-linked recessive disorders like hemophilia A and B. According to the Journal of Community Genetics, consanguineous marriages feature high frequencies in many Middle Eastern populations, significantly increasing the specific risk and expression of autosomal recessive genetic disorders within families. This demographic reality ensures a consistent and growing demand for clotting factor concentrates and bypassing agents. As per the World Health Organisation Eastern Mediterranean Regional Office, community genetics programs and preconception counselling are expanding across the region to manage inherited blood disorders, though systemic challenges remain in altering established custom-driven marital practices. Healthcare systems must therefore support a substantial number of severe cases requiring regular infusions. Patient registries in Egypt and Iran document thousands of active cases, driving procurement of therapeutic supplies. Pharmaceutical companies recognise this concentrated demand and invest in local distribution networks. Government subsidies for factor products make treatment accessible to low-income families. This persistent epidemiological factor underpins the structural necessity of the market. It compels continuous investment in care infrastructure and supply chain resilience.
MARKET RESTRAINTS
High Cost of Advanced Therapeutic Agents
Exorbitant costs of novel therapies and factor concentrates constrain the expansion of the MEA Hemophilia Management Market. This limits access for public healthcare systems and uninsured patients. Extended half-life factors and non-factor therapies command premium prices that strain national health budgets in many African and Middle Eastern countries. According to sources, the average annual cost of care for severe haemophilia can range up to $700,070 per person per year depending on treatment modality and geographic location, driven primarily by the high cost of clotting factor replacement therapy. Many governments cannot afford universal coverage for these expensive treatments, forcing reliance on on-demand therapy, which is less effective. The lack of local manufacturing capabilities for complex biologics necessitates imports subject to currency fluctuations and tariffs. Private insurance coverage is limited in many African nations, leaving patients to bear out-of-pocket expenses. Budget constraints lead to rationing of factor supplies, causing treatment interruptions. Hospitals struggle to maintain adequate stock levels due to cash flow issues. This financial burden prevents widespread adoption of standard-of-care prophylaxis. Patients often suffer preventable bleeds due to affordability issues. High costs stifle market expansion despite clinical availability.
Limited Healthcare Infrastructure and Specialist Shortage
Inadequate healthcare infrastructure and scarcity of haematologists inhibit the growth of the MEA Hemophilia Management Market. This restricts diagnosis and proper disease management. Many rural areas in Africa and parts of the Middle East lack specialised haemophilia treatment centres equipped for comprehensive care. According to the World Health Organisation, the density of core health workers (doctors, nurses, and midwives combined) in the WHO African Region averages 1.55 per 1,000 population, with many countries facing severe shortages that restrict access to basic and specialist care. This shortage means many patients remain undiagnosed or receive suboptimal treatment from general practitioners unfamiliar with bleeding disorders. Laboratory facilities for accurate coagulation testing are scarce in remote regions, delaying confirmation of diagnosis. Cold chain logistics for storing temperature-sensitive factor concentrates are unreliable in areas with unstable electricity supply. Lack of multidisciplinary teams, including physiotherapists and orthopaedic surgeons, hinders holistic management. Training programs for healthcare workers are insufficient to meet growing demand. Patients travel long distances to urban centres, increasing treatment burden and costs. These structural deficiencies prevent effective implementation of national management guidelines. The gap between urban and rural care quality remains wide. Infrastructure deficits constrain market penetration significantly.
MARKET OPPORTUNITIES
Expansion of Telemedicine and Remote Monitoring
The rapid adoption of telemedicine and remote monitoring technologies offers a major opportunity for the MEA Haemophilia Management Market. This overcomes geographic barriers to specialist care. Digital health platforms enable patients in remote areas to consult with haematologists and receive guidance on home infusion techniques without travelling to urban centres. According to sources, telehealth interventions and digital monitoring applications have been integrated into haematology care pathways within resource-limited areas to enhance patient education and support tracking of factor adherence rates. Mobile applications allow patients to log bleeding episodes and factor usage, generating real-world data for clinicians. Governments in the Gulf Cooperation Council are investing in digital health infrastructure supporting virtual care models. Remote monitoring reduces hospital visits, lowering overall healthcare costs and improving quality of life. Pharmaceutical companies partner with tech firms to offer integrated patient support programs. Data analytics from these platforms help optimise inventory management for factor supplies. Training webinars for local healthcare providers enhance capacity building. This digital shift expands the addressable market beyond major cities. It enables scalable management of chronic conditions in dispersed populations.
Development of Local Manufacturing Capabilities
Establishing local manufacturing facilities for biosimilars and factor concentrates unlocks potential for the MEA Haemophilia Management Market. This reduces dependency on imports and lowers costs. Several countries in the region are investing in biopharmaceutical production to achieve self-sufficiency in essential medicines. According to national strategy targets under Saudi Arabia's Vision 2030, the government is incentivising pharmaceutical investments to expand local manufacturing capabilities to fulfil at least 40% of the total drug market volume. Local manufacturing reduces exposure to currency fluctuations and supply chain disruptions affecting imported therapies. Biosimilar versions of clotting factors can be produced at lower costs, making prophylaxis more affordable for public health systems. Technology transfer agreements with global pharmaceutical companies facilitate knowledge sharing and quality assurance. Government incentives such as tax breaks and preferential procurement policies support local manufacturers. This strategy aligns with broader economic diversification efforts in the Middle East. Improved availability of affordable products expands patient access. It creates jobs and builds technical expertise within the region. Local production enhances resilience against global shortages.
MARKET CHALLENGES
Supply Chain Vulnerabilities and Cold Chain Requirements
Complex supply chain logistics and strict cold chain requirements challenge the MEA Haemophilia Management Market. This risks product integrity and availability. Clotting factor concentrates are temperature-sensitive biologics that require uninterrupted refrigeration from manufacturing to administration. According to the World Health Organisation, up to 50% of vaccines are wasted globally every year, a loss driven largely by a lack of temperature control, transport logistics, and shipment-related cold-chain failures. In many African countries, extreme heat and poor road networks compromise product stability during last-mile delivery. Power outages in hospitals and pharmacies threaten stored inventory, leading to significant financial losses. Import delays due to customs bottlenecks further disrupt supply continuity. Lack of real-time temperature monitoring devices in transit increases uncertainty. Manufacturers face high costs for specialised packaging and logistics partners. Stockouts force patients to miss doses, increasing bleeding risks. Emergency imports are expensive and slow to arrange. These logistical hurdles undermine confidence in treatment reliability. Ensuring consistent quality across vast geographies remains a persistent operational challenge.
Low Awareness and Social Stigma
Persistent lack of public awareness and deep-rooted social stigma constrain the MEA Haemophilia Management Market. This hinders early diagnosis and treatment-seeking behaviour. Many communities view bleeding disorders as supernatural curses or familial shame, leading to concealment of affected individuals. As per the World Federation of Haemophilia, close to 70% of the estimated people living with haemophilia worldwide remain undiagnosed due to a lack of systematic clinical infrastructure, diagnostic inequities, and social stigma. This silence prevents patients from accessing available care and support services. Misconceptions about inheritance patterns discourage family planning and genetic counselling. Women carriers often face marital difficulties due to fear of passing the gene. Religious interpretations sometimes conflict with medical advice regarding treatment options. Educational campaigns struggle to penetrate conservative rural areas effectively. Healthcare providers may lack training to communicate sensitively about genetic risks. Stigma reduces participation in patient support groups and clinical trials. This cultural barrier slows market education and product adoption. Overcoming deeply entrenched beliefs requires sustained community engagement and culturally appropriate messaging. Until stigma decreases, hidden suffering will persist.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Type, Drug, and Region |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered | KSA, UAE, Israel, Rest of GCC countries |
| Market Leaders Profiled | BiogenBaxter International Inc., Pfizer Inc., Bayer Pharma AGNovo Nordisk A/SGrifols International SAC, S.C.L., Behring, Octapharma, Swedish Orphan Biovitrum AB |
SEGMENTAL ANALYSIS
By Type Insights
The hemophilia A segment dominated the MEA Hemophilia Management Market and accounted for a substantial share in 2025. This dominance of the segment was driven by its significantly higher prevalence compared to Hemophilia B and the consequent greater demand for Factor VIII replacement therapies. According to the World Federation of Hemophilia, Hemophilia A represents approximately 80% to 85% of the total hemophilia population globally, presenting a significantly larger patient base requiring consistent clinical factor therapy. As per the World Federation of Hemophilia Annual Global Survey, the total number of identified people with bleeding disorders worldwide has surpassed 400,000, with over 250,000 explicitly diagnosed with Hemophilia A, driving factor registry enrollment and resource mapping in developing countries. The high incidence rate necessitates robust supply chains for Factor VIII concentrates, which constitute the largest revenue share in the region. According to studies, Hemophilia A represents a major inherited bleeding disorder requiring national care infrastructure, although von Willebrand disease (vWD) remains epidemiologically classified as the most common inherited bleeding disorder overall. Public health programs prioritise this condition due to the severity of spontaneous bleeding episodes associated with severe deficiency. Patient registries in Egypt and Iran document thousands of active Hemophilia A cases, ensuring steady demand for therapeutic agents. Pharmaceutical companies focus their marketing and distribution efforts on Factor VIII products to capture this dominant segment. Government subsidies often target Hemophilia A treatments first due to the larger affected population. This demographic reality sustains market leadership through volume-driven consumption. Clinical guidelines emphasise prophylaxis for severe Hemophilia A, further boosting product usage.
The hemophilia B segment is on the rise and is expected to be the fastest-growing segment in the market,y witnessing a CAGR of 6.8% from 2026 to 2034. This rapid growth is propelled by improved diagnostic capabilities and the introduction of novel long-acting Factor IX therapies. While less prevalent than Hemophilia A, increased awareness and genetic screening are identifying previously undiagnosed cases in rural and underserved areas. As per the Journal of Thrombosis and Haemostasis, the deployment of extended half-life (EHL) Factor IX products reduces infusion frequency from twice weekly to once weekly, or every 10 to 14 days, significantly lessening treatment burden and improving patient compliance. This convenience factor encourages more patients to seek diagnosis and initiate prophylactic treatment. According to the World Health Organisation Eastern Mediterranean Regional Office, newborn screening programs in Gulf Cooperation Council countries focus primarily on metabolic, endocrine, and hemoglobinopathies, whereas congenital bleeding disorders like Hemophilia B are typically diagnosed through targeted clinical coagulation assays following symptoms or family history. Early intervention prevents joint damage and reduces long term healthcare costs, making treatment more economically attractive to payers. Regulatory approvals for new biosimilar Factor IX products in countries like Saudi Arabia and South Africa are lowering costs and increasing accessibility. Patient advocacy groups specifically targeting Hemophilia B are reducing stigma and encouraging help-seeking behaviour. Clinical trials for gene therapies targeting Factor IX deficiency are showing promising results, generating optimism among clinicians. These advancements drive rapid adoption and market expansion for Hemophilia B management solutions.
By Drug Insights
The octocog alfa segment led the MEA Hemophilia Management Market and captured a significant share in 2025. This leading position of the segment was attributed to its widespread use as a recombinant Factor VIII concentrate for treating Hemophilia A. In addition, this medication is the standard of care for prophylaxis and on-demand treatment of bleeding episodes, offering high purity and reduced risk of viral transmission compared to plasma-derived products. According to the European Medicines Agency, octocog alfa exhibits a consistent clinical efficacy and safety profile in providing control and prophylaxis of bleeding episodes in patients with Hemophilia A. The Saudi Food and Drug Authority has approved several recombinant Factor VIII brands (including those utilising octocog alfa) to satisfy clinical demand within institutional purchasing frameworks. As per the World Federation of Hemophilia, the clinical transition from plasma-derived concentrates to recombinant factor technologies is heavily prioritised where economic capacity permits due to historical concerns regarding viral safety and blood-borne pathogens. Large-scale government tenders in Egypt and Algeria frequently include octocog alfa as a primary item, securing high-volume sales for manufacturers. Clinical guidelines from regional haematology societies recommend recombinant Factor VIII as first-line therapy for severe Hemophilia A. Insurance schemes in the United Arab Emirates cover branded recombinant factors, facilitating patient access. The established manufacturing infrastructure for octocog alfa ensures reliable delivery even during global supply fluctuations. Physicians trust its long track record of clinical success. This entrenched status sustains its market dominance despite the emergence of newer agents.
The nonacog alfa segment is likely to experience the fastest CAGR of 7.5% during the forecast period owing to the rising diagnosis of Hemophilia B and the adoption of recombinant Factor IX therapies. This recombinant product offers a safer alternative to plasma-derived Factor IX with lower immunogenicity risks, appealing to clinicians and patients alike. According to the International Society on Thrombosis and Haemostasis guidelines, access to Factor IX replacement therapy remains a priority for Hemophilia B management, while the introduction of biosimilar and extended half-life options slowly modifies market availability as procurement constraints drop. As per the African Society for Laboratory Medicine, improving basic coagulation testing and factor assay access is vital for identifying bleeding disorders, though widespread specific monitoring of nonacog alfa therapy remains constrained by specialised reagent costs. Governments in Kuwait and Qatar are updating their essential medicines lists to include newer recombinant Factor IX products, reflecting a commitment to advanced care standards. Patient support programs provided by manufacturers educate communities about Hemophilia B treatment options, driving demand. The convenience of subcutaneous administration formats under development for Factor IX therapies is anticipated to further boost adoption rates. Clinical data demonstrating reduced inhibitor development with recombinant products reinforces prescribing preferences. Local distributors are expanding their portfolios to include nonacog alfa to meet growing hospital requests. This momentum positions nonacog alfa as a key growth driver in the hemophilia drug market.
COUNTRY LEVEL ANALYSIS
Saudi Arabia Hemophilia Management Market Analysis
Saudi Arabia was the top performer in the MEA Hemophilia Management Market and occupied a commanding share in 2025. This supremacy of the Saudi market was driven by strong government support and comprehensive national healthcare programs. The Kingdom has established specialized hemophilia centers across major cities,s ensuring accessible care for patients. According to sources, the unified registry tracks approximately 1,489 hemophilia patients across Saudi provinces to streamline specialized healthcare data collection. Vision 2030 initiatives prioritize rare disease management,nt leading to increased funding for factor concentrates and novel therapies. The Saudi Food and Drug Authority expedites approvals for innovative treatments such as extended half-life factors, enhancing patient access. High consanguinity rates sustain a significant patient population requiring lifelong management. Public insurance covers the full cost of hemophilia treatment, removing financial barriers for citizens. Partnerships with international pharmaceutical companies ensure a steady supply of high-quality products. Research collaborations with global institutions contribute to clinical knowledge and best practices. This robust infrastructure supports sustained market growth and high treatment adherence rates.
United Arab Emirates Hemophilia Management Market Analysis
The United Arab Emirates was the next prominent region in the MEA hemophilia management market in 2025. This position was supported by advanced healthcare infrastructure and high adoption of premium hemophilia therapies. The country serves as a regional hub for medical excellence, attracting patients from neighboring nations. According to the Dubai Health Insurance Law (Law No. 11 of 2013), all compliant Essential Benefits Plans (EBP) mandated by the Dubai Health Authority must cover chronic and pre-existing conditions under an established minimum annual aggregate limit of AED 150,000. The UAE Ministry of Health and Prevention implements strict quality controls for imported biological products,s guaranteeing safety and efficacy. High per capita healthcare spending enables the use of latest-generation recombinant factors and prophylactic regimens. Specialized clinics in Abu Dhabi and Dubai offer multidisciplinary care including physiotherapy and psychological support. Government initiatives promote genetic counseling to reduce incidence rates. The presence of major pharmaceutical headquarters facilitates early access to new drugs. Digital health integration supports remote monitoring and patient engagement. This sophisticated environment drives demand for high-value hemophilia management solutions.
Israel Hemophilia Management Market Analysis
Israel grew steadily in the MEA hemophilia management market because of world-class research capabilities and advanced therapeutic adoption. The country has a well-established hemophilia treatment network supported by universal health coverage. As per the Israeli Ministry of Health, national guidelines emphasize early prophylaxis and comprehensive care,e resulting in excellent patient outcomes. Israel participates in global clinical trials for gene therapies and novel factor products, ts providing early access to cutting-edge treatments. Strong biomedical research institutions contribute to innovation in hemophilia management technologies. High physician expertise ensures optimal utilization of available therapies. Patient advocacy groups actively collaborate with policymakers to improve service delivery. The small population size allows for efficient centralized management and data collection. Regulatory frameworks are aligned with international standards, facilitating rapid product launches. This innovation-driven approach positions Israel as a leader in clinical excellence.
South Africa Hemophilia Management Market Analysis
South Africa is also a key player in the MEA hemophilia management market due to a relatively developed healthcare infrastructure and active patient advocacy. The country has established hemophilia foundations that collaborate with government and private sectors to improve care access. According to the National Health Laboratory Service (NHLS), specialized coagulation testing frameworks operate within major urban academic hospital laboratories to support clinical diagnosis and treatment monitoring across public health networks. Private medical schemes cover advanced therapies for insured patients, while public sector access remains limited but is improving. Local manufacturing of some blood products reduces reliance on imports for certain treatments. Academic institutions research hemophilia prevalence and treatment outcomes in the African context. Training programs for healthcare workers enhance capacity in rural areas. Patient registries help quantify disease burden and guide policy decisions. Economic constraints challenge widespread adoption of expensive novel therapies, but basic care is accessible. This dual system dynamic shapes unique market characteristics.
Egypt Hemophilia Management Market Analysis
Egypt is quickly accelerating in the MEA hemophilia management market owing to its large population and an established national hemophilia program. The government provides subsidized factor concentrates through public hospitals, ls ensuring basic access for many patients. According to ScienceDirect, the Egyptian public health ecosystem channels suspected bleeding disorders into two primary highly specialized reference centers to provide confirmatory diagnostics and clotting factor assay evaluations. High prevalence rates driven by genetic factors create substantial demand for therapeutic agents. Local production of some plasma-derived products helps mitigate supply shortages. International collaborations support training and capacity building for healthcare professionals. Patient registries assist in monitoring treatment outcomes and resource needs. Economic pressures limit access to newer, expensive therapies, but basic care is widely available. Awareness campaigns target rural communities to reduce late diagnoses. This scale ensures Egypt remains a critical market for volume-driven strategies.
Kenya Hemophilia Management Market Analysis
Kenya is an emerging country within the MEA hemophilia management market. It holds strategic importance as a regional hub for hemophilia advocacy and care in East Africa. According to official operational briefings from the Ministry of Health, the Kenya Haemophilia Association collaborates directly with health officials to expand patient support registries and incorporate clotting factor options under national social health frameworks. As per the Kenya Haemophilia Association, roughly 1,200 out of an estimated 5,000 hemophilia cases in Kenya have been formally diagnosed, with detected cases heavily concentrated around referral institutions in major urban areas. Private insurance schemes cover hemophilia treatment for a growing middle-class population. Public hospitals face supply challenges but receive support from international partners for factor provision. Mobile health initiatives help track patient status and manage appointments effectively. Training workshops for doctors and nurses enhance clinical skills in managing bleeding disorders. Local fundraising efforts supplement government resources for patient care. Nairobi serves as a center for regional conferences and knowledge sharing. This active civil society engagement drives incremental improvements in market access.
COMPETITIVE LANDSCAPE
The competition in the MEA Hemophilia Management Market is characterized by the presence of established global pharmaceutical giants and emerging regional players striving for dominance. Major companies compete primarily on product efficacy, safetprofilesss,s and patient support services rather than price alone. The market exhibits moderate consolidation, with leading firms holding significant influence due to their extensive distribution networks and brand reputation. High barriers to entry such as complex manufacturing requirements and stringent regulatory standards protect incumbent providers from new competitors. Innovation in extended half-life factors and gene therapies serves as a key differentiator for premium brands. Strategic alliances with local governments and healthcare providers help navigate fragmented regulatory landscapes across the Middle East and Africa. Trust remains a critical factor as patients and clinicians prioritize reliable supply and proven clinical outcomes. Supply chain resilience is increasingly important due to logistical challenges in remote areas. Companies that demonstrate commitment to patient education and access gain competitive advantage. This dynamic environment fosters steady growth for established players who can balance innovation with affordability. New entrants face significant hurdles in building credibility and scaling operations efficiently amidst economic constraints.
KEY MARKET PLAYERS
Some of the companies that are playing a dominating role in the Middle East & Africa Hemophilia Management Market include:
- Biogen
- Baxter International Inc.
- Pfizer Inc.
- Bayer Pharma AG
- Novo Nordisk A/S
- Grifols International SA
- CSL Behring
- Octapharma
- Swedish Orphan Biovitrum AB
TOP LEADING PLAYERS IN THE MARKET
- Takeda Pharmaceutical Company Limited maintains a strong presence in the MEA Hemophilia Management Market through its comprehensive portfolio of factor replacement therapies and non-factor treatments. The company focuses on providing advanced solutions for both Hemophilia A and B, including extended half-life products that improve patient quality of life. Takeda recently expanded its patient support programs in Saudi Arabia and South Africa to enhance treatment adherence and education. This initiative helps overcome barriers related to disease management and stigma in local communities. The firm collaborates with regional healthcare authorities to facilitate regulatory approvals and market access for novel therapies. Takeda invests in local training for healthcare professionals to ensure optimal use of its products. These efforts strengthen its reputation as a committed partner in rare disease care. The company also supports patient advocacy groups to raise awareness and drive policy changes. Such strategic engagements foster long-term trust and loyalty among stakeholders. Takeda continues to innovate its pipeline with gene therapy candidates tailored for global needs.
- Bayer AG plays a pivotal role in the MEA Hemophilia Management Market by offering high-quality recombinant factor concentrates and innovative hemostasis solutions. The company leverages its extensive distribution network to ensure reliable supply of critical medications across diverse geographies. Bayer recently launched educational campaigns in Egypt and Kenya to improve early diagnosis rates and clinical understanding of bleeding disorders. This outreach aims to bridge knowledge gaps among physicians and patients in resource-limited settings. The firm partners with local manufacturers and distributors to enhance accessibility and affordability of its products. Bayer emphasizes sustainability and corporate social responsibility by supporting community health initiatives. Its commitment to research and development drives the introduction of next-generation therapies with improved safety profiles. Regulatory engagement in Gulf Cooperation Council countries facilitates faster product launches. Bayer provides comprehensive patient assistance programs to mitigate financial burdens. These actions reinforce its position as a leader in hemophilia care innovation.
- CSL Behring contributes significantly to the MEA Hemophilia Management Market through its specialized plasma-derived and recombinant factor therapies. The company focuses on delivering consistent and safe treatment options for patients with severe bleeding disorders. CSL Behring recently strengthened its supply chain infrastructure in the United Arab Emirates to ensure uninterrupted availability of factor concentrates. This strategic move addresses logistical challenges and enhances reliability for healthcare providers. The organization collaborates with national hemophilia registries to support data collection and epidemiological research. CSL Behring invests in capacity building for laboratory technicians to improve diagnostic accuracy in the region. Its patient-centric approach includes dedicated support services for home infusion therapy. The company actively participates in regional medical conferences to share clinical expertise and best practices. Regulatory compliance with local standards ensures product quality and safety. These initiatives build strong relationships with key opinion leaders and healthcare institutions. CSL Behring remains dedicated to advancing care standards for hemophilia patients.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the MEA Hemophilia Management Market employ diverse strategies to maintain competitive advantage and drive sustainable growth. Establishing robust patient support programs remains a primary strategy to improve treatment adherence and outcomes in regions with limited healthcare infrastructure. Strategic partnerships with local distributors and government bodies facilitate market entry and ensure consistent supply of essential therapies. Companies invest heavily in educational initiatives targeting healthcare professionals and patients to raise awareness and reduce stigma associated with bleeding disorders. Regulatory engagement is crucial for navigating complex approval processes and securing reimbursement for high-cost treatments in various countries. Pricing strategies often include tiered models or donation programs to enhance accessibility in low-income markets. Investment in local manufacturing or packaging capabilities helps mitigate supply chain risks and currency fluctuations. Digital health tools are increasingly integrated to support remote monitoring and patient engagement. Collaborations with patient advocacy groups strengthen community ties and influence policy decisions. These multifaceted approaches enable firms to address unique regional challenges effectively while expanding their footprint.
MARKET SEGMENTATION
This research report on the MEA Hemophilia Management Market is segmented and sub-segmented into the following categories
By Type
- Hemophilia A
- Hemophilia B
By Drug
- Octocogalfa
- Nonacogalfa
- Desmopressin
- Other Drugs
By Country
- KSA
- UAE
- Israel
- Rest of GCC countries
- South Africa
- Ethiopia
- Kenya
- Egypt
- Sudan
- Rest of MEA