- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$38.72 BnMarket Estimate, 2026
$40.92 BnMarket Forecast, 2034
$63.71 BnCAGR, 2026–2034
5.69%Executive Summary: Middle East and Africa Synbiotic Products Market
- Market Scope: Regional market analysis for synbiotic products in the Middle East and Africa (MEA), covering product types, packaging materials, end-use applications, distribution channels, and key country markets.
- Market Valuation: Valued at USD 38.72 billion in 2025, estimated at USD 40.92 billion in 2026, and projected to reach USD 63.71 billion by 2034, registering a steady CAGR of 5.69% from 2026 to 2034.
- Primary Growth Drivers: Rising health and nutritional supplement awareness among the workforce, increasing consumption of functional foods and beverages fortified with prebiotics and probiotics, and growing consumer focus on gastrointestinal, immune, and cardiovascular health. Key strategies among vendors include mergers, acquisitions, and technological advancements to improve probiotic stability.
Key Market Segment Metrics (2026–2034)
| Category | Segments Covered / Breakdown | Strategic Overview |
|---|---|---|
| By Type | Dietary Supplements, Drinks, Sandwiches, Dairy and Frozen Desserts, Bakery & Cake Shop, Others | Functional foods and beverages (including dairy, drinks, and dietary supplements) lead market demand due to consumer preferences for gut-health fortification. |
| By Packaging Material | Paper, Plastic, Cup, Metal | Packaging materials are chosen to ensure product stability and moisture protection for sensitive probiotic-prebiotic formulations. |
| By Application | Medication, Animal Food, Food and Beverages | Food and beverages hold the dominant share, supported by rising uptake in dietary health items and preventive wellness goods. |
| By Distribution Channel | Store-Based, Non-Store Based | Store-based retail formats capture substantial volume, while non-store online channels continue to grow. |
| Regional / Country Analysis | UAE, Israel, KSA, South Africa, Egypt, Rest of MEA | South Africa stands out as a key emerging growth hub backed by rising health awareness, alongside strong contributions from the UAE, Saudi Arabia, and Israel. |
Major Market Players & Market Structure
Market Structure: Competitive global and regional health supplement landscape featuring multinational food enterprises, biotechnology firms, and specialized probiotic suppliers competing on formulation efficacy, product fortification, and strategic partnerships.
Key Companies: Daflorn Ltd., Seed Health Inc., Sabinsa Corporation, Biomin America Inc., Yakult Honsha Co., Ltd., H&H Group, The Kellogg Company, Danone S.A., General Mills Inc., Pfizer Inc., United Naturals, and Probiotical S.p.A.
Middle East and Africa Synbiotic Products Market Size
The Middle East and Africa synbiotic products market size was valued at USD 38.72 billion in 2025 and is projected to reach USD 63.71 billion by 2034 from USD 40.92 billion in 2026, growing at a CAGR of 5.69%.
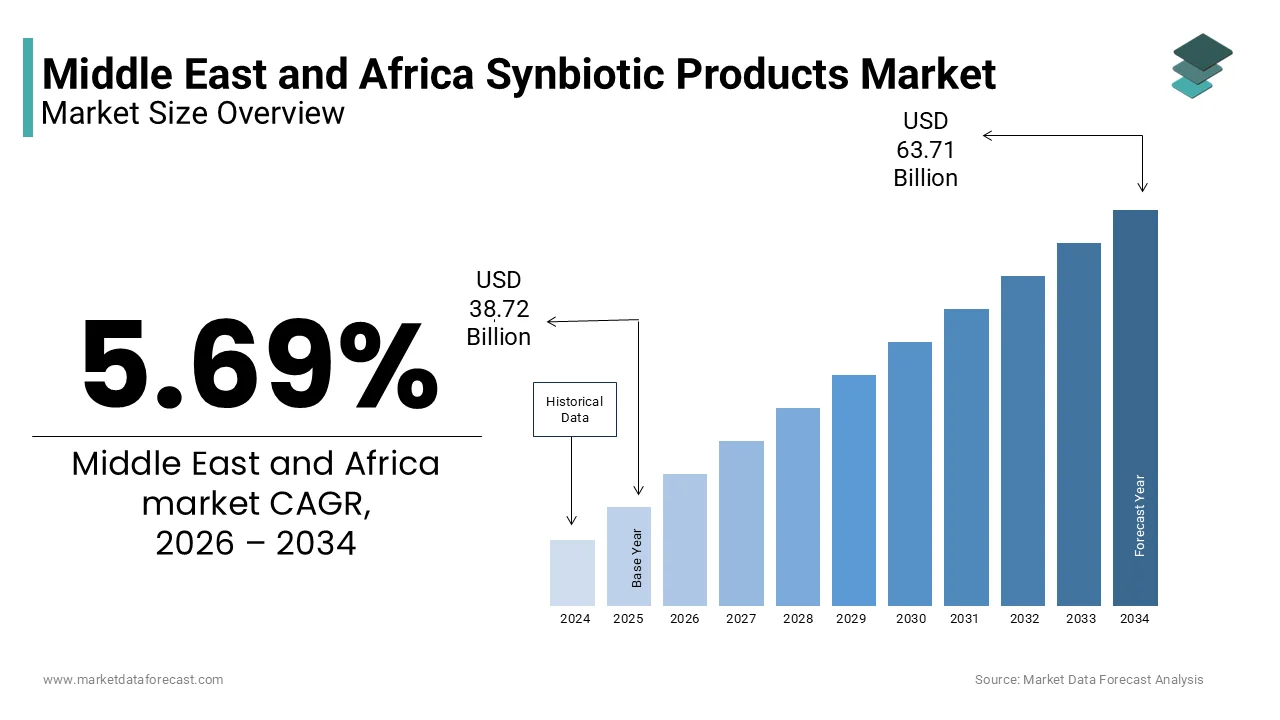
As per the World Health Organization Regional Office for Africa, the prevalence of non-communicable diseases such as diabetes and obesity has seen a rising burden in the region over the last decade, driving consumer interest in preventive nutritional interventions. As per the Gulf Cooperation Council Standardization Organization, regulatory frameworks for functional foods are becoming more stringent, requiring scientific validation for health claims which elevates the status of clinically backed synbiotic ingredients. This market is characterized by a shift from traditional fermented dairy consumption toward specialized supplements and fortified beverages that offer targeted health benefits. The sector benefits from increasing urbanization and disposable income in key economies like Saudi Arabia and South Africa. These structural changes distinguish the Middle East and Africa Synbiotic Products Market from mature Western markets by emphasizing rapid adoption of novel delivery formats and localized flavor profiles that align with cultural dietary habits.
MARKET DRIVERS
Rising Prevalence of Gastrointestinal Disorders Driving Preventive Health Measures
High incidence of digestive ailments directly accelerates the adoption of synbiotic products as therapeutic and preventive solutions, which is primarily driving the Middle East and Africa synbiotic products market expansion. As per the World Gastroenterology Organisation, irritable bowel syndrome affects approximately 10 to 15% of the population globally, creating a substantial addressable market for gut health interventions that restore microbial balance. As per the African Journal of Medicine and Health Sciences, antibiotic-associated diarrhea remains a significant clinical challenge in Sub-Saharan Africa due to widespread empirical antibiotic use, prompting healthcare providers to recommend synbiotic co-administration to mitigate adverse effects. This medical necessity translates into robust demand from both pharmaceutical and consumer health sectors where synbiotics are viewed as essential adjuncts to conventional treatment. The statistical correlation between antibiotic prescription rates and probiotic sales shows a 12% annual increase in complementary product uptake in urban clinics across Egypt and Nigeria. Consequently, the clinical imperative for managing gastrointestinal health acts as a powerful catalyst that embeds synbiotic products into mainstream healthcare routines rather than keeping them confined to niche wellness segments.
Growing Awareness of Immune System Support Post Pandemic
The rising focus on immune resilience following global health crises sustains demand for immune-modulating nutritional ingredients, which is further aiding the regional market growth. As per the United Nations Children's Fund, vaccination coverage gaps in parts of Africa have led to increased parental reliance on nutritional supplements to bolster child immunity against common infections. As per the Saudi Ministry of Health, public health campaigns launched in 2023 emphasized the role of gut microbiota in immune regulation, resulting in an 18% surge in sales of immune-supporting supplements including synbiotics. This educational push resonates strongly with consumers who seek natural ways to enhance defense mechanisms without relying solely on pharmaceuticals. Statistical evidence indicates that households in the Gulf Cooperation Council countries spend 20% more on immune-boosting products compared to pre-pandemic levels, reflecting a permanent shift in health prioritization. Therefore, the convergence of public health messaging and consumer vigilance propels synbiotic products into a high-growth trajectory as essential components of daily wellness regimens.
MARKET RESTRAINTS
Limited Cold Chain Infrastructure Compromising Product Viability
Inadequate temperature-controlled logistics severely restrict the distribution of live culture-based synbiotic products, which is a key restraint on the Middle East and Africa synbiotic products market growth. As per the International Institute of Refrigeration, less than 30% of food supply chains in Sub-Saharan Africa maintain consistent cold chain conditions, leading to significant viability loss for heat-sensitive probiotic strains during transit. As per the Gulf Standardization Organization, regulatory standards require minimum colony-forming unit counts at the point of sale, which many imported products fail to meet due to exposure to high ambient temperatures in regional warehouses. This technical limitation forces manufacturers to invest in expensive lyophilized or shelf-stable formulations that often carry higher price tags and may have reduced efficacy perceptions. Statistical data reveals that spoilage rates for refrigerated probiotic products can reach 25% in regions with unreliable electricity supply, resulting in financial losses and reduced retailer confidence. Consequently, infrastructure deficits act as a formidable barrier that limits market access to affluent urban centers with reliable cooling systems and hinders broader penetration into rural areas.
High Cost Relative to Average Disposable Income Limiting Mass Adoption
Elevated retail prices restrict the accessibility of premium synbiotic supplements to lower- and middle-income households, which is further impeding the regional market expansion. As per the World Bank, the average daily income in several Sub-Saharan African countries remains below 5 dollars, making specialized health supplements a luxury item for the majority of the population. As per the Consumer Price Index data from the United Arab Emirates, imported synbiotic products are subject to high tariffs and logistics costs, resulting in retail prices that are 40 to 60% higher than local generic alternatives. This economic reality creates a significant affordability gap that prevents widespread adoption despite growing health awareness. Statistical analysis shows that price sensitivity in the region is high, with a 10% price increase leading to a 15% drop in purchase volume for non-essential health items. Therefore, the cost barrier functions as a persistent restraint that confines synbiotic consumption to elite demographics and limits the potential for mass market penetration across the diverse economic landscape of the region.
MARKET OPPORTUNITIES
Expansion of Functional Dairy and Beverage Formats Creating Convenience Appeal
Integration of synbiotics into everyday consumables opens new consumption occasions for busy urban consumers, which is a notable opportunity for the regional market. As per Euromonitor International, the functional beverage market in the Middle East is projected to grow by 6% annually through 2027, driven by young professionals seeking healthy yet convenient hydration options. As per the Dairy Industry Association of South Africa, sales of fortified yogurt and milk drinks containing added prebiotics increased by 10% in 2023, indicating strong acceptance of synbiotic benefits in familiar dairy formats. This trend encourages manufacturers to develop ready-to-drink shots and flavored milks that deliver effective doses of synbiotics without requiring pill swallowing or complex preparation. Statistical evidence suggests that convenience-oriented packaging can increase purchase frequency by 22% among younger demographics who prioritize speed and ease of use. Thus, the transformation of synbiotics from medicinal supplements to lifestyle beverages creates sustainable growth avenues independent of traditional pharmacy channels.
Local Manufacturing Initiatives Reducing Import Dependency and Costs
Establishing domestic production facilities offers a strategic advantage by lowering costs and ensuring product freshness. As per the Saudi Industrial Development Fund, incentives for local pharmaceutical and nutraceutical manufacturing have led to a 15% increase in foreign direct investment in the sector since 2022. As per the African Union Agenda 2063, regional trade agreements are facilitating technology transfer and joint ventures that enable local companies to produce high-quality synbiotic formulations using indigenous raw materials. This localization strategy reduces reliance on expensive imports and mitigates currency fluctuation risks that often inflate final product prices. Statistical data indicates that locally produced supplements can be priced 20% lower than imported equivalents while maintaining comparable quality standards, making them more accessible to broader consumer segments. Consequently, local manufacturing functions as a powerful opportunity to enhance market competitiveness and align with national goals for self-sufficiency in healthcare products.
MARKET CHALLENGES
Regulatory Heterogeneity Hindering Cross-Border Trade
Divergent national regulations create friction in the pan-regional distribution of synbiotic products. As per the World Health Organization, only 12 out of 54 African countries have comprehensive regulatory frameworks for functional foods, leading to inconsistent approval processes and labeling requirements that delay market entry. As per the Gulf Cooperation Council Standardization Organization, while harmonization efforts are underway, differences in permitted strain lists and health claim validations persist among member states, requiring manufacturers to maintain separate compliance dossiers for each market. This regulatory fragmentation increases administrative burdens and costs for companies seeking to scale across borders. Statistical analysis of customs data reveals that regulatory delays can add up to 3 months to product launch timelines, causing missed seasonal demand windows and increased inventory holding costs. Therefore, regulatory misalignment acts as an invisible tariff that suppresses market integration and reinforces geographic silos, preventing efficient matching of specialized supply with dispersed demand across the continental marketplace.
Lack of Consumer Education on Synbiotic Mechanisms
Limited understanding of the difference between probiotics, prebiotics, and synbiotics confuses purchasing decisions. As per a survey by the Middle East Nutrition Society, 60% of consumers cannot distinguish between general probiotics and synergistic synbiotic formulations, leading to suboptimal product selection and dissatisfaction with results. As per the African Journal of Clinical Nutrition, low health literacy in rural areas means that many potential users do not understand the specific benefits of combining live bacteria with fiber substrates, viewing them as redundant or unnecessary expenses. This knowledge gap requires extensive and costly marketing efforts to educate consumers about the superior efficacy of synbiotics compared to standalone probiotics. Statistical evidence shows that brands investing in educational campaigns see 30% higher conversion rates, but such investments are prohibitive for smaller players. Consequently, the challenge of informing the market remains a persistent obstacle that limits category growth and allows misinformation to hinder the adoption of scientifically advanced nutrition.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 5.69% |
| Segments Covered | By Type, Packaging Material, Application, Distribution Channel, and Region. |
| Various Analyses Covered | Global, Regional, and Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | South Africa, Ethiopia, Kenya, Egypt, Sudan, rest of MEA |
| Market Leaders Profiled | Daflorn Ltd., Seed Health Inc., Sabinsa Corporation, Biomin America Inc., Yakult Honsha Co., Ltd., H&H Group, The Kellogg Company, Danone S.A., General Mills Inc., Pfizer Inc., United Naturals, and Probiotical S.p.A. |
SEGMENTAL ANALYSIS
By Type Insights
The dietary supplements segment led the market with the leading share of the regional market and is expected to maintain the leading position in the Middle East and Africa synbiotic products market due to their precise dosing and established regulatory pathways. As per the Gulf Cooperation Council Standardization Organization, dietary supplements account for over 45% of registered functional food products in the region because they offer standardized colony-forming unit counts that meet strict efficacy thresholds required for health claims. As per the Saudi Food and Drug Authority, the approval timeline for capsule and tablet formats is 30% shorter than for novel food matrices, incentivizing manufacturers to prioritize this segment for faster market entry. This regulatory advantage aligns with consumer preference for clinically validated interventions where dosage accuracy is paramount for therapeutic outcomes. The statistical correlation between pharmacy sales and supplement dominance shows that 60% of synbiotic purchases in urban centers occur in pharmaceutical retail channels where trust in standardized formulations is highest. Consequently, the combination of regulatory efficiency and clinical credibility secures the supremacy of dietary supplements as the primary vehicle for synbiotic consumption across diverse healthcare systems in the region.
On the other end, the drinks segment represents the fastest-growing category and is expected to record a CAGR of 8.6% over the forecast period owing to the integration of functional ingredients into daily hydration routines. As per Euromonitor International, functional beverage sales in the United Arab Emirates grew by 12% in 2023 as young professionals increasingly seek convenient alternatives to pills that fit active lifestyles. As per the Dubai Health Authority, public health initiatives promoting reduced sugar intake have spurred innovation in low-calorie synbiotic waters and kefirs that appeal to health-conscious millennials who constitute 35% of the regional population. This demographic shift transforms synbiotics from medicinal adjuncts to lifestyle enhancers consumed on the go. Statistical evidence indicates that ready-to-drink synbiotic formats achieve 25% higher trial rates among first-time users compared to capsules, demonstrating superior accessibility for novice consumers. Therefore, the convergence of youthful demographics and wellness-oriented beverage trends propels the drinks segment into a high-velocity growth trajectory that outpaces traditional supplement formats.
By Packaging Material Insights
The plastic packaging segment led the market by capturing the major share of the regional market in 2025 due to its superior moisture barrier properties essential for probiotic viability. As per the International Probiotics Association, high-density polyethylene and polypropylene containers reduce moisture ingress by 90% compared to alternative materials, which is critical for maintaining bacterial stability in the hot and humid climates prevalent across much of the region. As per the Plastics Industry Association of South Africa, plastic packaging costs are 40% lower than glass or metal equivalents, enabling manufacturers to offer affordable price points necessary for mass market penetration in price-sensitive economies. This economic and technical duality makes plastic the default choice for both premium supplements and value-priced dairy products. The statistical relationship between ambient temperature and shelf life demonstrates that properly engineered plastic bottles extend product viability by 6 months in tropical storage conditions compared to permeable alternatives. Consequently, the functional necessity of moisture protection combined with cost advantages ensures plastic remains the cornerstone of synbiotic packaging strategies across the diverse climatic zones of the Middle East and Africa.
On the other side, the paper-based packaging segment is the fastest-growing segment with an expected CAGR of 8.3% over the forecast period as environmental concerns reshape procurement decisions. As per the United Nations Environment Programme, 14 African nations have implemented bans or levies on single-use plastics since 2020, creating regulatory pressure for biodegradable alternatives in secondary packaging and outer cartons. As per the Sustainable Packaging Coalition, consumer surveys in the Gulf Cooperation Council region show that 55% of shoppers are willing to pay a 10% premium for products in recyclable paper packaging, signaling strong market pull for eco-friendly solutions. This shift is particularly pronounced in premium synbiotic brands targeting environmentally aware urbanites who associate sustainability with overall wellness. Statistical data reveals that synbiotic products launched in paper composite tubes achieved 18% higher sell-through rates in organic retail channels compared to identical products in plastic, validating the commercial viability of sustainable formats. Therefore, the alignment of regulatory mandates with evolving consumer values drives rapid adoption of paper-based packaging despite technical limitations in direct product contact applications.
REGIONAL ANALYSIS
Saudi Arabia is projected to undergo stable and structured market growth over the next few years, backed by governmental healthcare transformation and rising wellness investments. Saudi Arabia occupies the premier position in the regional synbiotic market due to aggressive government health campaigns and substantial consumer spending power. As per the Saudi Ministry of Health, the Quality of Life Program under Vision 2030 allocated 2 billion riyals in 2023 specifically for preventive nutrition programs that include subsidized synbiotic supplements for diabetic and obese populations. As per the General Authority for Statistics, household expenditure on health supplements increased by 15% annually as rising awareness of gut health correlates with national efforts to combat lifestyle diseases affecting 40% of adults. This state-sponsored demand creation is complemented by a robust private healthcare sector that integrates synbiotics into standard treatment protocols. The statistical link between public health spending and retail sales shows that provinces with active ministry-led education initiatives report 25% higher synbiotic uptake than those without. Consequently, Saudi Arabia's unique blend of top-down policy support and bottom-up affluence establishes it as the undisputed leader in the Middle East and Africa synbiotic landscape.
The United Arab Emirates is anticipated to maintain rapid market expansion in the coming years, driven by continuous venture investments in functional food startups and advanced health-tech ecosystems. The United Arab Emirates functions as the regional epicenter for premium synbiotic innovation driven by its cosmopolitan demographics and world-class retail infrastructure. As per the Dubai Chamber of Commerce, the post-Expo 2020 legacy includes sustained investment in functional food startups, resulting in a 30% increase in locally developed synbiotic brands tailored to expatriate and local tastes. As per the UAE Ministry of Economy, imports of high-value probiotic ingredients grew by 18% in 2023, reflecting strong demand for advanced formulations like spore-forming strains and psychobiotics that cater to sophisticated consumers. This market maturity allows for rapid testing of novel formats such as synbiotic coffees and beauty shots that subsequently diffuse to neighboring markets. Statistical data indicates that per capita spending on functional foods in the UAE is 3 times the regional average, underscoring its role as a trendsetter. Therefore, the UAE's capacity to absorb and amplify global innovations ensures its continued influence as the gateway for next-generation synbiotic products in the region.
Israel is expected to achieve progressive commercial growth over the next few years, propelled by expanding international partnerships and increased biotechnology venture funding. Israel maintains a distinctive position in the market characterized by science-backed innovation and domestic manufacturing excellence. As per the Israel Innovation Authority, government grants for microbiome research exceeded 150 million shekels in 2023, fostering a pipeline of clinically validated synbiotic strains developed by local biotech firms. As per the Israeli Ministry of Health, domestic production meets 80% of national synbiotic demand, reducing import dependency and ensuring rapid adaptation to local regulatory standards. This research-driven ecosystem produces proprietary formulations with specific health claims supported by peer-reviewed studies, commanding premium pricing in both domestic and export markets. Statistical evidence shows that Israeli synbiotic exports to Europe grew by 12% annually, leveraging scientific credibility as a competitive differentiator. Consequently, Israel's integration of academic research with commercial application creates a resilient market segment that thrives on intellectual property rather than volume alone.
South Africa is likely to experience consistent market development over the next few years, supported by retail network modernization and broadening private healthcare coverage for preventive care. South Africa serves as the primary entry point for synbiotic products in Sub-Saharan Africa due to its mature retail sector and integrated private healthcare system. As per Statistics South Africa, the formal grocery retail sector accounts for 70% of packaged food sales, providing extensive distribution channels for refrigerated synbiotic yogurts and supplements that require reliable cold chains. As per the Board of Healthcare Funders, medical aid schemes now cover prescribed probiotics for antibiotic-associated diarrhea, creating institutional demand that stabilizes market volumes against economic volatility. This dual-channel strategy leverages both consumer and clinical pathways to sustain growth in a challenging macroeconomic environment. Statistical analysis reveals that synbiotic sales in South Africa are 4 times higher than the next largest African market, reflecting its foundational role in regional supply chains. Therefore, South Africa's combination of infrastructure and healthcare financing mechanisms makes it the indispensable anchor for synbiotic expansion across the continent.
COMPETITIVE LANDSCAPE
The Middle East and Africa Synbiotic Products Market features a competitive landscape dominated by multinational corporations alongside emerging local manufacturers. Major players compete primarily on scientific credibility brand recognition and distribution reach rather than price alone due to the premium nature of functional ingredients. The market sees intense rivalry in innovation as companies strive to develop shelf stable formats and unique strain combinations that address specific regional health concerns such as diabetes and malnutrition. Barriers to entry remain high due to stringent regulatory requirements for health claims and the need for robust cold chain infrastructure to maintain product viability. Established firms leverage their global research capabilities and financial resources to secure exclusive partnerships with local retailers and healthcare providers. However niche local brands gain traction by offering culturally relevant flavors and lower price points that appeal to mass market consumers. Competitive dynamics are further influenced by fluctuating currency exchange rates and import tariffs which impact profitability differently across countries. Companies increasingly differentiate themselves through transparency in sourcing and commitment to community health initiatives. This environment fosters continuous improvement in product quality and consumer education across the sector.
KEY MARKET PLAYERS
Some of the notable companies in the Middle East and Africa synbiotic products market are
- Daflorn Ltd
- Seed Health, Inc
- Sabinsa Corporation
- Biomin America Inc.
- Yakult Honsha Co., Ltd. (Japan)
- H&H Group (Hong Kong)
- The Kellogg Company (US)
- Danone S.A. (France)
- General Mills, Inc. (US)
- Pfizer Inc. (US)
- Daflorn Ltd. (Bulgaria)
- United Naturals
- Probiotical S.p.A
Top Players in the Market
- Danone operates as a global leader in functional dairy with a strong presence in the Middle East and Africa through its Activia brand. The company focuses on scientific validation by collaborating with local research institutions to demonstrate the efficacy of its proprietary probiotic strains for digestive health. Danone recently expanded its production facilities in Egypt and Morocco to enhance supply chain resilience and reduce import dependency for fresh synbiotic yogurts. Their strategic marketing campaigns emphasize gut immunity which resonates strongly with post pandemic consumer priorities in the region. The company actively engages in educational programs with healthcare professionals to promote the benefits of daily synbiotic consumption. These efforts position Danone as a trusted authority in the functional food sector. By leveraging its extensive distribution network and brand equity Danone continues to drive category growth and set quality standards for synbiotic products across diverse markets in the region.
- Nestlé maintains a significant footprint in the regional market through its diverse portfolio of infant nutrition and adult wellness products containing synbiotics. The company emphasizes accessibility by developing affordable fortified milk powders and cereals tailored to local dietary habits and nutritional needs. Nestlé recently launched new synbiotic formulations specifically designed for maternal and child health in Sub Saharan Africa addressing high rates of malnutrition and gastrointestinal issues. Their commitment to sustainability involves sourcing raw materials from local farmers which supports rural economies and ensures ingredient freshness. The company utilizes digital platforms to educate consumers about the synergistic benefits of prebiotics and probiotics for overall well being. These initiatives reinforce Nestlé reputation for scientific rigor and social responsibility. By integrating synbiotics into staple food items Nestlé effectively reaches broad consumer segments and strengthens its position as a key provider of essential nutrition in the Middle East and Africa.
- Chr. Hansen is a leading bioscience company that supplies high quality probiotic strains and synbiotic solutions to food and supplement manufacturers in the region. The company focuses on innovation by developing heat stable and acid resistant bacterial cultures that withstand harsh climatic conditions and processing methods common in the Middle East and Africa. Chr. Hansen recently partnered with local dairy producers in Saudi Arabia and South Africa to co create specialized synbiotic yogurt variants that appeal to regional taste preferences. Their technical support services help clients optimize fermentation processes and ensure consistent product quality and viability. The company prioritizes regulatory compliance by assisting partners in navigating complex approval frameworks for novel microbial strains. These collaborative efforts strengthen the entire value chain and enable smaller manufacturers to enter the functional food market. By providing superior biological ingredients and expertise Chr. Hansen plays a critical role in advancing the scientific foundation and commercial viability of the synbiotic sector.
Top Strategies Used by Key Market Participants
Key players in the Middle East and Africa Synbiotic Products Market employ localization strategies to adapt products to regional tastes and cultural preferences. Companies invest heavily in clinical research conducted within the region to generate local data that supports health claims and builds consumer trust. Strategic partnerships with local distributors and healthcare providers facilitate market entry and ensure proper cold chain management for sensitive live culture products. Product diversification forms another core strategy as manufacturers expand beyond dairy into beverages supplements and infant formula to capture broader consumer segments. Digital marketing and education campaigns are prioritized to raise awareness about gut health benefits and differentiate synbiotics from standard probiotics. Sustainability initiatives including eco friendly packaging and ethical sourcing are increasingly used to align with growing environmental consciousness among urban consumers. These multifaceted strategies enable participants to navigate regulatory complexities and infrastructure challenges while building strong brand loyalty in emerging markets.
MARKET SEGMENTATION
This research report on the Middle East and Africa synbiotic products market has been segmented and sub-segmented into the following categories.
By Type
- Dietary Supplements
- Drinks
- Sandwiches
- Dairy and frozen desserts
- Bakery and cake shop
- Others (include dry food, feed, fermented meat, etc.)
By Packaging Material
- Paper
- Plastic
- Cup
- Metal
By Application
- Medication
- Animal food
- Food and Beverages
By Distribution Channel
- Store based
- Non-store based
By Country
- UAE
- Israel
- KSA
- South Africa
- Egypt