- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$18.62 BnMarket Estimate, 2026
$19.68 BnMarket Forecast, 2034
$30.66 BnCAGR, 2026–2034
5.70%Executive Summary: Global Next Generation Batteries Market
- Market Scope: Comprehensive global analysis tracking advanced battery technologies across diverse types (Li-Ion, Solid Electrodes, Metal-Air, Lithium Sulphur, etc.) and applications spanning automotive, transportation, aerospace & defense, industrial, and energy storage.
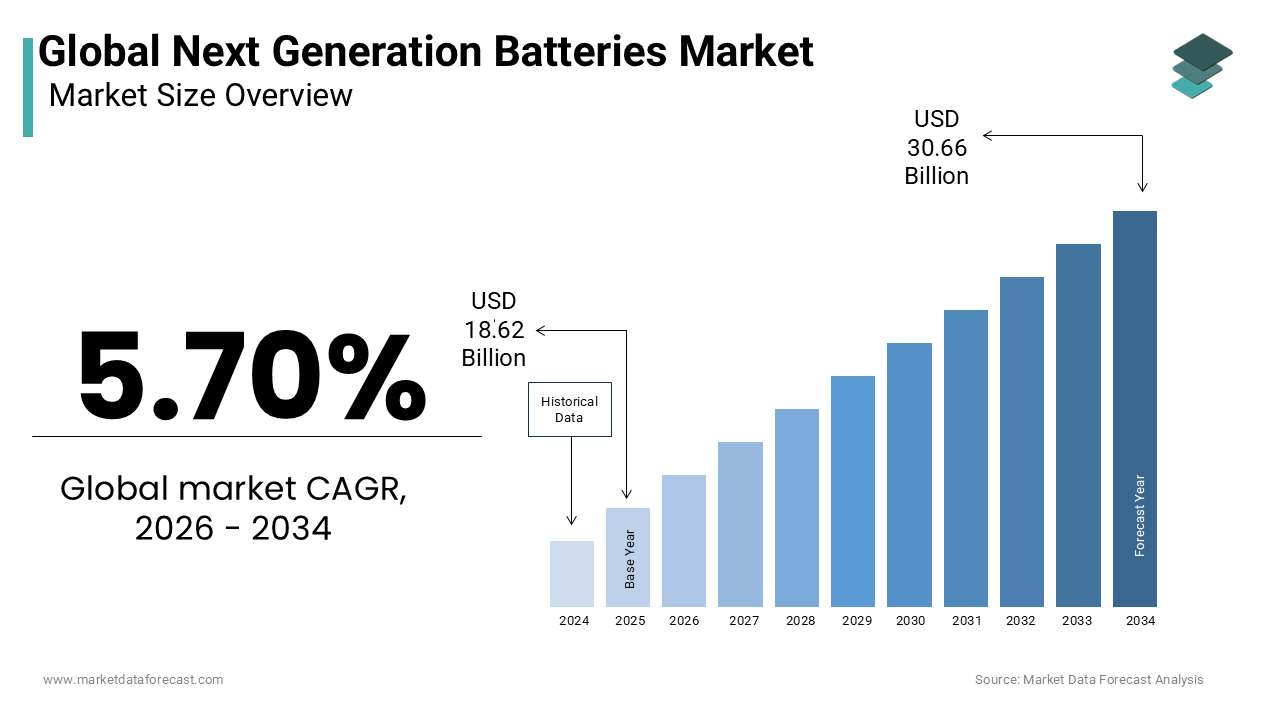
- Market Valuation: Valued at USD 18.62 billion in 2025, reaching USD 19.68 billion in 2026, and projected to expand to USD 30.66 billion by 2034, growing at a steady CAGR of 5.70% during the forecast period (2026–2034).
- Primary Growth Drivers: Escalating adoption of electric mobility and electric vehicles, growing clean energy/renewable energy infrastructure (wind and solar integration), and surging consumption of consumer electronic devices. Key restraints include technological limitations, high initial R&D/testing costs, and energy density/safety challenges.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment / Focus Area | Key Insights & Trends |
|---|---|---|
| By Type | Li-Ion & Advanced Chemistries (Solid Electrodes, Metal-Air, Lithium Sulphur) | Lithium-based and next-generation variants are evolving to store more charge in smaller physical sizes, offering higher efficiency, longer life, and improved power delivery. |
| By Application | Automotive & Transportation | Driven by the transition to electric vehicles (EVs), grid-tied battery storage systems for renewables, and portable consumer electronics. |
| By Region | North America & Asia-Pacific | North America leads via aggressive government emission mandates and EV support. Asia-Pacific (China, Japan, South Korea, India) experiences rapid capacity expansion driven by subsidies and growing domestic manufacturing. |
Major Market Players & Market Structure
Market Structure: Highly competitive and fragmented ecosystem comprising specialized technology developers, global electronics giants, and automotive cell manufacturers competing on energy density, cost reduction, and safety enhancement.
Key Companies: Panasonic Corporation, Sion Power, Envia Systems Inc., Ambri Inc., Hitachi, Fluidic Energy, LG Chemicals, Phinergy, Samsung, Saft Group, Amprius Inc., Mitsubishi Chemical, Seeo, Lockheed Martin, Uniross Batteries, PolyPlus Transfection, and OXIS Energy.
 Download Free Sample Report
Global Next Generation Batteries Market Size
The global next generation batteries market was estimated at USD 18.62 billion in 2025, and it is expected to reach a revised size of USD 30.66 billion by 2034 from USD 19.68 billion in 2026 with a CAGR of 5.70% over the foreseen period of 2026 to 2034.
Next-generation batteries are advanced energy storage technologies including solid state, lithium sulfur, sodium ion, and metal air systems that surpass conventional lithium ion limitations in energy density, safety, and sustainability. As per the International Energy Agency, global electric vehicle sales reached 14 million units in 2023, creating unprecedented demand for batteries with higher specific energy and faster charging capabilities than current chemistries can reliably provide. According to the United States Department of Energy, next generation battery targets require achieving 500 Wh/kg at the cell level by 2030 to enable long range aviation and heavy transport electrification, benchmarks that existing liquid electrolyte systems cannot meet without compromising thermal stability. This market is defined by its transition from laboratory scale innovation to pilot manufacturing, driven by urgent decarbonization mandates and critical mineral supply concerns. The sector operates at the intersection of materials science breakthroughs and industrial scaling challenges, where performance gains must be balanced against manufacturability and cost competitiveness to achieve commercial viability across automotive, aerospace, and grid storage applications.
MARKET DRIVERS
Electric Vehicle Range Anxiety and Performance Demands Accelerating Adoption
Consumer expectations for extended driving range and rapid charging directly propel investment in next generation battery architectures, which is majorly driving the global next-generation batteries market expansion. According to the International Council on Clean Transportation, 68% of prospective electric vehicle buyers cite insufficient range as their primary purchase barrier, necessitating energy densities above 400 Wh/kg that only solid state or lithium sulfur chemistries can practically deliver. As per the European Automobile Manufacturers Association, average new electric vehicle battery capacity increased by 15% between 2022 and 2023, reflecting manufacturer responses to consumer demands that push current lithium ion technology toward its theoretical limits. This performance gap creates a clear market pull for next generation solutions that promise 50% greater range without increasing pack weight or volume. For instance, the correlation between range capability and purchase intent demonstrates that vehicles exceeding 500 km real world range achieve 3 times higher conversion rates than shorter range alternatives. Consequently, the fundamental mismatch between consumer expectations and current battery capabilities acts as a powerful catalyst accelerating research funding and strategic partnerships aimed at commercializing advanced chemistries within this decade.
Critical Mineral Supply Vulnerabilities Driving Alternative Chemistry Development
Geopolitical risks and resource constraints associated with cobalt and nickel incentivize development of next generation batteries using abundant materials, which is further propelling the global market expansion. According to the International Energy Agency, cobalt prices fluctuated by over 300% between 2021 and 2023 due to supply concentration in the Democratic Republic of Congo, exposing manufacturers to severe cost volatility and ethical sourcing challenges. As per the United States Geological Survey, identified global lithium reserves may face deficit scenarios by 2035 under high electrification pathways, prompting urgent exploration of sodium ion and iron based alternatives that eliminate dependency on constrained minerals. This supply insecurity transforms next generation batteries from performance upgrades into strategic imperatives for supply chain resilience. For instance, automakers announcing cobalt free or reduced cobalt battery roadmaps received 25% higher investor valuations compared to peers maintaining conventional chemistries. Therefore, the imperative to de risk material supply chains functions as a structural driver that redirects capital toward next generation technologies regardless of near term performance tradeoffs.
MARKET RESTRAINTS
Manufacturing Scalability Barriers Limiting Commercial Deployment
The inability to translate laboratory success into high volume production severely constrains next-generation batteries market expansion. According to the Massachusetts Institute of Technology Technology Review, fewer than 5% of next generation battery startups have successfully transitioned from pilot line to gigawatt hour scale manufacturing due to unresolved yield and consistency issues in novel electrode fabrication processes. As per the Faraday Institution, solid state battery production currently achieves yields below 40% compared to 95% for mature lithium ion lines, making unit economics uncompetitive despite superior performance characteristics. This manufacturing gap creates a valley of death where promising technologies fail to reach commercial viability before funding expires. For instance, capital expenditure per kilowatt hour for next generation battery plants remains 3 to 5 times higher than equivalent lithium ion facilities, deterring private investment without substantial government subsidies. Consequently, the engineering complexity of scaling novel chemistries acts as a formidable restraint that delays widespread adoption and maintains incumbent technology dominance despite acknowledged performance advantages.
Safety Validation Timelines Extending Time to Market
Rigorous testing requirements for novel battery systems hinder the next-generation batteries market growth. According to Underwriters Laboratories, next generation batteries require 18 to 24 months of additional safety validation beyond standard lithium ion protocols due to unknown failure modes in solid electrolytes and metal anodes. As per the National Renewable Energy Laboratory, thermal runaway characterization for solid state cells demands specialized equipment and methodologies not yet standardized across the industry, adding 6 to 12 months to development timelines. This regulatory uncertainty forces manufacturers to maintain parallel development tracks with proven chemistries as fallback options, diluting focus and resources. For instance, automotive original equipment manufacturers require minimum 3 years of field validation data before integrating new battery types into production vehicles, effectively pushing commercial launch dates beyond initial projections. Therefore, the absence of established safety standards and validation infrastructure functions as a critical restraint that extends time to market and increases financial risk for technology developers.
MARKET OPPORTUNITIES
Grid Scale Storage Demand Creating New Application Vectors
The exponential growth of renewable energy integration opens massive markets for next generation batteries optimized for stationary storage. According to the International Renewable Energy Agency, global battery storage deployment must increase 8 fold by 2030 to support net zero pathways, requiring technologies with longer cycle life and lower levelized cost than current lithium ion systems. As per BloombergNEF, sodium ion batteries achieved cost parity with lithium iron phosphate at 50 dollars per kilowatt hour in 2023 for stationary applications, unlocking previously uneconomic use cases in emerging markets and frequency regulation services. This application diversification reduces dependence on automotive demand cycles and provides alternative revenue streams during technology maturation. For instance, grid storage projects utilizing next generation chemistries secured 40% more financing in 2023 compared to previous years as investors recognize differentiated value propositions. Thus, the stationary storage sector transforms next generation batteries from automotive centric innovations into multi vertical platforms with broader addressable markets and reduced commercialization risk.
Aerospace Electrification Enabling Premium Performance Niches
Aviation and space applications create willingness to pay premiums for weight critical next generation batteries, which is another prominent opportunity for the global market. According to the European Union Aviation Safety Agency, certified electric aircraft require energy densities exceeding 400 Wh/kg at system level, achievable only through lithium sulfur or solid state architectures that current technologies cannot provide. As per NASA, urban air mobility vehicles need batteries delivering 10C discharge rates with 5000 cycle life, specifications that drive targeted R&D investments from both public and private sectors. This niche positioning allows next generation battery developers to command margins 5 to 10 times higher than automotive applications while building flight heritage that validates technology for downstream mass markets. For instance, aerospace battery contracts awarded in 2023 totaled 2.3 billion dollars, representing 15% of total next generation battery funding despite constituting less than 1% of projected volume. Consequently, aerospace electrification serves as a high value beachhead opportunity that funds technology development and establishes credibility for eventual terrestrial applications.
MARKET CHALLENGES
Interface Stability Issues Compromising Cycle Life
Degradation mechanisms at electrode electrolyte interfaces fundamentally limit practical longevity of next generation batteries. According to Nature Energy, solid state batteries experience interfacial resistance growth that reduces capacity retention to below 80% within 300 cycles, far shortening the 1000 cycle minimum required for automotive applications. As per the Journal of Power Sources, lithium metal anodes exhibit dendrite formation that causes internal short circuits after 200 to 400 cycles in prototype cells, undermining safety claims that motivate technology adoption. These fundamental scientific challenges persist despite billions in research investment because interface phenomena remain poorly understood at atomic scales. For instance, only 12% of published next generation battery studies report cycle life exceeding 500 cycles under realistic testing conditions, indicating widespread performance inflation in academic literature. Therefore, unresolved interface instability acts as a persistent technical challenge that erodes confidence among industrial partners and delays commercial commitments until fundamental degradation mechanisms are solved.
Intellectual Property Fragmentation Hindering Standardization
Dispersed patent landscapes create licensing complexities that slow ecosystem development. According to the World Intellectual Property Organization, next generation battery patents are distributed across 2000 assignees with no single entity holding more than 3% share, creating dense thickets that increase transaction costs for technology integration. As per the European Patent Office, overlapping claims in solid electrolyte compositions have generated 45 active litigation cases since 2020, diverting resources from R&D to legal defense and creating uncertainty for potential licensees. This fragmentation prevents emergence of common standards that would enable supply chain interoperability and reduce duplication of effort. For instance, companies spend 15% to 20% of R&D budgets on freedom to operate analyses rather than innovation, significantly reducing effective research productivity. Consequently, intellectual property dispersion functions as a systemic challenge that inhibits collaborative progress and favors vertically integrated players who can navigate complex licensing environments, potentially limiting competition and slowing overall market development.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Type, Application, and Region. |
| Various Analyses Covered | Global, Regional, and Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Panasonic Corporation (Japan), Sion Power (U.S.), Envia Systems Inc. (U.S.), Ambri Inc. (U.S), Hitachi (Japan), Fluidic Energy (U.S.), LG Chemicals (South Korea), Phinergy (Israel), Samsung (South Korea), Saft Group (France), Amprius Inc. (U.S.), Mitsubishi Chemical (Japan), Seeo (U.S.), Lockheed Martin (U.S.), Uniross Batteries (South Africa), PolyPlus Transfection (France), and OXIS Energy (U.K) and Others. |
SEGMENTAL ANALYSIS
By Type Insights
The lithium-ion batteries segment dominated the market by holding 90.5% of the global market share in 2025 and is expected to maintain the leading market share over the forecast period due to their mature supply chain and proven performance in high volume applications. According to the International Energy Agency, lithium ion batteries accounted for over 95% of global electric vehicle battery deployments in 2023, benefiting from economies of scale that have reduced pack costs to below 100 dollars per kilowatt hour. As per the United States Department of Energy, existing gigafactory infrastructure supports annual production capacities exceeding 1 terawatt hour, creating significant barriers to entry for alternative chemistries that lack comparable manufacturing readiness. This industrial momentum ensures continuous incremental improvements in energy density and cycle life through advanced cathode formulations like nickel manganese cobalt. For instance, every doubling of cumulative lithium ion production has historically lowered prices by 20%, a trend that continues to favor incumbent technology. Consequently, the entrenched manufacturing base and relentless cost optimization secure the dominance of lithium ion batteries as the default choice for current electrification needs despite the emergence of next generation alternatives.
On the other side, the solid state batteries segment is estimated to showcase a promising CAGR in the global market during the forecast period owing to their potential to eliminate flammable liquid electrolytes and double energy density. According to Nature Energy, solid state prototypes have demonstrated energy densities exceeding 500 Wh/kg in laboratory settings, addressing the primary range limitation of current electric vehicles while significantly reducing fire risk. As per the Toyota Motor Corporation, the company plans to commence commercial production of solid state batteries by 2027, signaling industry confidence in overcoming interface stability challenges that previously hindered scalability. This technological breakthrough attracts substantial venture capital and corporate investment, with funding for solid state startups increasing by 60% in 2023 alone. For instance, automotive original equipment manufacturers have signed over 30 strategic partnerships with solid state developers since 2020, reflecting urgent demand for safer and longer ranging power sources. Therefore, the convergence of safety imperatives and performance breakthroughs propels solid state batteries into a high velocity growth trajectory that promises to redefine energy storage standards within the decade.
By Application Insights
The automotive segment led the market with the leading share of the global market in 2025 as global regulations phase out internal combustion engines and consumers embrace electric mobility. According to the International Council on Clean Transportation, over 30 countries have announced bans on new gasoline and diesel vehicle sales by 2035, forcing automakers to secure massive supplies of advanced batteries to meet production targets. As per the European Automobile Manufacturers Association, electric vehicle registrations in Europe reached 2.1 million units in 2023, representing 25% of total car sales and driving unprecedented demand for high capacity battery packs. This regulatory and market shift transforms batteries from component parts into strategic assets that determine vehicle competitiveness and brand viability. For instance, automakers have committed over 500 billion dollars to battery supply chains since 2020 to ensure compliance. Consequently, the existential threat of regulatory non-compliance combined with strong consumer demand solidifies the automotive sector as the primary driver of next generation battery development and deployment.
However, the aerospace and defense segment is the fastest growing application and is predicted to register the fastest CAGR in the global market during the forecast period as urban air mobility concepts move toward certification and military operations require portable high energy power. According to the Federal Aviation Administration, over 100 electric vertical takeoff and landing aircraft designs are currently under review, each requiring lightweight batteries with energy densities above 400 Wh/kg that only next generation chemistries can provide. As per the United States Department of Defense, military initiatives prioritize solid state and metal air batteries for silent surveillance and extended drone missions, allocating 2 billion dollars annually for advanced energy storage research. This dual use demand creates a premium market willing to pay for performance regardless of cost, enabling early commercialization of technologies not yet viable for mass automotive use. For instance, aerospace battery contracts grew by 45% in 2023, outpacing all other sectors due to urgent operational requirements. Thus, the unique performance demands of flight and tactical operations drive rapid adoption of next generation batteries in aerospace and defense applications.
REGIONAL ANALYSIS
North America Next Generation Batteries Market Analysis
North America had the major share of the global next-generation batteries market in 2025 and is likely to register strong industrial expansion and maintain its strategic leadership over the next few years, backed by aggressive federal funding and private investments under domestic supply chain initiatives. According to the United States Department of Energy, federal incentives have attracted over 100 billion dollars in private investment for battery manufacturing and material processing since 2022, aiming to reduce dependence on Asian supply chains. As per the Canadian Natural Resources Department, Canada possesses some of the world largest lithium reserves and has positioned itself as a key supplier of critical minerals for North American battery production. This policy driven reshoring effort supports numerous startups developing solid state and sodium ion technologies in hubs like Michigan and California. For instance, North American battery patent filings increased by 30% in 2023, reflecting intense innovation activity supported by government grants. Consequently, the region combination of financial incentives and resource abundance establishes it as a major center for next generation battery development and manufacturing.
Europe Next Generation Batteries Market Analysis
Europe is poised to experience steady market growth over the coming years, driven by rigorous sustainability policies and collaborative multi-country industrial frameworks. According to the European Commission, the New Battery Regulation mandates carbon footprint declarations and recycling efficiency targets that favor next generation batteries with lower environmental impacts and higher recyclability. As per the European Battery Alliance, member states have coordinated investments exceeding 40 billion euros to build a competitive local battery ecosystem, including several pilot lines for solid state production. This regulatory framework pushes automakers and suppliers to adopt advanced chemistries that meet sustainability criteria while maintaining performance. For instance, Europe accounts for 25% of global next generation battery research publications, highlighting its scientific leadership. Therefore, Europe commitment to green transition and industrial sovereignty drives steady adoption of innovative battery technologies across its automotive and industrial sectors.
Asia Pacific Next Generation Batteries Market Analysis
The Asia Pacific region is anticipated to sustain its undisputed manufacturing dominance and expand its production scale over the next few years, anchored by advanced refining facilities and integrated supply chains. According to the China Ministry of Industry and Information Technology, China produces over 70% of the world lithium ion batteries and controls significant shares of refining for cobalt, nickel, and graphite, providing unmatched supply chain leverage. As per the Japan Organization for Metals and Energy Security, Japanese companies lead in solid state battery patents and have formed consortiums to accelerate commercialization by 2030. This manufacturing hegemony allows Asian firms to iterate rapidly and reduce costs faster than competitors in other regions. For instance, Asia Pacific received 60% of global battery related foreign direct investment in 2023, reinforcing its central role. Consequently, the region integrated supply chain and technical expertise ensure its continued leadership in both current and next generation battery markets.
Latin America Next Generation Batteries Market Analysis
Latin America is projected to experience steady economic integration into global supply chains over the next few years, fueled by rising international demand for critical transition minerals. According to the United States Geological Survey, the Lithium Triangle comprising Argentina, Bolivia, and Chile holds over 50% of global lithium reserves, attracting significant exploration and extraction investments from international battery makers. As per the Brazilian Ministry of Mines and Energy, Brazil is expanding its nickel and graphite production capabilities to support global supply chains diversifying away from single source dependencies. This resource wealth positions the region as a strategic partner for North American and European battery initiatives seeking secure material inputs. For instance, mining investments in Latin American battery metals grew by 25% in 2023. Therefore, while local manufacturing remains limited, Latin America resource endowment makes it an indispensable component of the global next generation battery value chain.
Middle East and Africa Next Generation Batteries Market Analysis
The Middle East and Africa region is expected to register gradual market development over the coming years, supported by targeted sovereign wealth fund investments and regional resource wealth. According to the Saudi Arabian Ministry of Investment, the Kingdom has allocated billions toward establishing a local electric vehicle and battery ecosystem as part of its economic diversification strategy, including partnerships with international battery manufacturers. As per the African Union, countries like Democratic Republic of Congo and Zimbabwe hold vast cobalt and lithium reserves respectively, though efforts are underway to increase local value addition beyond raw export. These strategic moves aim to capture more value from the energy transition. For instance, renewable energy storage projects in the region grew by 15% annually, creating initial demand for advanced batteries. Consequently, the region combination of financial capital and natural resources positions it for gradual but significant integration into the global next generation battery market.
COMPETITIVE LANDSCAPE
The Next Generation Batteries Market features a highly dynamic competitive landscape characterized by intense rivalry between established chemical giants and agile startups. Major players compete primarily on technological breakthroughs intellectual property strength and strategic alliances with automotive manufacturers rather than current sales volume. The market sees fierce competition in securing talent and research funding as companies race to solve fundamental scientific challenges related to interface stability and cycle life. Barriers to entry remain extremely high due to the need for specialized materials science expertise and substantial capital for pilot manufacturing facilities. Established lithium ion producers leverage their existing supply chains and customer relationships to develop incremental improvements while startups focus on disruptive technologies like solid state and metal air batteries. Competitive dynamics are further influenced by government policies and subsidies that favor domestic production and specific chemistries. Companies increasingly differentiate themselves through licensing models and joint ventures to share development risks. This environment fosters rapid innovation but also leads to consolidation as weaker players struggle to reach commercial viability.
KEY MARKET PLAYERS
The Top players in Next Generation Batteries Market include
- Panasonic Corporation (Japan)
- Sion Power (U.S.)
- Envia Systems Inc. (U.S.)
- Ambri Inc. (U.S)
- Hitachi (Japan)
- Fluidic Energy (U.S.)
- LG Chemicals (South Korea)
- Phinergy (Israel)
- Samsung (South Korea)
- Saft Group (France)
- Amprius Inc. (U.S.)
- Mitsubishi Chemical (Japan)
- Seeo (U.S.)
- Lockheed Martin (U.S.)
- Uniross Batteries (South Africa)
- PolyPlus Transfection (France)
- OXIS Energy (U.K)
Top Players in the Next Generation Batteries Market
QuantumScape
QuantumScape operates as a pioneer in solid state battery technology focusing on lithium metal anodes and ceramic separators. The company collaborates closely with Volkswagen Group to validate its technology for electric vehicle applications aiming for commercial production by 2025. QuantumScape recently completed construction of its first commercial scale production line in California marking a critical milestone in transitioning from laboratory prototypes to manufacturable products. Their proprietary separator technology enables high energy density and fast charging while mitigating dendrite formation issues common in lithium metal systems. The company holds numerous patents covering core solid state innovations creating a strong intellectual property moat. These efforts position QuantumScape as a leader in the race to commercialize safe and high performance solid state batteries. By leveraging strategic automotive partnerships and scaling manufacturing capabilities QuantumScape strengthens its market position in the next generation battery landscape significantly.
Solid Power
Solid Power specializes in sulfide based solid electrolytes designed for compatibility with existing lithium ion manufacturing processes. The company has secured partnerships with Ford and BMW to develop and test its solid state battery cells for future electric vehicle platforms. Solid Power recently announced plans to license its technology to major battery manufacturers enabling broader adoption without requiring complete retooling of global production facilities. This licensing model accelerates market penetration by leveraging established industrial capacity rather than building standalone factories. The company focuses on achieving high ionic conductivity and stability at room temperature which are key technical hurdles for solid state commercialization. These strategic actions strengthen Solid Power position as a key enabler of solid state technology adoption. By prioritizing manufacturability and industry collaboration Solid Power effectively addresses scalability challenges inherent in next generation battery development.
Sion Power
Sion Power develops lithium metal battery technologies that offer significant improvements in energy density and weight reduction for aerospace and automotive applications. The company supplies batteries to Airbus for urban air mobility prototypes demonstrating the viability of its technology in demanding flight conditions. Sion Power recently partnered with Foxconn to establish large scale manufacturing capabilities in Taiwan aiming to produce millions of cells annually for electric vehicles and drones. Their patented anode protection layer prevents dendrite growth and extends cycle life addressing critical safety and longevity concerns. The company focuses on drop in solutions that can integrate with current battery pack designs facilitating easier adoption by manufacturers. These initiatives reinforce Sion Power reputation for practical innovation and commercial readiness. By targeting high value niche markets before mass automotive adoption Sion Power builds revenue streams and technical validation that support long term growth.
Top Strategies Used by Key Market Participants
Key players in the Next Generation Batteries Market employ strategic partnerships with automotive original equipment manufacturers to secure funding and validate technology for real world applications. Companies invest heavily in pilot production lines to demonstrate scalability and reduce manufacturing risks associated with novel chemistries like solid state and lithium sulfur. Intellectual property protection forms another core strategy as firms file extensive patent portfolios to create barriers to entry and attract venture capital. Diversification into multiple application sectors such as aerospace and grid storage allows participants to generate early revenue while automotive technologies mature. Collaboration with national laboratories and universities accelerates fundamental research and access to government grants. Sustainability initiatives including recycling programs and ethical sourcing are increasingly used to meet regulatory requirements and appeal to environmentally conscious investors. These multifaceted strategies enable companies to navigate the high capital intensity and technical uncertainty characteristic of the emerging next generation battery sector
RECENT MARKET DEVELOPMENTS
- Vionx Energy has announced an ecosystem of companies to launch and commercialize storage technology ready to transform the way modern networks are managed and optimized.
- Delhi-based battery maker Inverted Energy launched a new line of lithium-ion batteries for electric vehicles and home energy storage, among others, on Tuesday, saying its latest solution offers 20 percent energy efficiency.
MARKET SEGMENTATION
This research report on the Next Generation Batteries Market has been segmented & sub-segmented into the following categories
By Type
- Li-Ion
- Ni-Cd
- Ni-Metal Hydride
- Lithium Sulphur
- Magnesium Ion
- Solid Electrodes
- Metal-Air
- Ultra-Capacitors
By Application
- Automotive
- Transportation
- Aerospace & Defense
- Industrial
- Oil and Gas
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa