- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$2.66 BnMarket Estimate, 2026
$2.99 BnMarket Forecast, 2034
$7.52 BnCAGR, 2026–2034
12.24%Global Non-PVC IV Bags Market Size
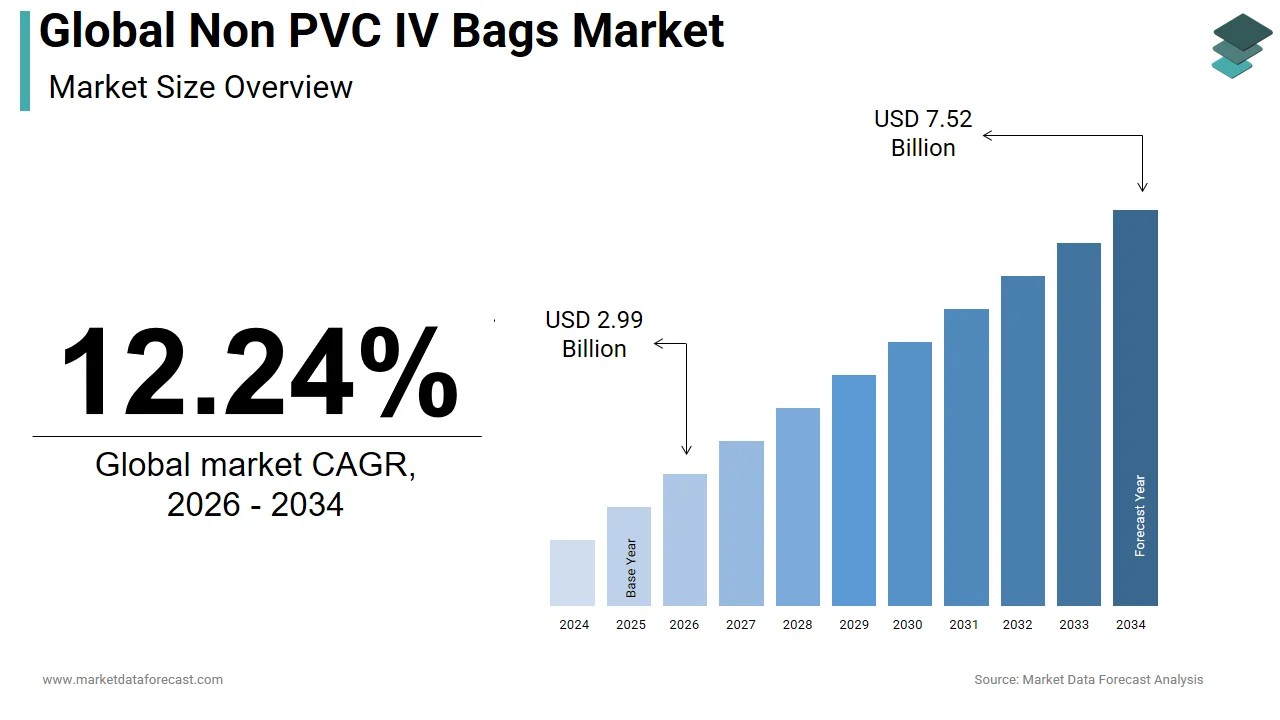
The global Non-PVC IV bags market was valued at USD 2.66 billion in 2025, is estimated to reach USD 2.99 billion in 2026, and is projected to reach USD 7.52 billion by 2034, growing at a CAGR of 12.24% from 2026 to 2034.
Non-PVC IV bags refer to the intravenous fluid delivery systems, designed to eliminate polyvinyl chloride and its associated plasticizers, such as (2-ethylhexyl) phthalate. These materials have been implicated in endocrine disruption and developmental toxicity, particularly in neonatal and immunocompromised populations. As per various studies on global healthcare practices, hundreds of millions of intravenous therapy events occur annually worldwide, forming a vast clinical canvas for safer alternatives and a key area of focus for global health initiatives. Regulatory bodies such as the European Medicines Agency (EMA) and the U.S. Food and Drug Administration (FDA) have issued guidance encouraging the minimization of plasticizer exposure, particularly for vulnerable patients, which promotes the use of non-PVC materials in specific care settings. In addition, the Adoption of non-PVC intravenous solution containers is a significant trend in global healthcare, with some developed nations and major hospital networks showing high rates of conversion to reduce leachable chemical risks, according to research. The United States Pharmacopeia (USP) general chapters, including the informational chapter <1661>, provide comprehensive guidance on extractables and leachables testing, which standardizes the rigorous chemical profiling of materials and indirectly reinforces the preference for chemically inert alternatives. This market is not an ancillary packaging trend but a deliberate, evidence-based shift aligned with toxicological research and patient safety imperatives.
MARKET DRIVERS
Material Safety Imperatives Are Accelerating Adoption of Non-PVC IV Bags Across Global Healthcare Systems
Regulatory and clinical consensus on the risks of PVC-derived plasticizers has grown, which is driving the expansion of the non-PVC IV bags market. This has transformed non-PVC IV bags from optional upgrades into essential safety tools. The European Medicines Agency has issued specific cautions against prolonged exposure to (2-ethylhexyl) phthalate in neonatal intensive care, where metabolic pathways are underdeveloped and detoxification capacity is limited. According to sources, approximately four hundred thousand infants are admitted annually to neonatal intensive care units in the United States alone, creating a concentrated clinical demand for non-leaching containers. Studies published in journals such as Environmental Health Perspectives and Pediatrics have consistently found that a significant majority of preterm and critically ill infants in NICUs receiving infusions or undergoing procedures with PVC-based devices exhibit plasma or urinary concentrations of di(2-ethylhexyl) phthalate (DEHP) and its metabolites that are several times higher than safe limits established for the general population. Moreover, the market trend in Germany reflects a significant shift towards DEHP-free and PVC-free medical devices, driven by general health concerns and evolving European Union regulations. These are not theoretical risks but clinically documented phenomena driving procurement through regulatory enforcement and institutional safety protocols.
Environmental Stewardship Mandates Are Reshaping Procurement Policies in Favor of Non-PVC IV Bags
The environmental burden of PVC medical waste has catalyzed institutional and legislative shifts toward non-PVC alternatives, and this further propels the growth of the non-PVC IV bags market. Incineration of PVC releases dioxins and furans, classified by the Stockholm Convention as persistent organic pollutants with documented bioaccumulative and carcinogenic properties. According to sources backed by the World Health Organization, healthcare facilities contribute approximately five percent of global greenhouse gas (GHG) emissions. The National Health Service (NHS) in England has a legally binding net-zero carbon commitment and is working to reduce emissions across its supply chain, including exploring non-PVC materials for medical devices. The Karolinska University Hospital in Sweden has successfully implemented initiatives to substitute PVC products, for example, transitioning to safer alternatives for nearly half of its gloves by 2007 as part of broader efforts to reduce hazardous materials in healthcare. The signing of California's Assembly Bill 2300 (AB 2300) in September 2024 signals a decisive shift in the medical device market, despite the phase-out period. The law prohibits the manufacture, sale, or distribution of intentionally added DEHP in intravenous (IV) solution containers and IV tubing, with staggered effective dates of January 1, 2030, for IV containers and January 1, 2035, for IV tubing. These mandates are not voluntary sustainability initiatives but codified legal obligations that directly influence supply chain architecture and vendor selection criteria across public health systems.
MARKET RESTRAINTS
High Production Complexity Imposes Significant Cost Barriers to Widespread Non-PVC IV Bag Adoption
The engineering required to replicate PVC’s mechanical properties without plasticizers introduces substantial cost premiums, which is a major restraint to the non-PVC IV bags market. This constrains adoption, particularly in price-sensitive markets. The multilayer coextrusion of ethylene vinyl acetate and polyolefin films to achieve flexibility, clarity, and drop resistance increases manufacturing costs, according to sources. Also, as per research, acute care hospitals in the United States operate with low median operating margins, rendering even marginal cost differentials decisive in procurement decisions. The adoption of non-PVC medical products is often hindered by a significant price premium over conventional PVC items. In India, High out-of-pocket healthcare costs in India present a barrier to the widespread adoption of premium medical products like non-PVC bags. Non-PVC alternatives remain largely restricted to high-end private healthcare facilities serving a limited segment of the patient population due to cost sensitivity. Even German hospitals, particularly mid-sized facilities, are often financially constrained and struggle to absorb the higher incremental costs of non-PVC products without corresponding adjustments to their reimbursement codes, leading to a slower transition to non-PVC alternatives in the market. These economic constraints are structural, not temporary, and remain a primary barrier despite clinical and environmental advantages.
Regulatory Fragmentation Across Geographies Impedes Standardized Global Supply Chains for Non-PVC IV Bags
Divergent regulatory expectations across jurisdictions create compliance complexity that inflates operational costs and delays market access, and these factors thereby degrade the growth of the non-PVC IV bags market. Under EudraLex Volume 4, Annex 1, the EU requires extensive extractables profiling, but the FDA's approach allows for equivalency based on less comprehensive biocompatibility data, creating a need for manufacturers to maintain separate validation processes. Companies face significant challenges with diverse national regulations for medical products across global markets, which demand varied documentation, testing, and compliance thresholds. Differences in data acceptance policies among regulatory agencies, such as stability testing requirements, often create substantial delays in bringing new products to market. The management of multiple, non-harmonized regulatory submission pathways substantially increases operational expenditure for companies seeking to market products internationally. In many emerging economies, the absence of specific, localized standards forces reliance on foreign certifications, which contributes to market access delays due to complex compliance requirements. This fragmentation undermines economies of scale and complicates global inventory planning.
MARKET OPPORTUNITIES
Emerging Economies Present Untapped Potential for Non-PVC IV Bag Penetration Driven by Expanding Critical Care Infrastructure
Rapid hospital infrastructure growth in low- and middle-income countries provides new opportunities for the expansion of the non-PVC IV bags market. This is creating a structural opening for non-PVC adoption aligned with global safety standards. According to various studies, projections indicate significant expansion in hospital bed capacity across several developing nations, notably driven by growth in India and Nigeria. India’s Ministry of Health allocated significant funds under the Pradhan Mantri Ayushman Bharat Health Infrastructure Mission for intensive care unit modernization, including procurement of safer medical consumables. Assessments in sub-Saharan Africa indicate that the use of non-PVC infusion systems in tertiary hospitals remains limited. The transition of public health systems toward a quality-focused model, rather than volume, makes infrastructure growth a sound expansion strategy, which offers both clinical justification and financial viability.
Technological Convergence with Smart Infusion Systems Unlocks Premium Value Positioning for Non-PVC IV Bags
Integration of digital tracking technologies into non-PVC bag films is transforming them from passive containers into active clinical safety tools, which creates fresh prospects for the non-PVC IV bags market. Embedding radio frequency identification tags and near field communication chips enables real-time monitoring of infusion rates, expiry alerts, and compatibility checks, reducing human error in high acuity settings. According to research, Intravenous medication administration is associated with a high rate of potential adverse drug events, and smart pump technology has demonstrated a significant reduction in administration errors in some pilot studies. The Veterans Health Administration, like other large healthcare systems, continues to adopt advanced technologies and best practices to improve patient safety and reduce medication errors. The use of smart, integrated medication delivery systems can lead to improvements in workflow efficiency and documentation processes, addressing concerns from healthcare professionals regarding time constraints. Regulatory bodies in various countries are beginning to acknowledge the potential safety and efficiency benefits of connected healthcare technologies, including those that integrate seamlessly with national electronic medical record systems. This convergence justifies premium pricing and creates defensible differentiation beyond material substitution.
MARKET CHALLENGES
Supply Chain Fragility for Specialty Polymers Threatens Consistent Availability of Non-PVC IV Bags
The concentrated global production of medical-grade polyolefin and ethylene vinyl acetate films creates systemic vulnerability to disruptions, which challenges the expansion of the non-PVC IV bags market. According to studies, the market for certain specialty resins is concentrated among a few global suppliers. Supply chain disruptions have caused significant production backlogs across manufacturers of certain medical products, as per sources. Disruptions to major suppliers, including weather-related events, have caused reductions in global output of critical materials for medical films. Import tariffs on resins have increased substantially over a sustained period. Specific resins are considered a highly vulnerable material category due to the limited geographic concentration of manufacturing capacity.
Clinical Inertia Among Prescribers and Nursing Staff Impedes Behavioral Adoption of Non-PVC IV Bags
Human factors remain a critical bottleneck in the non-PVC IV bags market. This is despite regulatory and technological readiness. Intravenous medication orders frequently do not include specifications for container material. A significant portion of healthcare staff are unable to accurately determine clinical indications for non-PVC bag use. Infusion errors, particularly those involving lipid emulsions, are often connected to staff being unfamiliar with the handling requirements of non-PVC products. Achieving competency in relevant handling procedures requires a substantial amount of dedicated training time. The absence of standardized protocols for using non-PVC bags is a regularly cited issue in medication safety reviews within accredited hospitals. This resistance stems not from opposition but from entrenched workflows and insufficient education, which makes behavioral change the final frontier in market maturation.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Type, Material, Application, and Region. |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Market Leaders Profiled | Renolit SE, Kraton Corporation, Shanghai Solve Care Co., Ltd., Shanghai Xin Gen Eco-Technologies Co., Ltd., PolyCine GmbH, Jiangxi Sanxin Medtec Co., Ltd., Sealed Air, Baxter, B. Braun Melsungen AG, Sichuan Kelun Pharmaceutical Co., Ltd., Fresenius Kabi AG, Otsuka Holdings Co., Ltd., Sartorius AG, Technoflex, and Huaren Pharmaceutical Co., Ltd. |
SEGMENTAL ANALYSIS
By Type Insights
The single-chambered non-PVC IV bag segment held the largest share of the global non-PVC IV bags market in 2024. The dominance of the single-chambered non-PVC IV bag segment is driven by its universal compatibility with standard infusion protocols and cost-efficient manufacturing. Single-chambered bags are the standard container for common intravenous solutions like saline, dextrose, and electrolytes. Their straightforward design enables efficient, high-speed production processes, leading to lower unit costs compared to multi-chambered alternatives. Healthcare reimbursement systems generally do not distinguish payment based on the number of chambers in the container. Official guidelines for solution quality and testing primarily specify compatibility with single-chambered containers. These bags are the predominant choice for the majority of non-chemotherapy infusions across various medical settings. Clinical inertia and reimbursement structures thus reinforce the hegemony of this format despite technological advances.
The multi-chambered non-PVC IV bag segment is predicted to witness the highest CAGR of 12.3% from 2026 to 2034. The rapid expansion of the multi-chambered non-PVC IV bag segment is propelled by the rising global incidence of complex chronic diseases requiring precisely sequenced drug nutrient combinations. Oncology protocols increasingly mandate staggered administration of cytotoxic agents and rescue nutrients within a single infusion event to minimize line access and infection risk. Many new drug treatments require specialized delivery methods to maintain drug stability. Regulatory bodies are increasingly approving advanced formulations, including multi-chambered bag systems. The use of multi-chambered bags has seen significant growth in clinical settings. Healthcare systems are investing substantial resources in procuring pre-filled, compartmentalized bags to actively reduce common medication errors associated with manual preparation. This growth is not speculative but anchored in clinical protocol evolution and institutional safety mandates.
By Material Insights
The ethylene vinyl acetate-based non-PVC IV bags segment was the prominent segment in the non-PVC IV bags market and captured a 61.7% share in 2024. Its unmatched balance of optical clarity, mechanical durability, and gas permeability, which closely mimics traditional PVC performance without plasticizers, has boosted the growth of the ethylene vinyl acetate-based non-PVC IV bags segment. The material exhibits flexibility at low temperatures, making it suitable for the cold chain transport of biologics and blood products, as per sources. Ethylene vinyl acetate films also demonstrate superior compatibility with lipid emulsions and protein-based therapeutics. The material demonstrates minimal leachable compounds after a specific period of contact. In addition, the use of this material is mandated for all fat emulsion containers for patients receiving lipid-based nutrition. As per various studies, bags made of this material successfully pass accelerated aging tests without issues like delamination or haze formation. These material properties are not merely advantageous but clinically non-negotiable for preserving drug integrity and ensuring visual inspection reliability.
The copolyester ether-based non-PVC IV bags segment is estimated to register the fastest CAGR of 15.3% during the forecast period. The material’s exceptional chemical resistance and extractables profile, which meets the stringent requirements of high-potency oncology and immunotherapy drugs, fuels the expansion of the copolyester ether-based non-PVC IV bags segment. Copolyester ether films exhibit undetectable levels of leachables after prolonged contact with solvents such as ethanol and propylene glycol. Moreover, copolyester ether has been designated as the reference material for cell and gene therapy infusions by a major regulatory agency. A major regulatory agency has granted breakthrough device designation to several copolyester ether-based bag platforms. Imports of copolyester ether bags have shown a significant increase. The material’s compatibility with gamma and electron beam sterilization without embrittlement further enhances its appeal for biologics manufacturers seeking shelf life extension beyond several months.
By Application Insights
The glucose injection segment led the non-PVC IV bags segment by holding a share of 39.5% in 2024. The leading position of the glucose injection segment is due to the universal clinical need for caloric maintenance and hypoglycemia correction across virtually all inpatient settings. According to research, Glucose-based infusions are widely administered, with dextrose five percent solutions commonly constituting a significant majority of intravenous fluid prescriptions in general medical wards. Glucose solutions are chemically stable and non-reactive, making them compatible with virtually all non-PVC film types, which simplifies procurement and reduces inventory complexity. In addition, Dextrose infusions are routinely used in the treatment of dehydration cases as part of standardized healthcare protocols. As per studies, Glucose solutions are the established primary intervention in most diabetic ketoacidosis admissions. Even in high acuity oncology units, glucose bags serve as maintenance fluids between chemotherapy cycles. Glucose bag use is a prevalent component of supportive care protocols in oncology units. This segment’s dominance is not transient but structurally embedded in foundational medical practice across disease states and care settings.
The targeted drug delivery segment is anticipated to witness the fastest CAGR of 18.1% over the forecast period, owing to the global proliferation of biologic and cell-based therapies that require chemically inert and precisely engineered containers. Monoclonal antibodies, small molecule inhibitors, and cell therapies such as CAR T cells are highly sensitive to surface interactions and leachables with Excipient container incompatibilities in oncology formulations have been extensively identified. Approved new targeted therapies commonly specify non-PVC copolyester or ethylene vinyl acetate containers in their prescribing information. Besides, approval processes for targeted delivery bag systems have been expedited. As per studies, targeted therapy infusions now represent a substantial percentage of all oncology admixtures in medical centers, showing significant growth. There has been a documented increase in the validation of non-PVC bags for antibody drug conjugates. This growth is not market speculation but a direct consequence of therapeutic innovation and regulatory specificity.
REGIONAL ANALYSIS
North America Non-PVC IV Bags Market Analysis
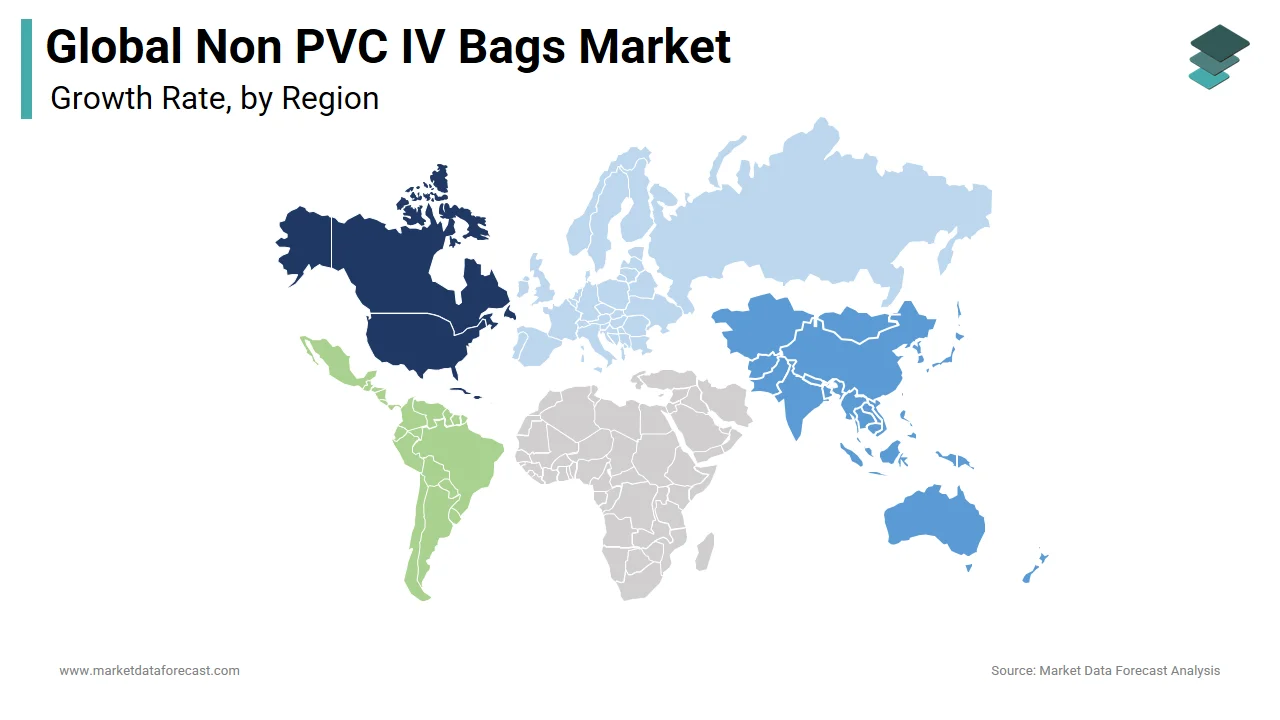
North America dominated the global non-PVC IV bags market by capturing a 34.2% share in 2024. Factors such as stringent regulatory enforcement, high reimbursement rates, and early adoption of smart infusion technologies contributed to the demand for non-PVC IV bags in the North American market. Regulatory bodies have rejected numerous PVC-based submissions on toxicological grounds. Healthcare payment systems reimburse non-PVC bags at a premium. Health systems have completed a full transition to non-PVC bags, which has reduced medication error rates, according to sources. Procurement alliances have standardized non-PVC specifications for all intravenous solutions. The region’s investment in digital health infrastructure further amplifies demand. Hospitals extensively use barcode-enabled infusion systems, which require RFID-compatible non-PVC films.
Europe Non-PVC IV Bags Market Analysis
In 2024, Europe was the second-largest region in the global non-PVC IV bags market and accounted for a 29.1% share. This growth is fueled by its harmonized regulatory framework and environmental legislation. The requirement for extractables data on plastic immediate packaging has pushed the pharmaceutical industry to conduct more rigorous compatibility and safety studies. Regulatory frameworks require specific disposal protocols for a particular type of medical waste, leading to high disposal costs, as per research. Many hospitals have made a full transition to alternative materials to comply with these requirements. The use of alternative materials has resulted in a significant reduction in certain emissions within healthcare systems. Mandatory criteria for procuring specific non-hazardous materials have been included in official healthcare supplier standards. Government health ministries have allocated funds specifically for upgrading medical systems and equipment in public hospitals. The region’s leadership is not merely economic but a regulatory setting global benchmarks for material safety and environmental compliance.
Asia Pacific Non-PVC IV Bags Market Analysis
Asia Pacific is another major player in the non-PVC IV bags market because of divergent adoption patterns between mature and emerging economies. Japan dominates the regional landscape with a notable share of Asia Pacific volume due to its early regulatory action and high geriatric care demand. Mandates for specific medical product types in pediatric and oncology infusions have been established, leading to high compliance. Regulatory approvals for numerous new product platforms of a particular type have increased. In contrast, India and Indonesia are in early growth phases but expanding rapidly. Significant funding has been allocated for the modernization of healthcare facilities. The Indonesian Food and Drug Monitoring Agency issued technical guidelines for non-PVC adoption in thousand twenty targeting tertiary hospitals in Jakarta and Surabaya. China’s growth is concentrated in Tier one cities, where biologics manufacturing hubs drive demand for copolyester ether bags, with import licenses showing a substantial increase over time.
Latin America Non-PVC IV Bags Market Analysis
Latin America is experiencing accelerated growth of the non-PVC IV bags market, which is driven by public health reforms and oncology expansion. Brazil leads regional adoption. The public health system mandates the use of non-PVC bags for specific infusions. As per sources, there has been a significant increase in the registration of non-PVC bags, with most volume captured by domestic manufacturers. The federal procurement agency standardized non-PVC specifications for all intravenous solutions in public hospitals, which has reduced the reliance on imports. Regulatory bodies are increasingly focusing on the safety and efficacy of container materials for sensitive biologics, leading to the evaluation and approval of alternative materials and non-PVC bags to meet evolving quality standards and reduce potential leaching concerns. Healthcare organizations and professional bodies are developing and implementing training programs and standardized protocols for the proper handling and administration of various infusion products, including those using non-PVC materials, to ensure patient safety and product integrity. The region’s growth is not organic but policy-driven, driven by regulatory modernization, unlocking latent demand.
Middle East and Africa Non-PVC IV Bags Market Analysis
Middle East and Africa region is expected to be the most lucrative region in the non-PVC IV bags market over the forecast period, owing to infrastructure investment and international accreditation mandates. A major health transformation program is directing significant funds toward hospital upgrades, with specific requirements for materials in all new facilities under construction. A regulatory body has given approval to numerous product platforms. Accreditation requirements for private hospitals include documented policies for specific material-free infusion systems. A national health department has collaborated with a global health organization to test product adoption in several hospitals, with plans for a broader implementation. A pharmaceutical regulatory authority has provided technical guidelines for using specific materials in certain hospital units. A federal health ministry has incorporated specific product procurement into its national essential medicines list revision. A health insurance fund has implemented financial incentives for hospitals using a particular type of product. The region’s expansion is strategically aligned with global quality benchmarks and donor-funded health system strengthening initiatives.
COMPETITIVE LANDSCAPE
The non-PVC IV bags market features concentrated competition among multinational healthcare manufacturers with differentiated technological capabilities and regulatory footprints. Baxter, Fresenius Kabi, and Sealed Air dominate through proprietary polymer formulations and global production networks while regional players compete on cost and local compliance. Innovation centers on material safety, extractables profiling, and smart integration rather than price. Regulatory agencies act as de facto gatekeepers, with approvals determining market access timelines. Collaboration with clinicians and hospital systems is critical to overcome behavioral resistance and ensure protocol alignment. Supply chain resilience is a key battleground, with resin sourcing and sterilization capacity defining scalability. Unlike commoditized segments, competition here is anchored in clinical validation, environmental certification, and digital interoperabilit,y making barriers to entry structural rather than financial. Market leadership correlates with regulatory agility and therapeutic relevance, not volume alone.
KEY MARKET PLAYERS
Some of the companies that are playing a dominating role in the global Non-PVC IV market include
- Renolit SE
- Kraton Corporation
- Shanghai Solve Care Co., Ltd.
- Shanghai Xin Gen Eco-Technologies Co., Ltd.
- PolyCine GmbH
- Jiangxi Sanxin Medtec Co., Ltd.
- Sealed Air
- Baxter
- Braun Melsungen AG
- Sichuan Kelun Pharmaceutical Co., Ltd.
- Fresenius Kabi AG
- Otsuka Holdings Co., Ltd.
- Sartorius AG
- Technoflex
- Huaren Pharmaceutical Co., Ltd.
TOP PLAYERS IN THE MARKET
- Baxter International Inc. has played a pivotal role in advancing non-PVC IV bag technology through continuous innovation in polymer formulation and global manufacturing infrastructure. The company maintains dedicated production facilities across three continents, enabling compliance with regional pharmacopoeial standards. It established clinical partnerships in Germany and Japan to integrate its bags with smart infusion systems. Baxter also launched educational initiatives across Latin America to support nursing staff in transitioning from PVC-based systems, ensuring operational adoption aligns with technological availability.
- Fresenius Kabi has cemented its position as a clinical solutions leader by designing non-PVC IV bags specifically for high acuity applications, including oncology and neonatal care. The company developed multi-chambered configurations that enable sequential drug nutrient delivery, while meeting stability requirements set by the European Medicines Agency. It expanded local manufacturing in India and Brazil to serve policy-driven emerging markets. Collaborations with nursing associations in Southeast Asia have standardized handling protocols, reinforcing safe clinical use across diverse healthcare environments.
- Sealed Air Corporation, through its Cryovac Healthcare unit, has pioneered sustainable material science innovations focused on chlorine-free polymers and digital integration. The company engineered gamma stable polyolefin laminates that maintain optical clarity without plasticizers or halogen content. Sealed Air established resin compounding hubs in Sweden and California to mitigate geographic supply risk. It also collaborated with waste authorities in Australia and the United Kingdom to validate end-of-life recyclability pathways. Its team contributed to three International Organization for Standardization specifications, enhancing global harmonization of non-PVC medical films.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players prioritize regulatory preemption by aligning material dossiers with pharmacopoeial revisions before enforcement deadlines. They invest in vertical integration, securing direct access to medical-grade polymer resins to insulate against supply volatility. Strategic clinical partnerships with oncology and neonatal networks ensure product design reflects real-world protocol demands. Companies embed digital tracking capabilities like near field communication and radio frequency identification to integrate with hospital informatics, reducing manual errors. Geographic expansion focuses on policy-driven markets where legislation mandates non-PVC adoption, creating defensible entry barriers. Training programs for nurses and pharmacists address behavioral inertia, ensuring operational adoption matches technological availability. These strategies collectively reinforce market presence through compliance innovation and ecosystem alignment.
MARKET SEGMENTATION
This research report on the global Non-PVC IV bags Market has been segmented and sub-segmented based on the Type, material, Application, and Region.
By Type
- Single-chambered
- Multi-chambered
By Material
- Polypropylene (PP) IV Bag
- Polyethylene IV Bag
- Copolyester Ether IV Bag
- Ethylene-Vinyl Acetate (EVA) IV Bag
- Others
By Application
- Chemotherapy
- targeted Drug Delivery
- Glucose Injection
- Sodium Chloride Solution
- Electrolyte Injection
- Nutrient Injection
By Region
- North America
- Latin America
- Europe
- Asia-Pacific
- Middle East and Africa