- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$3.81 BnMarket Estimate, 2026
$4.04 BnMarket Forecast, 2034
$6.37 BnCAGR, 2026–2034
5.87%Executive Summary: North America Flexographic Printing Inks Market
- Market Scope: Comprehensive North American flexographic printing inks market analysis covering ink technologies, application segments, country-level leadership frameworks, and sustainable packaging trends.
- Market Valuation: Valued at USD 3.81 billion (2025), estimated at USD 4.04 billion (2026), and projected to reach USD 6.37 billion by 2034, registering a steady CAGR of 5.87% (2026–2034).
- Primary Growth Drivers: Rising demand for flexible packaging, increasing sustainability initiatives, and the adoption of advanced printing technologies across packaging, food and beverage, pharmaceuticals, and e-commerce. Key catalysts include water-based/UV-curable inks, lightweight packaging, and bio-based formulations.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (Base Year Position) | Fastest-Growing Segment |
|---|---|---|
| By Ink Type / Technology | Water-Based Inks Segment (dominated with a 45.3% share in 2025 due to low VOCs and food safety compliance) | UV-Cured Inks Segment (projected to register the fastest CAGR of 7.8%) |
| By Application | Packaging Segment (held the largest market share in 2025 across labels, flexible packaging, and corrugated boxes) | Specialized and Extended Application Sectors |
| By Formulation Focus | Standard Solvent and Water-Based Formulations | Bio-based, compostable, and digital-compatible formulations |
| By Country / Region | United States (led the market with an 80.4% share in 2025, followed by Canada at 17.2%) | Expanding sustainable printed packaging networks across North America |
Major Market Players & Market Structure
Market Structure: Intense competitive landscape characterized by corporate focus on sustainable formulations, product innovation, digital compatibility, strategic partnerships, and facility expansions. Key strategic developments include Sun Chemical's bio-based ink launches and R&D investments, Flint Group's Illinois production facility expansion, and INX International's closed-loop recycling systems and customer support platforms.
Key Companies: DIC CORPORATION, INX International Ink Co., Sun Chemical Corp. Inc., Antonine Printing Inks Ltd, Kao Chimigraf, and Flint Group.
 Download Free Sample Report
North America Flexographic Printing Inks Market Size
The North America Flexographic Printing Inks Market is projected to grow from USD 3.81 billion in 2025 to USD 4.04 billion in 2026 and reach USD 6.37 billion by 2034, registering a CAGR of 5.87% from 2026 to 2034.
MARKET DRIVERS
Growing Demand for Flexible Packaging
Flexible packaging is a primary driver of the North America flexographic printing inks market, fueled by its versatility and cost-effectiveness across industries like food and beverage, pharmaceuticals, and e-commerce. This surge is attributed to the increasing consumer preference for convenient, resealable, and lightweight packaging solutions. Flexographic inks play a critical role in this segment, enabling high-quality printing on diverse substrates such as plastic films, paper, and aluminum foils. For instance, water-based flexographic inks are widely used in food packaging due to their non-toxic and odorless properties, ensuring compliance with FDA regulations. Another factor driving demand is the rise of e-commerce, which requires durable and visually appealing packaging to protect products during transit.
Shift Toward Sustainable Solutions
The shift toward sustainable printing solutions is another significant driver, propelled by stringent environmental regulations and consumer awareness. According to the Environmental Protection Agency, the U.S. generates over 80 million tons of packaging waste annually, which is prompting brands to adopt recyclable and biodegradable materials. UV-curable and water-based flexographic inks have gained traction as eco-friendly alternatives to solvent-based inks by reducing VOC emissions by up to 90%. Additionally, companies are investing in bio-based inks derived from renewable resources like vegetable oils by aligning with corporate sustainability goals.
MARKET RESTRAINTS
Volatile Raw Material Prices
One of the most pressing restraints in the North America flexographic printing inks market is the volatility of raw material prices for resins, pigments, and solvents. These materials are subject to price fluctuations driven by geopolitical tensions, supply chain disruptions, and energy costs. For instance, the price of titanium dioxide, a key pigment used in white inks, surged by over 30% in 2022 due to export restrictions in China. Such instability creates uncertainty for manufacturers, who must either absorb additional costs or pass them on to customers. This pricing volatility disproportionately affects small and medium-sized enterprises, which operate on tighter margins and lack the financial resilience to weather sudden cost spikes. Moreover, frequent price adjustments disrupt long-term planning and investment decisions by hindering market growth.
Stringent Regulatory Standards
Another significant restraint is the stringent regulatory framework governing VOC emissions and chemical usage in printing inks. Compliance with these regulations often involves costly R&D investments and process modifications. Additionally, state-level regulations, such as California’s Proposition 65, impose further restrictions, complicating cross-border operations. These challenges create barriers for smaller players and slow down the adoption of innovative solutions, thereby impacting overall market dynamics.
MARKET OPPORTUNITIES
Adoption of Digital Printing Technologies
The integration of digital printing technologies presents a transformative opportunity for the North America flexographic printing inks market. Flexographic inks are increasingly being optimized for compatibility with digital presses by enabling high-speed, customizable printing for short-run jobs. This trend is particularly relevant in the label and packaging sectors, where brands demand personalized designs and variable data printing. For instance, the food and beverage industry uses digital flexographic inks to print batch-specific information, such as expiration dates and QR codes, enhancing traceability and consumer engagement. Moreover, the ability to switch between traditional and digital workflows allows manufacturers to meet diverse customer needs while maintaining operational efficiency.
Expansion into Biodegradable and Compostable Inks
Another promising opportunity lies in the development of biodegradable and compostable flexographic inks, which cater to the growing demand for sustainable packaging. Bio-based inks, derived from renewable resources like soybean oil and cornstarch, offer a viable alternative to petroleum-based formulations, reducing environmental impact. The U.S. Department of Agriculture’s BioPreferred Program promotes the use of such materials by providing certification and marketing support to manufacturers. Additionally, compostable inks align with zero-waste initiatives, particularly in industries like food delivery and retail. For example, coffee chains are adopting compostable cups printed with bio-based inks to enhance their sustainability credentials.
MARKET CHALLENGES
Intense Competition and Price Wars
Intense competition within the North America flexographic printing inks market poses a significant challenge, exacerbated by the presence of numerous global and regional players vying for market share. This competitive environment often leads to price wars, eroding profit margins and making it difficult for companies to sustain long-term growth. Smaller players frequently undercut prices to attract customers, while larger companies struggle to differentiate their offerings in a saturated market. Additionally, the influx of low-cost imports from countries like China and India further intensifies pricing pressures. This combination of internal rivalry and external competition creates a challenging environment for businesses seeking profitability and market stability.
Limited Awareness of Advanced Ink Technologies
Another pressing challenge is the limited awareness and adoption of advanced ink technologies among end-users, particularly small and medium-sized enterprises. Despite the availability of innovative solutions like UV-curable and LED-curable inks, many businesses remain hesitant to invest due to perceived risks and upfront costs. According to a survey by Printing Industries of America, over 60% of small printing firms cite lack of knowledge and technical expertise as barriers to adopting new technologies. Moreover, the absence of standardized training programs and industry-wide education initiatives exacerbates the issue.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Product Type, Application and Country. |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis; DROC, PESTLE Analysis, Porter's Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Country Covered | The U.S., Canada and Rest of North America |
| Market Leader Profiled | DIC CORPORATION, INX International Ink Co., Sun Chemical Corp. Inc. |
SEGMENTAL ANALYSIS
By Product Type Insights
The water-based inks segment led the North America flexographic printing inks market by capturing 45.3% of the share in 2025 with their widespread use in food and beverage packaging, where safety and compliance with stringent regulations are paramount. According to the Food and Drug Administration (FDA), water-based inks are preferred for direct and indirect food contact applications due to their non-toxic and odorless properties. According to the Environmental Protection Agency, water-based inks emit up to 90% fewer VOCs compared to solvent-based alternatives by aligning with environmental goals. Another driving factor is the increasing adoption of lightweight flexible packaging. The Flexible Packaging Association reports that flexible packaging accounted for nearly 19% of the U.S. packaging market in 2022, driven by its recyclability and cost-effectiveness. Water-based inks excel in this segment due to their ability to adhere to diverse substrates like plastic films and paper without compromising print quality.
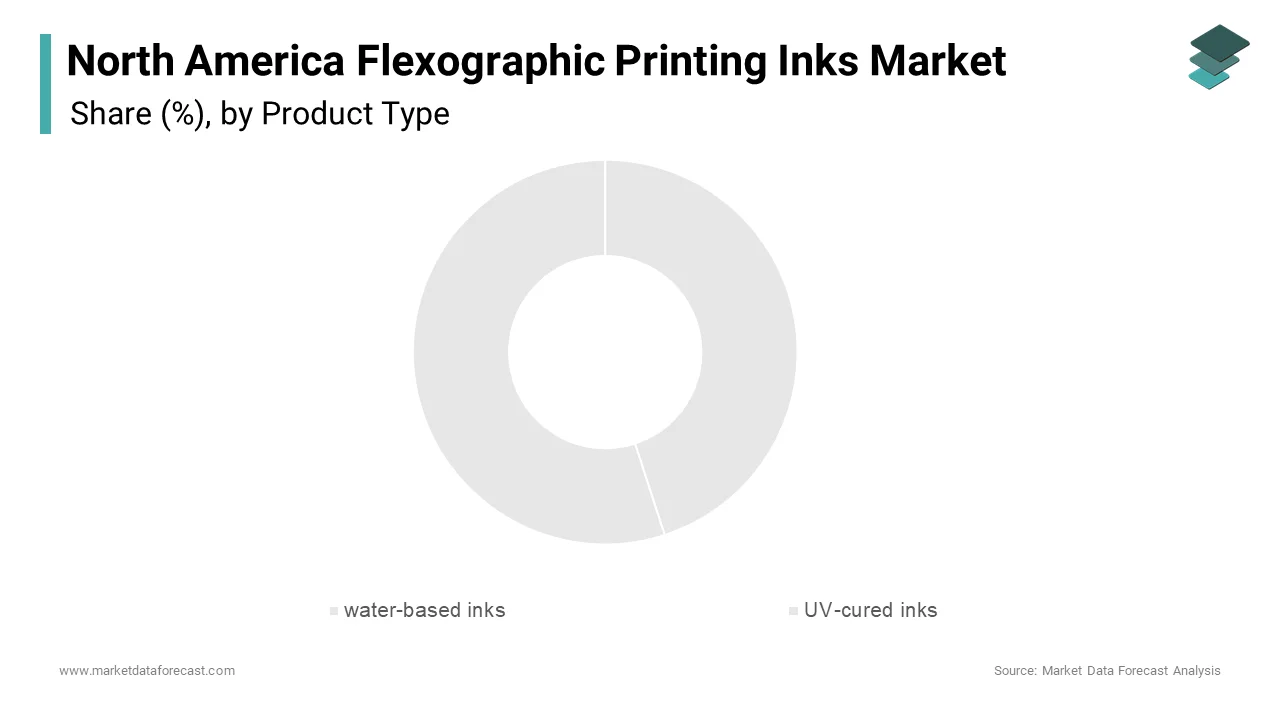
The UV-cured inks segment is projected to register a CAGR of 7.8% from 2025 to 2033. The growth of the segment is fueled by their superior performance characteristics, including instant curing, high durability, and vibrant color reproduction. A major factor driving this growth is the shift toward digital printing technologies. Keypoint Intelligence notes that hybrid printing systems combining flexography and inkjet technology are increasingly adopting UV-cured inks for their compatibility and efficiency. Another factor is the rising demand for premium packaging in industries like cosmetics and pharmaceuticals. UV-cured inks enable intricate designs and glossy finishes by meeting these aesthetic requirements while ensuring compliance with regulatory standards.
By Application Insights
The packaging was the largest segment in the North America flexographic printing inks market with dominant share in 2025. The growth of the segment is attributed to the extensive use of flexographic inks in flexible packaging, labels, and corrugated boxes, which are critical to industries like food and beverage, e-commerce, and pharmaceuticals. A key factor driving this dominance is the rise of e-commerce. Another contributing factor is the growing emphasis on sustainability. The Environmental Protection Agency estimates that over 80 million tons of packaging waste are generated annually in the U.S. by prompting brands to adopt recyclable materials. Water-based and UV-cured flexographic inks play a pivotal role in this transition by enabling eco-friendly printing without compromising quality.
The "Other" segment is likely to experience a CAGR of 6.5% in the foreseen years. The growth of the segment can be driven the versatility of flexographic inks in meeting diverse industrial needs. For instance, flexographic inks are widely used in textile printing for producing vibrant designs on fabrics in the fashion and home decor industries. Another factor is the increasing adoption of flexographic inks in the automotive sector for printing on interior components and decals. According to the Center for Automotive Research, vehicle production in North America exceeded 16 million units in 2022 by driving demand for high-quality inks. Additionally, advancements in ink formulations have expanded their applicability to unconventional substrates, such as metals and ceramics, further propelling growth.
COUNTRY LEVEL ANALYSIS
The United States led the North America flexographic printing inks market with 80.4% of the share in 2025 owing to a robust packaging industry and strong regulatory focus on sustainability. A key driver is the widespread use of water-based inks in food and beverage packaging by ensuring compliance with FDA regulations. Additionally, the rise of e-commerce has amplified demand for corrugated boxes and shipping labels will accelerate the growth of the segment.
Canada was second by capturing 17.2% of the North America flexographic printing inks market share in 2025 with the growing emphasis on sustainable packaging and the country’s strong presence in the food and beverage sector. According to Agriculture and Agri-Food Canada, the food processing industry contributes over CAD 140 billion annually to the economy by creating steady demand for safe and compliant printing inks. Water-based inks are widely adopted in this segment due to their non-toxic properties and alignment with environmental goals. Another factor is the increasing adoption of UV-cured inks in premium packaging applications. According to the Canadian Packaging Association, the demand for visually appealing packaging has surged in the cosmetics and pharmaceutical industries.
KEY MARKET PLAYERS AND COMPETITIVE LANDSCAPE
Companies playing a prominent role in the North America flexographic printing inks market are DIC CORPORATION, INX International Ink Co., Sun Chemical Corp. Inc., Antonine Printing Inks Ltd, Kao Chimigraf.
The North America flexographic printing inks market is characterized by intense competition with the presence of global leaders and regional players striving to innovate and capture market share. Companies are investing heavily in R&D to develop cutting-edge products, such as biodegradable inks and UV-curable solutions, to cater to diverse industrial needs. The market is also witnessing a surge in collaborations, mergers, and acquisitions by enabling firms to consolidate their positions and expand their portfolios. Regulatory pressures to adopt safer and greener alternatives have further intensified competition, pushing companies to align with sustainability goals. Additionally, price wars and aggressive marketing tactics are common among smaller players seeking to challenge established brands.
Top Players in the Market
Sun Chemical
Sun Chemical is a leading innovator in the North America flexographic printing inks market, renowned for its sustainable and high-performance ink solutions. The company has made significant contributions by developing eco-friendly products, such as bio-based and water-based inks, which align with regulatory standards and consumer preferences. In 2023, Sun Chemical launched a new line of bio-based inks designed to reduce carbon footprints while maintaining superior print quality. Additionally, the company has invested in expanding its R&D capabilities to enhance product recyclability and compatibility with digital printing technologies by reinforcing its commitment to sustainability and innovation.
Flint Group
Flint Group is a key player known for its advanced UV-cured and solvent-based flexographic inks, widely used in packaging and industrial applications. The company has strengthened its market position by expanding its production facilities in North America, particularly in Illinois, to meet rising demand for UV-cured inks. Flint Group has also introduced customized ink solutions tailored to specific customer needs, ensuring high performance across diverse substrates. Recent initiatives include collaborations with end-users to optimize ink formulations for sustainability and efficiency by reflecting its focus on delivering value-added solutions to the market.
INX International Ink Co.
INX International Ink Co. specializes in innovative flexographic inks, including water-based and UV-curable formulations by catering to industries like food packaging and e-commerce. The company has recently partnered with recycling firms to develop closed-loop systems for reusing spent inks, promoting circular economy practices. INX has also launched a digital platform to streamline customer orders and provide real-time technical support by enhancing operational efficiency.
Top Strategies Used by Key Players
Key players in the North America flexographic printing inks market employ strategies such as product innovation, strategic partnerships, and sustainability initiatives to maintain their competitive edge. Product innovation involves developing advanced inks, such as bio-based and UV-curable formulations, to meet evolving industry standards and consumer demands. Strategic partnerships with recycling firms and technology providers enable companies to enhance supply chain efficiency and adopt circular economy practices. Sustainability initiatives focus on reducing environmental impact through recyclable materials and energy-efficient manufacturing processes. Additionally, investments in R&D and facility expansions allow firms to enhance production capacities and deliver high-quality products.
RECENT HAPPENINGS IN THE MARKET
- In March 2023, Sun Chemical launched a new line of bio-based flexographic inks, which was designed to reduce carbon footprints while maintaining high performance.
- In June 2023, Flint Group expanded its production facility in Illinois, USA, to meet rising demand for UV-cured inks in the packaging sector.
- In August 2023, INX International partnered with a recycling firm to develop a closed-loop system for reusing spent inks, which is promoting circular economy practices.
- In November 2023, Siegwerk introduced a digital platform to streamline customer orders and provide real-time technical support for ink solutions.
- In February 2025, Toyo Ink acquired a startup specializing in water-based ink technology, which is enhancing its portfolio for food packaging applications.
MARKET SEGMENTATION
This research report on the north america flexographic printing inks market has been segmented and sub-segmented into the following.
By Product Type
- water-based inks
- UV-cured inks
By Application
- packaging
- Other
By Country
- The U.S.
- Canada
- Rest of North America