- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$1.24 BnMarket Estimate, 2026
$1.26 BnMarket Forecast, 2034
$1.39 BnCAGR, 2026–2034
1.26%North American Potato Chips Market Size, Growth, Trends & Forecast (2026–2034)
The North American potato chips market size was valued at USD 1.24 billion in 2025, is anticipated to be worth USD 1.26 billion in 2026, and is projected to reach USD 1.39 billion by 2034, growing at a compound annual growth rate (CAGR) of 1.26% during the forecast period. Driven by continuous flavor innovations, expansion into organic and natural snack variants, and the rapid rise of digital and e-commerce distribution channels, the market continues steady evolution across the region.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 1.24 Billion
- 2026 Current Valuation: USD 1.26 Billion
- 2034 Forecast Valuation: USD 1.39 Billion
- Compound Annual Growth Rate (CAGR): 1.26% (2026–2034)
- Dominant Product Type Segment: Flavored chips segment (holding 35% of the market share in 2025)
- Fastest-Growing Product Type Segment: Organic/natural potato chips segment (registering a CAGR of 8.3%)
- Dominant Distribution Channel Segment: Supermarkets and hypermarkets segment (holding 42.1% of the total retail volume in 2025)
- Fastest-Growing Distribution Channel Segment: Online retail segment (expanding at a CAGR of 9.5%)
- Dominant Region: United States (accounting for 74.1% of total regional consumption in 2025)
Core Market Drivers
- On-the-Go Snacking: Growing consumer preference for convenient, ready-to-eat, and portable snack items driven by fast-paced urban lifestyles.
- Flavor Innovation & Diversification: Continuous introduction of bold regional tastes, limited-edition releases, and clean-label wellness options by major brands.
Primary Market Restraints & Challenges
- Health Awareness & Regulations: Consumer shift toward low-fat/low-sodium alternatives, tightening nutritional labeling mandates (e.g., Health Canada's "High in" labels), and raw material price volatility.
North American Potato Chips Market Segmentation Breakdown
| Segment Category | Leading Sub-Segment (Base Year) | Fastest-Growing Sub-Segment |
|---|---|---|
| By Product Type | Flavored Chips (35% share in 2025) | Organic/Natural Potato Chips (CAGR of 8.3%) |
| By Distribution Channel | Supermarkets/Hypermarkets (42.1% share in 2025) | Online Retail (CAGR of 9.5%) |
Major Industry Players Profiled
Key market participants shaping the North American potato chips industry include PepsiCo (Frito-Lay), Kellogg Company (Pringles), Utz Brands (Utz Quality Foods), Kettle Brand, Cape Cod Potato Chips, Great Lakes Potato Chip Co., and Wise Foods.
North American Potato Chips Market Size
The North American potato chips market size was valued at USD 1.24 billion in 2025 and is expected to reach USD 1.39 billion by 2034 from USD 1.26 billion in 2026. The market is projected to grow at a CAGR of 1.26%.
The North American potato chips market refers to the production, distribution, and retail sales of crisped or baked potato-based snacks across the United States and Canada. As one of the most popular snack categories in the region, potato chips are consumed as standalone products and as part of multi-snack packs, catering to a wide range of consumer preferences for taste, texture, and convenience. The market encompasses traditional salted variants and an expanding array of flavor options that reflect evolving dietary trends and flavor experimentation. As per Statistics Canada, the food manufacturing sector witnessed a 6% increase in value-added production in 2023, with snack foods playing a notable role. Moreover, the influence of pop culture, social media-driven flavor innovation, and widespread availability through convenience stores, supermarkets, and online platforms further solidify the potato chips segment within the broader snack industry.
MARKET DRIVERS
Rising Consumer Preference for On-the-Go Snacking
One of the key drivers of the North American potato chips market is the growing consumer inclination toward convenient, ready-to-eat snacking solutions. With increasingly fast-paced lifestyles and higher levels of urbanization, individuals are opting for portable, shelf-stable snacks that can be easily consumed during work breaks, commutes, or outdoor activities. In addition, convenience store networks such as 7-Eleven and Circle K have expanded their snack aisles to include a broad range of potato chip varieties tailored to regional flavor preferences. These factors collectively indicate a deepening integration of potato chips into daily consumption habits, reinforcing sustained demand across the North American market.
Flavor Innovation and Product Diversification
Another significant driver of the North American potato chip market is the continuous introduction of innovative flavors and healthier product variations that cater to changing consumer tastes and dietary preferences. Manufacturers are investing heavily in R&D to develop distinctive flavor profiles rooted in global cuisines, limited-edition releases, and functional ingredients that align with wellness-focused consumption habits. For instance, brands like Lay’s and Kettle Brand have launched regional collaborations featuring locally sourced spices and artisanal seasonings, enhancing brand engagement and customer loyalty. Simultaneously, health-conscious consumers are shifting toward alternative varieties such as kettle-cooked, sea salt-infused, and organic potato chips.
MARKET RESTRAINTS
Growing Health Awareness and Shift Toward Low-Fat Alternatives
A primary restraint affecting the North American potato chips market is the increasing consumer awareness regarding the health implications of high-fat and high-sodium diets. As public health initiatives gain momentum across both the U.S. and Canada, consumers are becoming more cautious about their snack choices, often substituting potato chips with lower-calorie alternatives such as air-popped popcorn, veggie crisps, and rice cakes. According to the Centers for Disease Control and Prevention (CDC), cardiovascular disease remains the leading cause of death in the U.S., with excessive sodium intake identified as a major contributing factor. These findings have prompted regulatory bodies like the U.S. Food and Drug Administration (FDA) to propose voluntary sodium reduction targets for packaged snack foods, including potato chips. Moreover, school districts across North America have implemented nutrition policies restricting the sale of high-fat snacks on campuses, directly impacting youth consumption patterns.
Volatility in Raw Material Prices and Supply Chain Disruptions
Another critical restraint influencing the North American potato chips market is the fluctuating cost and availability of raw materials, particularly potatoes and vegetable oils—key components in production. Climatic variability, agricultural pests, and transportation bottlenecks have contributed to inconsistent supply conditions, leading to price volatility that affects both manufacturers and consumers. Simultaneously, oilseed prices, especially for sunflower and canola oils, experienced a 22% increase over the same period, driven by global trade disruptions and inflationary pressures. These increases were reflected in retail pricing, with major retailers such as Kroger and Walmart reporting a 6–10% hike in potato chip prices across select private-label brands in early 2025. Also, logistics constraints stemming from labor shortages and fuel cost surges have delayed deliveries and increased packaging expenses.
MARKET OPPORTUNITIES
Surge in Demand for Functional and Fortified Snacks
An emerging opportunity for the North American potato chip market lies in the growing consumer interest in functional and fortified snacks that offer added nutritional benefits. As modern consumers seek out products that align with their wellness goals, manufacturers are responding by incorporating protein enhancements, prebiotic fibers, and essential vitamins into potato chip formulations without compromising on taste or texture. According to the International Food Information Council (IFIC), 65% of U.S. consumers in 2025 indicated a preference for snacks that provide health benefits beyond basic nutrition. This shift has prompted companies like Frito-Lay and Utz Quality Foods to introduce lines enriched with plant-based proteins, omega-3 fatty acids, and reduced sodium content. Notably, Lay’s launched a line of protein-enhanced potato crisps in late 2023, which quickly gained traction among fitness-oriented consumers and office workers seeking satiating midday snacks. In Canada, the trend toward functional snacking is supported by Health Canada’s updated labeling regulations, which emphasize transparency in nutrient content and encourage the development of healthier processed foods.
Expansion of E-commerce and Direct-to-Consumer Distribution Channels
The rapid evolution of e-commerce platforms and direct-to-consumer (DTC) delivery services presents a significant growth opportunity for the North American potato chips market. As digital shopping becomes more ingrained in consumer behavior, brands are leveraging online channels to reach niche audiences, introduce specialty flavors, and enhance brand engagement through personalized offerings. Platforms such as Amazon Fresh, Instacart, and Shipt have made it easier for consumers to explore regional and gourmet potato chip varieties, including small-batch and ethnic-flavored options that may not be widely available in local stores. This accessibility has allowed boutique and independent brands to compete more effectively with established national players. Besides, social commerce initiatives fueled by TikTok Shop and Shopify integrations have enabled direct consumer engagement, allowing innovative brands to launch limited-edition flavors and track real-time customer feedback.
MARKET CHALLENGES
Regulatory Pressure and Nutrition Labeling Requirements
A major challenge facing the North American potato chips market is the tightening of food labeling regulations and increased scrutiny of nutritional content. Both the U.S. and Canadian governments have introduced stricter mandates aimed at improving consumer transparency and promoting healthier eating habits, which have placed pressure on manufacturers to reformulate products or disclose potential health risks. Similarly, Health Canada implemented mandatory “High in” labeling for packaged snacks exceeding specified thresholds for critical nutrients, effective from January 2025. These changes are intended to help consumers make informed choices, but they also pose reputational risks for traditional potato chip brands. In response, several manufacturers have accelerated efforts to reduce sodium, incorporate heart-healthy oils, and introduce low-acrylamide frying techniques. However, altering recipes can affect taste and texture, potentially deterring loyal customers.
Intensifying Competition from Alternative Snack Categories
An additional challenge confronting the North American potato chips market is the intensifying competition from alternative snack formats such as plant-based crisps, extruded snacks, and snack bars that offer comparable convenience with perceived health advantages. As consumer preferences shift toward diverse textures and functional ingredients, traditional potato chip brands face mounting pressure to innovate or risk losing market share. Products made from lentils, chickpeas, and root vegetables are being marketed as lower-carbohydrate, higher-protein alternatives that appeal to health-conscious millennials and Gen Z consumers. Moreover, the popularity of air-fried and dehydrated snacks has introduced a wider variety of options that mimic the crunch of potato chips without the same caloric density. At the same time, private-label brands offered by major retailers like Costco, Target, and Whole Foods have entered the fray with competitively priced alternatives, eroding the dominance of established national brands.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 1.26% |
| Segments Covered | By Product Type, Distribution Channel, And Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis; Segment-Level Analysis; DROC, PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | US, Canada, Mexico, and Rest of North America |
| Market Leaders Profiled | Frito-Lay, Utz Quality Foods, Kellogg Company, Kettle Brand, Cape Cod Potato Chips, Great Lakes Potato Chip Co, and Wise Foods |
SEGMENTAL ANALYSIS
By Product Type Insights
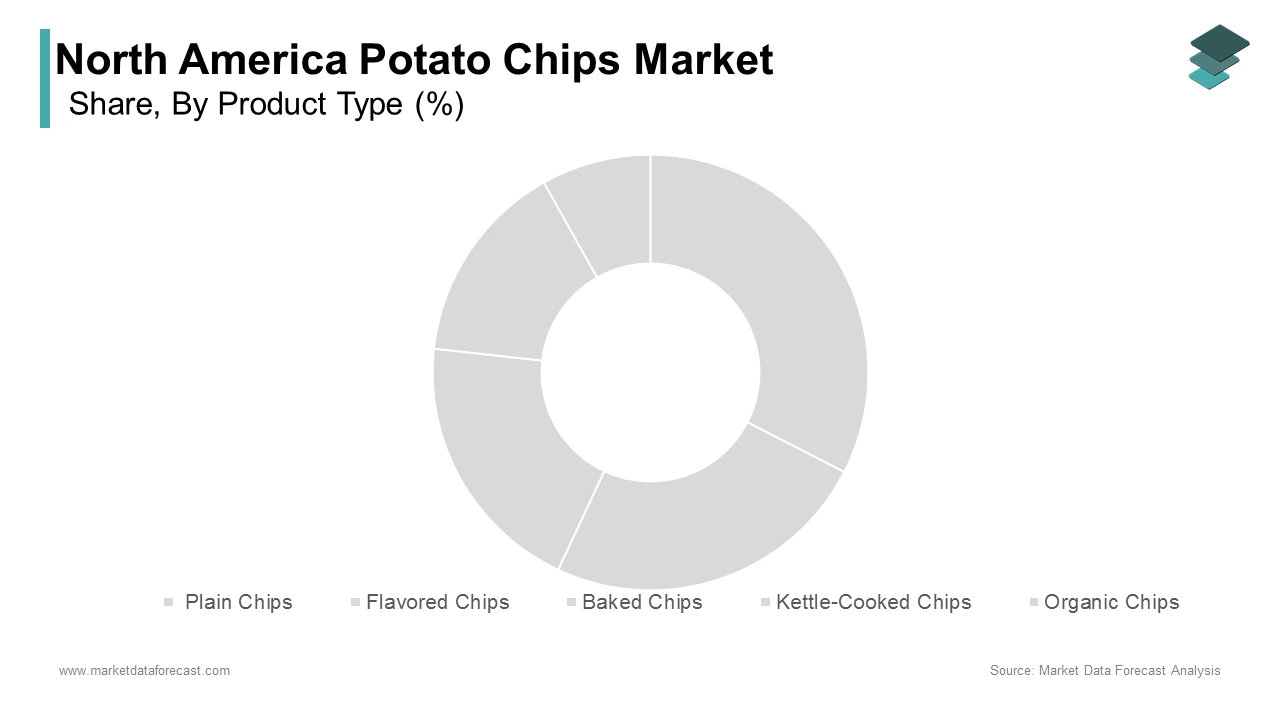
Flavored chips represented the largest segment in the North American potato chips market by capturing an estimated 35% of the total market share in 2025. This dominance is primarily driven by evolving consumer preferences for bold and diverse flavor experiences, which has led manufacturers to continuously innovate with regional, spicy, and globally inspired seasonings. Additionally, major brands such as Lay’s and Kettle Brand have launched limited-edition seasonal flavors and region-specific collaborations such as Lay’s “Texas BBQ” or Kettle Brand’s “Maple Bacon”—to capture consumer attention and drive repeat purchases.
The organic/natural potato chips segment is projected to grow at the fastest rate within the North American potato chips market, registering a CAGR of 8.3%. This rapid expansion is fueled by rising health consciousness among consumers and a shift toward minimally processed food options with clean-label ingredients. As per the Organic Trade Association (OTA), organic snack food sales in the U.S. grew by 12% in 2023 compared to the previous year, with potato chips being one of the top-performing categories. Health Canada's updated dietary guidelines in 2023 emphasized the reduction of artificial additives, encouraging manufacturers like Terra and Late July to expand their certified organic chip offerings. Moreover, younger consumers, particularly millennials and Gen Z, are prioritizing transparency in sourcing and production. A 2025 study by the International Food Information Council (IFIC) revealed that 67% of American consumers actively seek out organic claims when purchasing packaged snacks.
By Distribution Channel Insights
The supermarkets and hypermarkets accounted for the biggest distribution channel in the North American potato chips market by holding 42.1% of total retail volume in 2025. This control is credited to the widespread presence of these retail formats, their extensive product assortments, and the convenience they offer to consumers seeking both branded and private-label options. These retailers maintain strong promotional campaigns around popular potato chip brands, often featuring them in weekly flyers and loyalty programs to drive foot traffic. The integration of store-brand potato chip lines by major retailers further enhances accessibility and affordability, reinforcing the position of supermarkets/hypermarkets as the primary conduit for potato chip consumption across North America.
Online retail is rising as the quickest advancing distribution channel in the North American potato chips market, expanding at a CAGR of 9.5%. This accelerated growth is driven by the increasing adoption of digital shopping platforms, improved last-mile delivery infrastructure, and the growing appeal of niche and gourmet potato chip varieties available exclusively online. Platforms such as Amazon Fresh, Instacart, and Shipt have enabled consumers to access a broader range of products beyond what is typically available in local stores, including limited-run flavors and small-batch artisanal potato chips. Also, direct-to-consumer (DTC) models adopted by independent chip makers have allowed for personalized marketing and subscription-based services, enhancing customer retention.
REGIONAL ANALYSIS
The United States held the dominant position in the North American chips market by accounting for an estimated 74.1% of total regional consumption in 2025. This is underpinned by high per capita snack consumption, well-established brand presence, and a robust manufacturing ecosystem that supports both domestic and international demand. The influence of major players such as PepsiCo, Kellogg’s, and Utz Brands ensures continuous product innovation and marketing reach. Furthermore, the rise of convenience culture and on-the-go lifestyles has reinforced demand for single-serve and travel-friendly packaging. Canada's positioning reflects a stable consumer base, strong retail networks, and a growing emphasis on healthier snacking alternatives that cater to shifting dietary preferences. As per Statistics Canada, per capita consumption of salty snacks, including potato chips, has remained steady at around 7 kilograms annually, with urban centers such as Toronto, Montreal, and Vancouver showing higher-than-average consumption rates. Moreover, Canada’s regulatory environment is increasingly focused on nutrition transparency and reduced sodium content, prompting manufacturers to reformulate existing products.
The remaining North American countries are gradually gaining traction due to cross-border brand expansions, changing consumer habits, and rising disposable incomes. Frito-Lay and Sabritas, a subsidiary of PepsiCo, have maintained a significant presence in the Mexican market, offering localized flavors that resonate with regional tastes. In addition, trade agreements such as USMCA have facilitated smoother import channels for potato chips and other processed snacks into Central America and the Caribbean.
LEADING PLAYERS IN THE NORTH AMERICAN POTATO CHIPS MARKET
PepsiCo (Frito-Lay)
PepsiCo, through its Frito-Lay division, is a dominant force in the North American potato chips market. Known for iconic brands like Lay’s, Ruffles, and Doritos, the company has consistently led in product innovation, marketing, and distribution. Its strong supply chain infrastructure ensures widespread availability across retail and food service channels. In addition to traditional offerings, Frito-Lay has expanded into baked, kettle-cooked, and plant-based snack alternatives, catering to evolving consumer preferences. Globally, PepsiCo leverages its regional success in North America as a model for international expansion, reinforcing its leadership in the global savory snacks industry.
Kellogg Company (Pringles)
Kellogg Company, particularly through its Pringles brand, holds a significant share of the North American potato chips market. Unlike traditional bagged chips, Pringles’ unique saddle-shaped design and canister packaging have carved out a distinct niche in the category. The brand’s continuous investment in flavor innovation and limited-edition releases keeps it relevant among younger consumers. Internationally, Pringles serves as a flagship export product for Kellogg, with North America acting as a key innovation hub that influences global flavor rollouts and packaging strategies.
Utz Brands
Utz Brands is a prominent regional player known for its commitment to quality, family-owned heritage, and diversified product portfolio. With well-established brands such as Utz, Zapp’s, and Boulder Canyon, the company emphasizes natural ingredients, kettle cooking, and organic options tailored to health-conscious consumers. Utz has strengthened its position by acquiring smaller specialty chip brands and expanding its footprint through strategic partnerships. In the global context, Utz contributes to the growing demand for artisanal and premium potato chips, enhancing North America's reputation as a center for innovative snacking solutions.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
One major strategy employed by leading players in the NortAmericanca potato chips market is continuous flavor innovation and customization. Companies are investing heavily in research and development to introduce new taste profiles inspired by global cuisines, seasonal themes, and regional preferences, ensuring sustained consumer engagement and brand differentiation.
Another key approach is expanding product portfolios to include healthier variants, such as baked, reduced-fat, and organic options. As health consciousness grows, manufacturers are reformulating existing products and launching clean-label alternatives that align with dietary trends without compromising on taste or texture.
Lastly, strengthening omnichannel distribution networks has become a priority for major players. By optimizing both physical and digital sales channels—including supermarkets, convenience stores, e-commerce platforms, and direct-to-consumer models—companies are enhancing accessibility and brand visibility while adapting to shifting consumer purchasing behaviors.
KEY MARKET PLAYERS AND COMPETITION OVERVIEW
Major Players in the North American potato chips market include Frito-Lay, Utz Quality Foods, Kellogg Company, Kettle Brand, Cape Cod Potato Chips, Great Lakes Potato Chip CCo. and Wise Foods.
The competitive landscape of the North American potato chips market is marked by intense rivalry among a mix of global giants, regional leaders, and emerging niche players. Established companies such as PepsiCo, Kellogg’s, and Utz Brands dominate due to their extensive distribution networks, strong brand equity, and continuous product innovation. These firms leverage economies of scale to maintain pricing power while investing in marketing campaigns that reinforce consumer loyalty. At the same time, independent and specialty brands are gaining traction by focusing on organic, non-GMO, and locally sourced ingredients that appeal to health-conscious and environmentally aware consumers. The market also sees frequent introductions of limited-time flavors and co-branded promotions aimed at capturing attention in a highly saturated space. Retailers are further intensifying competition by developing private-label chip lines that offer cost-effective alternatives to national brands. This dynamic environment encourages constant evolution, pushing all players to innovate rapidly, enhance sustainability efforts, and expand digital engagement to retain and grow their market presence.
RECENT HAPPENINGS IN THE MARKET
- In January 2025, PepsiCo launched a new line of plant-based seasonings for its Lay’s brand, targeting vegan consumers and aligning with broader wellness trends, aiming to expand its reach within the health-focused snack segment.
- In May 2025, Kellogg Company announced a strategic partnership with a leading U.S. grocery delivery platform to enhance the availability of Pringles through same-day delivery services, strengthening its presence in the fast-growing online snack market.
- In August 2025, Utz Brands acquired a small-batch kettle chip manufacturer based in Oregon, reinforcing its foothold in the premium and artisanal snack category while diversifying its regional flavor offerings.
- In October 2025, Frito-Lay introduced eco-friendly compostable packaging for select snack chip varieties sold in natural food stores, responding to increasing consumer demand for sustainable packaging solutions across North America.
- In February 2026, a rising independent chip brand collaborated with a popular streaming service to release themed packaging featuring characters from an original series, leveraging pop culture to boost brand visibility and attract Gen Z consumers.
DETAILED SEGMENTATION OF NORTH AMERICA POTATO CHIPS MARKET INCLUDED IN THIS REPORT
This research report on the North AmericaAmerican chips market has been segmented and sub-segmented based on product type, distribution channel & region.
By Product Type
- Plain/Salted Chips
- Flavored Chips (e.g., BBQ, Sour Cream & Onion, Cheese, Spicy, Ranch, etc.)
- Baked Chips
- Kettle-Cooked Chips
- Organic/Natural Chips
By Distribution Channel
- Supermarkets/Hypermarkets
- Convenience Stores
- Online Retail
- Specialty Stores
- Vending Machines
By Region
- US
- Canada
- Mexico
- Rest of North America