- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$134.55 BnMarket Estimate, 2026
$157.42 BnMarket Forecast, 2034
$552.79 BnCAGR, 2026–2034
17%Global Nuclear Robotics Market Size, Share & Growth Analysis (2026–2034)
The global nuclear robotics market was valued at USD 134.55 billion in 2025, reaching USD 157.42 billion in 2026, and is projected to expand to USD 552.79 billion by 2034, registering a compound annual growth rate (CAGR) of 17.0% during the forecast period from 2026 to 2034.
- Market Scope: Comprehensive global evaluation covering robotics components by type (hardware, software, services), application sectors (measurements, inspections, radiochemical handling, nuclear decommissioning, and others), and geographic regions (North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa).
- Primary Growth Drivers: Heightened emphasis on worker safety in hazardous radioactive zones, strict nuclear facility regulations, massive investments in nuclear decommissioning, post-accident emergency intervention demands, and advanced technological collaborations like the 'LongOps' project.
Key Market Segment Metrics
| Category | Leading Segment Focus | Growth Dynamic Highlights |
|---|---|---|
| By Type & Application | Robot Hardware & Services (Dominating deployments for radiation-resistant physical operations) | Nuclear Decommissioning and Inspections act as core application drivers minimizing human exposure. |
| By Region | North America & Europe (Leading regions due to aging infrastructure and decommissioning initiatives like Sellafield) | Asia-Pacific emerging strongly through ongoing investments in new nuclear reactors and plant automation. |
Major Market Players & Industry Landscape
Competitive Structure: A specialized high-tech market driven by global defense contractors, nuclear engineering leaders, and advanced robotics firms collaborating on specialized radiation-tolerant machinery.
Leading Companies: Framatome, Qualter Hall, RAIN Hub, Kurion (Veolia), Northrop Grumman, Forth Engineering, Cyberia, BAE Systems, KUKA AG, and Boston Dynamics.
 Download Free Sample Report
Global Nuclear Robotics Market Size
The Global Nuclear Robotics Market was worth USD 134.55 billion in 2025 and is anticipated to reach a valuation of USD 552.79 billion by 2034 from USD 157.42 billion in 2026, and it is predicted to register a CAGR of 17% From 2026 to 2034.

Nuclear robotics refers to the use of specialized remote-controlled or autonomous robots designed to operate safely inside hazardous, high-radiation environments associated with nuclear power plants, waste storage, and decommissioning sites. These robotic solutions include crawlers, drones, manipulators, and underwater vehicles equipped with radiation hardened sensors and actuators. The imperative for such technology is driven by the global aging nuclear infrastructure and stringent safety regulations. According to the World Nuclear Association, there are currently about 440 nuclear power reactors operating worldwide in 31 countries. Furthermore, as per the World Nuclear Industry Status Report, 218 nuclear power reactors have been permanently closed worldwide as of mid-2025, with the European Union accounting for 132 of these closed reactors. This operational reality ensures that nuclear robotics are not merely optional tools but critical assets for ensuring worker safety and regulatory compliance. The complexity of dismantling activated components and managing radioactive waste necessitates precise and durable robotic systems, forming the backbone of modern nuclear facility management and environmental protection strategies across the energy sector.
MARKET DRIVERS
Accelerating Decommissioning of Aging Nuclear Facilities
The accelerating pace of nuclear plant decommissioning is the main reason behind the expansion of the nuclear robotics market. These processes demand extensive remote handling capabilities to ensure worker safety. According to the International Energy Agency, around 200 commercial nuclear reactors are expected to be shut down by 2040. This surge in decommissioning activities directly translates to increased procurement of robust manipulators and mobile platforms that can operate in highly contaminated zones. As per sources, the remediation of legacy nuclear facilities involves millions of tons of materials and radioactive waste, necessitating the development of remote handling solutions to minimize personnel exposure. Additionally, as per studies, nuclear phase-out policies adopted by several European nations continue to influence long-term planning for nuclear plant dismantling and decommissioning technology requirements. The complexity of these tasks, which often involve working in confined spaces with high radiation levels, makes manual intervention impractical and dangerous. Consequently, utility companies and government agencies are investing heavily in advanced robotics to manage these large scale projects. This structural shift toward decommissioning ensures a sustained and growing demand for nuclear robotics, positioning them as essential tools for the safe and effective closure of nuclear facilities.
Strict Regulatory Mandates for Worker Safety and Radiation Protection
Stringent regulatory frameworks governing radiation exposure and worker safety significantly propel the growth of the nuclear robotics market. These systems eliminate the need for human entry into hazardous zones. According to research, occupational ionizing radiation exposure is strictly limited to legal whole-body dose caps, encouraging operational facilities to employ remote handling tools during high-risk maintenance. As per sources, occupational exposure must follow the ALARA (As Low As Reasonably Achievable) principle, which supports using technical intervention methods to minimize direct human presence in radiation areas. According to studies, stringent oversight protocols govern nuclear facility operations to prevent accidental radiation exposure and eliminate human errors during safety-critical tasks. Furthermore, as per reports, international safety guidelines prioritize reducing occupational exposure to ionizing radiation through protective barriers and standard operating procedures. These regulatory pressures compel nuclear operators to integrate robotic solutions into their standard operating procedures, from routine inspections to complex repair tasks. The legal and ethical imperative to protect human health drives continuous investment in safer and more capable robotic technologies. As regulations become increasingly stringent, the reliance on nuclear robotics becomes indispensable. This shift ensures market growth through mandatory compliance and enhanced operational safety standards.
MARKET RESTRAINTS
High Initial Investment and Development Costs
The substantial financial burden associated with the development and acquisition of nuclear grade robotics is hindering the global market expansion. This constraint particularly affects smaller operators and developing nations. According to the National Aeronautics and Space Administration, designing electronics for extreme radiation environments requires specialized component selection and engineering processes that historically increase component unit costs and lead times compared to standard commercial off-the-shelf hardware. This high entry barrier discourages widespread adoption, as many nuclear facilities operate under tight budget constraints and must justify every capital expenditure. As per sources, the long-term lifecycle cost of maintaining and replacing specialized remote handling equipment in high-radiation environments is substantial, posing budgeting challenges for operational facilities. Additionally, the custom nature of many nuclear robotics solutions means that economies of scale are difficult to achieve, keeping unit prices high. According to studies, a historical reliance on bespoke, custom-built robotic systems for extreme environments often prevents components from being seamlessly swapped between different facilities, inflating project deployment costs. These financial constraints lead some operators to delay upgrades or rely on older, less efficient methods, limiting market growth. The economic pressure forces decision makers to carefully evaluate the return on investment, often prioritizing other critical infrastructure needs. This cost barrier hampers the rapid dissemination of advanced robotic technologies, restricting market penetration in key segments.
Technical Limitations in Extreme Radiation Environments
The harsh technical challenges posed by high radiation environments are also a major barrier to the performance and longevity of nuclear robotics in the global market. This limits their operational effectiveness. According to research, intense gamma and neutron radiation causes rapid lattice and chemical degradation of standard electronic semiconductors, leading to single-event disruptions and reduced system lifetimes. This vulnerability necessitates frequent replacements and repairs, increasing operational downtime and maintenance costs. As per reports, mitigating radiation-induced damage to sensors often requires heavy environmental shielding, which significantly increases system footprint and complicates deployment in confined spaces. Moreover, according to sources, high-density structural barriers and radioactive environments introduce significant electromagnetic and signal attenuation challenges for the reliable control of teleoperated systems. These technical limitations restrict the types of tasks that robots can perform reliably, often requiring human intervention for complex maneuvers. The need for constant innovation to improve radiation hardness slows down product development cycles and increases research expenditures. As a result, some potential applications remain unaddressed due to technological gaps. This technical hurdle thus limits the versatility of current nuclear robotics, slowing the overall adoption rate and restraining market dynamism until more robust solutions are developed.
MARKET OPPORTUNITIES
Integration of Artificial Intelligence and Autonomous Navigation
The integration of artificial intelligence and autonomous navigation technologies offers a lucrative opportunity for the expansion of the nuclear robotics market. This enhances their overall efficiency and capability. Modern facilities are increasingly adopting machine learning algorithms that enable robots to map unknown environments, identify anomalies, and make real time decisions without constant human input. According to research, artificial intelligence systems can reduce material defect inspection times by up to 40% compared to traditional methods. This technological evolution allows for continuous monitoring of hard-to-reach areas, minimizing downtime and improving safety margins. Furthermore, the ability to process vast amounts of sensor data locally facilitates predictive maintenance, preventing unexpected equipment failures. The International Atomic Energy Agency emphasizes that digital twins and AI driven simulations can enhance training and mission planning for robotic deployments. As nuclear facilities prioritize smart infrastructure, the demand for intelligent robotic platforms grows. Manufacturers who invest in developing AI enabled nuclear robots can differentiate their offerings and capture premium market segments. The convergence of robotics and artificial intelligence creates new revenue streams and strengthens the competitive position of innovators in the market.
Expansion into Nuclear Waste Management and Repository Monitoring
The growing focus on long-term nuclear waste management and repository monitoring is a key growth area for the nuclear robotics market. This development is accelerating as governments seek safe and sustainable disposal solutions. According to the International Atomic Energy Agency, the global inventory of stored spent nuclear fuel has exceeded 300,000 tonnes of heavy metal and continues to rise by approximately 7,000 tonnes annually. This transition drives demand for heavy duty manipulators and autonomous vehicles capable of operating in underground facilities for extended periods. As per the U.S. Government Accountability Office, the Department of Energy's Office of Environmental Management allocates billions of dollars annually to address complex environmental liabilities and deferred maintenance at federal nuclear waste cleanup sites. Additionally, the need for long-term monitoring of sealed repositories requires durable robots that can inspect containment integrity over decades. According to sources, implementing advanced automation techniques for waste characterization and segregation is critical to minimizing the final volume of high-level radioactive waste requiring permanent storage. Manufacturers can capitalize on this trend by designing specialized robots for waste processing plants and storage sites. The regulatory push for transparent and safe waste management ensures sustained demand. By focusing on durability and precision, companies can tap into this expanding market segment. These organizations can then offer critical tools for the final stages of the nuclear fuel cycle.
MARKET CHALLENGES
Complexity of Customization for Diverse Nuclear Facilities
The customization of robotic systems to meet the unique specifications of diverse nuclear facilities is a profound engineering challenge to the nuclear robotics market. Consequently, this bespoke approach severely constrains both market scalability and capital efficiency. Each nuclear plant has unique layouts, radiation profiles, and operational requirements, making it difficult to develop standardized robotic solutions. According to studies, structural variations across different reactor generations and plant architectures require custom tooling configurations for specific maintenance and decommissioning projects. This customization burden limits the ability to achieve economies of scale, keeping prices high and delivery times long. As per research, a lack of hardware-agnostic control frameworks across proprietary remote handling systems complicates their integration with legacy plant infrastructures. Consequently, healthcare facilities face increased pressure to manage multiple proprietary systems, raising training and maintenance costs. The complexity of integrating new robots into legacy systems also poses technical risks, potentially leading to project delays. Failure to address these integration challenges can result in operational inefficiencies and reduced return on investment. Manufacturers must therefore invest heavily in modular designs and flexible software architectures to address these concerns. Despite these efforts, the challenge of achieving universal compatibility remains a critical issue that influences purchasing decisions and limits the broader adoption of advanced nuclear robotics.
Shortage of Specialized Engineering Talent
The global shortage of engineers skilled in both robotics and nuclear science is a significant impediment to the innovation and deployment of nuclear robotics in the global market. Developing and maintaining these complex systems requires a rare combination of expertise in mechanical engineering, electronics, and radiation physics. According to the International Atomic Energy Agency, the nuclear industry faces an aging workforce, with a significant portion of experienced professionals nearing retirement, creating a knowledge gap in specialized fields. This staffing deficit means that fewer personnel are available to design, program, and troubleshoot advanced robotic systems, slowing down project timelines. As per research, establishing interdisciplinary educational tracks that combine nuclear science with advanced remote automation engineering remains a vital prerequisite to addressing the sector's specialized talent demands. Consequently, companies face higher recruitment costs and longer training periods for new hires. This lack of expertise hinders the adoption of sophisticated technologies that require specialized knowledge for optimal operation. Nuclear facilities may delay automation initiatives due to insufficient technical support, limiting market growth for advanced products. Additionally, high turnover rates in the tech sector further exacerbate the retention challenge. This human resource constraint restricts the full potential of nuclear robotics, as their success depends heavily on skilled development and operation. Addressing this issue requires significant investment in education and training programs, which many organizations struggle to implement effectively.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Type, Application, and Region. |
| Various Analyses Covered | Global, Regional, and Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Framatome, Qualter Hall, RAIN Hub, Kurion (Veolia), Northrop Grumman, Forth Engineering, Cyberia, BAE Systems, KUKA AG, Boston Dynamics, and Others. |
SEGMENTAL ANALYSIS
By Type Insights
In 2025, the robot hardware segment held the majority share in the nuclear robotics market, because physical manipulation and mobility are prerequisites for performing tasks in high radiation environments where human entry is prohibited. According to the International Energy Agency, almost 200 nuclear reactors out of the global fleet are due to retire by 2040. This massive wave of decommissioning activities directly drives the procurement of durable hardware capable of withstanding extreme conditions. As per studies, legacy waste infrastructure cleanup involves massive volumes of highly contaminated soils, structural debris, and hazardous remnants requiring remote mechanical extraction. These physical assets form the backbone of any nuclear robotics solution, as software alone cannot perform material handling or structural dismantling. The complexity of nuclear facilities necessitates specialized hardware designs that offer precision and strength, ensuring that hardware remains the largest revenue generating segment. Furthermore, the replacement cycle for radiation-damaged components ensures recurring demand for new hardware units. As nuclear operators prioritize safety and efficiency, the investment in advanced mechanical platforms continues to outpace other segments, solidifying the dominance of robot hardware in the market.
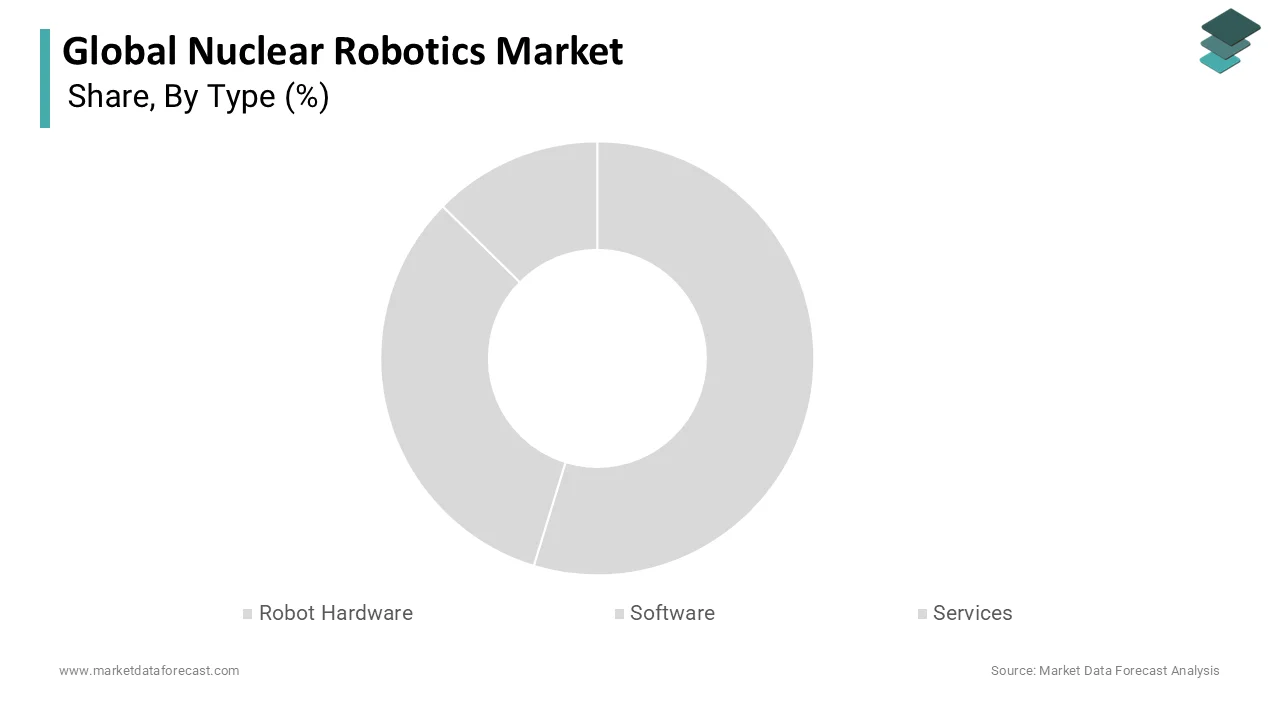
The substantial capital expenditure associated with acquiring radiation hardened robotic hardware contributes significantly to its leading position in the market. According to sources, constructing remote handling mechanisms that survive high neutron and gamma flux requires specialized shielding configurations and custom material selections that elevate design complexity compared to consumer automation systems Nuclear facilities are willing to bear these high costs because the alternative involves significant health risks to human workers and potential regulatory violations. As per studies, highly specialized custom manipulator arms built for severe core environments incur significant design, validation, and manufacturing costs due to extreme reliability and decontamination metrics. Additionally, the custom nature of many nuclear projects means that off-the-shelf solutions are often insufficient, driving demand for bespoke hardware configurations. This customization further increases the value of each transaction, boosting the overall segment revenue. The long lifespan of these hardware units also means that they represent major infrastructure investments for nuclear operators. As safety standards tighten globally, the willingness to invest in premium hardware grows, ensuring that this segment maintains its leadership through high-value transactions and continuous technological upgrades.
The software segment is on the rise and is expected to be the fastest growing segment in the market by witnessing a CAGR of 9.5% between 2026 and 2034. This rapid expansion is propelled by the increasing integration of artificial intelligence and autonomous navigation capabilities in nuclear robotics. According to research, integrating artificial intelligence tools into material scanning helps optimize processing steps and reduce the analysis timeline. This technological shift allows robots to operate with minimal human supervision, reducing labor costs and exposure risks. As per sources, 3D kinematic modeling and simulated environments are increasingly utilized to map workspaces and validate execution sequences prior to live system entry. These software solutions enhance mission success rates and prevent costly errors. Furthermore, the ability to process vast amounts of sensor data in real time facilitates predictive maintenance, preventing unexpected equipment failures. As nuclear facilities adopt smart infrastructure initiatives, the demand for sophisticated control algorithms and data analytics platforms surges. Manufacturers are increasingly bundling advanced software packages with hardware sales, creating new revenue streams. The scalability of software solutions also allows for easier updates and improvements, driving rapid adoption across the industry. This digital transformation ensures that the software segment will continue to grow at an accelerated pace.
The growing need for enhanced situational awareness and remote monitoring capabilities is fuelling the growth of this segment. According to sources, uninterrupted visual data mapping and real-time sensory transmission are fundamental to maintaining situational oversight inside confined containment zones. Modern software platforms provide operators with immersive 3D maps and live video feeds, allowing for precise control of robots in confined and hazardous spaces. As per studies, optimizing control protocol bandwidth and reducing transmission latency remain crucial milestones for safely managing high-consequence robotic tasks over remote communication channels. Additionally, cybersecurity software has become a priority, as connected robotic systems are vulnerable to cyber threats. According to research, applying comprehensive network security baselines across vital energy operating software is a standard prerequisite to defending critical facilities against digital exploits. This regulatory pressure ensures consistent demand for software updates and security patches. The integration of cloud-based platforms also enables collaborative monitoring and data sharing among multiple stakeholders. As remote operations become more prevalent, the reliance on robust software infrastructure intensifies, driving rapid growth in this segment.
By Application Insights
The nuclear decommissioning segment was the largest in 2025 and occupied a commanding share of the global market. This segment’s prominence was credited to the unprecedented number of aging reactors reaching the end of their operational lives worldwide. According to the World Nuclear Association, more than 210 commercial nuclear power reactors have been permanently shut down globally, with the fleet transitioning through various stages of decommissioning. This large scale cleanup effort requires specialized robots for cutting concrete, removing fuel rods, and sorting radioactive waste, tasks that are too dangerous for humans. As per studies, facility decommissioning is a complex process spanning multiple decades, resulting in prolonged baseline usage requirements for specialized remote tool installations. The complexity of these projects necessitates a wide array of robotic tools, from small inspection drones to large demolition machines. Governments in Europe and North America are allocating billions of dollars to fund these cleanup efforts, providing a stable financial base for the market. The regulatory requirement to restore sites to greenfield status further drives the adoption of efficient robotic solutions. As the global fleet of nuclear plants ages, the volume of decommissioning work will continue to increase, solidifying this segment's dominance.
Strict regulatory mandates for safe waste management and site restoration are bolstering the market share of this segment. According to sources, nuclear facilities are bound to rigorous effluent release limits and solid waste conditioning criteria to prevent the unintended structural migration of hazardous isotopes. These regulations often require detailed documentation and monitoring, which modern robotic systems can provide through integrated sensors and data logging. As per studies, minimizing collective dose rates to maintenance personnel during the dismantling of active cores requires shifting complex high-exposure operations to remote handling mechanisms. Consequently, utility companies prioritize robotic solutions that offer high precision and reliability to meet compliance requirements. According to reports, failing to meet strict decommissioning milestone protocols exposes utility operators to significant regulatory enforcement actions and remediation liabilities. This regulatory environment creates a non-negotiable demand for advanced decommissioning technologies. As standards become more stringent globally, the reliance on robotic assistance for compliant waste handling and site clearance intensifies, ensuring the continued leadership of this application segment.
The inspections segment is likely to experience a CAGR of 8.7% over the forecast period due to the industry's shift toward preventive maintenance and life extension programs for existing nuclear plants. According to the U.S. Nuclear Regulatory Commission, extending the original operational license of a commercial reactor by an additional 20 years requires comprehensive structural safety reviews to verify that critical components preserve adequate margins. Robotic inspection tools allow for detailed internal assessments without shutting down the plant, maximizing uptime and revenue. As per sources, deploying non-destructive sensor arrays to locate microscopic stress cracks and metallurgical wear early is key to ensuring long-term facility operability. This proactive approach reduces the need for costly emergency repairs and unplanned outages. Furthermore, advancements in non-destructive testing technologies, such as ultrasonic and eddy current sensors, have enhanced the accuracy of robotic inspections. Plant operators are increasingly adopting these technologies to meet regulatory requirements for asset integrity management. The economic benefit of avoiding unplanned downtime drives rapid adoption of inspection robots. As the global nuclear fleet ages, the frequency and scope of inspections will increase, fueling strong growth in this segment.
Technological advancements in sensor technology and robot miniaturization are accelerating the growth of this segment. According to studies, modern sub-centimeter scanning modules configured with specialized optoelectronic sensors can successfully negotiate narrow geometric pipe networks to log minor internal substrate anomalies. This capability allows for more comprehensive inspections and better decision-making regarding maintenance schedules. As per sources, advancements in high-frequency telemetric control frameworks permit uninterrupted data acquisition, reducing structural analysis turnaround cycles during field diagnostics. These innovations make robotic inspections faster, cheaper, and more effective than traditional manual methods. Additionally, the development of swarm robotics allows for simultaneous inspection of multiple areas, further enhancing efficiency. Nuclear operators are keen to adopt these advanced tools to improve safety and operational reliability. The ability to conduct thorough inspections without exposing workers to radiation is a key driver for adoption. As sensor technology continues to evolve, the capabilities of inspection robots will expand, driving further growth in this dynamic segment.
COUNTRY LEVEL ANALYSIS
North America Nuclear Robotics Market Analysis
North America emerged as the dominant region in the nuclear robotics market and secured a substantial share in 2025. This region's dominance was driven by its large inventory of aging nuclear power plants and robust regulatory framework. According to the Nuclear Regulatory Commission, the United States operates 94 commercial nuclear reactors across 28 states. As per sources, legacy waste complexes require robust deployment programs to manage heavy environmental site cleanup and high-volume hazardous material sorting. The presence of leading technology providers and research institutions in the region fosters innovation and rapid adoption of new robotic solutions. Additionally, strict occupational safety standards enforced by the Occupational Safety and Health Administration compel facilities to minimize human exposure through automation. The growing interest in small modular reactors also creates new opportunities for specialized robotic systems designed for compact facilities. These factors combine to maintain North America as a key market for nuclear robotics, characterized by high technological sophistication and significant government investment.
Europe Nuclear Robotics Market Analysis
Europe was positioned second in the nuclear robotics market in 2025. This standing of the European market was supported by aggressive decommissioning agendas and stringent environmental regulations. According to the European Commission, member states maintain independent energy mix strategies, with Germany having finalized a complete phase-out of its domestic nuclear fleet while France actively pursues long-term nuclear energy capacity expansion. As per research, specialized programs fund technical evaluations of remote waste characterization systems to assist structural dismantling operations. According to sources, a significant portion of regional generation fleets consists of facilities originally constructed in early industrial generations, which presents distinct long-term structural decommissioning timelines. Additionally,ass per the European Commission's Nuclear Illustrative Programme, over €240 billion in investment is required by 2050 to support the construction of new large-scale reactors and the lifetime extension of existing plants. The presence of major nuclear operators and specialized robotics firms in countries like the United Kingdom and Sweden further strengthens the regional market. Regulatory harmonization across the EU facilitates the spread of best practices and standardized robotic solutions, supporting steady market growth.
Asia Pacific Nuclear Robotics Market Analysis
The Asia-Pacific region is quickly accelerating in the growth of the nuclear robotics market, fueled by new reactor construction and an increasing focus on nuclear safety. According to the World Nuclear Association, the greatest expansion in global nuclear generation capacity is centered in Asia, driven primarily by China and India, which account for dozens of reactors currently under construction or planned. This expansion drives demand for robotic systems for installation, commissioning, and future maintenance. As per studies, regional facilities coordinate with international watchdogs to subscribe to benchmark safety codes that mandate minimizing collective radiation exposure to personnel. Japan, following the Fukushima incident, has invested heavily in robotic technologies for disaster response and decommissioning, setting a precedent for the region. Government initiatives to develop domestic robotics industries in countries like South Korea and China further boost market activity. The rising energy demand and commitment to low-carbon sources ensure long-term growth potential for nuclear robotics in Asia Pacific.
Latin America Nuclear Robotics Market Analysis
Latin America is at an early stage of development in the nuclear robotics market, primarily due to maintenance needs in existing facilities and local research initiatives. According to the World Nuclear Association, Brazil and Argentina operate the region’s few nuclear power plants, which require regular robotic inspections and maintenance to ensure safe operation. As per the Inter-American Development Bank Group's Energy Thematic Framework, the institution has lifted its long-standing ban on nuclear energy to pursue a phased approach focused primarily on client education, advisory services, and general grid infrastructure expansion. While large scale decommissioning is not yet a major driver, the region is beginning to plan for the eventual shutdown of older research reactors. Educational institutions and research centers are collaborating with international partners to develop local expertise in nuclear robotics. Economic constraints limit rapid adoption, but the emphasis on safety and regulatory compliance ensures steady demand for essential robotic tools. The potential for future nuclear expansion in countries like Mexico could further stimulate market growth in the coming years.
The Middle East and Africa Nuclear Robotics Market Analysis
The Middle East and Africa region is a rising player within the nuclear robotics market, owing to new nuclear power programs and international collaborations. According to the World Nuclear Association, the United Arab Emirates has successfully brought all four commercial nuclear units at the Barakah nuclear power plant online, generating zero-carbon baseload electricity for the nation. Other countries in the region are exploring nuclear energy options, driving initial investments in robotic infrastructure. As per research, centralized watchdogs routinely provide administrative training and peer-review support to member states to reinforce operational safety protocols. In Africa, research reactors in countries like South Africa and Egypt require robotic support for maintenance and waste management. Limited local manufacturing capabilities mean that the region relies heavily on imports from established global players. However, the strategic importance of nuclear energy for diversification and climate goals ensures continued interest in robotic solutions. As these programs mature, the demand for nuclear robotics is expected to grow steadily.
COMPETITIVE LANDSCAPE
The competition in the Nuclear Robotics Market is characterized by a mix of established industrial giants and specialized technology startups who compete on innovation and reliability. Leading companies differentiate themselves through proprietary radiation-hardened components and advanced autonomous navigation software that enhance operational safety and efficiency. The market sees intense rivalry in the development of versatile platforms capable of performing multiple tasks such as inspection, maintenance, and decommissioning. Price competition is secondary to performance and compliance, as nuclear operators prioritize proven safety records and regulatory adherence. Emerging players from Asia Pacific regions are gaining traction by offering cost-effective solutions with rapid customization capabilities. Strategic collaborations with national laboratories and universities help key players validate new technologies and accelerate commercialization. Intellectual property protection is crucial, with firms securing patents for novel mechanical designs and control algorithms. The competitive landscape is further shaped by high barriers to entry due to stringent certification requirements and long sales cycles. Continuous investment in customer support and lifecycle management serves as a key differentiator, ensuring long-term relationships with utility providers and government agencies involved in nuclear energy.
KEY MARKET PLAYERS
Some of the companies that are playing a dominating role in the Global Nuclear Robotics Market include:
- Framatome
- Qualter Hall
- RAIN Hub
- Kurion (Veolia)
- Northrop Grumman
- Forth Engineering
- Cyberia
- BAE Systems
- KUKA AG
- Boston Dynamics
TOP LEADING PLAYERS IN THE MARKET
- Boston Dynamics has established itself as a pioneer in advanced mobility solutions for hazardous environments through its Spot robot platform. The company actively collaborates with nuclear facilities to deploy quadrupedal robots for autonomous inspection tasks in high radiation zones. Recent initiatives include integrating specialized radiation sensors and thermal cameras to enhance data collection capabilities during routine plant walkthroughs. Boston Dynamics focuses on software updates that enable seamless integration with existing facility management systems, improving operational efficiency. The company partners with major energy providers to test durability and reliability in real-world scenarios, ensuring robust performance under extreme conditions. By prioritizing agility and ease of deployment, Boston Dynamics strengthens its position as a leader in mobile inspection robotics. Their continuous innovation in legged locomotion allows access to complex terrains within nuclear plants, reducing the need for human entry and enhancing overall safety protocols for industrial operators globally.
- General Electric Company leverages its extensive experience in power generation to offer comprehensive robotic solutions for nuclear maintenance and decommissioning. The company develops specialized manipulators and underwater vehicles designed for precise intervention in reactor cores and spent fuel pools. Recent actions include the launch of digital twin technologies that simulate robotic operations before physical deployment, minimizing risks and optimizing task execution. General Electric collaborates with regulatory bodies to ensure compliance with stringent safety standards, building trust among utility operators. The company invests heavily in research and development to create radiation-hardened components that withstand prolonged exposure. By combining hardware expertise with advanced analytics, General Electric provides end to end solutions that enhance plant reliability. Their focus on lifecycle support and training programs ensures successful adoption of robotic systems, reinforcing their reputation as a trusted partner in the nuclear energy sector.
- Veolia Group plays a critical role in the nuclear robotics market by providing integrated services for waste management and site remediation using remote operated machinery. The company designs custom robotic systems for handling radioactive waste and dismantling contaminated structures safely and efficiently. Recent strategies involve expanding its portfolio of autonomous vehicles equipped with advanced sorting and packaging capabilities for decommissioning projects. Veolia Group partners with government agencies to manage legacy nuclear sites, leveraging its global expertise in environmental services. The company emphasizes sustainability by developing robots that minimize waste volume and maximize recycling opportunities. Through strategic acquisitions of specialized technology firms, Veolia Group enhances its technical capabilities and market reach. Their commitment to innovation and safety ensures they remain at the forefront of nuclear cleanup efforts, delivering reliable solutions that meet the evolving needs of the industry.
TOP MAJOR STRATEGIES USED BY KEY PLAYERS
Key players in the Nuclear Robotics Market employ diverse strategies to maintain competitiveness and drive innovation in this specialized sector. Product differentiation through advanced radiation hardening and autonomous capabilities remains a primary focus, allowing companies to offer superior performance in hazardous environments. Strategic partnerships with nuclear operators and research institutions facilitate collaborative development and real-world testing of new technologies. Companies invest heavily in research and development to create modular and scalable robotic platforms that can be customized for specific applications. Expansion into emerging markets with growing nuclear infrastructure provides new growth opportunities and diversifies revenue streams. Additionally, firms prioritize cybersecurity measures to protect connected robotic systems from potential threats, ensuring operational integrity. Training and support services are enhanced to help clients integrate robotics seamlessly into their workflows. These multifaceted approaches enable key participants to address complex challenges and capture value in the evolving nuclear robotics landscape.
GLOBAL NUCLEAR ROBOTICS MARKET
- Researchers from the U.K. and Japan have collaborated to create new, safer techniques for deconstructing existing nuclear power stations such as the Fukushima Daiichi reactors. A long-reach robotic system utilized in this scientific cooperation named 'LongOps' would reduce hazards to public health while also speeding up the dismantling of outdated facilities. Besides Fukushima, such robots will be installed at Sellafield in Cumbria, northwest England, where nuclear material is processed and stockpiled.
- The IAEA has chosen the five top crowdsourcing competition submissions, seeking novel concepts or project outlines for furthering nuclear facility dismantling or environmental clean-up of highly radioactive polluted locations. Three of them concentrated on deactivation and two on ecological clean-up, with tools ranging from characterization tools to field tests and 3D radiation research instruments to automation and artificial intelligence.
MARKET SEGMENTATION
This research report on the Global Nuclear Robotics Market has been segmented and sub-segmented into the following categories.
By Type
- Robot Hardware
- Software
- Services
By Application
- Measurements
- Inspections
- Radiochemical Handling
- Nuclear Decommissioning
- Other
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa