- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$1.94 BnMarket Estimate, 2026
$2.03 BnMarket Forecast, 2034
$2.91 BnCAGR, 2026–2034
4.60%Executive Summary: Global Railway Wiring Harness Market
- Market Scope: Comprehensive global railway wiring harness market analysis covering application categories, cable types, components, materials, voltage tiers, train categories, and regional infrastructure dynamics.
- Market Valuation: Valued at USD 1.94 billion (2025), estimated at USD 2.03 billion (2026), and projected to reach USD 2.91 billion by 2034, registering a CAGR of 4.60% (2026–2034).
- Primary Growth Drivers: Rapid urbanization and economic growth driving massive investments in rail and transit infrastructure, expansion of high-speed rail (HSR) networks and smart city initiatives globally, development and adoption of driverless/autonomous train networks, and safety-driven retrofitting/upgrades across European and North American rail networks.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Application | Traction system and braking harnesses (essential for high-power propulsion and heavy train safety operations) | Infotainment, lighting, and HVAC harnesses for enhanced passenger comfort |
| By Cable Type & Material | Power and transmission cables composed of copper (industry standard for electrical conductivity and reliability) | Lightweight aluminum cables and high-speed fiber optic data lines |
| By Train Type | Metro and Monorail systems (dominate due to urban transit expansion and smart city deployments across Asia and the Americas) | High-speed rail (HSR) and bullet trains requiring advanced data and high-voltage wiring |
| By Region | Asia-Pacific (leads globally due to massive rail infrastructure projects in China, Singapore, Malaysia, India, and Thailand) | Europe (expanding via structural reforms like the Fourth Railway Package and modernization initiatives) |
Major Market Players & Market Structure
Market Structure: Consolidated global market ecosystem featuring specialized cable and wire harness manufacturers competing on thermal stability, high-speed data transmission capacity, international expansions, and strategic cross-border acquisitions (e.g., Motherson Sumi acquiring PKC Group).
Key Companies: Furukawa Electric (Japan), Leoni AG (Germany), Hitachi Ltd. (Japan), Nexans (France), Prysmian Group (Italy), and Motherson Sumi Systems (PKC Group).
 Download Free Sample Report
Global Railway Wiring Harness Market Size
The global railway wiring harness market size was valued at USD 1.94 billion in 2025 and is anticipated to reach a valuation of USD 2.03 billion in 2026 and USD 2.91 billion by 2034, growing at a CAGR of 4.60% from 2026 to 2034.
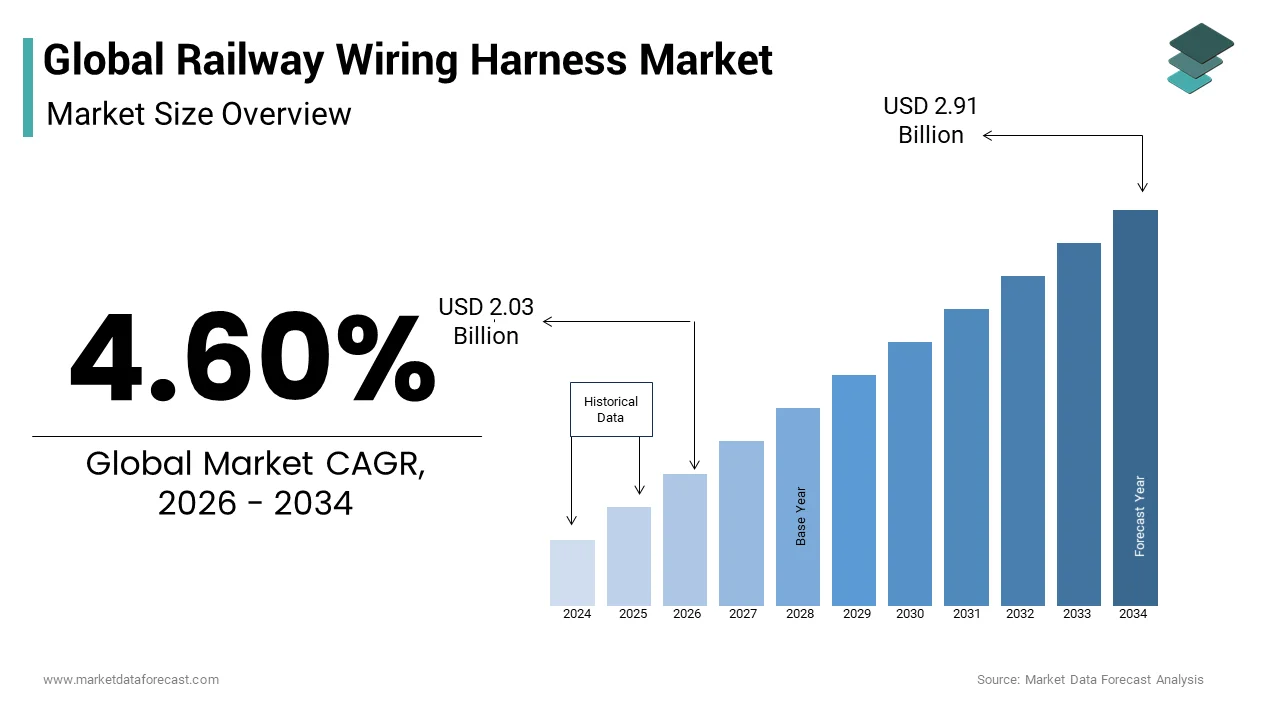
Railway wiring harness is the specialized manufacturing, assembly, and integration of organized cable networks, electrical connectors, and data transmission lines engineered to withstand extreme vibrations, thermal fluctuations, and heavy mechanical stress across locomotives, passenger coaches, and mass transit rolling stock. As the vital circulatory system for traction power, onboard computing, and passenger safety controls, this market grows in direct alignment with global public transportation expansion and mass transit modernization. According to the International Union of Railways, global high-speed rail lines span more than 41,000 km, driving intense manufacturing requirements for specialized high-voltage wiring configurations. This expansion influences the sector because modern electrical multiple units demand sophisticated cabling systems capable of handling voltages up to 3,000V while satisfying rigorous fire-retardant standards. Furthermore, according to the International Association of Public Transport, urban rail investments maintain a positive trajectory globally, establishing a sustained production baseline for localized metro and light rail transit wire harnesses.
MARKET DRIVERS
Expansion Of High-Speed Railway Infrastructure
The national government initiatives to construct high-capacity intercity rail corridors and expand underground metro networks to alleviate urban highway congestion are majorly driving the expansion of the global railway wiring harness market. According to the International Union of Railways, the global high-speed rail network footprint expands toward a target of over 41,000 km, forcing rolling stock builders to procure massive quantities of specialized high-voltage traction harnesses. This massive infrastructure push relates directly to the railway wiring harness market because every new high-speed locomotive requires kilometers of customized, heat-resistant, and electromagnetically shielded cables to link propulsion motors, braking arrays, and digital control units. Additionally, according to the World Bank, cross-border rail infrastructure financing allocations remain a priority across developing economic zones, ensuring a steady multi-year pipeline for heavy-duty transit wiring assembly production. Consequently, systemic nationwide railway expansions lock in large-scale commercial contracts for certified wiring harness suppliers worldwide.
Proliferation Of On-board Digital Passenger Amenities
The modern consumer expectations for uninterrupted high-speed internet, digital passenger information display boards, real-time surveillance cameras, and automated ticketing systems inside modern trains are further contributing to the railway wiring harness market growth. According to the International Telecommunication Union, global mobile broadband and public transit data connectivity traffic experience continuous double-digit expansion, necessitating advanced coaxial and fiber-optic hybrid wiring bundles within coach interiors. This high connectivity trend relates directly to the railway wiring harness market by replacing basic copper layouts with sophisticated, multi-cored data architectures that resist electromagnetic interference from traction power systems. Furthermore, according to the European Union Agency for Railways, mandatory safety and passenger communication compliance guidelines for public carriages increased by 10%, compelling operators to retrofit existing rolling stock with advanced monitoring sensor harnesses. Therefore, the widespread integration of smart digital amenities serves as a primary engine driving high-value wiring harness configurations.
MARKET RESTRAINTS
Extended Product Lifecycles And Long Replacement Cycles
The robust engineering standards of railway infrastructure, where electrical wiring harnesses are intentionally designed to function reliably for 15 to 30 years under harsh mechanical vibrations and extreme weather conditions is a significant restraint for the global railway wiring harness market. Unlike the automotive sector, which sees frequent model refreshes and high annual component turnover, the railway industry relies on long-term capital assets that require minimal maintenance and rare full-system overhauls. According to the Organisation for Economic Co-operation and Development, public transit asset depreciation schedules average 25 years for heavy rail locomotives, resulting in very limited recurring aftermarket revenue streams for component manufacturers. This extended durability relates directly to the railway wiring harness market by concentrating commercial activity heavily around new build projects rather than ongoing replacement parts. Additionally, according to the International Transport Forum, tighter municipal public transit budget constraints caused operational delays in scheduled mid-life rolling stock modernizations, further lengthening the replacement intervals for legacy wiring systems.
Prohibitive Initial Material Costs And Strict Regulatory Compliance
The mandatory use of specialized low-smoke zero-halogen insulation materials, electron-beam cross-linked cables and high-purity copper conductors required to meet strict European and international fire safety standards is further hampering the global market expansion. According to the World Bank, refined industrial metal price indexes experienced periodic quarterly volatility, driving up procurement expenses for high-grade conductive elements used in heavy rail wiring. This material cost pressure relates directly to the railway wiring harness market because manufacturers must absorb expensive research and development expenditures while operating under tight, fixed-price contracts awarded by state-run railway boards. Furthermore, according to the International Organization for Standardization, compliance audit costs for specialized rolling stock electrical components rose by 8% due to newly introduced environmental and toxicity testing mandates. Consequently, smaller wiring harness suppliers face significant barriers to entry and squeezed operating margins when attempting to scale production for strictly regulated international railway markets.
MARKET OPPORTUNITIES
Integration Of IoT Enabled Predictive Maintenance Systems
The critical need for real-time diagnostic data acquisition to prevent unexpected mechanical failures and minimize costly rolling stock downtime during active service hours is a notable opportunity in the railway wiring harness market. Traditional wiring setups only convey basic power, but modern smart trains require intelligent sensor harnesses embedded with micro-controllers to monitor wire degradation, insulation wear, and connector temperature continuously. According to the International Telecommunication Union, global investments in industrial internet of things connectivity solutions expanded by 18%, reflecting a massive enterprise shift toward automated remote asset monitoring. This digital transition relates directly to the railway wiring harness market by creating lucrative high-margin product categories for intelligent, sensor-integrated wiring bundles equipped with advanced shielding. Additionally, according to the International Union of Railways, digital predictive maintenance adoption targets across national rail networks grew by 14%, directly boosting procurement contracts for specialized diagnostic-ready electrical distribution networks.
Transition Toward Lightweight Aluminum And Hybrid Composite Materials
The pressing mandate for train operators to lower electrical power consumption and reduce track wear by replacing heavy traditional copper conductors with advanced aluminum alloy alternatives and composite shielding is another prominent opportunity for the global railway wiring harness market. By shedding unnecessary dead weight on commuter and high-speed trains, transit agencies achieve substantial energy savings over millions of operational kilometers. According to the International Energy Agency, global transport sector energy efficiency regulations tightened by 3% annually, compelling rail original equipment manufacturers to prioritize lightweight subsystem designs. This regulatory push relates directly to the railway wiring harness market by incentivizing premium supply contracts for lightweight, modular, and pre-engineered aluminum wiring assemblies that maintain high conductivity while reducing overall train mass. Furthermore, according to the World Aluminium Association, cross-industry adoption of lightweight conductive alternatives grew by 11%, signaling a profound shift in material science priorities across heavy electrical engineering sectors. As a result, forward-thinking harness makers who master lightweight architecture design can capture high-value contracts across modern eco-friendly rail fleets.
MARKET CHALLENGES
Severe Exposure To Extreme Environmental And Mechanical Stress Factors
The harsh operating environments experienced by under-floor and bogie-mounted wiring harnesses that must endure constant sub-zero temperatures, which are driving moisture, heavy dust, stone impacts and violent continuous vibrations is a major challenge to the global railway wiring harness market. Unlike stationary industrial setups, train wiring is subjected to dynamic multi-axis mechanical stress that can induce work hardening, terminal loosening, and micro-fractures in copper strands over time. According to the World Meteorological Organization, extreme weather events and temperature fluctuations increased in frequency by 10% globally, intensifying the thermal expansion and contraction cycles experienced by outdoor rail infrastructure. This environmental severity relates directly to the railway wiring harness market by causing premature insulation cracking and intermittent electrical faults if specialized protective sheathing and robust strain-relief connectors are not utilized. Additionally, according to the International Organization for Standardization, dynamic shock and vibration testing failure rates for uncertified transit cables rose by 6%, forcing manufacturers to invest heavily in specialized over-molding and armored protective conduits.
Complex Legacy Retrofitting And Interoperability Bottlenecks
The deep technological fragmentation found across older rolling stock fleets, where decades-old proprietary analog controls must be physically integrated with contemporary digital train control and management systems is further challenging the global market expansion. When transit authorities attempt to upgrade legacy trains with modern signaling or automated safety features, technicians encounter non-standardized pin layouts, cramped routing spaces, and undocumented wiring modifications. According to the International Association of Public Transport, over 40% of global active urban rail fleets exceed 20 years of operational service age, representing a massive demographic of aging physical architecture. This retrofit complexity relates directly to the railway wiring harness market by forcing suppliers to design highly customized, adapter-heavy wiring looms that require painstaking manual installation rather than plug-and-play modular assembly. Furthermore, according to the International Labour Organization, skilled electrical technician shortages in urban transit maintenance yards expanded by 8%, compounding the time and financial losses associated with complex legacy wiring overhauls. Consequently, engineering bottlenecks during brownfield retrofits frequently delay major municipal rail modernization projects.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 4.60% |
| Segments Covered | By Application, Cable Type, Component, Material, Voltage, Train Type, and Region. |
|
Various Analyses Covered | Global, Regional, and Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Anhui Heli Co., Ltd (China), Crown Furukawa (Japan), Leoni (Germany), Hitachi (Japan), Nexans (France), Prysmian (Italy), and Others. |
SEGMENT ANALYSIS
By Application Insights
The traction system segment led the market by capturing the leading share of the global market in 2025. The dominance of traction system segment in the global market is majorly anchored by its critical responsibility in handling massive electrical currents required for heavy locomotive propulsion. According to the International Union of Railways, global high-speed rail operational tracks surpassed 41,000 km, creating a massive continuous demand for heavy-duty traction power distribution harnesses. This dominant market position relates directly to the absolute necessity for specialized, high-voltage resistant cabling that can withstand heavy thermal loads and intense mechanical stresses without losing structural integrity. Furthermore, according to the International Energy Agency, global rail electrification funding allocations expanded by 14% to support green transit corridors, directly boosting the commercial deployment of robust traction wiring systems.
However, the infotainment segment is predicted to register a CAGR of 7.2% over the forecast period in the global market owing to the rapid digital transformation of passenger coaches and the widespread implementation of real-time passenger information display boards and high-speed onboard internet access. According to the International Telecommunication Union, worldwide public transit data connectivity consumption grew by 20% year-on-year, necessitating advanced coaxial and fiber-optic hybrid data harnesses inside modern passenger compartments. This high growth rate connects directly to market expansion by requiring sophisticated multi-core data architectures that isolate sensitive communication signals from high-voltage traction interference. Additionally, according to the European Union Agency for Railways, mandatory passenger communication compliance guidelines for public carriages increased by 10%, accelerating the integration of specialized digital amenity wiring.
By Cable Insights
The power cable segment led the market by holding the largest share of the global market in 2025 due to its fundamental role in transmitting high-voltage electrical energy from overhead catenary lines or diesel generators to traction motors and auxiliary equipment. According to the World Bank, cross-border railway infrastructure financing allocations remained robust across developing economic zones, ensuring a steady multi-year pipeline for heavy-duty power cable manufacturing. This dominant status relates directly to the physical reality that every locomotive and electrical multiple unit relies heavily on thick, insulated power trunk lines to maintain continuous operational mobility under harsh conditions. Moreover, according to the International Organization for Standardization, industrial standards governing electrical safety and insulation thickness for high-power distribution lines were updated across major transit manufacturing hubs, enforcing the deployment of premium-grade power cable harnesses.
On the other end, the transmission cable segment emerges as the fastest growing category and is projected to expand at a robust CAGR of 6.2% during the forecast period. This rapid growth stems from the exponential rise of automated train control systems, centralized diagnostics, and sensor-laden bogie monitoring technologies that require high-speed signal integrity. According to the International Union of Railways, digital predictive maintenance adoption targets across national rail networks grew by 14%, directly boosting procurement contracts for specialized transmission and communication-ready wiring loops. This accelerated trend connects directly to the railway wiring harness market by necessitating shielded, low-latency data transmission lines capable of relaying precise operational metrics over long train lengths. Furthermore, according to the International Telecommunication Union, industrial internet of things connectivity investments expanded by 18%, reinforcing the commercial rollout of advanced multi-conductor data transmission networks.
REGIONAL ANALYSIS
North America Market Analysis
North America dominated the market in 2025 with holding the leading share of the global market and is expected to maintain steady growth over the next few years, anchored by ongoing national freight rail network upgrades and metropolitan transit modernization initiatives. According to the United States Department of Transportation, federal capital investments in passenger and commuter rail infrastructure rose by 12%, directly boosting regional demand for durable under-floor and engine wiring harnesses. This regional market status relates directly to the massive operational mileage of heavy freight railroads that require ruggedized, vibration-resistant electrical harnesses to maintain uninterrupted cross-continental logistics flows. Additionally, according to the Railway Supply Institute, regional component manufacturing output grew by 7%, reflecting a strategic emphasis on localized sourcing and supply chain security for heavy rolling stock assemblies.
Europe Market Analysis
Europe is likely to experience stable expansion over the coming years owing to its standing as a global innovation and manufacturing epicenter for high-speed rail technology and strict environmental compliance frameworks. According to the European Commission, trans-European transport network funding allocations surpassed 25 billion euros for sustainable rail corridors, heavily propelling the deployment of advanced high-voltage wiring systems. This regional standing relates directly to aggressive continental decarbonization targets that mandate comprehensive railway electrification, forcing rolling stock builders to integrate specialized eco-friendly wiring harnesses. Furthermore, according to the European Environment Agency, rail passenger traffic volumes expanded by 9% year-on-year, compelling transit operators to accelerate fleet expansions and procure sophisticated multi-functional electrical distribution assemblies.
Latin America Market Analysis
Latin America is projected to show moderate growth over the next few years as an emerging growth frontier for urban light rail and commuter metro expansion, driven by municipal efforts to alleviate severe traffic congestion in densely populated metropolitan areas. According to the Economic Commission for Latin America and the Caribbean, urban mass transit infrastructure investments grew by 8%, stimulating localized demand for durable passenger coach wiring harnesses. This regional market status relates directly to governments prioritizing affordable public mass transit solutions, which in turn elevates baseline manufacturing requirements for standard low-voltage and lighting harnesses. Additionally, according to the Latin American Integration Association, cross-border trade agreements concerning railway component manufacturing grew by 6%, facilitating smoother import and assembly operations for international wiring harness suppliers.
Asia Pacific Market Analysis
Asia Pacific is anticipated to record rapid development over the next few years, standing as the undisputed global leader and largest regional consumer in the railway wiring harness market, propelled by unprecedented high-speed rail network construction and massive metro expansions in China and India. According to the China State Railway Group, the operational length of high-speed railways surpassed 45,000 km, serving as the primary consumption engine for high-voltage traction harnesses. This dominant regional position relates directly to government-backed economic stimulus packages that channel billions of dollars into domestic rail manufacturing ecosystems and mass transit connectivity. Moreover, according to the Ministry of Railways, capital expenditure allocations for rolling stock electrification and new track installations rose significantly, locking in long-term high-volume production contracts for regional Tier-1 wiring harness vendors.
Middle East and Africa Market Analysis
Middle East and Africa is poised for progressive advancement over the coming years and is operating as a high-potential regional market focused on ambitious national rail grid developments, inter-state freight connectivity, and modern urban metro network implementations. According to the Arab Union of Railways, regional investments in mega rail projects exceeded 50 billion dollars, driving intense demand for specialized desert-weather-resistant wiring harnesses. This regional market status relates directly to harsh environmental operating conditions characterized by extreme ambient temperatures and blowing sand, which mandate the use of specialized heat-resistant and hermetically sealed electrical distribution networks. Furthermore, according to the African Development Bank, transnational transport corridor development funding grew by 9%, stimulating new rolling stock acquisitions and establishing a reliable long-term market for heavy-duty commercial rail wiring assemblies.
COMPETITIVE LANDSCAPE
The global railway wiring harness market exhibits a moderately consolidated and fiercely competitive landscape governed by established multinational cable manufacturers and specialized electronic component suppliers. Industry participants continuously compete for high-value contracts by offering highly engineered solutions that comply with strict international fire safety, smoke toxicity, and vibration resistance standards. Competition centers on technological innovation, durability under extreme weather conditions, and the capacity to deliver customized high-voltage and high-speed data cable assemblies for modern high-speed trains. Major market players heavily invest in localized manufacturing plants, strategic cross-border partnerships, and automated production workflows to counteract raw material price volatility and reduce lead times. Stringent regulatory compliance requirements and long asset lifecycles further intensify rivalry, compelling firms to prioritize superior product reliability and comprehensive customer service to secure long-term operational growth.
KEY MARKET PLAYERS
Some of the market players dominate the global railway wiring harness market.
- Furukawa (Japan)
- Leoni (Germany)
- TE Connectivity
- Hitachi (Japan)
- Nexans (France)
- Prysmian (Italy)
Top Players In The Market
- TE Connectivity serves as a premier global technology industrial leader providing advanced connectivity and harness components designed for extreme railway operating conditions. Its primary market involvement centers on supplying ruggedized connectors, high-speed data cables, and robust power distribution systems that ensure fail-safe operation across high-speed locomotives and urban transit networks. To strengthen its commercial position, the firm continually invests in next-generation material science research, focusing on lightweight and flame-retardant composite insulation solutions. Furthermore, the corporation expands its regional manufacturing footprint through targeted acquisitions and strategic distribution agreements, enabling prompt delivery schedules for international rolling stock builders.
- Prysmian Group operates as a worldwide leader in the energy and telecom cable industry, offering specialized wiring harness products tailored for railway signaling, traction power, and telecommunication infrastructure. Its active involvement focuses on engineering durable, low-smoke, zero-halogen cables capable of withstanding intense thermal stress, moisture exposure, and mechanical vibration inside underground and surface rail systems. For strengthening its competitive standing, the company prioritizes sustainable manufacturing practices, advanced electron-beam cross-linking technologies, and large-scale plant modernizations across Europe and the Americas. These strategic operations allow the enterprise to secure high-value municipal contracts and maintain strict compliance with evolving international railway safety standards.
- Leoni AG functions as a vital international provider of specialized wiring systems, customized cable assemblies, and advanced distribution components dedicated to the global railway sector. Its corporate involvement highlights the delivery of tailored electrical wiring harnesses for passenger coach infotainment, automated signaling, and heavy locomotive propulsion units. To reinforce its market position, the company focuses heavily on digitalizing its production lines, integrating automated quality testing procedures, and forging collaborative partnerships with prominent rolling stock original equipment manufacturers. Such targeted industrial measures optimize operational efficiency, lower production bottlenecks, and solidify long-term client retention across competitive global markets.
Top Strategies Used By Key Market Participants
Key market participants deploy advanced strategic initiatives including geographic expansion into emerging rail corridors, long-term supply agreements with state railway authorities, joint ventures for fire-retardant material development, and portfolio diversification into fiber-optic hybrid data transmission cables. Furthermore, leading firms emphasize continuous investments in automated assembly robotics, rigorous environmental testing facilities, and customized engineering services to maintain competitive advantages within the global industry.
Major Strategic Actions Taken By Key Companies
- In April 2024, DynaTouch, a kiosk solutions provider, acquired KioWare, a kiosk management software company. This acquisition is anticipated to allow DynaTouch to offer more comprehensive kiosk solutions and strengthen the railway wiring harness market presence.
- In March 2025, TE Connectivity completed the expansion of its specialized manufacturing facility in Europe, integrating advanced electron beam cross-linking technology to enhance railway cable durability.
- In August 2025, Prysmian Group announced a multi-million-dollar capital investment program aimed at upgrading its specialized rolling stock cable production lines to support sustainable low-smoke zero-halogen outputs.
- In November 2025, Leoni AG entered a strategic supply agreement with a major European locomotive manufacturer to deliver customized high-voltage traction harness systems for upcoming intercity rail networks.
- In February 2026, Nexans S.A. completed a targeted acquisition of an industrial cable assembly business to broaden its specialized transit infrastructure portfolio and strengthen its regional market reach.
MARKET SEGMENTATION
This research report on the global railway wiring harness market has been segmented and sub-segmented based on application, cable type, component, material, voltage, train type, and region.
By Application
- HVAC
- Lighting Harness
- Brake Harness
- Traction System Harness
- Engine Harness
- Infotainment
- Others
By Cable Type
- Power Cable
- Transmission Cable
- Jumper Cable
- Others
By Component
- Wires
- Connectors
- Terminals
- Others
By Material
- Copper
- Aluminum
- Others
By Voltage
- Low Voltage
- Medium Voltage
- High Voltage
By Train Type
- Metro/Monorail
- Light Rail
- High-speed Rail/Bullet Train
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East and Africa