- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$335.6 BnMarket Estimate, 2026
$373.9 BnMarket Forecast, 2034
$886.8 BnCAGR, 2026–2034
11.40%Executive Summary: Retail Logistics Market
- Market Scope: Comprehensive global retail logistics market analysis covering solution types, service formats, transport modes, regional leadership frameworks, and e-commerce supply chain integration trends.
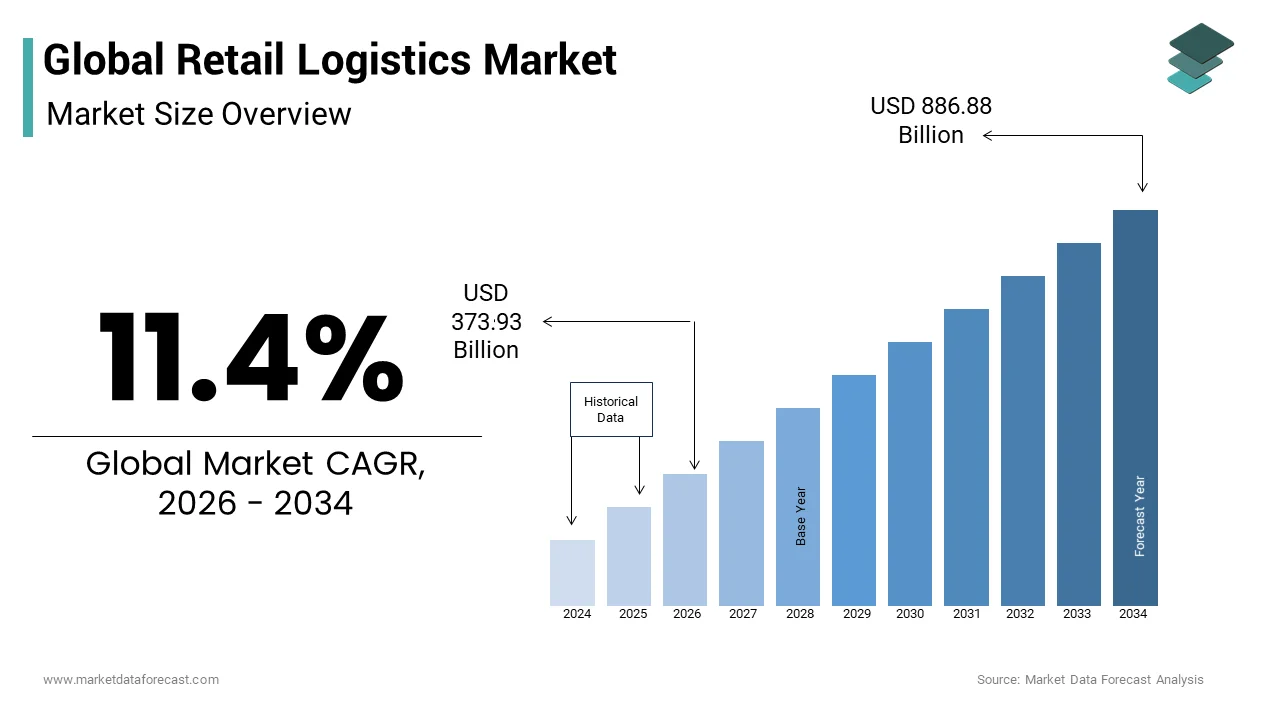
- Market Valuation: Valued at USD 336.66 billion (2025), estimated at USD 373.93 billion (2026), and projected to reach USD 886.88 billion by 2034, registering a strong CAGR of 11.4% (2026–2034).
- Primary Growth Drivers: Increased global trade activities from developing Asia-Pacific nations, worldwide transportation infrastructure developments, rapid urbanization driving urban fulfillment centers, and expanding e-commerce retail logistics.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Type / Format | Conventional Retail Logistics (captured the leading share in 2025) | E-Commerce Retail Logistics (expected to project a better CAGR during the forecast period) |
| By Solution & Transport | Supply Chain Solutions & Roadways (led solutions in 2025; roadways lead transport mode) | Supply Chain Solutions (expected to register the fastest CAGR alongside automated fulfillment) |
| By Region | Asia-Pacific - APAC (dominated regionally in 2025 due to massive exports and online retail) | North America & APAC (maintaining prominence via advanced logistics networks and tech integration) |
Major Market Players & Market Structure
Market Structure: Highly competitive global retail logistics landscape featuring major transport corporations, supply chain leaders, and logistics providers competing on automation, data analytics, cybersecurity integration, and urban fulfillment capabilities.
Key Companies: FedEx, Schneider, United Parcel Service, C.H. Robinson Worldwide, Inc., Nippon Express, APL Logistics Ltd, DHL International GmbH, A.P. Moller – Maersk, XPO Logistics, Inc., DSV, and Kuehne + Nagel International.
Global Retail Logistics Market Size
The global retail logistics market size was valued at USD 336.66 billion in 2025 and is anticipated to reach a valuation of USD 373.93 billion in 2026 and USD 886.88 billion by 2034, growing at a CAGR of 11.4% from 2026 to 2034.
Retail logistics is the comprehensive network of processes and technologies required to move goods from manufacturers to end consumers through various retail channels. This sector includes warehousing, inventory management, transportation, order fulfillment, and last-mile delivery services that ensure product availability and timely distribution. According to the United Nations Conference on Trade and Development, global merchandise trade volume reached 13 trillion dollars in 2023, underscoring the massive scale of goods movement that retail logistics must support. The shift towards omnichannel retailing has transformed traditional supply chains into complex, dynamic networks capable of handling both bulk shipments and individual parcel deliveries. According to the International Labour Organization, the transport and storage sector employs over 150 million people worldwide, highlighting its critical role in global employment and economic stability. According to the European Commission, logistics costs account for approximately 10% of the final price of consumer goods, driving retailers to optimize efficiency. The rise of e-commerce has further intensified the need for agile logistics solutions, with the World Bank reporting that global parcel volumes exceeded 160 billion in 2023. Retailers are increasingly integrating advanced technologies such as artificial intelligence and robotics to manage these complexities. The ability to provide real-time visibility and rapid delivery has become a key competitive differentiator. As consumer expectations for speed and convenience continue to rise, the retail logistics market serves as the backbone of modern commerce, ensuring that products reach customers seamlessly across physical and digital touchpoints.
MARKET DRIVERS
E-commerce Expansion and Rising Consumer Expectations for Speed
The exponential growth of e-commerce and the corresponding rise in consumer expectations for rapid delivery drive the global retail logistics market growth. Shoppers now demand same-day or next-day delivery options and this forces retailers to restructure their supply chains for greater agility and proximity to urban centers. According to the United Nations Conference on Trade and Development, global e-commerce sales reached 26.7 trillion dollars in 2023, representing a significant portion of total retail transactions. This surge in online shopping has led to a fragmentation of shipment sizes, with billions of small parcels replacing fewer large pallets. According to the Universal Postal Union, global parcel volume grew by 15% annually over the past five years, straining existing logistics infrastructure. Retailers are responding by establishing micro-fulfillment centers in densely populated areas to reduce last-mile delivery times. According to the National Retail Federation, 70% of consumers consider delivery speed a critical factor in their purchasing decisions. Consequently, companies are investing heavily in automated sorting systems and route optimization software to handle increased volumes efficiently. The expectation for free and fast shipping has also pressured retailers to absorb logistics costs or pass them on through subscription models. This dynamic environment requires continuous innovation in logistics operations to maintain service levels while managing costs. As mobile commerce continues to grow, the pressure on logistics providers to deliver faster and more reliably will only intensify, driving sustained investment in the sector.
Adoption of Automation and Digital Technologies in Supply Chains
The widespread adoption of automation and digital technologies is significantly propelling the retail logistics market expansion by enhancing operational efficiency and accuracy. Retailers are increasingly deploying robotics, artificial intelligence, and Internet of Things devices to streamline warehouse operations and improve inventory visibility. According to the International Federation of Robotics, the global stock of operational industrial robots reached 3.9 million units in 2022, with a significant portion utilized in logistics and warehousing. Automated guided vehicles and robotic picking systems can operate continuously, reducing labor dependency and minimizing human error. According to the McKinsey Global Institute, automation can reduce warehouse operating costs by up to 40% while increasing throughput by 20%. Furthermore, the integration of blockchain technology enhances transparency and traceability across the supply chain, allowing retailers to verify product authenticity and origin. According to the European Commission, digitalization in logistics can improve asset utilization by 30% through better data analytics and predictive maintenance. Cloud-based logistics platforms enable real-time collaboration between suppliers, distributors, and retailers, ensuring synchronized operations. These technologies also facilitate predictive analytics, which helps retailers anticipate demand fluctuations and optimize inventory levels. As labor shortages persist in many regions, automation becomes a necessary strategy to maintain service levels. The ability to process orders faster and with greater precision gives retailers a competitive edge in a crowded market. This technological transformation is reshaping the logistics landscape, making it more resilient and responsive to market dynamics.
MARKET RESTRAINTS
High Operational Costs and Labor Shortages
The high operational costs associated with retail logistics and persistent labor shortages are significant restraints on market growth. Logistics expenses, including fuel, warehousing, and transportation, constitute a substantial portion of retail overheads, making cost management a critical challenge. According to the International Energy Agency, fuel prices remained volatile in 2023, with average diesel prices increasing by 10% in major economies, impacting transportation costs directly. Additionally, the shortage of qualified truck drivers and warehouse workers exacerbates operational inefficiencies. According to the American Trucking Associations, the driver shortage in the United States reached 80,000 in 2023, leading to delayed shipments and increased wages. According to the European Road Transport Employers Federation, the sector faces a deficit of 400,000 drivers, affecting cross-border logistics. High turnover rates in warehouse jobs further increase recruitment and training costs for logistics providers. According to the International Labour Organization, the physical demands of logistics work contribute to high attrition rates, particularly among younger workers. These labor constraints force companies to invest in expensive automation technologies, which require significant upfront capital. Small and medium-sized retailers often lack the resources to make such investments, leaving them vulnerable to cost pressures. The combination of rising fuel costs, wage inflation, and labor scarcity squeezes profit margins and limits the ability of logistics providers to expand capacity. Until structural labor issues are addressed and energy costs stabilize, the industry will continue to face significant financial headwinds.
Regulatory Compliance and Environmental Sustainability Pressures
Stringent regulatory compliance requirements and growing pressure for environmental sustainability pose major restraints on the retail logistics market. Governments worldwide are implementing stricter emissions standards and labor regulations that increase operational complexity and costs for logistics providers. According to the International Maritime Organization, new carbon intensity regulations came into effect in 2023, requiring shipping companies to reduce greenhouse gas emissions by 40% by 2030. These mandates necessitate investments in cleaner fuels and newer vessels, which are capital-intensive. In the European Union, the Green Deal sets ambitious targets for reducing transport emissions by 90% by 2050, forcing logistics companies to transition to electric or hydrogen-powered vehicles. According to the European Environment Agency, transport accounts for 25% of total EU greenhouse gas emissions, making it a primary target for regulation. Additionally, urban low-emission zones restrict the entry of older diesel vehicles, requiring fleets to be upgraded prematurely. Compliance with diverse international trade regulations and customs procedures also adds administrative burdens and delays. According to the World Customs Organization, non-tariff barriers can increase logistics costs by up to 15% for cross-border shipments. Retailers must also adhere to packaging waste regulations, which require the use of recyclable materials and reduced plastic usage. These regulatory demands require continuous monitoring and adaptation, diverting resources from core business activities. The cost of transitioning to sustainable practices while maintaining competitiveness remains a significant challenge for many players in the retail logistics sector.
MARKET OPPORTUNITIES
Integration of Green Logistics and Circular Economy Practices
The integration of green logistics and circular economy practices is a substantial opportunity for the global retail logistics market as consumers and regulators prioritize sustainability. Retailers are increasingly adopting eco-friendly packaging, electric vehicle fleets, and reverse logistics systems to reduce their environmental footprint. According to the Ellen MacArthur Foundation, the circular economy could generate 4.5 trillion dollars in economic benefits by 2030 through resource efficiency and waste reduction. Reverse logistics, which involves the return and recycling of products, allows retailers to recover value from returned goods and minimize waste. According to the National Retail Federation, return rates in e-commerce range from 20 to 30%, creating a significant opportunity for efficient reverse supply chains. Companies are investing in biodegradable packaging materials and reusable container systems to meet consumer demand for sustainable options. According to the European Commission, 77% of EU citizens are concerned about the environmental impact of their purchases, influencing their buying behavior. Logistics providers are also optimizing routes using artificial intelligence to reduce fuel consumption and emissions. Electric last-mile delivery vehicles are becoming more common in urban areas, supported by government incentives and charging infrastructure development. By branding themselves as sustainable partners, retailers can enhance brand loyalty and attract environmentally conscious consumers. Furthermore, compliance with emerging environmental regulations positions early adopters as industry leaders. This shift towards sustainability opens new revenue streams through green services and creates a competitive advantage in a market where ethical considerations are increasingly important to stakeholders.
Expansion of Omnichannel Fulfillment and Micro-Fulfillment Centers
The expansion of Omnichannel fulfillment strategies and the deployment of micro-fulfillment centers offer significant opportunities for growth in the retail logistics market. Retailers are blending online and offline channels to provide seamless shopping experiences, such as buy-online-pick-up-in-store and curbside pickup. According to the Harvard Business Review, companies with strong Omnichannel capabilities retain 89% of their customers compared to 33% for those with weak capabilities. Micro-fulfillment centers located in urban areas enable faster delivery times and lower last-mile costs by storing inventory closer to consumers. According to Coresight Research, the number of micro-fulfillment centers in North America is expected to reach 1,000 by 2025, driven by the need for speed. These smaller facilities utilize automation to process orders efficiently in limited spaces. The ability to fulfill orders from multiple locations, including stores and warehouses, increases inventory flexibility and reduces stockouts. Retailers can leverage existing store networks as distribution hubs, optimizing asset utilization. The rise of social commerce and live-streaming sales further drives the need for agile fulfillment solutions that can handle sudden spikes in demand. By integrating data from all channels, retailers can gain better visibility into customer preferences and inventory levels. This holistic approach improves customer satisfaction and drives repeat purchases. As competition intensifies, the ability to offer flexible and fast fulfillment options becomes a key differentiator. Investing in Omnichannel logistics infrastructure allows retailers to capture a larger share of the consumer wallet and build long-term loyalty.
MARKET CHALLENGES
Supply Chain Disruptions and Geopolitical Instability
Persistent supply chain disruptions and geopolitical instability present major challenges to the global retail logistics market. Events such as pandemics, trade wars, and regional conflicts have exposed the vulnerabilities of global supply networks. According to the World Trade Organization, global merchandise trade volume declined by 1.2% in 2023 due to geopolitical tensions and economic uncertainty. Port congestions and shipping container shortages have led to significant delays and increased freight rates. According to the Shanghai Shipping Exchange, container freight indices fluctuated wildly in 2023, with some routes seeing costs increased by over 50% during peak periods. Dependence on single-source suppliers or specific geographic regions increases risk exposure. The Russian-Ukrainian conflict disrupted energy supplies and grain exports, affecting logistics costs and availability globally. Additionally, cyberattacks on logistics providers have become more frequent, causing operational shutdowns and data breaches. According to the International Chamber of Commerce, 60% of businesses experienced supply chain disruptions in the past two years. These uncertainties make it difficult for retailers to plan inventory and manage cash flow. Diversifying supply sources and nearshoring production are strategies being adopted, but they require time and investment. The lack of visibility into tier-two and tier-three suppliers further complicates risk management. As geopolitical tensions remain high, the retail logistics sector must build resilience through redundancy and flexibility, which often comes at a higher cost.
Talent Gap and Skill Mismatch in Logistics Workforce
The widening talent gap and skill mismatch in the logistics workforce pose a significant challenge to the global retail logistics market as the industry undergoes digital transformation. While automation is increasing, the demand for workers with technical skills such as data analysis, robotics maintenance, and software management is outpacing supply. According to the World Economic Forum, 50% of all employees will need reskilling by 2025 as adoption of technology increases. However, the logistics sector struggles to attract tech-savvy talent due to perceptions of it being a low-skill industry. According to the Chartered Institute of Logistics and Transport, 45% of logistics firms report difficulties in recruiting staff with digital competencies. Traditional warehouse roles are evolving into hybrid positions requiring both physical and digital literacy. The aging workforce in many developed countries further exacerbates the shortage of experienced personnel. Younger generations often prefer gig economy jobs over traditional logistics careers, leading to high turnover rates. Training programs are often insufficient to bridge the skill gap quickly enough to meet operational needs. According to the International Labour Organization, vocational training in logistics is underdeveloped in many regions. These skills mismatch leads to inefficiencies, errors, and increased operational costs. Companies must invest heavily in upskilling initiatives and employer branding to attract and retain talent. Without a skilled workforce, the full potential of advanced logistics technologies cannot be realized, which is hindering innovation and competitiveness in the market.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 11.4% |
| Segments Covered | By Type, Solution, Mode of Transport, and Region. |
|
Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | FedEx, Schneider, United Parcel Service, C.H. Robinson Worldwide, Inc., Nippon Express, APL Logistics Ltd, DHL International GmbH, A.P. Moller – Maersk, XPO Logistics, Inc., DSV, Kuehne + Nagel International, and Others. |
SEGMENTAL ANALYSIS
By Type Insights
The conventional retail logistics segment led the market by accounting for the major share of the global market in 2025, primarily due to its well-established infrastructure and efficiency in handling bulk shipments for brick-and-mortar stores. This segment relies on traditional distribution centers and long-haul transportation networks that have been optimized over decades to move large volumes of goods from manufacturers to regional warehouses. According to the International Chamber of Commerce, approximately 80% of global trade by volume is carried by sea, which forms the backbone of conventional retail supply chains. The economies of scale achieved through palletized and containerized shipping significantly reduce per-unit costs, making it the preferred method for stocking physical retail outlets. According to the World Bank, land-based transport accounts for 65% of domestic freight movement in developed economies, supporting the dense network of supermarkets and department stores. The predictability of demand in traditional retail allows for efficient inventory planning and consolidated shipments, which minimizes empty backhauls. Furthermore, the existing real estate footprint of major retailers includes vast warehouse spaces designed for bulk storage rather than individual item picking. According to the European Logistics Association, conventional logistics operations benefit from standardized processes and regulatory frameworks that have been refined over many years. This stability and cost-effectiveness ensure that, despite the rise of e-commerce, conventional logistics remains the dominant force in terms of total tonnage moved and revenue generated. The sheer volume of goods required to keep physical shelves stocked globally sustains the leadership of this segment.
On the other hand, the e-commerce retail logistics segment is the fastest-growing segment and is predicted to record a CAGR of 15.4% over the forecast period owing to the rapid shift in consumer purchasing behavior towards online channels. The need for fragmented small parcel delivery and rapid fulfillment has revolutionized logistics operations, requiring agile and technology-driven solutions. According to the United Nations Conference on Trade and Development, global e-commerce sales reached 26.7 trillion dollars in 2023, creating an unprecedented demand for last-mile delivery services. This segment requires complex sorting systems and micro-fulfillment centers located closer to urban consumers to meet expectations for same-day or next-day delivery. According to the Universal Postal Union, global parcel volume increased by 15% annually over the past five years, outpacing general freight growth. The integration of advanced technologies such as artificial intelligence for route optimization and robotics for automated picking is accelerating efficiency in this sector. According to the National Retail Federation, 70% of consumers consider delivery speed a critical factor in their purchasing decisions, forcing retailers to invest heavily in expedited logistics networks. Additionally, the rise of social commerce and live-streaming sales creates sudden spikes in demand that require flexible logistics capacity. Unlike conventional logistics, e-commerce logistics must handle high return rates and reverse logistics efficiently. The continuous innovation in delivery methods, including drone trials and autonomous vehicles, further propels this segment. As digital penetration increases in emerging markets, the growth trajectory of e-commerce logistics remains steep and robust.
By Solution Insights
The transportation management segment accounted for a dominant share of the global market in 2025 because it directly impacts the largest component of logistics costs and overall service reliability. Efficient management of freight movements across various modes is essential for maintaining profit margins and meeting delivery commitments. According to the Council of Supply Chain Management Professionals, transportation costs account for approximately 60% of total logistics expenses for most retailers, making effective management crucial. Transportation management systems provide real-time visibility into shipment status, allowing companies to proactively address delays and optimize routes. According to the American Trucking Associations, optimized routing can reduce fuel consumption by up to 15%, which is significant given volatile energy prices. These solutions also facilitate carrier selection and rate negotiation, ensuring that retailers secure the best possible pricing for their freight needs. According to the European Commission, digital transportation platforms can improve asset utilization by 20% through better load matching and reduced empty miles. Furthermore, compliance with diverse international regulations regarding hazardous materials and cross-border documentation is streamlined through these systems. The ability to integrate with enterprise resource planning systems ensures seamless data flow between procurement, sales, and logistics departments. As global supply chains become more complex, the need for centralized control over transportation operations grows. Retailers rely on these solutions to balance cost, speed, and reliability, making transportation management the cornerstone of modern retail logistics strategies.
However, the reverse logistics and liquidation segment is the fastest-growing solution segment and is estimated to showcase a CAGR of 12.5% over the forecast period owing to the high volume of returns associated with online shopping and sustainability mandates. The ease of returning items in e-commerce has led to return rates that are significantly higher than in brick-and-mortar retail, necessitating specialized processing capabilities. According to the National Retail Federation, the average return rate for online purchases is 20.8% compared to 8.9% for in-store purchases, creating a massive logistical burden. Efficient reverse logistics solutions enable retailers to inspect, refurbish, and restock returned items quickly, minimizing value loss. According to the Ellen MacArthur Foundation, effective circular economy practices, including reverse logistics, could unlock 4.5 trillion dollars in economic benefits by reducing waste. Liquidation services help retailers recover value from unsold or damaged inventory by connecting them with secondary markets and discount retailers. According to the European Environment Agency, stricter waste regulations are forcing companies to adopt formal reverse logistics processes to ensure proper recycling and disposal. Advanced software solutions now use predictive analytics to determine the most profitable path for returned items, whether it be resale, donation, or recycling. Consumers are increasingly expecting hassle-free return experiences, which drives investment in this area. As sustainability becomes a key brand differentiator, the ability to manage product lifecycles responsibly through reverse logistics becomes a competitive advantage. This segment is expanding rapidly as retailers seek to turn the cost center of returns into a value recovery opportunity.
By Mode Of Transport Insights
The roadways segment occupied the largest share of the global market in 2025. The dominance of roadways segment in the global market is attributed to their unparalleled flexibility, accessibility, and critical role in last-mile delivery. Trucks and vans can reach virtually any location, including remote rural areas and dense urban centers where other modes cannot operate effectively. According to the International Transport Forum, road transport accounts for approximately 75% of inland freight movement in OECD countries, highlighting its centrality to retail distribution. The door-to-door capability of road transport eliminates the need for multiple handling stages, reducing the risk of damage and delay. According to the European Road Transport Employers Federation, over 400,000 trucks operate daily in Europe alone, facilitating the continuous flow of goods to retail outlets. The rise of e-commerce has further cemented the dominance of roadways, as final delivery to consumers is almost exclusively performed by road vehicles. The ability to schedule frequent and smaller shipments aligns with the just-in-time inventory practices of modern retailers. Additionally, advancements in vehicle technology, such as electric trucks, are addressing environmental concerns while maintaining operational efficiency. The extensive network of highways and local roads provides a reliable infrastructure base that supports high-frequency deliveries. While other modes are efficient for long-haul bulk transport, they lack the granularity required for retail distribution. The immediacy and adaptability of road transport make it indispensable for meeting the dynamic demands of the retail sector, ensuring its continued leadership in the market.
However, the airways segment is anticipated to showcase the fastest CAGR of 10.4% over the forecast period in the global market owing to the increasing demand for speed and the globalization of premium and perishable goods. Retailers are increasingly relying on air freight to launch new products simultaneously across global markets and to deliver high-value items quickly. According to the International Air Transport Association, air cargo volumes grew by 8% in 2023, reflecting the resilience of high-value trade. The ability to transport goods across continents in less than 24 hours is crucial for fashion retailers and technology companies with short product life cycles. According to the World Customs Organization, while air freight represents less than 1% of global trade by volume, it accounts for over 35% by value, underscoring its importance for high-margin retail goods. The growth of cross-border e-commerce has also boosted air cargo demand, as consumers expect rapid delivery of international purchases. Perishable goods, such as fresh produce and flowers, rely heavily on air transport to maintain quality and shelf life. The expansion of dedicated cargo fleets by major airlines and integrators like FedEx and DHL enhances capacity and reliability. Although more expensive than other modes, the speed and reliability of air transport justify the cost for time-sensitive retail segments. As global middle-class consumption rises, the demand for exotic and premium products transported by air continues to accelerate.
REGIONAL ANALYSIS
North America Market Analysis
North America had 36.4% of the global market share in 2025 and is likely to maintain its leadership position in the global retail logistics market over the next few years due to continued high consumer spending and advanced technological investments, high consumer spending, advanced infrastructure, and widespread adoption of logistics technologies. The United States is the primary contributor, with its vast network of highways, railways, and distribution centers supporting a massive retail sector. According to the Bureau of Transportation Statistics, freight transportation in the US moved over 19 billion tons of goods in 2023, facilitating efficient retail distribution. The region is a pioneer in adopting automation and artificial intelligence in warehouses, with companies like Amazon setting global standards for fulfillment speed. According to the National Retail Federation, US retail sales exceeded 5 trillion dollars in 2023, creating immense demand for logistics services. The presence of major third-party logistics providers and technology firms fosters innovation and efficiency. Canada and Mexico also contribute significantly through integrated cross-border supply chains under the United States-Mexico-Canada Agreement. The high penetration of e-commerce in North America drives investment in last-mile delivery networks and micro-fulfillment centers. Consumer expectations for fast and free shipping are among the highest globally, pushing retailers to continuously optimize their logistics operations. The region's strong regulatory framework and investment in green logistics initiatives further support sustainable growth. With a mature market and continuous technological advancement, North America remains the benchmark for retail logistics excellence globally.
Asia Pacific Market Analysis
Asia Pacific is the fastest-growing region in the global retail logistics market with a projected Compound Annual Growth Rate of 12.1% over the forecast period due to the rapid industrialization, rising disposable incomes, and the boom in digital commerce. China, India, and Southeast Asian nations are experiencing unprecedented growth in retail consumption, driving demand for efficient logistics networks. According to the Asian Development Bank, the region's middle class is expected to reach 3.5 billion people by 2030, creating a massive consumer base for retail goods. China serves as the global manufacturing hub, requiring robust inbound and outbound logistics capabilities to support both domestic and international retail. According to the China Federation of Logistics and Purchasing, the country's logistics industry grew by 6% in 2023, supported by government infrastructure investments. The rapid adoption of mobile payments and e-commerce platforms in countries like India and Indonesia is transforming retail logistics requirements. Local players are investing heavily in automated warehouses and electric delivery vehicles to meet sustainability goals. The Belt and Road Initiative has improved connectivity across the region, facilitating smoother cross-border trade. Government policies promoting digital economy and smart logistics parks are accelerating modernization. The young demographic profile and increasing urbanization further drive demand for convenient retail services. As infrastructure improves and digital literacy spreads, Asia Pacific is poised to become the central engine of global retail logistics growth in the coming decade.
COMPETITIVE LANDSCAPE
The competition in the Retail Logistics Market is characterized by intense rivalry among global integrators regional carriers and emerging technology driven startups who strive to differentiate through speed and service quality. Major players compete on the basis of network coverage delivery speed technological integration and cost efficiency. The market sees frequent investments in automation and digital platforms that enhance visibility and customer experience. Price competition remains significant particularly in standard parcel delivery segments prompting companies to optimize operational costs through scale and efficiency. However leading firms mitigate this by offering specialized services such as white glove delivery and complex reverse logistics solutions that command higher margins. Regional competitors often leverage local knowledge and flexibility to serve niche markets effectively. Intellectual property protection plays a vital role as companies patent unique sorting technologies and routing algorithms. The absence of dominant monopolies ensures a fragmented landscape where innovation and customer centricity are key determinants of success. Continuous adaptation to e commerce trends and sustainability mandates further intensifies the competitive dynamics requiring agile responses from all market participants to sustain long term growth and brand loyalty in this rapidly evolving industry.
KEY MARKET PLAYERS
Some of the market players that dominate the global retail logistics market are.
- FedEx
- Schneider
- United Parcel Service
- Amazon.com Inc
- C.H. Robinson Worldwide, Inc
- Nippon Express
- APL Logistics Ltd
- DHL International GmbH
- A.P. Moller – Maersk
- XPO Logistics, Inc.
- DSV
- Kuehne + Nagel International
Top Players In The Market
- Amazon.com Inc revolutionizes the Retail Logistics Market through its extensive fulfillment network and advanced technological integration. The company operates a vast global infrastructure of warehouses sorting centers and delivery stations that enable rapid order processing. Recent actions include the expansion of its middle mile delivery capabilities and the deployment of thousands of robotic units in fulfillment centers to enhance efficiency. Amazon continues to invest in electric delivery vehicles and renewable energy to support its sustainability goals. Its proprietary logistics software provides real time visibility and predictive analytics for inventory management. By offering fulfillment services to third party sellers Amazon strengthens its ecosystem and drives volume. The company also experiments with drone delivery and autonomous robots to further reduce last mile costs. These innovations maintain its leadership in speed and reliability setting high standards for the industry.
- DHL Group serves as a critical partner in the Retail Logistics Market by providing comprehensive supply chain solutions and global connectivity. The company specializes in e commerce logistics offering tailored services for returns warehousing and last mile delivery. Recent initiatives include the expansion of its micro fulfillment centers in major urban areas to accelerate delivery times. DHL actively invests in sustainable aviation fuels and electric vehicle fleets to meet environmental regulations. Its digital platforms integrate seamlessly with retailer systems enabling end to end supply chain visibility. The group focuses on enhancing customer experience through flexible delivery options and transparent tracking. By strengthening its presence in emerging markets DHL captures growing demand for cross border retail logistics. Strategic partnerships with technology firms further enhance its operational efficiency and data driven decision making capabilities.
- FedEx Corporation plays a pivotal role in the Retail Logistics Market by leveraging its robust air and ground networks for reliable parcel delivery. The company focuses on integrating digital tools to improve shipment visibility and customer engagement. Recent actions include the acquisition of specialized logistics providers to expand its healthcare and retail capabilities. FedEx is heavily investing in automation at its sorting hubs to handle increasing e commerce volumes efficiently. The introduction of same day delivery services in key metropolitan areas addresses the demand for speed. The corporation also prioritizes sustainability by expanding its electric vehicle fleet and optimizing route efficiency. Its global reach ensures seamless cross border transactions for retailers. By enhancing its technology stack and network density FedEx maintains a competitive edge in serving diverse retail clients worldwide.
Top Strategies Used By Key Market Participants
Key players in the Retail Logistics Market primarily employ strategies centered on technological automation network expansion and sustainability initiatives to maintain competitive advantage. Companies heavily invest in robotics and artificial intelligence to streamline warehouse operations and reduce labor dependency. Integrating advanced data analytics allows for better demand forecasting and inventory optimization which enhances service reliability. Strategic partnerships with e commerce platforms and retailers enable logistics providers to secure long term contracts and increase shipment volumes. Additionally firms focus on expanding their last mile delivery networks through micro fulfillment centers and local hubs to reduce transit times. Adopting green logistics practices such as electric vehicles and eco friendly packaging helps comply with regulations and appeal to conscious consumers. Diversifying service offerings to include reverse logistics and value added services creates new revenue streams. These multifaceted approaches ensure that market participants can address evolving consumer expectations and operational challenges while capturing growth opportunities in the dynamic global retail sector.
MARKET SEGMENTATION
This research report on the global retail logistics market is segmented and sub-segmented into the following categories.
By Type
- Conventional Retail Logistics
- E-commerce Retail Logistics
By Solution
- Commerce Enablement
- Supply Chain Solutions
- Reverse Logistics & Liquidation
- Transportation Management
- Others
By Mode of Transport
- Railways
- Airways
- Roadways
- Waterways
By Region
- North America
- Europe
- APAC
- Latin America
- Middle East and Africa