- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$471 MnMarket Estimate, 2026
$564.92 MnMarket Forecast, 2034
$2,419 MnCAGR, 2026–2034
19.94%Global Surgical Simulation Market Size
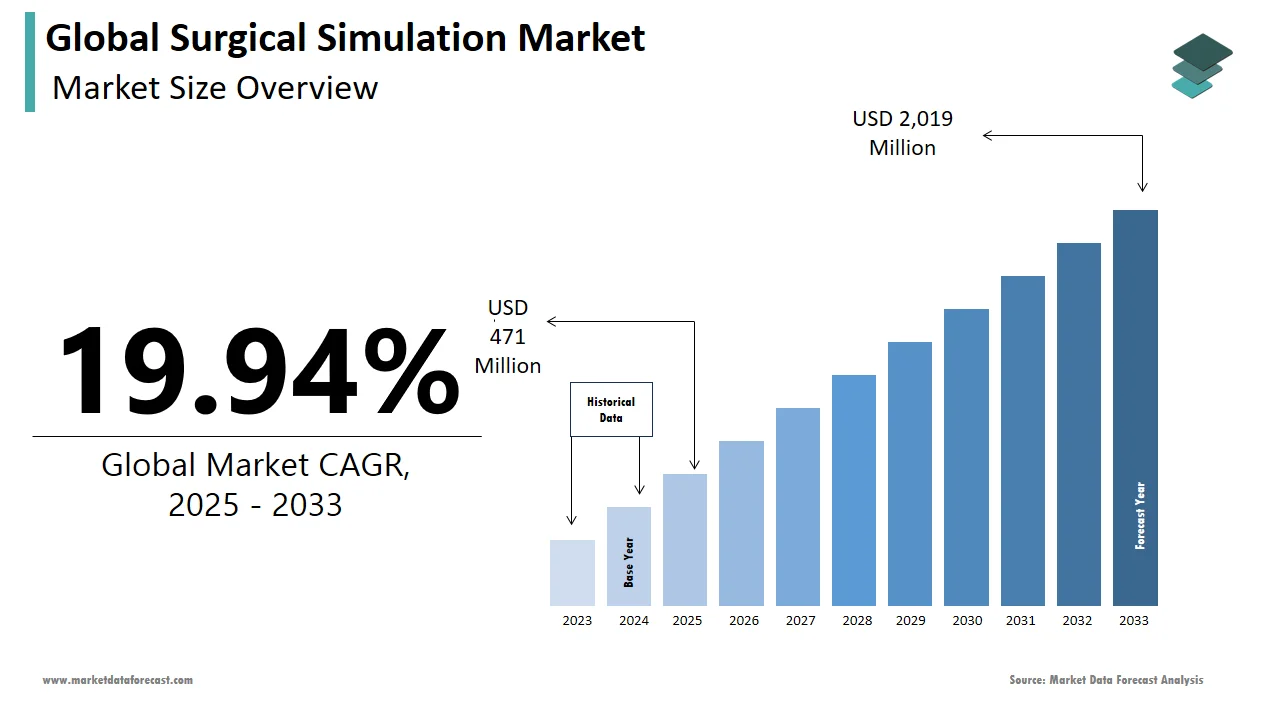
The global surgical simulation market was valued at USD 471 million in 2025. The global market is anticipated to grow at a CAGR of 19.94% from 2026 to 2034 and be worth USD 2,419 million by 2034 from USD 564.92 million in 2026.
MARKET DRIVERS
There has been a growth in the application of various surgical simulators due to its increasing necessity to identify the primary sources of medical errors, one of the major factors propelling the surgical simulation market growth.
Also, there has been an urgent need to seek solutions that emphasize patient safety, along with the full implementation of simulation training in healthcare in recent years, due to ongoing changes in healthcare systems leading to increasing demand for surgical training, thereby driving the growth of the market. It has been found that an approximation of 440,000 patients dies out of medical errors in the United States, which emphasizes reducing medical errors, which can be achieved using medical simulation.
Technological advances to boost the surgical simulation market growth.
Innovations in non-clinical surgical simulation have become a good demand for robotic simulators, cadavers, tabletop, and virtual reality (VR) due to rising current duty hour limitations and patient safety concerns. The investments by leading companies in developing technologically advanced products would help healthcare professionals improve their surgical skills. The latest among them, 3D printing, has gained ground in the medical field in recent years due to the development in Applications of 3D printing technology for using 3D models to augment patient education. These simulators have many advantages over other forms, which led to the acceptance of 3D printing in surgical simulation, contributing to the market's growth. Other such advances include telesurgery and the integration of patient-specific anatomy, paving the way for simulators to become essential parts of medical education.The benefits of simulations in surgical training, along with reduced associated costs while improving patient care outcomes, helps translation of skills learned through simulations into improvements in the operating room on the patients. In addition, they not only quickly integrate new medical technologies but also offer more faithful reconstructions of procedures, benefitting both novice and experienced surgeons. These factors are expected to drive the market growth of the global surgery simulation market.
MARKET RESTRAINTS
The major problems faced by the market leading to its growth decline include high cost of reimbursements, opportunities, high installation, operating, and maintenance costs, and more significant requirements of space. Additionally, the training experience of new surgeons in the operating room has also been severely constrained by the increasing emphasis on patient safety, prompting the creation of teaching methods that do not use actual patients.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Specialty, Application, End-user, and Region. |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Market Leaders Profiled | CATHI GmBH, CAE Inc., Limbs & Things Ltd., LAERDAL MEDICAL AS, Mentice AB, VitaMed Ag, Simendo Company, 3D Systems Corporation, Medical-X, Simulab Corporation, and Others. |
SEGMENTAL ANALYSIS
By Specialty Insights
Based on the specialty, the orthopedic segment is anticipated to hold a significant share of the global surgical simulation market during the forecast period. The dominance of this segment can be attributed to the increasing demand for surgical simulation products due to the increasing number of surgeries worldwide. In addition, there has been a rise in the number of orthopedic diseases like rheumatoid arthritis, osteoporosis, ligament injuries of the knee, and osteoarthritis, primarily due to lifestyle changes. This growing complexity of surgeries has resulted in the need for proper training, attributed to the growth of the surgical simulation market.Also, the neurological segment is expected to project a healthy CAGR during the forecast period owing to the rising incidence of neurological disorders, the growing frequency of treatment options available in the market, rising awareness of neurological disorders, and emerging healthcare infrastructure.
By Application Insights
Based on application, the polymer segment is anticipated to account for the largest share of revenue, mainly due to plastics, which are estimated to hold a high CAGR. Polymers offer various benefits such as increased comfort, decreased serious complications, decreased operative time, decreased incidence of fistula formation, poor scarring, and velopharyngeal insufficiency.On the other hand, the metals segment is expected to account for a substantial market share during the forecast period. Metals are significant and commonly used in surgical simulators, including titanium, aluminum, stainless steel, copper, cobalt-chromium and magnesium. The growing need for cost-effective surgical simulators will contribute to the segment's growth.
By End-User Insights
Based on end-user, the hospital segment is expected to account for a significant share of the surgical simulation market during the forecast period due to the considerable developments in the healthcare infrastructure, favorable surgical outcomes, growing demand for better planning ahead of complex surgeries, and Wide contacts for groups of medical students to learn and practice.The academic and research institute category is foreseen to witness the fastest growth in the surgical simulation market during the forecast period, mainly due to the generate the most significant demand for surgical simulators, high demand for educational training programs to train medicos and prepare them to become real surgeons and to improve the clinical performance.
REGIONAL ANALYSIS
Based on region, North America is expected to dominate the surgical simulation market throughout the forecast period, which may be due to the Early adoption of advanced technologies, the growing availability of improved healthcare infrastructure, growing collaborations between market players and healthcare associations, growing health awareness among people, an increasing number of surgical procedures, developments and product innovations by market players, and rising healthcare expenditures.
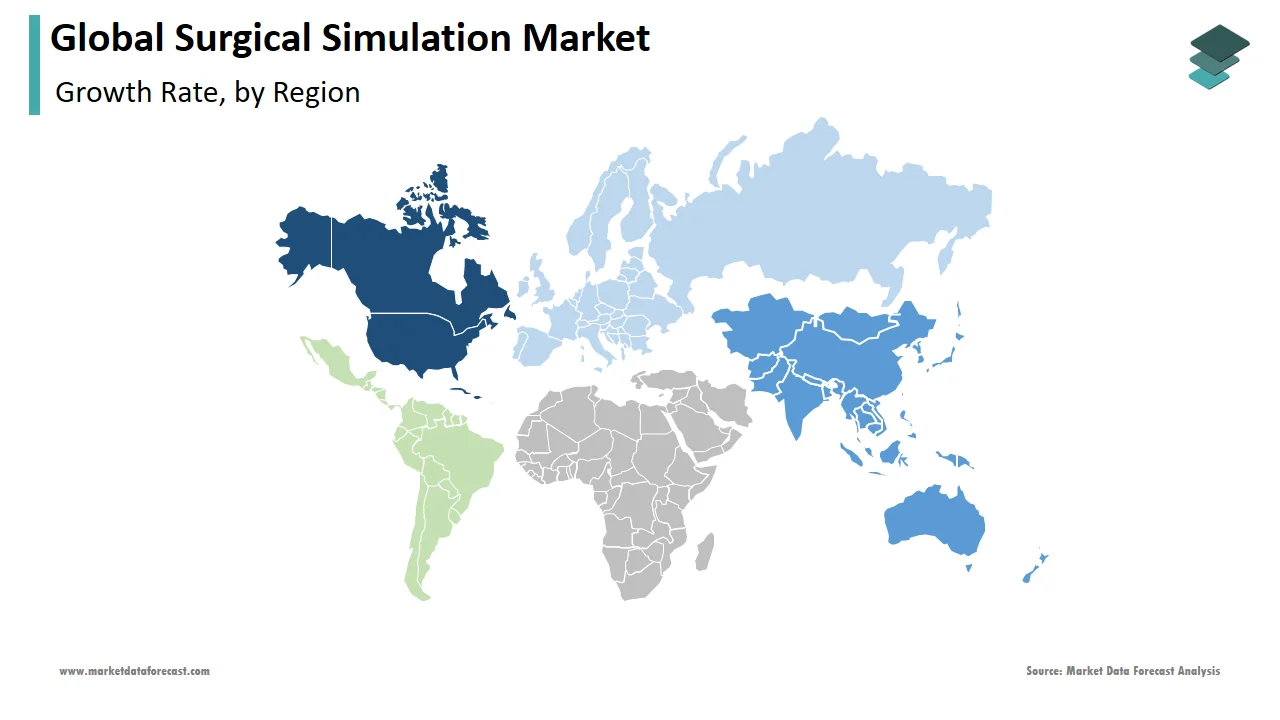
In Europe, there had been more estimations of registering a high growth rate in the market, being the first to standardize surgical training. In addition, medical simulation is rapidly evolving in this region with new technologies and methodologies in countries like France, ensuring doctors have high, measurable standards and enough rest before treating patients and making it even easier for residents to access the simulators, including a laparoscopic simulator.
The market in the Asia-Pacific region is anticipated to witness the fastest growth over the forecast period owing to the availability of high-quality labor, growing medical tourism sector, growing geriatric population, increased awareness of surgical simulation, and rising healthcare expenditures. Moreover, more supporting government initiatives, low manufacturing costs, the growing momentum of medical study and research in countries like China, and more investment by major players, as part of their business strategy, in the untapped markets, contributing to the growth of the regional market. In addition, there is also an increase in demand for healthcare simulation products and services in high-income countries for the increased use of simulation training and assessment for teaching surgery, which is the reason for the high ease of doing business in Asian countries.
African, Middle Eastern, and Latin American surgeons concur that simulation is an essential instructional tool that should be included throughout surgery residency. However, the availability of inexpensive instruments, sufficient money, and faith in the worth of the educational experience pose obstacles to attaining this objective in these regions, which is the reason for its gradual growth estimation across the forecast period. But by putting more effort into increasing the accessibility of simulation in these regions, the market would show lucrative growth over the forecast period.
KEY MARKET PLAYERS
Some of the companies that are playing a dominating role in the global surgical simulation market include
- CATHI GmbH
- CAE Inc.
- Limbs & Things Ltd.
- Laerdal Medical AS
- Mentice AB
- VitaMed AG
- Simendo Company
- 3D Systems Corporation
- Medical-X
- Simulab Corporation
GLOBAL SURGICAL SIMULATION MARKET NEWS
- In October 2022, a global health technology leader, Royal Philips, to improve the imaging and simulation of cancer radiation therapy of the head and neck, launched two new advancements in MRI-only workflows, for which it has received 510(k) clearance from the FDA.
- In May 2022, VirtaMed, a global leader in medical simulation training, collaborated with Medical Microinstruments (MMI) SpA, a robotics company dedicated to improving clinical outcomes for patients undergoing microsurgery, for the access of surgeons to innovative surgical simulations using the L MMI's Symani surgical team.
MARKET SEGMENTATION
This research report on the global surgical simulation market has been segmented and sub-segmented based on specialty, application, end-user, and region.
By Specialty
- Products
- Endoscopic
- Laparoscopic
- Cardiac
- Orthopedic
- Gynecological
- Arthroscopic
- Neurological
- Services
- Educational
- Technical
By Application
- Metal
- Polymer
- Plastic
- Others
By End-User
- Hospitals
- Academic Institutes
- Specialty Centers
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa