- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$5.19 BnMarket Estimate, 2026
$5.72 BnMarket Forecast, 2034
$12.51 BnCAGR, 2026–2034
10.28%Executive Summary: Global Thermal Interface Material (TIM) Market
- Market Scope: Comprehensive market analysis of the global thermal interface material sector covering product chemistries, application verticals, regional leadership frameworks, and high-performance thermal management growth drivers.
- Market Valuation: Valued at USD 5.19 billion (2025), estimated at USD 5.72 billion (2026), and projected to reach USD 12.51 billion by 2034, registering a steady CAGR of 10.28% (2026–2034).
- Primary Growth Drivers: Increasing semiconductor density, expanding AI and cloud computing infrastructure, rapid electric vehicle (EV) adoption, and the proliferation of 5G-enabled devices. Additional opportunities include hyperscale data center investments, renewable energy infrastructure, and next-generation battery technologies.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Product Type | Greases and adhesives (dominated with a 35.4% share in 2025) | Phase change materials (PCMs) (projected CAGR of 10.3% through 2034) |
| By Application | Computer segment (accounted for the largest 30.2% share in 2025) | Automotive electronics (registering the fastest CAGR of 11.2%) |
| By Region / Geography | Asia Pacific (led with a 45.3% share in 2025 due to semiconductor and EV manufacturing) | Asia Pacific (fastest-growing regional hub backed by electronics and battery production) |
Major Market Players & Market Structure
Market Structure: Highly competitive global landscape characterized by intensive R&D investments, focus on high-conductivity material formulations, localized manufacturing networks, sustainability initiatives, and strategic tier-1 OEM partnerships.
Key Companies: Henkel Corporation, Dow Inc., 3M Company, The Bergquist Company, Laird Technologies (Renesas Electronics), Shin-Etsu Chemical Co., Ltd., Momentive Performance Materials Inc., Parker Hannifin Corporation, Wakefield-Vette, Zalman Tech Co., Ltd., Indium Corporation, Panasonic Corporation, Arctic Silver, Inc., Fujipoly America Corporation, and Master Bond Inc.
Global Thermal Interface Material Market Size
The global thermal interface material market size was valued at USD 5.19 billion in 2025 and is expected to reach USD 12.51 billion by 2034 from USD 5.72 billion in 2026. The market is projected to grow at a CAGR of 10.28%.
The thermal interface materials (TIMs) are providing specialized materials that enhance heat dissipation between electronic components and heat sinks, ensuring device reliability and performance. These materials are ranging from thermal greases and adhesives to phase-change materials, which are indispensable in modern electronics, automotive systems, and industrial equipment. Similarly, the U.S. Department of Energy indicates that electronics overheating accounts for nearly 55% of unplanned device failures in industrial applications.
MARKET DRIVERS
Growth in High-Performance Electronics
The rising demand for smartphones, wearables, and high-performance computing devices is boosting the growth of thermal interface materials (TIMs) market. According to Ericsson, global smartphone subscriptions are projected to surpass 7.8 billion by 2028, driven by 5G adoption and IoT expansion. These devices generate higher thermal loads, requiring efficient TIMs to maintain functionality and prevent overheating. In high-performance computing, chip density has doubled in recent years, with the Semiconductor Industry Association noting that transistor counts per chip reached over 114 billion in 2022. This surge directly amplifies the use of TIMs as manufacturers prioritize durability and performance, making electronics miniaturization and performance acceleration a core growth driver.
Rising Adoption of Electric Vehicles (EVs)
Electric vehicles demand robust thermal management systems to ensure battery safety and efficiency is additionally fuelling the growth of thermal interface materials (TIMs) market. The International Energy Agency reported that EV sales exceeded 10 million units in 2022, accounting for 14% of global new car sales compared to just 9% in 2021. Lithium-ion batteries operate within narrow thermal windows, and overheating risks can compromise safety and longevity. TIMs provide vital solutions in battery packs, power electronics, and charging systems, which is improving energy efficiency and reducing thermal runaway risks.
MARKET RESTRAINTS
High Material and Manufacturing Costs
The advanced formulations significantly raise costs, which is major factor degrading the growth of thermal interface materials (TIMs) makret. High-performance products such as graphite sheets and phase-change materials are expensive to produce due to raw material limitations and precise processing. The U.S. Geological Survey noted that global graphite prices increased by nearly 23% in 2022 amid rising demand and supply shortages. These cost pressures hinder large-scale adoption in cost-sensitive industries, especially in developing economies. Smaller electronics manufacturers often opt for cheaper but less efficient alternatives by slowing the penetration of advanced TIMs across broader applications.
Complexity in Integration and Reliability Issues
Integration of TIMs into devices requires precise application and maintenance, and failure can compromise product reliability. According to the IEEE, nearly 40% of electronic device malfunctions in industrial environments are traced to inadequate or degraded thermal interface solutions. Challenges such as pump-out, drying, or void formation limit long-term reliability in automotive and aerospace sectors where durability is important. These technical complexities discourage manufacturers from investing heavily in advanced TIMs without proven lifecycle performance, which is posing a restraint to consistent adoption across industries.
MARKET OPPORTUNITIES
Expansion of Data Centers and Cloud Computing
The global surge in cloud services and artificial intelligence workloads is creating vast opportunities for the growth of thermal interface materials (TIMs) market. According to the International Telecommunication Union, internet traffic surged by over 23% in 2022, accelerating investments in hyperscale data centers. These centers rely on high-density servers, which generate substantial thermal loads. TIMs provide indispensable solutions in ensuring processors, GPUs, and memory modules operate within safe temperature ranges. TIM demand is poised to grow as thermal efficiency becomes a strategic priority for lowering energy consumption and achieving sustainability targets, with companies like Google and Microsoft scaling their data center footprints globally.
Advancements in Renewable Energy Systems
The integration of renewable technologies such as wind turbines and solar inverters is also to enhance the growth of thermal interface materials (TIMs) market. According to the International Renewable Energy Agency, renewable power capacity reached 3,372 GW in 2022, marking a 9.6% increase from the previous year. Inverters and power modules used in these systems generate significant heat, which is requiring effective TIMs to maintain performance and avoid failures.
MARKET CHALLENGES
Sustainability and Environmental Concerns
While TIMs enhance device performance, many contain synthetic polymers or additives with recycling and disposal challenges. Electronic waste remains the fastest-growing waste stream by reaching 53.6 million tonnes globally in 2019. Improper disposal of TIMs in discarded electronics exacerbates the environmental footprint of e-waste. Manufacturers face growing pressure to develop biodegradable or recyclable TIM alternatives, which remains technologically challenging and cost-intensive.
Volatility in Raw Material Supply Chains
The raw materials such as silicone, graphite, and metal oxides are vulnerable to supply disruptions. This factor is likely to inhibit the growth of thermal interface materials (TIMs) market. As per World Bank, raw material supply instability caused price volatility of industrial minerals by nearly 20% in 2022. Geopolitical tensions, mining restrictions, and logistical disruptions add further uncertainty. Such fluctuations create unpredictability in production costs and margins for TIM manufacturers, making long-term planning and customer pricing more difficult. Addressing these challenges requires diversification of sourcing and sustainable material innovation, both of which remain complex and capital intensive.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 10.28% |
| Segments Covered | By Type, Application, and Region. |
| Various Analyses Covered | Global, Regional and Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Henkel Corporation, Dow Corning Corporation (now Dow, Inc.), 3M Company, Bergquist Company, Laird Technologies (now part of Renesas Electronics Corporation), Shin-Etsu Chemical Co., Ltd., Momentive Performance Materials Inc., Parker Hannifin Corporation, Wakefield-Vette, Zalman Tech Co., Ltd., Indium Corporation, Panasonic Corporation, Arctic Silver, Inc., Fujipoly America Corporation, Master Bond Inc., and Others. |
SEGMENTAL ANALYSIS
By Type Insights
The greases and adhesives segment was the largest and held 35.4% of the global thermal interface materials (TIMs) market share in 2025, with the adoption in electronics, automotive modules, and industrial equipment due to excellent thermal conductivity and ease of application. As per International Electrotechnical Commission, poor thermal management is responsible for around 55% of semiconductor failures, making greases indispensable for reliability. In automotive, they are widely used in battery packs and powertrain electronics, where heat dissipation is important.
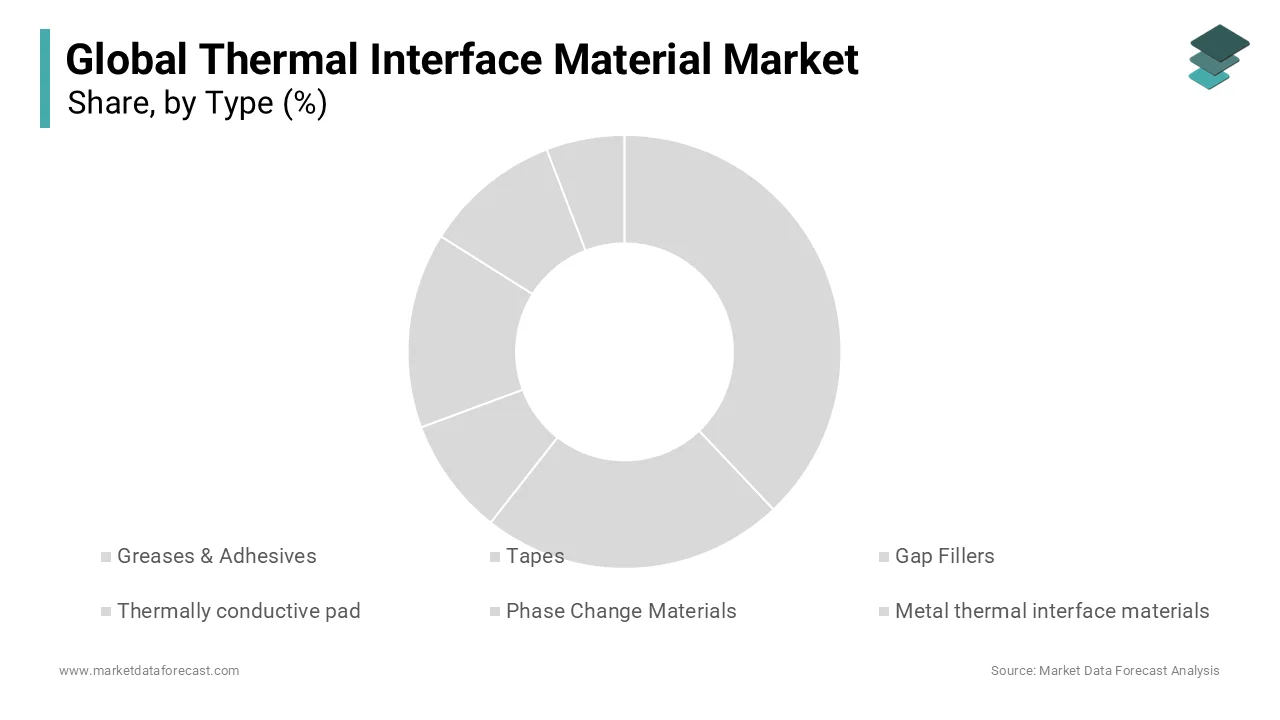
The phase change materials segment is projected to grow with an expected CAGR of 10.3% during the forecast period with the rapid scaling of data centers and AI-powered computing systems, where PCMs offer low thermal resistance and high reliability in continuous operation. According to the International Energy Agency, data centers consumed nearly 240–340 TWh of electricity in 2022, a figure expected to more than double by 2030. PCMs stabilize processor performance in high-density server environments and prevent hotspots.
By Application Insights
The computer segment led the global TIMs market by accounting for 30.2% of share in 2025 with the expansion of personal computing, high-performance gaming, and cloud servers has intensified the requirement for efficient thermal management. According to the Semiconductor Industry Association, transistor density in chips exceeded 114 billion in 2022, which significantly raises thermal load. TIMs are essential for cooling CPUs, GPUs, and memory units.
The automotive electronics segment is expected to grow with a CAGR of 11.2% during the forecast period with the electrification wave, with EVs and hybrid vehicles requiring TIMs for battery systems, inverters, and onboard chargers. Advanced driver-assistance systems (ADAS) and infotainment modules add further heat-management needs. The automotive sector is becoming a major TIM growth engine in Asia Pacific where EV adoption is accelerating at unprecedented levels.
REGIONAL ANALYSIS
Asia Pacific Market Analysis
Asia Pacific was the top performer in the thermal interface materials (TIMs) market with 45.3% of share in 2025 with its status as the manufacturing hub for semiconductors, electronics, and EV batteries. China alone produced over 1.5 billion smartphones in 2022 as per the China Academy of Information and Communications Technology, driving enormous TIM consumption. The region is also at the forefront of EV adoption, with China selling 6.8 million EVs in 2022 according to IEA, further reinforcing demand.
North America Market Analysis
North America thermal interface materials (TIMs) market growth is driven with its thriving data center industry and tech ecosystem. As per U.S. Energy Information Administration, data centers consumed about 4% of total U.S. electricity in 2022. The region is also a pioneer in AI computing, where GPUs and high-performance servers necessitate advanced TIMs. Strong EV adoption, with over 918,500 EV sales in the U.S. in 2022 as per the Department of Energy.
Europe Market Analysis
Europe thermal interface materials (TIMs) market growth is expected to grow with its aggressive EV policies and renewable energy adoption. TIMs play an important role in ensuring battery performance and safety under EU-mandated sustainability frameworks. Additionally, Europe’s high investment in wind and solar inverters creates non-traditional growth opportunities for TIM applications.
Latin America Market Analysis
Latin America thermal interface materials (TIMs) market growth is likely to grow with Brazil and Mexico serving as focal points due to expanding automotive production. The penetration of EVs is still nascent but rising, supported by government initiatives to decarbonize transport.
Middle East & Africa Market Analysis
The Middle East & Africa thermal interface materials (TIMs) market growth is likely to grow with demand linked to expanding telecom infrastructure and rising consumer electronics penetration.
COMPETITIVE LANDSCAPE
KEY MARKET PLAYERS
Some of the key players dominating the global thermal interface materials market are
- Henkel Corporation
- Dow Corning Corporation (now Dow, Inc.)
- 3M Company
- Bergquist Company
- Laird Technologies (now part of Renesas Electronics Corporation)
- Shin-Etsu Chemical Co., Ltd.
- Momentive Performance Materials Inc.
- Parker Hannifin Corporation
- Wakefield-Vette
- Zalman Tech Co., Ltd.
- Indium Corporation
- Panasonic Corporation
- Arctic Silver, Inc.
- Fujipoly America Corporation
- Master Bond Inc.
TOP STRATEGIES USED BY KEY MARKET PLAYERS
The leading players in the thermal interface materials market are employing a combination of innovation-driven and region-specific strategies to sustain their competitive edge. A central approach has been R&D investment aimed at producing higher conductivity, durable, and environmentally friendly TIMs tailored for electric vehicles, semiconductors, and renewable systems. Companies are also advancing localized manufacturing across Asia Pacific to minimize supply disruptions and respond to rising regional demand. Another key strategy is strategic partnerships with OEMs and technology companies, ensuring early-stage integration of TIM solutions into high-performance products.
COMPETITION OVERVIEW
The thermal interface materials market is marked by intense competition, fueled by rapid technological progress and increasing demand across electronics, automotive, and energy applications. Large multinational companies dominate with their broad product portfolios and global supply chains, but regional and niche manufacturers are steadily gaining traction by offering specialized solutions tailored to local market needs. The competition has intensified in Asia Pacific, where expanding EV adoption, semiconductor production, and 5G infrastructure are creating fertile ground for innovation. Players are competing not only on product performance but also on sustainability, cost efficiency, and supply security.
TOP PLAYERS IN THE MARKET
- Henkel has established itself as one of the most influential players in the thermal interface materials market, especially within Asia Pacific, where it supports electronics manufacturing hubs in China, South Korea, and Japan. The company’s LOCTITE brand of TIM solutions is widely adopted in consumer electronics and automotive systems, where high thermal reliability is also crucial. Henkel has strengthened its regional presence by investing in R&D centers in Shanghai and Bangalore, aiming to provide localized innovations for fast-growing EV and semiconductor industries.
- Parker Hannifin has a significant footprint in the Asia Pacific market, where its Chomerics division provides advanced thermal management solutions to leading automotive and telecom OEMs. The company’s TIM portfolio, including thermal gap fillers and pads, is particularly aligned with EV battery and power electronics requirements, which are expanding rapidly in China and Southeast Asia. Parker Hannifin has recently focused on developing high-conductivity materials for next-generation 5G infrastructure, an area of strong investment across Asia.
- Dow is a prominent global leader in silicone-based thermal interface materials, and its role in Asia Pacific is reinforced by partnerships with major electronics and automotive manufacturers. The company’s TIM solutions are widely used in semiconductors, consumer devices, and EV systems, where Dow leverages its silicone expertise to deliver consistent performance under extreme thermal loads. In 2022, Dow announced new expansions in South Korea and China to scale up advanced silicone TIM production, aligning with the region’s surging demand for semiconductor packaging.
Global Thermal Interface Materials Market News
- In January 2023, Henkel Thermal interface materials market launched a new high-performance silicone-free thermal pad for automotive electronics. This Thermal interface materials market innovation was designed to improve EV battery safety and durability.
MARKET SEGMENTATION
This research report on the global thermal interface materials market has been segmented and sub-segmented based on type, application, and region.
By Type
- Greases & Adhesives
- Tapes
- Gap Fillers
- Thermally conductive pad
- Phase Change Materials
- Metal thermal interface materials
By Application
- Telecom
- Computer
- Medical Devices
- Industrial Machinery
- Consumer Durables
- Automotive Electronics
- Others
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa