- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$14.28 BnMarket Estimate, 2026
$16.82 BnMarket Forecast, 2034
$62.38 BnCAGR, 2026–2034
17.80%Executive Summary: Traction Inverter Market
- Market Scope: Comprehensive global traction inverter market analysis covering vehicle types, powertrain applications, regional leadership frameworks, silicon carbide (SiC) integration, and electrification drivers.
- Market Valuation: Valued at USD 14.28 billion (2025), estimated at USD 16.82 billion (2026), and projected to reach USD 62.38 billion by 2034, registering a strong CAGR of 17.8% (2026–2034).
- Primary Growth Drivers: Stringent emission regulations, government EV incentives, expanding charging infrastructure, and the adoption of high-efficiency silicon carbide (SiC) designs to reduce switching losses.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Vehicle Type & End-User | Battery Electric Vehicles (BEVs) (maximum market share) & Automotive Manufacturers (largest end-user) | Passenger Cars (growing at an elevated rate due to rising global EV demand) |
| By Regional Leadership | North America (dominates regionally due to strong EV policies and commercial fleet electrification) | Asia-Pacific (emerges as fastest-growing region supported by aggressive government mandates in China, South Korea, and India) |
Major Market Players & Market Structure
Market Structure: Highly competitive global automotive semiconductor and power electronics landscape featuring major technology suppliers competing on SiC MOSFET integration, scalable power modules, and real-time control solutions.
Key Companies: Siemens AG, Infineon Technologies AG, Continental AG, Robert Bosch GmbH, Delphi Technologies, Hitachi Automotive Systems, Mitsubishi Electric Corporation, Toshiba Corporation, Fuji Electric Co. Ltd., ABB Ltd, Dana Incorporated, Lear Corporation, Texas Instruments Incorporated, STMicroelectronics, and ON Semiconductor.
 Download Free Sample Report
Global Traction Inverter Market Size
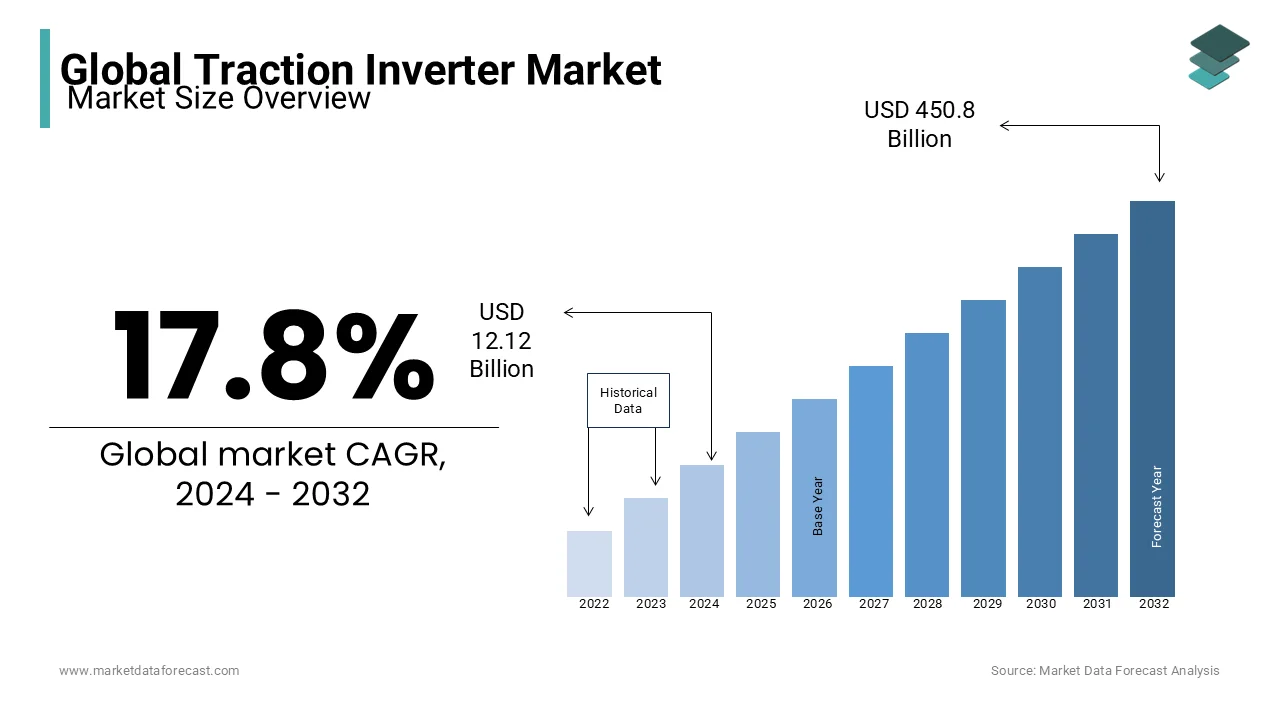
The global traction inverter market size was valued at USD 14.28 billion in 2025 and is anticipated to reach a valuation of USD 16.82 billion in 2026 and USD 62.38 billion by 2034, growing at a CAGR of 17.8%, from 2026 to 2034.
Introduction and Definition
The traction Inverter Market encompasses power electronic devices that convert direct current from batteries into alternating current to drive electric motors in vehicles and railway systems. These inverters regulate motor speed and torque ensuring efficient propulsion and regenerative braking capabilities for sustainable transportation solutions. According to the International Energy Agency transport sector accounts for 24 percent of global energy related carbon dioxide emissions which directly correlates with the urgent need for electrified mobility solutions relying on advanced traction inverters. As per the United Nations Conference on Trade and Development urban areas generate 70 percent of global greenhouse gas emissions necessitating widespread adoption of zero emission public transit systems equipped with high efficiency power conversion units. The integration of wide bandgap semiconductors and sophisticated control algorithms has transformed traditional power electronics into compact intelligent modules capable of handling extreme thermal and electrical stresses. This technological evolution supports automotive manufacturers in achieving extended driving ranges while maintaining robust performance under varying load conditions. The market serves passenger cars commercial vehicles and rail applications where demand for reliable and efficient power management continues to rise alongside global decarbonization initiatives and stringent emission regulations across developed and emerging economies worldwide.
MARKET DRIVERS
Surging Electric Vehicle Adoption Propels Demand
Surging electric vehicle adoption propels the Traction Inverter Market by creating massive volume requirements for power conversion systems that serve as the critical link between battery packs and propulsion motors in modern zero emission automobiles. Governments worldwide implement aggressive timelines for phasing out internal combustion engines prompting original equipment manufacturers to scale up electric vehicle production capacities rapidly to meet regulatory compliance and consumer demand. According to the International Energy Agency global electric car sales exceeded 14 million units in 2023 representing a significant milestone that drives corresponding demand for traction inverters capable of delivering high power density and thermal efficiency. As per the Society of Automotive Engineers each electric vehicle requires at least one sophisticated traction inverter unit meaning that every additional million vehicles sold translates directly into millions of power electronic modules entering the supply chain. These trends drive manufacturers to optimize inverter designs for cost reduction and manufacturing scalability while maintaining rigorous performance standards for safety and reliability. The shift toward platform based vehicle architectures allows automakers to standardize inverter specifications across multiple models achieving economies of scale that further reduce costs. Regulatory incentives such as tax credits and purchase subsidies lower barriers for consumers accelerating market penetration. Consequently the market benefits from predictable growth trajectories enabled by long term policy commitments allowing suppliers to invest in next generation semiconductor technologies and automated production facilities.
Expansion Of Public Rail Transit Systems Drives Integration
Expansion of public rail transit systems drives the Traction Inverter Market by generating substantial demand for heavy duty power conversion units required to operate electric trains trams and metro systems in growing urban centers globally. Municipalities invest heavily in sustainable mass transportation infrastructure to alleviate traffic congestion and reduce urban air pollution creating consistent procurement opportunities for specialized traction drive suppliers. According to the International Union of Railways global rail passenger traffic increased by 8 percent in 2023 as cities prioritize high capacity low emission transit options that rely on robust traction inverters for precise speed control and energy recovery during braking cycles. As per the American Public Transportation Association over 60 new light rail projects are currently in planning or construction phases in North America alone each requiring dozens of high power inverter modules for trainset propulsion and auxiliary power management. These infrastructure projects drive manufacturers to develop ruggedized inverters capable of withstanding harsh environmental conditions and continuous high load operations typical of public transit services. The longevity of rail assets ensures long term service contracts and replacement markets providing stable revenue streams for technology providers. Standardization efforts within the rail industry facilitate interoperability and reduce customization costs enabling suppliers to offer scalable solutions across different rolling stock types. Government funding for green transportation initiatives further accelerates deployment ensuring sustained market expansion through large scale public sector investments.
MARKET RESTRAINTS
High Manufacturing Costs Restrict Mass Market Penetration
High manufacturing costs restrict the Traction Inverter Market by creating significant price premiums for electric vehicles and rail systems that limit affordability and slow adoption rates among price sensitive consumer segments and budget constrained transit authorities. The complex nature of traction inverters requires expensive materials such as silicon carbide substrates copper windings and advanced cooling systems alongside precision assembly processes that demand specialized clean room environments and skilled labor. According to the BloombergNEF report traction inverters account for approximately 10 to 15 percent of total electric vehicle powertrain costs making them one of the most expensive single components after the battery pack itself. As per the Institute of Electrical and Electronics Engineers the cost of wide bandgap semiconductor modules remains 3 times higher than traditional silicon based alternatives limiting their widespread use despite superior efficiency and thermal performance characteristics. These financial constraints limit market penetration particularly in developing economies where purchasing power parity remains low and subsidies are insufficient to offset high initial vehicle prices. The requirement for rigorous testing and validation to meet automotive safety standards further escalates development expenses delaying time to market for new designs. While economies of scale are gradually reducing unit costs the pace of reduction lags behind consumer expectations for price parity with internal combustion vehicles. Consequently manufacturers face pressure to balance performance enhancements with cost containment strategies often compromising on feature sets or material quality to maintain competitive pricing structures.
Supply Chain Vulnerabilities Hamper Production Stability
Supply chain vulnerabilities hamper the Traction Inverter Market by disrupting availability of critical semiconductor components and rare earth materials leading to production delays inventory shortages and increased procurement costs for original equipment manufacturers. The concentration of semiconductor fabrication facilities in limited geographic regions combined with geopolitical tensions and trade restrictions has created persistent uncertainty in component sourcing forcing automotive and rail suppliers to maintain elevated safety stocks. According to the Semiconductor Industry Association lead times for automotive grade power modules exceeded 40 weeks during peak shortage periods causing widespread vehicle production halts and delayed rail project deliveries across major markets globally. As per the Resilinc Supply Chain Risk Management Index the automotive electronics sector experienced 45 percent more supply chain disruptions in 2023 compared to pre pandemic baselines highlighting systemic fragilities that continue to affect inverter production schedules and delivery commitments. These uncertainties necessitate conservative forecasting and dual sourcing strategies that tie up working capital and reduce operational flexibility for manufacturers already facing margin pressures from competitive bidding environments. Customers respond by qualifying multiple vendors and extending procurement cycles slowing overall market velocity and innovation adoption rates. Long term solutions require reshoring initiatives and strategic partnerships but near term volatility remains a significant constraint on market growth potential and customer satisfaction levels particularly for just in time manufacturing models.
MARKET OPPORTUNITIES
Adoption Of Wide Bandgap Semiconductors Creates Efficiency Gains
Adoption of wide bandgap semiconductors creates efficiency gains for the Traction Inverter Market by enabling higher switching frequencies reduced switching losses and improved thermal management that extend vehicle range and reduce cooling system complexity. Silicon carbide and gallium nitride materials offer superior electrical properties compared to traditional silicon allowing inverters to operate at higher voltages and temperatures without performance degradation or reliability issues. According to the United States Department of Energy silicon carbide based traction inverters can improve overall vehicle efficiency by 5 to 10 percent translating to significant range extensions or battery size reductions that lower total vehicle weight and cost. As per the Fraunhofer Institute for Integrated Systems and Device Technology wide bandgap devices reduce inverter volume by 30 percent while maintaining same power output enabling more compact packaging designs that free up space for additional battery capacity or passenger comfort features. This opportunity appeals to automotive manufacturers seeking competitive advantages through superior performance metrics and streamlined vehicle architectures that appeal to environmentally conscious consumers. Falling production costs for silicon carbide wafers due to improved crystal growth techniques make these technologies increasingly viable for mass market applications beyond premium segments. Regulatory push for higher efficiency standards further incentivizes adoption as manufacturers seek compliant solutions that avoid penalties. The ability to integrate passive components more effectively reduces bill of materials costs positioning wide bandgap inverters as key enablers of next generation electric mobility platforms.
Integration With Vehicle To Grid Technologies Opens New Revenue Streams
Integration with vehicle to grid technologies opens new revenue streams for the Traction Inverter Market by transforming electric vehicles into mobile energy storage units capable of supplying power back to the electrical grid during peak demand periods. Bidirectional traction inverters enable seamless energy flow between the vehicle battery and the grid supporting grid stability renewable energy integration and emergency backup power applications for homes and businesses. According to the National Renewable Energy Laboratory vehicle to grid capable inverters can provide ancillary services worth up to 1000 dollars annually per vehicle through participation in demand response programs and frequency regulation markets creating economic incentives for owners. As per the International Council on Clean Transportation bidirectional charging infrastructure is projected to grow at a compound annual growth rate of 25 percent through 2030 as utilities recognize the value of distributed storage resources managed through smart inverter controls. This convergence creates opportunities for specialized inverter designs featuring advanced communication protocols and grid synchronization capabilities that meet utility interconnection standards. Growing corporate commitments to energy resilience drive investment in fleet vehicles equipped with vehicle to grid functionality accelerating demand for compatible hardware. The ability to monetize idle battery capacity further enhances total cost of ownership calculations making electric vehicles more attractive to commercial fleet operators. Regulatory frameworks supporting peer to peer energy trading further expand market potential positioning inverters as critical interfaces in decentralized energy ecosystems.
MARKET CHALLENGES
Thermal Management Difficulties Challenge Performance Consistency
Thermal management difficulties challenge the Traction Inverter Market by limiting continuous power output and risking component damage due to heat buildup within compact housing units where space for cooling systems is severely restricted. High power density designs generate significant heat during rapid acceleration and regenerative braking cycles requiring sophisticated liquid cooling or advanced air flow mechanisms to maintain junction temperatures within safe operating limits. According to the IEEE Transactions on Power Electronics traction inverter junction temperatures can exceed 175 degrees Celsius during sustained high load operations causing a 15 percent decline in efficiency and accelerated aging of insulation materials if not properly managed. As per the Journal of Thermal Science and Engineering Applications passive cooling methods dissipate only 50 percent of generated heat effectively in compact automotive packages requiring active liquid cooling loops that add weight complexity and potential leak points to the vehicle architecture. These thermal constraints force designers to oversize components or derate power outputs resulting in heavier and bulkier units that negate some efficiency benefits of advanced semiconductor technologies. The challenge intensifies in high performance vehicles where repeated high power bursts create thermal cycling stress that leads to solder joint fatigue and eventual failure. Developing compact yet effective cooling systems remains a significant engineering hurdle that limits power density scalability and restricts application in space constrained vehicle platforms where every cubic centimeter matters for overall design optimization.
Electromagnetic Interference Issues Pose Compliance Risks
Electromagnetic interference issues pose compliance risks for the Traction Inverter Market by generating high frequency noise that disrupts sensitive onboard electronics communication systems and nearby infrastructure requiring extensive shielding and filtering measures. Rapid switching of high voltage currents in traction inverters produces electromagnetic emissions that can interfere with radio frequency signals sensor accuracy and vehicle to vehicle communication protocols essential for autonomous driving functions. According to the International Electrotechnical Commission automotive electronic systems must comply with strict electromagnetic compatibility standards such as CISPR 25 which mandate emission limits that are increasingly difficult to meet as switching frequencies rise above 100 kilohertz for efficiency gains. As per the Society of Automotive Engineers electromagnetic interference related failures account for 20 percent of warranty claims in electric vehicles highlighting the critical importance of robust design practices and thorough testing protocols during development phases. These compliance challenges require substantial investments in shielded cabling ferrite cores and filter components that increase bill of materials costs and assembly complexity for manufacturers. Failure to meet regulatory standards can result in vehicle recall campaigns and brand reputation damage creating liability concerns that deter some stakeholders from pursuing aggressive performance targets. Addressing these challenges requires ongoing simulation specialized testing facilities and collaboration with electromagnetic compatibility experts adding time and cost to product development cycles while limiting design flexibility for compact packaging solutions.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 17.8% |
| Segments Covered | By Vehicle Type, Electric Vehicle Type, End-User Type, and Region. |
|
Various Analyses Covered | Global, Regional, & Country Level Analysis; Segment-Level Analysis; DROC, PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Siemens AG, Infineon Technologies AG, Continental AG, Robert Bosch GmbH, Delphi Technologies, Hitachi Automotive Systems, Mitsubishi Electric Corporation, Toshiba Corporation, Fuji Electric Co., Ltd., ABB Ltd, Dana Incorporated, Lear Corporation, Texas Instruments Incorporated, STMicroelectronics, ON Semiconductor |
SEGMENT ANALYSIS
By Vehicle Insights
Passenger Cars Lead Market Dominance Through Volume
Passenger cars hold the leading position in the Traction Inverter Market due to massive production volumes driven by global consumer transition toward personal electric mobility and stringent emission regulations targeting light duty vehicles. Original equipment manufacturers prioritize passenger car electrification to meet regulatory mandates and capture growing consumer demand for zero emission transportation options that offer lower operating costs and enhanced driving experiences. According to the International Energy Agency battery electric passenger car sales reached 9.5 million units in 2023 representing over 60 percent of total electric vehicle sales globally which directly translates into substantial demand for compact and efficient traction inverters. As per the Society of Automotive Engineers over 80 percent of new passenger car platforms launched by major automakers are designed exclusively for electric powertrains requiring integrated inverter motor and gearbox units that optimize space and weight distribution. The domination stems from the sheer scale of the passenger vehicle segment compared to commercial or two wheeler markets ensuring consistent high volume orders for inverter suppliers. Economies of scale in manufacturing allow producers to reduce unit costs making advanced silicon carbide technologies increasingly accessible for mid range vehicles. Government incentives such as tax credits and purchase subsidies further accelerate adoption rates among individual consumers. The rapid iteration of passenger car models drives continuous innovation in inverter design focusing on higher power density and improved thermal management to extend driving range and reduce charging times for everyday users.
Commercial Vehicles Exhibit Fastest Growth Trajectory
Commercial vehicles exhibit the fastest growth trajectory in the Traction Inverter Market fueled by rising e commerce logistics demands urban delivery regulations and corporate sustainability commitments that necessitate fleet electrification for last mile and medium duty operations. Logistics companies and municipal authorities increasingly replace diesel trucks vans and buses with electric alternatives to reduce operational costs and comply with low emission zone restrictions in major metropolitan areas worldwide. According to the International Council on Clean Transportation electric commercial vehicle sales are projected to grow at a compound annual growth rate of 28 percent through 2030 as total cost of ownership advantages become more pronounced with falling battery prices and rising fuel costs. As per the American Trucking Associations over 40 percent of large fleet operators have announced plans to electrify at least half of their delivery vehicles by 2030 creating substantial procurement opportunities for heavy duty traction inverters capable of handling high torque and continuous load requirements. The rapid growth accelerates through government grants and subsidies specifically targeting commercial fleet conversions which offset higher initial purchase prices. Technological advancements in high voltage architectures enable faster charging and longer ranges making electric commercial vehicles viable for broader operational scenarios. The need for robust and durable inverters that withstand frequent stop start cycles and heavy payloads drives specialized product development. Regulatory pressures to decarbonize public transport further stimulate demand for electric buses equipped with high power traction systems.
By End-User Insights
Original Equipment Manufacturers Dominate Through Direct Integration
Original equipment manufacturers dominate the Traction Inverter Market end user type by accounting for the majority of unit volumes through direct supply agreements with automotive and rail vehicle producers who integrate inverters into new products during assembly lines. This channel benefits from large scale procurement contracts standardized specifications and long term partnerships that ensure consistent revenue streams for inverter suppliers while providing OEMs with quality assurance and technical support. According to the International Organization of Motor Vehicle Manufacturers over 75 percent of electric vehicle production globally utilizes traction inverters sourced directly from specialized component suppliers rather than aftermarket modifications reflecting the industry shift toward factory integrated electrification. As per the China Association of Automobile Manufacturers original equipment shipments reached 8 million units in 2023 demonstrating the massive scale of manufacturing operations that rely on established supply chains for timely delivery and cost competitive pricing structures. The leadership position results from the complexity of integrating inverters with vehicle batteries motors and thermal systems which requires engineering collaboration best achieved during initial design phases rather than retrofits. OEMs prioritize reliability and warranty coverage which direct supplier relationships facilitate through rigorous testing protocols and joint development initiatives. Economies of scale in manufacturing allow OEM channels to offer lower per unit costs compared to fragmented aftermarket sales enabling competitive retail pricing for end consumers. Regulatory certification processes are streamlined when components are approved as part of complete vehicle systems reducing time to market for new models.
Aftermarket Segment Grows Through Retrofitting Demand
The Aftermarket segment grows rapidly in the Traction Inverter Market driven by increasing interest in converting existing internal combustion vehicles to electric power and replacing failed units in aging electric fleets where original parts may be discontinued or expensive. This channel serves specialized conversion shops independent repair facilities and fleet managers who seek cost effective solutions to extend vehicle lifespan or customize performance characteristics without purchasing new vehicles. According to the Automotive Aftermarket Suppliers Association the global automotive aftermarket is expected to reach 1.5 trillion dollars by 2027 with electric vehicle components including traction inverters representing a fast emerging category as early generation EVs enter maintenance phases. As per the Electric Vehicle Conversion Association conversion kit sales including inverters increased by 35 percent annually as enthusiasts and small businesses seek affordable ways to electrify classic cars and light commercial vehicles amidst economic uncertainties. The rapid growth accelerates through online platforms and community forums that share installation guides and compatibility data lowering barriers to entry for non technical users. Availability of universal fitment kits simplifies selection processes while competitive pricing makes replacements attractive for extending asset life. Regulatory gray areas in some regions permit aftermarket modifications that attract performance oriented users seeking higher power outputs than factory limits. Expanding product ranges include refurbished and remanufactured inverters catering to budget conscious segments and supporting circular economy principles through component reuse.
REGION ANALYSIS
North America Maintains Strong Position Through Policy Support
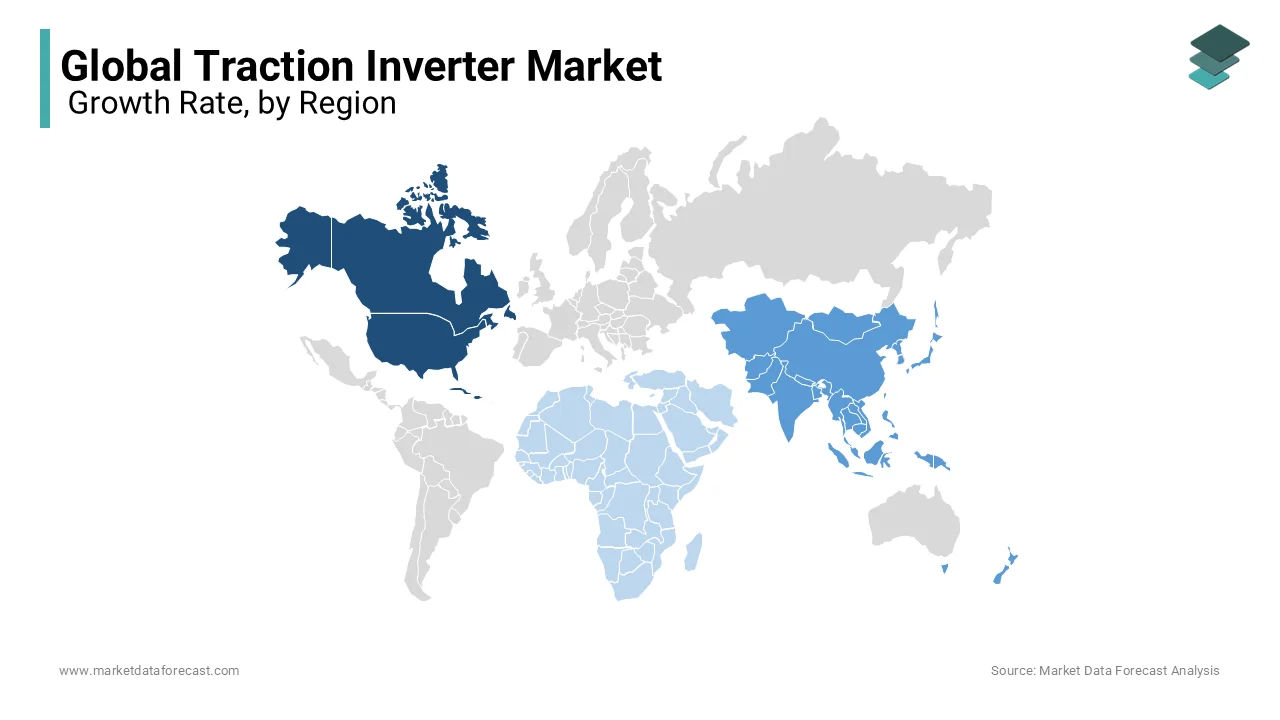
North America maintains a strong position in the Traction Inverter Market supported by favorable regulatory frameworks substantial federal investments in electric vehicle infrastructure and robust domestic manufacturing initiatives aimed at securing supply chain independence. The United States and Canada lead implementation efforts through policies such as the Inflation Reduction Act which provides tax credits for electric vehicles and components manufactured locally stimulating demand for domestically produced traction inverters. According to the United States Department of Energy federal funding allocated 7.5 billion dollars for electric vehicle charging networks which indirectly supports inverter adoption by alleviating range anxiety and encouraging consumer uptake of electric passenger and commercial vehicles. As per Statistics Canada electric vehicle registrations increased by 45 percent in 2023 reflecting growing consumer interest in eco friendly transportation options that utilize advanced power electronics for efficient propulsion and energy recovery. Strict safety and efficiency standards enforced by regulatory bodies ensure high quality components enter the market building consumer trust in reliability and performance. Major automotive manufacturers establish new battery and inverter production facilities in the region to qualify for incentives reducing dependency on overseas supplies. Growing corporate sustainability initiatives encourage fleet electrification further expanding market reach. Innovation hubs in Silicon Valley and Detroit foster technological advancements in wide bandgap semiconductors keeping the region at the forefront of product development trends.
Europe Leads Adoption Through Environmental Mandates
Europe leads adoption in the Traction Inverter Market driven by stringent environmental regulations ambitious carbon neutrality goals and comprehensive bans on internal combustion engine sales that mandate rapid transition to electric mobility across member states. Countries such as Germany France and Norway implement aggressive policies promoting zero emission vehicles including subsidies tax exemptions and extensive charging infrastructure that facilitate widespread electric vehicle usage. According to the European Automobile Manufacturers Association electric car registrations accounted for 21 percent of total new car sales in 2023 with traction inverters being critical components for meeting strict CO2 emission targets imposed by the European Union. As per the German Federal Ministry for Economic Affairs and Energy government incentives reduced average consumer cost for electric vehicles by 15 percent accelerating market penetration among middle income households seeking affordable sustainable transport alternatives. Strong emphasis on circular economy principles drives demand for durable and recyclable inverter designs that align with sustainability values prevalent among European consumers. Established manufacturing bases in Eastern Europe provide cost competitive production capabilities while maintaining high quality standards required by Western markets. Cross border trade within the European Union facilitates efficient supply chain operations and standardized certification processes reducing barriers for market entry and expansion.
Asia Pacific Dominates Production And Consumption
Asia Pacific dominates production and consumption in the Traction Inverter Market fueled by massive manufacturing capabilities in China rapid urbanization in Southeast Asia and strong government support for electric mobility solutions across India Japan and South Korea. The region accounts for over 60 percent of global traction inverter production due to concentrated supply chains for semiconductors magnets and electronic components enabling cost competitive manufacturing at scale. According to the China Association of Automobile Manufacturers domestic electric vehicle production exceeded 9 million units in 2023 with traction inverters being essential components for majority of models targeting both domestic and export markets. As per the Ministry of Heavy Industries India electric two wheeler and three wheeler registrations grew by 50 percent year over year driven by state level subsidies and rising fuel prices making affordable electric mobility attractive for daily commuters. Rapid infrastructure development in emerging economies creates demand for electric buses and commercial vehicles utilizing robust traction systems capable of handling varied road conditions. Increasing environmental awareness among younger demographics drives adoption of shared mobility services featuring electric vehicles. Local manufacturers innovate rapidly to meet diverse regional requirements ranging from compact city cars to heavy duty trucks ensuring broad market coverage and sustained growth momentum.
Latin America Shows Emerging Potential Through Urbanization
Latin America shows emerging potential in the Traction Inverter Market as rapid urbanization rising fuel costs and increasing environmental consciousness drive interest in affordable electric mobility solutions particularly in Brazil Mexico and Colombia. The region faces significant traffic congestion and air quality challenges prompting municipal authorities to explore electric public transport and micro mobility as part of broader urban planning strategies aimed at improving livability. According to the Inter American Development Bank investment in sustainable urban transport projects in Latin America reached 2 billion dollars in 2023 supporting infrastructure development that facilitates electric bus and taxi usage in major cities. As per the Brazilian Association of Electric Mobility electric vehicle sales increased by 40 percent in 2023 indicating growing consumer acceptance of electric vehicles powered by efficient traction inverters as practical alternatives to congested public transport and expensive car ownership. Economic constraints favor cost effective inverter designs that balance performance and affordability making them accessible to broader population segments. Local assembly operations begin to emerge reducing import dependencies and lowering final prices for consumers. Government pilot programs for electric public transit introduce citizens to benefits of electric travel creating future demand pipelines. Improving internet connectivity enables digital fleet management platforms to expand services further stimulating market growth through increased visibility and accessibility.
Middle East And Africa Gradually Expands Through Diversification
The Middle East and Africa gradually expands in the Traction Inverter Market driven by economic diversification initiatives smart city developments and increasing focus on sustainable transportation in key markets such as United Arab Emirates Saudi Arabia and South Africa. Wealthy Gulf nations invest heavily in futuristic urban projects incorporating electric mobility as core components of modern infrastructure aiming to reduce carbon footprints and enhance visitor experiences. According to the Saudi Arabian Ministry of Investment electric mobility initiatives are central to Vision 2030 goals with significant allocations for local manufacturing of electric vehicle components including traction inverters to build domestic industrial capacity. As per the South African Department of Transport pilot programs for electric bus fleets in Cape Town demonstrated operational feasibility highlighting potential for broader adoption if infrastructure and affordability challenges are addressed. Extreme climate conditions necessitate robust inverter designs with effective thermal management creating niche opportunities for specialized suppliers capable of delivering reliable performance in high temperature environments. Limited local manufacturing means reliance on imports however growing distributor networks improve availability and after sales support. Rising electricity costs compared to subsidized fuel slow mass adoption but corporate sustainability goals drive fleet conversions for hospitality and logistics sectors. Regional exhibitions promote awareness and facilitate connections between international suppliers and local buyers accelerating market maturation.
KEY MARKET PLAYERS
Some of the major market players are involved in the global traction inverter market.
- Siemens AG
- Infineon Technologies AG
- Continental AG
- Robert Bosch GmbH
- Delphi Technologies
- Hitachi Automotive Systems
- Mitsubishi Electric Corporation
- Toshiba Corporation
- Fuji Electric Co., Ltd.
- ABB Ltd
- Dana Incorporated
- Lear Corporation
- Texas Instruments Incorporated
- STMicroelectronics
- ON Semiconductor
Top Players In The Market
- BorgWarner Inc strengthens its position through comprehensive power electronics portfolios that integrate traction inverters with motors and gearboxes for optimized electric vehicle performance. The company recently expanded its manufacturing footprint in Europe and Asia to support global original equipment manufacturers with localized supply chains and reduced logistics costs. BorgWarner focuses on silicon carbide technology integration enabling higher efficiency and power density in compact packages suitable for diverse vehicle architectures. Their commitment to sustainability drives innovation in lightweight materials and recyclable components helping clients achieve environmental targets. The organization leverages extensive automotive experience to deliver robust solutions capable of withstanding extreme thermal and mechanical stresses. Continuous investment in research and development ensures compatibility with emerging high voltage platforms facilitating seamless integration into next generation electric drivetrains. BorgWarner collaborates with semiconductor suppliers to secure critical component availability supporting consistent production volumes and timely delivery schedules for international customers.
- Denso Corporation contributes significantly by offering advanced traction inverter systems under its electrification division focusing on reliability efficiency and compact design for hybrid and battery electric vehicles. The company introduced enhanced cooling technologies that enable sustained high power operation without thermal degradation addressing critical performance limitations in demanding driving conditions. Denso emphasizes vertical integration controlling key production processes from chip packaging to final assembly which ensures strict quality control and rapid response to custom engineering requirements. Their strategic initiatives include expanding service networks in emerging markets providing technical support and spare parts availability that enhance customer confidence. The organization actively participates in industry standardization efforts promoting interoperability and safety protocols that benefit the broader ecosystem. Denso invests in automated manufacturing lines increasing production efficiency and consistency while reducing labor costs associated with complex electronics assembly. Their focus on durability appeals to commercial fleet operators prioritizing low maintenance and long operational lifespans for total cost of ownership optimization.
- Hitachi Ltd advances the market through innovative traction inverter designs targeting both automotive and railway applications where extreme reliability and energy efficiency are essential. The company recently launched a new series of silicon carbide based inverters capable of delivering exceptional acceleration and regenerative braking performance for high speed trains and electric buses. Hitachi prioritizes customization offering tailored solutions for niche markets including heavy duty trucks and specialized industrial vehicles that require specific power characteristics. Their strategic partnerships with battery manufacturers ensure optimal system integration maximizing energy efficiency and range performance for end users. The organization supports global distributors with comprehensive training programs and marketing materials enhancing local sales capabilities and technical expertise. Hitachi invests heavily in testing facilities validating product performance under extreme conditions ensuring reliability and safety for high stress applications. Their reputation for engineering excellence attracts transit authorities and automotive manufacturers seeking premium propulsion systems that deliver uncompromising performance in challenging environments.
Top Strategies Used By Key Market Participants
Technology leadership remains a primary strategy where companies invest heavily in silicon carbide and gallium nitride semiconductors to achieve superior efficiency and power density advantages. Vertical integration allows firms to control critical component production such as power modules and controllers reducing dependency on external suppliers and improving cost structures. Geographic expansion targets emerging markets with growing electric mobility adoption providing new revenue streams beyond saturated developed regions with stable but slower growth rates. Strategic collaborations with automotive original equipment manufacturers create integrated powertrain solutions that offer optimized performance and simplified procurement for vehicle producers. Customization capabilities enable vendors to serve niche segments with specific torque speed or dimensional requirements creating high value propositions that command premium pricing. Investment in automated manufacturing enhances production consistency and scalability allowing rapid response to fluctuating demand volumes while maintaining quality standards. Sustainability initiatives focus on recyclable materials and energy efficient production processes aligning with global environmental regulations and corporate social responsibility goals. Intellectual property protection through patents safeguards innovative designs and manufacturing techniques preventing imitation and maintaining competitive advantages in key technological areas.
RECENT HAPPENINGS IN THE MARKET
- In May 2024, BorgWarner Inc opened a new manufacturing facility in Hungary to expand production capacity for silicon carbide traction inverters and serve European clients more efficiently. This expansion is anticipated to allow BorgWarner to reduce supply chain risks and strengthen the Traction Inverter Market.
- In August 2023, Denso Corporation launched a new series of compact traction inverters featuring advanced liquid cooling technologies designed for high performance electric vehicles. This launch is anticipated to allow Denso to address thermal management challenges and strengthen the Traction Inverter Market.
- In February 2024, Hitachi Ltd partnered with a leading semiconductor manufacturer to develop next generation silicon carbide modules for railway and automotive applications. This partnership is anticipated to allow Hitachi to offer optimized system performance and strengthen the Traction Inverter Market.
- In November 2023, Infineon Technologies AG introduced an updated line of high power traction inverter modules featuring improved switching efficiency for electric commercial vehicles. This introduction is anticipated to allow Infineon to improve product reliability and strengthen the Traction Inverter Market.
- In June 2024, Mitsubishi Electric Corporation acquired a specialized software firm to enhance smart connectivity and predictive maintenance features in their inverter systems. This acquisition is anticipated to allow Mitsubishi Electric to offer advanced digital integration and strengthen the Traction Inverter Market.
MARKET SEGMENTATION
This research report on the global traction inverter market is segmented and sub-segmented into the following categories.
By Vehicle Type
- Passenger Cars
- Commercial Vehicles
- Two-Wheelers
By Electric Vehicle Type
- Battery Electric Vehicles (BEVs)
- Plug-in Hybrid Electric Vehicles (PHEVs)
- Hybrid Electric Vehicles (HEVs)
By End-User Type
- Automotive Manufacturers
- Aftermarket Suppliers
- OEMs (Original Equipment Manufacturers)
By Region
- North America
- Asia Pacific
- Europe
- Latin America
- Middle East & Africa