- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$376.59 MnMarket Estimate, 2026
$419.52 MnMarket Forecast, 2034
$995.03 MnCAGR, 2026–2034
11.40%Executive Summary: Global Agricultural Enzymes Market
- Market Scope: Comprehensive global analysis covering product types, enzyme types, crop applications, and regional landscapes spanning North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa.
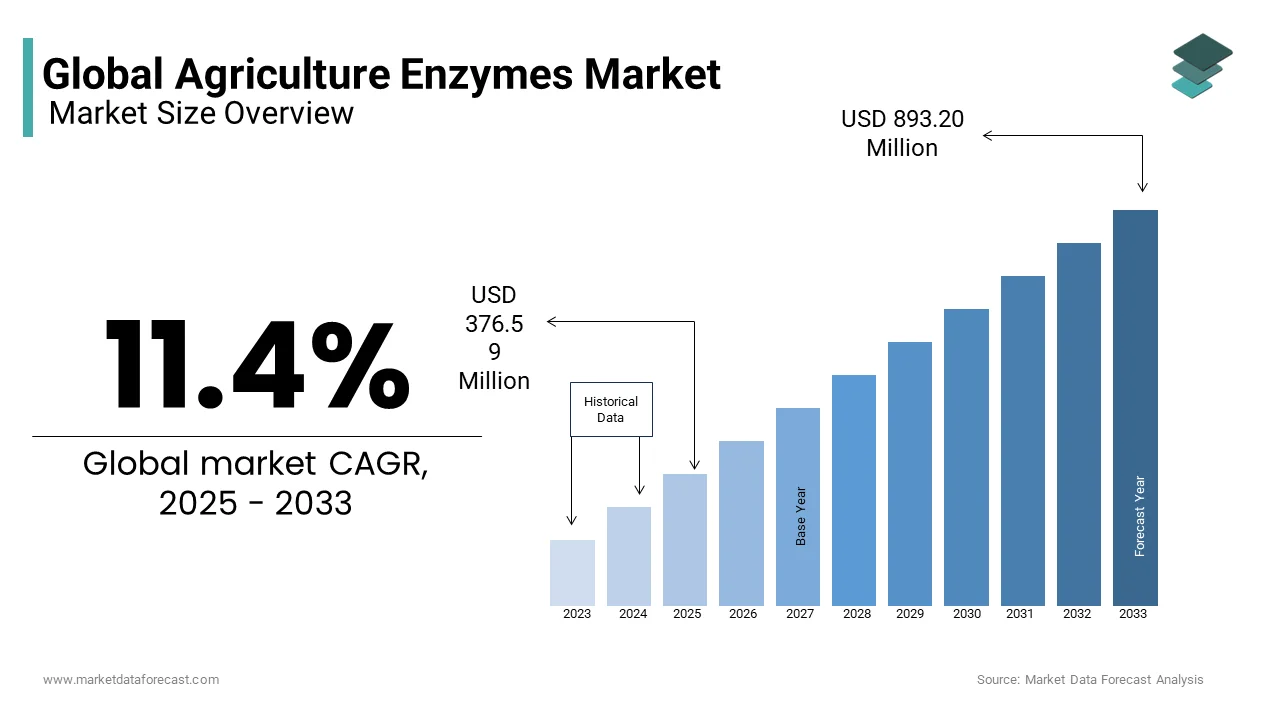
- Market Valuation: Valued at USD 376.59 million in 2025, estimated at USD 419.52 million in 2026, and projected to reach USD 995.03 million by 2034, registering a compound annual growth rate (CAGR) of 11.4% during the forecast period from 2026 to 2034.
- Primary Growth Drivers: Escalating global adoption of organic farming and natural food preferences; rising fertilizer costs driving a shift toward cost-effective, bio-degradable catalytic inputs; and heavy R&D investments by key players to boost crop production yields in arable lands. Key restraints include high R&D costs, strict biological regulations, and initial farmer hesitancy toward microbe-derived options.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment | Fastest-Growing Segment |
|---|---|---|
| By Type / Enzyme Type | Phosphatases (widely used for eliminating phosphate groups from proteins and solubilizing soil mineral elements) | Phosphatases & Dehydrogenases (sustained by robust demand for enhanced soil nutrient bio-availability) |
| By Crop Type | Cereals & Grains (held the largest market share due to massive global dietary demands and heavy use in rice cultivation) | Fruits & Vegetables (propelled by surging demand for organic produce with high nutritional value) |
| By Product Type | Soil Fertility Products (vital for reversing sharp drops in natural soil vitality and boosting nutrient uptake) | Soil Fertility Products (anticipated to experience the highest growth spike alongside growth-enhancing formulations) |
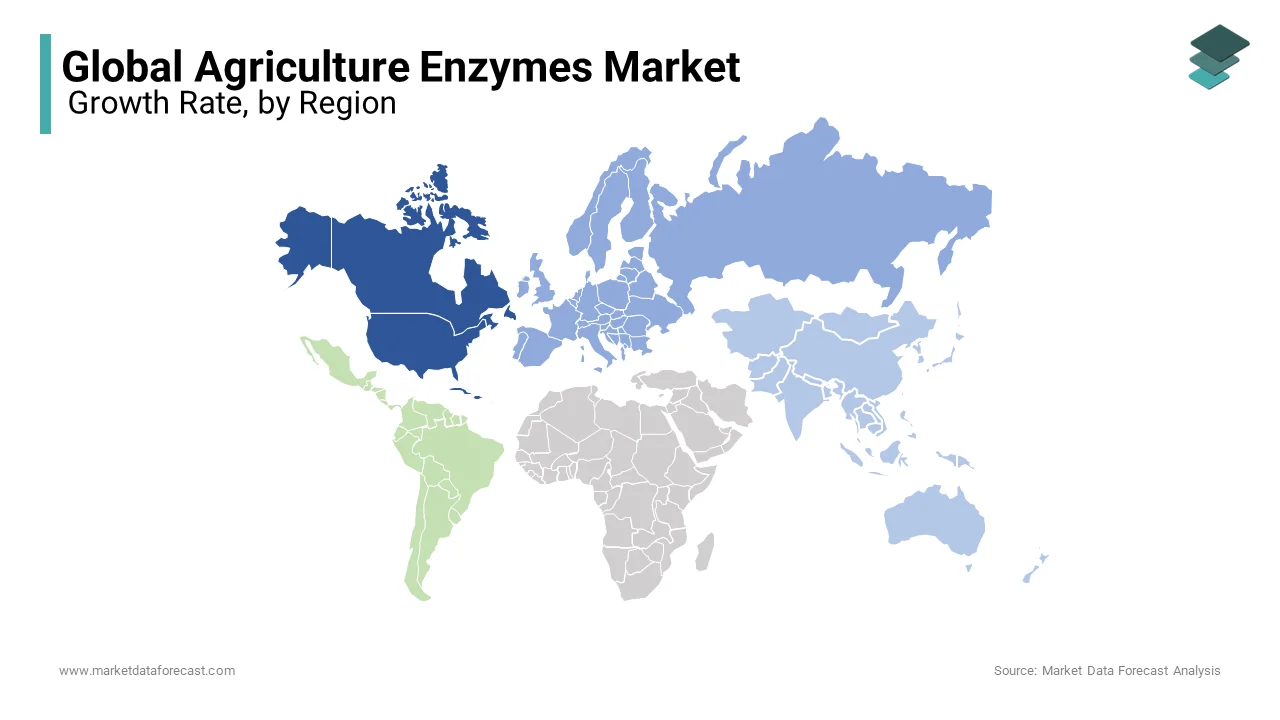
| By Region | North America (dominated via advanced ag-tech infrastructure, high awareness, and extensive biological investments) | Asia-Pacific (projected to register the highest CAGR driven by rapid organic farming transition and technological adoption) |
Major Market Players & Market Structure
Market Structure: Marked by intense competition where market leaders channel substantial investments into R&D initiatives, cost-effective enzyme engineering, and strategic bio-industrial partnerships (such as recent collaborations between Biotalys and Novozymes).
Key Companies: Novozymes, Agrinos, Agrilife, Stoller USA, Inc., BioWorks Inc., Syngenta AG, Aries Agro Limited, GreenMax AgroTech, Camson Bio Technologies Limited, Valmont Industries, Aum Enzymes, Cypher Environmental, DuPont, Deepak Fertilizers and Petrochemicals, Chr. Hansen Holding A/S, Amano Enzyme Inc., Aumgene Biosciences, Megazyme Ltd., and Enzyme Supplies Limited.
Global Agricultural Enzymes Market Size
The global agricultural enzymes market size was valued at USD 376.59 million in 2025 and it is anticipated to reach a valuation of USD 419.52 million in 2026, and USD 995.03 million by 2034, growing at a CAGR of 11.4%, from 2026 to 2034.
Introduction and Market Definition
Agricultural enzymes are specialised proteins that act as biological helpers to speed up chemical reactions in soil and plants. These specialised proteins accelerate biochemical reactions in the soil, facilitating the breakdown of organic matter and unlocking essential nutrients such as nitrogen, phosphorus, and potassium for plant uptake. As per the Food and Agriculture Organization of the United Nations, approximately 33% of global soils are moderately to highly degraded due to erosion, salinization, and chemical overuse, creating an urgent need for restorative agricultural inputs. Enzymes offer a sustainable solution by improving soil structure and microbial activity, which are critical for long-term fertility. According to the International Fertilizer Association, conventional fertilizer use efficiency remains below 50 percent in many major cropping systems, leading to significant economic losses and environmental pollution. The integration of enzymatic solutions helps bridge this efficiency gap by optimising nutrient release patterns. Furthermore, the growing regulatory pressure to reduce chemical residues in food and water sources drives adoption among commercial farmers seeking compliance with stringent environmental standards. This market is not merely about yield enhancement but revolves around restoring ecological balance in agricultural ecosystems, ensuring that intensive farming practices can continue sustainably while meeting the food demands of a growing global population. As per the United Nations Department of Economic and Social Affairs, the global human population is expanding and projected to reach approximately 9.7 billion by 2050, accelerating global food demand and the industrial consumption of biochemical yield-enhancers.
MARKET DRIVERS
Global Shift Toward Sustainable Farming Practices Accelerates Enzyme Adoption
The escalating global commitment to sustainable agriculture serves as a primary driver for the Agricultural Enzymes Market. Farmers and policymakers are seeking alternatives to chemical-intensive farming methods that degrade soil health. According to the European Commission, the Farm to Fork Strategy aims to reduce chemical pesticide use by 50% and fertilizer use by 20% by 2030, directly incentivizing the adoption of biological solutions such as enzymes that enhance nutrient efficiency without environmental harm. The regulatory push creates a favorable environment for enzyme manufacturers who provide tools to maintain productivity while lowering chemical dependency. As per the United States Department of Agriculture, conservation tillage practices, including no-till and reduced tillage, have expanded to cover major shares of cropland, such as 69% of wheat acreage and nearly 50% of corn, soybean, wheat, and cotton acreage combined, demonstrating a structural shift in farming techniques that favour biological inputs. Enzymes play a crucial role in these systems by accelerating the decomposition of organic matter, thereby releasing nutrients locked in plant debris and improving soil carbon sequestration. The alignment of enzymatic solutions with carbon farming initiatives further boosts their appeal, as healthy soils with high microbial activity are recognised as vital carbon sinks. Consequently, the drive to meet sustainability targets and restore soil vitality is transforming enzymes from niche additives into essential components of modern agronomic protocols, driving consistent demand across major agricultural regions.
Rising Demand for Organic Produce and Residue-Free Food Safety
The surging consumer preference for organic and residue-free food products is significantly propelling the growth of the Agricultural Enzymes Market. Producers are seeking effective biological tools to maintain crop health and yield without synthetic chemicals. According to the Organic Trade Association, sales of organic food and non-food products in the United States reached a record high of 61.9 billion USD during the 2020 market surge, reflecting a robust and expanding market that requires certified organic inputs for production. Enzymes are approved for use in organic farming systems because they are natural biological catalysts that do not leave harmful residues, making them ideal for growers aiming to meet strict organic certification standards. As per the Research Institute of Organic Agriculture, the global area under organic management has increased to over 76 million hectares according to consolidated global survey datasets, creating a vast addressable market for compliant soil enhancers and bio stimulants. The ability of enzymes to improve nutrient uptake efficiency allows organic farmers to compete with conventional yields while maintaining soil biodiversity. Furthermore, increasing awareness of the health risks associated with pesticide residues in conventional produce drives mainstream farmers to adopt integrated pest and nutrient management strategies that include enzymatic treatments. This transition is not limited to niche markets but is becoming a mainstream requirement for accessing premium retail channels. Hence, the economic incentive to produce high-value organic crops ensures sustained investment in enzymatic technologies that support clean and sustainable production methods.
MARKET RESTRAINTS
High Production Costs and Complex Formulation Challenges Limit Accessibility
The substantial cost associated with the production and stabilization of these enzymes is a major impediment to the agricultural enzymes market. This limits their widespread adoption among price-sensitive smallholder farmers who dominate agriculture in developing regions. According to the International Fund for Agricultural Development, smallholder farmers produce approximately 80% of the food consumed in sub-Saharan Africa and Asia but often operate on marginal profits that restrict their capacity to invest in premium-priced biological inputs. The complex fermentation processes required to produce high-purity enzymes involve significant energy and resource investments, resulting in higher end user prices compared to conventional synthetic fertilizers. As per the Journal of Industrial Microbiology and Biotechnology, downstream processing and stabilization of enzymes to guarantee shelf life and field performance account for up to 60% of total production costs, setting up an industrial barrier to competitive retail pricing. Additionally, enzymes are sensitive to environmental conditions such as temperature and pH, requiring sophisticated formulation technologies to protect their activity during storage and application. This technical complexity increases manufacturing expenses and limits the availability of robust, cost effective products suitable for diverse agricultural environments. Without economies of scale or government subsidies, the high initial cost prevents many farmers from transitioning to enzymatic solutions, despite their long-term benefits. This financial constraint restricts market penetration to larger commercial operations, leaving a significant portion of the global agricultural sector unable to access these advanced biological tools.
Lack of Awareness and Technical Knowledge Among Traditional Farmers
A pervasive lack of awareness and technical understanding regarding the mechanism and benefits of these enzymes hinders the growth of the agricultural enzymes market. This trend is particularly visible in regions where traditional farming practices are deeply entrenched. According to the World Bank, public agricultural extension services face persistent structural bottlenecks in developing nations, prompting an active transition toward digital channels to overcome the steep knowledge gaps associated with modern bio-inputs. Enzymes function differently from conventional fertilisers, requiring specific soil conditions and timing for optimal efficacy, which can be confusing for farmers accustomed to immediate visible results from chemical applications. As per the Food and Agriculture Organization of the United Nations, low levels of digital literacy in rural areas create a persistent barrier to the adoption of advanced precision agriculture tools and biological soil amendments. Misapplication of enzymes due to incorrect dosage or timing can lead to perceived failure, discouraging future use and damaging the reputation of the technology. Furthermore, the subtle and long term nature of soil health improvements provided by enzymes makes it difficult for farmers to quantify immediate return on investment, reducing their willingness to experiment with new products. The absence of localized demonstration projects and educational programs means that many potential users remain skeptical of biological solutions. Comprehensive training and evidence-based outreach initiatives must be implemented first. Until then, the knowledge deficit will continue to slow the acceptance and effective utilization of agricultural enzymes in key growing regions.
MARKET OPPORTUNITIES
Integration of Enzymes with Precision Agriculture and Digital Farming Tools
The convergence of these enzymes with precision agriculture technologies is a key growth area for the agricultural enzymes market. This integration enables optimised application and enhanced efficacy through data-driven decision-making. According to the McKinsey Global Institute, advanced digital connectivity and precision ag technologies can optimise field operations and generate significant cost savings, motivating an industry-wide integration of bio-inputs via smart variable-rate hardware. By using soil sensors and satellite imagery to map nutrient deficiencies and microbial activity, farmers can apply enzymes precisely where they are needed most, maximising their impact and minimising waste. As per the American Society of Agronomy, site-specific resource management and 4R nutrient stewardship improve field-scale input utilization and environmental indices, motivating a shift toward localized biological soil treatments. The integration allows for real-time monitoring of soil health parameters, enabling dynamic adjustments to enzyme formulations based on changing field conditions. Furthermore, digital platforms can track the performance of enzymatic treatments over time, providing farmers with verifiable data on soil improvement and yield enhancements. This evidence-based approach builds trust and encourages broader adoption among tech-savvy farmers. The synergy between biological solutions and digital tools also facilitates the development of customized enzyme blends tailored to specific crop and soil types, opening new avenues for product differentiation and value creation in the agricultural biotechnology sector.
Expansion into Emerging Markets with Growing Agricultural Mechanisation
The rapid mechanisation and modernisation of agriculture in emerging economies such as India, Brazil, and Southeast Asian nations offer substantial growth opportunities for the Agricultural Enzymes Market. According to the Indian Ministry of Agriculture, the government has rolled out initiatives to scale up Zero-Budget Natural Farming to reduce on-farm input expenditures to zero by leveraging indigenous on-farm bio-inoculants rather than commercially manufactured inputs. The policy support creates a favorable regulatory environment and reduces financial barriers for early adopters. As per the Brazilian Agricultural Research Corporation, under national decarbonization frameworks such as the ABC Plan, Brazil aims to recover and manage 30 million hectares of low-carbon agricultural land by 2030, driving up the regional baseline demand for sustainable soil management practices. The shift toward sustainable intensification in these regions is driven by the need to maintain soil productivity on existing farmland rather than expanding into fragile ecosystems. Enzymes provide a scalable solution to enhance soil health in these intensive cropping systems. Furthermore, the growing presence of multinational agribusinesses in these markets facilitates technology transfer and introduces advanced enzymatic products to local farmers. The combination of government incentives, changing farming practices, and increasing corporate involvement positions emerging markets as key growth engines for the global agricultural enzymes industry in the coming decade.
MARKET CHALLENGES
Instability of Enzyme Activity Under Variable Field Conditions
Maintaining stable enzyme activity is a primary hurdle for the Agricultural Enzymes Market. These bio-inputs degrade quickly when subjected to environmental fluctuations, such as extreme temperatures, changing pH levels, and UV radiation. According to the Soil Science Society of America, diurnal soil microclimate variations shift microbial metabolic activity and alter baseline enzyme kinetics, driving the industry to design localized biostimulant formulations tailored to regional environmental stress profiles. The sensitivity requires advanced encapsulation technologies to protect the enzymes, which adds complexity and cost to product development. As per the Journal of Agricultural and Food Chemistry, biological compounds deployed in field-scale environments face aggressive photolytic and oxidative degradation from natural sunlight, accelerating an industry-wide push for novel microencapsulation and UV-shielding protection technologies. Farmers often face unpredictable weather patterns that can further compromise enzyme performance, leading to inconsistent results and reduced confidence in the technology. The lack of standardised testing protocols for field stability also makes it difficult for manufacturers to guarantee performance across diverse geographic locations. Consequently, the risk of product failure due to environmental factors remains a persistent concern for both producers and users. Overcoming this challenge requires continuous innovation in formulation science to create robust enzyme products that can withstand harsh field conditions while maintaining biological activity, a hurdle that continues to limit widespread reliability and adoption.
Regulatory Hurdles and Lack of Harmonised Approval Processes
The absence of harmonized regulatory frameworks for agricultural enzymes across different jurisdictions holds back the expansion of the agricultural enzymes market. This creates significant barriers to market entry and international trade for manufacturers. According to the Organisation for Economic Co-operation and Development, non-harmonised cross-border regulatory frameworks complicate market authorisations for innovative ag-biocatalysts, prompting commercial manufacturers to build dedicated regional regulatory compliance portfolios to access key agricultural markets. The fragmentation forces companies to navigate distinct approval pathways for each market, delaying product launches and increasing compliance costs. As per the European Food Safety Authority, the assessment of microbial strains used in enzyme production involves rigorous safety evaluations that can take several years to complete, slowing down innovation cycles. In many developing countries, the lack of clear guidelines for biological inputs creates uncertainty for investors and manufacturers, hindering market development. Furthermore, the rapid pace of technological advancement in enzyme engineering often outpaces regulatory updates, leaving new products in a legal grey area. This regulatory lag stifles the introduction of innovative solutions and limits consumer access to advanced agricultural technologies. International bodies must establish standardised criteria for evaluating and approving agricultural enzymes. Until then, manufacturers will face significant operational challenges that impede global market expansion and equitable access to sustainable farming tools.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2023 to 2029 |
| Base Year | 2023 |
| Forecast Period | 2024 to 2029 |
| CAGR | 11.4% |
| Segments Covered | By Product Type, Crop Type, Type, Region |
| Various Analyses Covered | Global, Regional, & Country Level Analysis; Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Novozymes, Agrinos, Agrilife, Stoller USA, Inc., BioWorks Inc., Syngenta AG, Aries Agro Limited, GreenMax AgroTech., Camson Bio Technologies Limited, Valmont Industries, Aum Enzymes, Cypher Environmental, DuPont and Deepak Fertilizers and Petrochemicals, Chr. Hansen Holding A/S, Amano Enzyme Inc., Aumgene Biosciences, Megazyme Ltd., Enzyme Supplies Limited |
SEGMENTAL ANALYSIS
By Type Insights
Phosphatases
The phosphatases segment led the Agricultural Enzymes Market and captured a significant share in 2025. This leading position of the segment was attributed to its essential function in hydrolyzing organic phosphorus compounds into inorganic forms that are readily available for plant uptake. According to the International Fertilizer Association, a major percentage of applied phosphorus fertilizers become chemically fixed or precipitation-bound in the soil profile shortly after application, prompting an active commercial shift toward microbial and enzymatic biostimulants designed to solubilize fixed nutrients. The capability is crucial for maintaining crop productivity while reducing reliance on expensive synthetic phosphate fertilisers. As per the Food and Agriculture Organization of the United Nations, certain scientific and mineralogical estimates suggest that economically viable global phosphate rock reserves could face depletion within 50 to 100 years under peak consumption models, accelerating industrial research into biological nutrient-efficiency enhancers. The widespread deficiency of available phosphorus in tropical and subtropical soils further amplifies the demand for phosphatases, particularly in major agricultural regions like Latin America and Southeast Asia. Farmers increasingly recognize that integrating phosphatases into their nutrient management plans can reduce fertilizer costs while maintaining yield levels. The enzymatic breakdown of organic matter also improves soil structure and microbial diversity, contributing to long-term sustainability. Consequently, the critical role of phosphatases in addressing global phosphorus scarcity and improving nutrient cycling ensures their continued dominance in the market, as they offer a scientifically proven solution to one of agriculture’s most persistent chemical limitations.
Dehydrogenases
The dehydrogenase segment is expected to exhibit a noteworthy CAGR of 12.8% during the forecast period due to its increasing use as a reliable bioindicator of overall soil biological activity and health. According to the Soil Science Society of America, dehydrogenase activity reflects the metabolic activity of viable microbial communities, positioning it as a key indicator for tracking real-world shifts in soil health under conservation management systems. As farmers shift toward regenerative agriculture, the demand for tools that measure and enhance soil biological function is rising sharply. As per the European Commission’s Joint Research Centre, functional indexing of soil enzyme activities, including dehydrogenases, serves as an active environmental indicator for monitoring degradation patterns and land-use intensity across regional agricultural systems. Furthermore, dehydrogenases play a pivotal role in the decomposition of complex organic pollutants and pesticides, aligning with growing regulatory demands for bioremediation in agricultural lands. The ability of these enzymes to facilitate carbon cycling and improve soil respiration rates makes them integral to carbon farming initiatives that seek to sequester atmospheric carbon in soil organic matter. As certification programs for carbon credits expand, the measurement and enhancement of dehydrogenase activity become valuable assets for farmers seeking additional revenue streams. This multifaceted utility in health assessment, pollution control, and carbon management drives the rapid adoption of dehydrogenases, positioning them as the fastest-growing segment in the agricultural enzymes market.
By Product Insights
Soil Fertility Products
In 2025, the soil fertility products segment held the majority share in the Agricultural Enzymes Market because they address the foundational requirement of all agricultural systems: the availability of essential nutrients in the root zone. According to the World Bank, intensive agricultural operations accelerate severe soil degradation and land vulnerability worldwide, driving an active industry shift toward restorative biochemical inputs and nutrient-cycling enzymes. These products, which include phosphatases, ureases, and cellulases, work synergistically to break down organic matter and release nitrogen, phosphorus, and potassium, thereby restoring soil productivity. As per the United States Department of Agriculture, international market disruptions, geopolitical flashpoints, and export constraints keep baseline chemical fertilizer input costs elevated, prompting producers to integrate biological alternatives that improve input efficiency. Soil fertility enzymes allow producers to achieve similar or better yields with lower chemical inputs, offering immediate economic benefits. Additionally, the degradation of soil organic matter in intensive farming systems has reached critical levels in many regions, necessitating interventions that rebuild soil structure and water holding capacity. Enzymatic treatments accelerate the formation of stable soil aggregates, improving aeration and root penetration. The universal applicability of soil fertility products across various crop types and geographies ensures consistent demand, making this segment the backbone of the agricultural enzymes industry as producers prioritize long term soil health over short term chemical fixes.
Growth Enhancing Products
The growth enhancing products segment is predicted to witness the highest CAGR of 13.5% from 2026 to 2034 owing to the need to maximize crop yields under increasingly stressful environmental conditions. According to the Food and Agriculture Organization of the United Nations, climate change-induced disruptions could reduce global crop yields by up to 30% by 2050 in highly vulnerable regions if adaptation measures are not adopted, accelerating the commercial demand for crop resilience biostimulants. Growth enhancing enzymes, such as those involved in hormone regulation and cell wall modification, help plants maintain metabolic activity during stress periods, ensuring stable production levels. As per the Alliance of Bioversity International and CIAT, the integration of functional biostimulant technologies modifies the plant rhizosphere and modulates key metabolic enzymes to optimize root development and macro-nutrient uptake under drought stresses. The physiological advantage is particularly valuable in rain fed agricultural systems where irrigation is not available. Furthermore, the rising consumer preference for high-quality produce with extended shelf life drives farmers to adopt growth enhancers that improve fruit size, colour, and nutritional content. The ability of these products to deliver visible improvements in crop performance within a single season makes them attractive to commercial growers seeking competitive advantages. Precision agriculture technologies now enable a more targeted application of these growth enhancers. As a result, their efficacy and adoption rates continue to rise, marking them as the most dynamic segment in the market.
By Crop Insights
Cereals and Grains
The cereals and grains segment dominated the Agricultural Enzymes Market and accounted for a substantial share in 2025. This dominance of the segment was driven by its status as the primary source of calories for the global population and its cultivation on vast expanses of arable land. According to the Food and Agriculture Organization of the United Nations, cereal crops represent approximately 50% of the world's total harvested area, presenting a primary large-scale market category for active biological and nutrient management inputs. The intensive nature of cereal production often leads to soil nutrient mining and degradation, necessitating regular applications of enzymatic solutions to maintain fertility and prevent yield plateaus. As per the USDA Foreign Agricultural Service, global maize production regularly exceeds 1.2 billion metric tons annually, demanding intensive agricultural input interventions to optimize nutrient pathways and secure scalable crop yield performance under variable field conditions. The economic sensitivity of cereal farmers to input costs drives the adoption of enzymes that offer measurable return on investment through improved nutrient uptake and reduced fertilizer waste. Furthermore, government subsidies for staple crop production in many countries encourage the use of advanced agronomic tools to ensure food security. The widespread adoption of no-till farming in cereal systems also boosts demand for enzymes that facilitate residue decomposition. Given the sheer scale of cereal cultivation and its critical importance to global food stability, this segment remains the dominant force in the agricultural enzymes market, driving volume and innovation.
Fruits and Vegetables
The fruits and vegetables segment is growing at the fastest pace in the Agricultural Enzymes Market. This swift expansion of the segment is propelled by the high economic value of these crops and the stringent quality standards required by domestic and export markets. According to the Organic Trade Association, organic fruits and vegetables maintain an ongoing market expansion to comprise nearly 15% of all produce sales in the United States, expanding the active commercial pipeline for compliant bio-inputs. These crops are highly sensitive to nutrient imbalances and environmental stress, which can significantly affect appearance, taste, and shelf life, making precision nutrient management via enzymes crucial for profitability. As per the European Commission, the continuous updating and lowering of Maximum Residue Levels (MRLs) toward the limit of detection for non-renewed active substances forces conventional growers to adopt integrated farm management alternatives to sustain export and distribution viability. The ability of enzymes to enhance sugar content, color development, and firmness in fruits directly translates to higher market prices and reduced post harvest losses. Furthermore, the intensification of greenhouse and protected cultivation systems for high value vegetables creates controlled environments where enzymatic applications can be optimized for maximum effect. The combination of regulatory pressure, consumer preferences, and the need for premium quality ensures that the fruits and vegetables segment will continue to outpace other crop types in terms of growth rate and technology adoption.
REGIONAL ANALYSIS
North America Market Analysis
North America was the top performer in the Agricultural Enzymes Market and secured the largest share in 2025. This supremacy of the region in the global market was fuelled by advanced agricultural infrastructure and a strong regulatory framework supporting sustainable farming practices. According to the United States Department of Agriculture, the adoption intensity of advanced precision farming technologies varies widely across operations, with auto-guidance and section control systems forming the foundational core of modern, data-driven nutrient management networks. The region’s focus on reducing environmental footprint and improving soil health drives consistent demand for biological inputs. As per the Environmental Protection Agency, agricultural runoff contributes heavily to elevated localized nitrogen concentrations across the Upper Cedar river basin and broader Midwest, accelerating an industry-wide deployment of commercial urease inhibitors to limit fertilizer volatilization. The presence of major agribusiness companies and research institutions in the region fosters innovation and rapid commercialisation of new enzyme products. Furthermore, the high level of mechanisation and technical expertise among North American farmers enables effective application and monitoring of enzymatic treatments. The strong cooperative networks and extension services also play a vital role in educating producers about the benefits of soil biology. With a mature market for sustainable agricultural inputs and robust government support for conservation programs, North America remains a key driver of technological advancement and market growth in the global agricultural enzymes sector.
Europe Market Analysis
Europe followed closely behind in the agricultural enzymes market. It stands as a leader in the regulatory promotion of sustainable agriculture, significantly influencing the adoption of agricultural enzymes through stringent environmental policies and consumer demand for organic products. According to the European Commission, the Farm to Fork Strategy mandates a 50% reduction in chemical pesticide use and a 20% reduction in fertilizer use by 2030, creating a powerful legislative tailwind for biological alternatives like enzymes. The policy framework encourages farmers to transition toward regenerative practices that rely on soil biological activity rather than synthetic inputs. As per the Research Institute of Organic Agriculture, consolidated statistical data demonstrates that global organic farmland has expanded past 96 million hectares, driving the ongoing development of compliant bio-inputs across regional farming markets. The high awareness of environmental issues among European consumers drives retailers to source produce from farms using sustainable methods, further incentivizing enzyme adoption. Additionally, the region’s advanced research capabilities in biotechnology lead to the development of highly specialized enzyme formulations tailored to local soil and crop conditions. The strong emphasis on circular economy principles in agriculture also supports the use of enzymes for waste decomposition and nutrient recycling. Consequently, Europe’s regulatory leadership and consumer preferences create a robust and growing market for agricultural enzymes that align with its sustainability goals.
Asia Pacific Market Analysis
Asia Pacific is the fastest-growing region for the agricultural enzymes market because of the urgent need to increase food production for a large and growing population while addressing severe soil degradation issues. According to the Food and Agriculture Organization of the United Nations, Asia is home to over 60% of the world's smallholder farmers, who are actively scaling up the integration of low-cost biological inputs to sustain crop yields and offset volatile chemical fertilizer markets. Governments in countries like India and China are actively promoting natural farming initiatives, providing subsidies and training for the use of enzymatic and microbial products. As per the Indian Ministry of Agriculture, the National Mission on Sustainable Agriculture publicizes and prioritizes the deployment of microbial biofertilizers to promote climate-resilient farming, resource conservation, and long-term soil health reclamation across rainfed and intensively cultivated zones. The rapid urbanization and changing dietary patterns in the region are also driving demand for high quality fruits and vegetables, which benefit from enzymatic growth enhancers. Furthermore, the increasing awareness of the health hazards associated with chemical residues in food is shifting consumer preferences toward safer production methods. The combination of government support, demographic pressure, and rising environmental consciousness positions Asia Pacific as a critical growth engine for the global agricultural enzymes market, with significant potential for expansion in both smallholder and commercial sectors.
Latin America Market Analysis
Latin America occupies a strategic position in the Agricultural Enzymes Market. The region leverages vast arable land holdings, maintaining a global powerhouse status across soy, corn, and cattle production. According to the Brazilian Agricultural Research Corporation, under environmental and low-carbon frameworks such as the ABC Plan, agricultural sectors are scaling up regenerative management systems to recover and manage millions of hectares of degraded soil by 2030, intensifying demand for commercial bio-inputs. The region’s heavy reliance on exports makes compliance with international sustainability standards crucial, driving producers to adopt enzymatic solutions that enhance soil health and reduce chemical residues. As per the Inter-American Institute for Cooperation on Agriculture, extensive soil erosion and acute nutrient depletion stand out as key structural risks in Latin America, prompting regional public and private stakeholders to invest in alternative biological soil amendments to stabilize arable land productivity. The presence of large-scale commercial farms with the capital to invest in advanced technologies accelerates the adoption of premium enzymatic products. Furthermore, the growing interest in carbon farming and regenerative agriculture in the region offers new opportunities for enzyme manufacturers to provide solutions that sequester carbon and improve ecosystem services. Latin America features an expansive agricultural base and an increasing focus on sustainability. Driven by these factors, the region is poised for significant growth in the agricultural enzymes market.
Middle East and Africa Market Analysis
The Middle East and Africa region provides a unique landscape for the Agricultural Enzymes Market. It is known for challenging climatic conditions and a pressing need to enhance food security through sustainable intensification. According to the Food and Agriculture Organization of the United Nations, over 60% of the arable land resources across the African continent suffer from severe degradation, creating an active agronomic baseline that drives the adoption of restorative biochemical amendments and soil-enhancing inputs. In the Middle East, water scarcity is a critical constraint, driving the adoption of enzymes that improve soil water retention and root efficiency in irrigated systems. As per the African Union’s Comprehensive Africa Agriculture Development Programme, initiatives to promote climate smart agriculture are gaining traction, with biological inputs identified as key tools for building resilience against drought and soil salinity. The limited availability of affordable synthetic fertilisers in many African countries also makes enzymatic solutions an attractive alternative for smallholder farmers seeking to improve yields. Furthermore, the growing urban population in the region is increasing demand for fresh produce, encouraging commercial farmers to adopt technologies that enhance crop quality and consistency. While market maturity varies widely across countries, the fundamental need to restore soil health and optimise resource use ensures a steady growth trajectory for agricultural enzymes in the Middle East and Africa.
COMPETITIVE LANDSCAPE
The competition in the Agricultural Enzymes Market is characterized by a mix of established chemical giants and specialized biotechnology firms vying for dominance through innovation and sustainability credentials. Large multinational corporations leverage their extensive distribution networks and financial resources to scale production and offer integrated crop care solutions that include enzymatic components. Smaller niche players compete by offering highly specialized enzymes tailored to specific crops or soil conditions often providing superior technical support and customization. The market exhibits moderate consolidation as larger entities acquire innovative startups to bolster their biological portfolios and accelerate time to market for new products. Price competition remains intense particularly in commoditized segments prompting companies to differentiate through value added services such as soil testing and agronomic advice. Regulatory barriers to entry are significant due to the rigorous safety assessments required for biological inputs favoring established players with robust compliance capabilities. Customer loyalty is increasingly driven by proven field performance and environmental benefits rather than brand recognition alone. As sustainability becomes a central theme in agriculture the ability to demonstrate measurable ecological impact will define competitive success in this evolving market landscape.
KEY MARKET PLAYERS
Some of the market players dominate the global agriculture enzymes market.
- Novozymes
- Agrinos
- Agrilife
- Stoller USA, Inc
- BioWorks Inc
- Syngenta AG
- Aries Agro Limited
- GreenMax AgroTech
- Camson Bio Technologies Limited
- Valmont Industries
- Aum Enzymes
- Cypher Environmental
- DuPont and Deepak Fertilisers
- Petrochemicals
- Chr. Hansen Holding A/S
- Amano Enzyme Inc
- Aumgene Biosciences
- Megazyme Ltd
- Enzyme Supplies Limited
Top Players In The Market
- Novozymes A S Novozymes A S stands as a global leader in biological solutions, driving innovation in the Agricultural Enzymes Market through extensive research and development capabilities. The company focuses on creating specialized enzyme blends that enhance soil health and nutrient efficiency for major crops. Recently Novozymes launched new product lines tailored for tropical soils to address specific regional challenges in Latin America and Asia. This strategic expansion allows farmers in these regions to access advanced biological tools that improve yield stability. The company also collaborates with local agricultural institutions to conduct field trials demonstrating the efficacy of their enzymes in diverse climatic conditions. By prioritizing sustainability and scientific validation Novozymes strengthens its reputation as a trusted partner for modernizing farming practices. Their commitment to reducing the environmental footprint of agriculture aligns with global regulatory trends ensuring long term relevance and growth in the sector.
- BASF SE BASF SE leverages its strong chemical expertise to develop high performance agricultural enzymes that complement its broader crop protection portfolio. The company integrates enzymatic solutions into its digital farming platforms enabling precise application and monitoring for optimal results. Recently BASF expanded its production facilities in Europe to meet the rising demand for biological inputs driven by stringent environmental regulations. This investment ensures a stable supply chain and supports the company’s goal of offering sustainable alternatives to synthetic fertilizers. BASF also partners with seed companies to create coated seeds infused with enzymes that promote early root development and stress resistance. These collaborations enhance value for growers by providing integrated solutions that improve crop establishment. By combining chemical precision with biological innovation BASF strengthens its market position and addresses the evolving needs of modern agriculture effectively.
- Kemin Industries Kemin Industries specializes in ingredient solutions including agricultural enzymes that improve animal feed efficiency and soil health. The company focuses on developing robust enzyme formulations that withstand harsh processing and field conditions ensuring consistent performance. Recently Kemin acquired a biotechnology startup to enhance its pipeline of novel enzymes for sustainable agriculture. This acquisition expands their technological capabilities and allows for faster introduction of innovative products to the market. Kemin also invests heavily in customer education programs helping farmers understand the benefits of enzymatic treatments for soil restoration. Their global presence and technical support network enable them to serve diverse markets from North America to Asia. By focusing on practical solutions that deliver measurable economic benefits Kemin builds strong loyalty among producers seeking reliable and effective biological inputs for their operations.
Top Strategies Used By Key Market Participants
Key players in the Agricultural Enzymes Market primarily focus on strategic partnerships and continuous product innovation to maintain competitive advantage. Companies frequently collaborate with academic institutions and research organizations to discover new enzyme strains with enhanced stability and efficacy. They also engage in mergers and acquisitions to expand their product portfolios and gain access to proprietary technologies. Geographic expansion into emerging markets is another common strategy as firms seek to capitalize on growing demand for sustainable agricultural inputs in Asia and Latin America. Manufacturers invest heavily in educational initiatives and demonstration projects to overcome farmer skepticism and demonstrate the tangible benefits of enzymatic solutions. Additionally companies are integrating digital tools with their biological products to offer precision application services. Regulatory compliance and certification for organic use are also prioritized to access premium market segments. These multifaceted strategies enable firms to navigate complex market dynamics and drive sustained growth in the agricultural biotechnology sector.
RECENT HAPPENINGS IN THE MARKET
- In March 2024 Novozymes A S launched a new line of tropical soil enzymes to address regional nutrient challenges and strengthen the Agricultural Enzymes Market presence.
- In June 2023 BASF SE expanded its European production facilities for biological inputs to meet rising regulatory demand and strengthen the Agricultural Enzymes Market presence.
- In September 2023 Kemin Industries acquired a biotechnology startup to enhance its enzyme pipeline and strengthen the Agricultural Enzymes Market presence.
- In January 2024 Novozymes A S partnered with local agricultural institutes in Asia for field trials and strengthen the Agricultural Enzymes Market presence.
- In November 2023 BASF SE collaborated with seed companies to develop enzyme coated seeds and strengthen the Agricultural Enzymes Market presence.
MARKET SEGMENTATION
This research report on the agriculture enzymes market has been segmented & sub-segmented into the following categories.
By Type
- Phosphatases
- Dehydrogenases
- Proteases
- Sulfatases
- Others
By Crop Type
- Cereals & grains
- Fruits & vegetables
- Oilseeds & pulses
- Turfs & ornamentals
- Others
By Product Type
- Soil fertility products
- Growth enhancing products
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East and Africa