- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$5.85 BnMarket Estimate, 2026
$6.31 BnMarket Forecast, 2034
$11.60 BnCAGR, 2026–2034
7.9%Global Antijamming Equipment Market Size, Growth, Trends & Forecast (2026–2034)
The global antijamming equipment market was valued at USD 5.85 billion in 2025, is anticipated to reach USD 6.31 billion in 2026, and is projected to expand up to USD 11.60 billion by 2034, registering a compound annual growth rate (CAGR) of 7.9% during the forecast period from 2026 to 2034. Driven by the rising adoption of GPS technology in military operations, increasing threats of intentional and unintentional signal interference, and escalating defense expenditures, the market continues steady expansion worldwide.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 5.85 Billion
- 2026 Current Valuation: USD 6.31 Billion
- 2034 Forecast Valuation: USD 11.60 Billion
- Compound Annual Growth Rate (CAGR): 7.9% (2026–2034)
- Dominant Technology Segment: Nulling Systems (widely deployed and experiencing high growth due to advanced signal filtering capabilities)
- Dominant Application Segment: Navigation & Timing (critical for precise military and defense positioning)
- Dominant End-Use Segment: Military (accounting for the primary market share driven by satellite communication dependency and UAV integration)
- Dominant Region: North America (anchored by high concentrations of top industry players, heavy military budgets, and advanced weapon systems)
- Fastest-Growing Region: Asia-Pacific (expanding rapidly due to modernization of defense infrastructure and rising investments in secure GPS networks)
Core Market Drivers
- Military GPS Reliance: High dependence on satellite navigation for precise troop positioning, missile guidance, and unmanned aerial vehicle (UAV) operations.
- Proliferation of Jammers: Increased availability of low-cost jammers creating an urgent need for robust GNSS protection systems.
- Defense Budget Allocations: Expanding government funding and multi-million-dollar defense contracts aimed at upgrading GPS navigation antenna systems.
Primary Market Restraints & Challenges
- Legacy Incompatibility: Incompatibility between older, traditional GPS receivers and modern, efficient antijamming techniques such as beam-forming technologies.
Global Antijamming Equipment Market Segmentation Breakdown
| Segment Category | Leading Sub-Segment (2025 Base) | Fastest-Growing Sub-Segment (2026–2034) |
|---|---|---|
| By Technology | Beam Steering Systems (dominant advanced multi-element antenna defense) | Nulling Systems (rapid growth driven by research investments and robust interference suppression) |
| By Application | Navigation & Timing (essential for reliable positioning in hostile environments) | Surveillance & Reconnaissance / UAVs (high growth tied to unmanned defense systems) |
| By End-Use | Military (primary sector utilizing secure satellite communication and missile defense) | Civilian (emerging commercial applications in aviation and autonomous transport) |
| By Region | North America (dominant market share led by US defense programs and top industry contractors) | Asia-Pacific (fastest-growing regional market driven by defense modernization in regional powers) |
Major Industry Players Profiled
Key enterprises shaping the competitive global antijamming equipment market include Raytheon Technologies Corp., L3Harris Technologies, BAE Systems, Thales Group, Hexagon, Mayflower Communications, Lockheed Martin Corp., Israel Aerospace Industries Ltd., infinDome, and Furuno Electric Co., Ltd.
 Download Free Sample Report
Global Antijamming Equipment Market Size
The global antijamming equipment market was worth USD 5.85 billion in 2025. The global market is predicted to reach USD 6.31 billion in 2026 and USD 11.60 billion by 2034, growing at a CAGR of 7.9% from 2026 to 2034.

The high demand for GPS technology in military applications and ongoing innovations to improve the overall GPS infrastructure are two main factors driving the market's growth. Antijamming technology is a form of technology that protects GPS from outside interference and obstructions by amplifying and strengthening the signals. This technology is rapidly evolving and is expected to be widely used commercially in the near future. This technology aids in the reduction of interferences and obstructions, allowing GPS signals to be transmitted and received correctly.
Growing demand from various sectors to minimize GPS jamming to receive proper signals, increasing demand for unnamed airborne vehicles and devices, and increasing demand for low-power antijamming systems from missile manufacturers are all driving the market growth. Miniaturization of GNSS-based antijamming systems, increased dependency on satellite communication for various military operations, increased susceptibility to both unintentional and deliberate interferences, and proliferation of low-cost jammers are among the major factors driving the antijamming market. Moreover, in the forecast era, rising demand for UAVs and systems, as well as the advancement of low-cost GPS antijamming solutions, would generate new opportunities for the antijamming market.
Since GPS signals travel such a long distance back to the GPS receiver, they are highly susceptible to interference as well as deliberate jamming. There's also the possibility that the signal will be obliterated by higher Radio Frequency energy. With the technology allowing army soldiers to have a clear sense of maps and positions of enemies and strategic points, GPS technology has revolutionized military warfare techniques. Military organizations rely on satellite technology for precise positioning, timing, and communication daily. A low-power jammer can thus overwhelm GPS signals over a wide area, denying the enemy access.
One of the primary factors driving antijamming demand in recent years has been the exponential demand for GPS technology in military-based applications. In recent years, incompatibility with legacy GPS receivers has hampered the growth of the antijamming industry. During the forecast era, higher military and defense budgets allocated by the majority of governments around the world are expected to create huge opportunities for antijamming market players.
MARKET DRIVERS
Military units around the world are still on the lookout for modern, improved systems to ensure precise navigation using GPS technology. Mayflower Communications, for example, was awarded a USD 56 million contract for a GPS navigation antenna system in October 2020.
The United States military will use the technology, and it is expected to be completed in September 2025. This contract is for the Multi-Platform Anti-Jam Global Positioning System (GPS) Navigation Antenna (MAGNA), which provides GPS protection. Raytheon UK and the UK Ministry of Defense signed a deal in July 2020 to develop advanced GNSS antijamming technologies.
MARKET RESTRAINTS
Old GPS receivers are incompatible with new, more efficient GPS antijamming techniques, such as beam-forming technologies. Based on the path of jamming signals, the beamformer detects, selects, and downlinks signals from four satellites and offers four antijam solutions in the form of algorithms.
It cannot communicate with a regular GPS receiver that only has one input because it generates four outputs aimed at four selected satellites from the GPS receiver. This is one of the market restraints for GPS antijamming devices.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 7.9% |
| Segments Covered | By Technology, Application, End Use, and Region |
|
Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
|
Market Leaders Profiled | Raytheon Technologies Corp. (US), Hexagon (Holland), Thales Group (France), L3Harris Technologies (US), BAE Systems (UK), Mayflower Communications (US), infinDome (Israel), Lockheed Martin Corp. (US), Israel Aerospace Industries Ltd. (Israel), FURUNO ELECTRIC CO., LTD. (Japan), and Thales Group (France) and Others. |
REGIONAL ANALYSIS
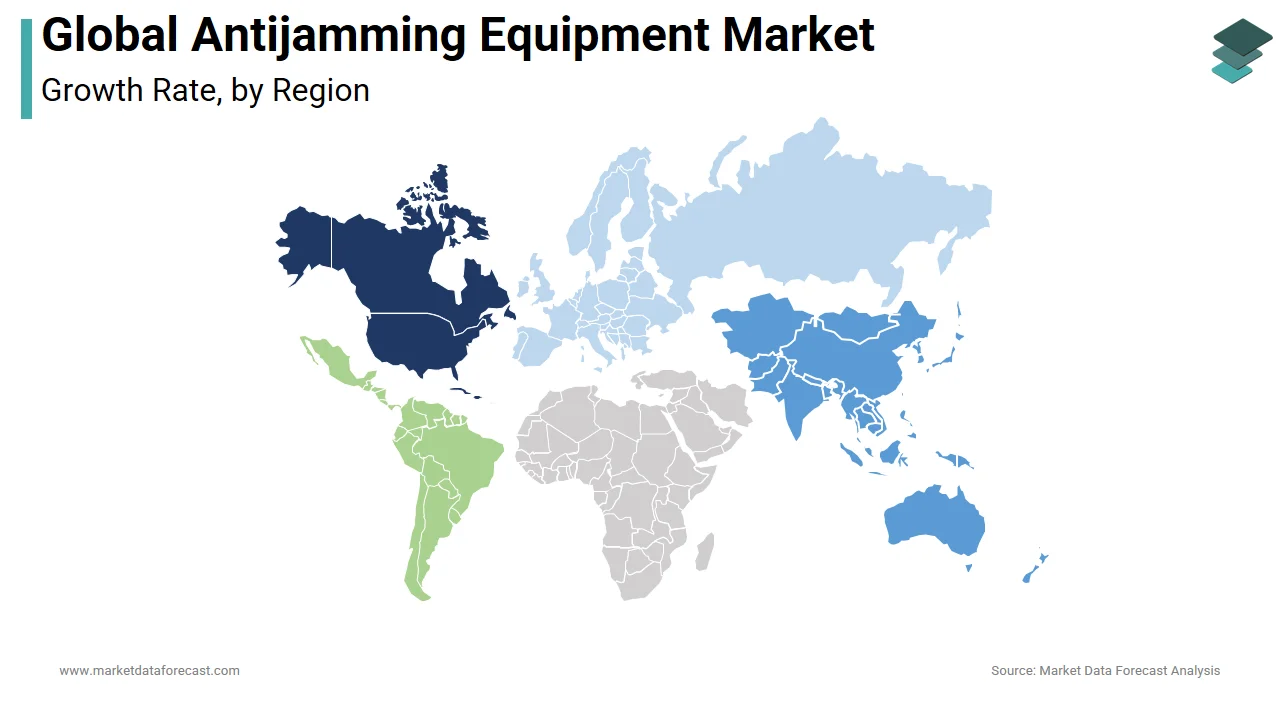
Because of the growing volume of weapon systems, the presence of top players in the antijamming market, the demand for miniaturization of GNSS-based antijamming products, and the reliance on satellite communication for various military operations in this area, North America dominates the antijamming market.
KEY MARKET PARTICIPANTS
The major companies operating in the global GPS antijamming market include Raytheon Technologies Corp. (US), Hexagon (Holland), Thales Group (France), L3Harris Technologies (US), BAE Systems (UK), Mayflower Communications (US), infinDome (Israel), Lockheed Martin Corp. (US), Israel Aerospace Industries Ltd. (Israel), FURUNO ELECTRIC CO., LTD. (Japan), Thales Group (France), and others.
RECENT MARKET HAPPENINGS
-
In July 2020, BAE Systems (UK) completed the acquisition of Raytheon Technologies Corporation's (US) Collins Aerospace Military Global Positioning System (GPS) business, adding decades of experience, advanced technology, and a large installed base of products to the group.
MARKET SEGMENTATION
This global research report on the antijam market is segmented and sub-segmented based on the technology, application, end-use, and region.
By Technology
-
Nulling Systems
-
Beam Steering Systems
-
Civilian Systems
Nulling systems segment is projected to have the highest growth rate in the coming years. Ongoing research and development activities and growing support from private organizations are propelling the demand of the market.
By Application
-
Flight Control
-
Surveillance & Reconnaissance
-
Location
-
Navigation & Timing
-
Safety Evacuation
-
Others
By End-Use
-
Military
-
Civilian
By Region
-
North America
-
The United States
-
Canada
-
Rest of North America
-
-
Europe
-
The United Kingdom
-
Spain
-
Germany
-
Italy
-
France
-
Rest of Europe
-
-
The Asia Pacific
-
India
-
Japan
-
China
-
Australia
-
Singapore
-
Malaysia
-
South Korea
-
New Zealand
-
Southeast Asia
-
-
Latin America
-
Brazil
-
Argentina
-
Mexico
-
Rest of LATAM
-
-
The Middle East and Africa
-
Saudi Arabia
-
UAE
-
Lebanon
-
Jordan
-
Cyprus
-