- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$5.92 BnMarket Estimate, 2026
$6.42 BnMarket Forecast, 2034
$12.29 BnCAGR, 2026–2034
8.45%Executive Summary: Asia-Pacific Active Implantable Medical Devices Market
- Market Scope: Comprehensive Asia-Pacific active implantable medical devices (AIMDs) market analysis covering product types, clinical applications, country frameworks, and cardiovascular/neurological device adoption metrics.
- Market Valuation: Valued at USD 5.92 billion in 2025, estimated at USD 6.42 billion in 2026, and projected to scale significantly over the forecast period at a compound annual growth rate (CAGR of 8.45%) from 2026 to 2034.
- Primary Growth Drivers: Rapidly aging population base across emerging economies, escalating prevalence of chronic cardiovascular and neurological disorders (such as Parkinson's disease, epilepsy, and cardiac rhythm failures), rising healthcare spending, and favorable infrastructural healthcare reforms. Key market restraints include device malfunction risks, cybersecurity vulnerabilities, and high procedural costs.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Product | Implantable Cardioverter Defibrillators (ICDs) and Cardiac Pacemakers (dominated regional demand for heart rhythm management) | Advanced Neurostimulators (Deep Brain & Spinal Cord Stimulators) and Insertable Loop Recorders |
| By Application | Cardiovascular disease management and rhythm monitoring | Neurological disorder therapies (Parkinson's and epilepsy treatment) |
| By Country | China (dominated the APAC market share due to its massive population, rising CVD cases, and large-scale manufacturing) | India (experiencing rapid market acceleration due to high chronic disease burdens and improving healthcare access) |
Major Market Players & Market Structure
Market Structure: Highly competitive and consolidated MedTech landscape featuring global healthcare device giants competing intensely on product miniaturization, battery longevity, wireless data transmission, and clinical efficacy.
Key Companies: Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, BIOTRONIK SE & Co. KG, LivaNova PLC., Cochlear Limited, MED-EL, Sonova Holding AG, William Demant Holding A/S, and Nurotron Biotechnology Co. Ltd.
 Download Free Sample Report
Asia-Pacific Active Implantable Medical Devices Market Size
The Asia-Pacific active implantable medical devices market was valued at USD 5.92 billion in 2025. The market is estimated at USD 6.42 billion in 2026 and is projected to reach USD 12.29 billion by 2034, growing at a CAGR of 8.45% from 2026 to 2034.
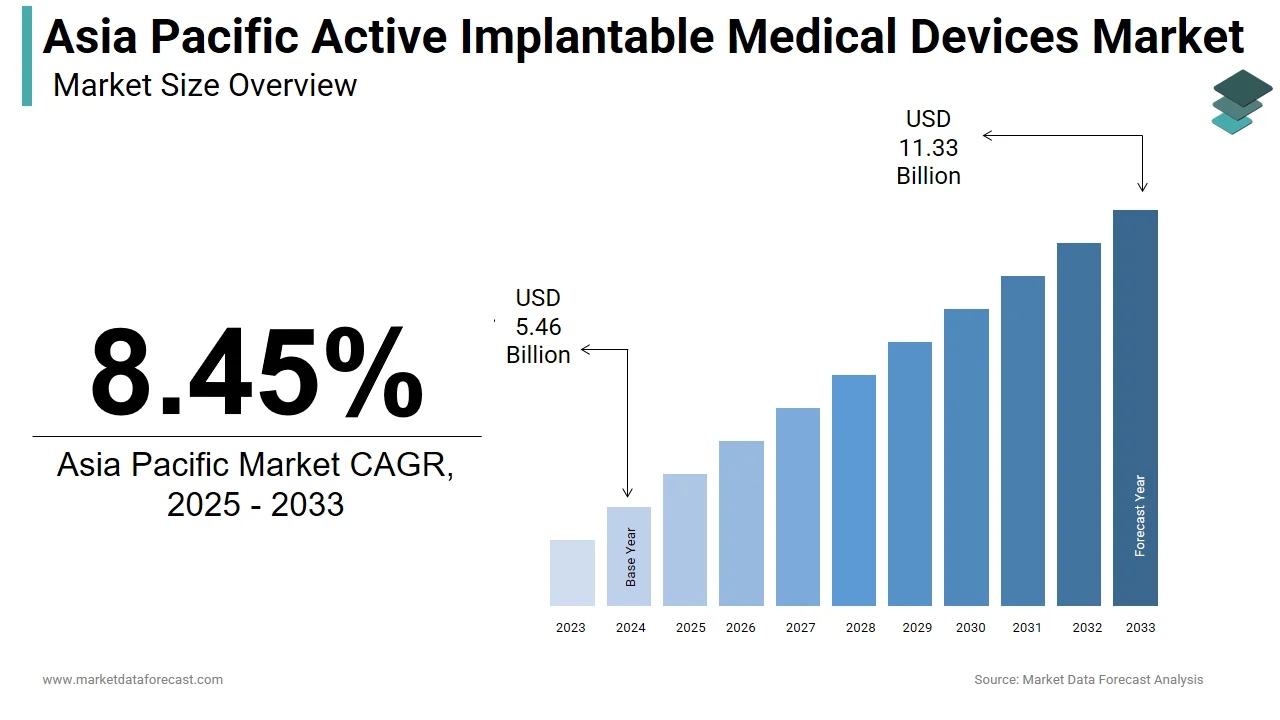
An Active Implantable Medical Device (AIMD) is any medical device that is completely or partially put inside the body and needs a power source, like a battery, to work. These technologies address critical health burdens across the region where chronic disease prevalence continues to rise sharply. The World Health Organization states that cardiovascular diseases cause 17.9 million deaths annually worldwide, with a disproportionate impact on Asian populations due to rapid urbanization and aging demographics. This epidemiological reality creates sustained clinical demand for life-sustaining implantable solutions beyond elective procedures. Furthermore, as per the International Diabetes Federation, the Western Pacific region had 206 million adults living with diabetes in 2021, which significantly increases the risk of complications requiring advanced device therapy. Such statistics underscore the urgent need for reliable active implants within regional healthcare systems. Regulatory bodies in Japan and Australia have streamlined approval pathways to accelerate patient access to innovative devices while maintaining safety standards. The integration of remote monitoring capabilities enhances treatment adherence and reduces hospital readmissions effectively. As healthcare infrastructure expands across Southeast Asia, equitable access to these essential therapies improves steadily. This convergence of technological maturity and demographic necessity positions the sector for resilient growth driven by genuine medical requirements.
MARKET DRIVERS
Rising Prevalence of Cardiovascular and Neurological Disorders
The escalating incidence of cardiovascular and neurological conditions is fueling the growth of the Asia Pacific active implantable medical devices market. According to sources, cardiovascular disease is a leading cause of mortality in Asia and constitutes a major portion of noncommunicable disease deaths in the region. This alarming statistic creates an immediate and sustained demand for cardiac rhythm management devices such as pacemakers and implantable cardioverter defibrillators among high-risk populations. Physicians increasingly rely on these active implants to manage life-threatening arrhythmias and prevent sudden cardiac death effectively. In addition, as per studies, stroke affects millions of individuals annually in Asia, frequently leading to long-term neurological impairments. The aging population structure in countries like Japan and China exacerbates this trend because older adults are disproportionately affected by these chronic conditions. According to the United Nations Department of Economic and Social Affairs, the number of people aged 60 years or older in Asia is projected to reach 1.3 billion by 2050. This demographic shift ensures a growing patient base requiring lifelong device therapy regardless of economic cycles. Healthcare systems prioritize early diagnosis, which drives uptake of advanced diagnostic tools followed by necessary implantable treatments.
Technological Advancements in Miniaturization and Remote Monitoring
Breakthroughs in device miniaturization and wireless connectivity significantly enhance the clinical appeal and patient acceptance of these devices in the Asia Pacific active implantable medical devices market. According to Medtronic, modern leadless pacemakers like the Micra are 93% smaller than traditional devices, which maximizes patient comfort during implantation. This technological evolution addresses previous concerns related to surgical complications and device rejection, thereby broadening the eligible patient population considerably. Furthermore, the integration of remote monitoring systems allows clinicians to track device performance and patient health metrics in real time without requiring frequent hospital visits. As per research, remote telemonitoring interventions for chronic heart failure patients help reduce the incidence of hospitalizations and improve quality of life. Such efficiency gains are particularly valuable in rural areas of India and Indonesia where access to specialized cardiac care remains limited. Manufacturers invest heavily in developing battery-efficient chips that extend device longevity up to 12 years and minimize replacement surgery needs. The adoption of artificial intelligence algorithms in device software enables predictive analytics for early detection of adverse events before they become critical. These innovations improve therapeutic outcomes while reducing the overall burden on healthcare infrastructure simultaneously. Patients prefer less invasive options with fewer follow-up requirements, which drives preference for next-generation active implants consistently.
MARKET RESTRAINTS
High Cost of Implantable Devices and Procedures
The substantial financial burden associated with these devices and their surgical implantation is a significant barrier for many countries in the Asia Pacific active implantable medical devices market. As per the World Bank, out-of-pocket health expenditure accounts for over 40% of total health spending in several Southeast Asian nations, which limits affordability for high-cost interventions severely. According to sources, active implants such as cochlear implants and spinal cord stimulators frequently range in price from $15,000 to over $30,000, which exceeds the annual income of many households in emerging economies. This price disparity restricts access to primarily urban affluent populations and leaves a vast majority of potential patients untreated indefinitely. Additionally, the complexity of implantation procedures requires highly skilled surgeons and specialized operating theaters, which further escalates the total cost of care significantly. As per studies, public health insurance coverage for advanced medical devices remains inconsistent across the Asia-Pacific region, with many health systems excluding newer technologies from standard reimbursement lists. Patients often face lengthy waiting periods or complete denial of coverage for these expensive treatments due to budget constraints. The lack of standardized pricing mechanisms leads to significant variations in device costs between different hospitals and regions unpredictably. This financial uncertainty discourages both patients and healthcare providers from opting for active implant solutions despite clinical necessity. Consequently, many individuals resort to cheaper pharmacological alternatives that may offer inferior long-term outcomes compared to device therapy.
Stringent Regulatory Approval Processes and Reimbursement Hurdles
Complex regulatory frameworks and inadequate reimbursement policies severely impede the timely availability and adoption of active implantable medical devices in the Asia Pacific market. According to research, regulatory bodies such as the Therapeutic Goods Administration in Australia and the Pharmaceuticals and Medical Devices Agency in Japan maintain rigorous evaluation standards that can contribute to regional delays in medical device launches relative to other global markets. These prolonged approval timelines hinder manufacturers from introducing innovative technologies promptly and cause patients to miss out on advanced therapeutic options unnecessarily. Furthermore, as per the Association of Southeast Asian Nations, member states have established the ASEAN Medical Device Directive (AMDD) to harmonize standards, but uneven national implementation and differing local regulatory requirements continue to create compliance burdens for companies entering regional markets. Each country requires separate clinical data submissions and local testing, which increases development costs and time to market substantially. Reimbursement challenges further compound the issue because many national health insurance schemes do not cover newer active implants due to insufficient local health economic evidence. Providers hesitate to recommend devices without guaranteed payment, which limits patient access to necessary care systematically. The lack of clear post-market surveillance requirements also creates uncertainty regarding long-term safety monitoring obligations for stakeholders. These administrative and financial hurdles discourage smaller innovators from entering the market and reduce competition and innovation overall.
MARKET OPPORTUNITIES
Expansion of Healthcare Infrastructure in Emerging Economies
The rapid development of healthcare facilities and increased government investment in medical infrastructure offer substantial opportunities for emerging economies in the Asia Pacific active implantable medical devices market. According to reports, public health spending and infrastructure projects across developing Southeast Asian economies aim to scale access to specialized healthcare services. These new facilities are equipped with advanced operating rooms and imaging technologies necessary for implanting and monitoring active devices safely and effectively. Countries like Vietnam and Thailand actively promote medical tourism by establishing world-class hospitals that attract international patients seeking affordable yet high-quality implant procedures. As per sources, India's Ayushman Bharat scheme currently covers 500 million citizens and includes coverage for medical implant procedures. Such initiatives expand the addressable patient population significantly beyond current limitations. Additionally, partnerships between global device manufacturers and local distributors facilitate better supply chain management and after-sales support in remote areas reliably. Increased training programs for cardiologists and neurosurgeons ensure adequate expertise for device implantation across tier two cities gradually. These infrastructural improvements create a favorable ecosystem for market growth by enhancing accessibility and affordability simultaneously for diverse patient groups.
Growing Adoption of Telemedicine and Digital Health Integration
The integration of telemedicine platforms with these devices unlocks significant potential for enhancing patient care within the Asia Pacific active implantable medical devices market. Furthermore, this technological synergy effectively expands market reach within the region. According to studies, telehealth consultations and telemonitoring platforms in Asia experienced widespread expansion during recent years. Modern active implants equipped with wireless connectivity can transmit real-time physiological data to healthcare providers via secure cloud platforms instantly and accurately. This capability enables timely intervention for device malfunctions or health deterioration without requiring frequent or urgent physical hospital visits. As per research, 5G network rollout in major cities aims to facilitate faster data transmission speeds and enhance connectivity infrastructure for electronic medical devices. Such technological synergy improves patient adherence to follow-up protocols and reduces the burden on overcrowded healthcare facilities considerably. Insurance providers increasingly recognize the cost-effectiveness of remote monitoring, which leads to broader coverage for digital health services linked to implants. Manufacturers develop user-friendly mobile applications that allow patients to track their device status and share reports with physicians easily and securely. This digital engagement fosters better patient empowerment and satisfaction throughout the treatment journey continuously. The convergence of Internet of Things technology with medical implants opens new revenue streams through subscription-based monitoring services sustainably. Healthcare systems benefit from reduced emergency admissions and optimized resource utilization through proactive digital management strategies.
MARKET CHALLENGES
Shortage of Skilled Healthcare Professionals for Implant Procedures
The acute shortage of trained cardiologists and neurosurgeons capable of implanting and maintaining active medical devices is a critical challenge to persistent growth of the Asia Pacific market. According to the World Health Organization, the estimated 4.3 million health worker deficit was a global shortfall figure identified across 57 crisis countries in the World Health Report 2006. This workforce gap limits the number of procedures that can be performed safely and effectively, which creates bottlenecks in patient access to necessary care. Complex implant surgeries require precise technical skills and extensive experience to minimize complications such as infection or lead displacement during operations. Many rural hospitals lack personnel with the necessary expertise, which forces patients to travel long distances to urban centers for treatment, inconveniently. As per the Lancet Commission on Global Surgery, the recommended target surgical volume is 5,000 procedures per 100,000 population, whereas actual low- and middle-income country volumes vary widely. Training programs for specialized implant techniques are limited and often concentrated in metropolitan areas, which exacerbates regional disparities in service availability. The turnover rate among skilled medical staff further strains existing resources and leads to longer waiting times for patients awaiting procedures. Device manufacturers struggle to provide adequate technical support due to the limited pool of qualified biomedical engineers available locally. This human resource constraint hinders the adoption of newer technologies that require sophisticated handling and maintenance expertise. The market cannot realize its full potential despite high clinical demand. This limitation exists because significant investment in medical education and workforce development is required.
Limited Patient Awareness and Cultural Barriers
Low levels of public awareness regarding the benefits and safety of these devices significantly challenge the Asia Pacific active implantable medical devices market expansion. Furthermore, cultural hesitancy in diverse APAC societies continuously intensifies these difficulties. According to sources, awareness of specialized surgical implants remains limited among rural patient populations in developing regions. Misconceptions about surgical risks and device reliability deter many individuals from seeking timely treatment until diseases progress to irreversible stages. Cultural beliefs in certain communities favor traditional medicine over modern technological interventions, which leads to delayed diagnosis and poorer health outcomes systematically. Religious considerations in some regions may also influence acceptance of foreign materials implanted in the body and create psychological barriers to adoption. As per the World Health Organization, health literacy and access to health information vary substantially across populations, disproportionately affecting disadvantaged and marginalized communities. Language barriers further complicate patient education efforts because instructional materials are often unavailable in local dialects or simplified formats. Physicians report difficulty in convincing patients to opt for implants due to fear of dependency on technology or social stigma associated with visible devices. Community outreach programs are insufficient to address these deep-seated psychological and cultural barriers that persist across generations. The lack of trusted local advocates and patient success stories perpetuates skepticism toward modern medical interventions unnecessarily. Overcoming these informational and cultural obstacles requires sustained multi-stakeholder engagement and tailored communication strategies designed specifically for diverse community contexts.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Product and Country. |
| Various Analyses Covered | Global, Regional and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered | India, China, Japan, South Korea, Australia, New Zealand, Thailand, Malaysia, Vietnam, Philippines, Indonesia, Singapore, and Rest of APAC |
| Market Leaders Profiled | Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, BIOTRONIK SE & Co. KG, LivaNova PLC, Cochlear Limited, MED-EL, Sonova Holding AG, William Demant Holding A/S, and Nurotron Biotechnology Co. Ltd. |
SEGMENTAL ANALYSIS
By Product Insights
In 2025, the implantable cardioverter defibrillator segment held the majority share in the Asia Pacific active implantable medical devices market mainly because of the escalating burden of heart failure and sudden cardiac arrest across the region. According to the World Heart Federation, the prevalence of heart failure is increasing globally, with an estimated 26 million people affected. This vast patient pool requires reliable protection against lethal arrhythmias, which these devices provide effectively. Furthermore, as per studies, sudden cardiac arrest represents a substantial cause of mortality within cardiovascular diseases across various global populations. Clinical guidelines increasingly recommend primary prevention ICDs for patients with reduced ejection fraction, which expands the eligible population substantially. The integration of cardiac resynchronization therapy defibrillators further enhances therapeutic efficacy for advanced heart failure cases. Hospitals in major economies like Japan and Australia have established specialized electrophysiology centers that facilitate higher procedure volumes. Reimbursement policies in developed markets support the adoption of these life-saving technologies despite their high initial cost. Physicians prioritize these devices due to robust clinical evidence demonstrating mortality reduction in high-risk cohorts. The aging demographic structure ensures a steady influx of new candidates requiring long-term rhythm management solutions. This consistent clinical demand solidifies the leading position of this product category within the regional market landscape.
Advanced technological features such as remote monitoring and extended battery life significantly contribute to the market leadership of this segment in the region. According to Boston Scientific product specifications, the Extended Longevity (EL) implantable cardioverter defibrillator (ICD) is designed to last nearly 12 years to minimize the frequency of avoidable replacement procedures. This durability appeals to both patients and healthcare providers who seek sustainable long-term treatment options. Additionally, subcutaneous ICD systems eliminate the need for transvenous leads, thereby reducing risks of infection and vascular damage during implantation. As per the EFFORTLESS and IDE, subcutaneous implantable cardioverter-defibrillators registered a 98% successful conversion rate in terminating ventricular fibrillation. Such safety improvements encourage wider adoption among younger patients and those with complex vascular anatomy. Manufacturers continue to innovate with smaller form factors and enhanced diagnostic algorithms that improve device reliability. Regulatory approvals for next-generation devices in key markets like China and South Korea accelerate market penetration. The ability to transmit real-time data to clinicians enables proactive management of device performance and patient health status. These technological advantages create a strong value proposition that sustains market dominance over other active implant categories. The continuous evolution of device capabilities ensures sustained clinical relevance and preference among medical practitioners.
The neurostimulator segment is witnessing the highest CAGR in the Asia Pacific active implantable medical devices market due to the surging prevalence of chronic pain and neurological conditions. According to Global Burden of Disease data, acute and chronic low back pain are among the leading causes of disability worldwide. This epidemic drives demand for spinal cord stimulators as an alternative to opioid medications, which face increasing regulatory scrutiny. Moreover, as per The BMJ, East Asia is projected to have the highest number of Parkinson's disease cases globally by 2050, reaching an estimated 10.9 million cases. This demographic trend creates an urgent need for deep brain stimulation therapies to manage motor symptoms effectively. Aging populations in countries like Japan and China are particularly susceptible to these debilitating conditions. Healthcare systems are shifting towards multimodal pain management strategies that include neuromodulation as a core component. Clinical evidence supporting the efficacy of neurostimulators in reducing pain scores by 50 % or more encourages physician adoption. Patients seek non-pharmacological solutions to avoid side effects associated with long-term drug use. The expansion of specialized pain clinics across the region facilitates greater access to these advanced therapies. This convergence of epidemiological trends and therapeutic preferences fuels rapid segment expansion.
Innovations in minimally invasive surgical techniques and closed-loop stimulation systems are propelling the rapid growth of this segment in the Asia Pacific market. According to studies, newer implantation methodologies aim to decrease hospital lengths of stay and lower patient complication rates compared to older clinical modalities. These procedural improvements make neurostimulation accessible to a broader patient base, including elderly individuals with comorbidities. Closed-loop systems adjust stimulation parameters in real time based on neural feedback which enhances therapeutic precision and patient comfort. As per reports, closed-loop spinal cord stimulators are evaluated in clinical trials to measure their comparative effectiveness against open-loop devices for chronic pain mitigation. Such superior performance metrics drive physician preference and patient acceptance across the region. Manufacturers are investing in wireless charging technologies and smaller pulse generators that improve usability and aesthetic appeal. Regulatory bodies in Australia and Singapore have expedited approvals for innovative neurostimulation platforms, encouraging market entry. Insurance coverage for chronic pain interventions is expanding in several countries, recognizing the long-term cost savings from reduced medication use. Training programs for interventional pain specialists are increasing the pool of qualified practitioners capable of performing these procedures. These technical and operational advancements collectively accelerate segment growth at an unprecedented pace.
COUNTRY LEVEL ANALYSIS
Japan Active Implantable Medical Devices Market Analysis
Japan is the second-largest country within the Asia Pacific active implantable medical devices market owing to its advanced healthcare infrastructure and rapidly aging population. According to Japan's Ministry of Health, Labour and Welfare, individuals aged 65 and older make up a record 29.1% of the total national population. This demographic reality drives consistent uptake of pacemakers and neurostimulators across the country. Furthermore, as per reports, pacemaker implant tracking databases maintain surgical adoption trends across Japanese cardiovascular networks. Universal health insurance coverage ensures financial accessibility for most patients seeking these essential therapies. The country serves as a hub for medical innovation, with local manufacturers collaborating closely with global leaders to develop tailored solutions. Regulatory pathways through the Pharmaceuticals and Medical Devices Agency are well established, facilitating timely market entry for new technologies. High healthcare expenditure per capita supports the adoption of premium devices with advanced features. Physicians in Japan are highly trained in electrophysiology and neuromodulation, ensuring optimal patient outcomes. The strong emphasis on quality of life for elderly citizens further prioritizes implantable interventions. This combination of demographic pressure and systemic support sustains Japan’s market position.
China Active Implantable Medical Devices Market Analysis
China dominated the Asia Pacific active implantable medical devices market and accounted for a substantial share in 2025. This dominance was driven by a massive population size and improving healthcare access. According to the National Health Commission, cardiovascular disease is the leading cause of death among urban and rural residents in China, accounting for 48.98% of rural deaths and 47.35% of urban deaths. Government initiatives such as Healthy China 2030 aim to enhance chronic disease management and expand insurance coverage for advanced treatments. Moreover, as per studies, the expansion of cardiac catheterization infrastructure across major Chinese medical institutions aims to support higher procedural capabilities. Rising disposable incomes allow more patients to afford out-of-pocket expenses for premium implants. Local manufacturing capabilities are strengthening, reducing costs and improving supply chain efficiency. Regulatory reforms by the National Medical Products Administration have streamlined approval processes for innovative devices, encouraging foreign investment. Urbanization trends lead to lifestyle changes that increase the prevalence of hypertension and diabetes, further fueling demand. Telemedicine integration in rural areas improves follow-up care for implant recipients. The sheer scale of the patient population offers unparalleled growth potential for market participants. Strategic partnerships between international firms and local distributors facilitate deeper market penetration.
India Active Implantable Medical Devices Market Analysis
India is rapidly expanding in the Asia Pacific active implantable medical devices market because of a large volume of procedures and growing medical tourism. According to sources, cardiovascular conditions impact tens of millions of individuals across urban and rural demographics in India. The government’s Ayushman Bharat scheme aims to provide health coverage to millions, potentially including implantable devices in future expansions. In addition, as per research, official cardiology subspecialty qualifications dictate the accredited framework for practicing medical specialists in India. Cost-effective manufacturing hubs attract global companies seeking to produce affordable devices for emerging markets. Medical tourists from neighboring countries seek high-quality yet affordable implant procedures in Indian hospitals. Awareness campaigns by professional associations educate patients about the benefits of active implants over conventional therapies. Private insurance penetration is increasing, enabling more middle-class patients to access advanced treatments. Technological adoption in tier two cities is accelerating due to improved infrastructure and skilled workforce availability. Challenges related to reimbursement consistency remain, but ongoing policy discussions aim to address these gaps. The market exhibits robust growth potential driven by volume and increasing affordability.
South Korea Active Implantable Medical Devices Market Analysis
South Korea has a strong presence in the Asia Pacific active implantable medical devices market, supported by advanced technology adoption and comprehensive health coverage. According to sources, the incidence and clinical burden of atrial fibrillation have significantly risen in South Korea over recent years due to an aging population. The National Health Insurance Service covers a wide range of implantable devices, ensuring high patient accessibility and adherence. Furthermore, the Ministry of Food and Drug Safety has implemented rigorous yet efficient regulatory frameworks that promote innovation while ensuring safety. High literacy rates and health awareness encourage patients to seek early intervention for chronic conditions. The country is a leader in digital health integration, allowing seamless remote monitoring of implanted devices. Local research institutions collaborate with global firms to develop next-generation implants tailored to Asian anatomies. Aging demographics similar to Japan create sustained demand for neurological and cardiac solutions. Hospital accreditation standards ensure high-quality care delivery for complex implant procedures. Government investments in biomedical research foster a conducive environment for market growth. The competitive landscape encourages continuous improvement in device quality and service delivery.
Australia Active Implantable Medical Devices Market Analysis
Australia is growing steadily within the Asia Pacific active implantable medical devices market, with strong emphasis on clinical outcomes. According to the Australian Bureau of Statistics (ABS), heart disease is the leading cause of death in Australia, accounting for approximately 11% to 13% of all registered nationwide deaths annually in recent data. This underscores the critical role of implantable cardioverter defibrillators and pacemakers in national health strategy. Besides, the Therapeutic Goods Administration maintains stringent quality standards that ensure only safe and effective devices reach patients. The Pharmaceutical Benefits Scheme provides subsidies for certain implantable therapies, reducing financial barriers for consumers. High healthcare spending per capita supports the adoption of premium technologies with advanced features. Remote monitoring infrastructure is well developed, enabling efficient management of patients with implanted devices. Clinical trials conducted in Australian centers contribute to global evidence bases for new devices. Strong patient advocacy groups raise awareness about treatment options and rights. The medical profession is highly specialized with excellent training programs for implant surgeons. Market growth is steady, driven by replacement procedures and technological upgrades rather than just new implants.
Thailand Active Implantable Medical Devices Market Analysis
Thailand is an emerging hub in the Asia Pacific active implantable medical devices market. This growth is propelled by medical tourism and improving domestic healthcare infrastructure. According to studies, cardiovascular disease remains a principal cause of morbidity and mortality in Thailand, steering public healthcare investments. The government’s Universal Coverage Scheme ensures basic access to essential implantable devices for the majority of the population. In addition, the Ministry of Public Health promotes medical tourism, which attracts international patients seeking high-quality and affordable implant procedures. Bangkok serves as a center of excellence for complex cardiac and neurological surgeries, attracting skilled professionals from across the region. Local manufacturing capabilities are developing to support regional supply chains for standard devices. Regulatory processes through the Thai FDA are becoming more streamlined to facilitate faster market entry. Awareness campaigns target urban populations to encourage early screening for heart conditions. Private hospitals compete on service quality and technology adoption, driving innovation in patient care. Training programs for local physicians enhance technical skills for implant procedures. The market benefits from both domestic demand and cross-border patient flows.
Malaysia Active Implantable Medical Devices Market Analysis
Malaysia displays steady expansion in the Asia Pacific active implantable medical devices market, fuelled by a dual-tier healthcare system and rising chronic disease prevalence. According to the Malaysian National Health and Morbidity Survey (NHMS), hypertension affects roughly 30% of adults aged 18 and older in Malaysia. The government subsidizes healthcare for public sector employees and low-income groups, ensuring basic access to essential devices. Furthermore, private healthcare providers cater to affluent patients seeking advanced implants with the latest technologies. Regulatory oversight by the Medical Device Authority ensures safety and quality standards align with international norms. Medical tourism initiatives promote Malaysia as a destination for affordable cardiac and neurological treatments. Local distributors partner with global manufacturers to ensure consistent supply of devices and spare parts. Awareness programs focus on lifestyle modifications to reduce the burden of preventable heart diseases. Training collaborations with international centers enhance the skills of local cardiologists and surgeons. The market balances cost containment with quality improvement through strategic procurement practices. Digital health initiatives begin to support remote monitoring of implanted devices in urban areas.
COMPETITIVE LANDSCAPE
The competitive landscape of the Asia Pacific active implantable medical devices market is characterized by intense rivalry among global giants and emerging local manufacturers. Established multinational corporations dominate due to their extensive product portfolios, strong brand recognition, and robust distribution networks. These leaders continuously innovate to maintain technological superiority and differentiate their offerings through advanced features such as wireless connectivity and artificial intelligence integration. Local players are gaining traction by offering cost-effective alternatives tailored to specific regional needs and regulatory requirements. Competition drives continuous improvement in device safety, efficacy, and patient comfort levels across all segments. Price sensitivity in emerging markets forces companies to balance premium pricing with affordability strategies to capture broader patient bases. Regulatory compliance serves as a significant barrier to entry, ensuring only qualified participants operate within the market. Collaborative efforts between competitors and healthcare institutions foster innovation and improve clinical standards. The race for talent and specialized expertise further intensifies competition as companies seek to build capable teams for research and development. Strategic alliances and joint ventures become common tactics to share risks and leverage complementary strengths. This dynamic environment encourages constant adaptation and innovation to meet diverse clinical demands effectively.
KEY MARKET PLAYERS
The leading companies operating in the Asia Pacific active implantable medical devices market include:
- Medtronic plc
- Abbott Laboratories
- Boston Scientific Corporation
- BIOTRONIK SE & Co. KG
- LivaNova PLC
- Cochlear Limited
- MED-EL
- Sonova Holding AG
- William Demant Holding A/S
- Nurotron Biotechnology Co. Ltd.
TOP PLAYERS IN THE MARKET
- Medtronic maintains a dominant presence in the Asia Pacific active implantable medical devices sector through its comprehensive portfolio of cardiac and neurological solutions. The company actively invests in local manufacturing facilities and research centers to tailor products for Asian anatomical variations. Recent initiatives include launching next-generation leadless pacemakers in Japan and Australia, which reduce surgical complications significantly. Medtronic collaborates with regional hospitals to establish specialized training programs for electrophysiologists, ensuring proper device utilization. Their focus on remote monitoring platforms enhances patient engagement and clinical outcomes across diverse healthcare settings. The company also partners with local distributors to improve supply chain efficiency in emerging markets like India and Southeast Asia. Strategic acquisitions of innovative startups further strengthen their technological leadership in neuromodulation and heart failure management. These efforts collectively reinforce their reputation for reliability and clinical excellence in the region.
- Abbott Laboratories strengthens its position in the Asia Pacific market by leveraging advanced miniaturization technologies and digital health integration. The company recently introduced ultra-small implantable cardioverter defibrillators in China and South Korea, addressing patient preferences for less invasive options. Abbott focuses on expanding its neuromodulation portfolio by launching new spinal cord stimulators designed for chronic pain management. Collaborations with telemedicine providers enable seamless remote monitoring services for implant recipients across rural areas. The company invests heavily in clinical trials within the region to generate local evidence supporting device efficacy. Regulatory approvals in key markets like Singapore and Malaysia facilitate faster product launches. Abbott also engages in physician education programs to enhance technical skills for complex implant procedures. Their commitment to innovation and accessibility drives sustained growth and patient trust in the competitive landscape.
- Boston Scientific Corporation contributes significantly to the Asia Pacific active implantable medical devices market through its robust pipeline of cardiac and neurostimulation products. The company recently expanded its subcutaneous ICD offerings in Japan and Australia, providing safer alternatives for high-risk patients. Boston Scientific emphasizes partnerships with local healthcare providers to improve access to advanced therapies in underserved regions. Their investment in artificial intelligence-driven diagnostic tools enhances device performance and predictive maintenance capabilities. The company launched new deep brain stimulation systems in South Korea, targeting Parkinson’s disease management effectively. Training initiatives for surgeons and technicians ensure optimal device implantation and long-term care. Boston Scientific also focuses on sustainable manufacturing practices to meet regional environmental standards. These strategic actions bolster their competitive edge and commitment to improving patient quality of life through innovative medical technologies.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the Asia Pacific active implantable medical devices market employ multifaceted strategies to consolidate their positions and drive growth. Product innovation remains central as companies invest heavily in research and development to create smaller, more efficient devices with extended battery lives. Strategic partnerships with local distributors and healthcare providers facilitate deeper market penetration, especially in emerging economies with complex regulatory landscapes. Companies prioritize obtaining regulatory approvals in major markets like Japan, China, and Australia to establish early footholds. Expansion of manufacturing facilities within the region helps reduce costs and mitigate supply chain disruptions. Digital health integration is another critical strategy where firms develop remote monitoring platforms to enhance patient engagement and clinical outcomes. Educational initiatives targeting physicians and patients raise awareness about advanced implant options and proper usage. Mergers and acquisitions allow larger corporations to absorb innovative startups and expand their product portfolios rapidly. Pricing strategies are adapted to local economic conditions, ensuring affordability while maintaining profitability. These combined approaches enable sustained competitiveness and responsiveness to evolving regional healthcare needs.
MARKET SEGMENTATION
This research report on the Asia-Pacific active implantable medical devices market has been segmented and sub-segmented into the following categories.
By Product
- Implantable Cardioverter Defibrillators
- Transvenous Implantable Cardioverter Defibrillators
- Biventricular Implantable Cardioverter Defibrillators (ICDs)/Cardiac Resynchronization Therapy Defibrillators (CRT-Ds)
- Dual-Chamber Implantable Cardioverter Defibrillators
- Single-Chamber Implantable Cardioverter Defibrillators
- Subcutaneous Implantable Cardioverter Defibrillator
- Transvenous Implantable Cardioverter Defibrillators
- Implantable Cardiac Pacemakers
- Ventricular Assist Devices
- Implantable Heart Monitors/Insertable Loop Recorders
- Neurostimulators
- Spinal Cord Stimulators
- Deep Brain Stimulators
- Sacral Nerve Stimulators
- Vagus Nerve Stimulators
- Gastric Electrical Stimulators
- Implantable Hearing Devices
- Active Hearing Implants
- Passive Hearing Implants
By Country
- India
- China
- Japan
- South Korea
- Australia
- New Zealand
- Thailand
- Malaysia
- Vietnam
- Philippines
- Indonesia
- Singapore
- Rest of APAC